
 Self-Sealing Ziplock Bags Market | 2026-2036
Self-Sealing Ziplock Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Sealing Ziplock Bags Market Analytics
Polymer compounding expertise is rotating toward high-clarity polyethylene formulations as converters race to meet recyclability mandates. Amcor leverages its film extrusion network across multiple continents to supply food-grade ziplock stock with consistent seal integrity. Berry Global sustains cost leadership through vertical integration into resin procurement and blown film production. Mondi anchors European demand with kraft-paper hybrid ziplock solutions that address paper-based packaging quotas.
Self-sealing ziplock bags are multi-layer or mono-material pouches incorporating interlocking rib-and-groove closures, typically manufactured via coextrusion or adhesive lamination at thicknesses ranging from 1.5 to 4.0 mil, designed for repeated opening and closing without compromising barrier properties. The polyethylene segment dominates volume due to its heat-seal compatibility and established mechanical recycling streams, while biodegradable alternatives compete on emerging compostability certifications despite higher unit costs. Food packaging occupies the largest end-use position, though medical storage commands premium pricing through sterilization-grade validation requirements.
The EU's Packaging and Packaging Waste Regulation and the US FDA's food-contact substance notifications jointly shape material selection and migration testing protocols for ziplock formats sold into regulated channels. REACH restrictions on phthalate plasticizers and California's SB 54 extended producer responsibility law are forcing reformulation of seal-layer additives across export-bound production lines. Stakeholders must monitor evolving state-level packaging EPR enactments and recyclability labeling standards to avoid stranded inventory in key distribution corridors.
Market Dynamics
Converters face mounting pressure from the EU's Packaging and Packaging Waste Regulation to abandon multi-layer laminates in favor of mono-material polyethylene constructions that qualify for mechanical recycling streams. This material pivot is redrawing supplier relationships and capital deployment across extrusion and converting operations.
Growth Catalysts
- EU recyclability mandates:The Packaging and Packaging Waste Regulation is compelling retail chains to specify certified recyclable ziplock formats, accelerating demand for mono-material polyethylene constructions in private-label food packaging programs.
- Food waste reduction priorities:Retailers across Germany and France are expanding resealable bag specifications to extend produce shelf life and reduce spoilage-related losses in their supply chains.
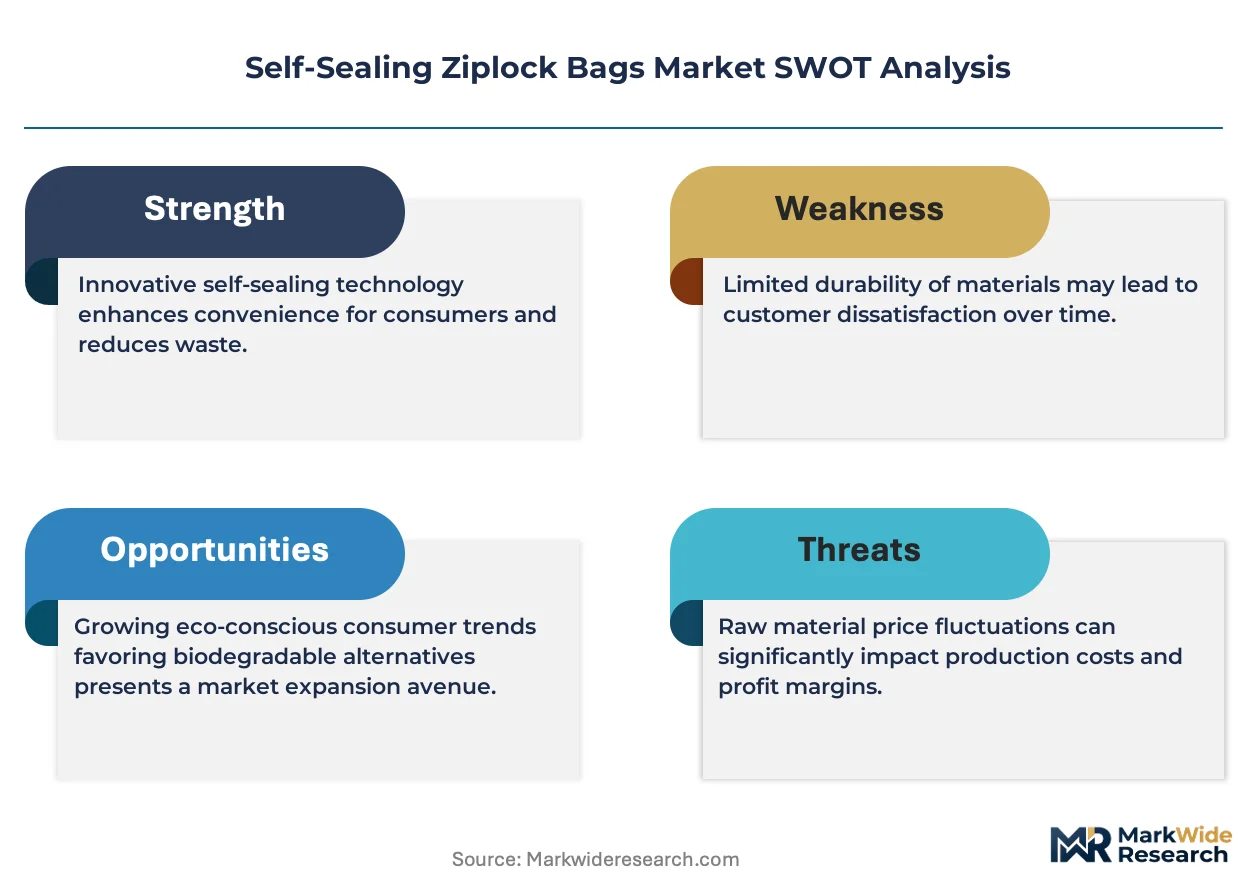
- Medical-grade sterilization requirements:Hospitals and pharmaceutical distributors are adopting validated ziplock formats for sterile device storage, creating premium-priced demand segments with rigorous barrier specifications.
Market Restraints
- Ethylene feedstock volatility:Polyethylene resin costs fluctuate with naphtha and natural gas liquid pricing, squeezing converter margins and complicating long-term contract negotiations with food-packaging buyers.
- Multi-layer technical lock-in:Existing coextrusion lines optimized for EVOH or nylon barrier layers require substantial retrofit capital to produce mono-material alternatives that meet new recyclability standards.
- Compostable film performance gaps:PLA and PBAT alternatives exhibit inferior moisture barrier properties and heat-seal consistency, limiting their displacement of polyethylene in high-throughput food applications.
Strategic Opportunities
- India organized retail expansion:Modern grocery chains in Mumbai and Bangalore are adopting resealable packaging formats for private-label dry goods, creating first-mover advantages for converters with localized production.
- Paper-hybrid quota compliance:The EU Green Deal's paper-based packaging targets are opening demand for kraft-laminated ziplock solutions that combine fiber content with moisture barrier functionality.
- RFID-enabled inventory tracking:Convergence of printed electronics with flexible packaging is enabling smart ziplock formats for pharmaceutical cold-chain verification, commanding substantial price premiums.
Industry Challenges
- Migration testing bottlenecks:REACH restrictions on phthalate plasticizers and novel seal-layer additives require extended EFSA validation timelines, delaying product launches by 12-18 months.
- Mechanical recycling contamination:Sorting facilities struggle to distinguish food-grade from non-food-grade polyethylene ziplocks, degrading rPE quality and threatening closed-loop circularity claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Sealing Ziplock Bags Market |
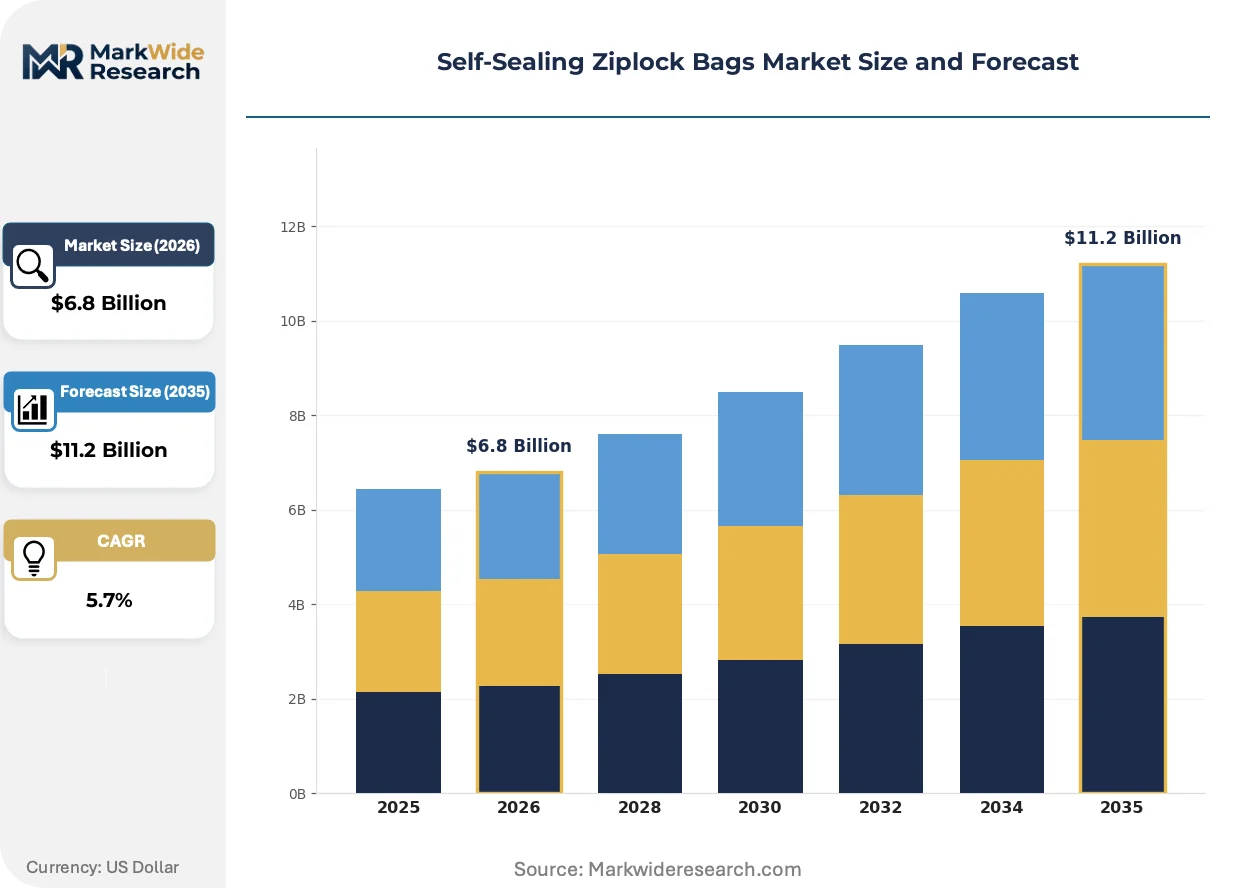
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
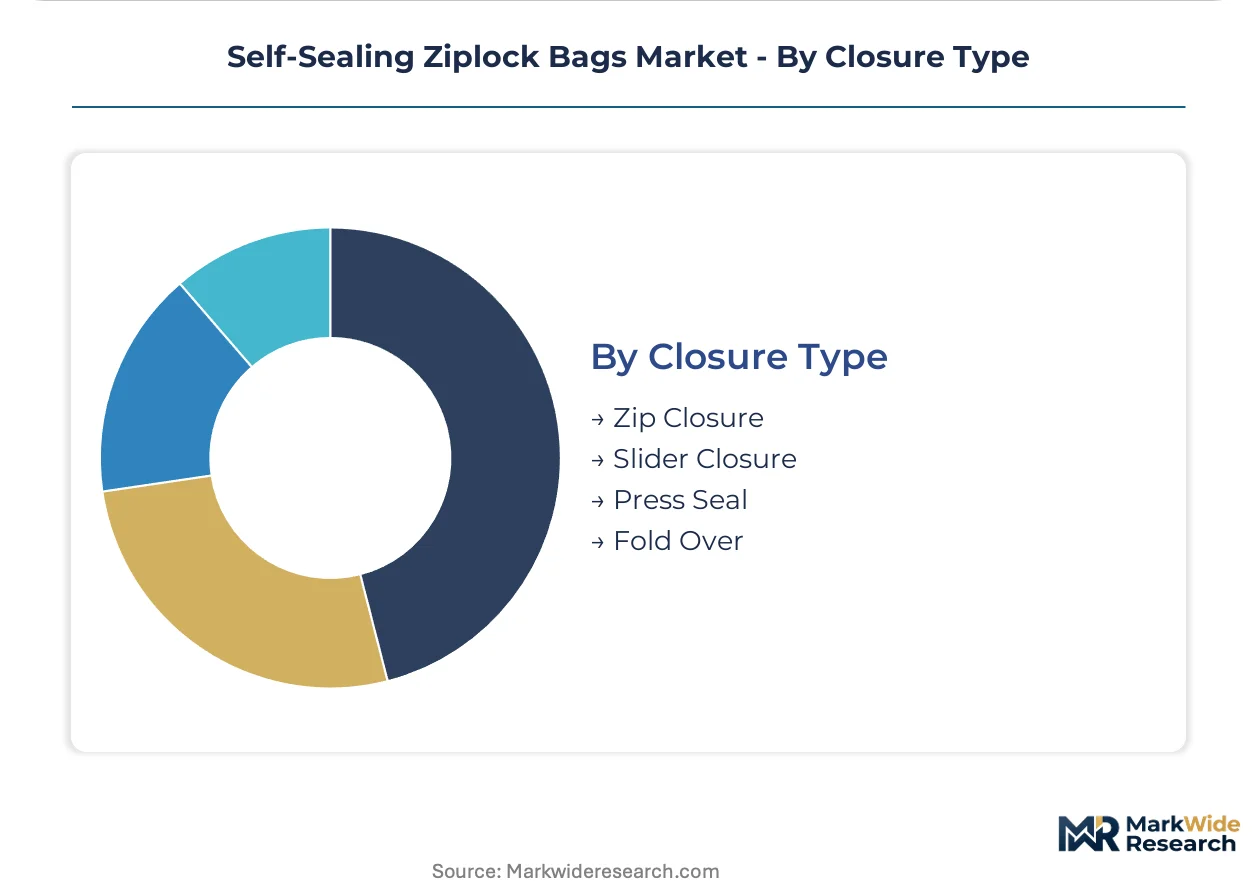
| Segmentation | Material Type: Plastic, Polyethylene, Biodegradable, Nylon Size: Small, Medium, Large, Extra Large End Use: Food Packaging, Medical Storage, Industrial Use, Household Organization Closure Type: Zip Closure, Slider Closure, Press Seal, Fold Over |
| Companies Covered | Amcor, Berry Global, Mondi, Glenroy, Flair Flexible Packaging, Winpak, Printpack, Sealed Air, Sonoco Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Sealing Ziplock Bags Market Evolving Landscape
Material science and regulatory compliance are converging to reshape ziplock bag specifications, with converters racing to deliver barrier performance without sacrificing recyclability credentials. Three developments are restructuring competitive positioning.
Mono-material polyethylene formulations incorporating metallocene-catalyzed resins are bifurcating the market between premium clarity grades for retail visibility and economy tiers for industrial bulk packaging. Food processors in Germany and the Netherlands are specifying the high-clarity variants for deli and produce applications, while logistics operators adopt the standard grades for parts and component storage. This technical split is compressing demand for conventional multi-layer laminates that fall outside mechanical recycling streams.
REACH restrictions on phthalate plasticizers and California's SB 54 extended producer responsibility law are forcing reformulation of seal-layer additives across export-bound production lines. Converters serving transatlantic customers must maintain dual formulation inventories or absorb compliance consulting costs. The medical storage segment is responding most aggressively, with sterilization-grade suppliers accelerating validation of non-phthalate seal technologies to preempt supply disruptions.
Retail procurement teams are consolidating supplier relationships around converters with in-house film extrusion and certified recycling partnerships, displacing fragmented broker-mediated sourcing. This concentration is most visible in France, where Carrefour and Intermarché have reduced their ziplock bag supplier bases by 40 percent since 2023. Smaller converters without backward resin relationships are exiting the market or accepting margin-compressing toll manufacturing arrangements.
Self-Sealing Ziplock Bags Market Segmentation
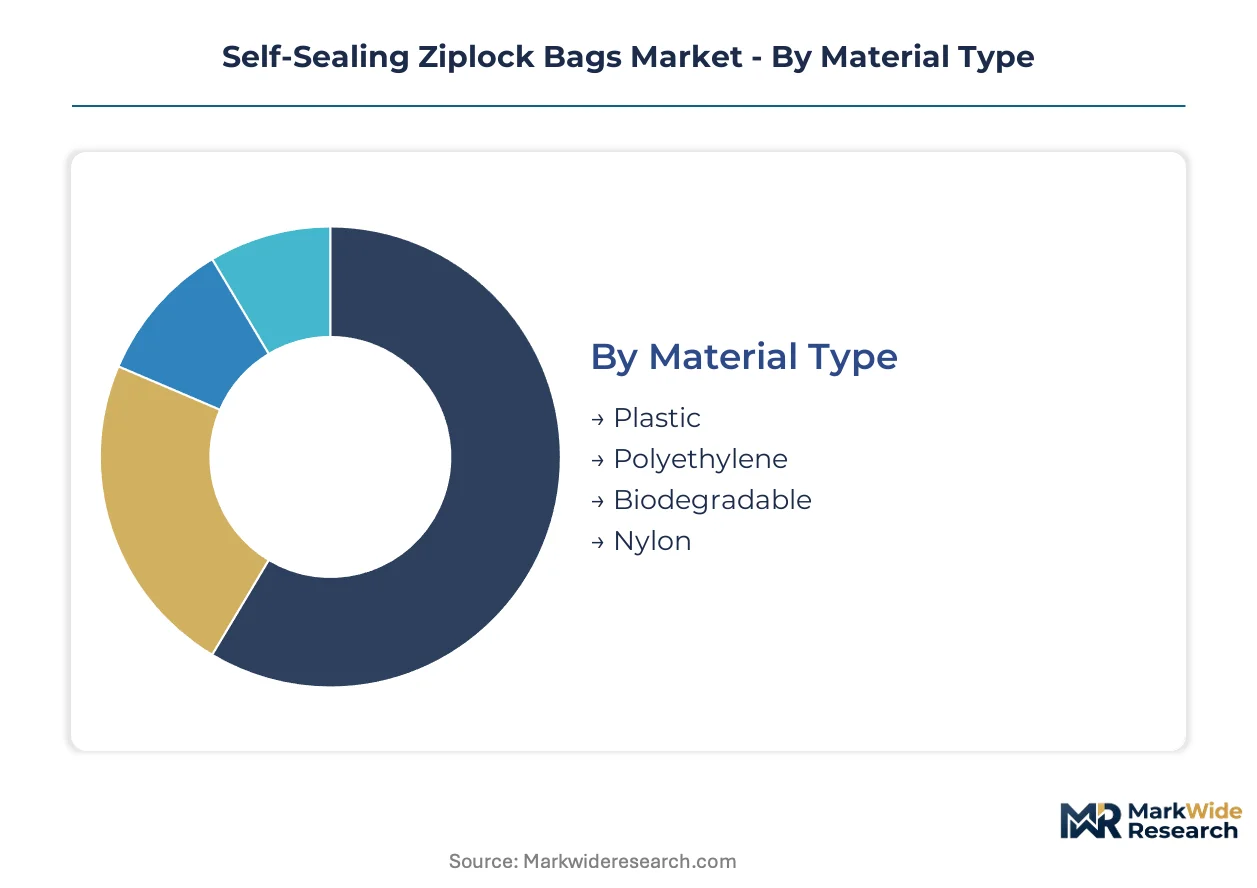
Segmentation in ziplock bags reveals how material chemistry and closure mechanics translate into differentiated margin pools. Food safety mandates and recyclability regulations are fragmenting what once appeared as a commodity category into technically distinct supply tiers.
Material Type:
Premium margins concentrate in formulations that balance barrier performance with mechanical recyclability credentials.
- Polyethylene:Mono-material constructions utilizing metallocene-catalyzed resins deliver heat-seal compatibility and established mechanical recycling streams. German retail chains specify certified recyclable polyethylene formats for private-label produce programs, displacing multi-layer alternatives.
- Biodegradable:PLA and PBAT formulations compete on emerging compostability certifications despite moisture barrier limitations and heat-seal inconsistency. Industrial users in France pilot these formats for controlled organic waste collection where end-of-life composting infrastructure exists.
- Plastic:Conventional multi-layer laminates incorporating EVOH or nylon barrier layers retain legacy industrial applications but face margin compression from EU recyclability mandates requiring costly line retrofits.
- Nylon:High-tensile specifications serve medical sterilization and heavy-duty industrial containment where puncture resistance outweighs recycling considerations.
Polyethylene holds installed capacity. Biodegradable is rotating up the share rankings.
Size:
Volume throughput and automation compatibility drive cost tier separation across dimensional specifications.
- Medium:Specifications ranging from sandwich to quart capacity dominate food retail SKUs, with standardized dimensions enabling high-speed form-fill-seal automation across European co-packers.
- Large:Gallon-plus formats capture household bulk storage and light industrial parts organization, with thicker gauge requirements (3.0-4.0 mil) supporting premium pricing over standard food grades.
- Small:Snack and portion-control dimensions serve single-serve food applications and pharmaceutical unit-dose packaging, though lower per-unit value complicates converter margin targets.
- Extra Large:Oversized constructions for bedding, garment, and bulk commodity storage operate through distinct distribution channels with seasonal demand patterns.
Medium formats anchor production volume. Large formats are climbing the fastest on household organization demand.
End Use:
Validation requirements and barrier specifications create three distinct customer types with diverging procurement behaviors.
- Food Packaging:The largest position by volume, spanning produce, deli, and dry goods applications where oxygen and moisture barrier properties extend shelf appeal. EFSA migration testing protocols govern seal-layer additive selection for EU-bound production.
- Medical Storage:Sterilization-grade validation requirements command substantial price premiums, with FDA 510(k) and EU MDR compliance timelines extending product development cycles. Hospital systems and pharmaceutical distributors specify validated formats for sterile device containment.
- Industrial Use:Parts storage, chemical containment, and logistics applications prioritize puncture resistance and reseal durability over optical clarity, with procurement consolidated through industrial distributors.
- Household Organization:Consumer retail channels for closet, travel, and craft storage exhibit high private-label penetration and price sensitivity, with seasonal promotional cycles compressing margins.
Food packaging holds installed capacity. Medical storage is rotating up the share rankings on sterilization validation demand.
Closure Type:
Mechanism complexity and user experience differentiate pricing tiers within what converters treat as a secondary specification.
- Zip Closure:Interlocking rib-and-groove constructions manufactured via coextrusion dominate food and medical applications, with seal integrity testing protocols varying by end-use regulatory channel.
- Slider Closure:Plastic zipper mechanisms enable one-handed operation for accessibility-focused medical and household segments, though component assembly adds unit cost and supply chain complexity.
- Press Seal:Adhesive-based closures serve temporary containment and lower-cycle applications where reseal count expectations remain modest, competing primarily on cost.
- Fold Over:Simple flap constructions without mechanical interlock serve bakery, produce, and short-duration storage where barrier requirements are minimal and price positioning drives selection.
Zip closure holds installed capacity. Slider closure is gaining share fastest on medical and accessibility applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA migration testing protocols govern seal-layer additive selection for converters supplying EU-bound production, while the Packaging and Packaging Waste Regulation tightens material recovery targets across member states. Retail procurement teams in Germany and France are consolidating supplier relationships around certified recyclable formats.
Germany
Carrefour and Intermarché have reduced their ziplock bag supplier bases by 40 percent since 2023, concentrating procurement around converters with backward resin relationships. The Packaging and Packaging Waste Regulation compels retail chains to specify certified recyclable formats, accelerating demand for mono-material polyethylene constructions. Industrial distributors in the Rhine-Ruhr region specify these formats for private-label programs.
United States
California's SB 54 extended producer responsibility law forces reformulation of seal-layer additives across export-bound production lines. FDA food-contact substance notifications shape material selection and migration testing protocols for ziplock formats sold into regulated channels. Food packaging operations across the Midwest are expanding their use of resealable formats to cut spoilage.
France
Retailers are expanding resealable bag specifications to extend produce shelf life and reduce spoilage-related losses in their supply chains. The EU Green Deal's paper-based packaging targets open demand for kraft-laminated ziplock solutions that combine fiber content with moisture barrier functionality. Converters in the Île-de-France region pilot PLA and PBAT formats for controlled organic waste collection.
India
Modern grocery chains in Mumbai and Bangalore are adopting resealable packaging formats for private-label dry goods, creating first-mover advantages for converters with localized production. FSSAI food safety mandates govern seal integrity for domestic food-contact applications. The Maharashtra industrial corridor attracts extrusion capacity investments targeting organized retail expansion.
China
SAMR standards and dual carbon goals pressure converters toward mono-material constructions compatible with mechanical recycling streams. GB standards for food-contact plastics influence seal-layer formulation choices for export-oriented producers. The Yangtze River Delta concentration of film extrusion capacity serves both domestic retail and transatlantic export demand.
Self-Sealing Ziplock Bags Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with backward integration into resin procurement distinguishing the upper tier from toll-dependent competitors. The market structure reflects this bifurcation: scale players with captive film extrusion networks compete on cost and compliance velocity, while mid-cap specialists defend niche positions in sterilization-grade or paper-hybrid formats. Two strategic archetypes dominate: vertically integrated resin-to-film converters and technology licensors with formulation IP. Competitive moves concentrate on M&A to secure recycling partnerships and capacity expansion in India and Southeast Asia.
Among North American integrated packaging corporations, Amcor, Berry Global, and Sealed Air exemplify the scale-driven archetype, each occupying positions that span multiple continents and end-use segments. These entities represent the premium clarity and economy tier split visible in German retail procurement, with their geographic dispersion enabling dual-formulation inventories for transatlantic compliance. Their market presence anchors the competitive structure without requiring specific product or technology claims.
| Leading Market Players |
|---|
| Amcor |
| Berry Global |
| Mondi |
| Glenroy |
| Flair Flexible Packaging |
| Winpak |
| Printpack |
| Sealed Air |
| Sonoco Products |
| Others |
Value Network & Pricing Analysis
Mono-material polyethylene substitution for multi-layer laminates is simultaneously relocating extrusion capacity toward Germany and compressing margins on legacy coextrusion lines. This material pivot forces converters to absorb retrofit capital or surrender share to backward-integrated competitors with certified recycling partnerships.
Pricing Analysis
Price spreads between German retail procurement and Indian industrial sourcing exceed transport-adjusted resin differentials, reflecting certification premiums for EFSA-compliant seal-layer formulations. Three-tier pricing structure across medical sterilization, food-grade clarity, and industrial bulk tiers separates validation investment levels. Pricing pressure stems from ethylene feedstock volatility squeezing converter margins on fixed-price retail contracts. Household organization buyers exhibit highest price sensitivity, while pharmaceutical distributors accept substantial premiums for validated sterile formats.
Supply Chain Analysis
Naphtha cracking capacity in the Rhine-Ruhr corridor and Yangtze River Delta film extrusion clusters constitute dual chokepoints for European and Asian supply. The supply chain draws from Saudi ethylene feedstock, metallocene catalyst technology licensed from U.S. petrochemical licensors, and masterbatch additives subject to REACH authorization timelines. Single-source vulnerability concentrates in medical-grade seal-layer resin supply. Distribution runs through industrial distributors for bulk formats and retail private-label channels for consumer SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where EFSA validation timelines and EU recyclability certification create structural barriers against commodity substitution.
For Market Incumbents: Compound backward resin relationships into captive recycling partnerships that preempt compliance velocity challenges from emerging mono-material specialists. Prioritize capacity addition in Maharashtra and Karnataka to intercept organized retail expansion before regional converters achieve scale. Defend against slider-closure technology licensors by accelerating in-house mechanism assembly capabilities. For New Entrants and Emerging Players: Lead with compostable film formulations for French controlled organic waste collection pilots, where infrastructure availability creates temporary performance tolerance. Target kraft-paper hybrid formats for EU Green Deal paper-based packaging quota compliance, exploiting incumbent converters' polyethylene-focused capital deployment. Pursue toll manufacturing arrangements with fragmented industrial distributors lacking extrusion assets. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European converters holding EFSA-validated product portfolios but lacking India production presence. Five-to-ten-year viability hinges on successful geographic diversification beyond EU regulatory exposure. Watch for FSSAI enforcement acceleration in Maharashtra as inflection signal for India market formalization.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Line Retrofit | Enables EU Packaging and Packaging Waste Regulation compliance for mechanical recycling streams. |
| India Extrusion Capacity Buildout | Captures organized retail expansion in Mumbai and Bangalore private-label programs. |
| Kraft-Paper Hybrid Format Development | Addresses EU Green Deal paper-based packaging targets with moisture barrier functionality. |
| Non-Phthalate Seal Validation | Preempts REACH restriction disruption for transatlantic medical and food-contact supply. |
| RFID-Enabled Smart Packaging Partnership | Commands pharmaceutical cold-chain verification premiums through printed electronics convergence. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with film extrusion plant managers, retail category buyers at Carrefour and Intermarché, industrial distribution procurement leads, and EFSA regulatory affairs specialists. Secondary validation drew from customs trade databases, EU Packaging and Packaging Waste Regulation implementation guidance, SEC filings of integrated packaging corporations, and German retail private-label specification documents. Bottom-up volume estimates from converter capacity utilization triangulated against top-down retail procurement value flows.
Across the analysis window, forecasts modeled material type substitution dynamics, end-use validation tier migration, and closure mechanism adoption curves. Segmentation dimensions included mono-material versus multi-layer construction, food versus medical versus industrial end-use, and geographic regulatory cluster. CAGRs derived from elasticity-adjusted demand projections and capacity expansion announcements. Industry-specific inputs incorporated ethylene-naphtha spread volatility and EFSA additive authorization timelines.
Underlying assumptions cover sustained EU recyclability mandate enforcement and India organized retail penetration rates, with deviation risk concentrated in compostable film performance breakthroughs or delays in Maharashtra extrusion capacity commissioning. Practitioners should keep alternative scenarios live as FSSAI enforcement intensity and EU Green Deal paper quota implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Multiwall Bags Market
Bags and Containers
Inner Bulk Liners Market
Bags and Containers
Circular Industrial Bags Market
Bags and Containers
Disposable Garbage Bags Market
Bags and Containers
Lawn and Leaf Bags Market
Bags and Containers
Compression Baggers Market
Bags and Containers
Bag-In-Box Packaging Market
Bags and Containers
Archive Boxes Market
Bags and Containers
Double Zipper Bags Market
Bags and Containers
Global Bag Filling Machines Market
Bags and Containers
Padding Bags Market
Bags and Containers
Garbage Bag Market
Bags and Containers
Wicketless Bags Market
Bags and Containers
Frosted Bag Market
Bags and Containers
Cross Bottom Bags Market
Bags and Containers
Vertical Form Fill Seal Baggers Market