
 Two Piece Metal Containers Market | 2026-2036
Two Piece Metal Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Two Piece Metal Containers Market Analytics
Lightweighting and alloy reformulation is reconfiguring the engineering priorities across two-piece metal container production. Ball Corporation leverages captive aluminum supply and integrated recycling infrastructure to sustain cost leadership in North American beverage can markets. Crown Holdings Inc. anchors its position through deep R&D investment in thinner-wall steel technologies for food preservation. Silgan Containers LLC specializes in aerosol and specialty tinplate formats where barrier performance commands premium positioning.
Two-piece metal containers are fabricated from a single metal blank drawn into a cup and then ironed to form a seamless body with a separately attached end, typically using aluminum alloy 3104-H19 or tinplate steel with internal epoxy-phenolic coatings to prevent corrosion and preserve flavor. The cans segment dominates volume as beverage brands standardize on 12-ounce and 16-ounce aluminum formats, while drums and pails retain structural importance in chemical transport where UN-certified stacking strength remains mandatory. Coating technology represents a critical margin pool as manufacturers migrate from bisphenol-A-based formulations to polyester and vinyl-organosol alternatives under tightening food-contact regulations.
The EPA regulates volatile organic compound emissions from can coating operations under Clean Air Act standards, while FDA Title 21 CFR provisions govern direct food-contact materials and migration limits for container linings. China's SAMR enforces GB standards for food packaging metals, creating divergent testing protocols that complicate cross-border supply chains. Stakeholders must monitor alloy cost volatility and regulatory divergence between North American and Asian compliance frameworks to optimize capital deployment across regional manufacturing footprints.
Market Dynamics
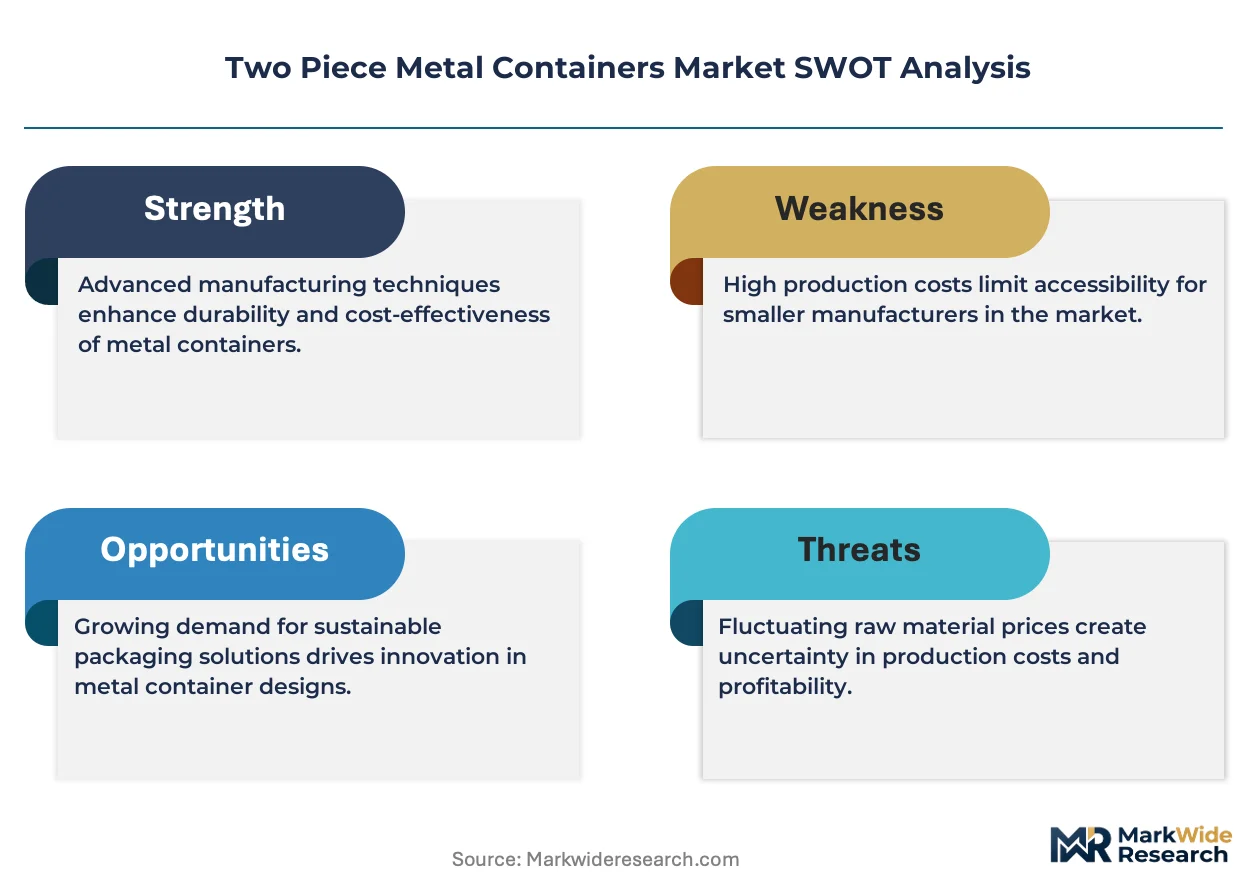
Lightweighting mandates under the EU Green Deal and parallel extended producer responsibility frameworks are compressing wall thickness specifications across aluminum beverage can production, forcing capital redeployment toward thinner-wall drawing and ironing equipment.
Growth Catalysts
- Aluminum Alloy Substitution:Breweries and sparkling water brands are migrating from glass to aluminum formats for logistics efficiency and recycling economics, tightening supply-demand balance for 3104-H19 coil.
- REACH-Driven Coating Reformulation:European manufacturers are accelerating bisphenol-A phase-outs ahead of ECHA restrictions, creating pull-through demand for polyester and vinyl-organosol liner alternatives.
- Craft Beverage Clustering:Regional microbrewery density in the United States, Germany, and China is generating distributed demand for smaller-run can formats and shorter lead-time supply contracts.
Market Restraints
- Primary Aluminum Volatility:London Metal Exchange price swings for aluminum ingot compress margin predictability for can body stock converters operating on fixed-price annual contracts.
- Coating Chemical Concentration:Epoxy-phenolic resin supply concentrates among a limited set of specialty chemical producers, exposing can makers to input bottlenecks during force majeure events.
- Steel Drum Substitution Ceiling:UN-certified steel drums retain structural advantages in corrosive chemical transport, capping aluminum pail penetration in industrial end-uses.
Strategic Opportunities
- Aerosol Tinplate Expansion:Personal care and household product brands in India and Southeast Asia are expanding propellant-based packaging, opening volume for specialty two-piece tinplate formats with barrier-optimized internal coatings.
- Deposit-Return System Alignment:Germany's DRS infrastructure and pending EU-wide harmonization create asset-light entry paths for can producers to plug into established reverse logistics networks.
- Digital Printing Convergence:Direct-to-can inkjet decoration is collapsing minimum order quantities, enabling mass customization for seasonal and limited-release beverage programs.
Industry Challenges
- Tooling Engineering Scarcity:Deep-draw die design expertise for sub-0.008-inch wall thicknesses concentrates among a narrow cohort of retired specialists and specialized equipment OEMs.
- Multi-Jurisdiction Certification Lag:Simultaneous FDA Title 21 CFR, China's GB standards, and EU food-contact compliance testing extends new product qualification timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Two Piece Metal Containers Market |
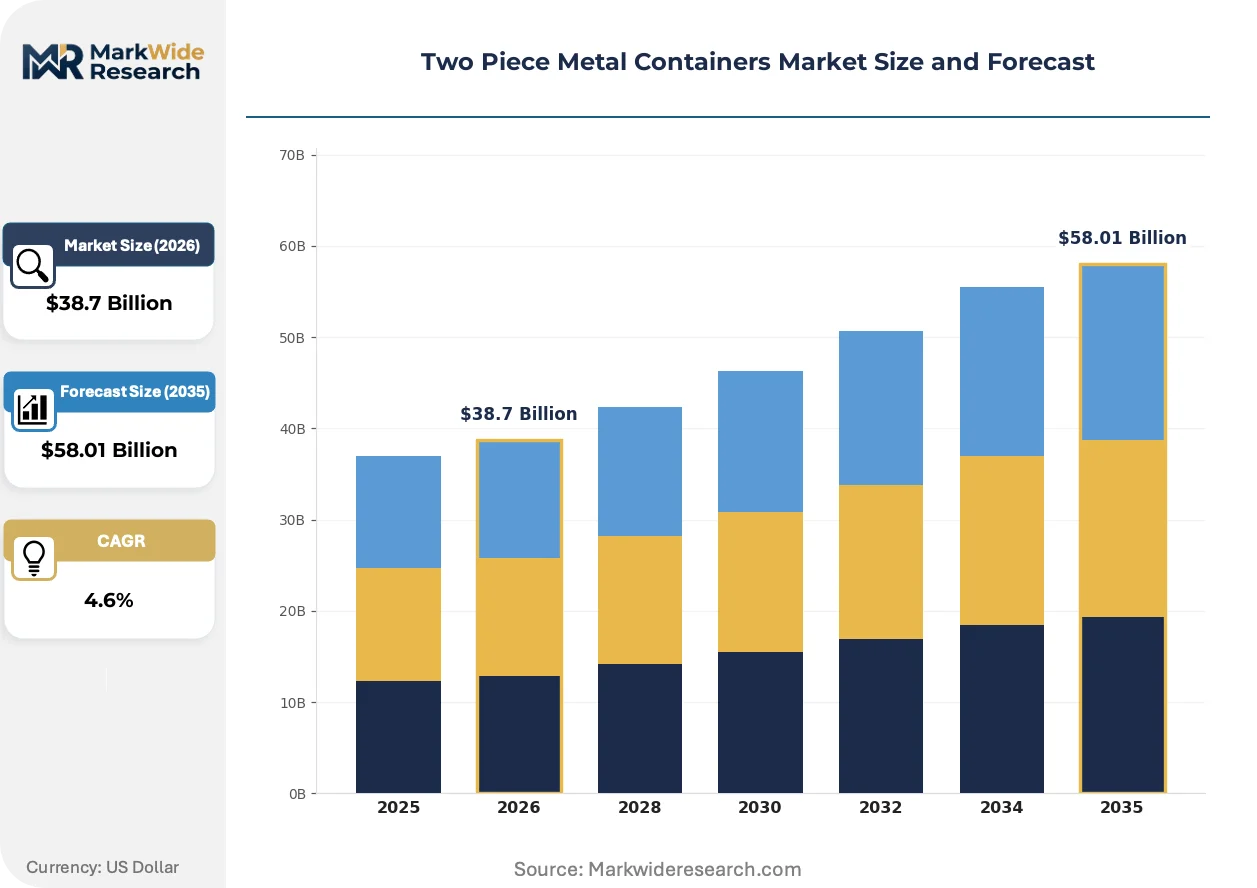
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cans, Tins, Drums, Pails Application: Food Packaging, Beverage Packaging, Industrial Storage, Chemical Transport End User: Food Manufacturers, Beverage Companies, Chemical Industry, Pharmaceutical Sector Technology: Electrolytic, Coating, Printing, Welding |
| Companies Covered | Ball Corporation, Crown Holdings Inc., Silgan Containers LLC, Ardagh Group, DS Containers, Trivium Packaging, DAIWA CAN COMPANY, Kian Joo Can Factory Berhad, Helvetia Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Two Piece Metal Containers Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are converging to redefine barrier performance standards, while digital manufacturing technologies are compressing batch economics and customization thresholds.
Polyester-based internal spray coatings are collapsing the historical performance gap with epoxy-phenolic systems for high-acid beverage applications. Citrus and craft seltzer brands in North America are qualifying these alternatives at accelerated pace. The technology is collapsing the regulatory compliance timeline for bisphenol-A elimination without sacrificing shelf stability.
China's SAMR enforcement of GB 4806.9-2023 for food-contact metals is tightening migration limit testing protocols for imported can components. Manufacturers must now duplicate analytical certification across Chinese and FDA methodologies. Aerosol and specialty food can segments face the steepest requalification burdens as dual-jurisdiction filing costs mount.
Direct-store-delivery beverage distributors are consolidating supplier relationships around integrated can-and-end sourcing to reduce logistics coordination overhead. National brewers in the United States are compressing vendor lists from six to two approved can suppliers per production facility. This concentration is most visible in the Midwest and Southeast production corridors where rail-served aluminum mill proximity determines contract awards.
Two Piece Metal Containers Market Segmentation
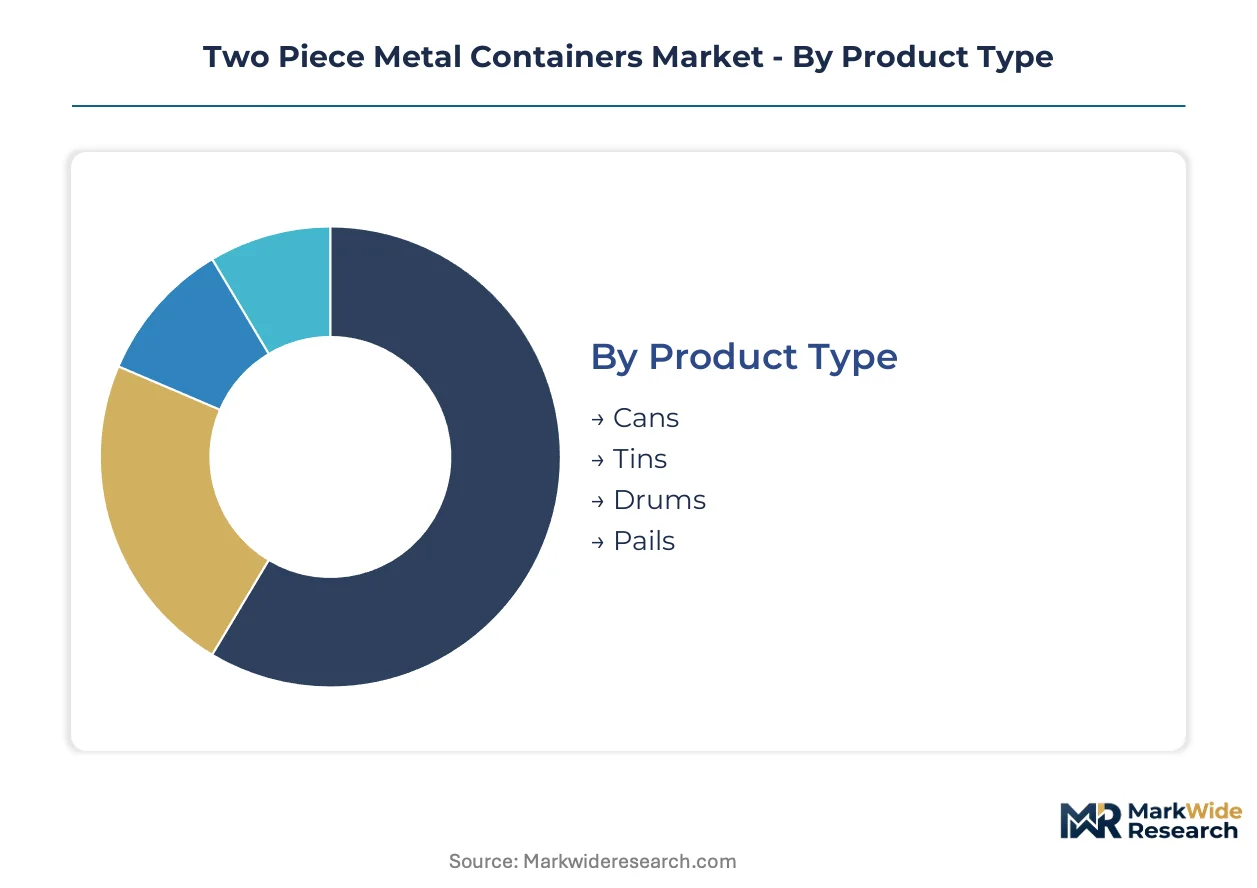
Segmentation in two-piece metal containers reveals how substrate selection, barrier requirements, and filling line compatibility divide manufacturing investment across radically different margin profiles and capital intensities.
Product Type:
End-use applications span single-serve beverages to bulk chemical containment, with wall thickness and alloy specification diverging sharply across the spectrum.
- Cans:Aluminum alloy 3104-H19 drawn and ironed bodies with separate ends dominate beverage filling lines. Craft breweries in the United States and sparkling water brands in Germany are compressing lead times and forcing smaller batch flexibility from suppliers.
- Drums:UN-certified steel constructions retain mandatory status for corrosive chemical transport where stacking strength and hazardous material compliance override lightweighting economics. German chemical clusters and Gulf Coast petrochemical corridors sustain dedicated drum production footprints.
- Tins:Tinplate formats serve specialty food and aerosol propellant applications where barrier performance commands premium positioning.
- Pails:Industrial lubricant and coating markets use handled steel or aluminum constructions for retail and professional trade channels.
Established volume favors cans; emerging adoption favors drums in specialized chemical logistics.
Application:
Regulatory chemistry restrictions and filling line speeds create divergent specification requirements across end-use categories.
- Beverage Packaging:High-speed aluminum can lines running at 2,000+ units per minute require precise flange tolerances and internal spray coating uniformity. Deposit-return system alignment in Germany and pending EU-wide harmonization are reshaping reverse logistics integration requirements.
- Food Packaging:Epoxy-phenolic and polyester internal coatings must prevent metal migration under FDA Title 21 CFR and EU food-contact frameworks. Acidic and high-sulfur content foods drive barrier specification divergence.
- Chemical Transport:UN certification for dangerous goods mandates specific steel grades and closure integrity testing.
- Industrial Storage:Non-regulated lubricants, coatings, and adhesives use lighter specification constructions with cost-optimized coating systems.
Beverage packaging commands the steepest capital intensity; food packaging faces the most complex multi-jurisdiction compliance burden.
End User:
Procurement scale and technical specification authority concentrate differently across customer categories.
- Beverage Companies:National brewers in the United States are consolidating supplier relationships from six to two approved can sources per production facility. Rail-served aluminum mill proximity determines contract awards in Midwest and Southeast production corridors.
- Food Manufacturers:Shelf-stable and retort applications require specialized internal coating qualification extending new product timelines by 8-14 months under dual FDA and SAMR testing protocols.
- Chemical Industry:Integrated petrochemical producers maintain captive drum fleets or long-term supply agreements with certified manufacturers.
- Pharmaceutical Sector:Aerosol and specialty tinplate formats for propellant-based drug delivery demand barrier-optimized internal coatings with batch traceability requirements.
Beverage companies drive volume consolidation; pharmaceutical sector requirements command the highest coating qualification overhead.
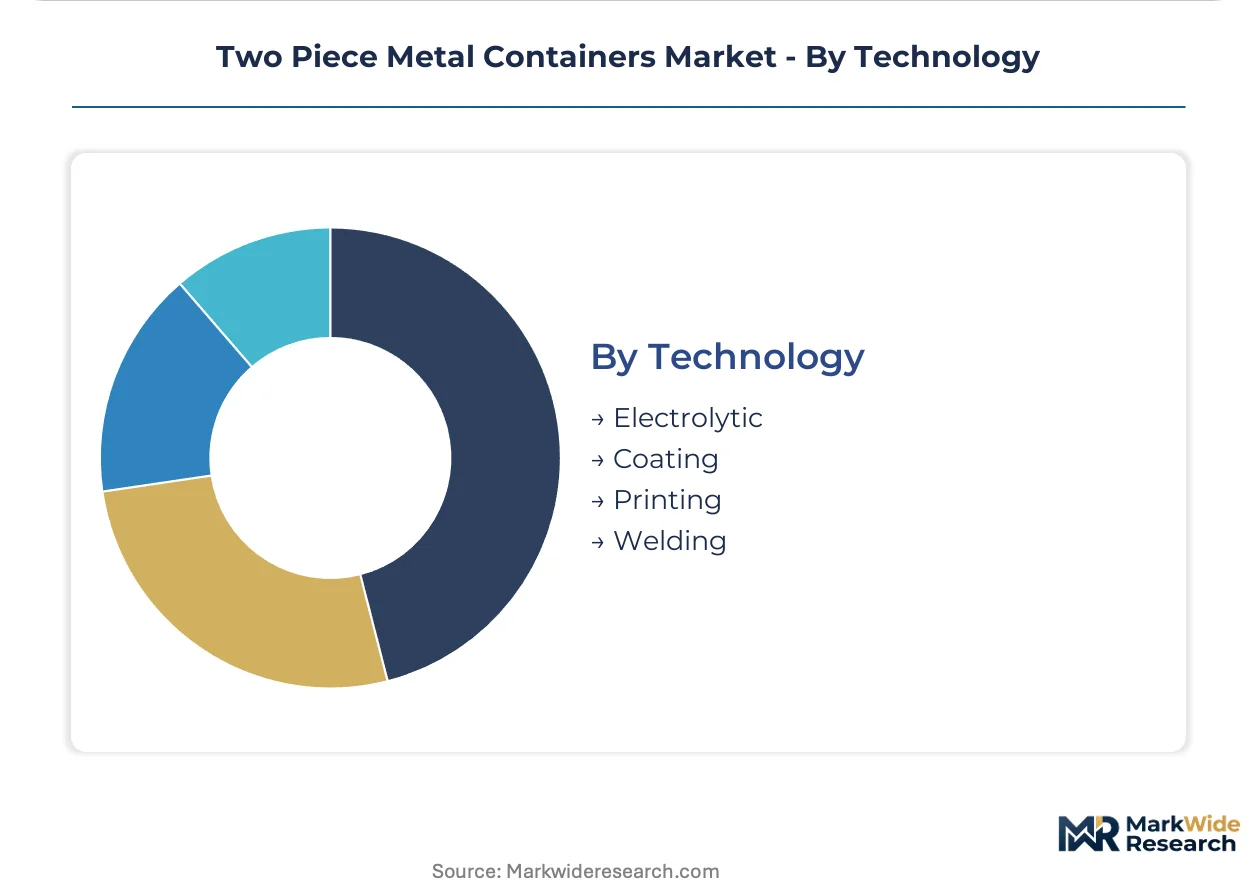
Technology:
Process capability differentiation separates commodity converters from specialty manufacturers.
- Coating:Internal spray application of epoxy-phenolic, polyester, or vinyl-organosol systems determines shelf stability and regulatory compliance. REACH-driven bisphenol-A phase-outs are accelerating polyester qualification for high-acid beverages.
- Electrolytic:Tin coating weight control on steel substrate governs corrosion resistance in food and aerosol applications.
- Printing:Direct-to-can inkjet decoration is collapsing minimum order quantities and enabling mass customization for seasonal beverage programs.
- Welding:Three-piece can side-seam technology retains relevance in certain food and industrial pail constructions where body integrity requirements exceed drawn-and-ironed capabilities.
Coating technology represents the critical margin pool; printing innovation is compressing batch economics fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German can exports flow into French and Benelux beverage filling networks, while Chinese aluminum coil shipments supply Southeast Asian can body converters. This trade architecture concentrates manufacturing investment near raw material terminals and high-speed filling corridors.
United States
Craft brewery density in Colorado and Michigan sustains demand for 12-ounce and 16-ounce aluminum formats with compressed lead times. EPA Clean Air Act standards govern volatile organic compound emissions from coating operations in Ohio and Texas production facilities. Midwest rail corridors linking aluminum mills to can plants in Illinois and Indiana determine contract awards for national brewers consolidating supplier lists.
Germany
Deposit-return system infrastructure creates asset-light entry paths for can producers plugging into established reverse logistics networks across Bavaria and North Rhine-Westphalia. EU Green Deal lightweighting mandates compress wall thickness specifications, forcing capital redeployment toward thinner-wall drawing equipment. The Rhine-Main chemical corridor sustains dedicated drum production for UN-certified hazardous material transport.
China
Sparkling water brands and regional beverage distributors in the Yangtze River Delta generate distributed demand for smaller-run can formats. SAMR enforcement of GB 4806.9-2023 tightens migration limit testing protocols for food-contact metals, complicating cross-border supply chains. Shandong Province hosts concentrated aluminum coil processing capacity serving domestic can body stock converters.
India
Personal care and household product brands in Maharashtra and Gujarat expand propellant-based packaging, opening volume for specialty tinplate formats. BIS standards govern food packaging metals alongside state-level environmental clearances for coating operations. The Delhi-Mumbai Industrial Corridor attracts aerosol can investment targeting domestic consumption growth.
Brazil
São Paulo beverage conglomerates standardize on aluminum cans for logistics efficiency and recycling economics in urban distribution networks. ANVISA regulates food-contact materials and migration limits for container linings in canned food exports. The Santos port complex anchors South American can end and closure supply flows to Argentine and Chilean filling operations.
Two Piece Metal Containers Market Competitive Landscape
On the supply side, the industry is consolidating around integrated aluminum producers and specialized coating technology providers. Tiered competitive positioning separates captive aluminum suppliers from independent converters dependent on spot coil markets. Two strategic archetypes dominate: vertically integrated beverage can specialists with rail-served mill access, and regional tinplate fabricators serving aerosol and specialty food niches. Capacity expansion and coating chemistry licensing represent the dominant competitive moves as manufacturers respond to bisphenol-A phase-out deadlines.
Among North American integrated producers, Ball Corporation and Crown Holdings Inc. exemplify the scale-driven archetype with captive aluminum supply chains. Silgan Containers LLC occupies a position within the specialty tinplate tier, serving aerosol and barrier-critical food applications where coating qualification overhead commands premium positioning. These three entities anchor the competitive structure through divergent substrate strategies rather than direct segment overlap.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings Inc. |
| Silgan Containers LLC |
| Ardagh Group |
| DS Containers |
| Trivium Packaging |
| DAIWA CAN COMPANY |
| Kian Joo Can Factory Berhad |
| Helvetia Packaging |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese aluminum coil processing is compressing margin predictability for can body stock converters, forcing suppliers toward fixed-price annual contracts and buyers toward rail-served mill proximity as the primary sourcing criterion.
Pricing Analysis
Current-generation drawn-and-ironed aluminum can technology commands premium positioning against prior-generation three-piece steel formats, while next-generation sub-0.008-inch wall thicknesses remain pre-commercial due to tooling engineering scarcity. Contract-based long-term offtake dominates volume procurement, with price differentiation driven by volume scale and rail-served aluminum mill proximity. Cost compression in standard 12-ounce beverage formats is intensifying because national brewers are consolidating approved supplier lists. Craft breweries exhibit highest price sensitivity due to batch-size inflexibility, while pharmaceutical aerosol buyers accept premium positioning for barrier-optimized coating qualification.
Supply Chain Analysis
Export-control scrutiny on advanced coating chemistries under REACH and EPA frameworks limits cross-border flows of bisphenol-A-containing formulations, accelerating regionalization of liner supply. Geographic concentration centers on China, the United States, and Germany for aluminum coil and can body production. Raw material dependencies rest on 3104-H19 aluminum alloy, tinplate steel substrate, and epoxy-phenolic or polyester resin systems. Single-source vulnerability concentrates in specialty chemical producers for internal spray coatings. Distribution runs through direct-store-delivery beverage networks and rail-linked aluminum mill corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deep-draw die design expertise for sub-0.008-inch wall thicknesses concentrates among a narrow cohort of retired specialists, creating a structural bottleneck that will determine competitive positioning across the next equipment replacement cycle.
For Market Incumbents: Pre-empt coating chemistry obsolescence by accelerating polyester and vinyl-organosol qualification ahead of ECHA bisphenol-A restrictions. Secure captive aluminum supply through backward integration into rail-served Midwest mill capacity to defend against spot coil volatility. Lock in multi-year supply agreements with regional craft breweries before digital printing capabilities democratize smaller-batch sourcing. For New Entrants and Emerging Players: Establish a beachhead in Indian and Southeast Asian aerosol tinplate segments where personal care propellant demand outpaces local barrier-coating capacity. Target Germany's deposit-return system infrastructure for asset-light market entry via reverse logistics partnerships rather than greenfield fabrication investment. Lead with direct-to-can inkjet decoration capabilities to collapse minimum order quantities for seasonal beverage programs. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across thinner-wall drawing and ironing equipment as EU Green Deal mandates force replacement cycles. Long-term viability favors vertically integrated specialists with captive aluminum supply and in-house recycling infrastructure over independent converters exposed to London Metal Exchange volatility. Watch for inflection when dual-jurisdiction FDA and SAMR certification timelines compress from 14 months toward 8 months as a signal of regulatory harmonization enabling cross-border scale.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Chemistry Reformulation | REACH-driven bisphenol-A phase-outs accelerate polyester qualification for high-acid beverage applications. |
| Backward Integration into Aluminum Supply | Rail-served mill proximity determines contract awards for national brewers consolidating supplier lists. |
| Digital Printing Capability Investment | Direct-to-can inkjet decoration collapses minimum order quantities for craft brewery seasonal programs. |
| Deposit-Return System Alignment | Germany's DRS infrastructure creates asset-light entry paths plugging into established reverse logistics networks. |
| Dual-Jurisdiction Certification Investment | Simultaneous FDA and SAMR compliance testing extends timelines but unlocks cross-border supply chain scale. |
Research Methodology
A spread of perspectives from can plant operations managers, beverage procurement directors, coating technology R&D leads, and aluminum mill sales executives converged on the working assumptions driving volume and value estimates. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, EPA emissions disclosures, EU ETS compliance data, and customs trade records for aluminum coil and tinplate movements. Bottom-up capacity utilization data from Ohio, Texas, and Shandong Province facilities was triangulated against top-down beverage production statistics.
Demand-supply balance modeling across the projection horizon incorporated segmentation by substrate type, end-use application, coating technology generation, and regional regulatory cluster. CAGRs were derived from installed capacity expansion schedules, replacement demand for thinner-wall equipment, and migration rates from glass to aluminum formats. Industry-specific inputs included London Metal Exchange aluminum price volatility bands, EPA Clean Air Act compliance cost trajectories, and ECHA restriction timeline scenarios for food-contact chemicals.
Stress conditions across primary aluminum price swings, coating resin supply disruptions, and dual-jurisdiction certification delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU Green Deal implementation pace and SAMR enforcement consistency for GB 4806.9-2023. Material shifts in REACH bisphenol-A restriction timelines or unexpected alloy substitution breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Specialty Tin Cans Market
Metal Packaging
Tin Cans Market
Metal Packaging
United Arab Emirates Metal Packaging Market
Metal Packaging
North America Metal Packaging Market
Metal Packaging
India Metal Packaging Market
Metal Packaging
Household Aluminum Foils Market
Metal Packaging
North America Aluminium Cans Market
Metal Packaging
Bi-Metal Cans Market
Metal Packaging
Aluminum Cans Market
Metal Packaging
Asia Pacific Metal Cans Market
Metal Packaging
Novelty Tins Market
Metal Packaging
Metal Packaging Coatings Market
Metal Packaging
Beverage Metal Cans Market
Metal Packaging
Aluminum Aerosol Cans Market
Metal Packaging
Vietnam Metal Can Packaging Market
Metal Packaging
Food Tins and Drink Cans Market