
 Octabin Market | 2026-2036
Octabin Market Size, Share, and Industry Trends Forecast 2026-2036
Octabin Market Analytics
Food industry demand for bulk dry-goods containment is expanding faster than chemical sector offtake as processors seek stackable, forklift-compatible alternatives to traditional drums. Smurfit Kappa leverages its European recycled fiber network to supply certified food-grade octabins to milling operations. DS Smith anchors its position through lightweight corrugated engineering that reduces freight cost per unit load. WestRock competes with integrated containerboard-to-converter operations across North American agricultural corridors.
An octabin is a large-format, octagonal corrugated bulk container typically constructed from triple-wall corrugated board with a laminated or coated inner ply, designed to hold between 500 kg and 1,500 kg of free-flowing dry material. Its geometry permits stable stacking up to three units high while allowing discharge through base apertures or liner valves. Standard octabins still occupy the highest volume share in food and chemical applications where commodity specifications dominate procurement. Collapsible octabins represent the fastest-growing configuration as return logistics programs at multinational packaging suppliers cut empty-backhaul cubic volume by roughly two-thirds. Paperboard material grades command the widest specification range, from virgin kraft liners for pharmaceutical containment to recycled-content fluting for non-food industrial loads.
FDA food-contact substance regulations in the United States and EU REACH chemical compliance requirements in Europe govern liner material selection and migration testing protocols for octabins handling regulated products. BIS certification for packaging materials in India adds a compliance layer for exporters serving pharmaceutical and food processing clients in that market. Stakeholders must monitor evolving extended producer responsibility frameworks, since pending revisions to EU Packaging and Packaging Waste Regulation will mandate minimum recycled content thresholds that reshape material sourcing and converter qualification criteria.
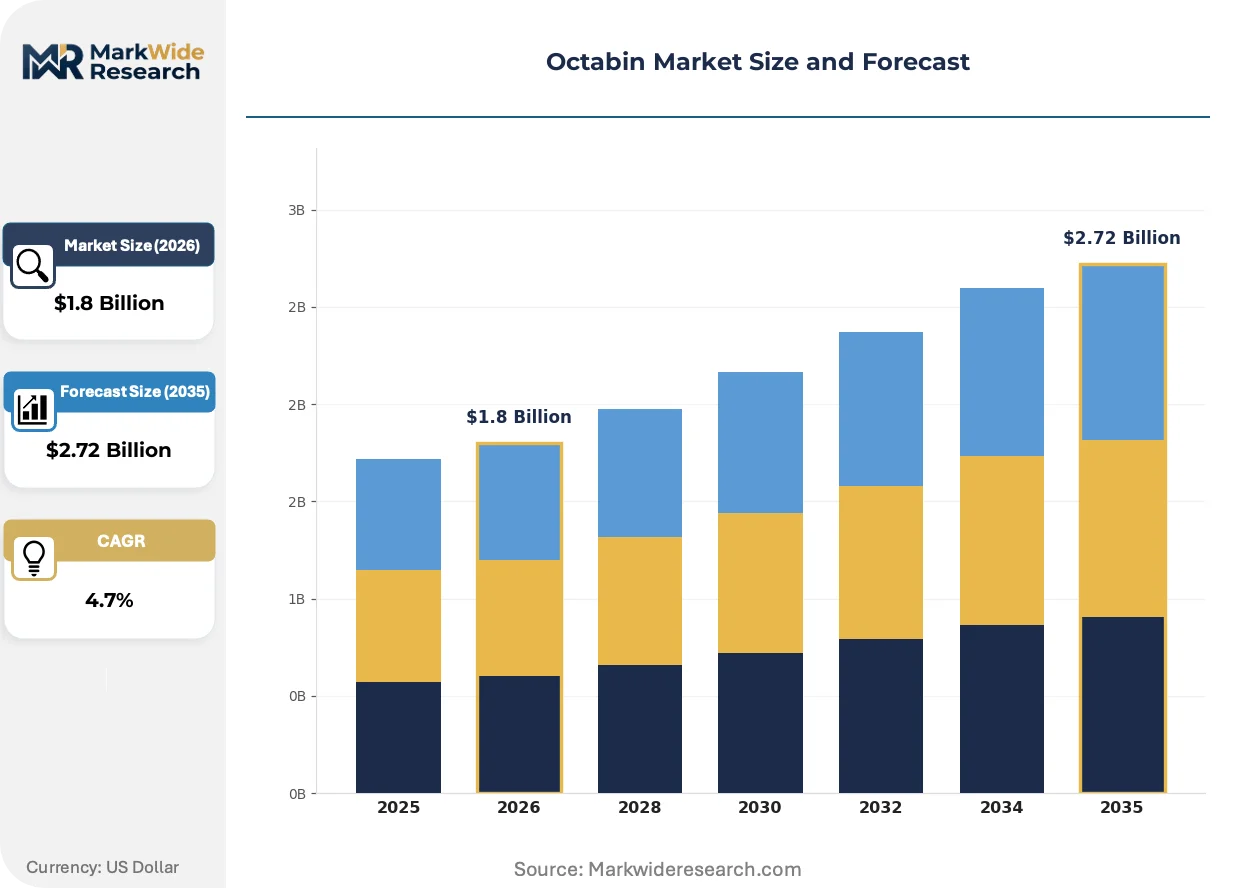
Market Dynamics
Food processors are consolidating intermediate bulk packaging procurement around stackable, forklift-compatible formats that reduce warehouse footprint and handling labor compared to traditional steel drums and flexible intermediate bulk containers.
Growth Catalysts
- EU Packaging Waste Directive compliance:REACH-aligned converters are accelerating recyclable paperboard octabin development to meet mandated recycled content thresholds and extended producer responsibility frameworks in Germany, France, and the Netherlands.
- Bulk grain handling automation:Milling operations across North American agricultural corridors are specifying octabins with integrated discharge valves and liner systems compatible with pneumatic conveying infrastructure.
- Pharmaceutical powder containment:FDA food-contact substance regulations are driving specification of virgin kraft linerboard constructions with migration-tested inner plies for active pharmaceutical ingredient intermediates.
Market Restraints
- Recycled fiber cost volatility:Old corrugated container feedstock prices fluctuate with municipal collection program yields and export demand from Asian packaging converters, compressing margin predictability for European producers.
- German converter concentration:Triple-wall board production and octabin fabrication capacity clusters disproportionately in Hamburg and the Rhine-Ruhr corridor, creating geographic supply risk and freight cost premiums for southern European buyers.
- Flexible IBC substitution:Polypropylene bulk bags retain cost advantage for single-use chemical and mineral applications where moisture protection and stacking strength requirements are less stringent.
Strategic Opportunities
- Indian pharmaceutical export packaging:BIS certification requirements for packaging materials serving pharmaceutical and food processing clients create qualified supplier scarcity that certified European and North American converters can exploit.
- Return logistics program expansion:Collapsible octabin configurations that reduce empty-backhaul cubic volume are penetrating multinational packaging supplier networks as sustainability metrics integrate into procurement scorecards.
- Lightweight corrugated engineering:DS Smith and similar engineered packaging specialists are developing reduced-basis-weight triple-wall constructions that maintain 1,500 kg load ratings while cutting material input and outbound freight cost per unit.
Industry Challenges
- Migration testing timeline compression:FDA and EFSA food-contact notification protocols for novel liner coatings and adhesive systems extend qualification cycles, delaying product launches for converters serving regulated end-uses.
- Triple-wall board press capacity constraints:Capital-intensive corrugator investments for heavy-duty flute combinations face long lead times and skilled technician shortages, limiting rapid capacity response to demand surges.
- Legacy drum handling infrastructure retrofit:Chemical processors with established steel drum filling, sealing, and tracking systems face integration friction when transitioning to octabin formats requiring different discharge equipment and inventory management protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Octabin Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Octabin, Custom Octabin, Collapsible Octabin, Printed Octabin Material: Cardboard, Plastic, Metal, Paperboard End User: Food Industry, Pharmaceutical, Chemicals, Packaging Suppliers Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | WestRock, Tri-Wall, Smurfit Kappa, Georgia-Pacific, Rengo Co., DS Smith, International Paper, VPK Packaging, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Octabin Market Evolving Landscape
Digital printing and smart labeling technologies are converging with lightweight structural engineering to transform octabin from commodity containment into traceable, brandable supply chain assets with embedded compliance documentation.
Coated and laminated inner ply technologies are expanding into pharmaceutical and high-humidity food applications where moisture vapor transmission rates must fall below strict thresholds. Active pharmaceutical ingredient manufacturers in Switzerland and Germany are specifying these constructions for hygroscopic powder containment. The technology is expanding into segments previously dominated by multi-wall paper bags with polyethylene liners, compressing total packaging cost per kilogram of contained product.
Pending revisions to the EU Packaging and Packaging Waste Regulation are mandating minimum recycled content thresholds that reshape material sourcing and converter qualification criteria. European converters must document post-consumer fiber percentages and demonstrate compliance with extended producer responsibility frameworks to maintain approved supplier status. Food-grade octabin specifications in Germany, France, and Italy are most affected, with buyers now requiring third-party chain-of-custody certification alongside traditional performance testing.
Consolidated procurement functions at multinational food and chemical processors are unbundling packaging specification from logistics execution, creating direct relationships with converters that displace traditional distribution intermediaries. Category managers in agricultural processing and specialty chemicals are centralizing octabin sourcing across regional manufacturing networks, demanding volume-based pricing transparency and sustainability documentation that distributors struggle to provide. This pattern is most visible in North American grain handling and European compound feed manufacturing, where procurement teams now engage converters on multi-year framework agreements with embedded cost reduction mechanisms.
Octabin Market Segmentation
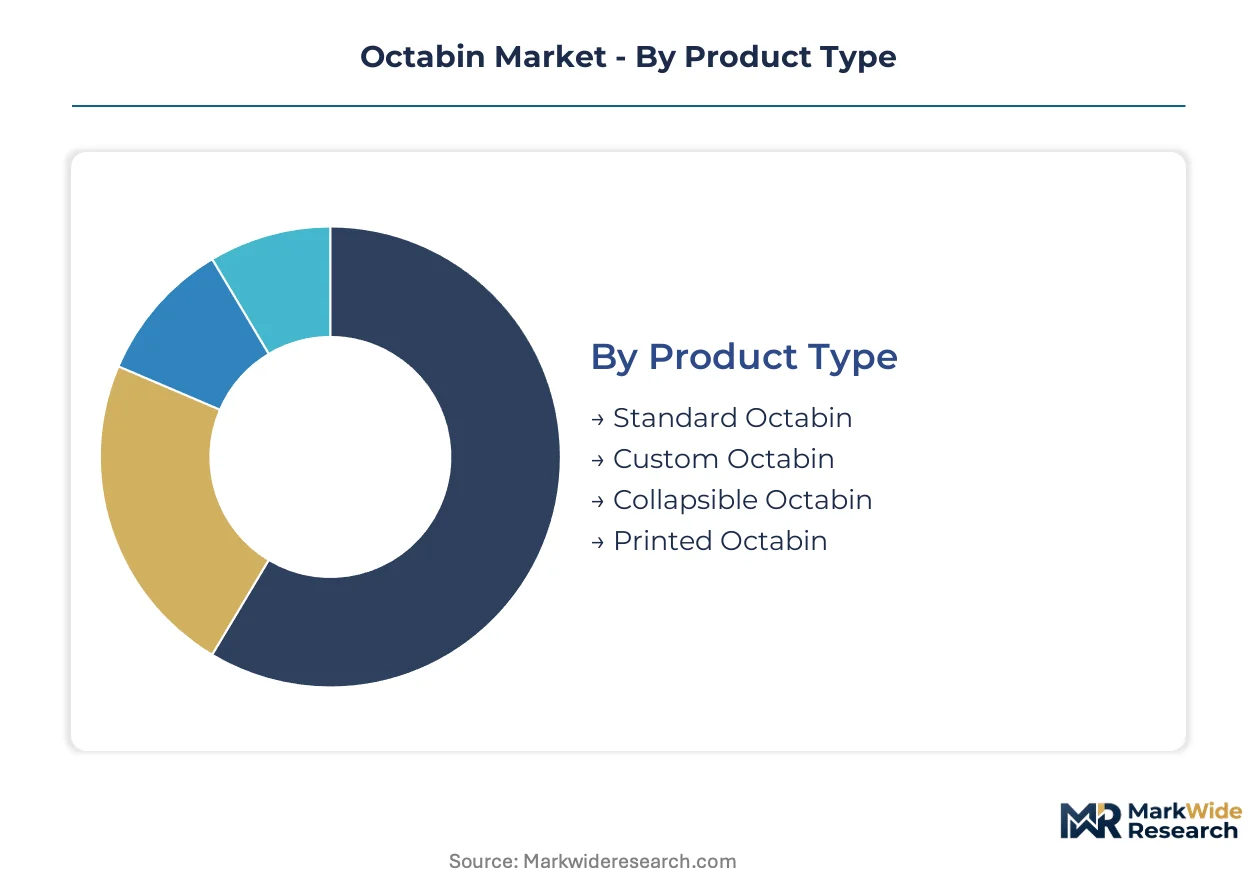
Octabin procurement patterns diverge sharply between commodity bulk handling and precision-regulated containment, with product configuration, material specification, and channel structure each reshaping supplier relationships and margin profiles across food, pharmaceutical, and chemical verticals.
Product Type:
Standard octabins dominate standalone bulk commodity applications where interchangeability drives procurement, while collapsible and custom configurations embed into return logistics programs and specialized discharge systems.
- Standard Octabin:Fixed octagonal geometry with triple-wall corrugated construction and base discharge apertures serves grain milling and mineral processing where forklift stacking and rapid filling speed take priority over customization. North American agricultural corridors and Rhine-Ruhr chemical clusters account for the heaviest volume placements due to established drum-to-octabin conversion programs.
- Collapsible Octabin:Fold-flat designs with reinforced corner posts and detachable bases reduce empty-backhaul cubic volume by roughly two-thirds, enabling return logistics economics at multinational packaging suppliers. DS Smith and Smurfit Kappa have integrated these configurations into closed-loop rental programs for European compound feed manufacturers.
- Custom Octabin:Tailored dimensions and discharge valve positioning serve pharmaceutical powder handling with pneumatic conveying integration.
- Printed Octabin:Direct digital or flexographic branding supports traceability and compliance documentation in food-grade supply chains.
Volume placements concentrate in Standard Octabin; the faster expansion belongs to Collapsible Octabin.
Material:
Material selection maps directly to regulatory exposure, with food-contact and pharmaceutical applications demanding virgin fiber traceability while industrial chemical loads tolerate higher recycled content.
- Paperboard:Triple-wall constructions with laminated or coated inner plies span the widest specification range, from virgin kraft liners for FDA-regulated pharmaceutical containment to recycled-content fluting for non-food industrial loads. German converters around Hamburg leverage integrated containerboard mills to supply certified food-grade constructions.
- Cardboard:Double-wall and single-wall corrugated grades serve lighter-duty applications with load ratings below 500 kg.
- Plastic:Polypropylene and polyethylene octabins penetrate chemical and mineral segments where moisture protection exceeds paperboard capabilities.
- Metal:Steel-reinforced hybrid constructions address extreme load requirements in heavy mineral and metal powder handling.
Procurement volume clusters in Paperboard; Plastic is climbing the fastest as moisture-critical chemical applications expand.
End User:
End-use segmentation reveals divergent compliance burdens, with food and pharmaceutical buyers imposing migration testing and chain-of-custody requirements that chemical processors rarely match.
- Food Industry:Grain milling, compound feed manufacturing, and dry ingredient processing drive specification of stackable, forklift-compatible formats with integrated liner systems. EU Packaging and Packaging Waste Regulation compliance pressures are accelerating demand for certified recycled content and extended producer responsibility documentation.
- Pharmaceutical:Active pharmaceutical ingredient and excipient containment requires virgin kraft linerboard with migration-tested inner plies under FDA food-contact substance regulations. Swiss and German manufacturers specify coated constructions for hygroscopic powder handling.
- Chemicals:Mineral, fertilizer, and specialty chemical applications prioritize cost efficiency and moisture protection over regulatory certification.
- Packaging Suppliers:Rental program operators and logistics integrators source collapsible configurations for closed-loop asset management.
Food Industry holds the dominant placement share; Pharmaceutical generates the steepest expansion trajectory.
Distribution Channel:
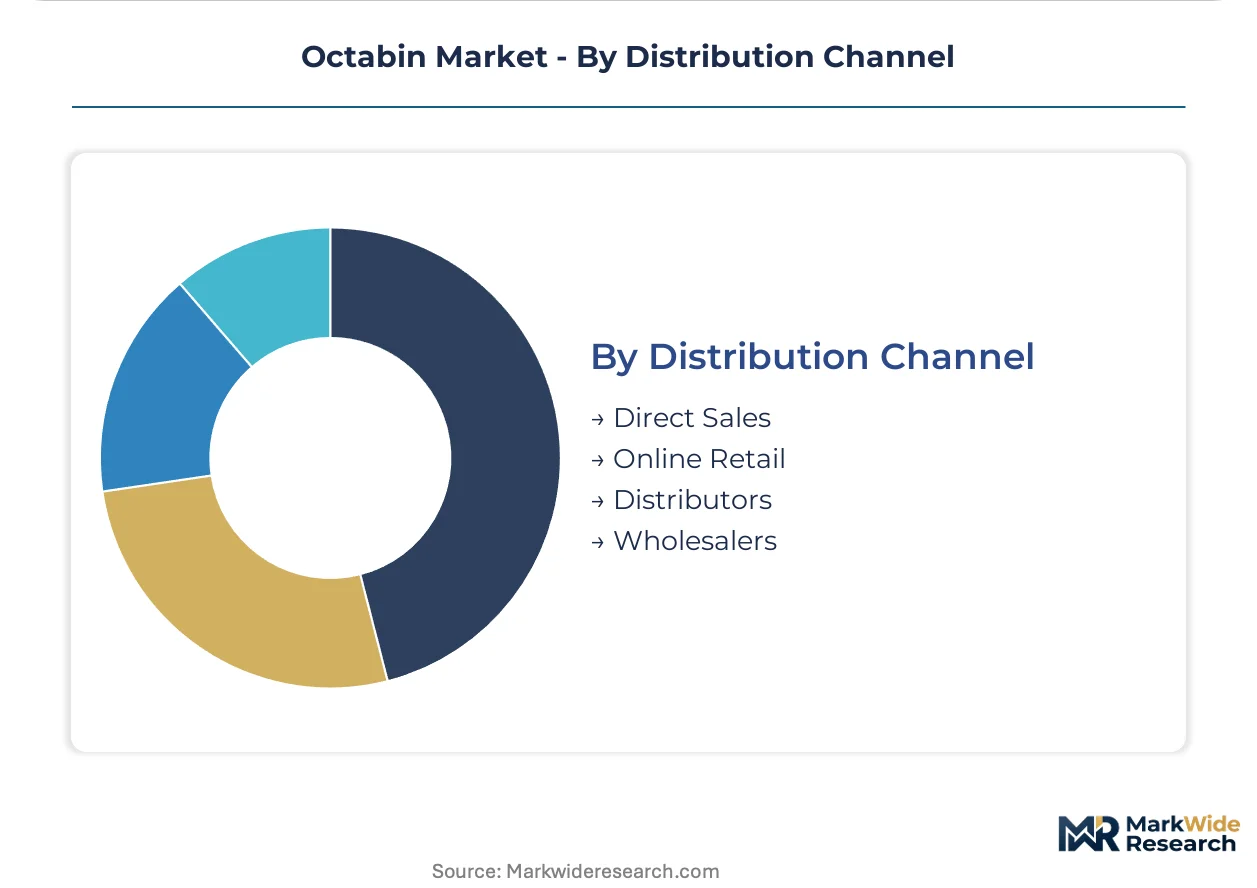
Channel structure is fragmenting as consolidated procurement functions at multinational processors bypass traditional intermediaries to engage converters directly on multi-year framework agreements.
- Direct Sales:Converter-direct relationships deliver volume-based pricing transparency and sustainability documentation that agricultural processing and specialty chemical procurement teams demand. North American grain handling and European compound feed manufacturing have shifted most volume to this channel.
- Distributors:Regional packaging distributors retain relevance for mid-tier chemical processors and smaller milling operations requiring technical support and inventory buffering.
- Online Retail:Digital procurement platforms serve spot buyers and smaller-scale users with standardized specifications.
- Wholesalers:Bulk resellers move commodity-grade octabins to price-sensitive industrial segments with minimal service attachment.
Direct Sales commands the volume concentration; Online Retail is gaining share fastest among smaller processors digitizing procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr corridor's industrial packaging cluster benefits from Germany's Energiewende tax incentives for sustainable manufacturing, concentrating triple-wall board production and octabin fabrication capacity in a narrow geographic band that shapes continental supply patterns.
Germany
Compound feed manufacturers in Lower Saxony and grain millers across Bavaria drive specification of collapsible octabins with integrated liner systems. REACH compliance mandates and the EU Packaging Waste Directive push Hamburg-area converters toward certified recycled-content constructions. The Rhine-Ruhr corridor hosts the densest concentration of heavy-duty corrugator capacity serving food-grade and chemical applications.
United States
Agricultural processors across Iowa, Illinois, and Nebraska are consolidating procurement around stackable formats compatible with pneumatic conveying infrastructure. FDA food-contact substance regulations govern liner material selection for pharmaceutical powder containment applications. The Pacific Northwest timber base supplies virgin kraft linerboard to WestRock and Georgia-Pacific operations serving West Coast chemical and food clients.
India
Pharmaceutical exporters in Maharashtra and Gujarat face BIS certification requirements for packaging materials serving regulated end-uses. The FSSAI and CDSCO impose parallel compliance burdens on food and active pharmaceutical ingredient shipments. Mumbai-Pune industrial corridor converters are qualifying for European and North American buyer audits to capture contract manufacturing packaging demand.
Switzerland
Swissmedic-regulated active pharmaceutical ingredient manufacturers in Basel and Zurich specify coated inner ply constructions for hygroscopic powder containment. The country's pharmaceutical cluster demands migration-tested virgin kraft linerboard with documented chain-of-custody certification. Basel-area logistics integrators operate closed-loop collapsible octabin rental programs for cross-border compound feed and specialty chemical movements.
France
Grain cooperatives in the Paris Basin and compound feed manufacturers in Brittany are adopting octabin formats to reduce warehouse footprint versus traditional steel drums. ANSM pharmaceutical regulations and EFSA food-contact protocols shape liner specification for regulated applications. The Hauts-de-France region's proximity to Belgian and German converter capacity creates procurement optionality for northern French industrial buyers.
Octabin Market Competitive Landscape
Top-tier vendors anchor integrated containerboard-to-converter operations, while mid-tier specialists compete on lightweight engineering and regional logistics proximity. The vendor base stratifies across three layers: multinational paperboard conglomerates with captive fiber supply, engineered packaging specialists focused on structural optimization, and regional fabricators serving price-sensitive commodity segments. Dominant competitive moves include capacity expansion in triple-wall corrugator installations and strategic partnerships between converters and multinational food processors for closed-loop rental program deployment.
Among European-based integrated producers, Smurfit Kappa and DS Smith exemplify the engineered packaging specialist archetype, with the former leveraging recycled fiber network density and the latter advancing lightweight corrugated constructions. WestRock anchors the North American integrated tier through containerboard-to-converter operations across agricultural corridors. Tri-Wall represents the heavy-duty industrial specialist segment with Asia-Pacific manufacturing footprint.
| Leading Market Players |
|---|
| WestRock |
| Tri-Wall |
| Smurfit Kappa |
| Georgia-Pacific |
| Rengo Co. |
| DS Smith |
| International Paper |
| VPK Packaging |
| Mondi Group |
| Others |
Value Network & Pricing Analysis
EU Packaging and Packaging Waste Regulation recycled content mandates gate qualified supply access and premium-tier pricing power, as converters lacking third-party chain-of-custody certification face exclusion from German and French food-grade procurement while certified suppliers capture margin premiums on REACH-aligned constructions.
Pricing Analysis
Short lead-time premiums distinguish the pricing landscape, with German converters around Hamburg commanding 15-20% markups for expedited triple-wall board delivery to southern European buyers while spot inventory of standard-grade octabins trades at discounted clearing levels. Three-tier pricing structure across certified food-grade, industrial-grade, and commodity spot levels separates procurement tiers, with virgin kraft linerboard constructions for pharmaceutical applications sitting at the premium extreme and recycled-content fluting for mineral handling at the base. Cost compression in industrial-grade segments is intensifying because Asian export demand for old corrugated container feedstock squeezes European converter margins. Mid-tier chemical processors exhibit the highest price sensitivity, while Swiss pharmaceutical manufacturers demonstrate minimal elasticity given regulatory compliance imperatives.
Supply Chain Analysis
Skilled technician shortages at heavy-duty corrugator operations in Germany, the United States, and India constrain rapid capacity scaling for triple-wall board production serving octabin fabrication. Raw material sourcing draws from Scandinavian pulp mills for virgin kraft linerboard, municipal collection programs across Europe for recycled fiber feedstock, and adhesive resin suppliers concentrated in the Rhine-Ruhr chemical cluster. Single-source vulnerability pervades the Hamburg-Rhine-Ruhr corridor where triple-wall capacity concentrates, exposing continental buyers to disruption risk from localized logistics constraints or energy price spikes. Distribution runs through converter-direct relationships for multinational food and chemical processors, with regional distributors retaining relevance for smaller milling operations requiring technical support and inventory buffering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as pending EU extended producer responsibility frameworks force sub-scale converters lacking certification infrastructure toward exit or acquisition.
For Market Incumbents: Cement market position through backward integration into containerboard production and captive recycled fiber collection networks, insulating margin structures from OCC price volatility while building the certification infrastructure that REACH-aligned buyers now mandate as a threshold qualification. Capacity addition in southern European geographies addresses the freight cost premium vulnerability that Hamburg-Rhine-Ruhr concentration creates for Italian and Spanish compound feed manufacturers. For New Entrants and Emerging Players: Logistics integrators operating closed-loop rental programs represent the most accessible channel partner type for penetrating the collapsible octabin segment without competing head-to-head against integrated containerboard conglomerates. Indian pharmaceutical export packaging offers the most penetrable white-space target, where BIS certification requirements create qualified supplier scarcity that certified European converters can exploit through Mumbai-Pune corridor partnerships. A certification-first go-to-market angle—securing FDA food-contact substance and EU REACH compliance before commercial launch—differentiates entrants against commodity-grade regional fabricators. For Investors and Strategic Acquirers: First-mover collapsible octabin rental program deployments by multinational packaging suppliers is the leading indicator that return logistics economics have crossed threshold viability and that asset-light platform models will displace traditional transactional supply relationships. The five-to-ten-year viability window favors converters with integrated containerboard-to-finished-goods operations and established pharmaceutical certification track records. Acquisition targets should emphasize engineered packaging specialists with lightweight corrugated R&D capabilities and existing closed-loop logistics partnerships.| Strategic Initiative | Industry Significance |
|---|---|
| Triple-Wall Corrugator Capacity Expansion | Heavy-duty flute combinations in Hamburg and Rhine-Ruhr address southern European supply gaps. |
| Backward Integration into Recycled Fiber Collection | Captive OCC sourcing insulates margin predictability from Asian export demand volatility. |
| Closed-Loop Rental Program Deployment | DS Smith and Smurfit Kappa models demonstrate return logistics economics at multinational compound feed manufacturers. |
| Pharmaceutical Certification Investment | FDA food-contact substance and Swissmedic compliance unlocks Basel-Zurich API containment demand. |
| Lightweight Structural Engineering R&D | Reduced-basis-weight triple-wall constructions cut material input while maintaining 1,500 kg load ratings. |
Research Methodology
Multi-period observation of converter capacity utilization, OCC feedstock price movements, and regulatory compliance certification rates anchored the trend analysis, supplemented by interviews with plant managers at European triple-wall corrugator operations, procurement leads at North American grain milling conglomerates, distribution channel partners in the Mumbai-Pune industrial corridor, and technical R&D directors at engineered packaging specialists. Secondary validation drew from customs and trade data tracking octabin and linerboard cross-border movements, Cefic and AF&PA industry association reports, SEC 10-K filings of integrated paperboard producers, and EU ECHA regulatory submission databases. Bottom-up demand modeling across food, pharmaceutical, and chemical end-uses triangulated against top-down supply-side capacity assessments.
Segment-weighting approaches distributed value and volume projections across product type (standard, collapsible, custom, printed), material grade (virgin kraft, recycled-content, coated constructions), end-use vertical (food, pharmaceutical, chemical, packaging supplier), and distribution channel (direct sales, distributor, online retail, wholesaler). CAGRs were derived from regression analysis of historical placement trends and forward projection of regulatory compliance deadlines and return logistics program penetration. Industry-specific forecast inputs incorporated pharmaceutical powder handling automation rates and pneumatic conveying infrastructure deployment across North American agricultural corridors.
Caveats apply where recycled fiber cost volatility, triple-wall corrugator capacity expansion delays, or migration testing timeline extensions for novel liner coatings could materially shift the outlook. Forecasts reflect assumptions about regulatory implementation schedules and buyer procurement consolidation trajectories. Material deviation in EU Packaging and Packaging Waste Regulation enforcement stringency or FDA food-contact notification processing speeds warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Conical Bags Packaging Market
Bags and Containers
Loose-Fill Peanuts Market
Bags and Containers
Conical Top Bulk Bag Market
Bags and Containers
BOPP Bags Market
Bags and Containers
Textile Bags Market
Bags and Containers
2 Loop FIBC Bags Market
Bags and Containers
Child Resistant Bags Market
Bags and Containers
Bulk Bag Unloaders Market
Bags and Containers
Breathable Bags Market
Bags and Containers
Household and Cleaning Container Market
Bags and Containers
On the Go Packaging Market
Bags and Containers
Conductive Bags Market
Bags and Containers
Wooden Boxes Market
Bags and Containers
Self-Sealing Ziplock Bags Market
Bags and Containers
Double Zipper Bags Market
Bags and Containers
Global PP Jumbo Bags Market