
 Drink Carrier Poly Bags Market | 2026-2036
Drink Carrier Poly Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Drink Carrier Poly Bags Market Foresight
Skilled polymer engineering talent is rotating toward sustainable material formulations faster than conventional polyethylene expertise can backfill, creating a workforce bottleneck that favors early movers in bioplastic conversion. Novolex leverages its integrated film extrusion and converting footprint to control resin-to-bag cost curves across North American quick-service accounts. International Paper Company anchors its position through hybrid fiber-polymer carrier systems that bridge paper sustainability messaging with poly bag durability. Smurfit Kappa Group competes via European circular-economy certifications that unlock procurement contracts with sustainability-mandated foodservice chains.
Drink carrier poly bags are thermoplastic film enclosures engineered to transport multiple beverage containers simultaneously, typically fabricated from LDPE or HDPE at gauges between 1.5 and 3.0 mils with die-cut handles or welded seams rated for liquid weight loads. Gusseted bag configurations dominate commercial procurement due to expanded cubic capacity for irregular cup sizes, while biodegradable material formulations represent the fastest-expanding segment as foodservice operators pre-empt regulatory bans on conventional plastics. Flat bags remain the mature volume baseline in cost-sensitive retail channels where standardization outweighs premium feature requirements.
EPA guidelines on recycled content claims and FDA food-contact material standards jointly shape product development pathways for domestic manufacturers, while EU REACH chemical restrictions and the EU Green Deal's packaging waste targets are redirecting export-oriented production toward certified compostable resin streams. Stakeholders must monitor how fragmented municipal bag-ban ordinances across U.S. states interact with emerging federal preemption debates to determine whether centralized or decentralized compliance investments yield superior returns.
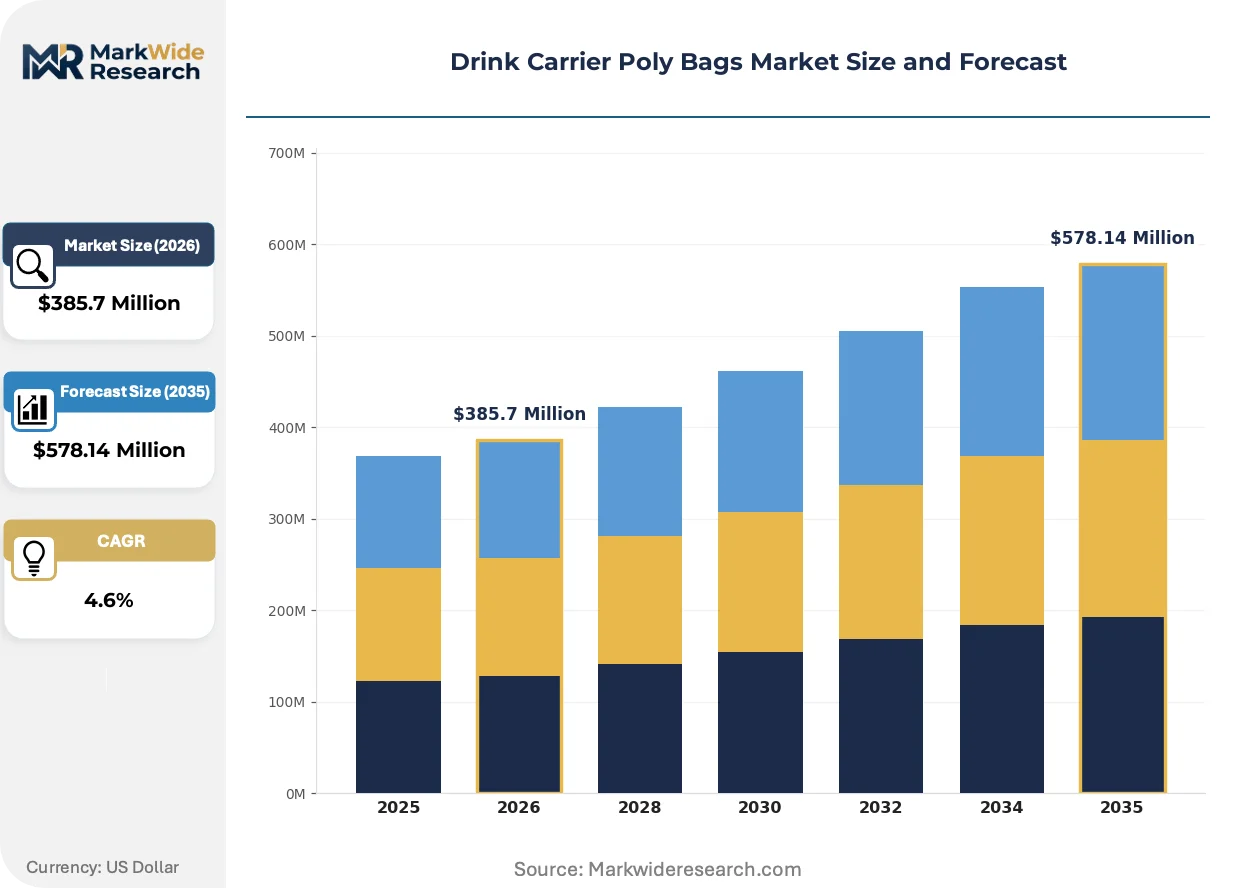
Market Dynamics
The EU Single-Use Plastics Directive is compressing demand for conventional polyethylene carriers while accelerating bioplastic formulation R&D across European converters. This regulatory pivot is redrawing material specifications and procurement criteria faster than supply chains can reconfigure.
Growth Catalysts
- Urban food delivery platforms:Bubble tea chains and quick-service operators in China are scaling carrier procurement volumes as on-demand beverage delivery penetrates tier-two cities. This demand concentration is pulling film extrusion capacity toward Asia-Pacific.
- REACH chemical restrictions:ECHA's expanding substance restrictions are disqualifying legacy plasticizers from EU food-contact applications. Manufacturers are reformulating toward certified compostable resin streams to maintain market access.
- Quick-service restaurant takeout expansion:US quick-service operators are hardwiring single-use beverage carriers into their off-premise operating models. This operational dependency sustains baseline demand even as material specifications tighten.
Market Restraints
- Resin cost volatility:Bio-based PLA and PBAT feedstocks trade at premiums to fossil-derived polyethylene. Price spreads compress converter margins and deter mass-market adoption.
- Composting infrastructure gaps:Industrial composting facility coverage remains sparse outside Western Europe and select US coastal corridors. Certified compostable carriers often route to landfill, undermining their environmental value proposition.
- Performance trade-offs:Biodegradable films at equivalent gauges exhibit lower puncture resistance and moisture barrier properties versus conventional LDPE. Foodservice operators resist specification changes where leakage risks escalate.
Strategic Opportunities
- India's quick-service penetration:Western and Indian quick-service chains are expanding drive-thru and delivery formats in Indian metros. Local film converters can capture carrier demand before multinational suppliers establish footprint.
- Hybrid fiber-polymer systems:Paperboard-polymer laminates bridge sustainability messaging with liquid containment performance. Quick-service chains seeking plastic reduction without functional compromise represent a receptive buyer segment.
- EU Green Deal packaging targets:Mandatory recycled content thresholds and extended producer responsibility fees are creating procurement preference for circular-economy-certified suppliers. Early certification investments unlock contract access with sustainability-mandated foodservice chains.
Industry Challenges
- Polymer engineering talent scarcity:Skilled formulators are rotating toward sustainable material development faster than conventional polyethylene expertise can backfill. Workforce bottlenecks delay bioplastic conversion timelines for mid-tier converters.
- Fragmented municipal compliance:US state and city bag-ban ordinances vary in scope, material exemptions, and enforcement mechanisms. Manufacturers face decentralized compliance investments without federal preemption clarity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drink Carrier Poly Bags Market |
| Market Size in 2026 | $385.7 Million |
| Market Size in 2035 | $578.14 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Gusseted Bags, Biodegradable Bags, Reusable Bags Material: LDPE, HDPE, Bioplastic, Recycled Plastic End User: Retail Stores, Restaurants, Event Venues, Catering Services Size: Small, Medium, Large, Custom |
| Companies Covered | Novolex, International Paper Company, Smurfit Kappa Group, A-Pac Manufacturing, Trioworld Group, Rutan Poly Industries, Rishaba Poly Product, Amcor Limited, Kazuo Beyin Paper and Plastic Packing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drink Carrier Poly Bags Market Shifts & Advancements
Material science advances and regulatory compression are converging to redefine carrier specifications. Three developments are actively reshaping competitive positioning and procurement criteria across foodservice channels.
Multi-layer coextrusion technology is miniaturizing film gauges while maintaining load-bearing capacity for beverage weights. Quick-service chains in the United States are specifying 1.5-mil constructions versus legacy 2.5-mil standards to reduce material intensity per unit. This gauge compression is miniaturizing resin consumption per carrier without sacrificing functional performance.
REACH Annex XVII restrictions on intentionally added microplastics are compelling reformulation of conventional polyethylene additives. European converters are eliminating slip agents and anti-block compounds that fail ECHA's biodegradability screening criteria. Food-contact certification timelines are extending as manufacturers resubmit formulations for EFSA compliance review.
Direct procurement relationships between quick-service chains and film converters are displacing distributor intermediaries in high-volume accounts. Large US-based restaurant operators are negotiating resin-indexed pricing and captive capacity allocations. This channel consolidation is most visible in the quick-service segment, where annual carrier volumes justify dedicated extrusion lines.
Drink Carrier Poly Bags Market Segmentation
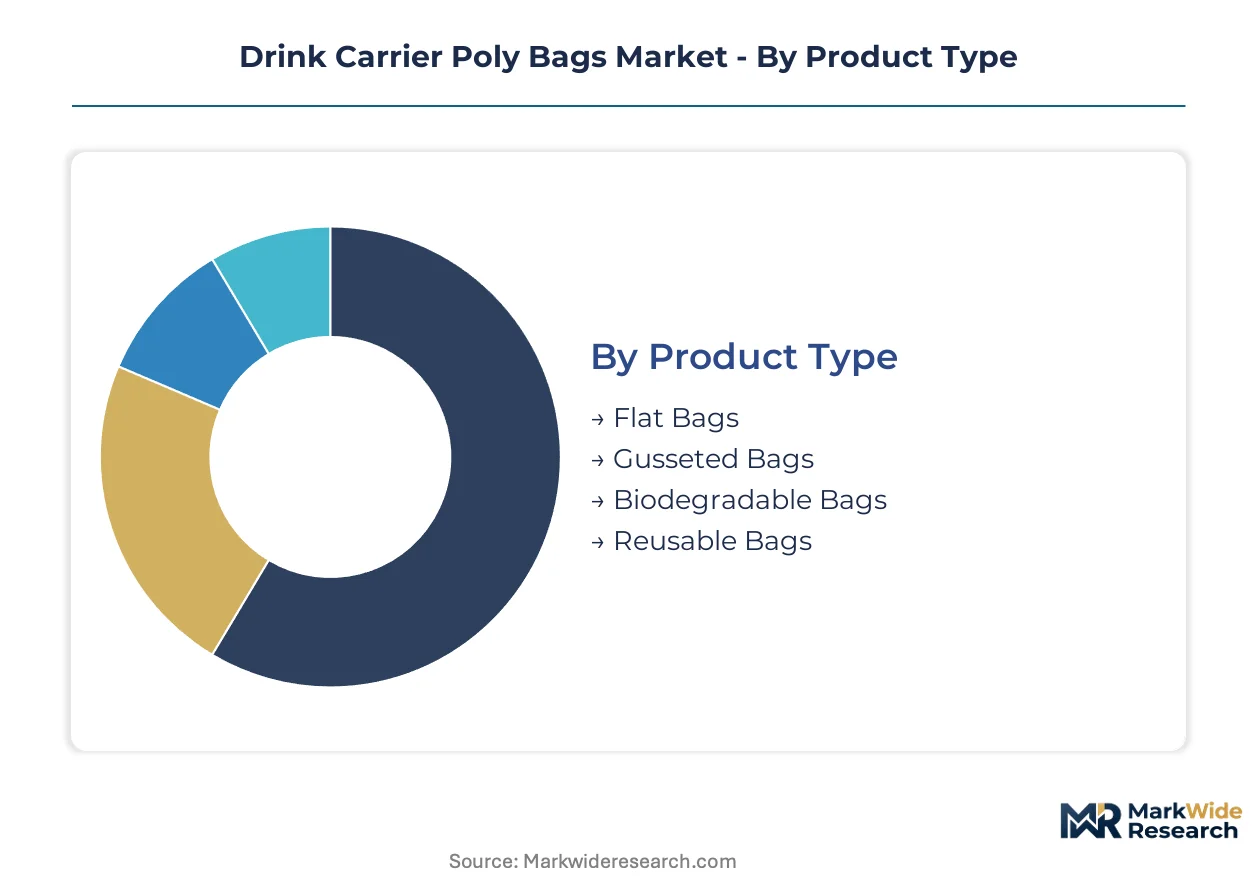
Segmentation in drink carrier poly bags determines resin selection, gauge specifications, and sustainability certifications required by procurement teams. Channel-specific requirements from quick-service chains, retail distributors, and event operators create distinct demand profiles that shape converter capacity allocation and margin structures.
Product Type:
Channel mix varies sharply by product configuration: quick-service chains specify gusseted formats through direct converter relationships, while retail distributors source flat bags via wholesale intermediaries. Biodegradable variants flow through sustainability-mandated procurement channels, and reusable formats concentrate in corporate catering and institutional accounts.
- Flat Bags:Single-layer LDPE or HDPE constructions at 1.5-2.0 mil gauges with die-cut handles serve standardized cup sizes. US retail distributors and cost-sensitive convenience store chains specify these for high-volume, low-complexity applications where unit economics outweigh premium features.
- Gusseted Bags:Side-folded constructions expand cubic capacity by 40-60% versus flat equivalents, accommodating irregular bubble tea cup profiles and multi-size beverage combinations. Chinese food delivery platforms and US quick-service operators with diverse menu portfolios drive specification intensity here.
- Biodegradable Bags:PLA, PBAT, or starch-blend formulations certified to EN 13432 or ASTM D6400 standards serve EU-regulated markets and US coastal jurisdictions with bag-ban ordinances.
- Reusable Bags:Woven polypropylene or heavy-gauge LDPE constructions rated for 50+ use cycles target corporate catering accounts and stadium concession operators with closed-loop inventory systems.
Flat bags dominate installed base across retail and convenience channels. Gusseted configurations are where expansion concentrates as beverage format diversification accelerates.
Material:
Cost tier stratification separates fossil-derived commodity resins from certified sustainable alternatives, with recycled-content formulations occupying a mid-tier position constrained by FDA food-contact certification timelines and batch consistency requirements.
- LDPE:Low-density polyethylene at melt indices of 2-10 g/10min delivers puncture resistance and heat-seal integrity for hot beverage applications. US quick-service chains and Chinese delivery platforms specify LDPE for its balance of clarity, flexibility, and extrusion throughput efficiency.
- HDPE:High-density polyethylene offers 25-35% higher tensile strength than LDPE at equivalent gauges, enabling downgauging to 1.5-mil constructions. European converters facing EU Green Deal packaging targets favor HDPE for its compatibility with mechanical recycling streams and lower carbon intensity per functional unit.
- Bioplastic:PLA derived from corn starch or PBAT from adipic acid and butanediol serve compostable-certified applications. Price premiums of 2-4x versus conventional polyethylene restrict penetration to regulatory-mandated procurement channels.
- Recycled Plastic:Post-consumer recycled (PCR) content at 25-50% loadings requires FDA food-contact notification for direct beverage contact. California's SB 54 and EU packaging waste directives are accelerating specification shifts toward verified PCR content.
LDPE and HDPE dominate installed base across conventional foodservice procurement. Bioplastic and recycled-content formulations are climbing the fastest as regulatory thresholds tighten.
End User:
Application-driven segmentation separates high-frequency, standardized procurement from event-driven, custom-specified demand with volatile seasonality and shorter lead-time tolerance.
- Retail Stores:Supermarkets, convenience chains, and liquor stores specify standardized flat or gusseted formats through distributor intermediaries. Volume concentration among top-10 US grocery chains creates procurement leverage that compresses converter margins.
- Restaurants:Quick-service and full-service operators represent the highest-specification segment, with direct converter relationships, resin-indexed pricing, and captive capacity allocations. US-based quick-service chains with 10,000+ unit footprints negotiate annual volume commitments.
- Event Venues:Stadiums, arenas, and concert halls require seasonal surge capacity and custom-printed branding specifications. Procurement concentrates in 4-6 month windows preceding major event calendars.
- Catering Services:Corporate and institutional caterers balance cost control with sustainability messaging, often specifying hybrid fiber-polymer carriers or certified compostable alternatives for client-facing delivery.
Restaurants dominate installed base by procurement value. Event venues represent the most volatile expansion trajectory as live entertainment scheduling normalizes post-pandemic.
Size:
Volume segmentation tracks beverage count capacity and cup diameter accommodation, with custom specifications capturing premium margin opportunities from branded quick-service chains requiring dimensional precision for automated packaging lines.
- Small:2-cup capacity configurations at 8-10 inch widths serve single-serve coffee and bubble tea delivery. Urban food delivery platforms in Chinese tier-two cities are scaling small-format procurement as on-demand beverage penetration deepens.
- Medium:4-cup capacity at 12-14 inch widths represents the commercial baseline for family meal delivery and office catering. US quick-service chains standardize on medium formats for combo meal packaging.
- Large:6-8 cup configurations target group catering and institutional foodservice. HDPE specifications predominate here for load-bearing requirements exceeding 5 kilograms.
- Custom:Dimensional specifications matched to proprietary cup profiles, automated filling equipment, or branded print requirements. Direct converter relationships bypass distributor markups for accounts with sufficient volume to justify dedicated extrusion die investments.
Medium formats dominate installed base across standardized foodservice procurement. Custom specifications are gaining share fastest as quick-service chains differentiate through proprietary packaging systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Chinese manufacturing clusters where film extrusion capacity scales aggressively, while European converters absorb compliance premiums from REACH and EU Green Deal mandates that inflate unit costs by double-digit percentages.
United States
Quick-service restaurant chains with 10,000-plus unit footprints drive carrier procurement through direct converter relationships with resin-indexed pricing. FDA food-contact material standards and EPA recycled content guidelines shape formulation decisions for domestic manufacturers. Film extrusion capacity clusters in the Midwest and Southeast serve national distribution networks.
China
Urban food delivery platforms and bubble tea chains in tier-two cities are scaling carrier volumes as on-demand beverage penetration deepens. SAMR packaging standards and MEE environmental compliance frameworks regulate material transitions. Manufacturing concentrates in the Yangtze River Delta and Pearl River Delta where integrated film extrusion and converting operations achieve cost leadership.
Germany
REACH Annex XVII chemical restrictions and EU Green Deal packaging waste targets are redirecting production toward certified compostable resin streams. ECHA's expanding substance restrictions disqualify legacy plasticizers from food-contact applications. Industrial converters in North Rhine-Westphalia and Bavaria are investing in bioplastic formulation capabilities to maintain EU market access.
India
Western and domestic quick-service chains are expanding drive-thru and delivery formats in metropolitan markets, creating carrier demand before multinational suppliers establish manufacturing footprint. BIS packaging standards and FSSAI food-contact regulations govern material specifications. Local film converters in Maharashtra and Gujarat are capturing procurement contracts through regional distribution advantages.
Japan
Convenience store chains and automated beverage retail formats sustain demand for precision-specified carrier formats. METI circular economy roadmaps and JIS standards drive material efficiency requirements. Manufacturing concentrates in the Kanto and Kansai regions where specialized film processors serve premium foodservice channels.
Drink Carrier Poly Bags Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated market structure where integrated resin-to-bag converters compete against specialized sustainability-focused formulators. The vendor base spans multinational packaging conglomerates with captive film extrusion capacity, regional converters serving quick-service accounts through direct relationships, and emerging bioplastic specialists. Three archetypes dominate: integrated film extrusion operators controlling resin cost curves, hybrid fiber-polymer system providers bridging sustainability messaging with performance, and certified compostable formulators capturing regulatory-mandated procurement channels. Competitive moves center on backward integration into resin supply and early certification investments to unlock sustainability-mandated contracts.
Among North American integrated operators, Novolex occupies a position exemplifying resin-to-bag cost curve control across quick-service accounts. International Paper Company anchors the hybrid fiber-polymer segment where paperboard-polymer laminates bridge plastic reduction goals with liquid containment performance. Smurfit Kappa Group sits within the European circular-economy certification tier, representing suppliers that leverage ESG credentials to access procurement contracts with sustainability-mandated foodservice chains.
| Leading Market Players |
|---|
| Novolex |
| International Paper Company |
| Smurfit Kappa Group |
| A-Pac Manufacturing |
| Trioworld Group |
| Rutan Poly Industries |
| Rishaba Poly Product |
| Amcor Limited |
| Kazuo Beyin Paper and Plastic Packing |
| Others |
Supply & Pricing Matrix
Film extrusion capacity utilization rates above 85% in Chinese Yangtze River Delta clusters compress converter margins elsewhere while anchoring global price floors for commodity-grade LDPE carriers. This scale concentration forces mid-tier North American and European converters toward specialty certifications or hybrid material formulations to escape cost-competition gravity.
Pricing Analysis
The customization-premium spread separates configured-to-order gusseted formats with proprietary die-cut specifications from standard flat-bag SKUs distributed through wholesale intermediaries. Pricing stratifies across premium, standard, and economy tiers based on certification grade (EN 13432 compostable, FDA food-contact, or unverified PCR claims) and volume scale. Cost compression in standard flat-bag segments is intensifying because Chinese manufacturing clusters are absorbing incremental global demand at resin-indexed contract rates. Quick-service restaurant chains with direct converter relationships exhibit the lowest price sensitivity, while retail distributors sourcing through wholesale channels face margin pressure that amplifies negotiation leverage.
Supply Chain Analysis
Just-in-time inventory strategies dominate quick-service procurement with 30-60 day resin-indexed contracts, while strategic stockpiling of certified compostable resins persists among European converters anticipating ECHA restriction timelines. Geographic supply concentration centers on China, the United States, and Germany, with film extrusion capacity clustering in the Yangtze River Delta, Midwest US, and North Rhine-Westphalia. Raw material dependencies draw from fossil-derived polyethylene feedstocks, bio-based PLA/PBAT resins, and post-consumer recycled content streams. Single-source vulnerability to SAMR environmental compliance shifts in China poses structural risk. Distribution runs through direct converter relationships for high-volume quick-service accounts and wholesale intermediaries for retail and convenience channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drink carrier poly bags are becoming a platform-economy battleground as food delivery platforms consolidate procurement specifications and demand API-integrated supplier onboarding. Interoperability between converter ERP systems and quick-service chain inventory management platforms is emerging as a competitive moat.
For Market Incumbents: Shield market share by accelerating bioplastic formulation R&D ahead of REACH Annex XVII expansion timelines, and deepen backward integration into resin supply to control cost curves against Chinese manufacturing clusters. Certification investments in EN 13432 and ASTM D6400 standards represent the priority lever for accessing sustainability-mandated procurement channels before mid-tier competitors complete workforce transitions.
For New Entrants and Emerging Players: Certification fast-tracks through EU notified bodies unlock procurement contracts with sustainability-mandated foodservice chains faster than incumbent reformulation cycles. India's quick-service penetration in metropolitan markets offers the most penetrable geography before multinational suppliers establish manufacturing footprint. A go-to-market angle anchored in regional distribution partnerships with Western quick-service franchisees avoids head-to-head competition with integrated Chinese exporters.
For Investors and Strategic Acquirers: Regional film converters with captive bioplastic formulation capabilities and EU circular-economy certifications represent the most defensible acquisition target archetype for long-term viability through the 5-10 year regulatory transition window. The signal to watch is ECHA's expansion of intentionally added microplastics restrictions, which would accelerate demand displacement toward certified compostable alternatives and strand conventional polyethylene capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Bioplastic Formulation Scale-Up | REACH Annex XVII compliance secures EU market access ahead of restriction deadlines. |
| Backward Integration into Resin Supply | Captive LDPE and PLA feedstock control insulates margins from commodity volatility. |
| Direct Procurement Platform Integration | API-connected inventory systems lock in quick-service chain volume commitments. |
| Hybrid Fiber-Polymer System Development | Paperboard-polymer laminates bridge plastic reduction goals with liquid containment performance. |
| EU Circular-Economy Certification Investment | Early EN 13432 and OK Compost certification unlocks sustainability-mandated contract access. |
Research Methodology
A spread of perspectives from film extrusion plant managers, quick-service procurement directors, food delivery platform supply chain leads, and regulatory affairs specialists converged on the working assumptions driving this analysis. Primary interview insights were validated against secondary sources including FDA food-contact material registrations, ECHA substance restriction databases, SAMR packaging standard filings, and trade flow data from Chinese customs authorities. Bottom-up capacity and demand estimates were triangulated with top-down market sizing derived from quick-service chain unit expansion disclosures and food delivery platform order volume trends.
Segmentation dimensions modeled include product configuration (flat, gusseted, biodegradable, reusable), material grade (LDPE, HDPE, bioplastic, recycled content), end-user channel (retail, restaurant, event venue, catering), and regional regulatory cluster (US FDA/EPA, EU REACH/Green Deal, China SAMR/MEE, India BIS/FSSAI). CAGRs were derived from regression analysis of historical procurement volume data and forward-projected quick-service unit expansion schedules. Industry-specific forecast inputs incorporated bubble tea chain penetration rates in Chinese tier-two cities and US quick-service off-premise revenue mix shifts.
Decision-makers should treat outputs as directional under base assumptions of continued regulatory tightening in EU and US coastal jurisdictions; material deviation in federal preemption clarity or composting infrastructure buildout would warrant model refresh. Practitioners should keep alternative scenarios live as ECHA microplastics restriction timelines and Chinese environmental compliance enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Bulk Bag Unloaders Market
Bags and Containers
Tote and Ingredient Bags Packaging Market
Bags and Containers
Flip-Up Vacuum Pack Market
Bags and Containers
Waterproof Bags Market
Bags and Containers
Slider Bags Market
Bags and Containers
Bulk Bag Conditioners Market
Bags and Containers
Freezing Bags Market
Bags and Containers
Packaging Nets Market
Bags and Containers
Low Melt Point Bags Market
Bags and Containers
Piping Bags Market
Bags and Containers
Bag Making Machine Market
Bags and Containers
Breathable Bags Market
Bags and Containers
Non-Laminated Heat-Sealed Bags Market
Bags and Containers
Ventilated FIBC Market
Bags and Containers
Bagster Bag Market
Bags and Containers
Flip Lip Bags Market