
 Wicketless Bags Market | 2026-2036
Wicketless Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Wicketless Bags Market Analytics
Asset-light leasing models for high-speed wicketless bag converting equipment is rewriting competitive entry dynamics for mid-tier converters. Berry Global leverages captive resin sourcing and integrated film extrusion to sustain margin control across North American retail accounts. Amcor anchors its position through R&D intensity in mono-material wicketless structures that navigate emerging recycling mandates. Novolex competes on manufacturing scale, operating one of the largest domestic converting footprints for food service wicketless formats.
Wicketless bags are pre-opened polyethylene or polypropylene bags manufactured without wire wicket supports, instead utilizing perforated headers or adhesive blocks for automated dispensing at 60–120 units per minute on standard bagging equipment. Their primary commercial purpose centers on high-velocity packaging lines in retail, grocery, and e-commerce fulfillment where manual loading speed directly determines labor cost per unit. Gusseted bags and stand-up pouches occupy the fastest-expanding margin pools as brands convert from rigid containers to flexible formats for shelf presence and cube utilization. Flat bags remain the mature volume base, while biodegradable film substrates represent the emerging technology tier where converters are repositioning product portfolios ahead of regulatory phase-outs.
The EPA guides state-level plastic waste reduction frameworks in the United States, while REACH and the EU Packaging and Packaging Waste Regulation establish substance restrictions and extended producer responsibility thresholds across European markets. California's SB 54 mandates 30% recycled content in plastic bags by 2028, directly shaping material specification requirements for wicketless bag producers serving West Coast retail chains. Stakeholders must monitor how diverging state and federal timelines for recycled content rules reshape supplier qualification criteria and capital allocation across converting networks.
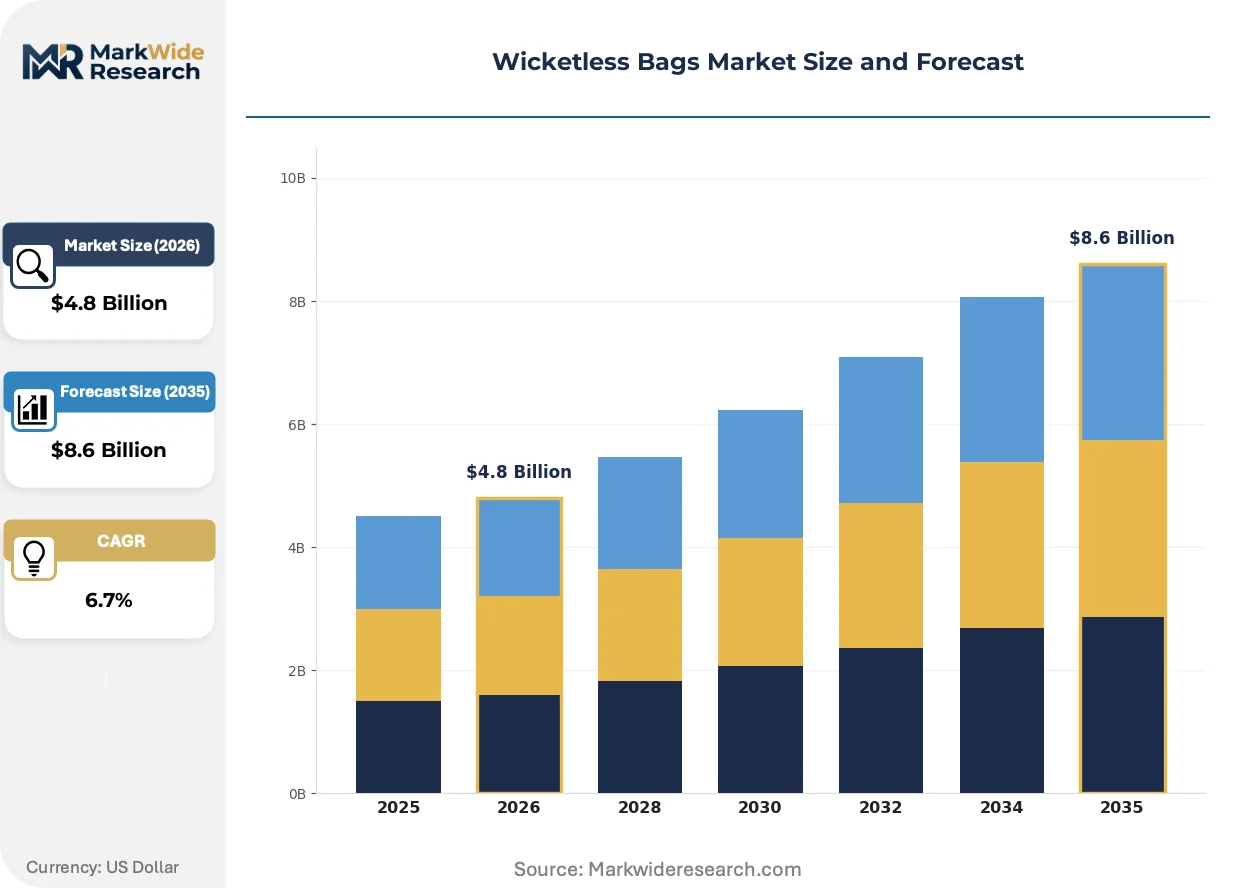
Market Dynamics
Food service automation is compressing wicketless bag specification cycles as operators demand higher dispensing speeds and thinner gauge films to cut per-unit packaging costs. This operational pressure is cascading upstream to film extruders and converting equipment suppliers.
Growth Catalysts
- EU Single-Use Plastics Directive:The directive mandates reduction targets for conventional plastic packaging, accelerating converter investment in biodegradable wicketless formats across German and French retail supply chains.
- High-velocity e-commerce fulfillment:Automated packaging lines in grocery delivery hubs now specify wicketless bags for pre-opened dispensing at 100+ units per minute, reducing labor touchpoints per order.
- California SB 54 recycled content rules:The mandate requires 30% post-consumer resin in plastic bags by 2028, forcing material reformulation in wicketless products serving West Coast retail accounts.
Market Restraints
- Resin price volatility:Polyethylene and polypropylene feedstock costs fluctuate with crude oil indices, compressing converter margins on fixed-price annual contracts with food service distributors.
- Biodegradable film performance gaps:Current PLA and starch-based substrates lack the seal strength and moisture barrier of conventional polyethylene, limiting adoption in frozen and wet-goods applications.
- Equipment lock-in:Legacy wicketed bag machinery dominates installed bases at mid-tier converters, creating capital friction for wicketless format transitions.
Strategic Opportunities
- Mono-material recyclable structures:Amcor and competitors are developing single-polymer wicketless bags that satisfy emerging extended producer responsibility schemes under the EU Packaging and Packaging Waste Regulation.
- Asset-light equipment leasing:Converting machinery vendors now offer subscription-based access to high-speed wicketless lines, lowering entry barriers for regional packaging specialists.
- Pharmaceutical secondary packaging:Wicketless polyethylene bags are penetrating cleanroom environments for device kitting, where pre-opened dispensing reduces particulate contamination risks.
Industry Challenges
- Multi-state regulatory fragmentation:Converters serving US national accounts must navigate divergent recycled content timelines across California, New York, and pending state legislation, complicating inventory segmentation.
- Film gauge optimization trade-offs:Downgauging to reduce resin costs risks seal failures at high-speed dispensing, requiring precise calibration between material scientists and line operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wicketless Bags Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Gusseted Bags, Stand-Up Pouches, Retail Bags Material: Plastic, Biodegradable Film, Polypropylene, Paper End User: Retail, Food Service, Grocery, E-Commerce Application: Packaging, Storage, Transportation, Waste Management |
| Companies Covered | Berry Global, Amcor, Novolex, Mondi, Sealed Air, Coveris, Inteplast, ProAmpac, Emerald Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wicketless Bags Market Evolving Landscape
Material science breakthroughs and regulatory phase-outs are rewriting wicketless bag specifications faster than equipment replacement cycles, creating temporary capability gaps between early adopters and laggard converters.
Mono-material polyethylene wicketless structures is migrating from niche sustainable packaging portfolios toward mainstream retail adoption. German supermarket chains Aldi and Lidl now specify mono-material formats for private-label bakery and produce bags to satisfy sorting infrastructure at municipal recycling facilities. This migration from multi-layer barrier films is compressing demand for conventional metallized and nylon-reinforced wicketless products.
REACH substance restrictions are tightening permissible additives in food-contact films across European markets. The ECHA evaluation of plasticizers and slip agents is forcing reformulation of wicketless bag surfaces to maintain dispensing performance without restricted chemicals. Converters serving EU food service accounts are responding by qualifying alternative masterbatch suppliers ahead of sunset dates.
Direct equipment financing from resin suppliers is displacing traditional bank lending for wicketless converting lines. Berry Global and Novolex now bundle resin supply contracts with leased high-speed equipment, locking in volume commitments from mid-tier converters. This captive financing model concentrates most visibly in North American markets where converter fragmentation exceeds European levels.
Wicketless Bags Market Segmentation
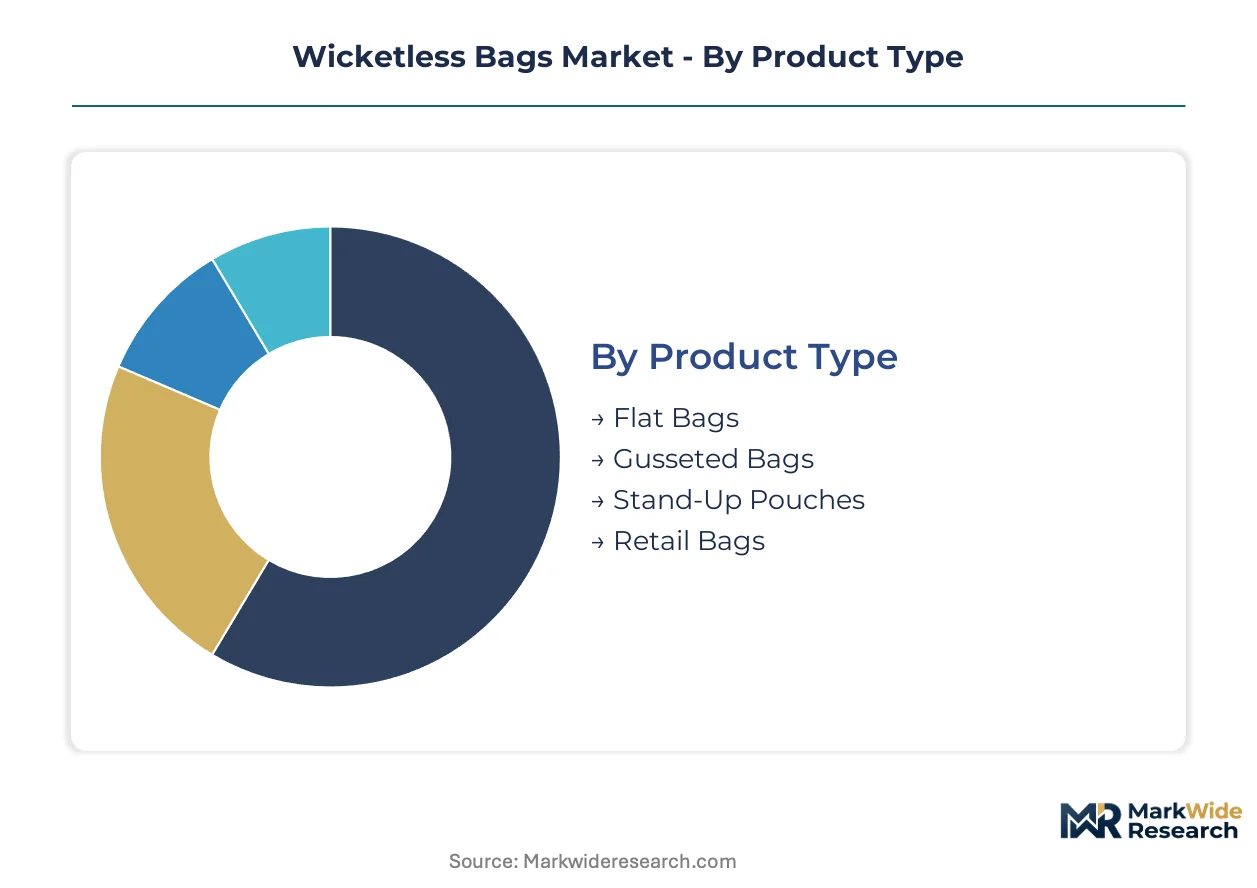
Wicketless bag specifications diverge sharply across dispensing velocity requirements and barrier performance needs. Material choices and format dimensions determine compatibility with automated bagging equipment ranging from 60 to 120 units per minute.
Product Type:
Use-case spectrum spans high-velocity food service dispensing to premium retail shelf presentation, with format selection driven by cube utilization and brand visibility requirements.
- Flat Bags:Single-layer polyethylene or polypropylene constructions with perforated headers for horizontal dispensing. Mature volume base in North American grocery bakery and produce applications where cost per thousand units dominates procurement criteria.
- Gusseted Bags:Side-folded constructions that expand to accommodate irregular shapes while maintaining stack stability. German retail chains Aldi and Lidl specify gusseted wicketless formats for private-label bakery lines to optimize shelf cube utilization.
- Stand-Up Pouches:Bottom-gusseted flexible formats with resealable closures. Premium snack and pet food brands in California specify these for e-commerce fulfillment where shipping damage reduction justifies higher unit costs.
- Retail Bags:Pre-printed wicketless formats with integrated carrying handles. French supermarket operators specify these for self-service produce to reduce checkout labor touchpoints.
Established volume favors Flat Bags; emerging adoption favors Stand-Up Pouches.
Material:
Cost tier stratification separates commodity resin volumes from premium biodegradable substrates facing performance validation hurdles.
- Plastic:Conventional polyethylene and polypropylene films dominate installed equipment compatibility. California SB 54 recycled content mandates are forcing reformulation toward post-consumer resin blends for West Coast retail accounts.
- Biodegradable Film:PLA and starch-based substrates lacking moisture barrier performance for frozen applications. EU Single-Use Plastics Directive acceleration in Germany and France is compressing qualification timelines for food service converters.
- Polypropylene:Higher clarity and temperature resistance than polyethylene. Hot-fill food service applications in New York state specify polypropylene wicketless bags for prepared meal dispensing.
- Paper:Kraft and grease-resistant substrates for bakery and dry goods. Nordic retail operators specify paper wicketless formats ahead of broader European plastic restriction phase-outs.
Commodity resin volumes concentrate in Plastic; regulatory pressure is concentrating converter R&D expenditure on Biodegradable Film.
End User:
Customer type fragmentation creates divergent specification priorities between labor-cost-sensitive food service and brand-conscious retail channels.
- Retail:Private-label and branded merchandise requiring pre-printed graphics and consistent dispensing performance. German supermarket chains specify mono-material recyclable structures to satisfy municipal sorting infrastructure.
- Food Service:High-velocity operators demanding thinner gauge films and 100+ unit per minute dispensing speeds. US national accounts are compressing specification cycles as automation investments accelerate.
- Grocery:Hybrid requirements spanning self-service produce and behind-deli-counter applications. California and New York state regulations are segmenting inventory requirements for multi-state operators.
- E-Commerce:Fulfillment centers specifying pre-opened bags for automated packing lines. Grocery delivery hubs in dense urban markets represent the steepest expansion trajectory for wicketless format adoption.
Procurement scale favors Retail; automation intensity favors Food Service.
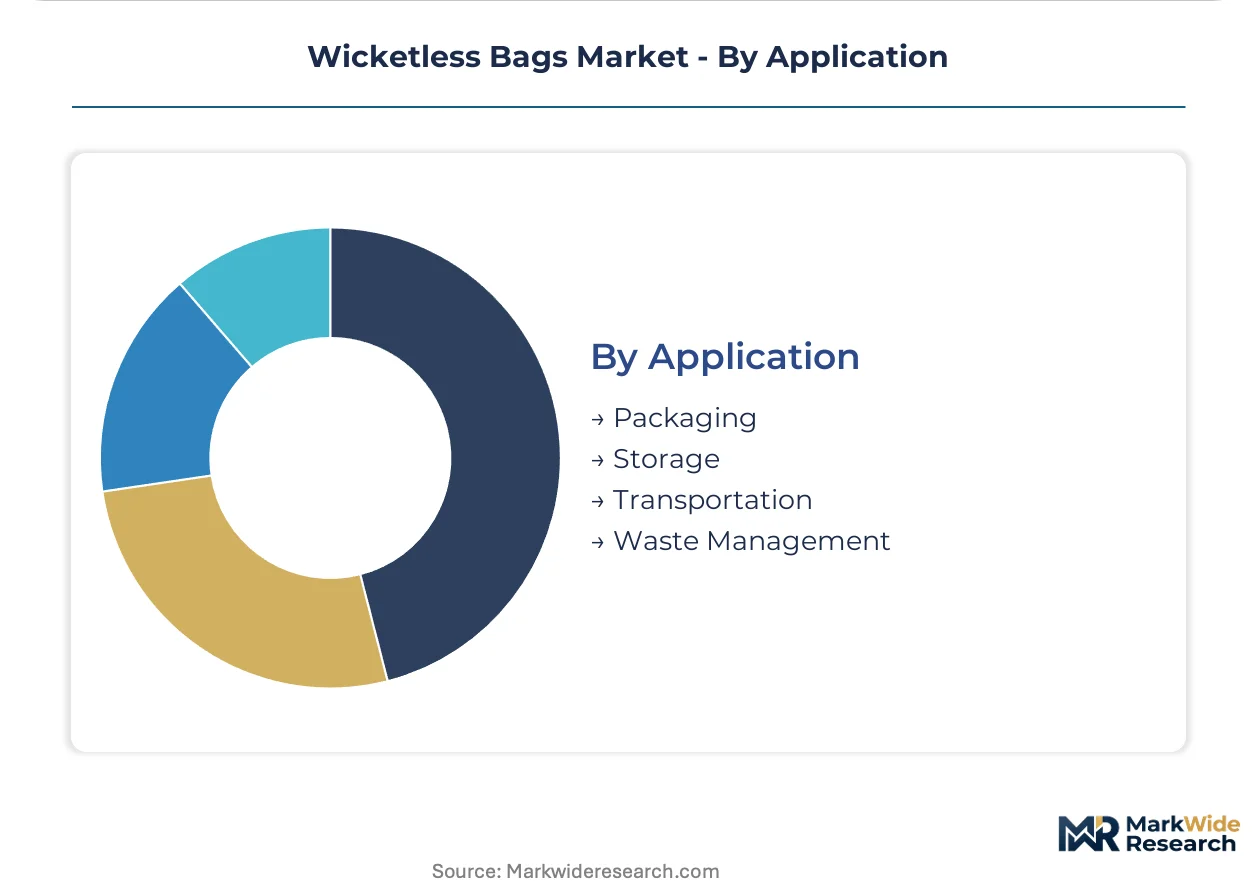
Application:
Functional requirements range from primary product contact to secondary containment, with barrier specifications varying by contents and dwell time.
- Packaging:Primary contact applications requiring FDA or EFSA food-contact compliance. Frozen and wet-goods specifications remain constrained by biodegradable film seal strength limitations.
- Storage:Intermediate holding applications in distribution centers and back-of-house operations. Gusseted wicketless bags dominate for irregular shape accommodation.
- Transportation:Secondary containment for shipment consolidation and damage reduction. E-commerce fulfillment specifications emphasize puncture resistance for automated handling.
- Waste Management:Liners and collection bags for commercial and institutional streams. Paper substrates are penetrating this segment ahead of plastic restriction deadlines in EU markets.
Unit volume concentrates in Packaging; regulatory tailwinds favor Waste Management substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's SB 54 recycled content mandate and Germany's EU Packaging and Packaging Waste Regulation implementation are redirecting converter capital toward compliant substrate technologies across both markets.
United States
Food service automation and e-commerce fulfillment hubs in California and New York are compressing wicketless bag specification cycles for thinner gauge films. The EPA guides state-level plastic waste frameworks while California SB 54 mandates 30% post-consumer resin by 2028. Los Angeles and New York City grocery delivery operators specify pre-opened wicketless formats for 100+ unit per minute dispensing speeds.
Germany
Retail chains Aldi and Lidl specify mono-material recyclable wicketless structures for private-label bakery and produce lines. REACH substance restrictions and the EU Single-Use Plastics Directive accelerate biodegradable film qualification timelines. The Rhine-Ruhr packaging converting cluster advances wicketless specifications ahead of broader European adoption curves.
France
Supermarket operators specify pre-printed wicketless retail bags with integrated carrying handles for self-service produce applications. EFSA food-contact compliance requirements under EU Packaging and Packaging Waste Regulation reshape masterbatch formulations. The Île-de-France region concentrates converter R&D expenditure on alternative slip agents ahead of ECHA sunset dates.
United Kingdom
E-commerce fulfillment centers specify puncture-resistant wicketless formats for automated handling and shipping damage reduction. Extended producer responsibility thresholds under UK packaging regulations segment inventory requirements. The Midlands converting corridor adapts legacy wicketed machinery toward wicketless format transitions through equipment leasing arrangements.
India
Organized retail expansion in Maharashtra and Karnataka creates specification demand for pre-opened dispensing formats in grocery and quick-commerce channels. FSSAI food-contact compliance requirements shape imported film qualification protocols. The Mumbai-Pune industrial belt attracts regional packaging specialists through asset-light equipment leasing models from machinery vendors.
Wicketless Bags Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base fragments between resin-integrated majors and regional converting specialists serving single-state accounts. Three archetypes dominate: captive resin producers with backward integration into film extrusion, pure-play converters leasing high-speed equipment, and sustainability-focused developers of mono-material structures. Competitive moves concentrate on M&A for geographic coverage and strategic partnerships for biodegradable substrate access.
Among North American resin-integrated majors, Berry Global and Novolex exemplify the captive supply archetype through polyethylene sourcing control and large domestic converting footprints. Amcor occupies a distinct position within the sustainability-specialist tier, anchoring industry attention on mono-material recyclable structures. These three entities represent divergent strategic postures: backward integration at scale, manufacturing scale concentration, and R&D intensity in regulatory-compliant formats.
| Leading Market Players |
|---|
| Berry Global |
| Amcor |
| Novolex |
| Mondi |
| Sealed Air |
| Coveris |
| Inteplast |
| ProAmpac |
| Emerald Packaging |
| Others |
Value Network & Pricing Analysis
The Rhine-Ruhr corridor's freight cost dynamics amplify pricing power for German film extruders while forcing downstream differentiation between commodity converters and certified food-contact specialists serving Aldi and Lidl specifications.
Pricing Analysis
Certification level (FDA/EFSA-grade) creates the primary spread between commodity polyethylene wicketless bags and validated food-contact formats. Three-tier pricing structure across premium certified, standard industrial, and economy non-food tiers dominates transactional contracts. Cost compression in economy grades is intensifying because resin suppliers bundle equipment financing with volume commitments. Food service distributors exhibit highest price sensitivity; pharmaceutical secondary packaging buyers show least.
Supply Chain Analysis
Contract manufacturing concentration rests with Berry Global, Novolex, and Amcor operating captive film extrusion across the United States, Germany, and France. Raw material dependencies draw from polyethylene and polypropylene resin feedstocks plus imported biodegradable PLA substrates. Single-source vulnerability concentrates in German specialty masterbatch suppliers facing REACH sunset dates. Distribution runs through national food service distributors and direct retail chain procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated US national food service accounts and German retail chains, fragmenting converter margins as specification cycles compress.
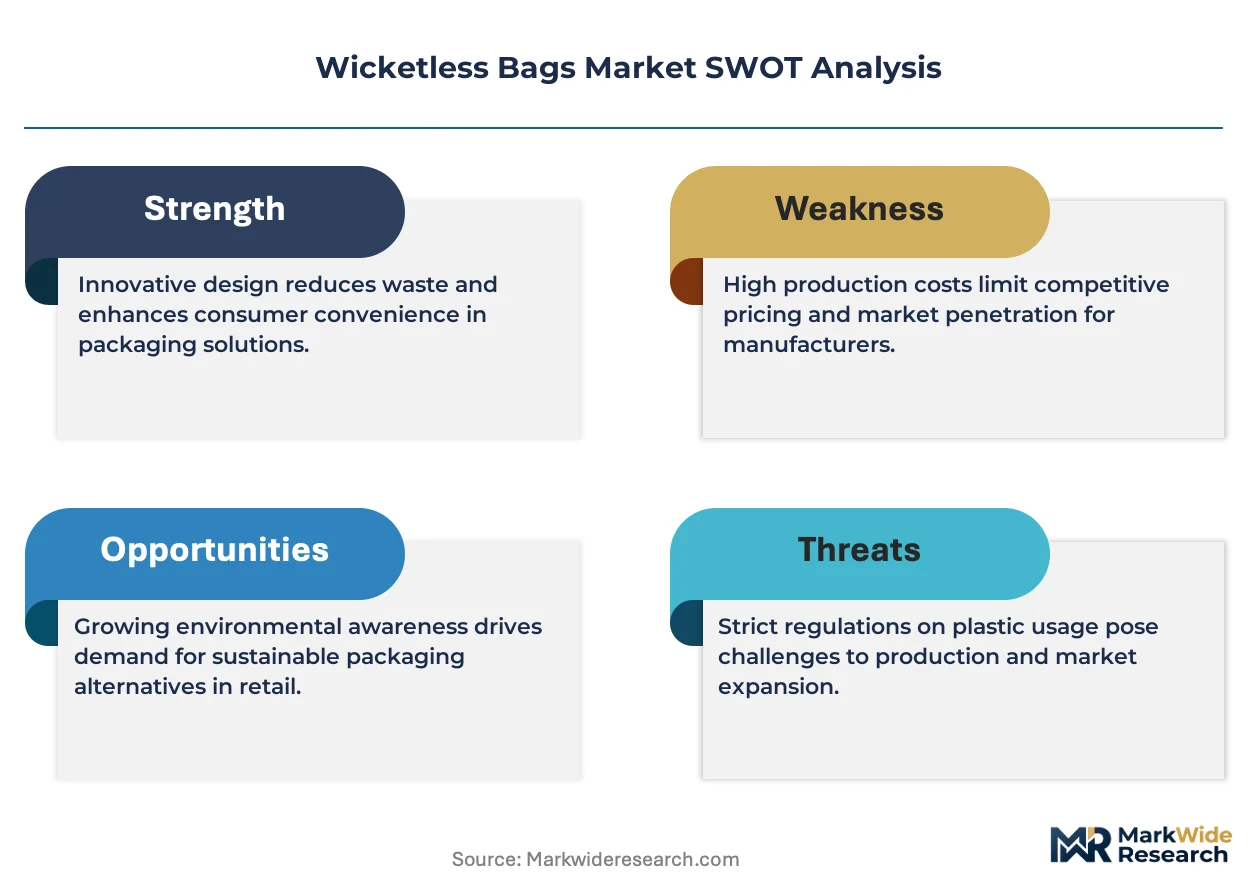
For Market Incumbents: Pre-empt biodegradable film qualification gaps by locking Indian and Southeast Asian resin suppliers into long-term offtake agreements before EU Single-Use Plastics Directive deadlines. Defend margin position through backward integration into mono-material film extrusion rather than equipment leasing exposure. Channel control via direct retail chain partnerships offers stronger protection than distributor intermediation against price erosion. For New Entrants and Emerging Players: Maharashtra and Karnataka's organized retail expansion presents the most penetrable white-space for asset-light converting specialists. Target quick-commerce grocery delivery hubs in dense Indian urban corridors where automated dispensing specification demand outpaces local supply. A go-to-market angle through machinery vendor equipment leasing partnerships sidesteps capital barriers that constrain legacy converter transitions. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with underperforming wicketless bag divisions lacking mono-material R&D capabilities. Long-term viability hinges on regulatory-compliant substrate portfolios rather than commodity resin scale. Watch biodegradable film performance validation milestones in frozen applications as the inflection signal separating viable acquisition targets from stranded assets.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material R&D Investment | Amcor's recyclable structures satisfy EU Packaging and Packaging Waste Regulation extended producer responsibility thresholds. |
| Asset-Light Equipment Leasing | Machinery vendor subscription models lower entry barriers for regional Indian and Southeast Asian packaging specialists. |
| Biodegradable Film Qualification | PLA and starch substrate validation ahead of EU Single-Use Plastics Directive deadlines secures German retail chain contracts. |
| Captive Resin Supply Integration | Berry Global's polyethylene sourcing control sustains margin protection against crude oil-indexed feedstock volatility. |
| Pharmaceutical Cleanroom Penetration | Wicketless polyethylene formats for device kitting reduce particulate contamination risks in FDA-regulated secondary packaging. |
Research Methodology
Desk research of trade association filings, customs records, and regulatory databases preceded structured interviews with film extrusion plant managers, food service procurement directors, retail category buyers, and converting equipment vendors. Primary fieldwork centered on packaging converting clusters in the Rhine-Ruhr region, California's Central Valley, and the Mumbai-Pune industrial belt. Secondary validation drew from EPA guidance documents, ECHA substance restriction timelines, and FSSAI food-contact compliance protocols. Bottom-up unit volume estimates triangulated against top-down market size assessments.
Assumptions held fixed include regulatory phase-out timelines for conventional plastics and resin feedstock price correlation with crude oil indices; variables tested encompass biodegradable film performance breakthroughs and equipment leasing penetration rates. Segmentation dimensions modeled span product type, material substrate, end-user channel, and application function across the projection horizon. CAGRs derived from trend extrapolation of dispensing automation adoption curves and material transition velocities.
Practitioners should monitor resin price volatility spikes and biodegradable film seal strength validation milestones for early signals requiring forecast revision. Quarterly review of EU Packaging and Packaging Waste Regulation implementation pace and California SB 54 recycled content compliance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Vacuum Sealer Bags Market
Bags and Containers
Liner Bags Market
Bags and Containers
Block Sack Market
Bags and Containers
Anti-Static Collapsible Tote Bins Market
Bags and Containers
Laser Scored Bags Market
Bags and Containers
Textile Bags Market
Bags and Containers
BOPP Bags Market
Bags and Containers
Twin Seal Bags Market
Bags and Containers
Conical Bags Packaging Market
Bags and Containers
Loose-Fill Peanuts Market
Bags and Containers
Isothermal Bags and Containers Market
Bags and Containers
Frosted Bag Market
Bags and Containers
Non-Barrier Bag Market
Bags and Containers
Vertical Form Fill Seal Baggers Market
Bags and Containers
Shopping Bag Market
Bags and Containers
Handle Gusseted Bags Market