
 Isothermal Bags Market | 2026-2036
Isothermal Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Isothermal Bags Market Foresight
Phase-change material integration with vacuum-insulated panels is rewriting thermal performance benchmarks for portable cold chain equipment. Pelican Biothermal LLC leverages its North American manufacturing footprint to sustain leadership in pharmaceutical-grade container systems. Cryopak Europe anchors European distribution through specialized gel pack and insulated bag portfolios tailored to clinical trial logistics. Sofrigam SA Ltd competes on regulatory depth, navigating EMA and GDP compliance requirements across its temperature-controlled packaging lines.
Isothermal bags are engineered thermal enclosures utilizing multi-layer insulation composites—typically polyethylene or nylon exteriors bonded with aluminum reflective films and expanded polystyrene or aerogel cores—to maintain defined temperature ranges between minus eighty degrees Celsius and plus twenty-five degrees Celsius for periods extending from four hours to over one hundred twenty hours. Healthcare Providers represent the dominant end-user segment, with pharmaceutical distributors prioritizing validated cold chain solutions for biologics and cell therapies. Insulated Bags lead product type demand, though Gel Packs are displacing traditional ice-based cooling in last-mile vaccine delivery where precise temperature maintenance replaces crude refrigeration.
FDA 21 CFR Part 211, EU GDP Guidelines, and IATA CEIV Pharma certification collectively shape product design, qualification protocols, and market access for temperature-sensitive logistics equipment. REACH and RoHS restrictions on flame retardants and plasticizers are forcing material substitutions in European supply chains, raising compliance costs for non-adapted suppliers. Stakeholders must monitor evolving pharmacopeial standards for thermal packaging qualification and decide whether to absorb certification investments internally or outsource through specialized cold chain as-a-service platforms.
Market Dynamics
Phase-change material integration with vacuum-insulated panels is compressing thermal performance thresholds while REACH and F-Gas Regulation compliance costs are redistributing competitive positions among European suppliers.
Growth Catalysts
- EMA GDP Guidelines:Stringent temperature documentation requirements for biologics distribution are mandating validated cold chain packaging across European pharmaceutical corridors.
- Cell therapy logistics:Chimeric antigen receptor T-cell therapies require minus eighty degrees Celsius maintenance for cryopreserved patient materials, expanding demand for ultra-low temperature portable systems.
- Germany vacuum-insulated panel production:Concentrated manufacturing capacity in Bavaria and Saxony is shortening lead times for pharmaceutical-grade thermal enclosures across Central Europe.
Market Restraints
- Aluminum reflective film supply:Primary aluminum smelting energy costs and EU carbon border adjustment mechanisms are inflating input material expenses for multi-layer insulation composites.
- Aerogel core availability:Limited commercial-scale silica aerogel manufacturing in Europe creates supply concentration risk for premium thermal performance segments.
- RoHS flame retardant restrictions:Substituting halogenated compounds with phosphorus-based alternatives in polyethylene exteriors raises material costs and complicates bonding processes with aluminum films.
Strategic Opportunities
- India clinical trial expansion:CDSCO regulatory harmonization with ICH-GCP standards is attracting multinational pharmaceutical sponsors, generating demand for temperature-qualified logistics in Mumbai and Hyderabad corridors.
- Last-mile drone delivery:Integration of isothermal bags with unmanned aerial systems for vaccine distribution to remote health posts is opening channel innovation in East African markets.
- EU Green Deal procurement incentives:Public health system tender preferences for lower-global-warming-potential insulation technologies are creating competitive advantage for vacuum-insulated panel adopters.
Industry Challenges
- Thermal qualification engineering talent:Scarcity of professionals combining heat transfer modeling with pharmaceutical regulatory documentation is extending product development cycles.
- IATA CEIV Pharma certification timelines:Extended validation protocols for air cargo temperature-controlled containers are delaying market entry for new product lines.
- Legacy ERP integration:Connecting serialized temperature monitoring systems with existing pharmaceutical distributor inventory management platforms requires costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isothermal Bags Market |
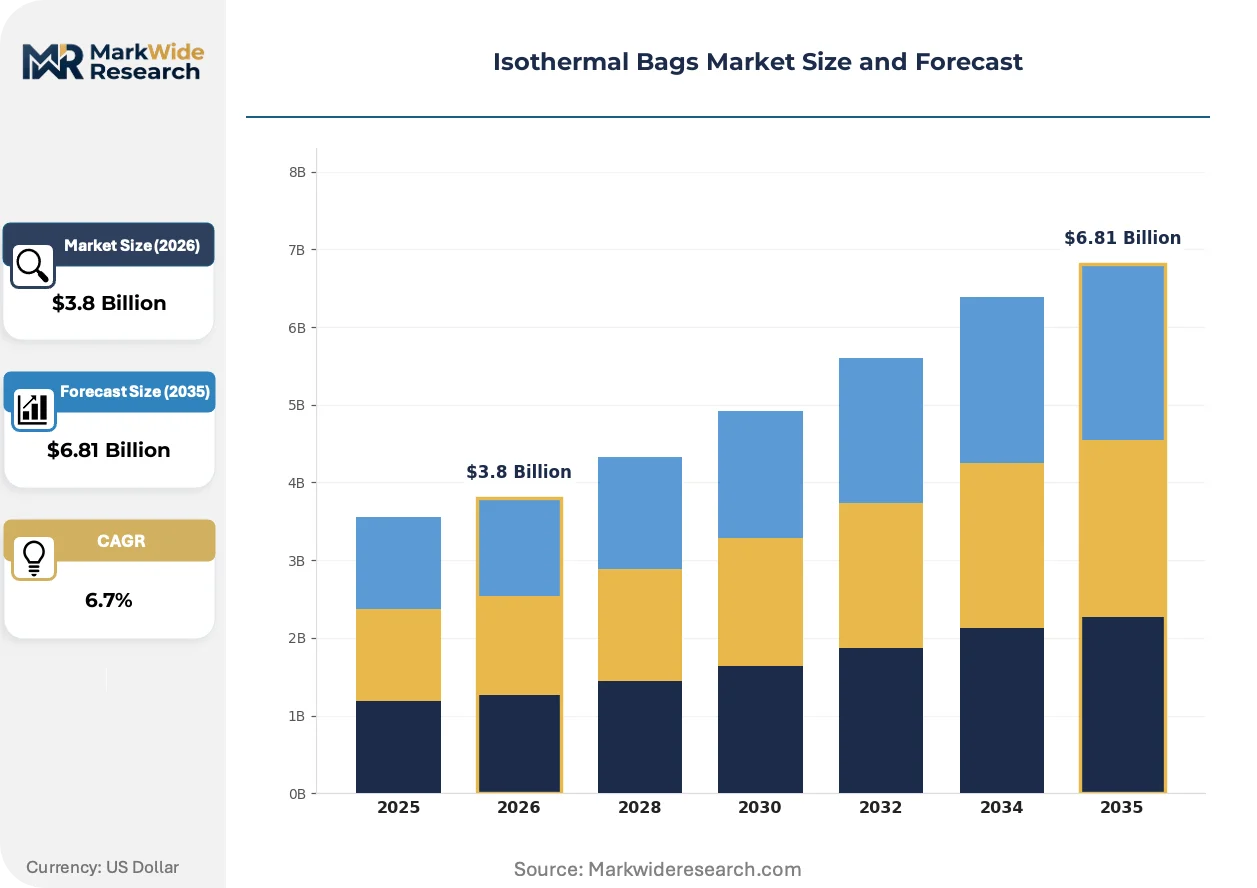
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Bags, Gel Packs, Coolers, Refrigerated Bags Material: Polyethylene, Nylon, Polystyrene, Aluminum End User: Healthcare Providers, Food Transporters, Retailers, Event Planners Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Sonoco Products Company, Pelican Biothermal LLC, Cryopak Europe, Sofrigam SA Ltd, Cold & Co Sprl, Envirotainer Ltd, va-Q-tec AG, Berry Global, Inc., Tecnisample s.l., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isothermal Bags Market Shifts & Advancements
Material science convergence and regulatory stringency are redefining thermal packaging performance standards while procurement patterns shift toward integrated cold-chain-as-a-service models.
Vacuum-insulated panel technology is hybridizing with phase-change material matrices to achieve temperature stability durations exceeding one hundred twenty hours in sub-five-liter payloads. Pharmaceutical distributors handling cell therapies and gene-modified products are adopting these hybrid systems at accelerated rates. The technology is hybridizing cost structures by compressing dry ice consumption and reducing reverse logistics complexity for temperature-sensitive shipments.
EU F-Gas Regulation phase-down schedules are prohibiting hydrofluorocarbon blowing agents in expanded polystyrene cores, forcing insulation manufacturers toward carbon dioxide or cyclopentane alternatives. Industrial consequence includes reformulated density specifications and recalibrated thermal conductivity ratings across product lines. German and French pharmaceutical packaging suppliers are most affected, responding with accelerated vacuum-insulated panel adoption to bypass foam-core regulatory exposure entirely.
Buying organizations are consolidating vendor relationships around full-service cold chain platform providers rather than discrete packaging procurement. Pharmaceutical logistics departments are displacing traditional bid-based purchasing with multi-year performance contracts bundling equipment, monitoring, and compliance documentation. This pattern is most visible in Benelux and Nordic markets where centralized hospital procurement authorities dominate purchasing decisions.
Isothermal Bags Market Segmentation
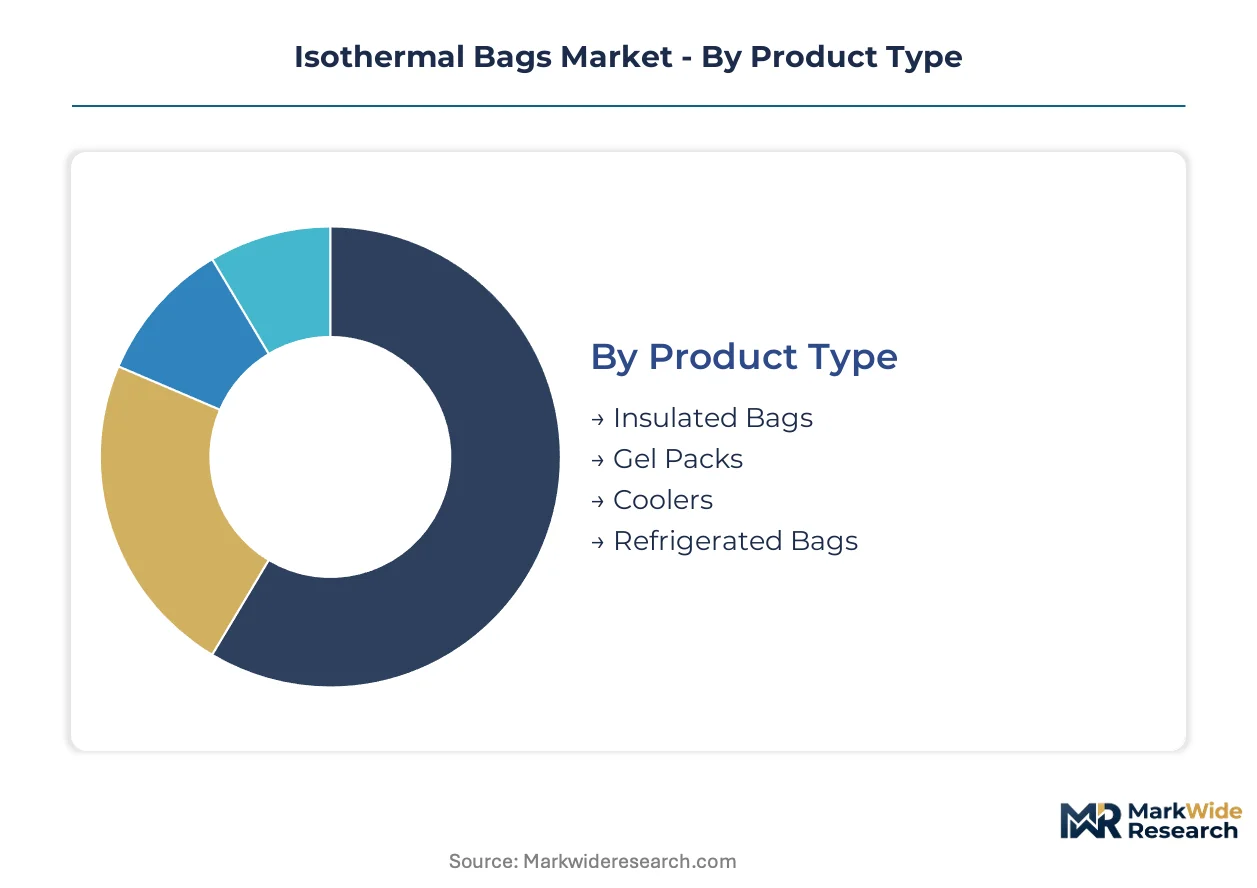
Segmentation in the isothermal bags market reveals how material science specialization and regulatory compliance requirements create distinct competitive arenas. Product architecture, insulation composition, and end-use thermal specifications determine pricing power and certification burdens across supplier tiers.
Product Type:
Mature envelope configurations dominate pharmaceutical procurement, while emerging hybrid systems capture biologics logistics investment.
- Insulated Bags:Multi-layer composites of polyethylene or nylon exteriors bonded with aluminum reflective films and expanded polystyrene cores maintain temperature stability for 4–120 hours. Healthcare providers in Germany and France prioritize these for validated cold chain distribution of vaccines and insulin, with EMA GDP documentation requirements mandating qualification protocols that elevate procurement standards.
- Gel Packs:Phase-change material matrices store latent heat at precise temperature setpoints, enabling calibrated thermal mass deployment without dry ice hazards. Last-mile vaccine delivery programs across East Africa and South Asia are displacing traditional ice-based cooling with gel pack-integrated bags where precise temperature maintenance replaces crude refrigeration.
- Coolers:Rigid-wall polyurethane or expanded polystyrene containers with gasket-sealed lids serve food service and outdoor recreation markets.
- Refrigerated Bags:Active compressor-based portable units bridge passive insulation gaps for extended-duration pharmaceutical transport.
Insulated Bags retain volume leadership; Gel Packs hold the steepest expansion curve.
Material:
Cost tier stratification separates commodity polymer supply from premium aerogel and vacuum-insulated panel adoption in regulated pharmaceutical channels.
- Polyethylene:Low-density and linear low-density variants form flexible exteriors through blown film extrusion, with RoHS flame retardant restrictions forcing substitution of halogenated compounds for phosphorus-based alternatives. European suppliers face elevated bonding complexity with aluminum reflective layers under REACH compliance timelines.
- Aluminum:Metallized PET or pure aluminum foil laminates provide radiant barrier performance critical for multi-day temperature stability. German vacuum-insulated panel manufacturers in Bavaria and Saxony anchor concentrated production capacity, shortening lead times for pharmaceutical-grade thermal enclosures across Central Europe.
- Nylon:Polyamide substrates offer puncture resistance and tensile strength for reusable clinical trial logistics applications.
- Polystyrene:Expanded and extruded forms face EU F-Gas Regulation phase-down pressure on hydrofluorocarbon blowing agents, accelerating displacement by alternative core technologies.
Polyethylene commands the widest application base; Aluminum captures the premium pricing tier in regulated segments.
End User:
Customer type determines validation depth, with healthcare procurement mandating qualification documentation that food and retail channels bypass.
- Healthcare Providers:Hospital pharmacies, clinical research organizations, and biologics distributors require FDA 21 CFR Part 211 and EU GDP-compliant temperature-controlled packaging with serialized monitoring integration. Cell therapy logistics for cryopreserved patient materials at minus eighty degrees Celsius are expanding demand for ultra-low temperature portable systems.
- Food Transporters:Meal kit delivery services and fresh produce distributors prioritize cost-efficient passive cooling for sub-24-hour distribution cycles.
- Retailers:Supermarket chains and convenience stores deploy isothermal bags for click-and-collect frozen and chilled grocery fulfillment.
- Event Planners:Catering and hospitality procurement emphasizes aesthetic customization and brandability over thermal performance certification.
Healthcare Providers anchor revenue concentration; Food Transporters are climbing the fastest on e-commerce fulfillment expansion.
Distribution Channel:
Supply concentration in specialized cold chain platforms is displacing discrete packaging procurement across pharmaceutical buyer organizations.
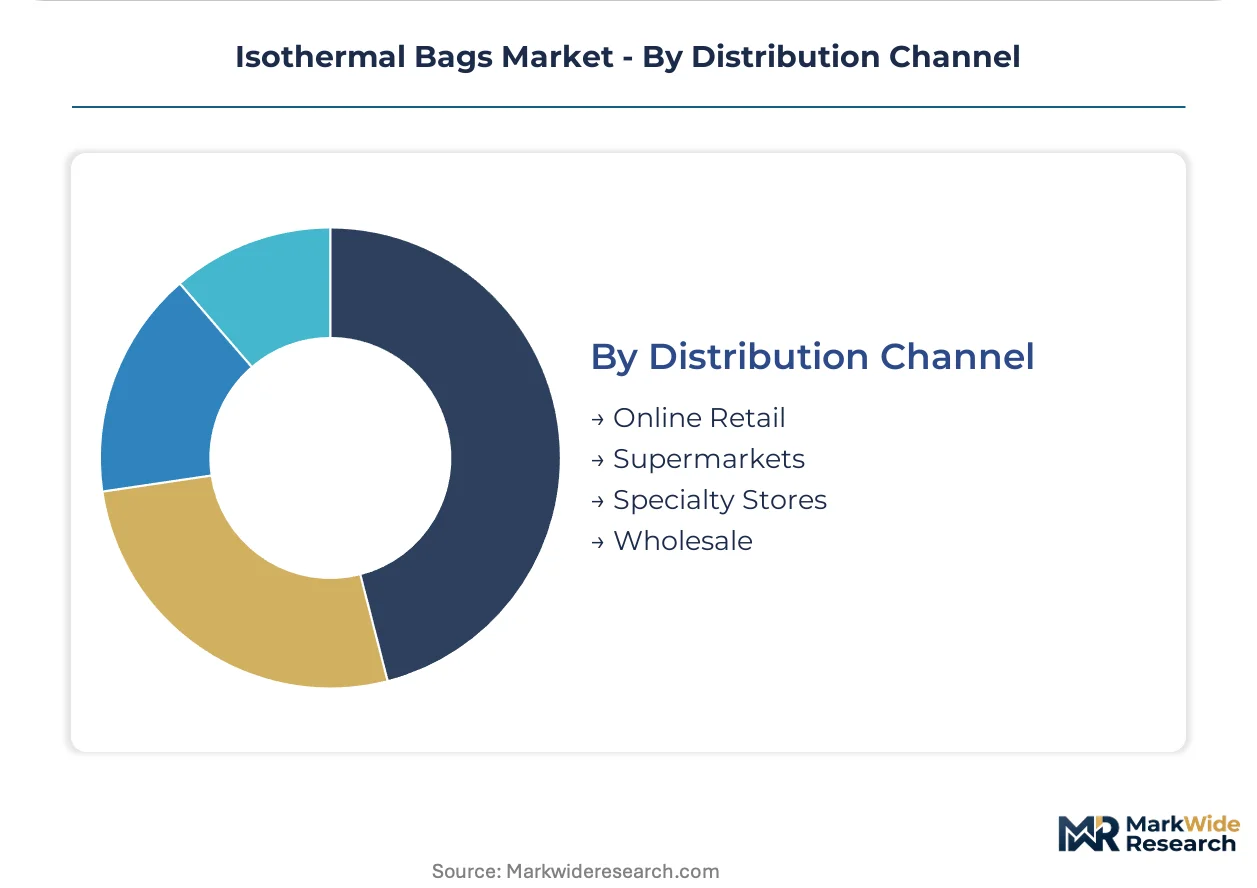
- Online Retail:Direct-to-consumer and B2B marketplace channels enable rapid specification comparison for standardized insulated bag configurations. Benelux and Nordic hospital procurement authorities are consolidating vendor relationships through multi-year performance contracts bundling equipment, monitoring, and compliance documentation.
- Specialty Stores:Temperature-controlled packaging distributors provide application engineering support and qualification documentation for pharmaceutical-grade deployments.
- Supermarkets:Mass retail chains serve consumer-grade cooler and insulated bag demand for recreational and household use.
- Wholesale:Industrial distributors supply volume food service and logistics operators with standardized thermal enclosure configurations.
Online Retail captures procurement modernization momentum; Specialty Stores defend margin position on technical advisory value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical distributors and clinical research organizations concentrate procurement authority in corridors with dense biologics manufacturing and stringent GDP enforcement. Cold chain validation requirements reshape supplier selection across national boundaries.
Germany
Bavarian and Saxony-based vacuum-insulated panel production clusters serve pharmaceutical-grade thermal enclosure demand across Central Europe. EMA GDP Guidelines mandate serialized temperature documentation for biologics distribution, elevating qualification standards for packaging procurement. va-Q-tec AG anchors concentrated manufacturing capacity in Würzburg, shortening lead times for ultra-low temperature portable systems.
United States
FDA 21 CFR Part 211 compliance drives validated cold chain packaging investment for cell therapy logistics requiring minus eighty degrees Celsius maintenance. The IRA's domestic manufacturing incentives accelerate regional production of phase-change material matrices. Greater Boston's biotech corridor generates concentrated demand for cryopreserved patient material transport solutions.
India
CDSCO regulatory harmonization with ICH-GCP standards attracts multinational pharmaceutical sponsors to Mumbai and Hyderabad clinical trial corridors. FSSAI cold chain mandates for temperature-sensitive pharmaceuticals expand validated packaging requirements. Karnataka's biopharma manufacturing belt drives procurement of gel pack-integrated bags for last-mile vaccine delivery.
France
ANSM pharmacovigilance requirements tighten thermal packaging qualification for biologics distribution through Paris and Lyon logistics hubs. EU Green Deal procurement incentives favor lower-global-warming-potential insulation technologies in public health system tenders. Sofrigam SA Ltd exemplifies regulatory depth navigation across EMA and GDP compliance frameworks.
United Kingdom
MHRA post-Brexit regulatory autonomy maintains alignment with EU GDP standards while preserving CE marking recognition for thermal packaging equipment. London's clinical trial logistics sector demands hybrid vacuum-insulated panel systems for gene-modified product transport. The Southeast's pharmaceutical distribution concentration drives consolidation around full-service cold chain platform providers.
Isothermal Bags Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tiers where regulatory documentation capabilities separate premium positioning from commodity supply. Consolidation pressure intensifies as pharmaceutical buyers bundle equipment, monitoring, and compliance documentation into multi-year performance contracts. Three archetypes dominate: integrated cold chain platform providers, vacuum-insulated panel technology specialists, and regional gel pack fabricators. Strategic moves concentrate on capacity expansion in Bavaria and Saxony manufacturing clusters alongside technology licensing agreements for phase-change material formulations.
Among German-based specialists, va-Q-tec AG and Sofrigam SA Ltd occupy positions within the regulatory-depth tier, exemplifying how EMA GDP compliance navigation anchors competitive positioning. Pelican Biothermal LLC represents the North American manufacturing footprint archetype, while Cryopak Europe anchors European distribution specialization. These named entities illustrate how geographic concentration and certification depth stratify market access rather than scale alone.
| Leading Market Players |
|---|
| Sonoco Products Company |
| Pelican Biothermal LLC |
| Cryopak Europe |
| Sofrigam SA Ltd |
| Cold & Co Sprl |
| Envirotainer Ltd |
| va-Q-tec AG |
| Berry Global, Inc. |
| Tecnisample s.l. |
| Others |
Supply & Pricing Matrix
Bavarian vacuum-insulated panel manufacturing clusters concentrate upstream capacity, anchoring margin pools in pharmaceutical-grade thermal enclosure qualification services rather than commodity bag fabrication. REACH compliance costs and F-Gas Regulation material substitutions redistribute pricing power toward suppliers with in-house regulatory documentation capabilities.
Pricing Analysis
Cost-plus contracts with aluminum indexation dominate pharmaceutical procurement, insulating German and French suppliers from raw material volatility while compressing margins for non-integrated fabricators. Three-tier pricing structure across validated cold chain, standard insulated, and consumer recreational tiers separates EMA GDP-compliant documentation bundles from basic thermal performance. Pricing pressure stems from RoHS flame retardant substitution costs in polyethylene exteriors. Food transport buyers exhibit highest price sensitivity; cell therapy logistics buyers prioritize qualification depth over unit cost.
Supply Chain Analysis
Tariff exposure between primary aluminum smelting jurisdictions and EU carbon border adjustment mechanisms dominates input cost risk for multi-layer insulation composites. Manufacturing concentrates in Germany, France, and the United States for pharmaceutical-grade systems, with China and Vietnam supplying consumer-tier flexible exteriors. Raw material dependencies center on metallized PET films, silica aerogel precursors, and phase-change material formulations. Single-source vulnerability concentrates in European aerogel core supply. Distribution runs through specialized cold chain platform providers consolidating equipment, monitoring, and compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of professionals combining heat transfer modeling with pharmaceutical regulatory documentation constrains product development velocity and creates acquisition premiums for qualified engineering teams. This capability gap stratifies competitive tiers between documentation-capable incumbents and commodity suppliers.
For Market Incumbents: Insulate position by deepening backward integration into vacuum-insulated panel core manufacturing in Bavaria and Saxony clusters, capturing margin otherwise lost to aerogel suppliers. Accelerate IATA CEIV Pharma certification investment to preempt emerging entrants lacking validation infrastructure. Defend against cold-chain-as-a-service platform consolidation by bundling serialized temperature monitoring with multi-year performance contracts. For New Entrants and Emerging Players: Establish a beachhead in India's CDSCO-harmonized clinical trial corridors, where multinational pharmaceutical sponsor demand outpaces qualified local supply. Target last-mile drone delivery integration for East African vaccine programs, a segment bypassed by incumbent pharmaceutical-focused portfolios. Lead with gel pack-integrated bag configurations displacing ice-based cooling in cost-constrained health systems. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional gel pack fabricators lacking EMA GDP compliance depth. Long-term viability hinges on regulatory documentation capabilities becoming table stakes for pharmaceutical procurement. Watch for IATA CEIV Pharma certification backlogs as inflection signal—extended validation timelines indicate demand outstripping qualified supplier capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Vacuum-Insulated Panels | va-Q-tec AG's Bavarian production scaling shortens lead times for ultra-low temperature systems. |
| Backward Integration into Aerogel Core Supply | In-house silica aerogel manufacturing reduces dependency on limited European commercial-scale suppliers. |
| EMA GDP Compliance Certification Investment | Documentation capabilities separate premium pharmaceutical procurement from commoditized food service tiers. |
| Phase-Change Material Formulation Licensing | Technology partnerships accelerate hybrid system development for cell therapy minus-eighty-degree logistics. |
| Cold-Chain-as-a-Service Platform Consolidation | Benelux and Nordic hospital procurement authorities bundle equipment, monitoring, and compliance into multi-year contracts. |
Research Methodology
Cross-validation between cold chain logistics director interviews and EMA GDP guideline documentation anchors the qualitative findings. Primary fieldwork engaged pharmaceutical packaging procurement managers, thermal qualification engineers, clinical trial supply chain leads, and regulatory affairs specialists across Germany, France, the United States, and India. Secondary sources included FDA 21 CFR Part 211 filings, EMA submissions, IATA CEIV Pharma certification registries, and REACH restriction candidate list updates. Bottom-up demand modeling triangulated against top-down pharmaceutical cold chain expenditure estimates.
Calibration against historical vacuum-insulated panel adoption curves and phase-change material penetration rates validated the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product architecture, insulation composition, end-use thermal specifications, and regional regulatory cluster. CAGRs derived from weighted average of demand-side pharmaceutical biologics growth and supply-side material substitution timelines. Industry-specific inputs included cell therapy logistics expansion trajectories and EU F-Gas Regulation phase-down schedules.
Stress conditions across aluminum price volatility, aerogel supply disruption, and CEIV Pharma certification timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization progress and material science innovation adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
PE Jumbo Bags Market
Bags and Containers
Jumbo Bags Market
Bags and Containers
Water Soluble Bags Market
Bags and Containers
Trash Can Liners Market
Bags and Containers
Multiwall Bags Market
Bags and Containers
Liquid Packaging Bag Market
Bags and Containers
Global Polypropylene Woven Bags and Sacks Market
Bags and Containers
Bakery Bread Bag Market
Bags and Containers
Pasted Valve Bags Market
Bags and Containers
Bulk Bag Divider Market
Bags and Containers
Anti-Static Polyethylene Bag Market
Bags and Containers
Bin Liners Market
Bags and Containers
Bag-In-Box Filler Market
Bags and Containers
Ventilated Bulk Bags Market
Bags and Containers
Lawn and Leaf Bags Market
Bags and Containers
Trash Bags Market