
 Cross Bottom Bags Market | 2026-2036
Cross Bottom Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Cross Bottom Bags Market Analytics
Multi-source sourcing of kraft paper and specialty films is pivoting as converters seek supply resilience against pulp price volatility. Smurfit Kappa Group leverages its integrated European pulp network to sustain margin stability across cross bottom bag contracts. Novolex Holdings anchors North American food service demand through proprietary extrusion and converting assets. Greif competes in industrial-grade segments where moisture-resistant paper grades command specification premiums.
Cross bottom bags are square-bottomed paper or plastic containers sealed at four corners to create a flat base, typically constructed from 40-80 gsm kraft paper or laminated polypropylene with side gussets expanding capacity by 30-50% over flat styles. These bags serve primary commercial purposes in food retail, agriculture, and industrial powder containment where self-standing stability and stacking efficiency matter. Paper material types now lead volume in European food service channels as brand owners phase out plastic under Extended Producer Responsibility frameworks. Medium size grades represent the fastest-expanding segment within retail end users where portion-controlled bakery and deli formats standardize packaging footprints. Flexographic printing methods dominate agricultural and industrial applications where single-color branding and regulatory markings suffice at lowest unit cost.
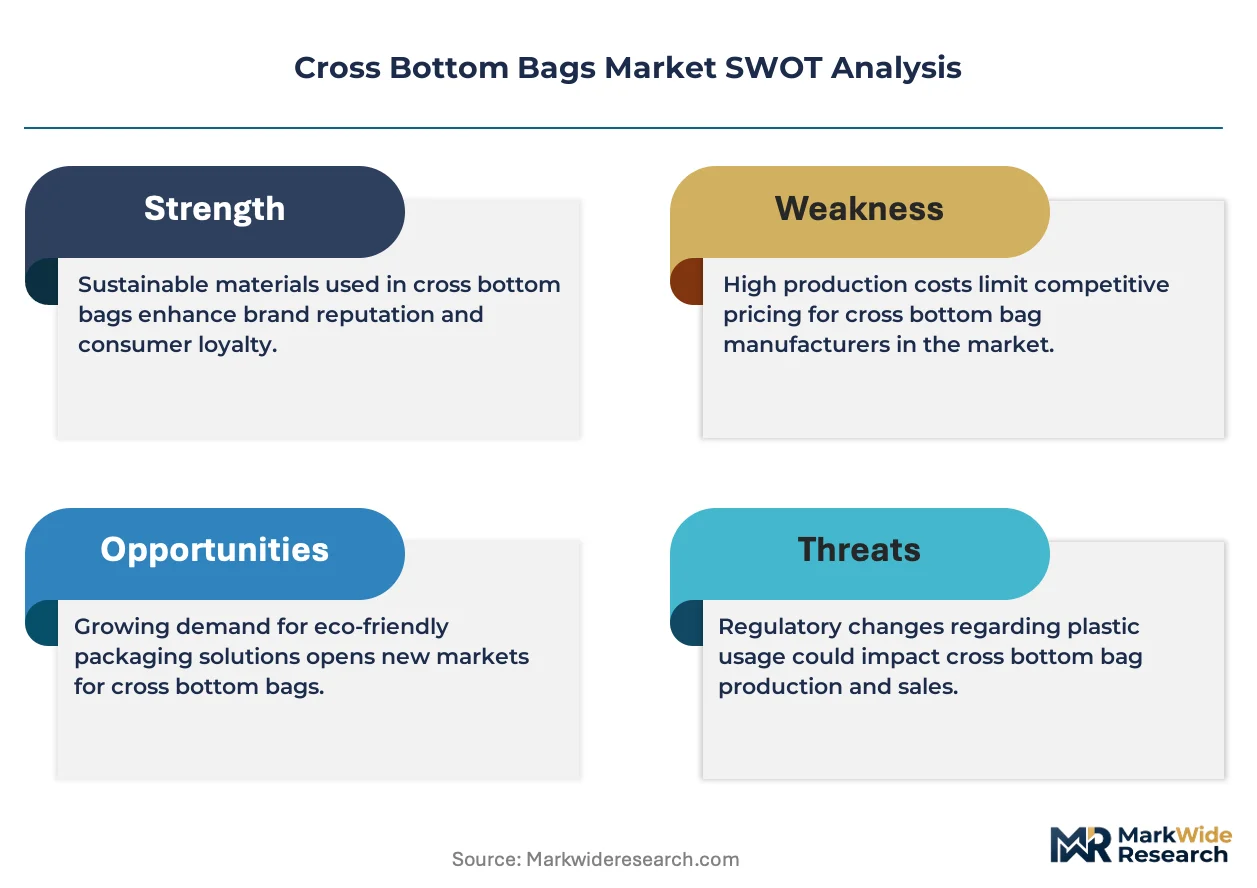
FDA food contact substance regulations govern paper and adhesive compositions for US food service applications, while REACH restricts certain fluorinated treatments once common in grease-resistant kraft grades across European supply chains. EFSA guidelines on mineral oil saturated hydrocarbons in recycled fiber are pressing mills toward virgin or controlled recycled content certifications. Stakeholders must monitor evolving state-level plastic bag bans in California and New York that create asymmetric compliance obligations for multi-region suppliers.
Market Dynamics
Material substitution mandates under the EU Packaging Waste Directive are forcing converters to reengineer multi-layer structures toward mono-material or fiber-based alternatives, compressing lead times and tightening specification control across supply chains.
Growth Catalysts
- Extended Producer Responsibility frameworks:European brand owners now face financial liability for post-consumer packaging waste, accelerating paper bag adoption in bakery and deli formats across Germany and France.
- Quick-service restaurant expansion:Hot and cold takeaway packaging specifications at major food service chains are standardizing cross bottom bag footprints for operational efficiency.
- Grease-resistant kraft innovation:Fluorine-free barrier coatings are achieving performance parity with legacy treatments while satisfying EFSA mineral oil migration thresholds.
Market Restraints
- Pulp price volatility:Unbleached softwood kraft supply concentration in Nordic and Baltic mills exposes converters to freight and energy cost swings.
- Recycled fiber contamination limits:EFSA guidelines on mineral oil saturated hydrocarbons restrict post-consumer content in food-contact grades, raising raw material costs.
- Flexible plastic substitution:High-barrier polyethylene and polypropylene pouches retain cost advantages in moisture-sensitive industrial powder applications.
Strategic Opportunities
- North American state-level plastic bans:California and New York asymmetric compliance obligations create first-mover positioning for paper-based suppliers with multi-region certification.
- Agricultural seed and feed packaging:Moisture-resistant paper grades with flexographic printing are penetrating crop protection distribution channels previously dominated by woven polypropylene.
- Digital printing convergence:Inkjet and toner-based systems enable short-run customization for seasonal bakery promotions without plate changeover costs.
Industry Challenges
- Barrier chemistry reformulation:Eliminating per- and polyfluoroalkyl substances while maintaining hot-grease resistance requires extended R&D timelines and mill-scale validation.
- Adhesive migration compliance:FDA food contact substance regulations for cross bottom bag seams demand lot-level testing documentation that strains quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cross Bottom Bags Market |
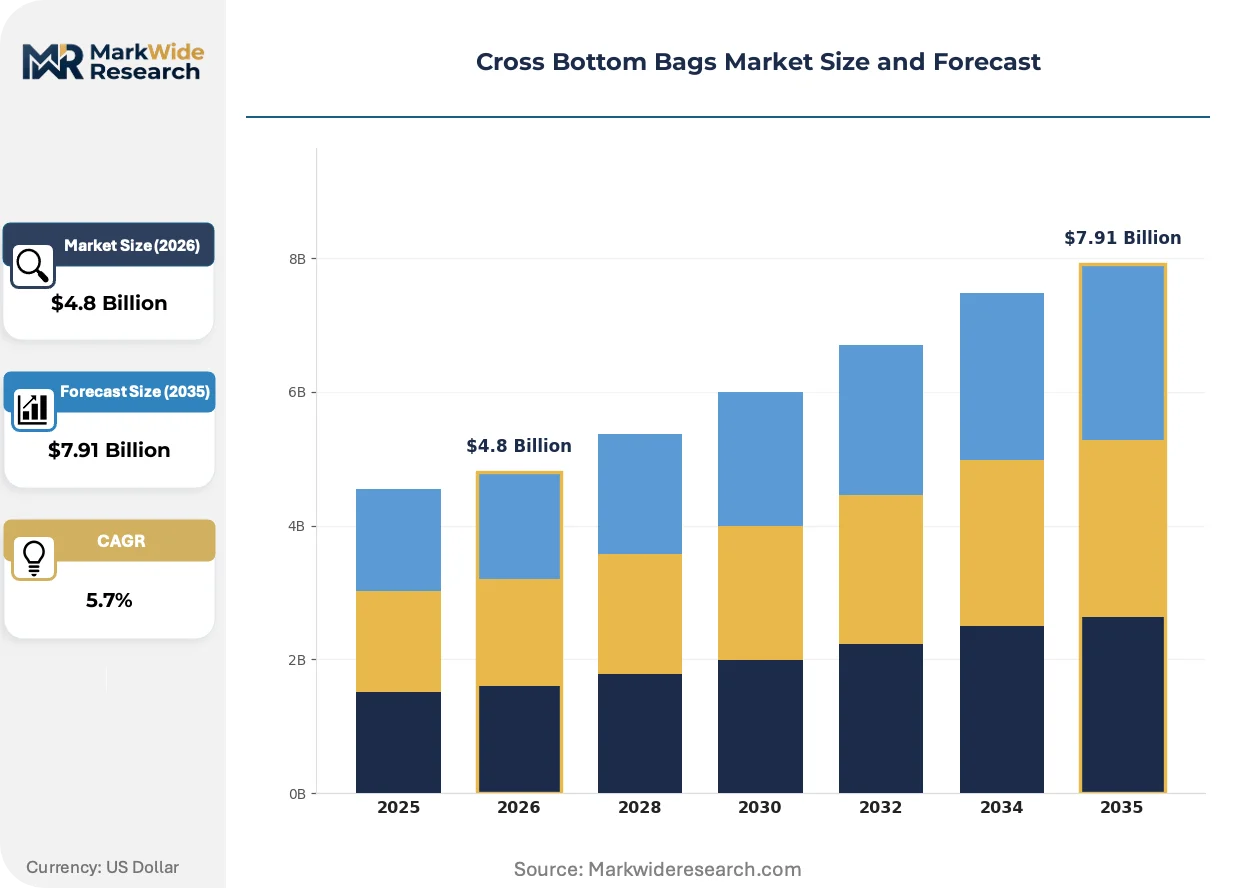
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Biodegradable, Composite End User: Retail, Food Service, Agriculture, Industrial Size: Small, Medium, Large, Extra Large Printing Method: Flexographic, Gravure, Digital, Offset |
| Companies Covered | International Paper Company, Novolex Holdings, Inc., Smurfit Kappa Group, Amcor Limited, Berry Global Inc., Greif, Inc., LC Packaging International BV, Conitex Sonoco, Sack Industrials Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cross Bottom Bags Market Evolving Landscape
Active material science breakthroughs and regulatory chemistry bans are compressing product development cycles while opening specification windows for novel barrier technologies.
Water-based acrylic barrier coatings are consolidating technical credibility as the successor to fluorinated grease-resistant treatments. Bakery chains in Germany and Austria are qualifying these coatings for hot pastry applications at accelerated pace. The shift is consolidating supplier power among integrated paper mills with captive coating capacity, squeezing independent converters.
REACH restrictions on perfluorinated compounds have eliminated legacy grease-resistant kraft grades from European food service supply chains. Mills must now certify virgin fiber streams and controlled recycled content under EFSA mineral oil protocols. Prepared food retail formats in France and Italy are absorbing modest price premiums for compliant specifications.
Brand owners are consolidating SKU portfolios around standardized bag dimensions to optimize shelf merchandising and logistics cube utilization. Medium-size cross bottom bags with 30-50% gusset expansion are displacing flat styles in deli and bakery cases. This concentration is most visible in German food retail where private label standardization drives volume concentration toward approved supplier lists.
Cross Bottom Bags Market Segmentation
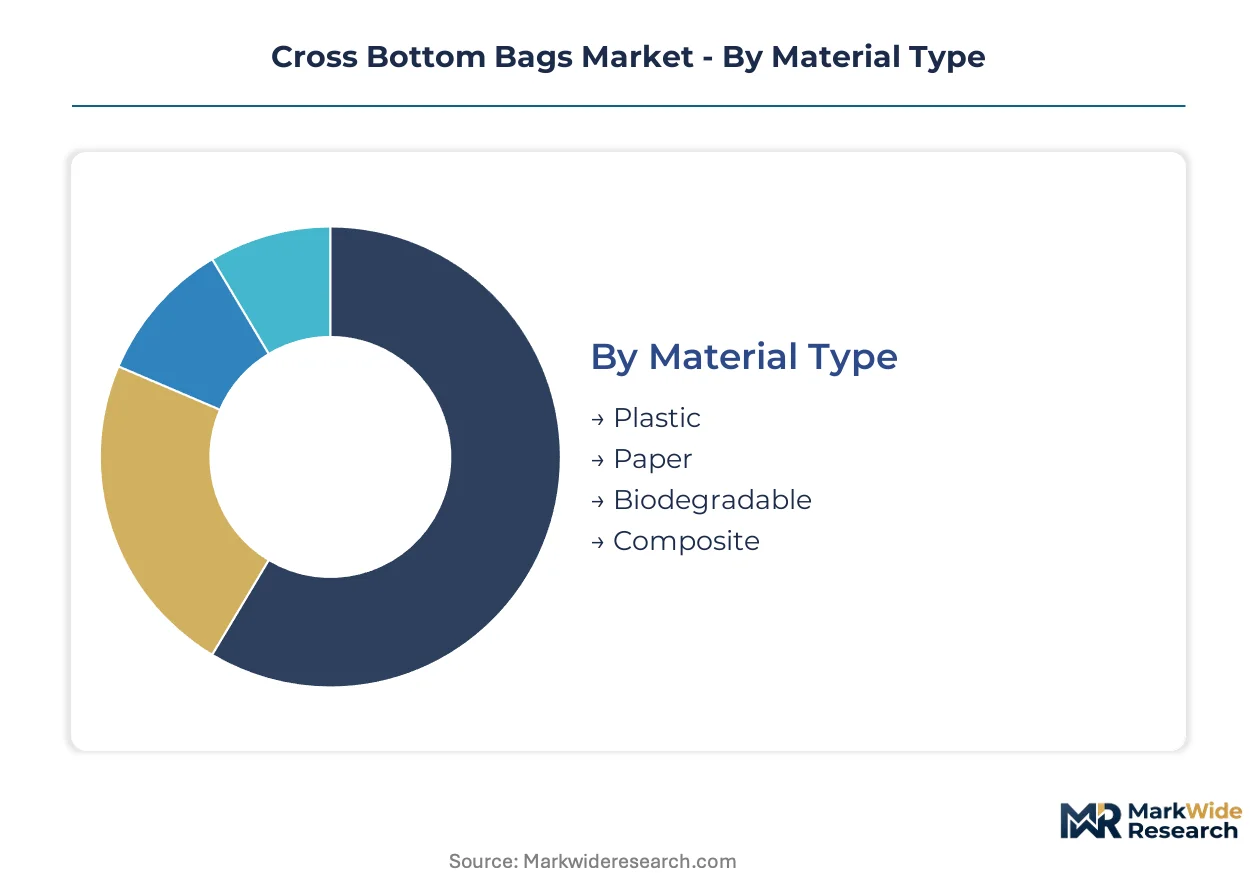
Cross bottom bag specifications diverge sharply across material grades and end-use channels, with regulatory chemistry bans and food contact compliance creating rigid qualification barriers that segment supply chains into distinct certification tiers.
Material Type:
Customization intensity runs highest in barrier-coated paper grades where fluorine-free formulations require mill-specific validation, while plastic and biodegradable alternatives standardize around established extrusion and composting protocols.
- Paper:Unbleached kraft grades from 40-80 gsm dominate European food service channels under EFSA mineral oil protocols. German bakery chains and French prepared food retailers absorb price premiums for virgin fiber certifications that satisfy post-consumer content restrictions.
- Plastic:Laminated polypropylene and polyethylene structures retain cost advantages in moisture-sensitive industrial powder containment. REACH multi-layer restrictions are forcing converters toward mono-material designs that sacrifice barrier performance for recyclability compliance.
- Biodegradable:PLA and starch-based films serve niche agricultural seed packaging where soil contact justifies compostability premiums.
- Composite:Paper-plastic laminates persist in high-barrier deli applications pending full chemistry reformulation to eliminate perfluorinated treatments.
Most installed capacity flows through Paper. Expansion is steepest in Biodegradable.
End User:
Volume concentration tracks directly against regulatory exposure, with food-facing segments bearing the heaviest compliance burden while industrial buyers prioritize unit economics over certification depth.
- Food Service:Quick-service restaurant chains standardize cross bottom bag footprints for hot and cold takeaway operational efficiency. Major operators in Germany and France are consolidating approved supplier lists around REACH-compliant paper specifications.
- Retail:Private label standardization in German food retail drives medium-size bag concentration toward approved vendor pools. Shelf merchandising optimization favors 30-50% gusset expansion formats over legacy flat styles.
- Agriculture:Moisture-resistant paper grades with flexographic printing penetrate crop protection distribution channels previously served by woven polypropylene. Seed and feed packaging specifications are shifting toward paper-based alternatives in European markets.
- Industrial:Powder containment applications favor high-barrier plastic structures where moisture ingress tolerance is lowest. FDA food contact substance regulations rarely apply, reducing qualification overhead.
Food Service commands the dominant revenue share. Retail is gaining share fastest.
Size:
Portion control standardization in prepared food formats is collapsing SKU proliferation toward mid-range dimensions that optimize logistics cube utilization and display case compatibility.
- Medium:30-50% gusset expansion capacity serves deli and bakery portion control formats across German and Austrian retail chains. This dimension balances shelf presence with transport density for refrigerated supply chains.
- Small:Single-serve pastry and confectionery applications in French urban convenience formats favor compact footprints that minimize material cost per unit.
- Large:Bulk agricultural seed and industrial powder volumes require structural reinforcement that increases per-unit material cost disproportionately.
- Extra Large:Limited adoption concentrated in specialty crop protection and construction additive segments where filling volumes exceed standard equipment tolerances.
Medium size grades absorb the majority of new capacity investment. Small formats are climbing the fastest.
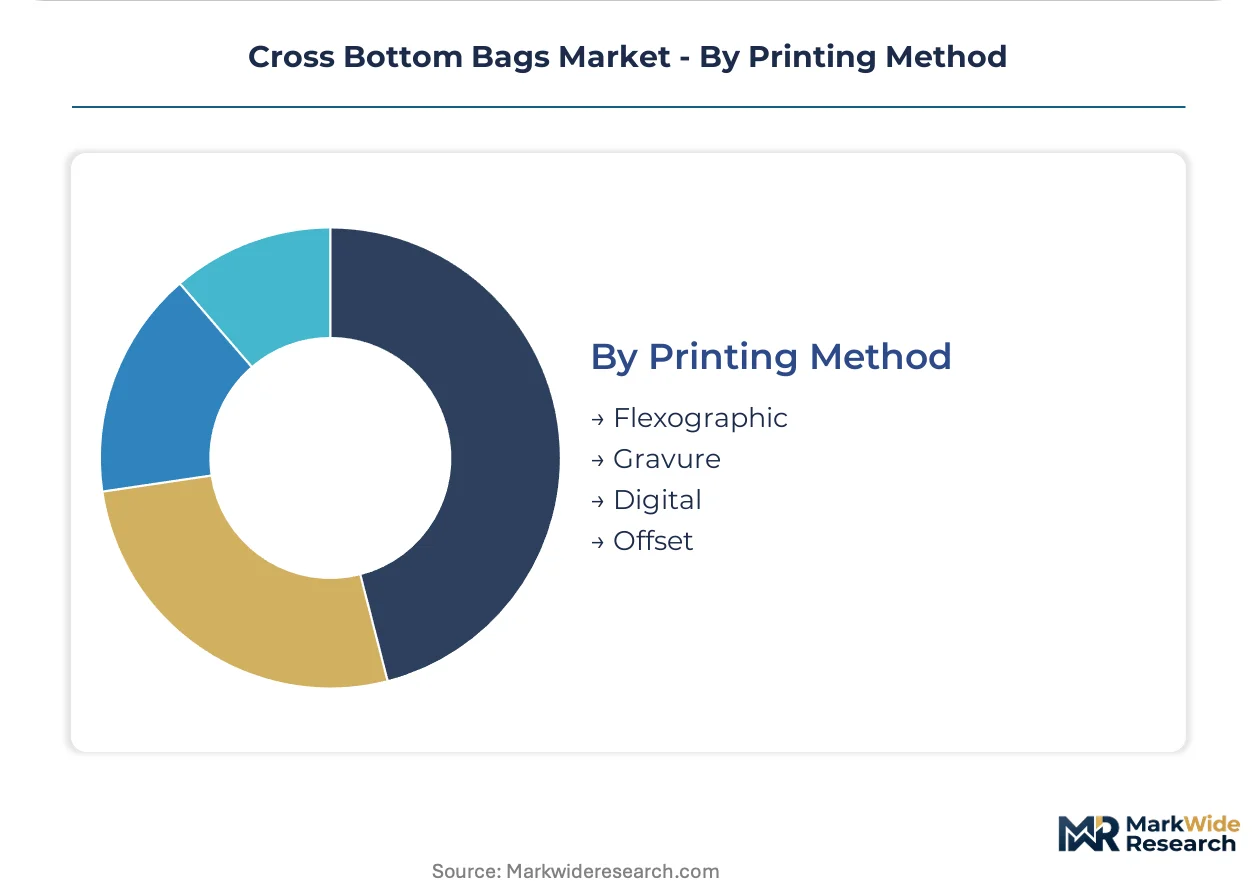
Printing Method:
Run length economics and color registration requirements divide the technology base, with long-run agricultural and industrial applications tolerating plate-based systems while promotional retail demands digital flexibility.
- Flexographic:Single-color branding and regulatory markings at lowest unit cost dominate agricultural seed packaging and industrial powder containment. Anilox roller specifications standardize across European converters.
- Digital:Inkjet and toner-based systems enable short-run seasonal bakery promotions without plate changeover costs. German retail chains are piloting personalization for private label limited editions.
- Gravure:High-volume food service contracts with consistent artwork leverage cylinder durability for extended production runs.
- Offset:Premium retail applications requiring photographic reproduction quality retain niche positioning despite higher per-unit costs.
Flexographic equipment represents the largest installed base. Digital is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German food retail clusters in Bavaria and North Rhine-Westphalia dominate European cross bottom bag consumption. Bakery chains and prepared food operators across Munich, Cologne, and Düsseldorf absorb premium paper specifications under REACH compliance mandates. The regional pattern concentrates converter capacity near major pulp terminals.
Germany
Bakery and deli format expansion drives medium-size bag standardization across REWE and EDEKA private label programs. EFSA mineral oil protocols restrict post-consumer fiber content in food-contact grades. Converter networks cluster around Hamburg port facilities for Nordic kraft pulp access.
France
Urban convenience formats in Paris and Lyon favor compact small-size bags for single-serve pastry applications. ANSM enforces strict food contact substance documentation for imported paper packaging. Prepared food retailers in Île-de-France absorb price premiums for compliant virgin fiber certifications.
United States
Quick-service restaurant chains standardize cross bottom footprints for operational efficiency in California and New York markets. FDA food contact substance regulations govern adhesive and coating compositions for hot takeaway applications. State-level plastic bag bans create asymmetric compliance obligations for multi-region suppliers.
Italy
Artisan bakery traditions in Lombardy and Emilia-Romagna sustain demand for premium printed paper bags. REACH restrictions on perfluorinated compounds eliminate legacy grease-resistant grades from food service channels. Milan-based packaging distributors consolidate approved supplier lists around fluorine-free barrier coatings.
United Kingdom
Supermarket bakery counters in London and Southeast England transition from plastic to paper-based takeaway formats. Extended Producer Responsibility frameworks impose financial liability for post-consumer packaging waste. Major retailers specify medium-size gusseted bags for refrigerated supply chain compatibility.
Cross Bottom Bags Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biodegradable material niches and digital printing capabilities. The vendor base organizes around three archetypes: integrated paper mills with captive pulp supply, independent converters with regional flexographic capacity, and specialty film laminators serving industrial moisture-barrier applications. Dominant competitive moves include backward integration into coating chemistry and geographic expansion through distributor partnerships in state-ban markets.
Within the integrated mill tier, Smurfit Kappa Group and International Paper Company exemplify scale-driven positioning through European and North American pulp network control. Novolex Holdings anchors food service specialization with proprietary extrusion assets. These three entities represent distinct competitive vectors: pulp integration, regional converting density, and end-use application depth.
| Leading Market Players |
|---|
| International Paper Company |
| Novolex Holdings, Inc. |
| Smurfit Kappa Group |
| Amcor Limited |
| Berry Global Inc. |
| Greif, Inc. |
| LC Packaging International BV |
| Conitex Sonoco |
| Sack Industrials Inc. |
| Others |
Value Network & Pricing Analysis
Family-owned Nordic pulp mills anchor supply-side discipline through long-term offtake relationships with German converters, translating softwood kraft concentration into asymmetric pricing power against fragmented independent bag producers. This ownership structure insulates raw material costs from spot volatility while compressing margins for non-integrated competitors across European food service channels.
Pricing Analysis
Input-cost pass-through from unbleached softwood kraft pulp dominates pricing dynamics, with Nordic mill concentration enabling rapid freight and energy surcharge recovery. Three-tier pricing structure across premium virgin-fiber, standard controlled-recycled, and economy industrial grades separates EFSA-compliant food-contact specifications from moisture-barrier plastic alternatives. Pricing pressure stems from fluorine-free coating R&D amortization costs. Quick-service restaurant chains exhibit highest price sensitivity due to standardized footprint requirements, while artisan bakery formats absorb premiums for certified barrier performance.
Supply Chain Analysis
Single-source vulnerability sits with Baltic and Nordic pulp terminals serving Hamburg and Rotterdam converter clusters, exposing downstream bag producers to ice-bound shipping seasonality. Geographic supply concentration centers on Sweden, Finland, and Estonia for virgin kraft, with German and French converters drawing from these feedstocks. Raw material dependencies rest on softwood pulp, water-based acrylic barrier chemistries, and FDA-compliant food-contact adhesives. Supply chain risk manifests through REACH chemical restriction compliance timelines. Distribution runs through approved supplier lists maintained by REWE, EDEKA, and major French retail consolidators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EU Packaging Waste Directive material substitution mandates driving paper-based specification demand across German and French food retail channels.
For Market Incumbents: Extend fluorine-free coating capacity through backward integration into captive chemistry production, defending margin position against specialty film laminators encroaching from industrial segments. Consolidate approved supplier list status with REWE and EDEKA through EFSA mineral oil certification investments. Prioritize digital printing asset deployment for seasonal bakery promotion flexibility. For New Entrants and Emerging Players: REACH restrictions on perfluorinated compounds in France and Italy open a window for water-based acrylic barrier specialists to penetrate artisan bakery segments previously locked by legacy grease-resistant kraft incumbents. Target compact small-size bag formats for Paris and Lyon urban convenience channels. Pursue distributor partnership routes rather than direct retail procurement access. For Investors and Strategic Acquirers: Valuations sit cheapest among independent flexographic converters lacking captive pulp supply or barrier coating capabilities. Five-to-ten year viability hinges on regulatory chemistry ban acceleration outpacing R&D amortization capacity. Monitor California and New York state-level plastic ban implementation velocity as inflection signal for North American paper bag demand migration.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Coating Scale-Up | REACH compliance deadlines in Germany and France eliminate legacy grease-resistant grades from approved supplier lists. |
| Digital Printing Asset Deployment | German retail chains pilot personalized private label limited editions without plate changeover costs. |
| Nordic Pulp Terminal Partnership | Long-term offtake agreements with Swedish and Finnish mills insulate converters from freight volatility. |
| California Distribution Network Expansion | State-level plastic bag bans create asymmetric compliance obligations favoring pre-certified paper suppliers. |
| EFSA Mineral Oil Certification Investment | Virgin fiber documentation requirements restrict post-consumer content in food-contact grades. |
Research Methodology
Bottom-up food service operator modeling reconciled against top-down pulp mill capacity tracking forms the analytical core, combining primary interviews with quick-service restaurant procurement directors, German retail category managers, Nordic pulp mill sales executives, and flexographic converter operations heads with secondary validation through REACH regulatory filings, EFSA guidance documents, FDA food contact substance registrations, and European paper industry association capacity surveys.
Historical trendline analysis across material substitution patterns and regulatory compliance cost trajectories informs projection modeling over the analysis window, with segmentation dimensions spanning material type, end-use channel, size grade, and printing method. CAGRs derive from installed capacity expansion announcements, approved supplier list consolidation trends, and barrier coating qualification timelines. Forecast inputs incorporate EFSA mineral oil protocol adoption curves and state-level plastic ban legislative tracking.
Forecast precision tightens around the base case; tail outcomes carry wider variance under pulp price spike scenarios or accelerated perfluorinated compound restriction timelines. Forecasts reflect documented assumptions regarding REACH implementation velocity and quick-service restaurant chain standardization decisions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Breather Bags Market
Bags and Containers
Twin Seal Bags Market
Bags and Containers
Bulk Bags Market
Bags and Containers
Conical Bags Packaging Market
Bags and Containers
Inflatable Bags Packaging Market
Bags and Containers
Bin Liners Market
Bags and Containers
Bag on Valve Technology Market
Bags and Containers
Anti-Static Collapsible Tote Bins Market
Bags and Containers
4-Loop FIBC Market
Bags and Containers
Drum Liners Market
Bags and Containers
Dome Shrink Basket Bags Market
Bags and Containers
Isothermal Bags Market
Bags and Containers
Woven Bags Market
Bags and Containers
Bag in Drum Market
Bags and Containers
Loop Handle Bags Market
Bags and Containers
Single Lip Bags Market