
 Isosorbide-Based Engineering Polymer Monomers Market | 2026-2036
Isosorbide-Based Engineering Polymer Monomers Market Size, Share, and Industry Trends Forecast 2026-2036
Isosorbide-Based Engineering Polymer Monomers Market Insights
The EU Green Deal is recalibrating procurement criteria across European automotive and electronics supply chains. Roquette Frères leverages its starch-based feedstock infrastructure to anchor isosorbide production in France. Mitsubishi Chemical Group competes through specialized dimethacrylate grades for optical applications. Covestro differentiates via polycarbonate copolymer platforms incorporating isosorbide biscarbonates.
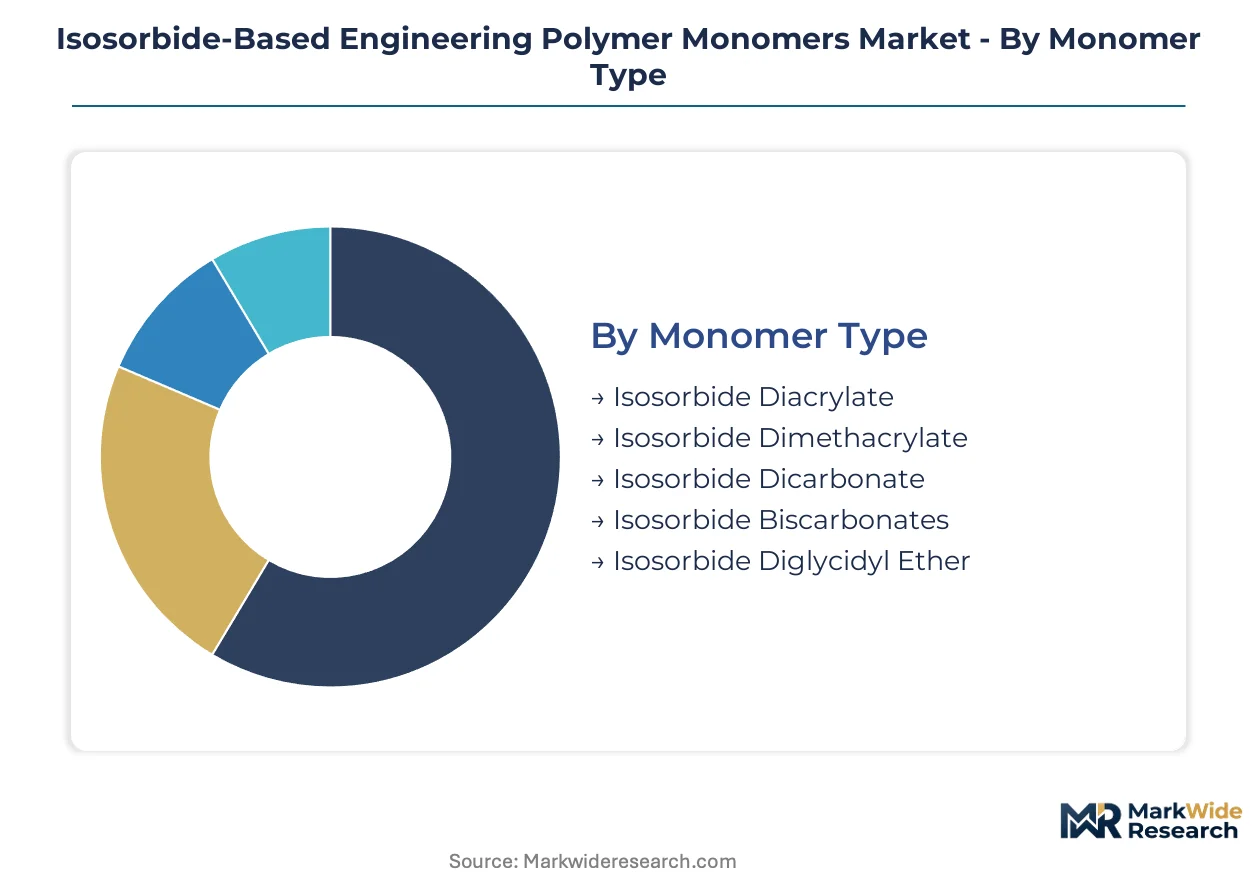
Isosorbide-based engineering polymer monomers comprise rigid bicyclic diol derivatives synthesized from sorbitol dehydration, featuring glass transition temperatures exceeding 150°C in polycarbonate copolymers and optical clarity comparable to bisphenol-A analogues. These monomers serve primarily as petrochemical replacements in high-performance thermoplastics and UV-curable systems. Isosorbide dicarbonate variants lead the monomer type landscape due to established polycarbonate copolymer demand. Free radical polymerization dominates the technology mix for acrylate and methacrylate grades, while ring-opening polymerization captures growth in epoxy and thermoset applications where diglycidyl ether derivatives offer low shrinkage and high crosslink density.
REACH registration requirements and the EU F-Gas Regulation shape monomer purity standards and restrict perfluorinated processing aids in polymerization. EMA guidelines on medical device biocompatibility and FDA biocompatibility testing protocols for implantable electronics create dual certification burdens for suppliers targeting healthcare-adjacent electronics packaging. Stakeholders must monitor evolving bio-based content thresholds in public procurement rules across France, Germany, and Japan to anticipate specification shifts before they harden into mandatory minimums.
Market Dynamics
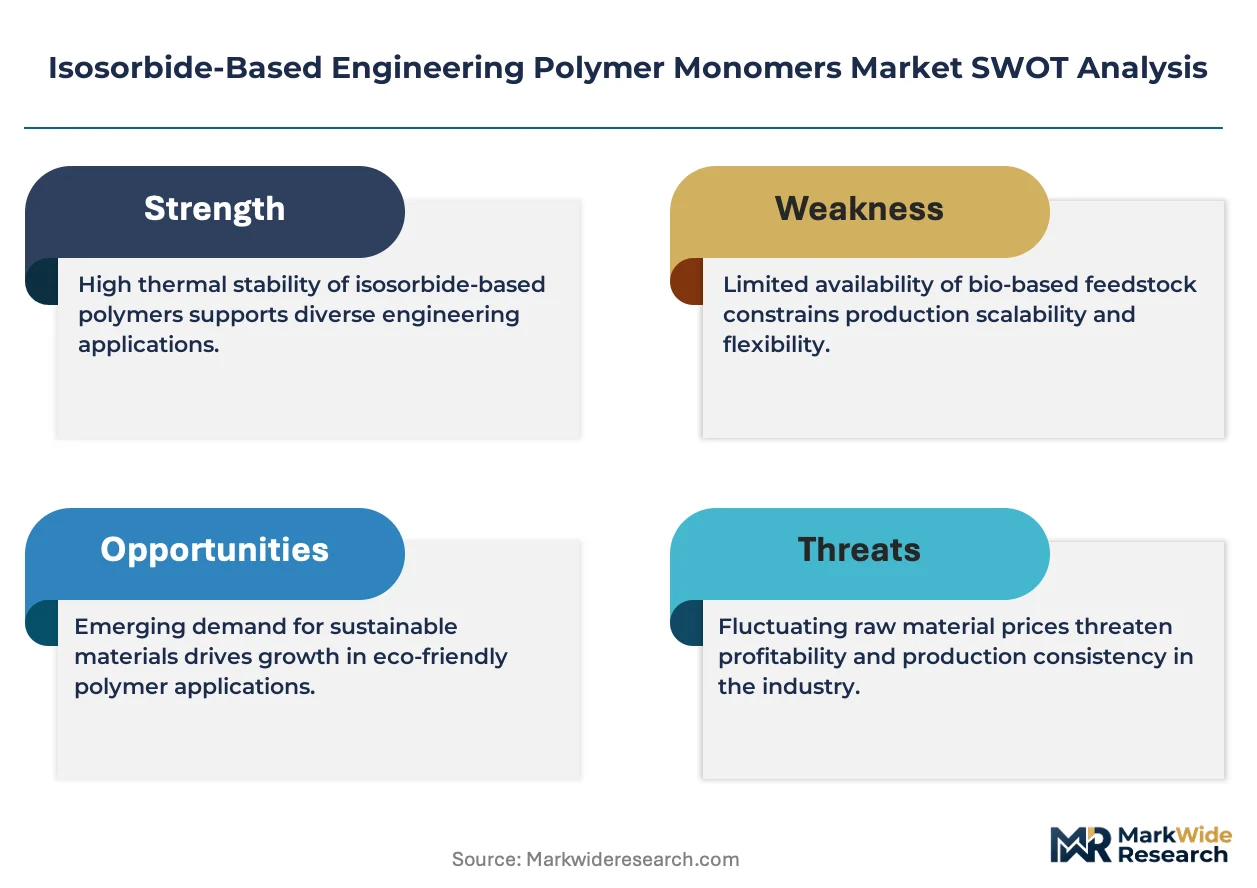
The EU Green Deal's bio-based content mandates are forcing automotive and electronics manufacturers to requalify entire polymer supply chains around isosorbide-derived monomers. REACH registration deadlines and F-Gas processing aid restrictions compound this pressure, creating a structural pivot away from bisphenol-A and petrochemical diols.
Growth Catalysts
- REACH Compliance Deadlines:ECHA registration requirements for high-volume chemicals are blocking conventional petrochemical monomer imports, redirecting formulation work toward isosorbide dicarbonates and dimethacrylates with existing dossiers.
- Automotive Interior Mandates:German and French vehicle assemblers now specify bio-based monomers for dashboard and door panel applications, pulling isosorbide polycarbonate copolymers into Tier 1 supplier qualification pipelines.
- Sorbitol Dehydration Yields:Advances in catalytic dehydration efficiency are compressing production costs for isosorbide diol, narrowing the feedstock cost gap with petroleum-derived bisphenol-A.
Market Restraints
- Feedstock Concentration Risk:Sorbitol supply concentrates among starch processors in the US Midwest and Northern France, exposing monomer producers to agricultural commodity volatility and single-source dependency.
- Purity Specification Ceilings:Medical device and optical-grade applications demand isosorbide monomer purity above 99.95%, requiring capital-intensive crystallization trains that smaller producers cannot finance.
- Bisphenol-A Cost Asymmetry:Conventional polycarbonate monomers retain a 40-60% cost advantage at scale, limiting isosorbide penetration in price-sensitive packaging and construction segments.
Strategic Opportunities
- Japan Medical Electronics Packaging:PMDA biocompatibility protocols for implantable device housings create a certification moat where isosorbide polycarbonates' non-estrogenic profile commands premium positioning against bisphenol-A alternatives.
- UV-Curable Optical Coatings:Convergence of isosorbide dimethacrylates with LED-curing lithography equipment is opening wafer-level packaging applications in semiconductor fabrication.
- French Public Procurement Thresholds:Upcoming bio-based minimums in state-funded infrastructure projects will mandate isosorbide content in specified coating and adhesive categories.
Industry Challenges
- Specialized Polymer Chemistry Talent:Formulation expertise bridging carbohydrate chemistry and high-performance thermoplastics remains concentrated among retirees from legacy cellulose derivative producers, constraining R&D velocity.
- Dual Certification Burden:Suppliers targeting healthcare-adjacent electronics must simultaneously satisfy FDA biocompatibility testing protocols and EMA medical device guidelines, extending qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isosorbide-Based Engineering Polymer Monomers Market |
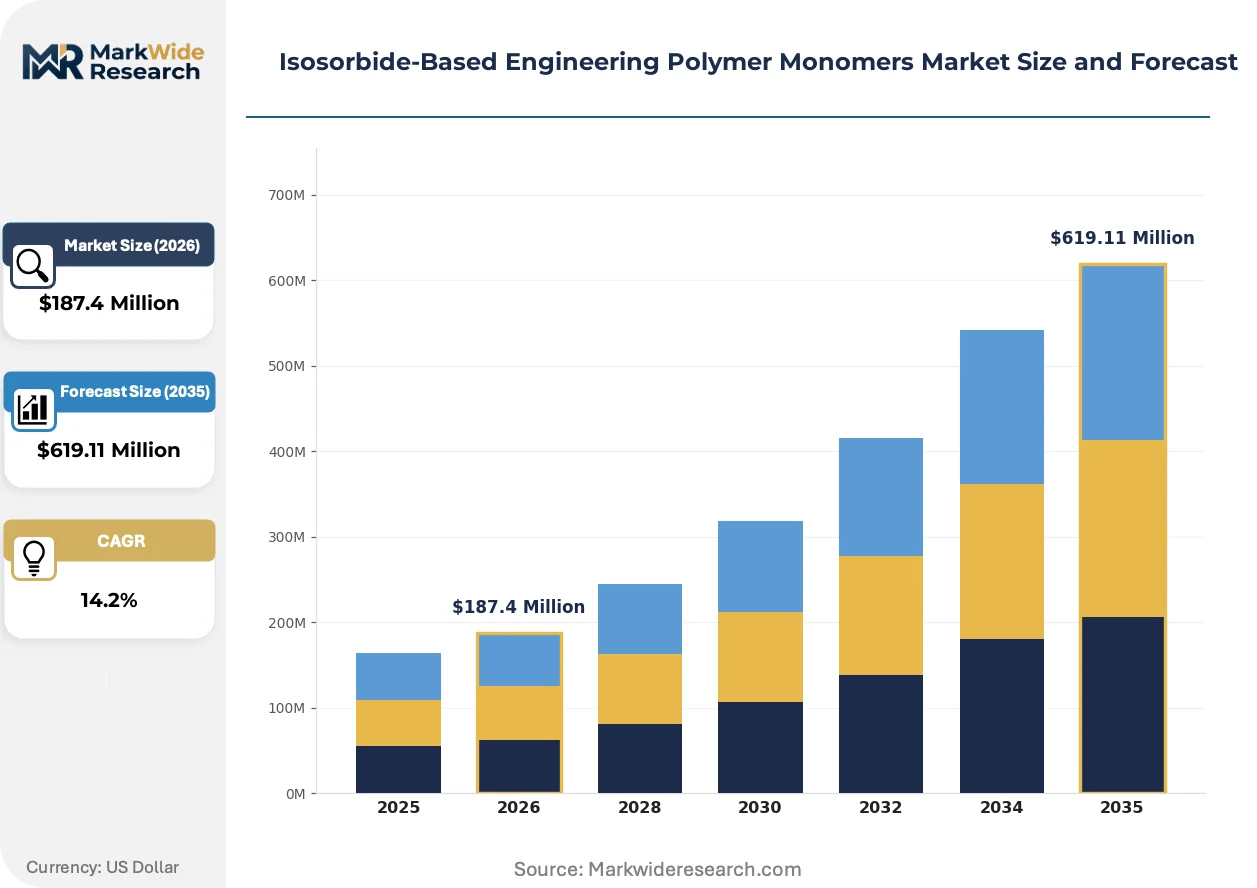
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Monomer Type: Isosorbide Diacrylate, Isosorbide Dimethacrylate, Isosorbide Dicarbonate, Isosorbide Biscarbonates, Isosorbide Diglycidyl Ether Application: Coatings, Adhesives, Electronics, Packaging, Automotive Components End User Industry: Consumer Electronics Manufacturers, Packaging Firms, Vehicle Assemblers, Furniture Producers, Textile Fabricators Polymerization Technology: Free Radical Polymerization, Step-Growth Polymerization, Ring-Opening Polymerization, Controlled Radical Polymerization, Emulsion Polymerization |
| Companies Covered | Roquette Frères, Mitsubishi Chemical Group, Mitsui Chemicals, Covestro, BASF SE, Toray Industries, Teijin, Indorama Ventures, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isosorbide-Based Engineering Polymer Monomers Market Trends and Innovations
Continuous processing technology and bio-refinery integration are compressing isosorbide monomer production economics while regulatory pressure on endocrine-disrupting chemicals accelerates formulation substitution in optical and medical-grade polymers.
Continuous flow reactors for sorbitol dehydration are decentralizing isosorbide production away from centralized batch chemical plants. Specialty polymer compounders in the US and Germany are adopting these modular systems to secure captive monomer supply. This distributed manufacturing model is compressing logistics costs and enabling just-in-time qualification for automotive Tier 1 contracts.
The EU F-Gas Regulation's phase-down of perfluorinated processing aids is forcing polymerization facilities to retool around non-fluorinated surfactants and internal mold release systems. Isosorbide-based polycarbonate copolymers process effectively under these constrained conditions due to lower melt viscosity profiles. Optical sheet extruders in Italy and the Netherlands are converting production lines ahead of the 2030 ban deadlines.
Specification-driven procurement now dominates electronics packaging polymer selection, with OEM technical teams embedding bio-based content thresholds directly into component qualification scorecards. Distributors serving medical device manufacturers are restructuring inventory around certified isosorbide grades with pre-submitted FDA master files. This preference shift is most visible in German and Swiss precision electronics clusters where supply chain audit requirements have tightened.
Isosorbide-Based Engineering Polymer Monomers Market Segmentation
Formulation engineers select isosorbide monomers based on polymerization compatibility and end-use performance thresholds. Specification requirements from German vehicle assemblers and Japanese electronics OEMs cascade through each segment, compressing qualification timelines for suppliers.
Monomer Type:
Buyers prioritize thermal stability and optical clarity when selecting monomer chemistry for polycarbonate copolymers and UV-curable systems.
- Isosorbide Dicarbonate:Polycarbonate copolymer feedstock achieving glass transition temperatures above 150°C. Demand concentrates in automotive interior panels where German assemblers enforce bio-based content mandates through Tier 1 supplier contracts.
- Isosorbide Dimethacrylate:Bicyclic diol methacrylate enabling low-shrinkage optical coatings. Japanese semiconductor packaging houses specify this grade for wafer-level lithography applications requiring LED-curing compatibility.
- Isosorbide Diacrylate:Fast-curing acrylate monomer for industrial coatings and graphic arts.
- Isosorbide Biscarbonates:Higher-functionality carbonate variants for crosslinked thermoset networks.
- Isosorbide Diglycidyl Ether:Epoxy precursor delivering low shrinkage and high crosslink density in electronic encapsulants.
Isosorbide dicarbonate leads on scale; isosorbide dimethacrylate leads on momentum.
Application:
REACH compliance deadlines and F-Gas processing restrictions are redirecting formulation work toward segments with established regulatory dossiers.
- Coatings:UV-curable and powder coating systems replacing petrochemical diols in industrial finishes. French public procurement thresholds for bio-based infrastructure coatings are pulling isosorbide grades into state-funded projects.
- Electronics:Semiconductor packaging and implantable device housings requiring non-estrogenic polycarbonates. PMDA biocompatibility protocols in Japan create premium positioning against bisphenol-A alternatives.
- Automotive Components:Dashboard and door panel substrates for German and French vehicle platforms.
- Adhesives:Structural bonding systems for furniture and transportation assembly.
- Packaging:Medical and food-contact films facing cost pressure from conventional polycarbonates.
Coatings dominate current volume; electronics climbs the fastest on specification premiums.
End User Industry:
Procurement teams in regulated industries embed bio-based thresholds directly into supplier scorecards, segmenting demand by certification burden.
- Vehicle Assemblers:German and French OEMs specifying isosorbide polycarbonates for interior panels. EU Green Deal mandates cascade through Tier 1 supplier qualification pipelines with compressed requalification timelines.
- Consumer Electronics Manufacturers:Swiss and German precision electronics clusters requiring supply chain audit documentation for medical-adjacent device housings.
- Packaging Firms:Medical device and food-contact film producers navigating FDA and EMA dual certification requirements.
- Furniture Producers:Adhesive and coating formulators serving EU bio-based procurement rules.
- Textile Fabricators:Technical textile coatings with emerging isosorbide content specifications.
Vehicle assemblers command the largest order volumes; consumer electronics manufacturers pay the steepest specification premiums.
Polymerization Technology:
Process selection hinges on monomer functionality and end-use performance requirements, with F-Gas restrictions eliminating perfluorinated processing aids from several routes.
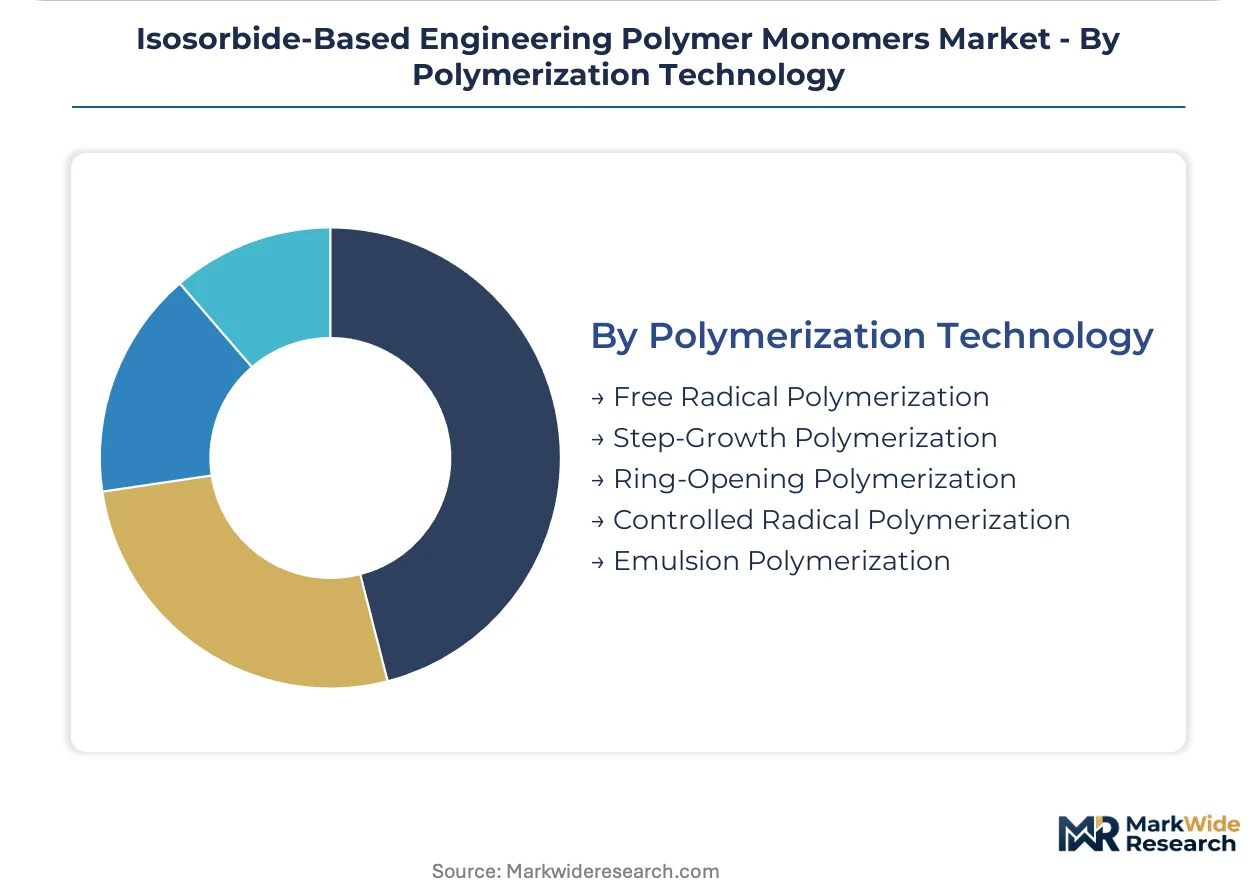
- Free Radical Polymerization:Dominant route for acrylate and methacrylate grades in coating and adhesive applications. Italian and Dutch optical sheet extruders are converting production lines ahead of 2030 F-Gas ban deadlines due to favorable melt viscosity profiles.
- Ring-Opening Polymerization:Capturing growth in epoxy and thermoset applications where diglycidyl ether derivatives deliver low shrinkage. Semiconductor packaging houses in Japan specify these systems for stress-sensitive wafer-level encapsulation.
- Step-Growth Polymerization:Polycarbonate copolymer production from dicarbonate monomers.
- Controlled Radical Polymerization:Precision molecular architecture for specialty coating resins.
- Emulsion Polymerization:Waterborne systems facing reformulation pressure from surfactant restrictions.
Free radical polymerization anchors current capacity; ring-opening polymerization expands most quickly on electronics demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial isosorbide production first achieved commercial scale in France during the early 2000s, establishing Northern France as the foundational geography for bio-based diol chemistry before capacity expansion spread to Germany and Japan.
France
Starch processors in the Picardy region supply feedstock for isosorbide diol production serving polycarbonate copolymer demand. The EU Green Deal's bio-based procurement thresholds for state-funded infrastructure projects mandate isosorbide content in specified coating categories. Lille-Roubaix chemical clusters host formulation facilities converting dicarbonate monomers into automotive interior panel substrates.
Germany
Vehicle assemblers in Bavaria and Baden-Württemberg enforce bio-based monomer specifications through Tier 1 supplier contracts for dashboard applications. REACH registration deadlines from ECHA redirect formulation work toward isosorbide dimethacrylates with existing dossiers. Frankfurt-Rhine-Main chemical corridors concentrate optical-grade polycarbonate extrusion capacity ahead of 2030 F-Gas ban deadlines.
Japan
PMDA biocompatibility protocols for implantable device housings create premium positioning for non-estrogenic polycarbonates against bisphenol-A alternatives. Semiconductor packaging houses in the Tokyo-Yokohama corridor specify isosorbide diglycidyl ether derivatives for stress-sensitive wafer-level encapsulation. Osaka-Kobe industrial zones host specialty polymer compounders qualifying medical electronics grades.
United States
Midwest starch processors in Iowa and Illinois concentrate sorbitol supply for isosorbide feedstock, exposing producers to agricultural commodity volatility. FDA biocompatibility testing protocols for healthcare-adjacent electronics packaging create dual certification burdens with EMA requirements. Houston-Gulf Coast petrochemical corridors are retrofitting continuous flow reactors for modular isosorbide production.
Netherlands
Optical sheet extruders in Eindhoven and Rotterdam are converting production lines to process isosorbide-based polycarbonate copolymers under constrained F-Gas conditions. The country's national chemical regulator enforces purity specifications above 99.95% for medical-grade applications. Amsterdam-Rotterdam-Antwerp logistics hubs distribute certified monomer grades to German automotive supply chains.
Isosorbide-Based Engineering Polymer Monomers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the isosorbide monomer landscape, with integrated starch processors maintaining captive feedstock advantages while specialty chemical houses focus on high-purity crystallization and qualification services. The vendor base separates into three archetypes: agricultural conglomerates with backward integration into sorbitol supply, diversified chemical majors leveraging polycarbonate copolymer platforms, and niche optical-grade specialists serving semiconductor packaging houses. Competitive dynamics center on capacity expansion in continuous flow dehydration technology and strategic partnerships bridging carbohydrate chemistry expertise with automotive Tier 1 qualification pipelines.
Among European agricultural processors, Roquette Frères anchors the feedstock-integrated tier through its starch-based infrastructure in Northern France. Mitsubishi Chemical Group and Covestro exemplify the diversified chemical major archetype, with the former occupying a position in specialized methacrylate grades and the latter representing polycarbonate copolymer platform strategies. These three companies collectively illustrate how competitive positioning depends on controlling either upstream agricultural supply or downstream polymer formulation channels.
| Leading Market Players |
|---|
| Roquette Frères |
| Mitsubishi Chemical Group |
| Mitsui Chemicals |
| Covestro |
| BASF SE |
| Toray Industries |
| Teijin |
| Indorama Ventures |
| Eastman Chemical Company |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between optical-grade and industrial-grade isosorbide monomers manifests in both pricing stratification and supply chain configuration. Medical device and semiconductor packaging buyers absorb 40-60% premiums for 99.95% purity crystallization trains, while automotive interior panel specifications tolerate lower grades sourced through distributed batch processors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs isosorbide monomer transactions. Premium tiers attach to FDA-master-filed and PMDA-certified grades for implantable electronics, while standard tiers serve REACH-compliant automotive specifications and economy tiers address industrial coating formulations. Cost compression in the economy tier intensifies because bisphenol-A retains substantial feedstock advantages. Automotive Tier 1 suppliers exhibit highest price sensitivity due to volume procurement mandates, whereas Japanese semiconductor packaging houses show least sensitivity given biocompatibility certification requirements.
Supply Chain Analysis
Sorbitol feedstock supply rests on starch processors in the US Midwest, Northern France, and Northeast China. Isosorbide diol production draws from catalytic dehydration facilities, polycarbonate copolymer extrusion lines, and specialty crystallization trains. Single-source vulnerability concentrates in Picardy-region agricultural supply where climate volatility disrupts feedstock availability. Distribution runs through Amsterdam-Rotterdam-Antwerp chemical hubs serving German automotive corridors and Swiss precision electronics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The isosorbide-based engineering polymer monomers market compounds steadily as EU Green Deal bio-based mandates harden across automotive and electronics procurement specifications.
For Market Incumbents: To counter feedstock concentration risk in Northern France, secure backward integration into Midwest US sorbitol supply or establish dual-source starch partnerships with Northeast Chinese processors. Prioritize capacity addition in continuous flow dehydration technology to compress unit economics ahead of 2030 F-Gas ban deadlines. For New Entrants and Emerging Players: Capture white-space opportunity in UV-curable optical coatings for Japanese semiconductor packaging houses where LED-curing compatibility specifications create qualification moats. Penetrate French public procurement coating categories ahead of mandatory bio-based threshold implementation. Lead with pre-submitted FDA master file positioning to accelerate medical electronics qualification timelines. For Investors and Strategic Acquirers: Consolidation pressure builds where specialty crystallization capabilities and existing REACH dossiers concentrate among legacy cellulose derivative producers. Five-to-ten year viability favors asset-light compounders with captive carbohydrate chemistry expertise over pure-play monomer producers exposed to agricultural commodity cycles. Watch PMDA biocompatibility protocol expansions as inflection signal for premium grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sorbitol Supply | Roquette Frères leverages Picardy starch infrastructure to anchor captive feedstock security. |
| Continuous Flow Reactor Deployment | Modular dehydration systems compress logistics costs for just-in-time automotive Tier 1 contracts. |
| FDA Master File Pre-Submission | Pre-submitted biocompatibility dossiers accelerate qualification for implantable electronics packaging. |
| REACH Dossier Expansion | Existing ECHA registrations for dimethacrylate grades block petrochemical monomer import competition. |
| Joint Venture with Optical Sheet Extruders | Italian and Dutch converters retool production lines ahead of F-Gas processing aid bans. |
Research Methodology
Bottom-up automotive and electronics packaging modeling reconciled against top-down sorbitol dehydration capacity tracking forms the analytical core. Primary interviews with plant managers at starch processing facilities, procurement leads at German Tier 1 automotive suppliers, technical R&D directors at polycarbonate compounders, and regulatory affairs specialists at medical device OEMs combined with secondary validation from ECHA registration databases, EU customs trade data, SEC 10-K chemical segment disclosures, and PMDA medical device filings.
Input-output matrices map monomer grade production volumes through polymerization technology routes to end-use applications across the analysis window. Segmentation dimensions modeled include monomer functionality tier, polymerization chemistry type, end-use industry vertical, and regional regulatory cluster. CAGRs derive from supply-side capacity expansion schedules cross-referenced against demand pull from bio-based procurement mandates. Forecast inputs incorporate catalytic dehydration yield improvements and REACH registration timeline accelerations.
Feedstock price volatility, regulatory dossier approval delays, and F-Gas ban implementation timing are the dominant revision risks. Forecasts reflect documented assumptions regarding sorbitol supply stability and automotive qualification pipeline conversion rates. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Europe Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Asia-Pacific Polymer Emulsion Market
Polymers & Resins
Global Polyurethane Dispersions Market
Polymers & Resins
Global Polymer Market
Polymers & Resins
Polymer Modifiers Market
Polymers & Resins
Photocure Resins Market
Polymers & Resins
Polycyclohexylenedimethylene Terephthalate (PCT) Market
Polymers & Resins
Polyolefin Compound Market
Polymers & Resins
Renewable PVDF Market
Polymers & Resins
Long-Chain Polyamide Market
Polymers & Resins
Soy Polysaccharides Market
Polymers & Resins
Bio-Based Emulsion Polymers Market
Polymers & Resins
Styrene Acrylonitrile (SAN) Resins Market
Polymers & Resins
Polytetramethylene Ether Glycol (PTMEG) Market
Polymers & Resins
Europe Polycarbonate (PC) Market
Polymers & Resins
Bio-Based Polypropylene in Medical Devices Market