
 Bio-Based Emulsion Polymers Market | 2026-2036
Bio-Based Emulsion Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based Emulsion Polymers Market Outlook
Performance-grade bio-based emulsion specifications is collapsing the gap between petroleum-derived and renewable feedstock polymers. BASF SE leverages its integrated biopolymer R&D pipeline to anchor European supply for high-solid waterborne coatings. Dow Inc. sustains North American manufacturing scale across acrylic emulsion platforms, while Arkema S.A. differentiates through specialty bio-sourced monomer technology for adhesive formulations.
Bio-based emulsion polymers are aqueous dispersions of synthetic or naturally derived polymers with particle sizes typically ranging from 0.1 to 1.0 micrometers, produced through free-radical emulsion polymerization using surfactant-stabilized systems; these materials function primarily as film-forming binders that confer adhesion, durability, and barrier properties to applied coatings and bonded substrates. Acrylic emulsions dominate volume consumption in architectural coatings where weathering resistance and gloss retention command premium positioning, while waterborne technology captures the fastest expansion trajectory as regulatory VOC ceilings tighten across manufacturing jurisdictions. Styrene-acrylic hybrids concentrate margin pools in industrial maintenance and automotive refinish segments where balance of cost and performance remains critical.
EPA restrictions on hazardous air pollutants and REACH Annex XVII limitations on solvent content are reshaping product standards, compelling manufacturers to validate bio-content claims through third-party certification. FDA indirect food contact guidelines and EU Ecolabel criteria further constrain additive packages and residual monomer thresholds in packaging-adjacent coating applications. Stakeholders must monitor feedstock certification schemes and polymerization efficiency benchmarks as the primary variables determining cost-competitive scale.
Market Dynamics
REACH Annex XVII solvent restrictions and EPA hazardous air pollutant rules are compressing reformulation timelines, forcing coatings manufacturers to validate bio-content through third-party certification schemes before qualifying for automotive OEM and construction material supplier scorecards.
Growth Catalysts
- REACH VOC ceilings:European architectural coatings procurement now mandates waterborne systems, pulling styrene-acrylic emulsion volumes into industrial maintenance segments previously served by solvent-borne alkyds.
- Automotive OEM sustainability scorecards:Tier-1 suppliers to Volkswagen, BMW, and Ford now require validated bio-based binder content in refinish and OEM coating specifications.
- Starch and lignin feedstock processing:Pilot-scale biorefineries in Germany and the United States are achieving polymerization-grade monomer purity from agricultural residues, narrowing cost gaps with petroleum-derived acrylic acid.
Market Restraints
- Propylene oxide price volatility:Acrylic emulsion feedstock costs fluctuate with crude oil benchmarks, compressing margin buffers for producers lacking backward integration into bio-based alcohols.
- Specialty surfactant supply concentration:German and Dutch chemical clusters control 60% of reactive surfactant capacity for high-solid emulsion polymerization, creating single-source risk for new entrants.
- Residual monomer thresholds:FDA indirect food contact guidelines and EU Ecolabel criteria constrain additive packages, limiting formulation flexibility in packaging-adjacent applications.
Strategic Opportunities
- Underpenetrated Indian architectural coatings:BIS energy efficiency building codes and FSSAI-adjacent state regulations are creating first-mover windows for waterborne bio-based primers in commercial construction.
- Adhesive convergence with pressure-sensitive tapes:E-commerce fulfillment demand is pulling bio-based acrylic emulsions into corrugated board sealing applications at specification-grade performance thresholds.
- EU Green Deal public procurement mandates:Member state infrastructure tenders now weight bio-based content at 15-20% of technical evaluation scores, redirecting specification authority toward sustainability-verified suppliers.
Industry Challenges
- Emulsion polymerization scale-up engineering:Heat removal and particle size distribution control at >50% solids content require reactor configurations unavailable from standard equipment vendors, extending commissioning timelines.
- Multi-standard certification complexity:USDA BioPreferred, TUV Austria OK Biobased, and DIN CERTCO schemes impose divergent testing protocols, forcing redundant analytical expenditure for multi-jurisdiction suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based Emulsion Polymers Market |
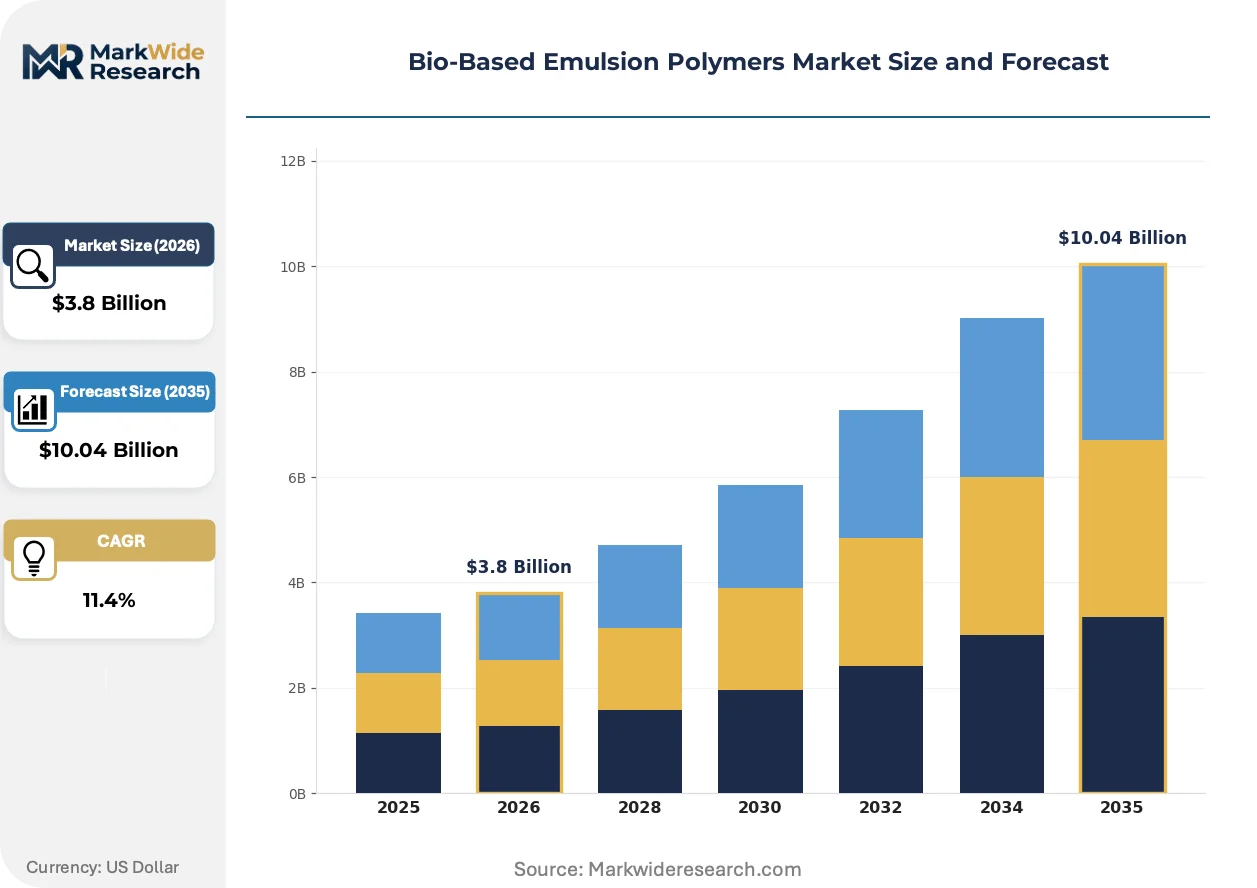
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Styrene-Acrylic, Polyvinyl Acetate, Others End Use Industry: Paints & Coatings, Adhesives, Textiles, Paper Application: Emulsion Paints, Adhesive Formulations, Coating Applications, Textile Finishing Technology: Solvent-Free, Waterborne, High Solid, Others |
| Companies Covered | Synthomer plc, Dow Inc., Arkema S.A., Solvay S.A., Celanese Corporation, BASF SE, Wacker Chemie AG, DIC Corporation, Trinseo PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based Emulsion Polymers Market Strategic Shifts
Reformulation chemistry is pivoting toward high-solid waterborne systems as regulatory pressure intensifies, with particle engineering and bio-monomer synthesis commanding disproportionate R&D allocation relative to conventional petroleum-derived emulsion platforms.
Hybrid bio-based styrene-acrylic emulsions are displacing conventional solvent-borne alkyds in industrial maintenance coatings. Marine and protective coatings contractors in Northern Europe are adopting these systems at specification-grade film build rates. The displacement is compressing alkyd resin capacity utilization and redirecting capital toward aqueous dispersion reactor trains.
REACH Annex XVII solvent content limitations and EPA National Emission Standards for Hazardous Air Pollutants are tightening in parallel enforcement waves. Coating manufacturers serving both jurisdictions face harmonized testing burdens for VOC content and residual monomer thresholds. Automotive refinish segments in Germany and the United States are responding with accelerated waterborne basecoat conversion programs.
Certification-driven supplier qualification is restructuring procurement relationships in construction materials. Tier-1 drywall and flooring adhesive buyers in France and California now require third-party bio-content validation before contract renewal. The shift favors emulsion producers with captive analytical laboratories and documented supply chain traceability over commodity distributors lacking certification infrastructure.
Bio-Based Emulsion Polymers Market Segmentation
Bio-based emulsion polymer specifications diverge sharply across end-use applications, with regulatory thresholds on volatile organic compounds and bio-content validation requirements forcing distinct formulation strategies for architectural coatings versus food-contact adhesives. Procurement patterns now favor suppliers capable of certifying feedstock provenance through multiple jurisdiction-specific schemes simultaneously.
Product Type:
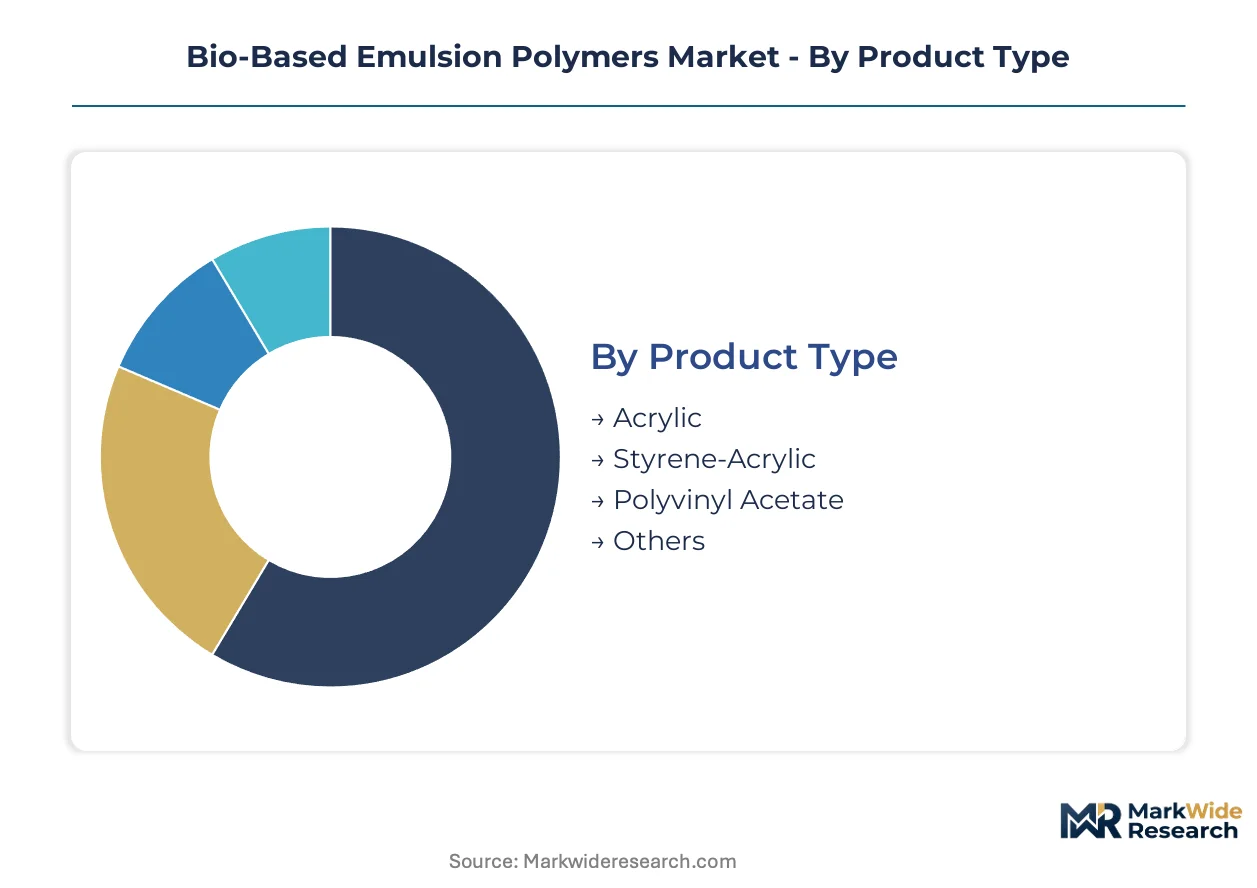
REACH Annex XVII solvent restrictions and EPA hazardous air pollutant rules differentiate compliance burdens across polymer chemistries, with acrylic and styrene-acrylic platforms facing distinct monomer residual thresholds and feedstock certification requirements.
- Acrylic:Aqueous dispersions of polyacrylate chains deliver superior weathering resistance and gloss retention in exterior architectural coatings. Demand concentrates in Germany and California where automotive OEM sustainability scorecards mandate validated bio-based binder content in refinish specifications.
- Styrene-Acrylic:Hybrid copolymer architectures balance cost performance with film integrity in industrial maintenance segments. Marine and protective coatings contractors in Northern Europe adopt these systems at specification-grade film build rates, displacing conventional solvent-borne alkyds.
- Polyvinyl Acetate:Cost-competitive homopolymer emulsions serve interior architectural primers and paper coating binders where moisture resistance requirements are moderate.
- Others:Bio-based polyurethane and epoxy emulsion platforms address specialty adhesive and textile lamination niches requiring elevated thermal or chemical resistance.
Acrylic handles the majority of throughput; styrene-acrylic is the fastest mover on share.
End Use Industry:
Customer procurement sophistication varies dramatically across end-use verticals, with automotive OEMs and construction material suppliers enforcing third-party bio-content validation that commodity adhesive buyers rarely require.
- Paints & Coatings:Film-forming binders confer adhesion, durability, and barrier properties to applied substrates. Architectural coatings procurement in France and California now mandates waterborne systems with documented supply chain traceability.
- Adhesives:Pressure-sensitive tape formulations for e-commerce corrugated board sealing pull bio-based acrylic emulsions into specification-grade performance thresholds. E-commerce fulfillment demand is accelerating conversion from solvent-borne systems.
- Textiles:Fabric finishing and lamination applications require emulsions with controlled hand-feel and wash durability, constrained by EU Ecolabel criteria on residual monomer thresholds.
- Paper:Surface sizing and coating binders prioritize cost efficiency over performance premium, with FDA indirect food contact guidelines limiting additive package flexibility in packaging-adjacent grades.
Paints and coatings dominates volume absorption; adhesives is climbing the fastest as e-commerce logistics specifications tighten.
Application:
Application-level specifications translate regulatory VOC ceilings into concrete technical requirements for film build rates, drying characteristics, and substrate compatibility.
- Emulsion Paints:Waterborne architectural coatings achieving weathering resistance and gloss retention through high-solid acrylic dispersions. German and US enforcement of REACH and EPA rules accelerates conversion from solvent-borne alkyds.
- Adhesive Formulations:Pressure-sensitive and structural bonding systems for corrugated board, flooring, and automotive assembly. Tier-1 suppliers to Volkswagen and BMW require validated bio-based content in bonding specifications.
- Coating Applications:Industrial maintenance and marine protective systems where film integrity under aggressive environments commands premium positioning. Northern European contractors lead specification-grade adoption of hybrid bio-based platforms.
- Textile Finishing:Soft-hand coatings and functional treatments for apparel and technical fabrics, constrained by divergent certification schemes across USDA BioPreferred, TUV Austria OK Biobased, and DIN CERTCO protocols.
Emulsion paints absorbs the largest share of polymer volumes; adhesive formulations is expanding most quickly as fulfillment infrastructure scales.
Technology:
Process technology selection determines capital intensity, emission profiles, and qualification timelines for automotive and construction procurement scorecards.
- Solvent-Free:Reactive hot-melt and radiation-cure systems eliminating volatile organic compound emissions entirely. Automotive refinish segments in Germany respond with accelerated conversion programs as REACH Annex XVII tightens.
- Waterborne:Aqueous dispersion platforms capturing regulatory-driven substitution across architectural and industrial coatings. Heat removal and particle size distribution control at elevated solids content require specialized reactor configurations unavailable from standard equipment vendors.
- High Solid:Emulsion polymerization above 50% solids content reduces drying energy and transport costs. Commissioning timelines extend due to engineering complexity in heat transfer and particle stability control.
- Others:Powder and UV-cure technologies addressing niche applications in furniture and electronics coatings where line speed and substrate heat sensitivity dominate specification criteria.
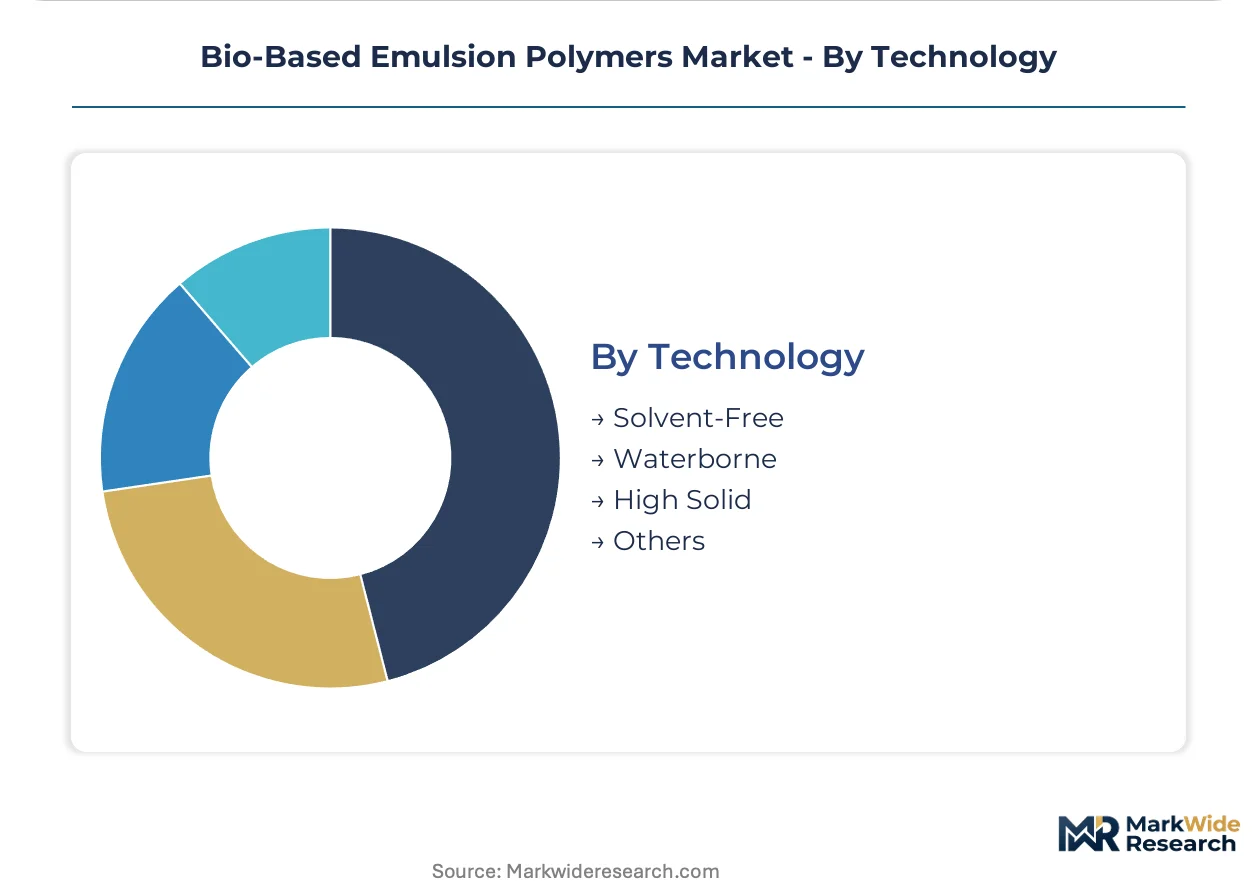
Waterborne technology carries the dominant installed base; high solid systems are gaining share fastest as energy efficiency and transport cost pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German bio-based emulsion polymer exports supply automotive coating formulators across the European Union, while Chinese production scales to serve domestic construction and packaging adhesive demand.
Germany
Automotive OEM sustainability scorecards from Volkswagen and BMW pull validated bio-based binder volumes into refinish specifications. REACH Annex XVII solvent restrictions compress reformulation timelines for industrial maintenance coatings. The Rhine-Ruhr chemical cluster anchors European supply for high-solid waterborne systems, with pilot-scale biorefineries achieving polymerization-grade monomer purity from agricultural residues.
United States
Construction material suppliers in California and Texas enforce third-party bio-content validation for architectural coatings procurement. EPA National Emission Standards for Hazardous Air Pollutants accelerate waterborne basecoat conversion in automotive refinish segments. The Gulf Coast petrochemical corridor hosts backward-integrated producers expanding acrylic emulsion capacity to serve packaging adhesive demand from e-commerce fulfillment infrastructure.
China
Domestic architectural coatings consumption concentrates in Yangtze River Delta and Pearl River Delta urban construction booms. Dual carbon goals and GB standards on VOC emissions redirect specification authority toward waterborne bio-based systems. Shanghai and Guangzhou chemical parks attract capacity investments for styrene-acrylic emulsions displacing solvent-borne alkyds in industrial maintenance.
India
BIS energy efficiency building codes and FSSAI-adjacent state regulations create first-mover windows for waterborne bio-based primers in commercial construction across Maharashtra and Gujarat. State-level public procurement mandates in infrastructure tenders weight bio-based content in technical evaluation scores. The Mumbai-Pune industrial corridor concentrates adhesive formulation demand from corrugated board sealing applications serving e-commerce logistics.
France
EU Green Deal public procurement mandates redirect specification authority toward sustainability-verified suppliers in infrastructure tenders. Tier-1 drywall and flooring adhesive buyers require third-party bio-content validation before contract renewal. The Lyon chemical cluster specializes in specialty bio-sourced monomer technology for adhesive formulations serving packaging-adjacent coating applications.
Bio-Based Emulsion Polymers Market Competitive Environment
Listed leaders compete with private specialists across certification infrastructure and feedstock integration depth. The vendor base concentrates around integrated chemical conglomerates with captive biopolymer R&D pipelines and regional specialists with dedicated emulsion polymerization assets. Three archetypes dominate: backward-integrated petrochemical majors with bio-based diversification programs, mid-cap emulsion specialists with third-party certification capabilities, and biorefinery-anchored innovators with agricultural residue feedstock contracts. Competitive moves center on multi-standard certification acquisition and high-solid reactor commissioning to capture automotive and construction procurement scorecards.
Within the integrated chemical conglomerate tier, BASF SE and Dow Inc. exemplify archetypes with European and North American manufacturing scale respectively. Arkema S.A. occupies a position among specialty bio-sourced monomer technology providers. These three entities represent distinct competitive vectors: feedstock integration depth, geographic manufacturing footprint, and specialty formulation expertise for adhesive applications.
| Leading Market Players |
|---|
| Synthomer plc |
| Dow Inc. |
| Arkema S.A. |
| Solvay S.A. |
| Celanese Corporation |
| BASF SE |
| Wacker Chemie AG |
| DIC Corporation |
| Trinseo PLC |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles for reactive surfactants in German and Dutch chemical clusters concentrate procurement leverage among backward-integrated emulsion producers, compressing margin buffers for distributors lacking captive monomer supply or multi-standard certification infrastructure.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command spreads through USDA BioPreferred and TUV Austria OK Biobased certification, while standard grades compete on volume scale and economy tiers serve interior architectural primers with minimal traceability. Price differentiation hinges on feedstock provenance documentation and polymerization efficiency benchmarks. Pricing pressure stems from propylene oxide cost volatility tracking crude oil benchmarks, with commodity distributors facing the steepest margin compression.
Supply Chain Analysis
Just-in-time inventory strategies dominate among automotive OEM coating formulators, while strategic stockpiling concentrates among construction material suppliers anticipating REACH Annex XVII enforcement waves. Raw material dependencies center on acrylic acid, styrene monomers, and specialty reactive surfactants. Supply concentrates in Germany, the United States, and China, with the Rhine-Ruhr and Gulf Coast corridors anchoring polymerization-grade capacity. Single-source vulnerability runs through German and Dutch surfactant clusters controlling sixty percent of reactive capacity. Distribution runs through technical distributors serving regional coating formulators and direct supply agreements with Tier-1 automotive suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bio-based emulsion polymers sit in early-cycle expansion as regulatory VOC ceilings tighten across automotive and construction procurement specifications, with validated bio-content becoming a non-negotiable qualifier for Tier-1 supplier scorecards.
For Market Incumbents: Consolidate certification infrastructure and captive monomer supply to defend against specialty biorefinery entrants achieving polymerization-grade purity from agricultural residues. Prioritize backward integration into bio-based alcohols to buffer propylene oxide price volatility. Commission high-solid reactor trains above fifty percent solids content to capture automotive OEM sustainability scorecards.
For New Entrants and Emerging Players: Anchor in underpenetrated Indian commercial construction corridors where BIS energy efficiency codes and state-level procurement mandates create first-mover windows for waterborne bio-based primers. Target corrugated board sealing applications serving e-commerce fulfillment infrastructure, where specification-grade performance thresholds are tightening fastest. Pursue direct technical partnerships with regional coating formulators lacking multi-standard certification capabilities.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized emulsion polymerization assets and dormant bio-based R&D pipelines. Five-to-ten year viability hinges on feedstock integration depth and certification infrastructure scale. Watch for inflection when EU Green Deal public procurement mandates expand bio-content weighting in infrastructure tenders beyond current fifteen-to-twenty percent technical evaluation thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Alcohols | Captive supply of fermentation-derived monomers buffers propylene oxide cost volatility for European producers. |
| Multi-Standard Certification Acquisition | USDA BioPreferred and DIN CERTCO documentation unlocks automotive OEM and construction procurement scorecards. |
| High-Solid Reactor Commissioning | Above-fifty-percent solids capacity reduces drying energy and qualifies suppliers for REACH Annex XVII compliance. |
| Biorefinery Feedstock Partnerships | Agricultural residue contracts with German and United States pilot facilities narrow cost gaps with petroleum-derived acrylic acid. |
| Regional Distribution Control | Technical distributor relationships in Maharashtra and Gujarat secure first-mover positioning under BIS energy efficiency codes. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with plant managers at emulsion polymerization facilities, procurement leads at automotive OEM coating divisions, technical R&D directors, and distribution channel partners; and secondary validation through customs and trade data, SEC 10-K filings, Cefic industry reports, and REACH Annex XVII regulatory filings. Bottom-up volume modeling triangulated against top-down market sizing across polymer chemistry, end-use industry, application, and technology segments.
Across the analysis window, the forecasting framework modeled demand trajectories by polymer grade tier, end-use vertical, regional production hub, and certification status. CAGRs derived from segment-level penetration curves and substitution elasticity against solvent-borne alternatives. Key inputs included automotive OEM sustainability scorecard adoption rates, biorefinery monomer purity achievements, and enforcement intensity of EPA National Emission Standards for Hazardous Air Pollutants.
Decision-makers should treat outputs as directional under base assumptions of sustained regulatory enforcement and bio-based feedstock cost convergence; material deviation would warrant model refresh. Specific risks include propylene oxide price volatility spikes, reactive surfactant supply disruptions, and delays in multi-standard certification harmonization. Revision becomes warranted when bio-based monomer production costs cross parity thresholds with petroleum-derived equivalents.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polymer Stabilizer Market
Polymers & Resins
Polyisoprene Latex Market
Polymers & Resins
Biobased Thermosetting Polymers Market
Polymers & Resins
Europe Polyacrylamide Market
Polymers & Resins
Thermoplastic Polyurethane (TPU) Market
Polymers & Resins
Molding and Trim Materials Market
Polymers & Resins
US Acrylic Solid Surface Market
Polymers & Resins
Europe Fluoropolymer Market
Polymers & Resins
Poly(P-Phenylene Ether) (PPE) Market
Polymers & Resins
Plastic Calendering Resins Market
Polymers & Resins
Bio-Based PVC Market
Polymers & Resins
United States Polyols Market
Polymers & Resins
Copolyesters Market
Polymers & Resins
Styrenics Market
Polymers & Resins
Epoxy Resin Reactive Diluent Market
Polymers & Resins
US Polycarbonate Market