
 Polycyclohexylenedimethylene Terephthalate (PCT) Market | 2026-2036
Polycyclohexylenedimethylene Terephthalate (PCT) Market Size, Share, and Industry Trends Forecast 2026-2036
Polycyclohexylenedimethylene Terephthalate (PCT) Market Analytics
South Korea is reshaping competitive dynamics in PCT resin supply through expanded polymerization capacity at Yeosu and Ulsan industrial complexes. SK Chemicals leverages backward integration into CHDM feedstock to sustain margin control across the value chain. Toray Industries anchors high-performance fiber-grade PCT production for automotive and electronics buyers in Asia-Pacific markets.
Polycyclohexylenedimethylene terephthalate is a semi-crystalline thermoplastic polyester synthesized from cyclohexanedimethanol and terephthalic acid, exhibiting heat deflection temperatures exceeding 100°C and superior hydrolytic stability against standard PET. Its primary industrial purpose centers on replacing metals and engineering plastics in thermal management components, electrical connectors, and industrial films where dimensional stability under humidity and elevated temperatures proves critical. Granules dominate volume throughput as the feedstock form for injection molding operations across automotive and electronics sectors, while films represent the fastest-expanding category driven by flexible circuit substrate and high-barrier packaging applications. Electronics housing applications command premium pricing due to UL 94 V-0 flame retardancy requirements and tight tolerances for miniaturized connector geometries.
REACH registration requirements in Europe, FDA food contact regulations in the United States, and China's GB standards for automotive plastics collectively elevate testing burdens and compliance costs for PCT compounders seeking multi-regional market access. Japan's METI chemical substance reporting framework adds further documentation requirements for imported resin formulations used in consumer electronics manufacturing. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as alternative flame-retardant synergies in PCT compounds face heightened regulatory scrutiny across major end-use jurisdictions.
Market Dynamics
Automotive electrification is compressing thermal management design cycles, forcing PCT compounders to qualify materials for integrated battery housings and inverter enclosures under stricter OEM timelines than traditional engine-bay components allowed.
Growth Catalysts
- China's dual carbon goals:Stricter GB standards for automotive plastics mandate higher heat deflection temperatures, accelerating PCT substitution of standard polyamides in under-the-hood connectors and sensors.
- Flexible circuit substrates:Film-grade PCT demand is virtualizing from smartphone manufacturing clusters in Vietnam and India as electronics assemblers diversify beyond China.
- REACH registration:ECHA compliance requirements for imported resin formulations create captive demand for EU-based compounders serving medical device and food contact applications.
Market Restraints
- CHDM feedstock concentration:Cyclohexanedimethanol supply concentrates among Asian petrochemical complexes, exposing compounders to input cost volatility and force majeure risks.
- Polyamide 6T substitution:High-performance nylons with comparable heat resistance threaten PCT adoption in cost-sensitive automotive connector applications.
- Flame-retardant regulatory friction:Per- and polyfluoroalkyl substance restrictions under REACH and state-level US mandates complicate UL 94 V-0 formulation pathways.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor and mobile device production create virgin demand for high-barrier PCT films in flexible circuit substrates.
- Bio-based CHDM pathways:Renewable feedstock technologies for cyclohexanedimethanol synthesis align with EU Green Deal procurement criteria for automotive tier-one suppliers.
- Medical device sterilization:Steam and gamma sterilization compatibility positions PCT for surgical instrument trays and drug delivery components under FDA 510(k) pathways.
Industry Challenges
- Polymerization scale-up expertise:Specialized reactor design and CHDM purification know-how concentrate among legacy polyester producers, constraining new entrant capacity additions.
- Multi-jurisdiction certification timelines:Concurrent UL, VDE, and CQC approval processes for automotive electronics grades extend qualification cycles by 18-24 months.
- Legacy injection molding reconfiguration:Tooling modifications for PCT's higher melt temperatures and crystallization rates disrupt established PET and PBT processing workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polycyclohexylenedimethylene Terephthalate (PCT) Market |
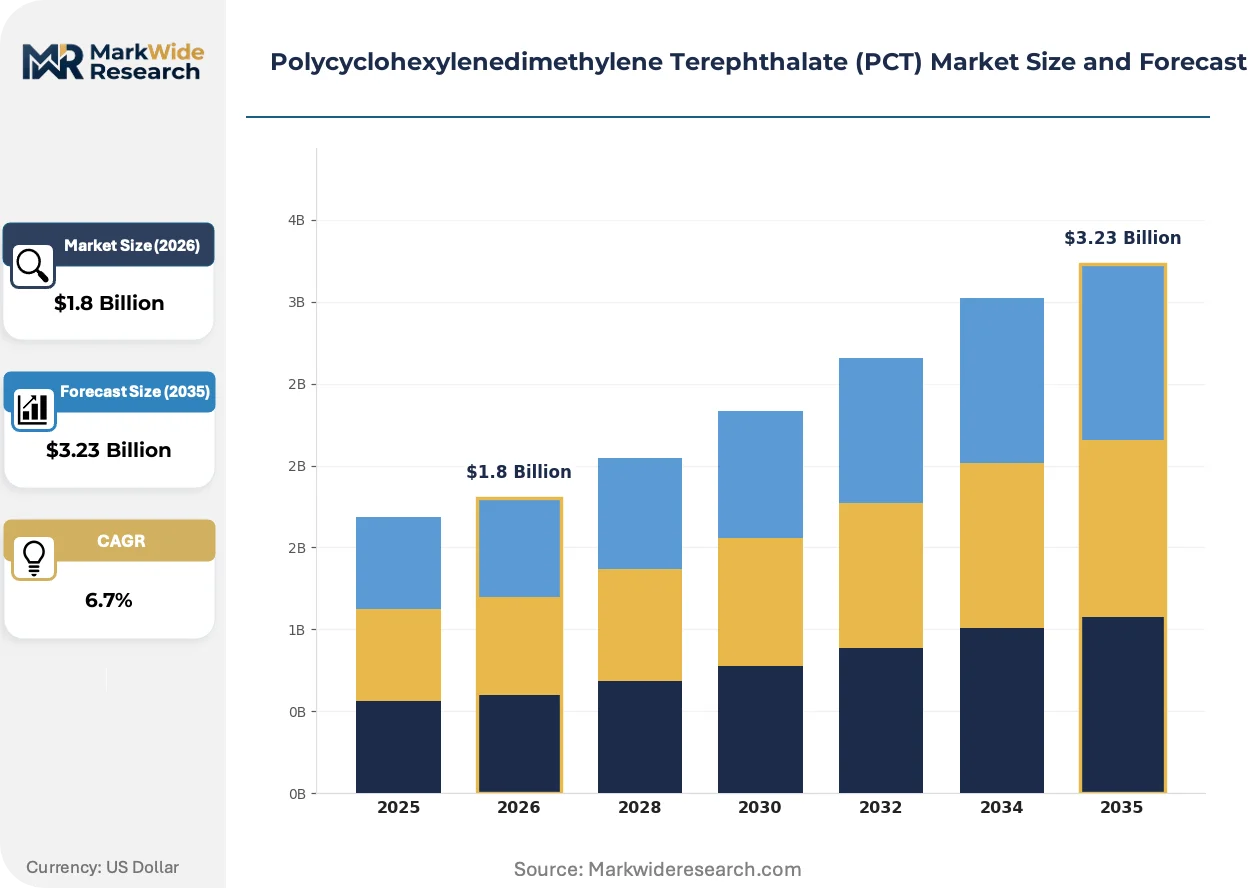
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Sheets, Films, Fiber Application: Automotive Components, Electronics Housing, Packaging Materials, Textiles End User: Aerospace, Consumer Electronics, Textile Industry, Packaging Form: Solid, Liquid, Powder, Composite |
| Companies Covered | Triveni Chemicals, Dow, Celanese Corporation, Toray Industries, Teijin Limited, SK Chemicals, BASF, Asahi Kasei Corporation, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polycyclohexylenedimethylene Terephthalate (PCT) Market Evolving Landscape
Digital twin technologies and advanced simulation platforms are compressing material qualification timelines while regulatory pressure on halogenated flame retardants is forcing formulation chemistry reinvention across high-temperature polyester portfolios.
Reinforced PCT compounds with glass fiber loadings exceeding 30% are virtualizing metal replacement in electric vehicle thermal management modules. Tier-one automotive suppliers in Germany and Japan are adopting these grades for battery cooling plates and power electronics housings. The technology is virtualizing traditional aluminum die-casting supply chains by eliminating secondary machining operations and corrosion protection steps.
REACH restrictions on perfluorinated substances are forcing compounders to develop phosphorus-nitrogen synergies for UL 94 V-0 compliance without halogenated additives. European electrical connector manufacturers face reformulation costs and requalification delays. Medical device housings and automotive sensors constitute the most affected application segments, with compounders accelerating collaboration with FR additive specialists.
Electronics assemblers are consolidating resin procurement through direct compounder relationships, bypassing traditional distributor channels for high-volume PCT grades. Taiwan and South Korea-based contract manufacturers now specify material properties directly with SK Chemicals and Toray Industries for smartphone and laptop connector programs. This disintermediation compresses pricing transparency and accelerates lot-to-lot consistency requirements.
Polycyclohexylenedimethylene Terephthalate (PCT) Market Segmentation
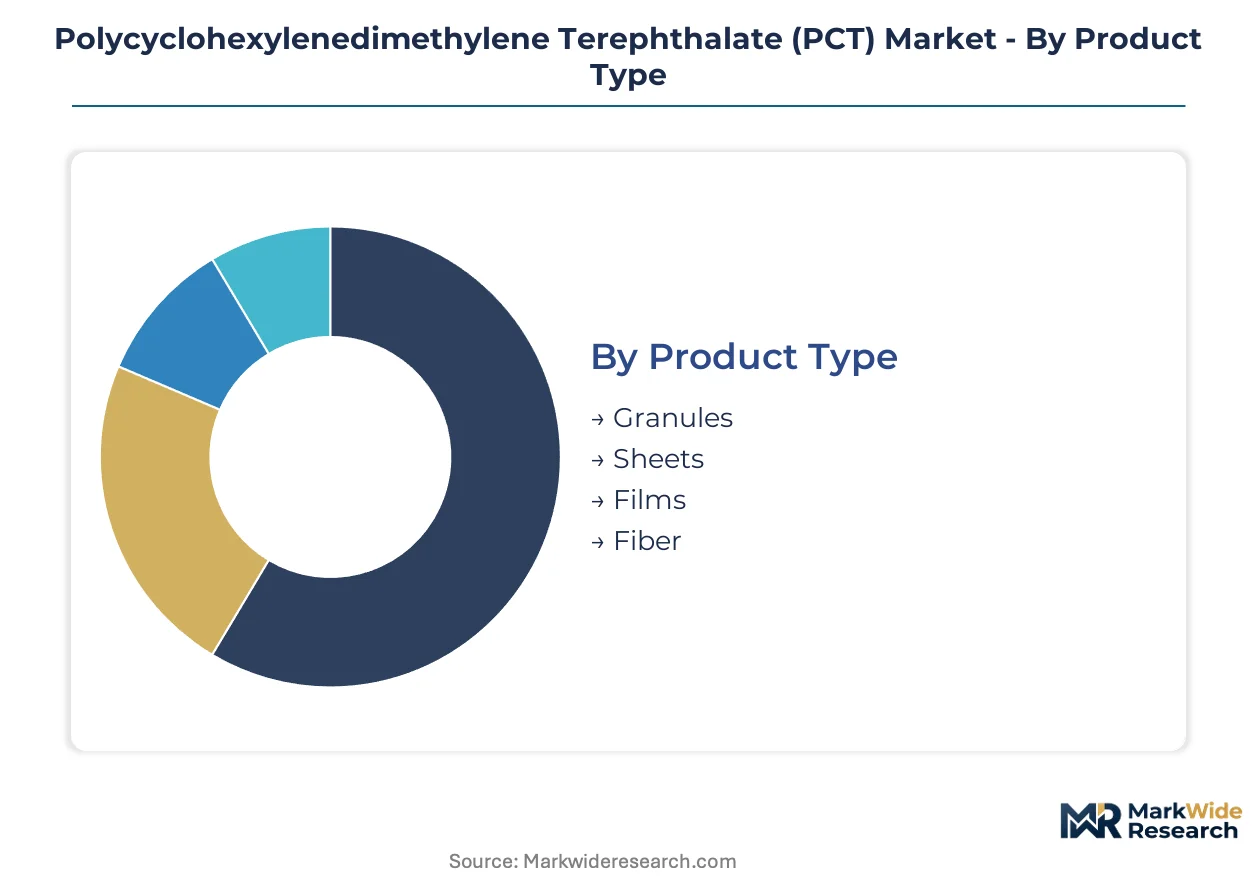
PCT market segmentation reveals distinct performance requirements across material forms and end-use specifications. Each dimension carries unique qualification barriers and margin structures that shape supplier positioning.
Product Type:
Cost tier differentiation separates commodity feedstock grades from specialty formulations commanding premium positioning.
- Granules:Standard pelletized resin serves injection molding operations for automotive connectors and industrial components. Demand concentrates in South Korea and Japan where automotive OEMs specify tight dimensional tolerances for under-the-hood thermal management parts. CHDM feedstock integration at major polymerization complexes sustains margin control for volume producers.
- Films:Biaxially oriented and cast film grades deliver high-barrier properties and dielectric stability for flexible circuit substrates. Electronics assemblers in Vietnam and India are rotating procurement toward film-grade PCT as smartphone manufacturing diversifies beyond China. This segment is climbing the fastest share rankings due to 5G antenna substrate and foldable display component requirements.
- Sheets:Extruded sheet stock supports thermoformed trays and structural panels where intermediate thickness and rigidity prove essential.
- Fiber:Melt-spun filament grades target industrial textile and high-performance reinforcement applications with controlled crystallinity profiles.
Granules hold installed capacity. Films is rotating up the share rankings.
Application:
Application-based segmentation maps directly to thermal and electrical performance certification requirements.
- Automotive Components:Under-the-hood connectors, sensors, and battery thermal management modules require heat deflection temperatures exceeding 150°C and hydrolytic stability against engine bay humidity. China's GB standards for automotive plastics are compressing substitution timelines for standard polyamides in EV inverter housings.
- Electronics Housing:Miniaturized connector geometries and UL 94 V-0 flame retardancy specifications command premium pricing tiers. Medical device and consumer electronics manufacturers in Germany and Japan face concurrent UL, VDE, and CQC approval cycles extending qualification by 18-24 months.
- Packaging Materials:High-barrier food contact films and pharmaceutical blister packs leverage PCT's chemical resistance and clarity for sterilizable applications.
- Textiles:Industrial fiber applications include conveyor belts and filtration media where dimensional stability under mechanical stress proves critical.
Automotive Components holds installed capacity. Electronics Housing is rotating up the share rankings.
End User:
Customer type segmentation distinguishes specification intensity and procurement consolidation patterns across industrial verticals.
- Consumer Electronics:Smartphone and laptop manufacturers specify material properties directly with resin producers, bypassing traditional distribution channels. Taiwan and South Korea-based contract manufacturers now mandate lot-to-lot consistency for high-volume connector programs.
- Packaging:Food contact and medical device applications face layered FDA and EFSA compliance requirements with extended documentation burdens for multi-regional market access.
- Aerospace:Cabin interior and structural applications demand FAA and EASA certification for flame retardancy and smoke toxicity under stringent aviation standards.
- Textile Industry:Industrial fabric producers prioritize melt viscosity consistency and dye affinity for continuous processing operations.
Consumer Electronics holds installed capacity. Packaging is rotating up the share rankings.
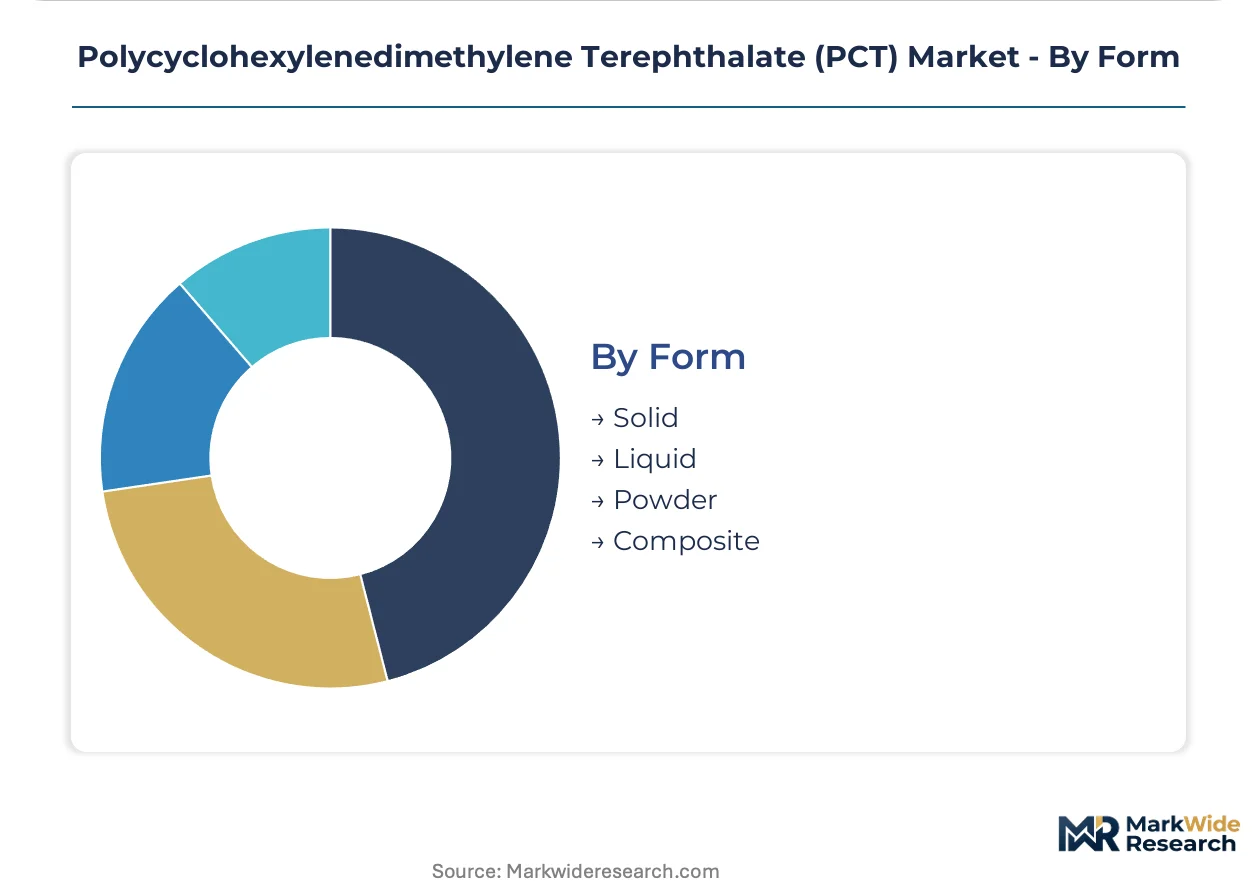
Form:
Physical form determines processing methodology and supply chain configuration from producer to compounder.
- Solid:Standard pellet and chip forms dominate bulk logistics and automated feeding systems for injection molding and extrusion operations.
- Powder:Fine particle grades serve rotational molding and coating applications requiring uniform melt distribution across complex geometries.
- Liquid:Specialized oligomer and prepolymer formulations enable reactive processing and in-situ polymerization for composite manufacturing.
- Composite:Pre-compounded reinforced grades with glass fiber or mineral fillers target metal replacement in structural automotive and electrical applications.
Solid holds installed capacity. Composite is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive electrification drives divergent consumption patterns across geographies. China deploys PCT primarily for battery thermal management under stricter GB standards. Japan and South Korea prioritize electronics-grade formulations for semiconductor packaging and flexible circuit substrates.
China
Domestic EV production volumes and dual carbon mandates compress substitution timelines for metal components. MIIT-enforced GB standards for automotive plastics mandate heat deflection temperatures above 150°C for under-the-hood applications. Yangtze River Delta manufacturing clusters around Shanghai and Suzhou concentrate polymer compounding capacity for battery housing exports.
South Korea
Electronics contract manufacturers specify material properties directly with resin producers for smartphone connector programs. K-REACH chemical substance reporting requirements layer documentation burdens on imported formulations. Yeosu and Ulsan industrial complexes host expanded polymerization capacity with captive CHDM feedstock integration.
Japan
Automotive OEMs in Nagoya and Tokyo anchor demand for fiber-grade PCT in high-performance thermal management modules. METI chemical substance reporting frameworks extend qualification cycles for medical device and consumer electronics applications. Chubu region compounders serve tier-one suppliers with concurrent UL, VDE, and domestic JIS certification requirements.
Germany
REACH registration requirements for imported resin formulations create captive demand for EU-based compounders serving automotive and medical device markets. ECHA restrictions on perfluorinated substances force reformulation of UL 94 V-0 grades without halogenated additives. Bavaria and Baden-Württemberg host metal-replacement qualification programs for EV cooling plates and power electronics housings.
United States
FDA food contact regulations and state-level PFAS restrictions complicate multi-regional market access for PCT compounders. Automotive electrification in Michigan and California accelerates material qualification for integrated battery housings under compressed OEM timelines. Medical device sterilization applications in Massachusetts and Minnesota leverage steam and gamma compatibility for surgical instrument trays.
Polycyclohexylenedimethylene Terephthalate (PCT) Market Competitive Landscape
Capability concentration sits with integrated petrochemical groups possessing CHDM feedstock control; scale advantage sits with diversified chemical conglomerates serving multiple high-performance polymer lines. The market structures around three tiers: backward-integrated Asian producers, European compounders with regulatory compliance expertise, and North American specialists in medical-grade formulations. Dominant competitive moves include capacity expansion at industrial complexes with feedstock integration and strategic partnerships with automotive tier-one suppliers for metal-replacement qualification programs.
Within the integrated petrochemical tier, SK Chemicals and Toray Industries exemplify producers with captive cyclohexanedimethanol supply chains and direct specification relationships with electronics assemblers. Celanese Corporation occupies a position among diversified chemical conglomerates with medical device and automotive qualification expertise across multiple jurisdictions. These three anchors demonstrate how geographic feedstock access and regulatory compliance capabilities stratify competitive positioning in high-temperature polyester supply.
| Leading Market Players |
|---|
| Triveni Chemicals |
| Dow |
| Celanese Corporation |
| Toray Industries |
| Teijin Limited |
| SK Chemicals |
| BASF |
| Asahi Kasei Corporation |
| Eastman Chemical Company |
| Others |
Value Network & Pricing Analysis
CHDM feedstock concentration at Yeosu and Ulsan industrial complexes in South Korea funnels margin capture toward backward-integrated polymerization operators. Compounders without captive cyclohexanedimethanol supply face persistent cost volatility that compresses blending margins and limits pricing autonomy.
Pricing Analysis
Long-term offtake contracts dominate volume procurement between automotive tier-one suppliers and integrated resin producers, insulating qualified grades from spot market swings. Three-tier pricing structure across premium, standard, and economy levels separates UL 94 V-0 certified electronics grades from commodity automotive feedstock and unmodified base resin. Cost compression in standard granule tiers is intensifying because polyamide 6T substitution threats force PCT compounders to absorb margin erosion. Electronics housing manufacturers exhibit lowest price sensitivity due to miniaturization tolerances and flame-retardancy requirements, while packaging converters face acute pressure from lower-cost barrier film alternatives.
Supply Chain Analysis
Cyclohexanedimethanol synthesis capacity anchors in South Korea, Japan, and China, with petrochemical complexes at Yeosu, Ulsan, and Ningbo commanding regional feedstock allocation. PCT polymerization draws from purified terephthalic acid, cyclohexanedimethanol, and flame-retardant additive packages sourced through specialized chemical distributors. Single-source vulnerability concentrates around CHDM purification know-how held by legacy polyester producers. Distribution runs through direct compounder relationships with automotive OEMs and electronics assemblers, bypassing traditional resin distributors for high-volume qualified grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PCT penetration sits at early-cycle expansion with automotive electrification compressing metal-to-plastic substitution timelines for battery thermal management. China's dual carbon mandates and stricter GB standards for automotive plastics accelerate qualification windows beyond historical engine-bay adoption curves.
For Market Incumbents: Build certification moats around concurrent UL, VDE, and CQC approval cycles that extend competitor requalification timelines by 18-24 months. Deepen backward integration into CHDM feedstock at existing polymerization complexes to defend margin control against input cost volatility. Prioritize capacity expansion in South Korea and Japan where automotive OEMs specify tight dimensional tolerances for under-the-hood connectors.
For New Entrants and Emerging Players: India's electronics manufacturing corridors present virgin demand creation under PLI scheme incentives for semiconductor and mobile device production. Target high-barrier film grades for flexible circuit substrates in Vietnam and India as smartphone assembly diversifies beyond China. Pursue partnership pathways with Taiwan-based contract manufacturers seeking lot-to-lot consistency for high-volume connector programs.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across medical-grade PCT formulations due to layered FDA and EFSA compliance documentation burdens. Acquisition focus should center on EU-based compounders with REACH registration expertise and captive demand from medical device sterilization applications. Monitor bio-based CHDM pathway development as an inflection signal for EU Green Deal procurement alignment.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into CHDM Feedstock | Captive cyclohexanedimethanol supply at Yeosu and Ulsan insulates SK Chemicals from force majeure volatility. |
| Concurrent Multi-Jurisdiction Certification | UL, VDE, and CQC approval cycles create 18-24 month qualification barriers against polyamide substitution threats. |
| Direct Compounder Relationships | Taiwan and South Korea electronics assemblers bypass distributors, compressing pricing transparency and accelerating consistency requirements. |
| Bio-Based CHDM Pathway Development | Renewable feedstock technologies align with EU Green Deal procurement criteria for automotive tier-one suppliers. |
| Medical Device Sterilization Qualification | Steam and gamma compatibility positions PCT for FDA 510(k) surgical instrument trays and drug delivery components. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this analysis. Plant managers at South Korean and Japanese polymerization complexes, procurement leads at German automotive tier-one suppliers, and technical R&D directors at electronics compounders provided operational data. Secondary sources include ECHA REACH registration databases, MIIT GB standard publications, FDA 510(k) device listings, and SEC 10-K disclosures from diversified chemical conglomerates. Bottom-up demand modeling across automotive, electronics, and medical end-uses triangulates against top-down petrochemical capacity assessments.
Calibration against historical substitution patterns in high-temperature polyesters and concurrent metal-to-plastic conversion timelines in electric vehicle thermal management informs the projection framework. Segmentation dimensions span product form, application certification tier, end-user vertical, and regional production hub. CAGRs derive from elasticity-adjusted demand curves incorporating OEM qualification cycle compression and regulatory mandate acceleration. Industry-specific inputs include CHDM feedstock capacity utilization rates and multi-jurisdiction flame-retardant compliance pathway evolution.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, petrochemical feedstock pricing, or perfluorinated substance regulatory stringency would shift the trajectory. Forecasts incorporate documented assumptions regarding polymerization scale-up expertise concentration and electronics manufacturing geographic diversification. Cross-checking against IHS Markit automotive plastics demand benchmarks and Cefic high-performance polymer trade flows is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Styrene Acrylonitrile (SAN) Market
Polymers & Resins
Asia-Pacific Engineering Plastics Market
Polymers & Resins
Plastic Compounding Market
Polymers & Resins
Global Polypropylene Random Copolymer Market
Polymers & Resins
Polyimide and Imide Polymers Market
Polymers & Resins
Thermosetting Plastics Market
Polymers & Resins
Polypropylene Powder Market
Polymers & Resins
Foamed Plastics Market
Polymers & Resins
Middle East Polymer Market
Polymers & Resins
Vinyl Acetate Emulsion Polymers Market
Polymers & Resins
Polyetherketone Market
Polymers & Resins
Chlorinated Polyolefins Market
Polymers & Resins
Oman PVC Products Market
Polymers & Resins
Paper Processing Resins Market
Polymers & Resins
Synthetic Polymer Waxes Market