
 Renewable PVDF Market | 2026-2036
Renewable PVDF Market Size, Share, and Industry Trends Forecast 2026-2036
Renewable PVDF Market Analytics
Fluoropolymer binder chemistry is rewriting how lithium-ion electrode architectures achieve cycle stability and adhesion under high-voltage operation. Arkema S.A. leverages its integrated fluorochemicals platform to secure precursor supply for battery-grade PVDF dispersions. Solvay SA anchors European production capacity with membrane-specialized grades serving water treatment and energy storage simultaneously. Daikin Industries Ltd. competes through vertical control over R-142b feedstock and downstream polymerization in Asia-Pacific manufacturing hubs.
Renewable PVDF denotes polyvinylidene fluoride synthesized from bio-sourced or recycled carbon feedstocks rather than virgin petrochemical precursors, typically exhibiting melt viscosities between 10 and 100 kPa·s and dielectric constants near 12 at 1 MHz for electrical insulation applications. The material serves primarily as a chemically resistant binder, coating, and membrane substrate across energy storage, semiconductor fabrication, and industrial fluid handling systems. Film and membrane grades command structural attention due to their penetration of solid-state battery prototyping lines and hydrogen fuel cell humidifier stacks. High purity grades sustain premium positioning as semiconductor wafer processing and pharmaceutical fluid management impose extractables limits below 50 parts per billion.
The EPA regulates fluoropolymer facility emissions under Clean Air Act amendments targeting hydrofluorocarbon byproducts, while REACH and the EU F-Gas Regulation constrain perfluorinated precursor availability and mandate substitution planning for specified applications. China's MEE enforces dual carbon goals that tighten energy intensity benchmarks for fluorochemical monomer production, reshaping cost structures for export-oriented PVDF resin. Stakeholders must monitor feedstock certification schemes and regional carbon border adjustments to determine where renewable attribution claims withstand downstream customer audit protocols.
Market Dynamics
Battery-grade fluoropolymer specifications are tightening faster than conventional petrochemical PVDF production can adapt, forcing a structural pivot toward bio-attributed feedstock verification and carbon accounting transparency across European and Asian supply bases.
Growth Catalysts
- EU F-Gas Regulation phase-down schedules:Perfluorinated precursor quotas are redirecting capital toward bio-based R-142b synthesis routes in German and Belgian chemical corridors.
- Solid-state battery prototyping acceleration:Separator coating specifications above 5 micron thickness are absorbing high-purity PVDF dispersions from pilot lines in South Korea and Japan.
- Hydrogen fuel cell humidifier membrane demand:Proton exchange membrane stacks require chemically stable fluoropolymer substrates for cathode air humidification systems.
Market Restraints
- R-142b feedstock concentration:Three Chinese producers control over 70% of global hydrochlorofluorocarbon intermediate supply, exposing downstream polymerization to export license volatility.
- Electrochemical grade purity thresholds:Semiconductor wafer processing demands extractables below 50 parts per billion, filtering out standard industrial PVDF resin batches.
- Perfluorinated substance substitution mandates:REACH authorization procedures are constraining long-chain fluorochemical precursor availability for conventional PVDF synthesis.
Strategic Opportunities
- Post-consumer PVDF chemical recycling:Pyrolysis-based monomer recovery from end-of-life lithium-ion battery binders is opening circular feedstock channels outside virgin petrochemical sourcing.
- India PLI scheme battery manufacturing:Domestic cell production incentives are creating first-mover positioning for fluoropolymer dispersion localized supply.
- ISO 14067 carbon footprint certification:Product-level greenhouse gas verification is enabling premium pricing separation for bio-attributed resin grades in German automotive procurement.
Industry Challenges
- Fluoropolymer synthesis chemist scarcity:Specialized expertise in controlled radical polymerization for battery-grade molecular weight distribution is concentrated among retiring European technical workforces.
- Multi-standard certification timelines:Simultaneous REACH registration, FDA food contact notification, and semiconductor-grade qualification stretches commercialization cycles to 24-36 months.
- Legacy electrode binder specification lock-in:Established lithium-ion cell architectures specify conventional PVDF grades, creating formulation revalidation costs for renewable alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renewable PVDF Market |
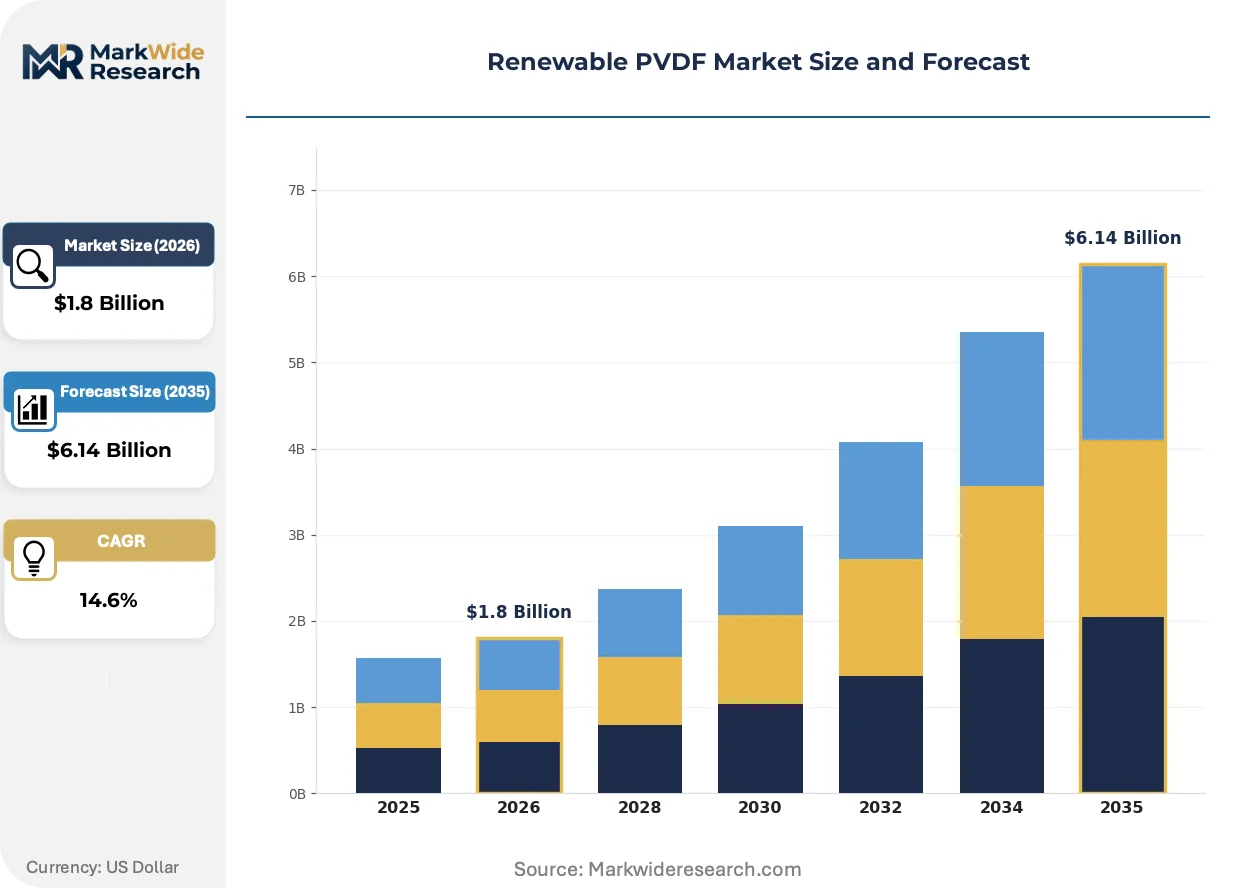
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Film, Coatings, Membranes, Sheets End Use Industry: Aerospace, Electronics, Automotive, Oil & Gas Grade: High Purity, Industrial, Medical, Electrical Deployment: On-site, Off-site, Modular, Integrated |
| Companies Covered | Arkema S.A., Solvay SA, Daikin Industries Ltd., Kureha Corporation, 3M Company, Dyneon GmbH, Dongyue Group, Sinochem, Shanghai Ofluorine Chemical Technology Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renewable PVDF Market Evolving Landscape
Electrode binder chemistry is fragmenting across performance tiers as solid-state prototypes diverge from conventional liquid electrolyte architectures, while regulatory carbon accounting forces material provenance documentation deeper into supply chain contracts.
Aqueous PVDF dispersion formulations are migrating from laboratory-scale coating trials into high-volume electrode manufacturing lines. Korean battery producers are qualifying water-based binder systems at 20,000-ton annual coating capacity. This migration is compressing solvent recovery infrastructure investments while demanding reformulated rheology modifiers for uniform slurry distribution.
REACH restriction proposals targeting per- and polyfluoroalkyl substances are forcing polymerization route disclosures from European compounders. The industrial consequence is accelerated capital allocation toward bio-circular attribution certification schemes. Battery separator manufacturers in Germany and France are restructuring supplier qualification protocols to exclude non-compliant fluorochemical precursors.
Automotive OEM procurement teams are consolidating fluoropolymer binder specifications across cell suppliers to reduce qualification redundancy. Tier-one battery producers are responding with master service agreements covering multi-year PVDF volume commitments. This concentration is most visible in German Rhine corridor clusters where chemical processors and automotive headquarters coordinate technical roadmaps.
Renewable PVDF Market Segmentation
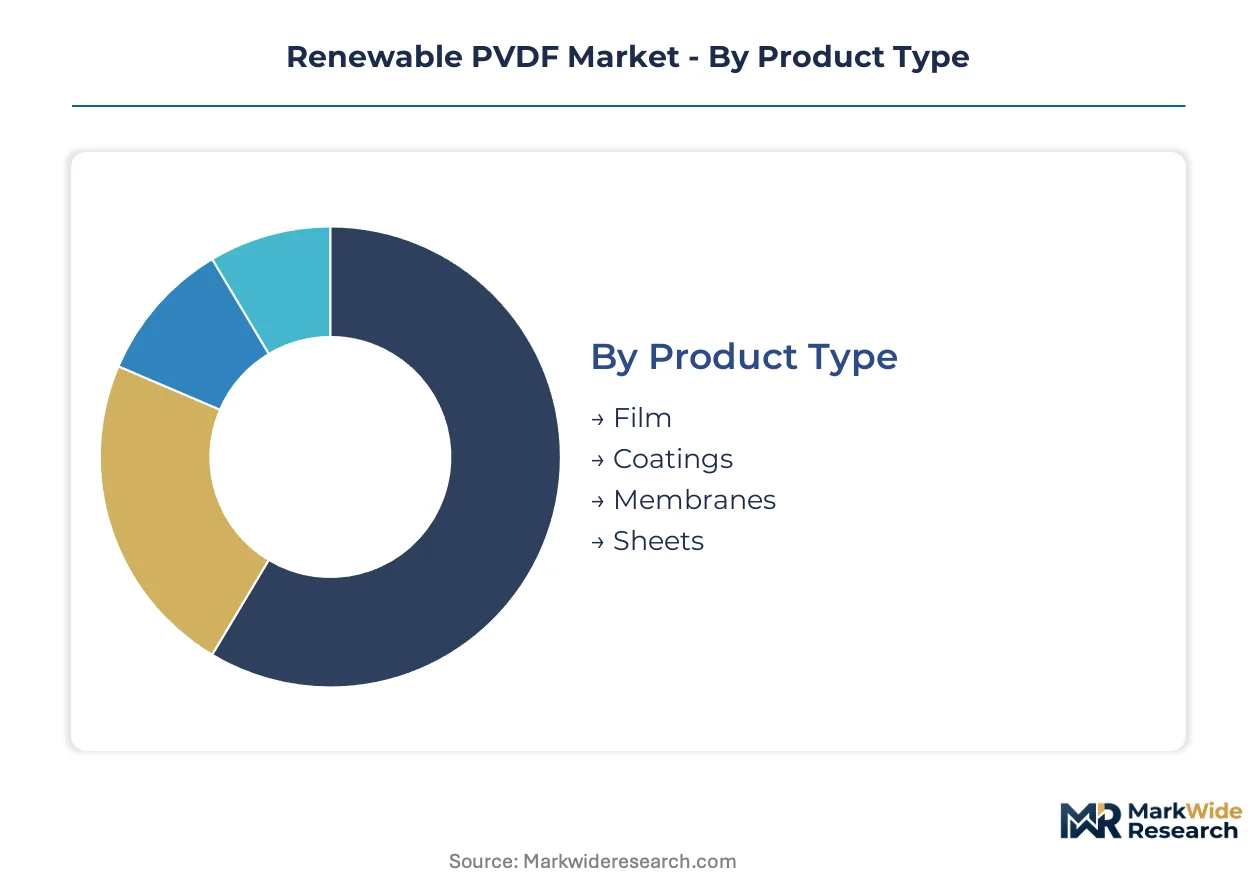
Segmentation in renewable PVDF markets exposes how technical specifications diverge across regulatory environments and end-use qualification protocols. Each dimension carries distinct certification burdens, supply chain configurations, and pricing architectures that reshape procurement decisions.
Product Type:
After-sales technical support intensity varies dramatically across product forms, with membrane and film grades requiring sustained field engineering engagement for installation validation and performance monitoring.
- Film:Thin-gauge extruded layers between 5-50 microns serve solid-state battery separator substrates and capacitor dielectrics. Korean battery producers are qualifying film grades at 20,000-ton annual coating capacity for aqueous dispersion compatibility.
- Membranes:Porous structures with controlled pore size distribution below 0.1 microns function in hydrogen fuel cell humidifier stacks and water treatment modules. German automotive OEMs along the Rhine corridor specify membrane grades for proton exchange membrane stack integration.
- Coatings:Dispersion-based surface treatments for chemical protection and electrical insulation.
- Sheets:Thick-section compression-molded plates for industrial fluid handling and semiconductor fabrication equipment.
Film holds the largest share; momentum sits with membranes.
End Use Industry:
Cost tier stratification separates aerospace qualification premiums from automotive volume pricing, with electronics and oil & gas occupying intermediate positions based on purity thresholds and batch size requirements.
- Automotive:Electric vehicle battery manufacturers drive fluoropolymer binder specifications for electrode architectures. The EU Green Deal and F-Gas Regulation redirect investment toward bio-based feedstock routes for German and Belgian chemical processors serving automotive OEM procurement teams.
- Electronics:Semiconductor wafer processing demands extractables below 50 parts per billion, filtering standard industrial resin batches. REACH authorization procedures constrain long-chain fluorochemical precursor availability for conventional synthesis routes serving this segment.
- Aerospace:Fuel system components and wire insulation requiring flame resistance certification.
- Oil & Gas:Downhole equipment and chemical transfer systems in corrosive environments.
Automotive commands volume leadership; electronics climbs fastest on purity premium expansion.
Grade:
Volume concentration patterns favor industrial grades for commodity applications while high purity and medical segments extract margin through certification scarcity and audit-intensive supply chain documentation.
- High Purity:Extractables limits below 50 parts per billion sustain premium positioning for semiconductor fabrication and pharmaceutical fluid management. China's MEE dual carbon goals tighten energy intensity benchmarks for monomer production, reshaping cost structures for export-oriented high purity resin.
- Industrial:Standard melt viscosity grades between 10-100 kPa·s serve bulk coating and molding applications. R-142b feedstock concentration among three Chinese producers exposes downstream polymerization to export license volatility affecting industrial grade availability.
- Medical:Biocompatibility testing and FDA food contact notification requirements for implantable and diagnostic device components.
- Electrical:Dielectric constants near 12 at 1 MHz for wire insulation and capacitor applications.
Industrial grade dominates volume; high purity captures expanding margin pools.
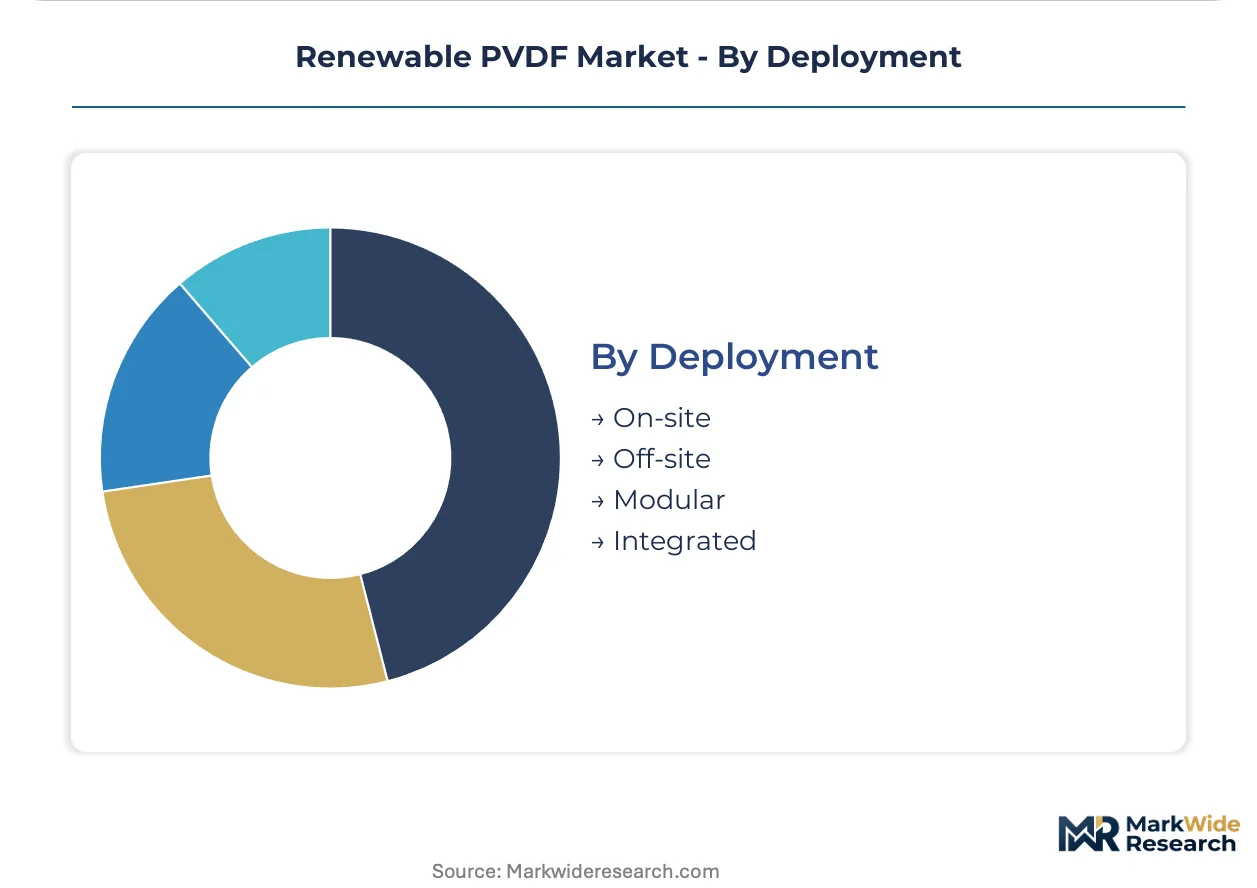
Deployment:
Customer type segmentation separates integrated chemical processors with captive polymerization capacity from modular operators purchasing resin for downstream compounding and formulation.
- Integrated:Vertically controlled production from R-142b feedstock through dispersion formulation. Daikin Industries anchors Asia-Pacific manufacturing hubs with downstream polymerization control, while Solvay SA anchors European capacity with membrane-specialized grades.
- Modular:Distributed compounding operations sourcing certified resin for regional formulation and technical service. ISO 14067 carbon footprint certification enables premium pricing separation for bio-attributed grades in German automotive procurement channels.
- On-site:Captive coating and molding operations at battery cell manufacturing facilities.
- Off-site:Third-party toll processing and contract manufacturing for specialized grades.
Integrated deployment holds structural advantage; modular configurations gain share in emerging battery manufacturing geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in fluoropolymer intermediates are redirecting regional investment patterns. Countries with captive R-142b feedstock capacity command structural advantages in downstream polymerization economics.
Germany
Automotive OEM procurement teams along the Rhine corridor are consolidating multi-year PVDF volume commitments for electric vehicle battery programs. The EU F-Gas Regulation phase-down schedules redirect capital toward bio-based R-142b synthesis routes in German and Belgian chemical corridors. Chemical processors in North Rhine-Westphalia coordinate technical roadmaps with automotive headquarters.
China
Domestic battery cell production expansion absorbs membrane-grade PVDF from integrated fluorochemical platforms. The MEE enforces dual carbon goals tightening energy intensity benchmarks for monomer production, reshaping cost structures for export-oriented resin. Three producers concentrate over 70% of global hydrochlorofluorocarbon intermediate supply, exposing downstream polymerization to export license volatility.
United States
Semiconductor wafer processing facilities demand extractables below 50 parts per billion, filtering standard industrial resin batches from import channels. The EPA regulates fluoropolymer facility emissions under Clean Air Act amendments targeting hydrofluorocarbon byproducts. Gulf Coast petrochemical corridors evaluate bio-attributed feedstock verification for carbon accounting transparency.
South Korea
Battery producers qualify water-based binder systems at 20,000-ton annual coating capacity, compressing solvent recovery infrastructure investments. The MFDS maintains pharmaceutical-grade fluoropolymer standards for diagnostic device components. Pilot lines in Gyeonggi Province absorb high-purity PVDF dispersions for solid-state battery separator coatings above 5 micron thickness.
Japan
Proton exchange membrane stack manufacturers require chemically stable fluoropolymer substrates for hydrogen fuel cell humidifier systems. METI coordinates national hydrogen roadmap procurement specifications with domestic chemical producers. Manufacturing hubs in Osaka and Nagoya maintain vertical control over R-142b feedstock and downstream polymerization.
Renewable PVDF Market Competitive Landscape
On the supply side, the industry is consolidating around integrated fluorochemical platforms with captive monomer capacity and dispersion formulation expertise. Three strategic archetypes dominate: vertically controlled Asian producers with upstream feedstock dominance, European membrane specialists with regulatory compliance infrastructure, and modular compounders sourcing certified resin for regional formulation. Capacity expansion and bio-attribution certification constitute the dominant competitive moves.
Among integrated chemical processors, Arkema S.A., Solvay SA, and Daikin Industries Ltd. exemplify the three regional archetypes. Arkema represents European integrated fluorochemicals platforms securing precursor supply. Solvay occupies a position anchoring European production capacity with specialized grades. Daikin sits within the Asia-Pacific manufacturing hub tier with downstream polymerization control. These three structures illustrate how geographic feedstock concentration and regulatory compliance infrastructure determine competitive positioning.
| Leading Market Players |
|---|
| Arkema S.A. |
| Solvay SA |
| Daikin Industries Ltd. |
| Kureha Corporation |
| 3M Company |
| Dyneon GmbH |
| Dongyue Group |
| Sinochem |
| Shanghai Ofluorine Chemical Technology Co. Ltd. |
| Others |
Value Network & Pricing Analysis
The North Rhine-Westphalia chemical corridor concentrates fluoropolymer polymerization capacity along the Rhine, feeding German automotive OEM procurement teams with membrane-grade PVDF while Chinese R-142b export licensing volatility transmits upstream cost shocks into European dispersion pricing.
Pricing Analysis
Conventional petrochemical PVDF grades trade at substantial discounts to bio-attributed and high-purity electrochemical specifications, with next-generation solid-state battery separator coatings commanding the steepest premiums. Pricing stratifies across premium, standard, and economy tiers based on extractables certification and carbon footprint verification under ISO 14067 protocols. Cost compression in industrial-grade resin is intensifying because three Chinese producers dominate hydrochlorofluorocarbon intermediate supply. Automotive battery manufacturers exhibit the highest price sensitivity, while semiconductor wafer processors absorb premium pricing for sub-50 ppb purity thresholds.
Supply Chain Analysis
Export-control regimes targeting fluorochemical precursors under EU F-Gas Regulation quotas and Chinese MEE licensing procedures constrain R-142b flows from Jiangsu and Shandong provinces into European polymerization facilities. Supply concentrates in China, Germany, and Japan, with downstream dispersion formulation drawing from bio-based feedstock verification systems and REACH-registered monomer channels. Single-source vulnerability pervades the hydrochlorofluorocarbon intermediate tier. Distribution runs through integrated chemical processors with captive polymerization capacity and modular compounders serving regional battery manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Renewable PVDF markets are recovering from feedstock constraint cyclicality as EU F-Gas Regulation phase-down schedules redirect capital toward bio-based R-142b synthesis routes and solid-state battery prototyping accelerates separator coating demand.
For Market Incumbents: Entrench fluoropolymer binder specification lock-in across German automotive OEM procurement teams through multi-year master service agreements covering aqueous dispersion volume commitments. Prioritize backward integration into bio-attributed R-142b feedstock certification to defend margin position against REACH restriction proposals targeting perfluorinated precursors. Accelerate high-purity grade capacity expansion in North Rhine-Westphalia to capture semiconductor wafer processing demand.
For New Entrants and Emerging Players: India's battery manufacturing corridors under the PLI scheme present underpenetrated white-space for localized fluoropolymer dispersion supply, bypassing incumbent European qualification protocols. Target modular compounding configurations serving South Korean battery producers qualifying water-based binder systems at pilot-line scale. Pursue ISO 14067 carbon footprint certification as the primary go-to-market wedge for German automotive procurement channels.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated fluorochemical platforms with captive monomer capacity and membrane-specialized grade portfolios over modular compounders exposed to feedstock volatility. Long-term viability hinges on bio-circular attribution infrastructure and solid-state battery separator coating qualification timelines. Watch for aggressive capacity additions by Chinese state-backed producers as the signal forcing pricing recalibration across European and Asian supply bases.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Attributed Feedstock | Secures precursor supply independence from EU F-Gas Regulation quota constraints. |
| High-Purity Grade Capacity Expansion | Captures semiconductor wafer processing demand requiring extractables below 50 ppb. |
| Long-Term Supply Agreement with Automotive OEMs | Locks in multi-year PVDF volume commitments across Rhine corridor procurement teams. |
| Aqueous Dispersion Formulation Investment | Aligns with Korean battery producers qualifying water-based binder systems at scale. |
| Post-Consumer Chemical Recycling Infrastructure | Opens circular feedstock channels from end-of-life lithium-ion battery binder recovery. |
Research Methodology
Desk research of fluorochemical trade flow databases, EU REACH registration filings, and SEC 10-K disclosures preceded structured interviews with fluoropolymer plant managers, automotive OEM procurement leads, battery cell technical directors, and distribution channel partners across German, Chinese, and South Korean manufacturing hubs. Secondary validation drew from customs export records, MEE dual carbon policy documentation, and ISO certification registry data. Bottom-up resin volume estimates triangulated against top-down end-use demand modeling across the analysis window.
Forecast assumptions held EU F-Gas Regulation phase-down schedules and Chinese R-142b export licensing procedures within observed administrative patterns while varying solid-state battery prototyping acceleration rates and bio-attributed feedstock cost curves across the projection horizon. Segmentation dimensions modeled include product form, end-use industry, grade purity tier, and deployment configuration. CAGRs derived from logistic diffusion curves fitted to battery-grade fluoropolymer adoption trajectories, with hydrogen fuel cell humidifier membrane demand and semiconductor fabrication equipment spend as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-backed producers or accelerated REACH restriction timelines would shift outcomes. Material shifts in bio-attributed R-142b synthesis route economics or solid-state battery separator coating specification finalization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polymer Plastic Plain Bearings Market
Polymers & Resins
Polyisobutylene (PIB) Market
Polymers & Resins
Rosin Resin Market
Polymers & Resins
Fluoropolymers in Healthcare Market
Polymers & Resins
Antiviral Polymers for Packaging Market
Polymers & Resins
Packaging Resins Market
Polymers & Resins
US Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Nonchlorinated Polyolefins Market
Polymers & Resins
Asia-Pacific Thermoplastics Market
Polymers & Resins
Sustainable Polymers Market
Polymers & Resins
PA66 Market
Polymers & Resins
Optically Clear Resin Market
Polymers & Resins
Thermoplastics Market
Polymers & Resins
Polyimide and Imide Polymers Market
Polymers & Resins
Soft PVC Sealing Strip Market
Polymers & Resins
United States Polymer Emulsion Market