
 Polyolefin Compound Market | 2026-2036
Polyolefin Compound Market Size, Share, and Industry Trends Forecast 2026-2036
Polyolefin Compound Market Analytics
EU REACH restrictions on persistent organic pollutants is recalibrating the cost-of-entry calculus for compounders serving European automotive OEMs. Dow Inc. leverages its Gulf Coast feedstock integration to sustain cost-competitive supply of engineered polyolefin grades. LyondellBasell Industries anchors its position through proprietary Hostalen catalyst technology and differentiated metallocene polyethylene portfolios. ExxonMobil Chemical dominates high-performance TPO compounds through its Vistamaxx platform, controlling specification-setting relationships with tier-one automotive suppliers.
Polyolefin compounds are thermoplastic formulations produced by blending base polyolefin resins with fillers, reinforcements, stabilizers, and functional additives to achieve targeted mechanical, thermal, or electrical properties, typically processed via twin-screw extrusion at melt temperatures between 180°C and 260°C. These materials serve as lightweight, cost-efficient substitutes for metals and engineering polymers across automotive interior panels, flexible packaging films, and construction geomembranes. Polypropylene compounds command the largest volume share due to their superior balance of stiffness, impact resistance, and chemical inertness in under-hood automotive applications. Packaging applications represent the fastest-expanding demand pool, driven by mono-material recyclability mandates that favor polyethylene-based barrier formulations over multi-layer alternatives.
FDA food-contact regulations, EPA emissions standards for automotive materials, and EU Ecodesign requirements collectively shape product development roadmaps and market access conditions for polyolefin compound manufacturers. China's GB standards for plastic food packaging and SAMR quality supervision protocols add compliance layers for suppliers targeting domestic consumer goods channels. Stakeholders must monitor evolving extended producer responsibility frameworks and polymer-specific recycling targets, as these mechanisms will determine which compound formulations retain commercial viability across regulated end-use sectors.
Market Dynamics
Automotive lightweighting mandates are compressing substitution cycles for metal components, pulling glass-filled polypropylene compounds into structural applications previously reserved for engineering thermoplastics and aluminum castings. Compounders must now certify flame-retardant grades against simultaneous OEM crash-performance and OEM volatile-organic-compound emissions protocols.
Growth Catalysts
- REACH Persistent Organic Pollutant Restrictions:European compounders are accelerating reformulation programs to eliminate restricted halogenated flame retardants, creating first-mover advantage for suppliers with certified alternative chemistries already in production.
- Yangtze River Delta Manufacturing Corridor:Integrated polymer-to-parts ecosystems in this Chinese cluster are consolidating procurement decisions, rewarding compounders with local compounding assets and just-in-time delivery capabilities.
- Mono-Material Recyclability Mandates:Packaging converters across EU member states are specifying polyethylene-based barrier compounds to replace multi-layer film structures, directly lifting demand for metallocene-grade polyethylene formulations.
Market Restraints
- Propylene Feedstock Volatility:North American compounders face margin compression when regional propane dehydrogenation outages spike propylene monomer costs, particularly affecting suppliers without backward integration into refinery streams.
- Automotive Tier-One Supplier Concentration:Three global automotive interior module suppliers control specification-setting for North American and European OEM programs, creating customer-side bargaining power that limits pricing flexibility for mid-tier compounders.
- Polyamide Substitution in Under-Hood Applications:Heat-stabilized polyamide 6,6 compounds retain temperature-performance advantages above 150°C in turbocharger ducting, blocking polypropylene penetration in this high-value automotive segment.
Strategic Opportunities
- India BIS Certification Gap:Domestic compounders with pre-certified automotive grades under Bureau of Indian Standards protocols capture specification windows as Maruti Suzuki and Tata Motors localize supply chains under production-linked incentive schemes.
- Post-Consumer Recycled Content Mandates:EU Ecodesign requirements for recycled plastic content in packaging create pull-through demand for compatibilized recycled polyethylene compounds that maintain barrier properties.
- Twin-Screw Reactive Extrusion Convergence:Real-time rheology monitoring is enabling on-line viscosity adjustment during maleic anhydride grafting, allowing compounders to produce custom-modified grades without batch-to-batch variation penalties.
Industry Challenges
- Metallocene Catalyst Sourcing:Limited qualified suppliers of constrained-geometry catalyst systems for single-site polyethylene production create supply security risks for compounders scaling high-performance TPO grades.
- Multi-Jurisdiction Food-Contact Compliance:Simultaneous FDA, EU EFSA, and China GB standard certification for mineral-filled polypropylene compounds extends product development timelines by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyolefin Compound Market |
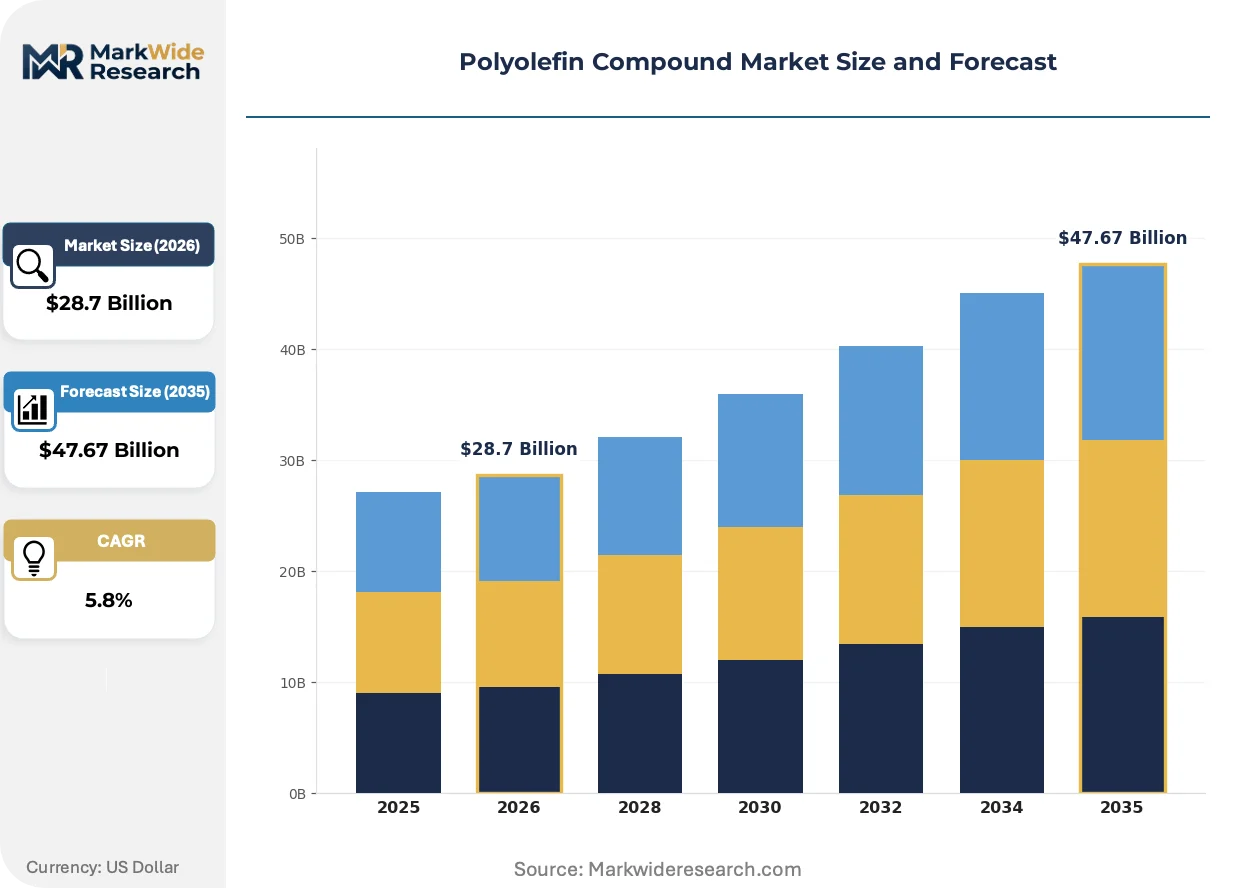
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $47.67 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
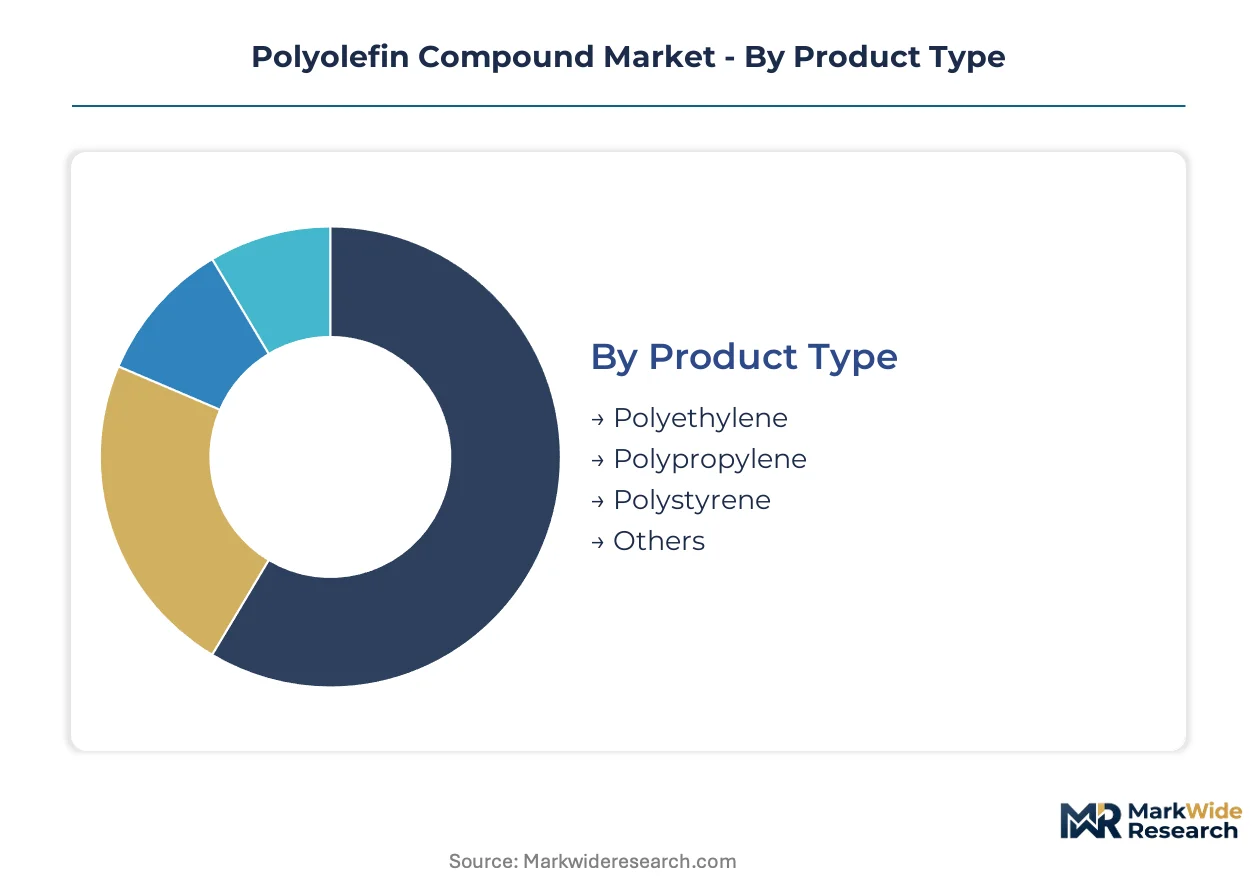
| Segmentation | Product Type: Polyethylene, Polypropylene, Polystyrene, Others Application: Automotive, Packaging, Consumer Goods, Construction Form: Granules, Powder, Film, Sheet End User: Manufacturers, Distributors, Retailers, Suppliers |
| Companies Covered | LyondellBasell Industries, Dow Inc., ExxonMobil Chemical, SABIC, Borealis AG, Braskem, Mitsui Chemicals, BASF SE, Avient Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyolefin Compound Market Evolving Landscape
Real-time process analytical technology is compressing development cycles for custom-engineered compounds, while regulatory pressure on carbon intensity is forcing feedstock provenance transparency across automotive supply chains.
Long-glass-fiber polypropylene direct compounding is converging with in-mold welding techniques to enable structural automotive modules without metal inserts. Tier-one seating suppliers in Germany and the US Midwest are adopting these hybrid processes for seat back frames and instrument panel carriers. The technology is converging with automated fiber placement to reduce part count and assembly labor in electric vehicle platforms where weight reduction extends battery range.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluorocarbon replacement in extrusion foaming operations, pushing compounders toward carbon dioxide and nitrogen physical blowing agents for interior trim applications. Automotive OEMs in France and Italy now require supplier documentation of global warming potential for all foamed components. The regulation is compressing equipment replacement cycles at European compounding facilities as processors retrofit extrusion lines for alternative blowing agent compatibility.
Specification-setting authority is migrating from OEM material engineering groups to tier-one module suppliers with integrated design and manufacturing responsibility. These suppliers in China's Yangtze Delta and Michigan's automation corridor now contract directly for compound grades rather than deferring to OEM-approved material lists. The shift concentrates volume with compounders capable of co-development programs and localized technical service, disadvantaging distributors and non-integrated resin suppliers.
Polyolefin Compound Market Segmentation
Polyolefin compound formulations diverge sharply in their integration depth across value chains. Some grades ship as standalone pellets for downstream conversion, while others arrive as pre-engineered systems embedded within tier-one automotive modules or flexible packaging films.
Product Type:
Integration depth varies by polymer chemistry, with base resins serving discrete compounding operations versus formulated compounds feeding direct-to-mold processes.
- Polyethylene:Metallocene-grade and Ziegler-Natta polyethylene compounds dominate flexible packaging barrier formulations. Demand concentrates in Germany and France where EU Ecodesign mandates favor mono-material recyclability over multi-layer alternatives.
- Polypropylene:Glass-filled and talc-reinforced polypropylene compounds serve structural automotive interior panels. Specifications are tightening around crash-performance and volatile-organic-compound emissions protocols from OEMs in Stuttgart and Detroit.
- Polystyrene:High-impact polystyrene compounds retain niche positions in consumer appliance housings.
- Others:Ethylene-vinyl acetate and polybutene-1 compounds address specialty adhesive and sealant applications.
Polypropylene leads volumes today; polyethylene is gaining share fastest.
Application:
Cost-tier stratification separates specification-grade automotive compounds from commodity packaging formulations, with margin structures diverging by a factor of three or more.
- Automotive:Long-glass-fiber polypropylene compounds enable seat back frames and instrument panel carriers through in-mold welding techniques. OEMs in Germany and the US Midwest specify these grades for electric vehicle platforms where mass reduction extends battery range.
- Packaging:Polyethylene-based barrier compounds replace multi-layer film structures under EU recyclability mandates. Converters in the Netherlands and Italy are consolidating procurement around metallocene grades with proven seal-layer performance.
- Consumer Goods:Mineral-filled polypropylene compounds serve small appliance housings and furniture components.
- Construction:Geomembrane-grade polyethylene compounds provide chemical resistance in containment applications.
Automotive commands premium pricing tiers; packaging shows the steepest volume expansion trajectory.
Form:
Supply concentration favors granule producers with twin-screw extrusion assets, while film and sheet formats require downstream calendering or blown-film integration.
- Granules:Pelletized compounds feed injection molding and extrusion operations across automotive and packaging value chains. Compounders in China's Yangtze River Delta cluster dominate just-in-time delivery to tier-one suppliers.
- Powder:Micronized polyolefin powders serve rotational molding and coating applications with specific particle size distributions.
- Film:Pre-extruded film compounds bypass converter extrusion steps for high-volume flexible packaging converters.
- Sheet:Thick-gauge sheet compounds target thermoformed automotive interior trim and construction panels.
Granules anchor current production volumes; film formats are climbing fastest as converters seek process integration.
End User:
Customer-type fragmentation creates divergent service requirements, from technical co-development with manufacturers to transactional spot purchasing through distribution channels.
- Manufacturers:Tier-one automotive module suppliers and packaging converters contract directly for custom-engineered grades with certified flame-retardant or barrier properties. These relationships now bypass traditional OEM-approved material lists.
- Distributors:Regional distributors stock commodity grades for small-batch processors lacking compound qualification capabilities.
- Retailers:Private-label consumer goods retailers specify compound grades indirectly through contract manufacturers.
- Suppliers:Resin producers and additive houses supply pre-compounded masterbatches to downstream formulators.
Manufacturers capture the highest volume concentration; direct supplier relationships are expanding most quickly as specification authority migrates upstream.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer engineering talent clusters in Germany's Rhineland and Michigan's automotive corridor anchor compound innovation, while process chemistry expertise concentrates in Japan's petrochemical belt and China's Yangtze Delta manufacturing hubs.
United States
Automotive lightweighting programs in Detroit and the Midwest pull glass-filled polypropylene compounds into structural seat frames and instrument panel carriers. EPA emissions standards for volatile organic compounds tighten material certification protocols for interior applications. The US Gulf Coast petrochemical complex sustains cost-competitive feedstock supply for engineered polyolefin grades serving domestic OEMs.
Germany
EU REACH restrictions on persistent organic pollutants force compound reformulation across European automotive supply chains. The F-Gas Regulation accelerates hydrofluorocarbon replacement in extrusion foaming for interior trim components. Stuttgart's tier-one seating suppliers adopt long-glass-fiber polypropylene direct compounding with in-mold welding for electric vehicle platforms.
China
Integrated polymer-to-parts ecosystems in the Yangtze River Delta consolidate procurement decisions around just-in-time compound delivery. SAMR quality supervision protocols and GB standards for plastic food packaging add compliance layers for consumer goods channels. Shanghai and Suzhou house the densest concentration of twin-screw extrusion assets serving regional automotive and packaging converters.
India
Production-linked incentive schemes drive Maruti Suzuki and Tata Motors to localize supply chains, opening specification windows for certified compounders. BIS automotive grade certification creates competitive moats for domestic suppliers with pre-qualified materials. Gujarat and Maharashtra host emerging compounding capacity targeting tier-one supplier integration.
Japan
Metallocene catalyst technology development concentrates in the Chubu petrochemical corridor around Nagoya. METI industrial policy supports advanced polyolefin research for high-performance thermal management applications. Japanese compounders supply specification-grade materials to domestic automotive OEMs with stringent material traceability requirements.
Polyolefin Compound Market Competitive Landscape
The competitive structure tilts toward integrated petrochemical majors with captive resin supply and specialized compounders with formulation expertise. Dow Inc., LyondellBasell Industries, and ExxonMobil Chemical anchor the top tier through Gulf Coast feedstock integration and proprietary catalyst platforms. Mid-tier regional compounders compete on technical service proximity and custom formulation speed. Strategic moves concentrate on backward integration into refinery streams and geographic expansion into China's Yangtze Delta cluster.
Within the integrated petrochemical tier, Dow Inc. and LyondellBasell Industries represent archetypes of feedstock-advantaged suppliers with Gulf Coast asset bases. ExxonMobil Chemical occupies a position exemplifying metallocene technology leadership through its Vistamaxx platform specialization. Among diversified chemical conglomerates, BASF SE and Mitsui Chemicals sit within the portfolio-broad archetype, leveraging cross-divisional additive and resin synergies. SABIC and Borealis AG exemplify regional champions with Middle East and European feedstock positioning respectively. Avient Corporation represents the specialized compounder model focused on custom formulation and technical service proximity rather than captive resin production.
| Leading Market Players |
|---|
| LyondellBasell Industries |
| Dow Inc. |
| ExxonMobil Chemical |
| SABIC |
| Borealis AG |
| Braskem |
| Mitsui Chemicals |
| BASF SE |
| Avient Corporation |
| Others |
Value Network & Pricing Analysis
Polymer engineering talent clusters in Germany's Rhineland and Michigan's automotive corridor anchor formulation expertise, with labor-cost differentials between these engineering hubs and China's Yangtze Delta compounding zones driving three-tier pricing spreads across specification-grade, certified-standard, and commodity-economy compound tiers.
Pricing Analysis
Compound supply splits between bundled technical-service contracts and unbundled pellet-only transactions. Three-tier pricing structure across premium, standard, and economy levels separates OEM-certified automotive grades from FDA food-contact tiers and commodity packaging formulations. Price differentiation hinges on metallocene catalyst sourcing and REACH-compliant flame-retardant certification. Cost compression in standard-grade polypropylene is intensifying because propane dehydrogenation outages spike propylene monomer costs. Packaging converters show highest price sensitivity; tier-one automotive module suppliers prioritize performance consistency over unit cost.
Supply Chain Analysis
Post-consumer recycled content flows and regrind compatibilization are emerging as reverse-logistics competencies for EU Ecodesign compliance. Feedstock supply concentrates in the US Gulf Coast, Saudi Arabia, and China's coastal petrochemical corridors. Production draws from constrained-geometry catalyst systems, glass fiber rovings, and maleic anhydride grafting agents. Single-source vulnerability in metallocene catalyst supply creates specification-security risks for high-performance TPO grades. Distribution runs through integrated polymer-to-parts ecosystems in China's Yangtze Delta and direct mill relationships with European automotive tier-ones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polyolefin compound market functions as a regulatory compounder where EU REACH persistent organic pollutant restrictions and mono-material recyclability mandates are recalibrating formulation demand across automotive and packaging value chains.
For Market Incumbents: Deepen backward integration into refinery streams to buffer propylene feedstock volatility, and expand twin-screw extrusion assets in India's Gujarat corridor to capture BIS-certified automotive specification windows before Maruti Suzuki and Tata Motors complete supply chain localization under production-linked incentive schemes. For New Entrants and Emerging Players: The price-point gap between premium long-glass-fiber polypropylene compounds and economy-grade mineral-filled formulations creates white-space opportunity in mid-tier consumer appliance housings and furniture components. Target India's domestic compounding capacity shortfall with pre-certified grades under Bureau of Indian Standards protocols. Lead with reactive extrusion technical service to differentiate from commodity pellet suppliers. For Investors and Strategic Acquirers: Integrated petrochemical majors with captive resin supply and proprietary catalyst platforms are the most active acquirers in this space, consolidating regional compounders to secure Yangtze Delta manufacturing corridor positioning. Long-term viability over the next decade rests on feedstock-advantaged asset bases and Ecodesign-compliant formulation pipelines. Monitor EU extended producer responsibility framework implementation timelines as the inflection signal for which compound formulations retain commercial viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refinery Streams | Gulf Coast propane dehydrogenation assets buffer margin compression from propylene monomer volatility. |
| Reactive Extrusion Technology Deployment | Real-time rheology monitoring during maleic anhydride grafting eliminates batch-to-batch viscosity variation penalties. |
| REACH-Compliant Flame-Retardant Certification | Alternative chemistry pre-qualification captures first-mover advantage as EU persistent organic pollutant restrictions tighten. |
| Yangtze Delta Manufacturing Footprint | Localized twin-screw extrusion assets secure just-in-time delivery contracts with tier-one automotive module suppliers. |
| Post-Consumer Recycled Content Compatibilization | Barrier-property retention in recycled polyethylene compounds meets EU Ecodesign packaging mandates. |
Research Methodology
Bottom-up automotive and packaging demand modeling reconciled against top-down resin supply and catalyst production tracking forms the analytical core of this study. Primary interviews with compound plant managers, tier-one automotive procurement leads, flexible packaging converter technical directors, and distribution channel partners were cross-validated against secondary sources including customs and trade flow data, SEC 10-K filings of integrated petrochemical majors, American Chemistry Council and Cefic industry reports, and SAMR quality supervision protocols. Triangulation between stakeholder interview insights and published regulatory filings ensures segmentation integrity across polymer chemistry, application, and regional production hub dimensions.
Input-output matrix framing connects propylene and ethylene monomer supply forecasts to compound production capacity and end-use consumption patterns across the projection horizon. The analytical framework models volume and value trajectories by polymer type, integration depth, formulation grade tier, and regional manufacturing cluster. CAGRs were derived from elasticity-adjusted demand projections and capacity utilization assumptions. Industry-specific forecast inputs include electric vehicle platform lightweighting content-per-vehicle assumptions and EU Ecodesign recycled content mandate implementation schedules.
Caveats apply where propylene feedstock volatility, REACH regulatory scope expansion, or automotive OEM specification migration could materially shift the outlook. Forecasts reflect stated policy trajectories and announced capacity investments without contingency for unplanned outages or trade barrier imposition. Practitioners should monitor EU F-Gas Regulation phase-down schedules and metallocene catalyst supplier concentration ratios for early signals of supply chain stress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
South Korea Engineering Plastics Market
Polymers & Resins
Polymer Antioxidants Market
Polymers & Resins
Lactic Acid and Polylactic Acid Market
Polymers & Resins
Thermoplastic Starch (TPS) Market
Polymers & Resins
Phthalonitrile Resin Market
Polymers & Resins
Global Acrylic Polymer Market
Polymers & Resins
North America Polycarbonate (PC) Market
Polymers & Resins
Resorcinol Formaldehyde Resin Market
Polymers & Resins
Global Acrylic Emulsions Market
Polymers & Resins
Bio-Sourced Nylon Market
Polymers & Resins
Virgin Resin Market
Polymers & Resins
South America Engineering Plastics Market
Polymers & Resins
Global Ethylene Vinyl Acetate Resins Market
Polymers & Resins
Global Polyoxymethylene (POM) Market
Polymers & Resins
Global Polyphthalamide Market
Polymers & Resins
Smart Polymers Market