
 Polytetramethylene Ether Glycol (PTMEG) Market | 2026-2036
Polytetramethylene Ether Glycol (PTMEG) Market Size, Share, and Industry Trends Forecast 2026-2036
Polytetramethylene Ether Glycol (PTMEG) Market Intelligence
The commoditization of standard-grade PTMEG is narrowing the premium historically captured by specialty formulations for niche applications. Chemical producers such as BASF SE leverage extensive R&D to develop differentiated products for high-margin segments including medical-grade elastomers. INVISTA sustains its market position through proprietary process technologies and large-scale production capabilities for spandex fibers. Mitsubishi Chemical Corporation differentiates through its focus on high-purity grades for demanding industrial applications.
Polytetramethylene ether glycol is a waxy, white solid polyether polyol produced through the catalytic polymerization of tetrahydrofuran (THF). Its primary industrial function is to provide soft-segment elasticity, low-temperature flexibility, and hydrolytic stability in polyurethanes, polyesters, and polyamides. The spandex application, driven by consumption in the textile and footwear industries, represents the largest volume segment. Coatings and adhesives for the automotive sector offer higher-margin opportunities, particularly for specialized grades like PTMEG 2000 that enhance durability.
Producers must navigate a complex regulatory environment, including the European Union's REACH framework for chemical registration and the US EPA's Toxic Substances Control Act. In China, directives from the Ministry of Ecology and Environment (MEE) on volatile organic compounds (VOCs) influence formulation choices in coatings and sealants. The strategic imperative for manufacturers now involves securing access to key feedstocks while scaling up production of bio-based alternatives to meet sustainability goals from end-users.
Market Dynamics
The central dynamic shaping the PTMEG market is the tension between the established, cost-efficient petrochemical production pathway and the emergent, sustainability-driven bio-based manufacturing route. This creates a dual market structure with distinct feedstock, cost, and compliance considerations.
Growth Catalysts
- High-Performance Textiles:Insatiable demand for spandex in athletic wear, swimwear, and comfort apparel provides a consistent, high-volume consumption base. This is particularly strong in textile manufacturing centers across China and Vietnam.
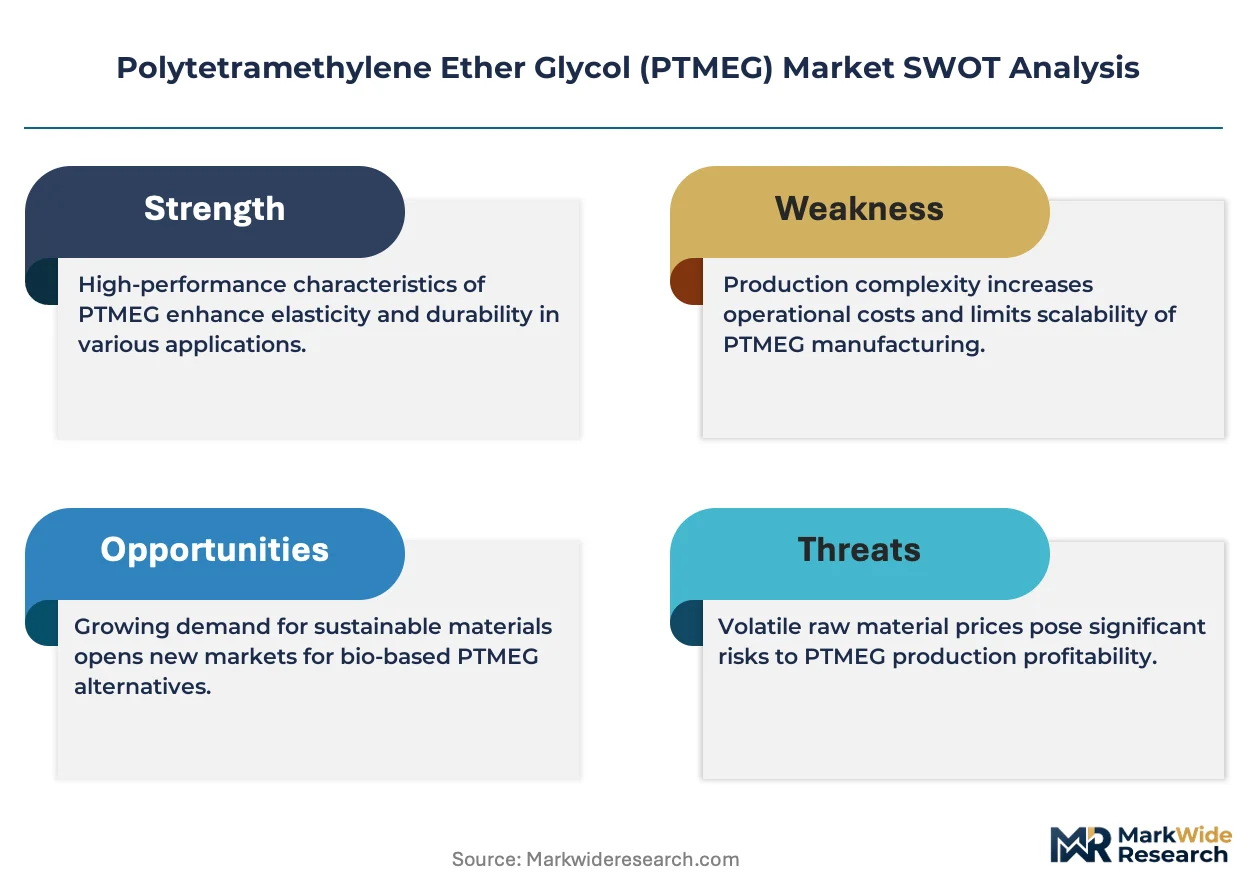
- Bio-Based Alternatives:The development of bio-PTMEG from renewable sources like corn or sugarcane aligns with corporate sustainability mandates and appeals to environmentally conscious consumers, creating a new premium product category.
- Automotive Sector Demand:Use in high-performance coatings, sealants, and synthetic leather for automotive interiors offers a higher-margin segment. These applications leverage PTMEG's durability, UV resistance, and flexibility.
Market Restraints
- Feedstock Price Volatility:Production costs are directly tied to the fluctuating prices of petrochemical feedstocks, primarily tetrahydrofuran (THF), creating margin pressure and pricing instability for producers.
- Substitution from Other Polyols:In less demanding applications, PTMEG faces competition from lower-cost polyols such as polypropylene glycol (PPG) and polyester polyols, which can offer adequate performance at a lower price point.
- High Capital Investment:The construction of world-scale, integrated PTMEG and THF production facilities requires substantial capital expenditure, creating a high barrier to entry for new market participants and concentrating supply.
Strategic Opportunities
- Medical Grade Polymers:Untapped potential exists in the medical device sector for high-purity, biocompatible PTMEG grades used in catheters, tubing, and implantable elastomers, representing a significant value-up opportunity.
- Geographic Expansion:As textile production diversifies, opportunities are emerging in nascent manufacturing hubs in South Asia and Africa, which are currently underserved by local PTMEG production.
- Advanced Industrial Elastomers:Development of specialized PTMEG grades for demanding industrial applications like mining equipment, rollers, and seals can open new niches where hydrolytic and abrasion resistance are critical.
Industry Challenges
- Process Technology Licensing:Access to efficient and proprietary THF polymerization technology is a critical operational challenge, with intellectual property controlled by a small number of established producers.
- Bio-Feedstock Supply Chain:Establishing a reliable, cost-effective, and scalable supply chain for renewable feedstocks presents a significant logistical and agricultural challenge for producers of bio-based PTMEG.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polytetramethylene Ether Glycol (PTMEG) Market |
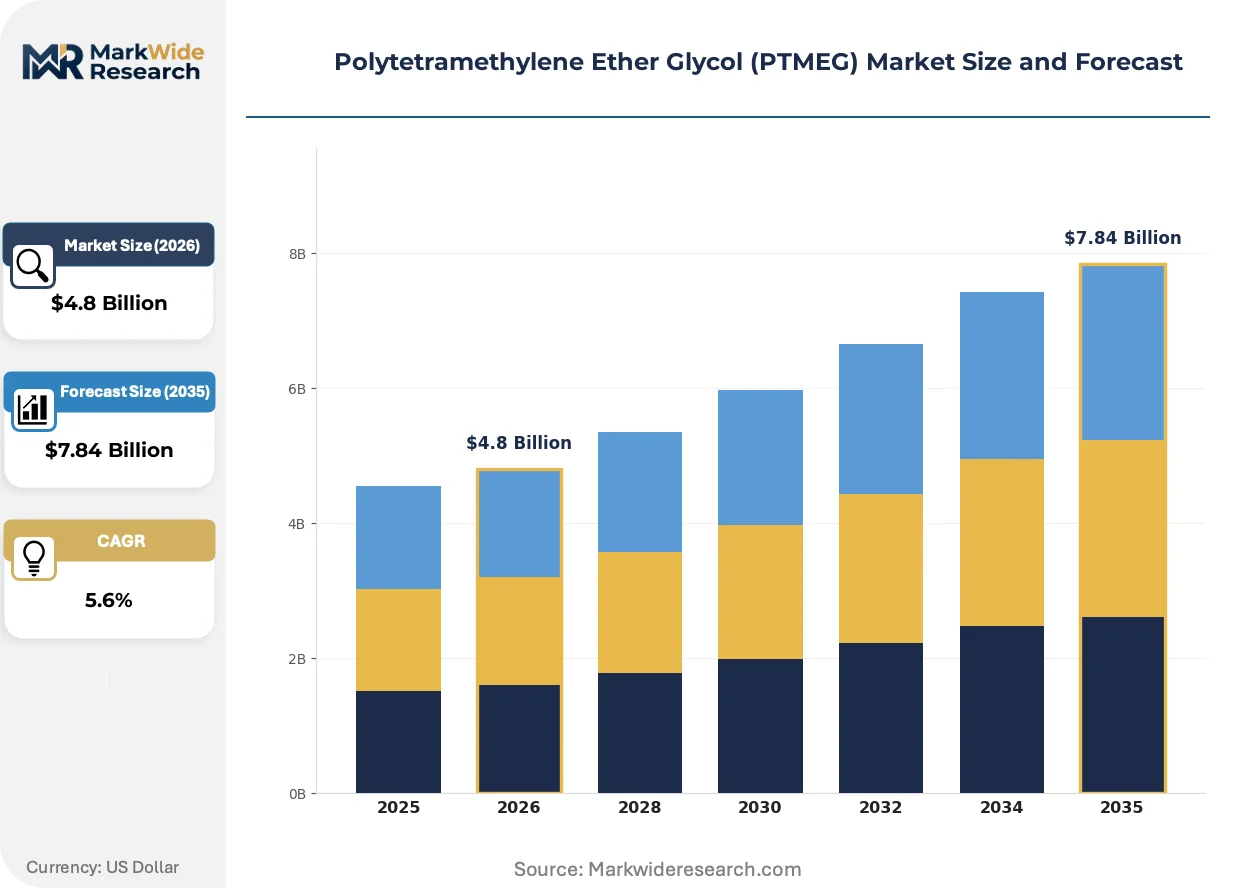
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PTMEG 1000, PTMEG 1800, PTMEG 2000, PTMEG 3000 Application: Spandex, Coatings, Adhesives, Sealants End User: Textiles, Automotive, Construction, Footwear Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Mitsubishi Chemical Corporation, LyondellBasell Industries Holdings BV, BASF SE, Korea PTG, Chang Chun Group, INVISTA, Dairen Chemical Corporation, Sinopec Great Wall Energy and Chemical Co., Ltd, Hyosung Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polytetramethylene Ether Glycol (PTMEG) Market Strategic Shifts & Innovations
Performance differentiation and sustainability are the twin engines of innovation in the PTMEG market. Producers are investing in both process technology to create specialized grades and bio-based pathways to meet new environmental standards from end-users.
Advanced process control (APC) and simulation software are key enabling technologies in PTMEG production. Chemical producers are adopting these tools to optimize reaction conditions, maximize THF conversion, and reduce energy consumption. This trend is digitizing the polymerization process, enabling real-time adjustments that result in tighter control over molecular weight and improved batch-to-batch consistency for specialty formulations.
The European Union's REACH regulation imposes stringent registration and evaluation requirements on all chemical substances manufactured or imported. This framework increases compliance costs and complexity for PTMEG producers and importers targeting the European market. The coatings and adhesives segments are most affected, driving formulators to prioritize PTMEG grades with complete and updated REACH dossiers to ensure market access.
End-users are exhibiting a clear preference shift toward suppliers who can provide comprehensive product lifecycle data and transparent sustainability metrics. This change moves procurement decisions beyond simple cost-per-ton analysis to include factors like carbon footprint and renewable content. This behavior is most visible in the consumer-facing textile and footwear industries, particularly within North American and European markets.
Polytetramethylene Ether Glycol (PTMEG) Market Segmentation
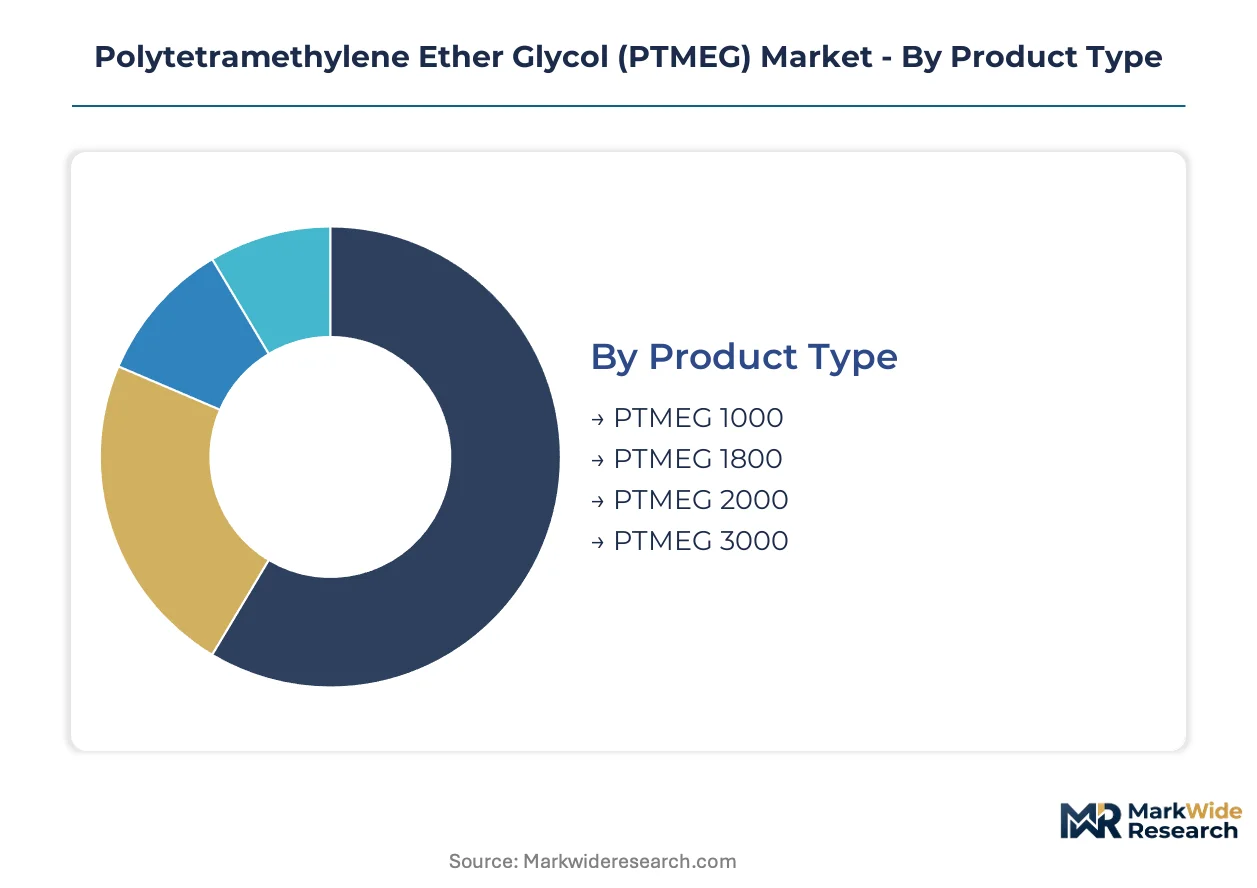
The Polytetramethylene Ether Glycol (PTMEG) market segmentation provides a granular view of product variations, application diversity, and end-user consumption patterns. This detailed breakdown helps manufacturers align production capabilities with specific market demands and identify areas for strategic development.
Product Type:
The Polytetramethylene Ether Glycol market categorizes product types based on molecular weight, influencing their suitability across a wide spectrum of end-use applications.
- PTMEG 2000:This grade features a molecular weight of approximately 2000 g/mol, offering enhanced durability and hydrolytic stability. Demand concentrates in the automotive sector for specialized coatings and adhesives that require robust performance characteristics.
- PTMEG 1000:Characterized by a lower molecular weight of around 1000 g/mol, this type provides excellent elasticity and low-temperature flexibility. Consumption is primarily driven by the textile industry for high-performance spandex fibers in athletic wear and comfort apparel.
- PTMEG 1800:This intermediate molecular weight grade finds application in various polyurethane formulations where a balance of flexibility and strength is required. It serves as a versatile building block for diverse elastomer products.
- PTMEG 3000:Offering a higher molecular weight, this grade is utilized in more demanding applications requiring superior tear strength and abrasion resistance. Its properties are valuable in specific industrial elastomer formulations.
The dominant share belongs to PTMEG 1000, while PTMEG 2000 is closing the gap fastest.
Application:
Application segmentation highlights the primary industrial uses for PTMEG, distinguishing between high-volume segments and specialized niche areas.
- Spandex:This application leverages PTMEG's soft-segment elasticity and hydrolytic stability to produce highly stretchable fibers. Consumption is substantial in the global textile and apparel industries, particularly in China and Vietnam.
- Coatings:PTMEG enhances the durability, flexibility, and UV resistance of various coating formulations. The automotive sector utilizes these coatings extensively for interior components and protective layers.
- Adhesives:PTMEG contributes to the flexibility, bond strength, and low-temperature performance of polyurethane-based adhesives. These are critical in construction and automotive assembly.
- Sealants:PTMEG provides flexibility and hydrolytic stability to sealant formulations, ensuring long-term performance in construction and industrial applications. It helps create robust and durable seals.
Spandex applications drive the largest consumption volume, with Coatings representing a significant value-added segment.
End User:
End-user industries define the ultimate consumers of PTMEG-derived products, influencing product specifications and sustainability requirements.
- Textiles:This sector utilizes PTMEG primarily for spandex production, creating fabrics for athletic wear, swimwear, and comfort apparel. Global textile manufacturing hubs in Asia are major consumers.
- Automotive:The automotive industry employs PTMEG in various components, including synthetic leather, coatings, and sealants, valuing its durability and flexibility. High-performance grades are critical for interior and exterior applications.
- Footwear:PTMEG contributes to the elasticity and comfort of footwear materials, particularly in athletic shoes and specialized boots. It enhances the flexibility and longevity of soles and uppers.
- Construction:This industry uses PTMEG in sealants, adhesives, and insulation materials for its hydrolytic stability and flexibility. It improves the structural integrity and longevity of building components.
The Textiles sector remains the primary end-user, while the Automotive industry offers substantial growth potential for specialized grades.
Distribution Channel:
Distribution channels illustrate the pathways through which PTMEG reaches its end-users, reflecting supply chain complexities and customer relationship models.
- Direct Sales:Manufacturers engage directly with large industrial customers, offering customized product specifications and technical support. This channel is prevalent for high-volume orders and strategic partnerships.
- Distributors:Intermediaries manage sales to smaller and medium-sized enterprises (SMEs) across diverse geographic regions. Distributors provide localized inventory and technical assistance.
- Online Retail:This channel serves niche markets or smaller buyers seeking specific grades in lower volumes. It facilitates rapid procurement for specialized applications.
- Others:This category includes specialized agents, brokers, or integrated supply chain solutions tailored for specific industrial clusters. These channels address unique logistical or procurement requirements.
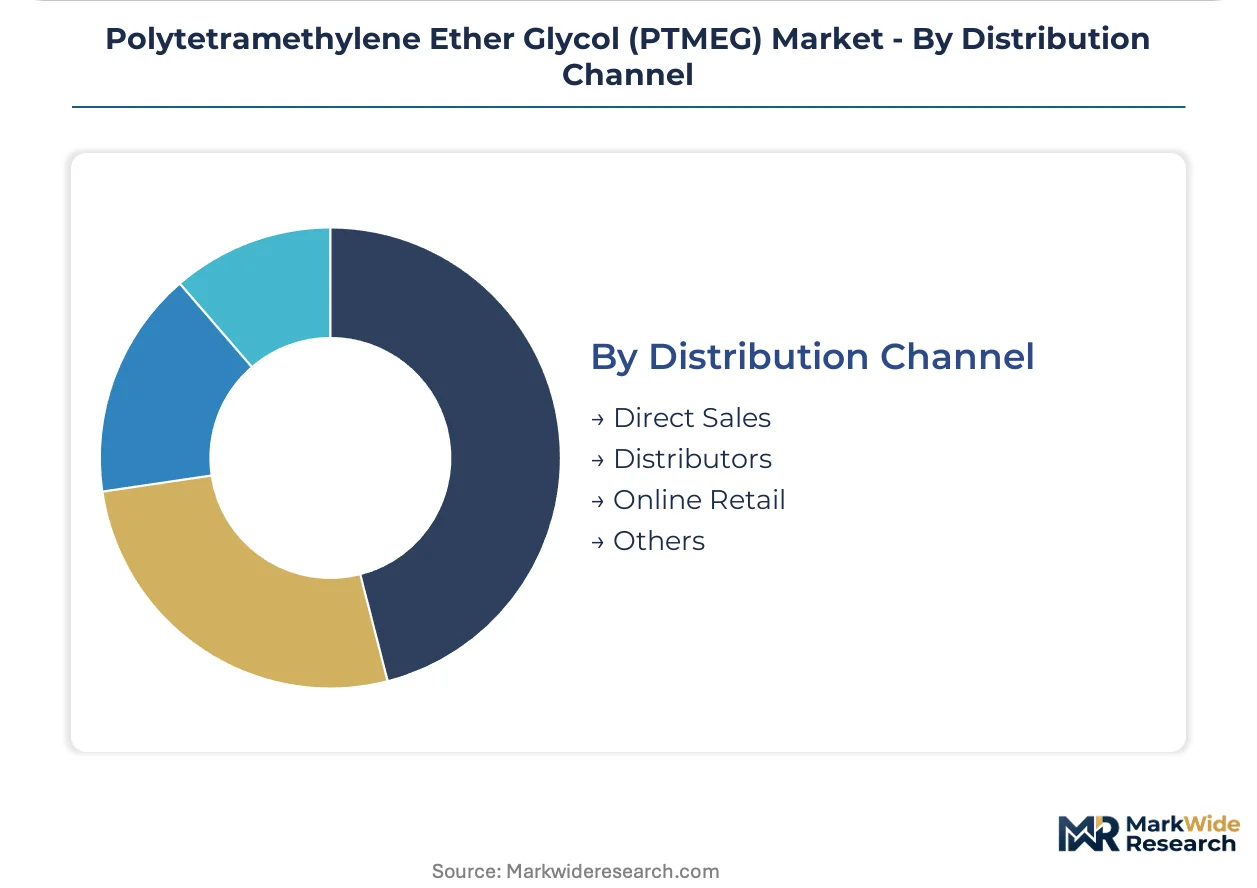
Direct Sales ensure tailored solutions for major clients, while Distributors provide efficient market penetration for diverse customer bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The PTMEG market exhibits varying demand elasticity across geographies, with high-volume textile applications proving more price-sensitive than specialized industrial or medical-grade segments. Global consumption patterns concentrate in regions with robust textile and automotive manufacturing bases. These areas drive consistent demand for PTMEG, influencing regional investment and supply chain strategies.
China
Demand for PTMEG in China primarily stems from its expansive spandex production for the global textile industry, alongside a growing need for performance coatings in the automotive sector. Directives from the Ministry of Ecology and Environment (MEE) on volatile organic compounds (VOCs) influence formulation choices for coatings and sealants. Textile manufacturing centers across the Yangtze River Delta and Pearl River Delta remain significant consumption hubs for PTMEG.
United States
The United States market focuses on high-value applications such as medical-grade elastomers and specialized industrial coatings. Compliance with the US EPA's Toxic Substances Control Act (TSCA) is critical for market access and product registration. Chemical production facilities along the Gulf Coast are increasingly developing and producing high-purity PTMEG grades for demanding applications.
Germany
Germany represents a strong market for high-performance PTMEG grades, particularly in its advanced automotive and industrial manufacturing sectors. The European Union's REACH framework imposes stringent registration and evaluation requirements on all chemical substances, impacting PTMEG producers. Chemical industry clusters, including those around Ludwigshafen, drive significant research and development efforts for differentiated PTMEG products.
Vietnam
Vietnam's rapidly expanding textile and footwear manufacturing industry creates substantial demand for PTMEG, especially for spandex used in athletic wear. Government incentives for foreign direct investment in manufacturing support the growth of these industries. Industrial zones near Ho Chi Minh City and Hanoi are experiencing increased PTMEG imports to support their growing production capacities.
India
Growing domestic textile production and infrastructure development projects drive PTMEG consumption in India, particularly for sealants and adhesives. Adherence to the Bureau of Indian Standards (BIS) for chemical quality is essential for market participation. Manufacturing hubs in Gujarat and Maharashtra are witnessing increased utilization of PTMEG in diverse industrial applications.
Polytetramethylene Ether Glycol (PTMEG) Market Key Industry Players
Large, diversified chemical producers and specialized PTMEG manufacturers split the market, each leveraging distinct competitive advantages. The market structure is characterized by a balance between global chemical giants and focused regional players. Strategic archetypes include integrated producers with proprietary technology and niche specialists targeting high-margin applications. Dominant competitive moves involve technology licensing and strategic capacity expansion to meet growing demand.
Among established chemical producers, Mitsubishi Chemical Corporation exemplifies a focus on high-purity grades for demanding industrial applications. INVISTA sustains its market position through proprietary process technologies and large-scale production capabilities for spandex fibers. BASF SE, a German-based chemical company, leverages extensive R&D to develop differentiated products for high-margin segments, including medical-grade elastomers.
| Leading Market Players |
|---|
| Mitsubishi Chemical Corporation |
| LyondellBasell Industries Holdings BV |
| BASF SE |
| Korea PTG |
| Chang Chun Group |
| INVISTA |
| Dairen Chemical Corporation |
| Sinopec Great Wall Energy and Chemical Co., Ltd |
| Hyosung Corporation |
| Others |
Cost & Logistics Intelligence
The Polytetramethylene Ether Glycol (PTMEG) market's upstream concentration in tetrahydrofuran (THF) production significantly influences downstream specialty grade pricing. This dependency creates margin pools for producers with proprietary process technologies.
Pricing Analysis
High-purity certifications and technical support drive lifetime value in specialized PTMEG segments. The dominant pricing model combines contract-based long-term offtake for standard grades with value-based pricing for specialty formulations. Price differentiation stems from quality grade, REACH compliance, and volume scale. Pricing softness reflects volatile tetrahydrofuran (THF) feedstock costs, making the textile industry highly price-sensitive compared to less elastic medical-grade and automotive applications.
Supply Chain Analysis
Feedstock price volatility for tetrahydrofuran (THF) creates a primary supply chain risk for PTMEG producers. Geographic supply concentrates in China and Vietnam for high-volume textile applications, with specialized production in the United States and Germany. Intellectual property surrounding efficient THF polymerization technology also creates a significant bottleneck for market entry. Distribution runs through direct sales to large industrial customers and distributors serving smaller and medium-sized enterprises across diverse regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a service-attach opportunity, with specialized technical support and certifications for high-purity grades expanding faster than basic PTMEG volumes. These value-added services enhance customer loyalty and capture premium pricing.
For Market Incumbents: Pre-empt margin erosion in standard grades by accelerating R&D into bio-based PTMEG alternatives. This mitigates feedstock price volatility and addresses end-user sustainability mandates. Invest in advanced process control to optimize production efficiency and ensure consistent quality for specialty formulations, countering competitive pressure from emerging regional players. Secure long-term supply agreements for key raw materials like THF.
For New Entrants and Emerging Players: Nascent manufacturing hubs in South Asia and Africa represent geographic underpenetration for PTMEG production. Target these regions by establishing localized distribution networks and offering tailored product grades for textile and construction applications. A go-to-market angle focused on cost-effective, regionally compliant products can capture early market share. Emphasize supply chain reliability to differentiate from distant suppliers.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated specialty chemical producers with proprietary bio-PTMEG technology and strong intellectual property portfolios. Long-term viability (5-10 years) favors companies capable of navigating regulatory complexities and securing sustainable feedstock access. Target acquisition archetypes include mid-sized firms with established R&D capabilities in medical-grade or bio-based elastomers. The signal to watch is successful commercialization of bio-based PTMEG at scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Address growing demand for spandex in China and Vietnam textile manufacturing. |
| Bio-based PTMEG Commercialization | Meet corporate sustainability mandates and open new premium product categories. |
| R&D for Medical-Grade Elastomers | Capture higher margins in the demanding medical device sector. |
| Proprietary Process Technology Licensing | Secure market position and control over efficient THF polymerization. |
| Long-term Feedstock Offtake Agreements | Mitigate raw material price volatility for stable production costs. |
Research Approach
Desk research of industry reports, company financial filings, and trade association publications preceded structured interviews with chemical plant managers, procurement leads at OEM manufacturers, and distribution channel partners. This approach combined primary insights with secondary validation, ensuring a comprehensive market understanding. Bottom-up data collection was triangulated with top-down market sizing.
Assumptions regarding stable regulatory environments and sustained textile industry growth were held fixed across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end-user, and regional consumption patterns. Compound annual growth rates were derived from historical trends and projected demand forecasts. Key inputs included global spandex production volumes and automotive sector growth projections.
Practitioners should monitor significant shifts in petrochemical feedstock prices or new environmental regulations for early signals of forecast revision. Forecasts reflect current market assumptions, acknowledging potential impacts from geopolitical events or supply chain disruptions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Ethylene Acrylic Acid (EAA) Copolymers Market
Polymers & Resins
Metallocene Polyethylene Market
Polymers & Resins
Global Polycarbonate Market
Polymers & Resins
Terpene Resins Market
Polymers & Resins
Global Impregnating Resins Market
Polymers & Resins
Vinyl Acetate Homopolymer Emulsion Market
Polymers & Resins
India Flooring Resins Market
Polymers & Resins
Flame Retardant Thermoplastics Market
Polymers & Resins
Global Polyamide Market
Polymers & Resins
Rigid Spray Polyurethane Foam Market
Polymers & Resins
C9 Resin Market
Polymers & Resins
Polyurethane (PU) Foam Market
Polymers & Resins
Synthetic and Bio Emulsion Polymers Market
Polymers & Resins
Isosorbide-Based Engineering Polymer Monomers Market
Polymers & Resins
PP Homopolymer Market
Polymers & Resins
Novolac Resins Market