
 Dimethyl Dicarbonate Market | 2026-2036
Dimethyl Dicarbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Dimethyl Dicarbonate Market Outlook
The Dimethyl Dicarbonate market is consolidating around a widening split between pharmaceutical-grade specifications and commodity beverage-grade supply. UBE Corporation leverages its integrated methyl carbonate backbone to sustain premium purity output. BASF SE anchors European supply through specialized cold-chain logistics for sensitive formulations. Shandong Hualu Hengsheng Group Co. competes on manufacturing scale in China's chemical corridor.
Dimethyl dicarbonate is an organic ester with the formula C4H6O5, synthesized through methanol carbonylation or phosgene-free routes, functioning primarily as a cold-sterilizing agent and chemical intermediate. Food Grade DMDC dominates volume through beverage stabilization demand, while Pharmaceutical Grade commands margin concentration due to sterility validation requirements. Chemical Intermediates applications are expanding fastest as downstream methylating agents find new synthetic pathways.
The EU EFSA and China's SAMR enforce divergent maximum residue limits that shape formulation standards and cross-border product registration. The US FDA governs DMDC application rates under 21 CFR 172.133, directly limiting per-liter dosing in wine and juice processing. Stakeholders must monitor regulatory harmonization pressures between REACH-aligned purity protocols and emerging national food additive registers.
Market Dynamics
Pharmaceutical-grade sterility validation requirements are compressing margins for commodity producers while rewarding integrated methyl carbonate operators who can guarantee sub-ppm impurity thresholds across batch records.
Growth Catalysts
- Cold-fill beverage preservation:Asia-Pacific bottlers are retrofitting aseptic lines to eliminate heat treatment energy costs, pulling DMDC demand from Shandong chemical corridors into ASEAN packaging hubs.
- EU E242 authorization expansion:EFSA's clarified maximum residue limits for non-alcoholic beverages opened formulation pathways previously restricted to wine applications alone.
- Phosgene-free synthesis routes:Methanol carbonylation catalyst improvements are lowering capital barriers for mid-scale producers seeking pharmaceutical-grade certification.
Market Restraints
- Methyl carbonate feedstock concentration:Shandong province controls over sixty percent of Asian merchant supply, creating single-point vulnerability for non-integrated DMDC manufacturers.
- Residual methanol specification tightening:China's GB 2760-2024 amendments reduced permitted methanol carryover by forty percent, forcing reformulation investments at legacy plants.
- Peracetic acid substitution:Some juice processors are reverting to peracetic acid cold-sterilization where DMDC decomposition kinetics complicate extended shelf-life claims.
Strategic Opportunities
- Indian FSSAI food additive registration:India's 2023 consolidated food safety regulations created a defined pathway for DMDC import and local blending that remains underexploited by foreign suppliers.
- Biopharmaceutical buffer applications:Cell culture media producers are evaluating DMDC as a terminal sterilization alternative to gamma irradiation for temperature-sensitive biologics.
- Direct-to-brewery distribution:Craft beverage cooperatives in Germany and Belgium are forming buying consortia to bypass traditional chemical distributor markups on small-batch DMDC orders.
Industry Challenges
- Analytical chemist scarcity:Validated gas chromatography methods for DMDC residue quantification require specialized toxicology training that outpaces university program output in Eastern Europe and Latin America.
- Cross-border registration synchronization:Divergent stability study requirements between FDA 21 CFR 172.133 and China's SAMR notification procedures extend product launch timelines by eighteen to thirty-six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dimethyl Dicarbonate Market |
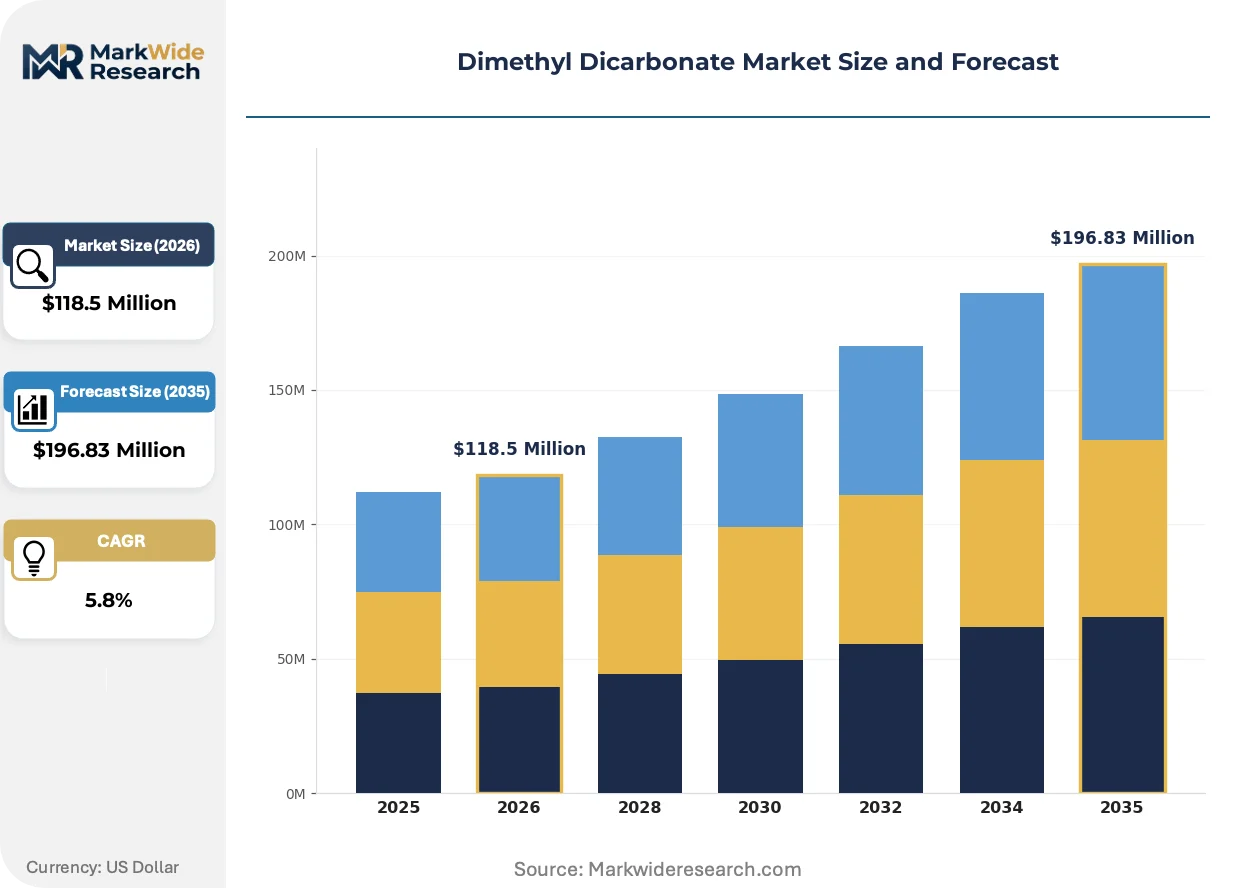
| Market Size in 2026 | $118.5 Million |
| Market Size in 2035 | $196.83 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Pharmaceutical Grade, Cosmetic Grade End Use Industry: Beverage, Pharmaceutical, Agriculture, Personal Care Application: Food Preservation, Beverage Stabilization, Chemical Intermediates, Surface Disinfection Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | UBE Corporation, LOTTE Chemical Corporation, Shandong Hualu Hengsheng Group Co., Shinghwa Advanced Material Group Co., Ltd., BASF SE, Mitsubishi Gas Chemical Company, Solvay, Shandong Haike Chemical Group Co., Ltd., Sankyo Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dimethyl Dicarbonate Market Strategic Shifts
Continuous flow reactor technology is displacing batch methyl carbonate synthesis, altering the capital intensity and geographic feasibility of DMDC production at multiple scales simultaneously.
Membrane-based methanol recovery systems are decentralizing purification economics for small-batch pharmaceutical-grade output. Regional compounders in the US Midwest and Northern Italy are adopting skid-mounted units that bypass centralized Shandong supply. This technology is compressing the minimum efficient scale for purity-certified production by an order of magnitude.
REACH-aligned substance evaluation under ECHA's 2024 work program is forcing re-registration of DMDC as a chemical intermediate separate from its food additive classification. Downstream methylating agent manufacturers face reformulation deadlines that favor suppliers with existing pharmaceutical dossiers. European custom synthesis houses are consolidating their supplier qualification lists to preempt authorization gaps.
Consolidated procurement through beverage industry buying groups is fragmenting historical distributor relationships. Major bottlers in Germany's Rhineland and Spain's Catalonia are negotiating direct supply agreements that displace regional chemical traders. This pattern is most visible in private-label juice segments where cost transparency pressures override traditional channel loyalty.
Dimethyl Dicarbonate Market Segmentation
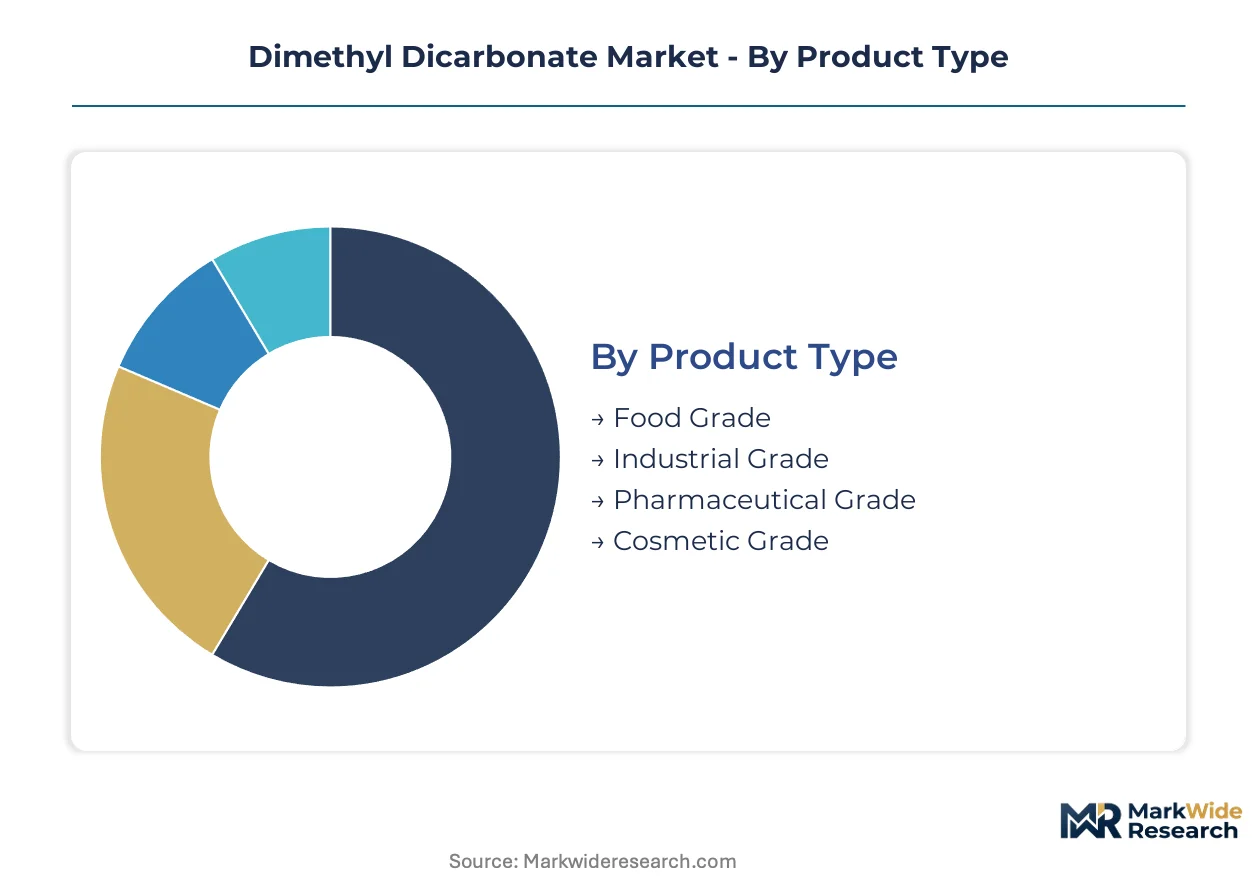
Dimethyl dicarbonate's functional versatility across sterilization, preservation, and synthesis applications creates distinct specification tiers that command divergent margin profiles. Segmentation by purity grade, end-use validation requirements, and channel access determines competitive positioning for producers and procurement strategy for buyers.
Product Type:
Purity thresholds separate commodity supply from certified-grade markets, with synthesis route and analytical validation creating tiered entry barriers.
- Food Grade:DMDC for beverage and food applications meets E242 and GB 2760 specifications for methanol carryover and decomposition kinetics. China's Shandong province and Germany's Rhineland beverage clusters absorb the majority of merchant supply, with cold-fill line retrofits in ASEAN bottling plants pulling incremental volume.
- Pharmaceutical Grade:Sub-ppm impurity thresholds validated across batch records support terminal sterilization for biologics and cell culture media. Sterility documentation requirements compress margins for non-integrated producers while rewarding methyl carbonate-backward operators with captive purification assets.
- Industrial Grade:Intermediate purity for chemical synthesis and methylating agent production, priced on methanol recovery efficiency and catalyst selectivity.
- Cosmetic Grade:Niche specification for personal care preservation, requiring cosmetic safety dossiers under EU and ASEAN regulatory frameworks.
Food Grade leads on scale; Pharmaceutical Grade leads on momentum.
End Use Industry:
Customer technical sophistication and regulatory burden vary sharply across sectors, reshaping sales force deployment and technical service investment.
- Beverage:Wine, juice, and non-alcoholic drink processors apply DMDC for cold-sterilization without heat treatment energy costs. EU EFSA's clarified maximum residue limits for non-alcoholic beverages expanded addressable formulation space beyond traditional wine applications.
- Pharmaceutical:Biopharmaceutical buffer and cell culture media producers evaluate DMDC against gamma irradiation for temperature-sensitive biologics terminal sterilization. FDA 21 CFR validation requirements and China's SAMR notification procedures extend registration timelines.
- Agriculture:Crop protection and post-harvest treatment applications, with residue limit protocols governing cross-border product movement.
- Personal Care:Cosmetic preservation and surface treatment, regulated under EU cosmetic safety assessments and ASEAN harmonized standards.
Beverage dominates volume absorption; Pharmaceutical expands most quickly.
Application:
Functional use case determines formulation concentration, stability study requirements, and competitive substitution risk from peracetic acid or heat treatment.
- Food Preservation:Direct addition to packaged foods for microbial control, governed by national food additive registers and maximum residue limits that vary across FDA, EFSA, and SAMR jurisdictions.
- Beverage Stabilization:Cold-sterilization in wine, juice, and functional drinks eliminates pasteurization energy costs. Some juice processors revert to peracetic acid where DMDC decomposition kinetics complicate extended shelf-life claims.
- Chemical Intermediates:Fastest-expanding application as downstream methylating agents find new synthetic pathways. REACH-aligned substance evaluation under ECHA's work program favors suppliers with existing pharmaceutical dossiers.
- Surface Disinfection:Industrial and healthcare cleaning applications, competing with quaternary ammonium and peroxide-based alternatives on contact time and material compatibility.
Beverage Stabilization anchors current demand; Chemical Intermediates commands steepest expansion trajectory.
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and buyer consolidation patterns across end-use segments.
- Direct Sales:Large beverage bottlers and pharmaceutical manufacturers negotiate supply agreements that bypass distributor markups, with Germany's Rhineland and Spain's Catalonia cooperatives forming buying consortia for small-batch orders.
- Distributors:Regional chemical traders serve mid-scale processors requiring formulation guidance and regulatory documentation support, though consolidated procurement through industry buying groups fragments historical relationships.
- Wholesalers:Bulk supply for industrial-grade applications with standardized specifications and lower technical service requirements.
- Online Retail:Emerging channel for small-volume cosmetic and research-grade orders, constrained by hazardous material shipping regulations.
Direct Sales captures margin concentration; Distributors retains volume breadth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized analytical chemists concentrate in Germany's Rhineland and China's Shandong province, anchoring quality validation capacity for pharmaceutical-grade output. Regulatory divergence between FDA 21 CFR 172.133 and China's SAMR notification procedures shapes where producers locate technical service teams. Cold-fill beverage retrofit projects pull talent toward ASEAN packaging hubs.
China
Shandong province hosts over sixty percent of Asian methyl carbonate merchant supply, with integrated producers operating captive DMDC purification trains. SAMR's GB 2760-2024 amendments reduced permitted methanol carryover by forty percent, forcing reformulation investments at legacy plants in the chemical corridor. Qingdao and Weifang clusters see capacity expansions targeting pharmaceutical-grade certification.
Germany
Rhineland beverage cooperatives form buying consortia to bypass traditional chemical distributor markups on small-batch orders. EFSA's clarified E242 maximum residue limits for non-alcoholic beverages expanded addressable formulation space beyond wine applications. BASF SE anchors European supply through specialized cold-chain logistics for sensitive formulations in Ludwigshafen.
United States
FDA 21 CFR 172.133 governs per-liter dosing limits in wine and juice processing, directly constraining formulation latitude for domestic bottlers. Midwest regional compounders adopt skid-mounted membrane methanol recovery units that bypass centralized Asian supply. Craft beverage producers in the Pacific Northwest evaluate direct-to-brewery distribution models.
India
FSSAI's 2023 consolidated food safety regulations created a defined pathway for DMDC import and local blending that remains underexploited by foreign suppliers. Maharashtra and Gujarat pharmaceutical clusters evaluate DMDC as terminal sterilization alternative to gamma irradiation for temperature-sensitive biologics. Mumbai-based analytical labs build SAMR-aligned validation capacity for export registration support.
Japan
METI guidance on phosgene-free synthesis routes accelerates methanol carbonylation catalyst improvements among domestic chemical producers. PMDA sterility documentation requirements compress margins for non-integrated DMDC manufacturers seeking pharmaceutical-grade entry. Kansai region biopharmaceutical buffer producers pilot DMDC against established terminal sterilization protocols.
Dimethyl Dicarbonate Market Competitive Environment
Capital-heavy producers compete with asset-light distributors across a market consolidating around purity-grade tiering. Integrated methyl carbonate operators sustain premium output through captive purification assets, while merchant buyers face feedstock concentration risk in Shandong province. Three archetypes dominate: backward-integrated chemical conglomerates, regional beverage-grade specialists, and pharmaceutical-certification custom synthesis houses. Competitive moves center on direct-to-brewery distribution partnerships and membrane-based methanol recovery technology licensing.
Among Japanese chemical conglomerates, UBE Corporation exemplifies the backward-integrated archetype with methyl carbonate backbone control. Mitsubishi Gas Chemical Company and Sankyo Chemical Co., Ltd. occupy positions within the specialty chemical tier, serving pharmaceutical and electronics-grade demand channels. Germany's BASF SE anchors European supply infrastructure through cold-chain logistics specialization. Chinese producers Shandong Hualu Hengsheng Group Co. and Shandong Haike Chemical Group Co., Ltd. represent manufacturing-scale competition from the Shandong chemical corridor. Solvay and LOTTE Chemical Corporation sit within the diversified materials group tier, leveraging cross-product purification expertise.
| Leading Market Players |
|---|
| UBE Corporation |
| LOTTE Chemical Corporation |
| Shandong Hualu Hengsheng Group Co. |
| Shinghwa Advanced Material Group Co., Ltd. |
| BASF SE |
| Mitsubishi Gas Chemical Company |
| Solvay |
| Shandong Haike Chemical Group Co., Ltd. |
| Sankyo Chemical Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical-grade sterility certification against commodity beverage-grade supply creates a bifurcated margin structure that feeds directly into supply chain configuration choices. Buyers seeking E242-compliant cold-sterilization agents face spot-market volatility in Shandong-dependent feedstock channels, while pharmaceutical dossier holders capture contract premiums through validated batch documentation.
Pricing Analysis
Packaged analytical validation services versus unbundled commodity supply separates pricing models across buyer tiers. Three-tier pricing structure across pharmaceutical, food-grade, and industrial purity levels reflects certification burden and methanol recovery efficiency. Cost compression in beverage-grade supply is intensifying because peracetic acid substitution threats force reformulation investments. Small-batch craft cooperatives exhibit highest price sensitivity; biopharmaceutical buffer producers demonstrate lowest sensitivity due to sterility validation requirements.
Supply Chain Analysis
Analytical chemist scarcity in Eastern European and Latin American manufacturing geographies constrains quality validation capacity expansion. Supply concentrates in China's Shandong province, Germany's Rhineland, and the US Midwest, with methyl carbonate feedstock and phosgene-free catalyst technology as critical inputs. Single-source vulnerability in Shandong merchant supply creates structural risk for non-integrated DMDC manufacturers. Distribution runs through direct sales agreements for large beverage bottlers and pharmaceutical manufacturers, with regional chemical traders serving mid-scale processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where pharmaceutical-grade sterility validation commands widening margin premiums over commodity beverage supply. The demand-shift toward biopharmaceutical buffer applications rewards producers with existing FDA 21 CFR and SAMR-aligned dossiers.
For Market Incumbents: Acquire membrane-based methanol recovery technology to decentralize purification economics and bypass Shandong feedstock concentration. Secure backward integration into methyl carbonate supply to defend against peracetic acid substitution threats in juice processing. Invest in SAMR-aligned analytical validation capacity to compress cross-border registration timelines.
For New Entrants and Emerging Players: Beverage cooperatives in Germany's Rhineland and Spain's Catalonia represent the most penetrable channel partner type for direct-to-brewery distribution bypass. Target India's FSSAI-registered import and local blending pathway as an underexploited white-space geography. Lead with small-batch pharmaceutical-grade certification to differentiate from Shandong commodity supply.
For Investors and Strategic Acquirers: Consolidation pressure builds where methyl carbonate backward integration separates viable pharmaceutical-grade producers from margin-compressed commodity suppliers. Long-term viability favors asset-light technology licensors and captive purification operators over feedstock-dependent merchant buyers. Watch ECHA's REACH-aligned substance evaluation deadlines as an inflection signal for custom synthesis house consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methyl Carbonate | Captive feedstock supply insulates UBE Corporation and Shandong Hualu Hengsheng from Shandong merchant market volatility. |
| Membrane Methanol Recovery Technology Licensing | Skid-mounted units enable Midwest regional compounders to bypass centralized Asian supply for pharmaceutical-grade output. |
| Direct-to-Brewery Distribution Partnerships | Rhineland and Catalonia cooperatives displace traditional chemical distributor markups on small-batch DMDC orders. |
| SAMR-Aligned Analytical Validation Investment | Mumbai-based labs build GB 2760-2024 compliance capacity to compress FDA-SAMR cross-border registration synchronization delays. |
| Phosgene-Free Synthesis Route Scale-Up | Methanol carbonylation catalyst improvements lower capital barriers for mid-scale pharmaceutical-grade certification entry. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build segment-level conviction. Primary discussions with beverage plant managers, pharmaceutical procurement leads, chemical distribution channel partners, and regulatory affairs directors informed demand-side validation. Secondary sources included customs and trade flow data, SEC 10-K filings from listed chemical producers, EFSA and SAMR regulatory notifications, and ACC and Cefic industry reports. Bottom-up capacity modeling and top-down demand triangulation cross-validated volume estimates.
Segment-weighting approaches applied purity grade, end-use industry, and regional regulatory cluster as core dimensions across the projection horizon. CAGRs derived from installed cold-fill line retrofit trajectories in ASEAN packaging hubs and pharmaceutical-grade certification expansion rates. Forecast inputs incorporated methanol carbonylation catalyst efficiency improvements and ECHA REACH re-registration timelines for chemical intermediate classifications.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SAMR-FDA regulatory harmonization progress and peracetic acid substitution adoption in juice processing. Forecasts reflect documented assumptions around Shandong feedstock concentration stability and analytical chemist training program expansion in Eastern Europe. Material deviation in EFSA E242 authorization scope or GB 2760 methanol carryover amendments warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Lauoryl Chloride Market
Chemical Intermediates
Copper Chemicals Market
Chemical Intermediates
Global Electrophoresis Reagents Market
Chemical Intermediates
Glycidyl Methacrylate Market
Chemical Intermediates
Diethyl Phthalate Market
Chemical Intermediates
Pharmaceutical Intermediates Market
Chemical Intermediates
Nutrition Chemicals Market
Chemical Intermediates
Octenylsuccinate Market
Chemical Intermediates
Bromate Substitute Market
Chemical Intermediates
1, 3, 5-Triazine Market
Chemical Intermediates
Nickel Acetate Market
Chemical Intermediates
Fungal Staining Reagent Market
Chemical Intermediates
Carboxylic Acid Chlorides Market
Chemical Intermediates
Tertiary Butylhydroquinone Acids Market
Chemical Intermediates
Dye Intermediates Market
Chemical Intermediates
Reagent Bottle Market