
 Bio-Based Polypropylene in Medical Devices Market | 2026-2036
Bio-Based Polypropylene in Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based Polypropylene in Medical Devices Market Analytics
The capital-intensity divergence between integrated petrochemical majors and specialized bio-polymer developers is redrawing competitive boundaries in medical-grade resins. TotalEnergies SE leverages its refinery-to-polymer integration to secure feedstock cost advantages for certified bio-attributed propylene. Braskem SA anchors its position through sugarcane-derived ethanol feedstock control in Brazil, extending traceability credentials that European hospital procurement teams now require. Neste Oyj competes via renewable naphtha supply partnerships with LyondellBasell Industries NV, positioning both firms for pharmaceutical-grade polymer qualification.
Bio-based polypropylene in medical devices denotes isotactic polypropylene synthesized from renewable feedstocks such as vegetable oils, bio-naphtha, or agricultural waste streams rather than fossil-derived propylene, with melt flow indices typically ranging from 2 to 50 g/10 min to accommodate diverse sterilization and forming requirements. Its primary purpose centers on replacing conventional petroleum-based polypropylene in single-use and limited-use medical articles without compromising gamma or autoclave sterilization tolerance. Injection molding dominates volume throughput for containers and surgical instrument handles, while extrusion commands premium positioning in tubing for drug delivery and patient monitoring circuits where dimensional precision governs fluid dynamics. Casting occupies a narrower niche in implant prototyping, though regulatory qualification timelines for permanent implant applications remain protracted relative to disposable categories.
FDA 21 CFR Part 177 compliance for indirect food additives and the EU MDR's reinforced biological evaluation requirements under ISO 10993 collectively elevate testing burdens for novel bio-based resin introductions. REACH substance registration and ECHA guidance on polymer monomer traceability further constrain market access for uncertified imports into European healthcare supply chains. Stakeholders must monitor evolving EPA bio-preferred procurement mandates and corresponding state-level hospital sustainability purchasing protocols to anticipate demand inflection points.
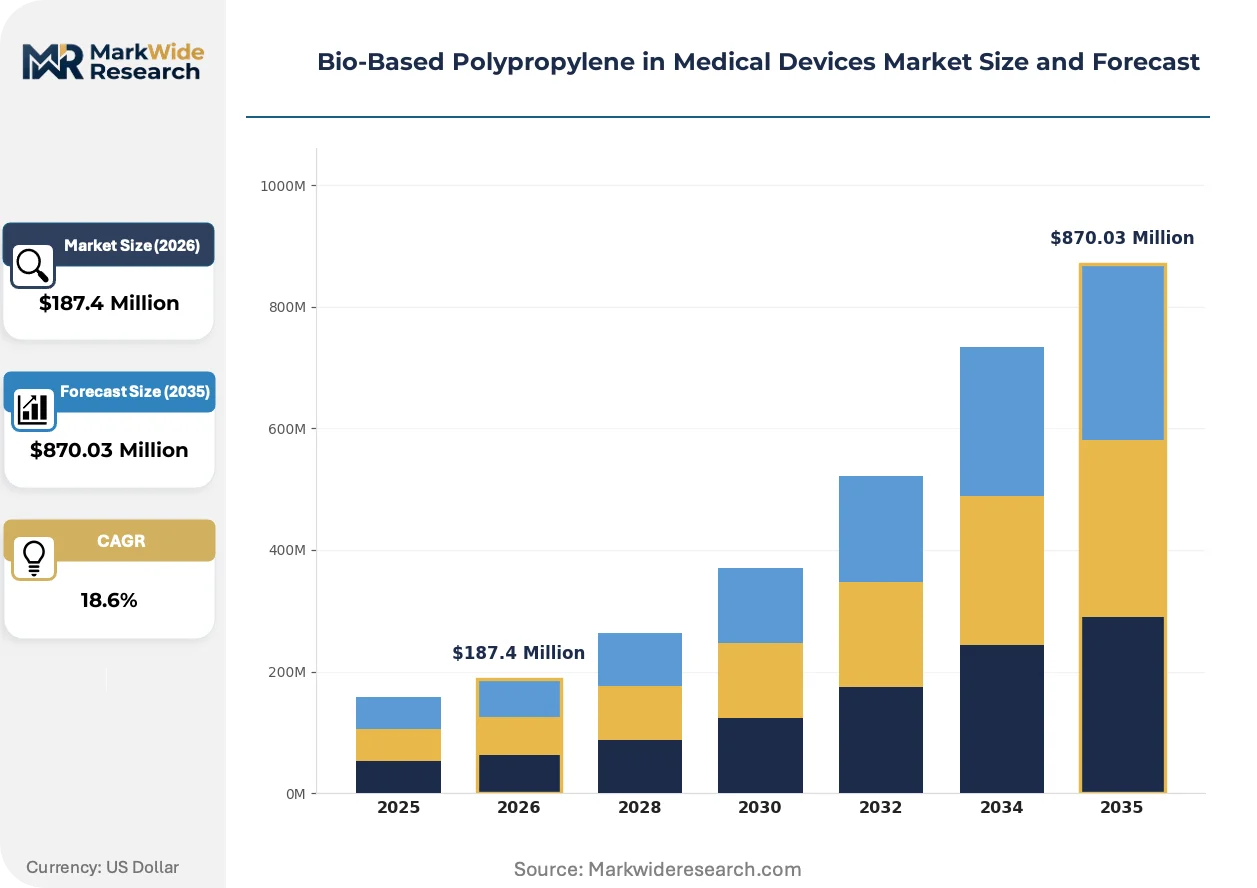
Market Dynamics
Hospital procurement departments now embed carbon accounting into resin qualification protocols, forcing polymer suppliers to demonstrate mass-balance certification and feedstock traceability before contract renewal cycles.
Growth Catalysts
- EU MDR biological evaluation mandates:Device manufacturers must document material origin under ISO 10993-1, creating preference pull for certified bio-attributed grades that streamline technical file preparation.
- Injection molding throughput expansion:Single-use surgical instrument producers in Baden-Württemberg are retrofitting lines for bio-PP grades with matched melt flow indices to petroleum equivalents.
- Scope-three emissions accounting:German hospital networks now report supply chain carbon intensity to federal health ministries, converting polymer selection into a compliance variable.
Market Restraints
- Feedstock cost volatility:Vegetable oil and bio-naphtha prices track agricultural commodity markets, exposing resin converters to margin compression absent in fossil-propylene supply chains.
- European polymer qualification concentration:ECHA REACH registration requirements and notified body capacity limits create bottleneck conditions for non-European resin entrants seeking MDR certification.
- Gamma sterilization performance gaps:Certain bio-PP grades exhibit accelerated yellowing under irradiation, restricting deployment in transparent drug-delivery containers where optical clarity is specified.
Strategic Opportunities
- Bavaria medical device cluster expansion:Polymer innovation ecosystems around Munich and Nuremberg offer co-location advantages for resin suppliers seeking integrated device-manufacturer partnerships.
- EPA bio-preferred procurement mandates:Federal hospital purchasing protocols in the United States are incorporating renewable content thresholds, opening qualification pathways for certified European suppliers.
- Extrusion-grade tubing convergence:Drug-delivery catheter producers are evaluating bio-PP alternatives to PVC in peristaltic pump segments where plasticizer migration concerns are tightening material specifications.
Industry Challenges
- Polymer characterization expertise scarcity:Analytical chemists capable of validating bio-attributed content through carbon-14 testing and isotope ratio mass spectrometry command premium compensation, constraining quality team scaling.
- Legacy sterilization validation transfer:Device manufacturers must repeat bioburden and endotoxin studies when switching feedstock origins, extending time-to-revenue for reformulated resin introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based Polypropylene in Medical Devices Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containers, Surgical Instruments, Implants, Tubing Technology: Casting, Injection Molding, Blow Molding, Extrusion End User: Hospitals, Clinics, Laboratories, Research Facilities Application: Drug Delivery, Diagnostic Devices, Surgical Procedures, Patient Monitoring |
| Companies Covered | TotalEnergies SE, BASF SE, LyondellBasell Industries NV, Neste Oyj, Avient Corporation, Borealis AG, Mitsui Chemicals Inc., Saudi Basic Industries Corp, Braskem SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based Polypropylene in Medical Devices Market Evolving Landscape
Material science advances and regulatory data requirements are fragmenting the previously uniform polypropylene specification landscape into performance-tiered categories with distinct sterilization tolerances and traceability credentials.
Mass-balance certification methodologies are bifurcating the supplier base into integrated petrochemical majors with refinery-attributed bio-naphtha streams and specialized bio-polymer developers dependent on agricultural waste or vegetable oil hydroprocessing. German hospital procurement teams now demand ISCC PLUS certification for scope-three reporting compliance, compressing market access for uncertified resin traders. The structural consequence is a two-tier pricing architecture where certified grades command sustained premiums despite equivalent mechanical properties.
REACH substance registration under ECHA guidance is tightening monomer traceability requirements for polymer imports into European healthcare supply chains. Industrial consequence includes mandatory supply chain documentation extending to third-tier feedstock origins, with enforcement actions against incomplete dossiers accelerating since the 2023 registration deadline. Drug-delivery device manufacturers sourcing extrusion-grade tubing are most affected, responding by consolidating supplier panels to vertically integrated resin producers with captive mass-balance systems.
Hospital sustainability purchasing protocols are embedding carbon intensity thresholds into multi-year polymer supply agreements, displacing spot-market procurement for strategic resin categories. German university hospital networks in North Rhine-Westphalia now require science-based target alignment from polymer vendors, with contract renewal contingent on verified feedstock origin documentation. The shift is most visible in single-use surgical instrument procurement, where Baden-Württemberg device clusters report accelerated qualification timelines for bio-attributed alternatives.
Bio-Based Polypropylene in Medical Devices Market Segmentation
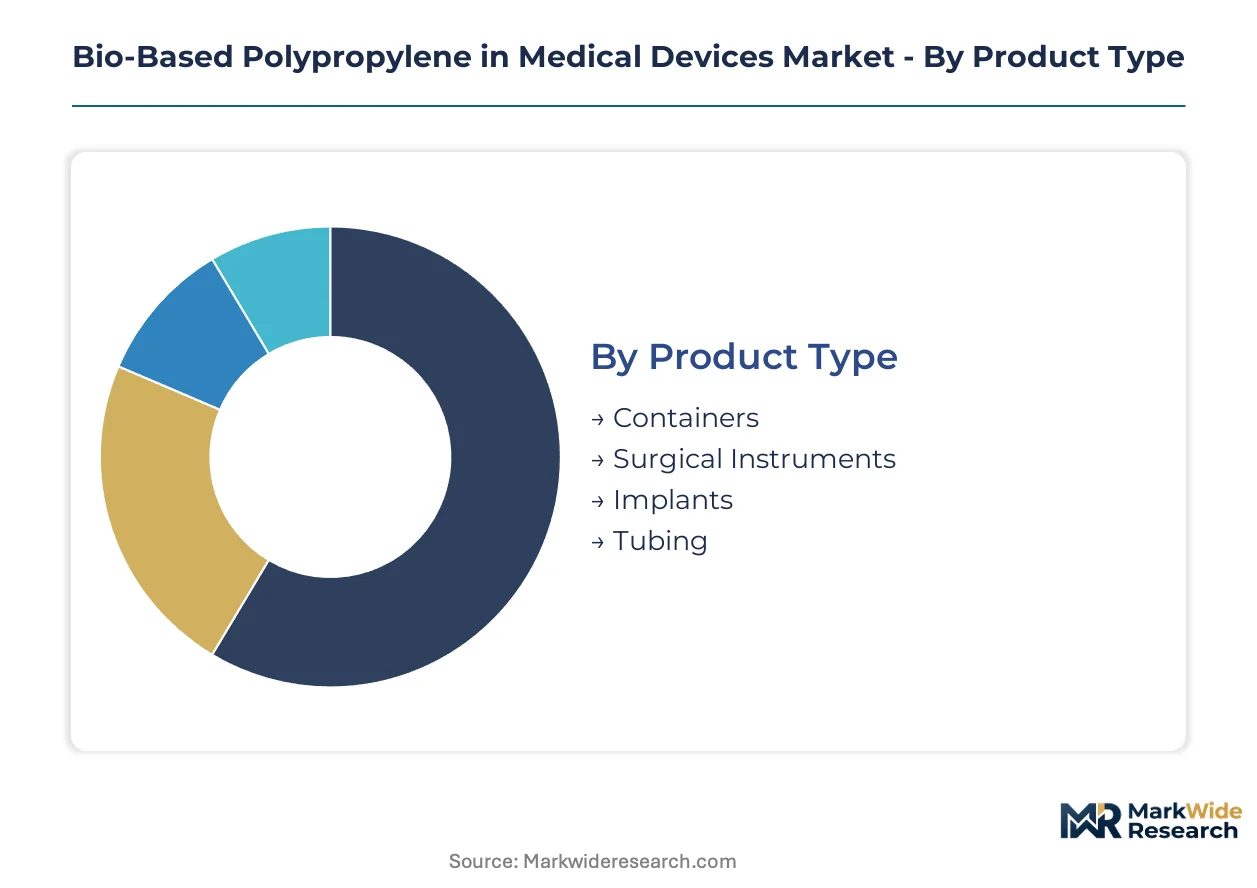
Segmentation in bio-based polypropylene reveals how regulatory pathways diverge across sterilization requirements and traceability mandates. Device manufacturers select grades based on ISO 10993-1 biological evaluation tiers and mass-balance certification availability.
Product Type:
FDA 21 CFR Part 177 and EU MDR biological evaluation requirements create tiered qualification burdens depending on patient contact duration and invasiveness.
- Surgical Instruments:Single-use scalpels, forceps, and retractors dominate procurement volumes in German hospital networks. Baden-Württemberg device clusters report accelerated qualification timelines as procurement teams embed carbon accounting into contract renewals.
- Containers:Specimen collection vessels and pharmaceutical storage containers require gamma sterilization tolerance. Certain bio-PP grades exhibit accelerated yellowing under irradiation, restricting deployment where optical clarity is specified.
- Tubing:Drug-delivery catheter producers evaluate bio-PP alternatives to PVC in peristaltic pump segments.
- Implants:Permanent implant applications face protracted regulatory qualification timelines relative to disposable categories.
Established volume favors surgical instruments; emerging adoption favors tubing.
Technology:
Processing method determines melt flow index specifications and sterilization validation requirements, with cost tiers separating high-throughput molding from precision extrusion.
- Injection Molding:High-volume throughput for containers and instrument handles requires matched melt flow indices to petroleum equivalents. German producers in Baden-Württemberg are retrofitting lines for bio-PP grades.
- Extrusion:Commands premium positioning in tubing for drug delivery and patient monitoring circuits where dimensional precision governs fluid dynamics.
- Blow Molding:Used for hollow container fabrication with specific wall thickness requirements.
- Casting:Occupies a narrower niche in implant prototyping with limited commercial scale.
Injection molding captures current procurement scale; extrusion gains share fastest in premium device segments.
End User:
Customer type dictates volume concentration versus specification complexity, with hospital procurement centralization driving standardization.
- Hospitals:German university hospital networks in North Rhine-Westphalia require science-based target alignment from polymer vendors. Contract renewal is contingent on verified feedstock origin documentation.
- Clinics:Outpatient surgical centers prioritize cost efficiency over mass-balance certification.
- Laboratories:Specimen handling applications demand consistent sterilization performance.
- Research Facilities:Implant prototyping drives small-batch casting demand with extended qualification timelines.
Hospitals anchor procurement volume; research facilities represent the steepest expansion trajectory for certified grades.
Application:
Clinical use case determines biological evaluation intensity under ISO 10993-1, with patient contact duration governing regulatory pathway selection.
- Drug Delivery:Peristaltic pump tubing and infusion sets face tightening plasticizer migration concerns. Manufacturers are consolidating supplier panels to vertically integrated resin producers.
- Surgical Procedures:Single-use instrument demand concentrates in Bavaria and Baden-Württemberg medical device clusters.
- Diagnostic Devices:Specimen collection containers require gamma sterilization compatibility.
- Patient Monitoring:Circuit tubing demands dimensional precision for reliable fluid dynamics.
Surgical procedures dominate current procurement; drug delivery shows the strongest certification-driven growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement teams in Germany absorb price premiums for certified bio-attributed grades without volume elasticity, while outpatient clinics in Brazil and India remain acutely sensitive to resin cost differentials. This demand-elasticity contrast structures regional expansion sequencing for polymer suppliers.
Germany
University hospital networks in North Rhine-Westphalia mandate science-based target alignment from polymer vendors, with contract renewal contingent on verified feedstock origin documentation. The EU MDR's reinforced biological evaluation requirements under ISO 10993-1 create preference pull for certified bio-attributed grades. Medical device clusters in Baden-Württemberg and Bavaria anchor polymer innovation ecosystems around Munich and Nuremberg.
United States
Federal hospital purchasing protocols are incorporating renewable content thresholds through EPA bio-preferred procurement mandates, opening qualification pathways for certified European suppliers. FDA 21 CFR Part 177 compliance for indirect food additives elevates testing burdens for novel bio-based resin introductions. The Southeast and Midwest manufacturing corridors concentrate injection molding capacity for single-use surgical instruments.
Brazil
Sugarcane-derived ethanol feedstock control anchors traceability credentials that European hospital procurement teams now require, though domestic price sensitivity limits premium-grade absorption. ANVISA maintains alignment with FDA biocompatibility standards for polymer qualification. The São Paulo and Rio de Janeiro industrial basins concentrate resin conversion capacity for regional medical device supply.
Japan
PMDA maintains stringent pharmaceutical-grade polymer qualification timelines that extend market access for bio-based alternatives relative to disposable categories. METI supports renewable feedstock transition through industrial decarbonization programs targeting scope-three emissions. The Kanto and Kansai manufacturing belts concentrate precision extrusion capacity for drug-delivery tubing applications.
China
NMPA's evolving biocompatibility standards and GB standards for medical polymers create dual-track qualification complexity for imported bio-based resins. Dual carbon goals accelerate domestic renewable feedstock capacity investment. The Yangtze River Delta and Pearl River Delta medical device manufacturing clusters drive injection molding demand for single-use instruments.
Bio-Based Polypropylene in Medical Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with refinery-attributed bio-naphtha streams separating scale players from agricultural waste-dependent developers. Petrochemical majors leverage mass-balance certification and captive feedstock integration to defend position in hospital procurement channels. Specialist developers compete through sugarcane or vegetable oil hydroprocessing traceability. Dominant competitive moves include strategic partnerships for renewable naphtha supply and capacity expansion for pharmaceutical-grade polymer qualification.
Within the integrated petrochemical tier, TotalEnergies SE and LyondellBasell Industries NV exemplify refinery-to-polymer positioning that secures feedstock cost advantages for certified bio-attributed propylene. Braskem SA anchors the agricultural-origin specialist segment through Brazilian sugarcane-derived ethanol feedstock control. Neste Oyj occupies a bridging position via renewable naphtha supply partnerships that extend traceability credentials across multiple downstream polymer producers.
| Leading Market Players |
|---|
| TotalEnergies SE |
| BASF SE |
| LyondellBasell Industries NV |
| Neste Oyj |
| Avient Corporation |
| Borealis AG |
| Mitsui Chemicals Inc. |
| Saudi Basic Industries Corp |
| Braskem SA |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements with mass-balance certification lock in both feedstock access and price visibility for German hospital procurement teams, converting polymer selection into a multi-year compliance variable rather than spot-market discretion.
Pricing Analysis
After-sales revenue from sterilization validation services and technical file support drives lifetime value for resin suppliers serving EU MDR-compliant device manufacturers. Three-tier pricing structure across ISCC PLUS-certified premium grades, standard mass-balance alternatives, and uncertified economy tiers separates hospital networks from cost-sensitive clinics. Pricing pressure stems from vegetable oil and bio-naphtha commodity volatility, compressing converter margins absent in fossil-propylene supply chains. Outpatient surgical centers in Brazil and India exhibit acute price sensitivity, while German university hospitals absorb certified-grade premiums without volume elasticity.
Supply Chain Analysis
Brazil and Germany anchor bio-based polypropylene production, with Braskem SA's sugarcane-derived ethanol streams feeding European traceability requirements and TotalEnergies SE's refinery-attributed bio-naphtha securing cost advantages for certified grades. Feedstock dependencies rest on agricultural commodity markets, renewable naphtha supply partnerships, and mass-balance certification infrastructure. Single-source vulnerability concentrates in European notified body capacity for MDR qualification, creating bottleneck conditions for non-European resin entrants. Distribution runs through vertically integrated polymer producers with captive mass-balance systems, displacing spot-market traders from hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Analytical chemists capable of carbon-14 testing and isotope ratio mass spectrometry command premium compensation, constraining quality team scaling and fragmenting competitive position between certificate-holding integrated majors and expertise-dependent specialists.
For Market Incumbents: Shield hospital procurement relationships by embedding science-based target alignment into contract renewal cycles before Brazilian sugarcane-origin competitors achieve European notified body certification. Prioritize backward integration into renewable naphtha supply partnerships to defend feedstock cost advantages against agricultural commodity volatility. For New Entrants and Emerging Players: Mass-balance certification service gaps in mid-tier Asian resin conversion create entry pathways for specialized bio-polymer developers. Target peristaltic pump tubing segments where PVC plasticizer migration concerns tighten specifications and incumbent qualification timelines lag. Lead with ISCC PLUS documentation bundled with sterilization validation support. For Investors and Strategic Acquirers: Agricultural-origin specialists with Brazilian feedstock control and European distribution partnerships represent the most defensible acquisition archetype. Monitor EPA bio-preferred procurement mandate expansion as inflection signal for US hospital network demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Mass-Balance Certification Investment | ISCC PLUS documentation unlocks German hospital procurement contract renewals. |
| Renewable Naphtha Supply Partnership | Neste Oyj partnerships extend traceability credentials across European polymer producers. |
| Sterilization Validation Transfer | Gamma and autoclave bioburden studies accelerate device manufacturer time-to-revenue. |
| Hospital System Partnership | Baden-Württemberg device clusters anchor co-location advantages for resin suppliers. |
| Pharmaceutical-Grade Polymer Qualification | FDA 21 CFR Part 177 compliance opens US federal hospital purchasing protocols. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) submissions, EMA MDR technical files, ISCC PLUS certification databases, and European hospital procurement records. Interviews with polymer plant managers, biomedical engineers at German university hospitals, GPO contracts managers, and regulatory affairs directors at device manufacturers inform supply-side capacity and demand-side qualification requirements. Bottom-up resin production estimates triangulate against top-down hospital procurement spend analysis.
Segmentation dimensions modeled span sterilization tolerance grade, mass-balance certification tier, processing technology, patient contact duration under ISO 10993-1, and regional regulatory cluster. CAGRs derive from feedstock cost trajectory scenarios, hospital sustainability mandate adoption curves, and notified body certification capacity constraints across the projection horizon. Forecast inputs incorporate EU MDR biological evaluation timeline assumptions and EPA bio-preferred procurement threshold evolution.
Underlying assumptions cover vegetable oil price stability, notified body capacity expansion, and gamma sterilization performance parity for bio-PP grades, with deviation risk concentrated in agricultural commodity volatility and REACH substance registration enforcement acceleration. Recalibration cycles align with material shifts in EU MDR guidance documents and federal hospital purchasing protocol amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Agar Resin Market
Polymers & Resins
Polymer Modifiers Market
Polymers & Resins
Emulsion PVC Market
Polymers & Resins
Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Soil Release Polymer Market
Polymers & Resins
Acetal (POM) Copolymer Market
Polymers & Resins
Antimicrobial Plastics Market
Polymers & Resins
Global Polyamide 6 Market
Polymers & Resins
Italy Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Global Polymerization Initiator Market
Polymers & Resins
Resorbable Polymers Market
Polymers & Resins
Polybenzoxazine Resins Market
Polymers & Resins
Silyl Acrylate Polymer (SAP) Market
Polymers & Resins
Wood Coating Resins Market
Polymers & Resins
Silane-Modified Polymers Market
Polymers & Resins
Global Amino Resin Market