
 Global Isosorbide Market | 2026-2036
Global Isosorbide Market Size, Share, and Industry Trends Forecast 2026-2036
Global Isosorbide Market Foresight
Pharmaceutical procurement among cardiovascular API buyers is consolidating, forcing isosorbide suppliers to secure long-term offtake contracts. Roquette Frères leverages its starch-derived sorbitol feedstock to anchor European supply security. Mitsubishi Chemical Corporation sustains captive demand through downstream polymer integration. SK Chemicals competes on bioplastics-grade purity specifications.
Isosorbide is a bicyclic sugar alcohol synthesized from sorbitol dehydration, yielding a rigid diol with two hydroxyl groups positioned at 120 degrees for enhanced polymer backbone stiffness. It serves primarily as a pharmaceutical intermediate for nitrate ester anti-anginal drugs and as a bio-based building block for polycarbonates and polyurethanes. Isosorbide Mononitrate commands the largest revenue share in pharmaceutical applications due to its extended-release cardiovascular efficacy. Isosorbide Ether represents the fastest-growing product type as epoxy resin formulators replace bisphenol A in high-performance coatings. Plasticizers application segment carries concentrated margin pools where food-contact compliance commands premium pricing.
EMA pharmacopoeial standards govern nitrate purity thresholds for European pharmaceutical use, while REACH restricts residual sorbitol impurities in polymer-grade material. EPA bio-preferred program procurement rules and China's GB standards for food-contact plastics shape regional demand specifications. FDA current good manufacturing practice inspections determine market access for cardiovascular API exports to the United States. Stakeholders must monitor regulatory divergence between pharmaceutical-grade and industrial-grade purity benchmarks as dual-use capacity planning becomes critical.
Market Dynamics
Pharmaceutical procurement consolidation among cardiovascular API buyers is compressing supplier margins while forcing dual-use capacity investments that bridge pharmaceutical-grade and polymer-grade purity specifications.
Growth Catalysts
- REACH bio-based polymer mandates:European manufacturers face binding renewable content thresholds in polycarbonate and polyurethane formulations, redirecting technical grade demand toward isosorbide feedstocks.
- Nitrate ester cardiovascular efficacy:Extended-release isosorbide mononitrate maintains preference among German and Chinese formulators for stable angina therapeutics despite generic competition.
- Epoxy resin formulator switching:High-performance coating manufacturers in China's coastal zones actively replace bisphenol A with isosorbide ether to meet food-contact compliance requirements.
Market Restraints
- Sorbitol feedstock volatility:Corn and wheat starch price swings directly transmit to isosorbide production economics, squeezing margin buffers for non-integrated processors.
- European supply concentration:Roquette Frères' dominance in starch-derived sorbitol creates single-source vulnerability for continental pharmaceutical-grade material.
- Catalytic dehydration yield ceilings:Current acid-catalyzed processes plateau at 70-75% conversion efficiency, capping unit economics improvements without reactor redesign.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO's accelerated API approval pathways and production-linked incentive schemes attract isosorbide nitrate investment for domestic cardiovascular drug output.
- Bioplastics-grade purity premiums:Food-contact polycarbonate specifications in Japan and South Korea reward ultra-low residual sorbitol material with 15-25% price premiums over technical grades.
- Continuous flow reactor adoption:Microchannel dehydration technology converging with real-time spectroscopic monitoring enables modular capacity scaling without batch reactor capex thresholds.
Industry Challenges
- Dual pharmacopoeial certification timelines:EMA nitrate purity validation and FDA current good manufacturing practice inspections impose 18-24 month market entry delays for new pharmaceutical-grade entrants.
- Specialized process engineering scarcity:Catalytic dehydration expertise resides with a narrow cohort of sugar alcohol chemists, constraining rapid capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Isosorbide Market |
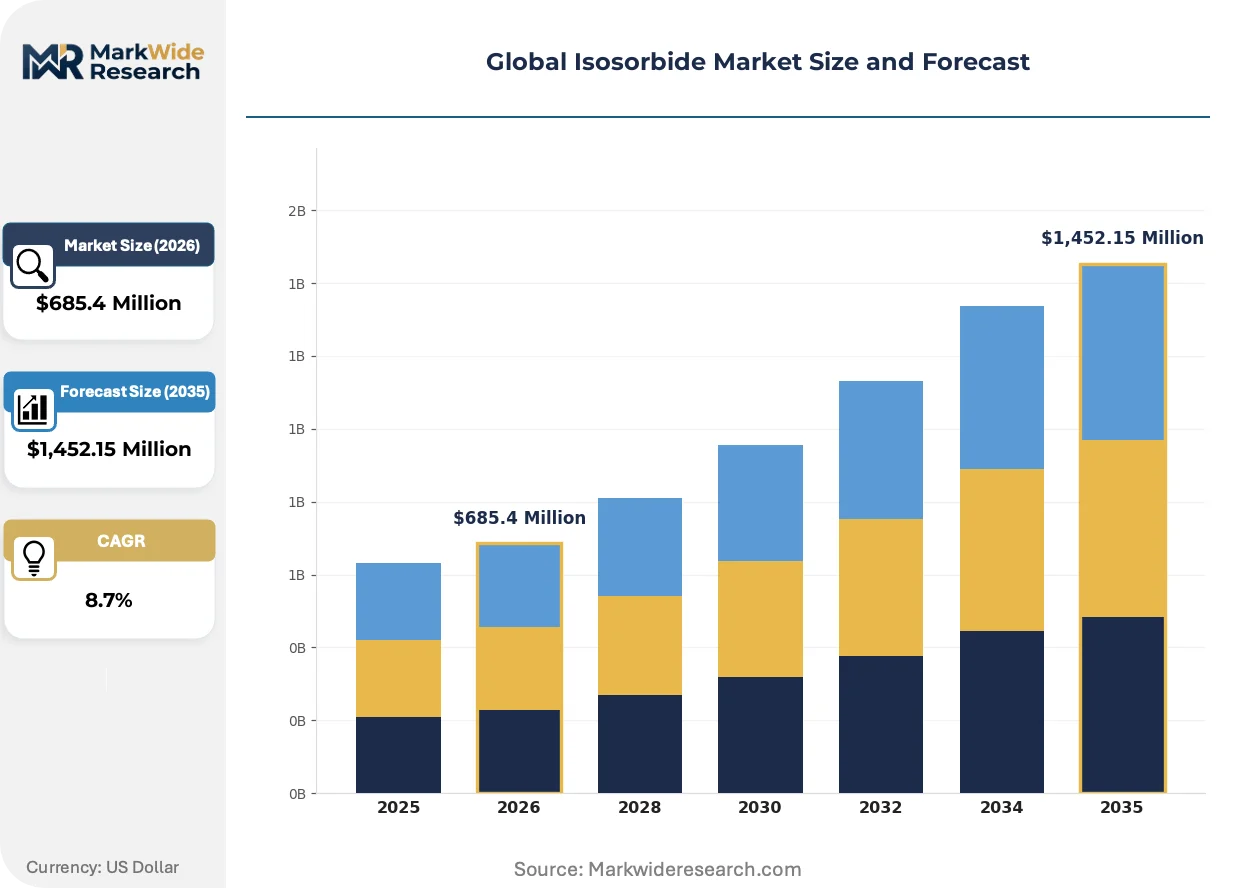
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isosorbide Dinitrate, Isosorbide Mononitrate, Isosorbide Acetate, Isosorbide Ether Application: Pharmaceuticals, Plasticizers, Resins, Solvents, Coatings End User Industry: Cardiovascular Therapeutics, Chemical Manufacturing, Polymer Production, Adhesive Formulators Packaging Type: Bulk Containers, Drum Packaging, Bottled Form, Intermediate Bulk Containers, Sachets |
| Companies Covered | Roquette Frères, Mitsubishi Chemical Corporation, Archer Daniels Midland Company, Novaphene, Samyang Innochem, Ecogreen Oleochemicals, Jinan Hongbaifeng Industry & Trade Co., Ltd., SK Chemicals, Jinan Yu Teng Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Isosorbide Market Shifts & Advancements
Continuous processing technology and regulatory convergence between pharmaceutical and food-contact standards are compressing the traditional separation between medical-grade and industrial-grade isosorbide production architectures.
Continuous flow microreactor dehydration is consolidating batch-reactor market share among European and Asian producers. Specialty chemical manufacturers in Germany's chemical corridor adopt skid-mounted systems to reduce solvent use and thermal degradation. This technology is consolidating process control advantages that previously separated large-scale starch processors from mid-cap polymer feedstock suppliers.
REACH restrictions on residual sorbitol impurities in polymer-grade material are tightening analytical thresholds for European industrial buyers. ECHA's 2023-2025 substance evaluation roadmap specifically targets bicyclic diols in food-contact applications. German polycarbonate compounders now demand sub-500ppm residual sorbitol certificates, forcing upstream dehydration technology upgrades.
Long-term offtake contracting is displacing spot market transactions among cardiovascular API buyers. German pharmaceutical formulators now secure 36-48 month supply agreements with fixed purity escalation clauses. This pattern concentrates procurement leverage with established European and Chinese suppliers possessing validated dual-grade production lines.
Global Isosorbide Market Segmentation
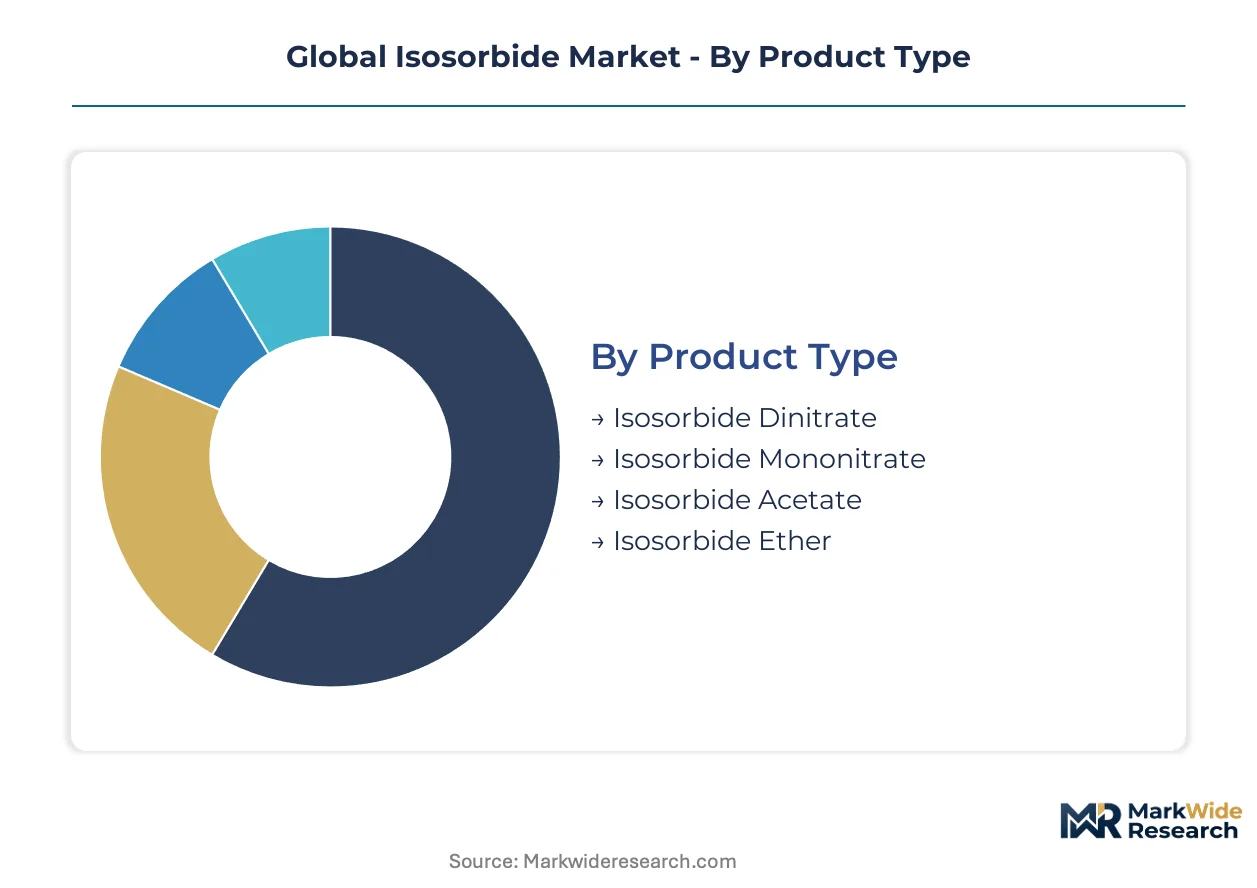
Isosorbide's dual utility across pharmaceutical nitrates and bio-based polymers creates distinct specification tiers that reshape procurement patterns. Manufacturers must navigate divergent purity benchmarks between cardiovascular API production and food-contact polymer applications.
Product Type:
Dehydration chemistry and downstream functionalization determine the technical specification ladder for sorbitol-derived bicyclic diols.
- Isosorbide Mononitrate:Single nitrate ester modification delivers extended-release cardiovascular efficacy with superior metabolic stability. German pharmaceutical formulators anchor procurement volumes for stable angina therapeutics despite generic competition intensifying.
- Isosorbide Ether:Epoxy resin formulators in China's coastal manufacturing zones actively substitute this bisphenol A replacement to satisfy GB standards for food-contact compliance in high-performance coatings.
- Isosorbide Dinitrate:Dual esterification yields rapid-onset anti-anginal compounds with shorter half-life profiles.
- Isosorbide Acetate:Esterified derivative serves niche polymer plasticizer applications requiring modified hydroxyl reactivity.
Mature deployment sits with Isosorbide Mononitrate. Newer deployment is concentrated in Isosorbide Ether.
Application:
End-use specifications split between pharmacopoeial-grade nitrates and industrial-grade polymer feedstocks with diverging margin structures.
- Pharmaceuticals:Nitrate ester APIs demand EMA-validated purity thresholds and FDA current good manufacturing practice certification. CDSCO's accelerated approval pathways in India are attracting capacity investment for domestic cardiovascular drug manufacturing.
- Plasticizers:Food-contact polycarbonate specifications in Japan and South Korea command 15-25% price premiums for ultra-low residual sorbitol material. REACH mandates on renewable content in polyurethane formulations redirect technical grade demand toward isosorbide-derived alternatives.
- Resins:Epoxy formulators leverage rigid diol backbone for enhanced thermal resistance in electronic encapsulation.
- Solvents:Bicyclic structure provides selective dissolution properties for specialty extraction processes.
- Coatings:High-performance industrial finishes utilize isosorbide ether for bisphenol A-free formulation compliance.
Established volume concentrates in Pharmaceuticals. Steepest expansion trajectory is emerging in Plasticizers.
End User Industry:
Customer technical capabilities and certification requirements stratify across medical-grade and industrial-grade demand pools.
- Cardiovascular Therapeutics:API manufacturers consolidate procurement through 36-48 month offtake contracts with fixed purity escalation clauses. Long-term contracting patterns favor established suppliers possessing validated dual-grade production lines.
- Polymer Production:Polycarbonate and polyurethane compounders in Germany's chemical corridor drive bioplastics-grade purity premiums. Sub-500ppm residual sorbitol certificates now represent standard procurement requirements.
- Chemical Manufacturing:Specialty intermediate producers utilize technical grades for downstream functionalization.
- Adhesive Formulators:Pressure-sensitive and structural adhesive manufacturers incorporate isosorbide derivatives for bio-based content claims.
Procurement leverage clusters with Cardiovascular Therapeutics. Capacity expansion is targeting Polymer Production.
Packaging Type:
Logistics economics and contamination risk govern format selection across pharmaceutical and industrial supply chains.
- Drum Packaging:Standard 200-liter steel drums dominate pharmaceutical-grade shipments requiring nitrogen blanketing and moisture protection. German and Chinese suppliers maintain dedicated drum filling lines for EMA-certified material.
- Intermediate Bulk Containers:1000-liter IBC totes reduce handling costs for polymer-grade bulk shipments to chemical manufacturing customers. Modular capacity scaling through continuous flow microreactor technology enables IBC-direct fulfillment without batch reactor infrastructure.
- Bulk Containers:Tank truck and railcar deliveries serve integrated polymer producers with captive dehydration capacity.
- Bottled Form:Laboratory and pilot-scale quantities support R&D sampling and pharmacopoeial reference standard distribution.
- Sachets:Unit-dose packaging addresses specialized pharmaceutical sampling and clinical trial material requirements.
Volume concentration favors Drum Packaging. Format innovation is advancing through Intermediate Bulk Containers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical procurement for cardiovascular APIs clusters in Germany's chemical corridor, while polymer-grade demand concentrates in China's coastal manufacturing zones and India's emerging API hubs.
Germany
EMA pharmacopoeial standards for nitrate purity drive pharmaceutical-grade procurement consolidation among cardiovascular formulators. REACH bio-based polymer mandates redirect technical grade demand toward renewable polycarbonate feedstocks. The Rhine-Ruhr chemical corridor anchors European supply security through integrated starch-derived sorbitol processing.
China
GB standards for food-contact plastics accelerate epoxy resin formulator switching from bisphenol A to isosorbide ether in high-performance coatings. NMPA oversight of cardiovascular API exports shapes quality benchmarks for domestic manufacturers. Coastal manufacturing zones in Jiangsu and Zhejiang provinces concentrate bioplastics-grade purification capacity.
India
CDSCO's accelerated API approval pathways and production-linked incentive schemes attract investment for domestic cardiovascular drug output. BIS standards for industrial chemicals create dual certification requirements for polymer feedstock suppliers. Maharashtra and Gujarat pharmaceutical clusters drive demand for nitrate ester intermediates.
United States
FDA current good manufacturing practice inspections determine market access for cardiovascular API imports. EPA bio-preferred program procurement rules shape federal purchasing specifications for bio-based polymer alternatives. Texas and Louisiana chemical manufacturing corridors evaluate isosorbide feedstocks for polycarbonate compounding.
Japan
METI policies on sustainable materials support bioplastics-grade purity premiums for food-contact polycarbonate specifications. PMDA pharmaceutical standards govern nitrate ester API quality thresholds for domestic cardiovascular therapeutics. Osaka and Nagoya industrial zones integrate isosorbide derivatives into specialty polymer formulations.
Global Isosorbide Market Competitive Landscape
European producers anchor pharmaceutical-grade supply through integrated starch processing; Asian specialists hold polymer-grade purification capabilities. The vendor base stratifies across three tiers: multinational chemical conglomerates with captive sorbitol feedstock, mid-cap bioplastics processors, and regional pharmaceutical intermediate suppliers. Strategic archetypes include backward-integrated starch processors, downstream polymer compounders, and API-focused formulators. Capacity expansion and long-term offtake contracting represent the dominant competitive moves.
Among European-based producers, Roquette Frères exemplifies the backward-integrated archetype through starch-derived sorbitol feedstock control. Mitsubishi Chemical Corporation occupies a position within the polymer-downstream tier, while SK Chemicals represents the bioplastics-grade purity specialist segment. These three entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Roquette Frères |
| Mitsubishi Chemical Corporation |
| Archer Daniels Midland Company |
| Novaphene |
| Samyang Innochem |
| Ecogreen Oleochemicals |
| Jinan Hongbaifeng Industry & Trade Co., Ltd. |
| SK Chemicals |
| Jinan Yu Teng Pharmaceutical |
| Others |
Supply & Pricing Matrix
Corn starch futures volatility cascades through isosorbide value chains, compressing margins for non-integrated processors while amplifying pricing power for sorbitol-backward-integrated suppliers serving pharmaceutical and polymer-grade tiers.
Pricing Analysis
Volume concentration in pharmaceutical-grade nitrates subsidizes margin capture in bioplastics-grade ethers. Pricing stratifies across EMA-certified pharmaceutical, food-contact polymer, and technical industrial tiers, with residual sorbitol thresholds as the primary differentiation driver. Cost compression in technical grades intensifies as Chinese epoxy formulators consolidate procurement leverage. Cardiovascular API buyers exhibit lowest price sensitivity due to pharmacopoeial compliance requirements, while coating manufacturers demonstrate highest elasticity.
Supply Chain Analysis
Sorbitol feedstock supply rests on corn and wheat starch processors in the United States, France, and China. Isosorbide production draws from acid catalysts, dehydration reactor systems, and nitric acid for esterification. Single-source vulnerability concentrates in European pharmaceutical-grade material where Roquette Frères dominates starch-derived inputs. Distribution runs through drum packaging for pharma-grade shipments and intermediate bulk containers for polymer-grade bulk deliveries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH bio-based polymer mandates and EMA pharmacopoeial standards erect compliance moats that favor capitalized incumbents with dual-grade certification infrastructure, raising effective barriers for undercapitalized entrants.
For Market Incumbents: Deploy long-term offtake contracting as the primary lever to lock in cardiovascular API volumes before generic competition intensifies. Secure captive sorbitol supply through backward integration or strategic partnerships with starch processors. CDSCO's accelerated approval pathways in India represent the critical expansion geography for nitrate ester capacity. For New Entrants and Emerging Players: Continuous flow microreactor technology offers a technology-first wedge to bypass batch reactor capex thresholds and serve mid-cap polymer compounders with modular IBC-direct fulfillment. Target India's emerging pharmaceutical clusters where production-linked incentive schemes reduce effective entry costs. Lead with bioplastics-grade purity specifications to capture Japan and South Korea food-contact premiums. For Investors and Strategic Acquirers: Distressed-cycle entries favor bioplastics-grade purification specialists in China's coastal manufacturing zones where GB standards enforcement is tightening. Five-to-ten-year viability hinges on dual-use capacity flexibility across pharmaceutical and polymer specifications. Watch ECHA's substance evaluation roadmap implementation as the signal for residual sorbitol threshold tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sorbitol Feedstock | Roquette Frères' starch processing control secures margin buffers against corn price volatility. |
| Continuous Flow Reactor Adoption | Microchannel dehydration enables German specialty producers to scale without batch infrastructure. |
| Dual-Grade Certification Investment | EMA-validated lines with sub-500ppm residual sorbitol capture polymer and pharma premiums simultaneously. |
| Long-Term Supply Agreement | 36-48 month offtake contracts with German cardiovascular formulators reduce spot market exposure. |
| India Capacity Expansion | CDSCO accelerated pathways and PLI schemes attract nitrate ester investment for domestic drug output. |
Research Methodology
Independent corroboration across dehydration technology suppliers, pharmaceutical procurement directors, and polymer compounder technical leads underwrites the qualitative findings. Primary fieldwork engaged plant managers at European starch processors, nitrate API formulators in Germany and India, and epoxy resin R&D directors in China's coastal zones. Secondary validation drew from EMA pharmacopoeial submissions, REACH registration dossiers, CDSCO approval databases, and customs trade flows. Bottom-up capacity modeling triangulated against top-down demand segmentation across pharmaceutical and polymer end-uses.
Rate-of-change decomposition across the analysis window isolates volume drivers from price-mix effects in pharmaceutical versus polymer applications. Segmentation dimensions span product type, application, end-user industry, packaging format, and regional production hub. CAGRs derive from iterative convergence between supply-side capacity buildout schedules and demand-side procurement pattern shifts. Forecast inputs incorporate sorbitol feedstock price elasticity, regulatory timeline acceleration, and continuous flow technology adoption curves.
Several conditions sit outside the modeled scope, including unforeseen REACH substance evaluation timeline shifts, corn starch supply disruptions from climate events, and breakthrough catalytic dehydration yield improvements. Forecasts reflect documented assumptions on regulatory enforcement intensity and technology diffusion rates. A small set of named triggers warrants ongoing watch: ECHA residual sorbitol threshold revisions, CDSCO inspection capacity expansion, and Chinese GB standards harmonization with food-contact specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Competitive Inhibitors Market
Additives
Phenolic Antioxidant Market
Additives
Agrochemicals Additives Market
Additives
Anti-Slip Additives Market
Additives
Global Formulation Additives Market
Additives
Dispersing Agents Market
Additives
North America Fuel Additives Market
Additives
Micronized Powder Market
Additives
Marine Fuel Additives Market
Additives
Inhibited Propylene Glycol Market
Additives
Green Chelates/Natural Chelating Agents Market
Additives
Stabilizers Market
Additives
LAMEA Driveline Additives Market
Additives
Global Anti-Fog Additives Market
Additives
Polymeric Plasticizer Market
Additives
Weighing Agents Market