
 Europe Polyvinylpyrrolidone (PVP) Market | 2026-2036
Europe Polyvinylpyrrolidone (PVP) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Polyvinylpyrrolidone (PVP) Market Foresight
Technical support and formulation advisory services is pivoting how PVP suppliers capture value beyond commodity polymer sales. BASF SE leverages its Ludwigshafen integrated site to sustain captive supply of pharmaceutical-grade Kollidon grades. Evonik Industries AG anchors high-margin copovidone production for immediate-release tablet applications. Croda International Plc competes through lipid-PVP hybrid excipient technology.
Polyvinylpyrrolidone is a water-soluble synthetic polymer synthesized via free-radical polymerization of N-vinylpyrrolidone monomer, with molecular weights spanning 2,500 to 3,000,000 g/mol. It functions primarily as a binder, disintegrant, film-former, and solubility enhancer across pharmaceutical, cosmetic, and adhesive systems. Pharmaceutical Grade dominates value generation due to stringent European Pharmacopoeia compliance burdens and qualification timelines that lock in supplier relationships. Powder formulation leads volume throughput in tablet compression lines, though Solution grades capture expanding demand in ophthalmic and parenteral drug delivery where sterile filtration compatibility matters.
EMA guidelines on excipient quality and the EU REACH Regulation govern monomer residual limits and polymer impurity profiles for PVP entering European pharmaceutical and personal care supply chains. The EU Green Deal pushes producers toward bio-based N-vinylpyrrolidone feedstocks and solvent recovery systems. Stakeholders must monitor how ECHA substance evaluation updates affect polymer registration costs and whether Germany's chemical cluster advantages persist as energy-intensive manufacturing faces carbon border adjustment pressures.
Market Dynamics
REACH substance evaluation and the EU Green Deal are compressing supplier margins while locking in qualified incumbents through multi-year pharmaceutical qualification timelines that new entrants cannot shortcut.
Growth Catalysts
- Oral Solubility Enhancement:Immediate-release tablet formulations rely on copovidone and K-grade PVPs to stabilize amorphous solid dispersions, driving volume through contract manufacturing organizations in Germany and Switzerland.
- EMA Excipient Quality Guidelines:Mandatory ICH Q3D elemental impurity testing and residual monomer limits force end-users toward pre-qualified suppliers, reducing supplier-switching behavior.
- Film-Forming Ophthalmic Demand:Eye drop and contact lens solution manufacturers specify low-molecular-weight PVP grades for mucoadhesive retention, expanding sterile solution applications.
Market Restraints
- N-Vinylpyrrolidone Feedstock Volatility:Acetylene-based and gamma-butyrolactone routes to the monomer face natural gas price swings that transmit directly to polymer contract pricing.
- Ludwigshafen Supply Concentration:A single integrated site produces the majority of European pharmaceutical-grade material, creating geographic risk exposure for continental formulators.
- Cellulosic Substitution Threat:Hydroxypropyl methylcellulose and croscarmellose sodium compete for tablet binder and disintegrant slots in cost-sensitive generic portfolios.
Strategic Opportunities
- Poland and Czech Republic CMO Expansion:Central European contract manufacturing clusters lack qualified local PVP supply, creating entry points for distributors with pharmacopoeia certification capabilities.
- Bio-Based N-Vinylpyrrolidone Feedstocks:The EU Green Deal's renewable content mandates incentivize fermentation-derived monomer pathways that qualify for green chemistry procurement preferences.
- Lipid-PVP Hybrid Excipient Convergence:Solubilization technologies combining polyvinylpyrrolidone with phospholipids address poorly soluble BCS Class II APIs in oncology and CNS pipelines.
Industry Challenges
- Pharmacopoeia Qualification Timelines:European Pharmacopoeia compliance and customer audit cycles demand 18-24 months before volume shipments commence, straining working capital.
- Energy-Intensive Solvent Recovery:Aqueous polymerization and subsequent spray drying require sustained natural gas inputs that German producers struggle to hedge against carbon border adjustment pressures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Polyvinylpyrrolidone (PVP) Market |
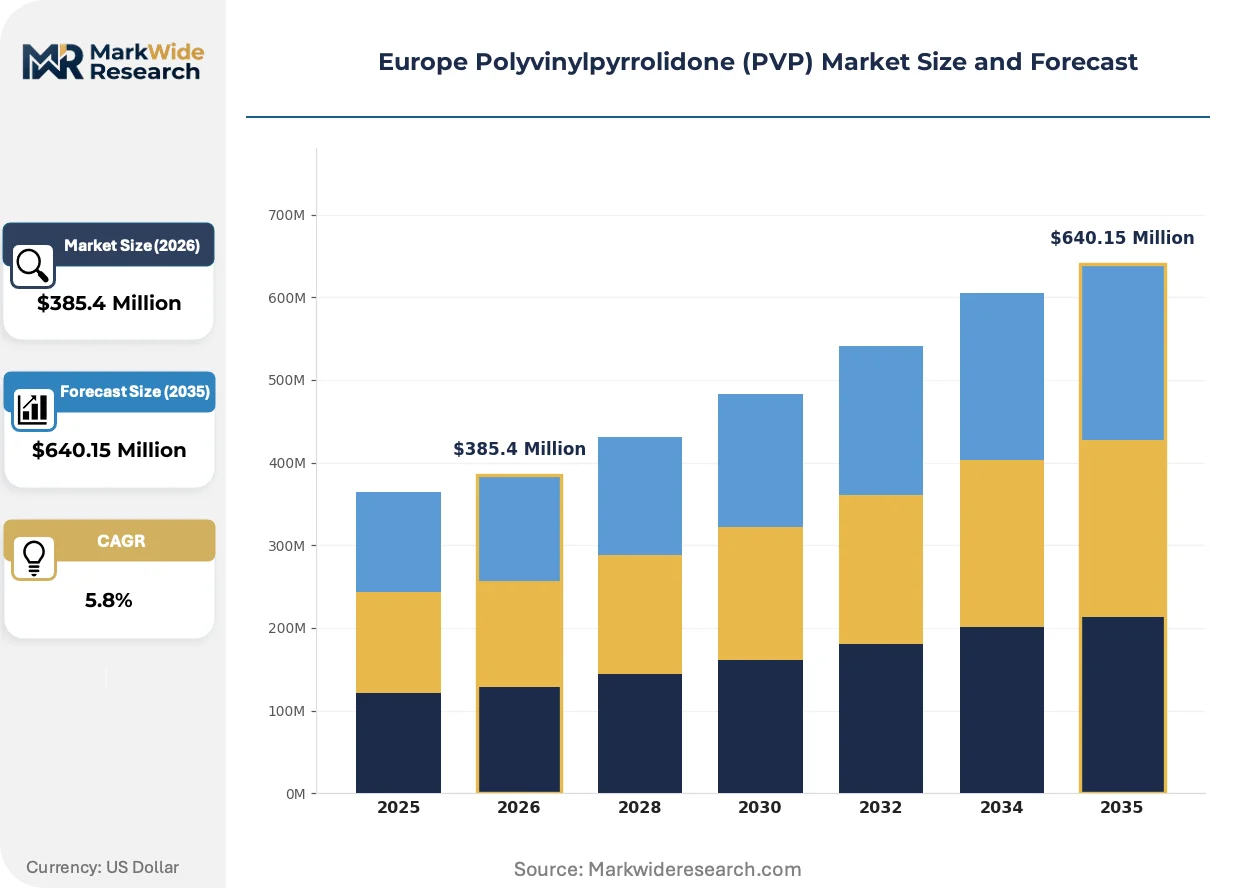
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical Grade, Cosmetic Grade, Industrial Grade, Food Grade Application: Pharmaceuticals, Personal Care, Food & Beverages, Adhesives Formulation Type: Powder, Solution, Granules, Tablets End User: Pharmaceutical Companies, Cosmetics Manufacturers, Food Processors, Research Institutions |
| Companies Covered | BASF SE, Ashland Global Holdings Inc., Evonik Industries AG, Croda International Plc, Lamberti S.p.A., J RETTENMAIER and SOHNE GmbH and Co KG, Nouryon, Kemira Oyj, Merck KGaA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Polyvinylpyrrolidone (PVP) Market Shifts & Advancements
Formulation science and regulatory chemistry are converging to redefine how excipient suppliers capture value, with purity certification and technical advisory services displacing commodity polymer sales.
Continuous manufacturing adoption in oral solid dose production is consolidating batch-to-batch PVP specification requirements. Large pharmaceutical manufacturers in Germany and Switzerland now demand real-time release testing data and reduced residual monomer windows. This specification compression favors suppliers with integrated analytical capabilities and captive monomer production.
REACH authorization candidate list expansion is tightening residual N-vinylpyrrolidone thresholds in cosmetic and pharmaceutical grades. ECHA substance evaluation updates force reformulation of personal care spray applications where inhalation exposure pathways trigger stricter classification. Suppliers with advanced chromatographic purification and validated detection methods capture specification premiums.
Buyer concentration among top-ten European pharmaceutical manufacturers has compressed tender cycles and unbundled technical support from base polymer pricing. Procurement teams now negotiate three-year framework agreements with embedded formulation advisory hours, transferring risk to suppliers while locking in volume commitments. This service bundling is most advanced in German and Swiss markets where CMO consolidation has reduced the customer base.
Europe Polyvinylpyrrolidone (PVP) Market Segmentation
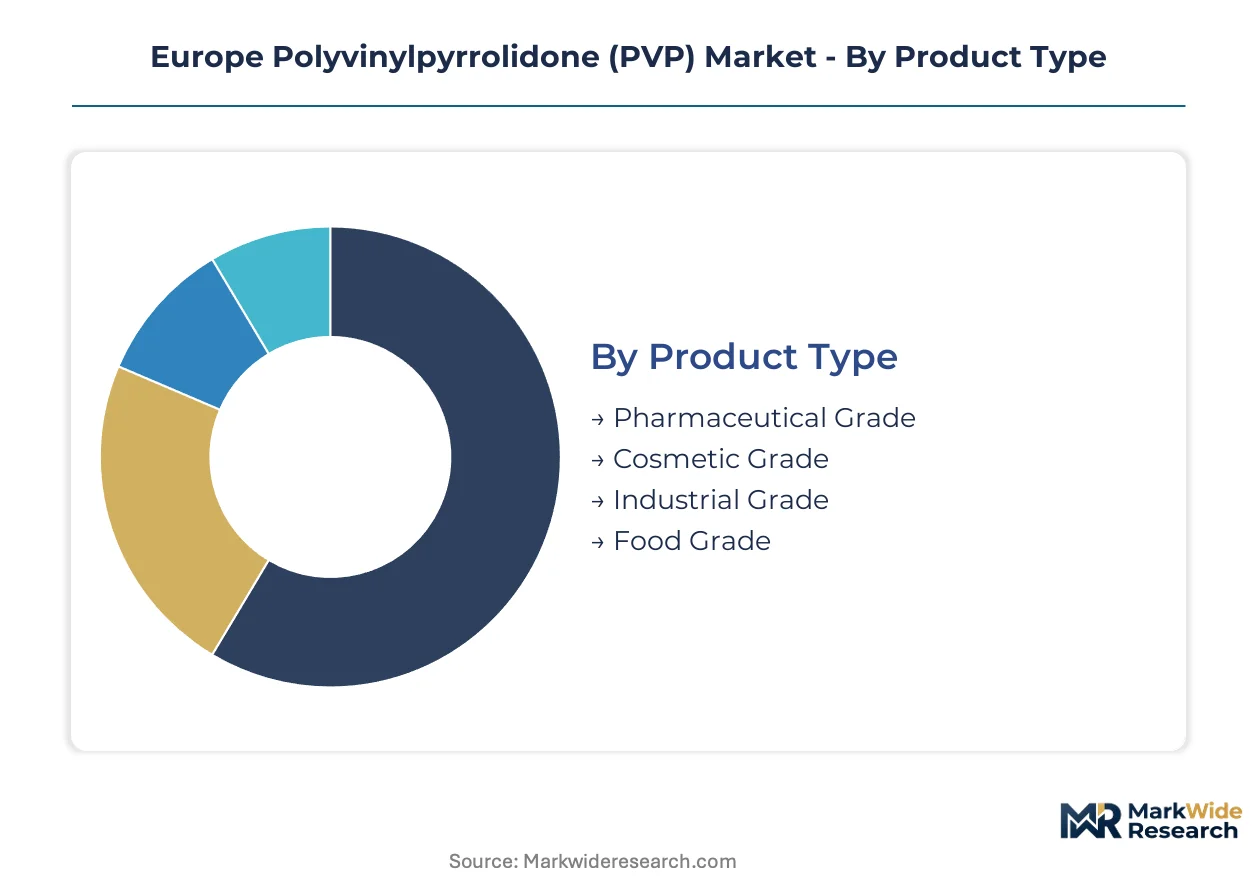
Segmentation in the European PVP market reveals how purity specifications and formulation requirements fragment supply relationships. Pharmaceutical-grade material commands qualification premiums while industrial applications compete on delivered cost per kilogram.
Product Type:
Pharmaceutical Grade captures the majority of value through European Pharmacopoeia compliance burdens, while Industrial Grade moves the largest tonnages at compressed margins.
- Pharmaceutical Grade:Manufactured to monograph standards with residual N-vinylpyrrolidone below 10 ppm and validated endotoxin limits. German contract manufacturing organizations lock in multi-year supply agreements with pre-qualified producers to satisfy EMA excipient quality guidelines.
- Cosmetic Grade:Formulated for skin and hair applications with controlled peroxide values and reduced ash content. French and Italian personal care formulators specify mid-tier grades where REACH substance evaluation on residual monomer is tightening faster than pharmaceutical standards.
- Industrial Grade:Technical polymer for adhesives and coatings with broader molecular weight distribution.
- Food Grade:Compliant with EU food additive regulations for clarifying agents and packaging adhesives.
Today's leader: Pharmaceutical Grade. Tomorrow's challenger: Cosmetic Grade.
Application:
Pharmaceuticals concentrates demand in the Rhine corridor, while Personal Care applications spread across Mediterranean cosmetic clusters.
- Pharmaceuticals:Binder, film-former, and solubility enhancer functions across immediate-release tablets, ophthalmic solutions, and parenteral formulations. Swiss and German manufacturers of amorphous solid dispersions specify copovidone grades for BCS Class II APIs.
- Personal Care:Hair fixative polymers and skin film-formers with tailored hygroscopicity profiles. Spanish and Portuguese contract manufacturers for multinational beauty brands source lower-molecular-weight K-grades for aerosol hair spray compliance with evolving inhalation exposure standards.
- Food & Beverages:Wine and beer clarification, plus edible film coatings for controlled release.
- Adhesives:Pressure-sensitive and water-remoistenable formulations for paper and packaging.
Pharmaceuticals retains the steepest expansion trajectory through oncology and CNS pipeline solubilization needs.
Formulation Type:
Powder dominates tablet compression throughput, while Solution grades capture sterile filtration premiums in parenteral and ophthalmic delivery.
- Powder:Spray-dried particulates with defined particle size distribution for direct compression and dry granulation. High-volume German generic manufacturers prefer K-30 and K-90 powders for cost-efficient binder incorporation.
- Solution:Aqueous concentrates with specified viscosity and microbial limits for sterile manufacturing. Benelux ophthalmic specialists specify low-molecular-weight solutions where endotoxin testing and sterile filtration compatibility justify specification premiums.
- Granules:Agglomerated forms for improved flow properties in high-speed tableting.
- Tablets:Pre-compressed excipient systems combining PVP with disintegrants for direct use.
Powder commands current volume leadership. Solution is gaining share fastest through biologic and ophthalmic delivery expansion.
End User:
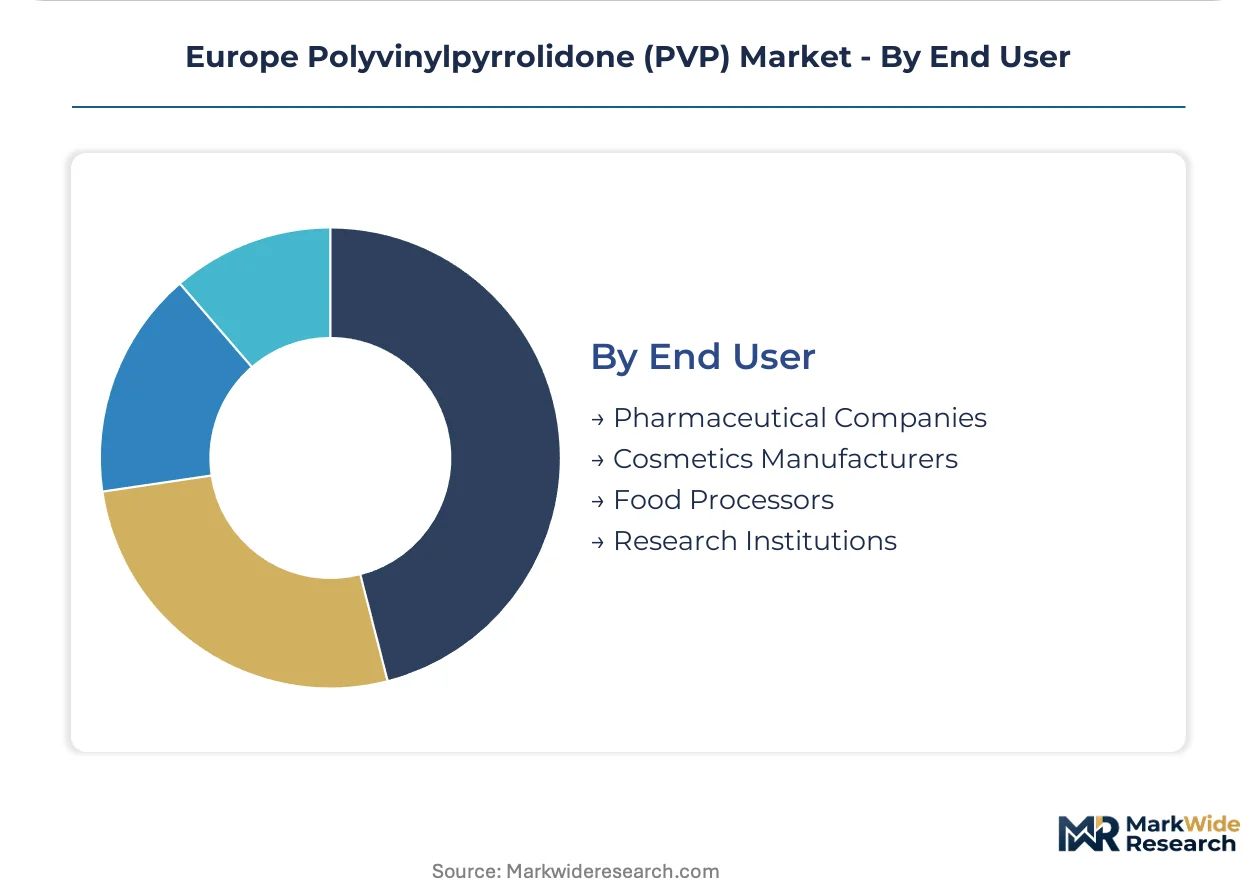
Pharmaceutical Companies consolidate procurement through framework agreements, while Cosmetics Manufacturers fragment across regional formulation houses.
- Pharmaceutical Companies:Multinational manufacturers and CMOs with captive formulation science teams. Top-ten European pharmaceutical buyers in Germany and Switzerland now unbundle technical advisory services from base polymer pricing in three-year tenders.
- Cosmetics Manufacturers:Mid-sized regional formulators and multinational beauty brand contract manufacturers. Italian and French cosmetic clusters demand flexible batch sizing with shorter lead times than pharmaceutical qualification cycles permit.
- Food Processors:Beverage clarification and edible packaging film producers with food additive regulatory compliance requirements.
- Research Institutions:Academic and contract research organizations sourcing pharmacopoeia reference materials and development-scale quantities.
Pharmaceutical Companies anchor supplier relationships. Research Institutions represent the most price-sensitive segment with minimal volume commitment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany absorbs pharmaceutical-grade volumes at scale unmatched elsewhere in Europe, while Switzerland concentrates high-value copovidone demand through specialized contract manufacturing.
Germany
Contract manufacturing organizations in Ludwigshafen and Leverkusen drive pharmaceutical binder consumption for immediate-release tablet lines. REACH substance evaluation updates force residual monomer thresholds below 10 ppm across all grades. The Rhine-Neckar chemical cluster sustains captive N-vinylpyrrolidone production with integrated solvent recovery systems.
Switzerland
Basel-based pharmaceutical manufacturers specify copovidone grades for amorphous solid dispersions targeting BCS Class II APIs. Swissmedic guidelines on excipient quality align with ICH Q3D elemental impurity standards. The Basel-Land region concentrates formulation science expertise for oncology and CNS pipeline solubilization.
France
Parisian and Lyon cosmetic formulators source mid-tier PVP grades for hair fixative and skin film-former applications. ANSM oversight on personal care spray products tightens inhalation exposure thresholds faster than pharmaceutical benchmarks. The Île-de-France region hosts multinational beauty brand contract manufacturers demanding flexible batch sizing.
Italy
Milan and Bologna personal care clusters consume low-molecular-weight K-grades for aerosol hair spray formulations. EU Green Deal renewable content mandates push producers toward bio-based feedstock certification. The Emilia-Romagna packaging belt generates industrial-grade demand for water-remoistenable adhesive applications.
Poland
Warsaw and Krakow pharmaceutical contract manufacturing expansions lack qualified local PVP supply, creating distributor entry points. ECHA registration cost burdens disadvantage smaller compounders without pharmacopoeia certification capabilities. The Central European CMO corridor attracts German and Swiss manufacturers seeking cost-advantaged tablet production.
Europe Polyvinylpyrrolidone (PVP) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade qualification timelines locking in pre-approved suppliers against commodity challengers. The vendor base concentrates around integrated chemical producers with captive monomer supply and spray-drying capacity. Three archetypes dominate: Ludwigshafen-anchored integrated majors, Swiss-German copovidone specialists, and Italian-French cosmetic-grade distributors. Competitive moves center on pharmacopoeia certification expansion and three-year framework agreements bundling technical advisory services.
Among Germany-based integrated producers, BASF SE exemplifies the captive-supply archetype through its Ludwigshafen site concentration. Evonik Industries AG and Croda International Plc occupy positions within the high-margin specialty tier, with the latter representing lipid-PVP hybrid technology convergence. These three anchors illustrate how qualification barriers and formulation advisory bundling reshape value capture beyond base polymer sales.
| Leading Market Players |
|---|
| BASF SE |
| Ashland Global Holdings Inc. |
| Evonik Industries AG |
| Croda International Plc |
| Lamberti S.p.A. |
| J RETTENMAIER and SOHNE GmbH and Co KG |
| Nouryon |
| Kemira Oyj |
| Merck KGaA |
| Others |
Supply & Pricing Matrix
Natural gas price benchmarks cascade through European PVP supply chains, compressing margins at acetylene-based monomer producers while amplifying price premiums for REACH-compliant pharmaceutical grades. Ludwigshafen-anchored integrated sites hedge feedstock exposure through captive N-vinylpyrrolidone production, leaving Central European distributors exposed to contract volatility.
Pricing Analysis
Capacity additions in Poland and the Czech Republic are reshaping price floors for mid-tier cosmetic grades, though pharmaceutical qualification barriers protect incumbent premiums. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial grades anchors differentiation to European Pharmacopoeia certification status and residual monomer thresholds. Cost compression in industrial applications intensifies as hydroxypropyl methylcellulose substitution accelerates in generic tablet portfolios. Generic manufacturers exhibit acute price sensitivity, while Swiss oncology formulators prioritize specification compliance over unit economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Antwerp consolidate bulk pharmaceutical-grade shipments before hub-and-spoke deployment to Rhine corridor CMOs. Manufacturing concentrates in Germany, with secondary technical-grade capacity in Italy and France. N-vinylpyrrolidone monomer, acetylene feedstock, and gamma-butyrolactone precursors draw from petrochemical complexes near Ludwigshafen. Single-source vulnerability at the Ludwigshafen integrated site creates continental risk exposure for sterile filtration-grade material. Distribution runs through qualified chemical distributors with pharmacopoeia certification capabilities rather than commodity polymer traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH substance evaluation milestones and EMA excipient quality guidelines continuously tighten entry barriers and consolidate procurement around pre-qualified suppliers.
For Market Incumbents: Cement multi-year framework agreements with embedded formulation advisory services to lock in German and Swiss CMO volume commitments before bio-based feedstock transitions disrupt cost structures. Deepen backward integration into solvent recovery systems to hedge carbon border adjustment exposure. Prioritize pharmacopoeia certification expansion into Poland and Czech Republic distributor networks to preempt emerging CMO demand. For New Entrants and Emerging Players: Capture white-space opportunity in Central European contract manufacturing corridors where qualified local PVP supply remains absent. Target cosmetic-grade aerosol hair spray applications in Spain and Portugal where REACH inhalation exposure thresholds are tightening faster than incumbent response cycles permit. Lead with flexible batch sizing and shortened lead times rather than commodity pricing. For Investors and Strategic Acquirers: Consolidation pressure builds where pharmacopoeia qualification timelines and ECHA registration cost burdens strand smaller compounders without certification capabilities. Five-to-ten year viability favors integrated producers with captive monomer supply and spray-drying infrastructure over pure-play distributors. Target acquisition archetype: mid-sized Italian or French cosmetic-grade specialists with established multinational beauty brand relationships. Monitor ECHA substance evaluation updates on residual N-vinylpyrrolidone thresholds as inflection signal for reformulation-driven specification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into N-Vinylpyrrolidone Monomer | Captive feedstock supply hedges natural gas price volatility for Ludwigshafen producers. |
| Pharmacopoeia Certification Expansion | Emerging CMO demand in Poland and Czech Republic lacks qualified local supply sources. |
| Bio-Based Feedstock Transition | Fermentation-derived monomer pathways qualify for EU Green Deal procurement preferences. |
| Formulation Advisory Service Bundling | Three-year tenders now unbundle technical support from base polymer pricing. |
| Solvent Recovery System Investment | Energy-intensive spray drying faces carbon border adjustment pressures. |
Research Methodology
Coverage spans Western Europe and Central Europe, with primary inputs from each regional cluster combining executive interviews with pharmaceutical procurement directors, CMO plant managers, cosmetic formulators, and chemical distribution specialists. Secondary validation draws from EMA excipient quality guidelines, ECHA substance evaluation updates, European Pharmacopoeia monographs, and customs trade data. Bottom-up volume modeling triangulates against top-down value estimates across grade tier, end-use industry, and regional production hub dimensions.
Granularity-level modeling disaggregates pharmaceutical-grade, cosmetic-grade, and industrial-grade segments with separate treatment of powder, solution, and granule formulation types. CAGRs derive from segment-level volume trajectories and value-per-kilogram compression patterns across the projection horizon. Forecast inputs incorporate REACH authorization candidate list expansion timelines, CMO capacity buildout announcements, and bio-based feedstock certification adoption curves.
Underlying measurement precision varies by segment; pharmaceutical-grade volumes carry tighter precision than cosmetic-grade estimates due to consolidated buyer concentration and framework agreement visibility. Forecasts reflect documented assumptions on regulatory timeline adherence and feedstock price trajectory stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
India Epoxy Resins Market
Polymers & Resins
Polyethylene Furanoate (PEF) Barrier Resin Market
Polymers & Resins
Hair Styling Biopolymers Market
Polymers & Resins
Polyolefin (PO) Market
Polymers & Resins
Polyvinyl Alcohol (PVA) Market
Polymers & Resins
Gel Polymer Electrolytes Market
Polymers & Resins
Photopolymers Market
Polymers & Resins
Water Soluble Polymers Market
Polymers & Resins
Polyisobutylene (PIB) Market
Polymers & Resins
Global Polyethylene Market
Polymers & Resins
Microcellular Plastics Market
Polymers & Resins
Acrylonitrile Styrene Acrylate (ASA) Market
Polymers & Resins
Global Polyphenylene Market
Polymers & Resins
Chlorinated Polyolefins Market
Polymers & Resins
Neoprene Market
Polymers & Resins
Europe Polyurethane Market