
 Polymer Modifiers Market | 2026-2036
Polymer Modifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Modifiers Market Outlook
Multi-source procurement of impact modifiers and stabilizers is decoupling from the traditional single-supplier model that dominated automotive tier-1 relationships. BASF SE leverages its Ludwigshafen integrated site to sustain captive supply of specialty plasticizers across European OEM qualification programs. Dow Inc. anchors North American demand through its Gulf Coast polyethylene compatibilizer production, while Arkema SA competes in high-performance polyamide impact modification for electric vehicle thermal management systems.
Polymer modifiers encompass chemical and physical additives that alter mechanical, thermal, or processing characteristics of base resins, including melt flow index adjustment, impact strength enhancement, and UV degradation resistance through hindered amine light stabilizer incorporation. These materials enable polypropylene and polyvinyl chloride formulations to meet specification thresholds for infrastructure piping, automotive interior panels, and flexible packaging films. Impact modifiers command premium positioning in automotive applications where dashboard and bumper regulations mandate low-temperature ductility, while plasticizers face margin compression in European construction amid phthalate substitution pressures. Stabilizers in granule form dominate bulk compounding workflows, though liquid delivery systems are gaining share in continuous extrusion operations for packaging film producers.
REACH registration requirements under ECHA govern substance authorization for plasticizers and heat stabilizers entering European polymer supply chains, while China's SAMR enforces GB standards for food-contact PVC formulations that restrict specific modifier chemistries. The US EPA evaluates phthalate alternatives under TSCA Section 5 new chemical review, creating pre-market approval bottlenecks for novel modifier introductions. Stakeholders must monitor regulatory divergence between EU F-Gas Regulation impacts on fluoropolymer processing aids and China's dual carbon goals for recycled-content mandates, as these frameworks will determine which modifier chemistries retain market access across major formulation centers.
Market Dynamics
Automotive OEM qualification programs are compressing formulation approval cycles while simultaneously demanding broader temperature performance envelopes, forcing modifier suppliers to pre-certify chemistries across multiple regulatory jurisdictions before volume commitments materialize.
Growth Catalysts
- Electric vehicle thermal management expansion:Battery pack housings and power electronics require polyamide formulations with enhanced low-temperature impact resistance, pulling specification-grade modifiers into new automotive subsystems.
- REACH authorization timelines:European substance restrictions on legacy heat stabilizers are accelerating substitution toward calcium-zinc and organic-based alternatives, opening formulation windows for compliant modifier portfolios.
- Yangtze River Delta compounding concentration:Integrated petrochemical operations in China's Jiangsu and Zhejiang provinces are achieving economies of scale in modifier-blending operations that feed regional automotive and packaging clusters.
Market Restraints
- Phthalate substitution cost premiums:Non-phthalate plasticizers command 15-40% raw material cost premiums over conventional chemistries, compressing margins in European construction applications where price sensitivity dominates tender processes.
- Specialty additive supply concentration:Hindered amine light stabilizer production concentrates among three German and Japanese chemical groups, creating qualification bottlenecks when capacity constraints emerge.
- Fluoropolymer processing aid regulatory friction:EU F-Gas Regulation restrictions on perfluorinated compounds are eliminating established processing aid chemistries before fully validated alternatives achieve commercial scale.
Strategic Opportunities
- India automotive compounding localization:PLI scheme incentives for advanced chemistry manufacturing are drawing modifier suppliers toward Gujarat and Maharashtra industrial corridors to serve domestic OEM qualification programs.
- Recycled-content mandate convergence:China's dual carbon goals and emerging EU packaging waste directives are creating specification demand for compatibilizers that restore mechanical properties to post-consumer polyolefin streams.
- Liquid delivery system channel innovation:Continuous extrusion operators in flexible packaging are bypassing traditional granule distribution to adopt direct-injection modifier systems that reduce compounding step counts.
Industry Challenges
- Cross-jurisdictional registration timelines:Simultaneous EPA TSCA Section 5, ECHA REACH, and China MEE new chemical notifications require 18-36 month pre-market investment cycles before revenue recognition.
- Polymer compounding technical integration:Modifier suppliers must embed formulation scientists within tier-1 automotive compounders to achieve real-time rheological adjustment during specification qualification.
- Legacy equipment retrofit requirements:Liquid modifier adoption in continuous extrusion demands capital expenditure on precision metering systems that many mid-scale packaging converters defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Modifiers Market |
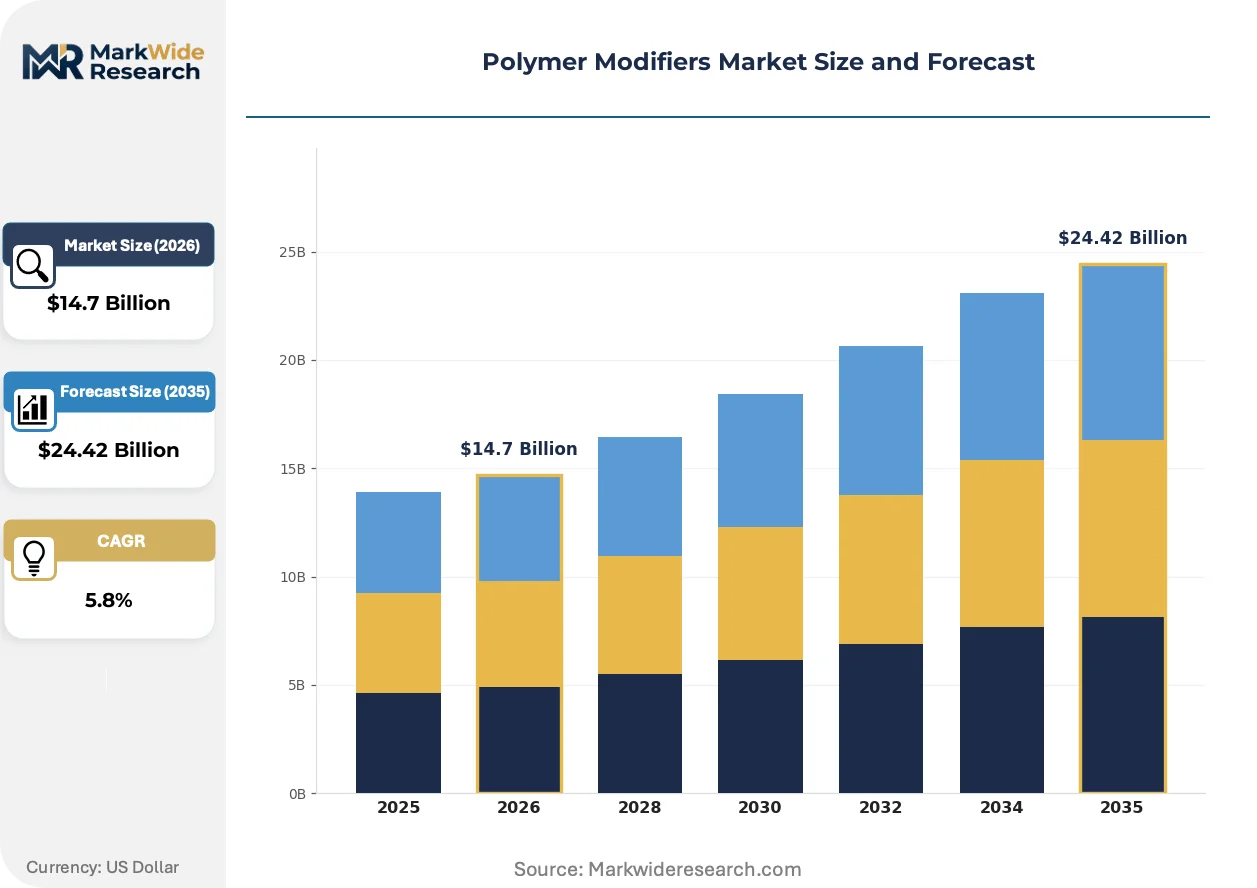
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $24.42 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasticizers, Fillers, Impact Modifiers, Stabilizers Application: Construction, Automotive, Packaging, Electronics Form: Granules, Powders, Liquids, Pellets End User: Manufacturers, Distributors, Retailers, Installers |
| Companies Covered | BASF SE, Dow Inc., Arkema SA, ExxonMobil Chemical, Milliken & Company, Clariant International Ltd, Baerlocher GmbH, AkzoNobel N.V., Valtris Specialty Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Modifiers Market Strategic Shifts
Bio-based modifier feedstocks, reactive extrusion compounding, and digital formulation platforms are converging to compress development cycles while expanding performance envelopes beyond legacy petroleum-derived chemistries.
Reactive compatibilization technology is rewriting supply chain economics for recycled polyolefin applications. Maleic anhydride grafting systems manufactured by Dow and BASF enable post-consumer streams to achieve virgin-equivalent impact strength. Automotive interior panel suppliers in Germany and the United States are qualifying these chemistries for 30-50% recycled content targets.
EU F-Gas Regulation phase-down schedules are eliminating perfluorooctanoic acid-based processing aids from fluoropolymer extrusion workflows. Compounders serving wire and cable insulation markets are reformulating with fluorine-free polymer processing aids that reduce die buildup without regulatory exposure. Italian and French cable manufacturers are driving fastest adoption amid tightening national environmental enforcement.
Specification-grade modifier procurement is consolidating toward multi-year framework agreements with embedded volume commitments. Tier-1 automotive compounders in China's Yangtze Delta are replacing spot purchasing with integrated supply partnerships that lock in qualified chemistries across model-year transitions. Japanese OEMs are extending this pattern through keiretsu-style supplier development programs.
Polymer Modifiers Market Segmentation
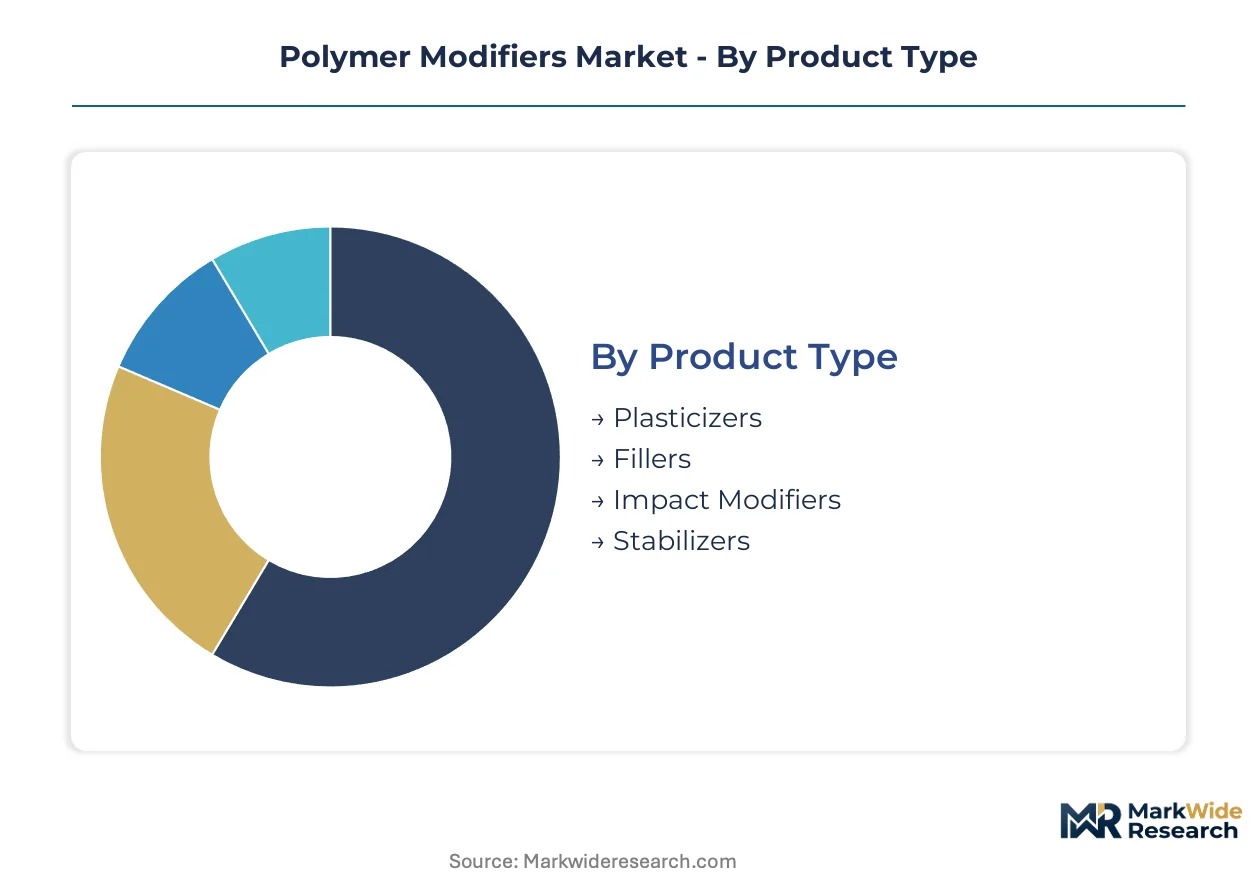
Polymer modifiers serve distinct performance requirements across formulation workflows. Segmentation reveals how technical specifications, delivery formats, and procurement channels determine supplier positioning and margin structures.
Product Type:
Volume applications concentrate in commodity plasticizers while premium capture sits with specification-grade impact modifiers serving automotive qualification programs.
- Plasticizers:Phthalate and non-phthalate chemistries adjust flexibility and processability in PVC formulations. Demand concentrates in European construction where ECHA REACH restrictions on legacy chemistries are accelerating calcium-zinc and bio-based substitutions amid tender price sensitivity.
- Impact Modifiers:Core-shell acrylic and MBS elastomers enhance low-temperature ductility in polypropylene and polyamide systems. Specification-grade purchases are expanding among Asia-Pacific automotive OEMs for battery pack housings and bumper applications requiring crash-performance certification.
- Fillers:Calcium carbonate and talc reduce material cost while modifying stiffness and dimensional stability.
- Stabilizers:Hindered amine light stabilizers and heat stabilizers prevent UV and thermal degradation in outdoor and high-temperature applications.
Mature deployment sits with plasticizers in bulk construction compounding. Newer deployment is concentrated in impact modifiers for electric vehicle thermal management systems.
Application:
Automotive qualification timelines stretch 18-36 months while packaging converters demand immediate formulation flexibility.
- Automotive:Interior panels, bumpers, and under-hood components require modifiers meeting OEM specification thresholds for low-temperature impact and thermal aging. China's Yangtze River Delta compounding cluster anchors regional demand through integrated supply partnerships with tier-1 suppliers.
- Construction:PVC piping, siding, and flooring formulations consume plasticizers and heat stabilizers at volume scale. European phthalate substitution pressures compress margins despite regulatory mandates driving compliant chemistry adoption.
- Packaging:Flexible films and rigid containers utilize slip agents, anti-block additives, and compatibilizers for recycled content streams.
- Electronics:Wire and cable insulation, connectors, and housings require flame-retardant and processing aid modifiers meeting UL and IEC standards.
Specification-grade revenue concentrates in automotive. Volume throughput leadership belongs to construction applications.
Form:
Granule dominance in batch compounding confronts liquid system encroachment in continuous extrusion workflows.
- Granules:Standardized pelletized delivery enables precise metering in twin-screw extrusion and batch mixing operations. Bulk compounders in China's petrochemical corridor prefer this format for inventory handling efficiency.
- Liquids:Direct-injection delivery systems eliminate pre-compounding steps in flexible packaging film production. Mid-scale converters defer capital expenditure on precision metering equipment, slowing penetration.
- Powders:Fine-particle dispersion serves specialty masterbatch and dry-blend PVC formulations.
- Pellets:Larger-diameter formats reduce dust generation in automated handling systems for high-volume operations.
Established infrastructure supports granule deployment. Liquid adoption is climbing the fastest among continuous extrusion operators seeking step-count reduction.
End User:
Manufacturer captive compounding capabilities are reshaping distributor relevance across regional supply chains.
- Manufacturers:Integrated polymer producers and tier-1 compounders source modifiers directly for captive formulation operations. BASF's Ludwigshafen site exemplifies backward integration into specialty plasticizer production.
- Distributors:Regional chemical distributors serve mid-scale converters lacking volume for direct supplier contracts. Technical service capabilities differentiate positioning in fragmented European markets.
- Retailers:Limited role in bulk modifier distribution; concentrate on small-volume specialty additives for repair and maintenance segments.
- Installers:End-use contractors in construction specify finished polymer products rather than raw modifiers.
Direct procurement dominates high-volume automotive and packaging channels. Distributor-mediated supply persists in construction and specialty electronics applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability in the US Gulf Coast and integrated refining corridors across Germany's Rhine-Ruhr region anchor modifier production economics. These localities sustain backward-integrated supply chains that feed compounding operations serving automotive and packaging demand centers.
United States
Electric vehicle battery pack manufacturing in Michigan and Ohio pulls specification-grade polyamide impact modifiers into new thermal management applications. EPA TSCA Section 5 review timelines for phthalate alternatives create pre-market bottlenecks that favor incumbents with existing chemical registrations. The Gulf Coast petrochemical corridor around Houston sustains integrated polyethylene compatibilizer production feeding domestic automotive tier-1 compounders.
Germany
Automotive OEM qualification programs for interior panels and bumpers demand low-temperature ductility certification stretching 18-36 months. ECHA REACH authorization timelines for legacy heat stabilizers accelerate substitution toward calcium-zinc and organic-based alternatives. The Ludwigshafen chemical complex anchors captive specialty plasticizer supply across European OEM programs through backward-integrated operations.
China
Integrated polymer compounding in Jiangsu and Zhejiang provinces achieves economies of scale in modifier-blending operations. SAMR-enforced GB standards for food-contact PVC formulations restrict specific modifier chemistries and redirect formulation strategies. The Yangtze River Delta petrochemical cluster feeds regional automotive and packaging demand through direct supply partnerships replacing spot purchasing.
Japan
Keiretsu-style supplier development programs extend multi-year framework agreements with embedded volume commitments across model-year transitions. METI oversight of chemical substance management aligns modifier registration with industrial policy objectives. Automotive compounders in the Nagoya industrial corridor qualify specification-grade impact modifiers for hybrid and electric vehicle platforms.
India
PLI scheme incentives for advanced chemistry manufacturing draw modifier suppliers toward Gujarat and Maharashtra industrial corridors. BIS certification requirements for construction-grade PVC formulations create compliance barriers for imported chemistries. Domestic OEM qualification programs in the Chennai-Bangalore automotive belt are compressing formulation approval cycles while demanding broader temperature performance envelopes.
Polymer Modifiers Market Competitive Environment
Strategic partnerships dominate the current landscape as modifier suppliers embed formulation scientists within tier-1 automotive compounders to achieve real-time rheological adjustment. The vendor base clusters around three archetypes: integrated petrochemical majors with captive modifier production, specialty chemical houses focused on specification-grade impact modification, and regional compounders serving construction and packaging volume segments. M&A activity and capacity expansion in Asia-Pacific represent the dominant competitive vectors as suppliers position for automotive qualification windows and recycled-content mandate convergence.
Within the integrated petrochemical tier, BASF SE and Dow Inc. exemplify backward-integrated positioning through Ludwigshafen and Gulf Coast production sites respectively. Arkema SA occupies a position among specialty chemical houses targeting high-performance polyamide applications. These three anchors demonstrate how geographic production concentration and qualification program embedding determine competitive access to automotive specification revenue.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Arkema SA |
| ExxonMobil Chemical |
| Milliken & Company |
| Clariant International Ltd |
| Baerlocher GmbH |
| AkzoNobel N.V. |
| Valtris Specialty Chemicals |
| Others |
Value Chain & Pricing Dynamics
Phthalate feedstock costs cascade through three distinct pricing tiers for plasticizer formulations, with non-phthalate alternatives commanding 15-40% raw material premiums that compress margins for European construction compounders while specification-grade impact modifiers retain pricing power through automotive OEM qualification lock-ins.
Pricing Analysis
Service bundling separates specification-grade modifier supply from commodity plasticizer transactions, with technical formulation support and real-time rheological adjustment embedded in multi-year framework agreements for automotive tier-1 compounders. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment scale, with REACH-compliant calcium-zinc stabilizers occupying the premium tier. Pricing pressure stems from phthalate substitution mandates in European construction, where tender price sensitivity dominates procurement decisions. Mid-scale packaging converters exhibit highest price sensitivity due to capital constraints on liquid delivery system retrofits, while integrated automotive compounders in China's Yangtze Delta demonstrate lowest sensitivity through captive supply partnerships.
Supply Chain Analysis
Specialty additive production rests on concentrated German and Japanese chemical groups for hindered amine light stabilizers, with core-shell acrylic and MBS elastomer manufacturing anchored in the US Gulf Coast, Germany's Rhine-Ruhr corridor, and China's Jiangsu province. Crude oil derivatives, maleic anhydride, and calcium-zinc intermediates constitute critical input dependencies. Single-source vulnerability concentrates in fluoropolymer processing aids facing EU F-Gas Regulation phase-down before validated alternatives achieve commercial scale. Distribution runs through direct procurement channels for high-volume automotive and packaging manufacturers, with regional chemical distributors serving fragmented construction and specialty electronics segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around qualification program embedding and regulatory compliance capabilities, with cross-jurisdictional registration timelines forcing sub-scale modifiers toward exit or acquisition.
For Market Incumbents: Deepen backward integration into captive specialty plasticizer production at integrated sites like Ludwigshafen or the Gulf Coast to defend margin position against phthalate substitution cost compression. Expand technical service teams embedded within tier-1 automotive compounders to accelerate real-time formulation adjustment during specification qualification windows, neutralizing emerging specialty chemical houses targeting high-performance polyamide applications. For New Entrants and Emerging Players: Regional chemical distributors in fragmented European construction markets offer the most penetrable channel partnership for non-phthalate plasticizer portfolios facing tender price sensitivity. Target India's Gujarat and Maharashtra industrial corridors where PLI scheme incentives for advanced chemistry manufacturing are drawing supply localization ahead of domestic OEM qualification program expansion. Lead with technical service differentiation rather than price competition to bypass established granule distribution relationships. For Investors and Strategic Acquirers: REACH authorization timeline acceleration for legacy heat stabilizers is the leading indicator that compliant calcium-zinc and organic-based alternative portfolios will command acquisition premiums. Five-to-ten year viability favors specialty chemical houses with specification-grade impact modifier capabilities in electric vehicle thermal management applications. Watch for tier-1 automotive compounders in China's Yangtze Delta replacing spot purchasing with integrated supply partnerships as the signal for downstream consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Plasticizer Production | BASF's Ludwigshafen site exemplifies how captive supply sustains margin defense across European OEM programs. |
| Embedded Technical Service Expansion | Modifier suppliers deploying formulation scientists within tier-1 compounders achieve faster specification qualification cycles. |
| Non-Phthalate Portfolio Substitution | Calcium-zinc and bio-based alternatives capture share as ECHA REACH restrictions eliminate legacy heat stabilizer chemistries. |
| India Manufacturing Localization | PLI scheme incentives in Gujarat and Maharashtra corridors attract supply positioning ahead of domestic automotive demand expansion. |
| Recycled-Content Compatibilizer Development | Maleic anhydride grafting systems from Dow and BASF enable post-consumer polyolefin streams to achieve virgin-equivalent impact strength. |
Study Parameters
Independent corroboration across regulatory filings with ECHA and EPA, customs and trade data from major petrochemical exporting regions, and SEC 10-K disclosures from integrated chemical majors underwrites the qualitative findings. Primary interviews with plant managers at compounding facilities, procurement leads at automotive tier-1 suppliers, distribution channel partners in European construction markets, and technical R&D directors at specialty additive producers combined with secondary validation from ACC and Cefic industry reports. Bottom-up volume estimates from application-level consumption patterns triangulate against top-down production capacity assessments across the Yangtze River Delta, US Gulf Coast, and Rhine-Ruhr corridors.
Rate-of-change decomposition separates volume growth from value expansion across product type, application, form, and end-user segments over the projection horizon. Segmentation dimensions modeled include plasticizer versus impact modifier versus stabilizer chemistry tiers, automotive versus construction versus packaging end-use industries, granule versus liquid versus powder delivery formats, and direct manufacturer procurement versus distributor-mediated supply channels. CAGRs derive from regression analysis against macroeconomic indicators and industry-specific demand drivers including electric vehicle battery pack production expansion and recycled-content mandate implementation.
Caveats apply where regulatory divergence between EU F-Gas Regulation phase-down schedules and China's dual carbon goals could materially shift the outlook for specific modifier chemistries. Forecasts reflect assumptions about automotive OEM qualification timeline compression and phthalate substitution cost trajectory that warrant revision if REACH authorization accelerates or construction tender price sensitivity intensifies. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Nylon Resins Market
Polymers & Resins
Polyolefin (PO) Market
Polymers & Resins
Heat Resistant Polymer Market
Polymers & Resins
North America Epoxy Resins Market
Polymers & Resins
Polystyrene (PS) and Expanded Polystyrene (EPS) Market
Polymers & Resins
Middle East Polyamide Market
Polymers & Resins
Polyvinyl Chloride Resins Market
Polymers & Resins
Europe Superabsorbent Polymers Market
Polymers & Resins
Hydrophobic Interaction Chromatography Resins Market
Polymers & Resins
Polymer Alloys Market
Polymers & Resins
Hybrid Polymer Market
Polymers & Resins
Ethylene Copolymer Market
Polymers & Resins
Global Polyethylene Glycol Market
Polymers & Resins
Asia-Pacific Geopolymer Market
Polymers & Resins
Acrylonitrile Styrene Acrylate (ASA) Market
Polymers & Resins
Polytetramethylene Ether Glycol (PTMEG) Market