
 Isoprene Rubber (IR) Latex Market | 2026-2036
Isoprene Rubber (IR) Latex Market Size, Share, and Industry Trends Forecast 2026-2036
Isoprene Rubber (IR) Latex Market Intelligence
Medical device makers is rotating share toward synthetic IR latex formulations as natural latex allergy concerns reshape procurement criteria across hospital networks. Kraton Corporation leverages its solution polymerization expertise to supply high-clarity grades for surgical applications. Kuraray Co., Ltd. anchors Asian supply chains through captive isoprene monomer sourcing. JSR Corporation differentiates via emulsion technology optimized for thin-wall glove production.
Isoprene Rubber (IR) Latex is an aqueous dispersion of polyisoprene particles, typically containing 40-60% solids by weight, produced through emulsion or solution polymerization of isoprene monomer. It serves as a synthetic substitute for natural rubber latex in applications requiring protein-free, hypoallergenic elastomeric films. Synthetic IR latex commands premium positioning in medical supplies due to consistent batch purity and absence of allergenic proteins. Adhesives and coatings represent adjacent growth vectors where emulsion IR latex displaces solvent-based systems under VOC regulations. Bulk containers and drums constitute the dominant packaging configuration, reflecting downstream manufacturers' consumption scale and just-in-time logistics requirements.
FDA device regulations and EU MDR conformity assessments shape product qualification timelines for latex entering clinical supply chains. EPA and REACH frameworks restrict residual monomer thresholds and classify isoprene handling under industrial emissions controls. Stakeholders must monitor evolving biocompatibility testing protocols and regional chemical registration requirements to sustain market access across regulated end uses.
Market Dynamics
Medical glove manufacturers in Malaysia are consolidating synthetic IR latex procurement around vertically integrated suppliers as EU MDR biocompatibility testing timelines compress qualification windows for new material entrants.
Growth Catalysts
- EU MDR Purity Mandates:Stricter residual protein thresholds for clinical latex are redirecting hospital procurement toward synthetic IR formulations that eliminate allergen risks entirely.
- Emulsion Polymerization Advances:Thin-wall glove production lines in Southeast Asia are achieving higher yields per batch through particle size optimization in waterborne IR latex systems.
- Malaysian Manufacturing Clusters:Concentrated glove production zones around Kuala Lumpur and Penang generate localized demand density that attracts specialized chemical distributors.
Market Restraints
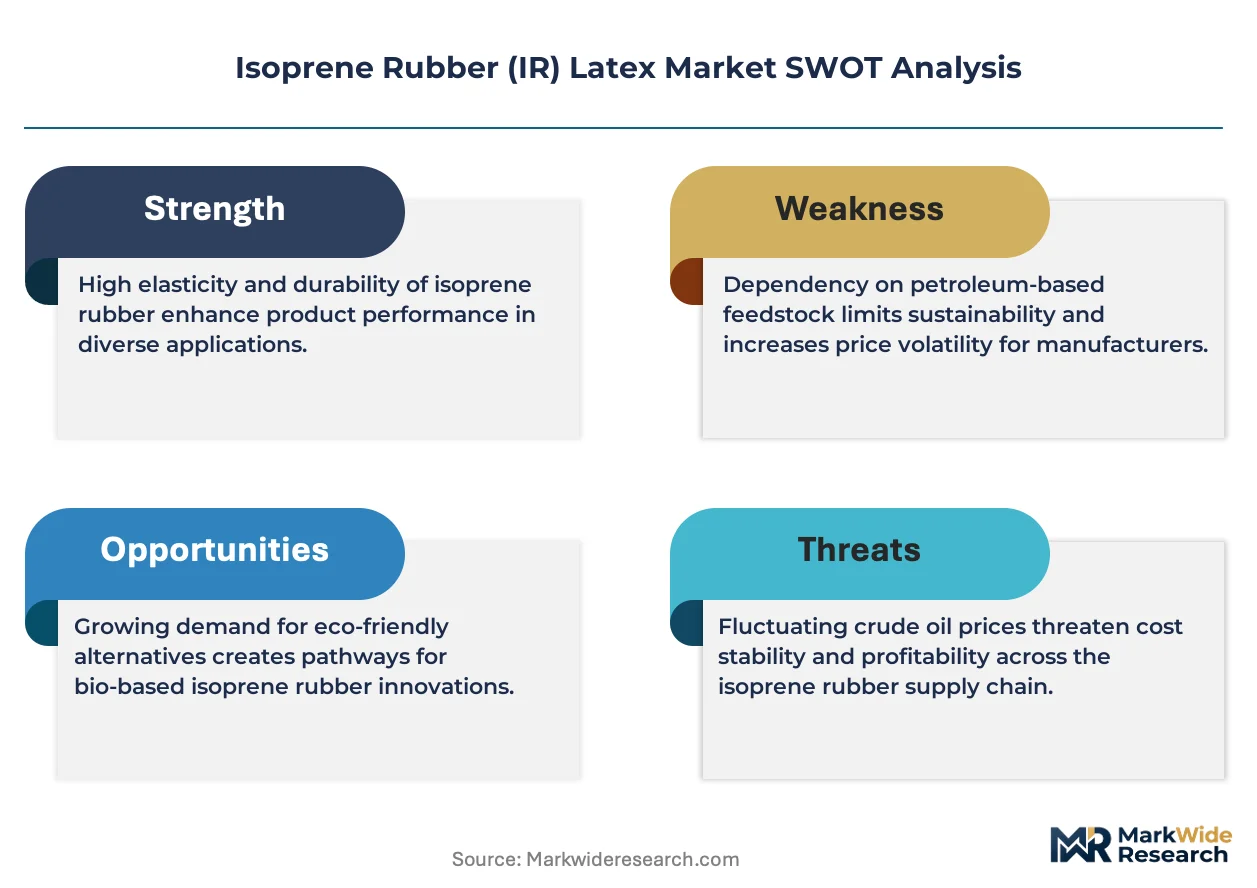
- Isoprene Monomer Volatility:Crude oil-linked feedstock pricing creates margin compression for non-integrated latex producers without captive naphtha cracking capacity.
- REACH Registration Burden:ECHA substance volume thresholds impose documentation costs that disproportionately burden smaller emulsion compounders seeking European market access.
- Natural Latex Substitution Resistance:Established glove makers with sunk costs in Hevea brasiliensis supply chains delay synthetic conversion despite allergy liability exposure.
Strategic Opportunities
- Adhesives Formulation Pivot:VOC regulations in industrial coatings are opening formulation slots where waterborne IR latex replaces solvent-based neoprene and SBR binders.
- Condom Manufacturing Diversification:Thai and Japanese personal health product makers are trialing synthetic IR for premium non-allergenic product lines.
- EPA Emission Controls:Stricter isoprene handling standards are advantaging producers with closed-loop polymerization systems and vapor recovery infrastructure.
Industry Challenges
- Biocompatibility Certification Timelines:ISO 10993 cytotoxicity and sensitization testing protocols extend product qualification cycles by 18-24 months for new latex grades.
- Specialized Polymer Chemistry Talent:Emulsion stability formulation expertise resides with a narrow cohort of aging technical specialists in Japan and Germany.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isoprene Rubber (IR) Latex Market |
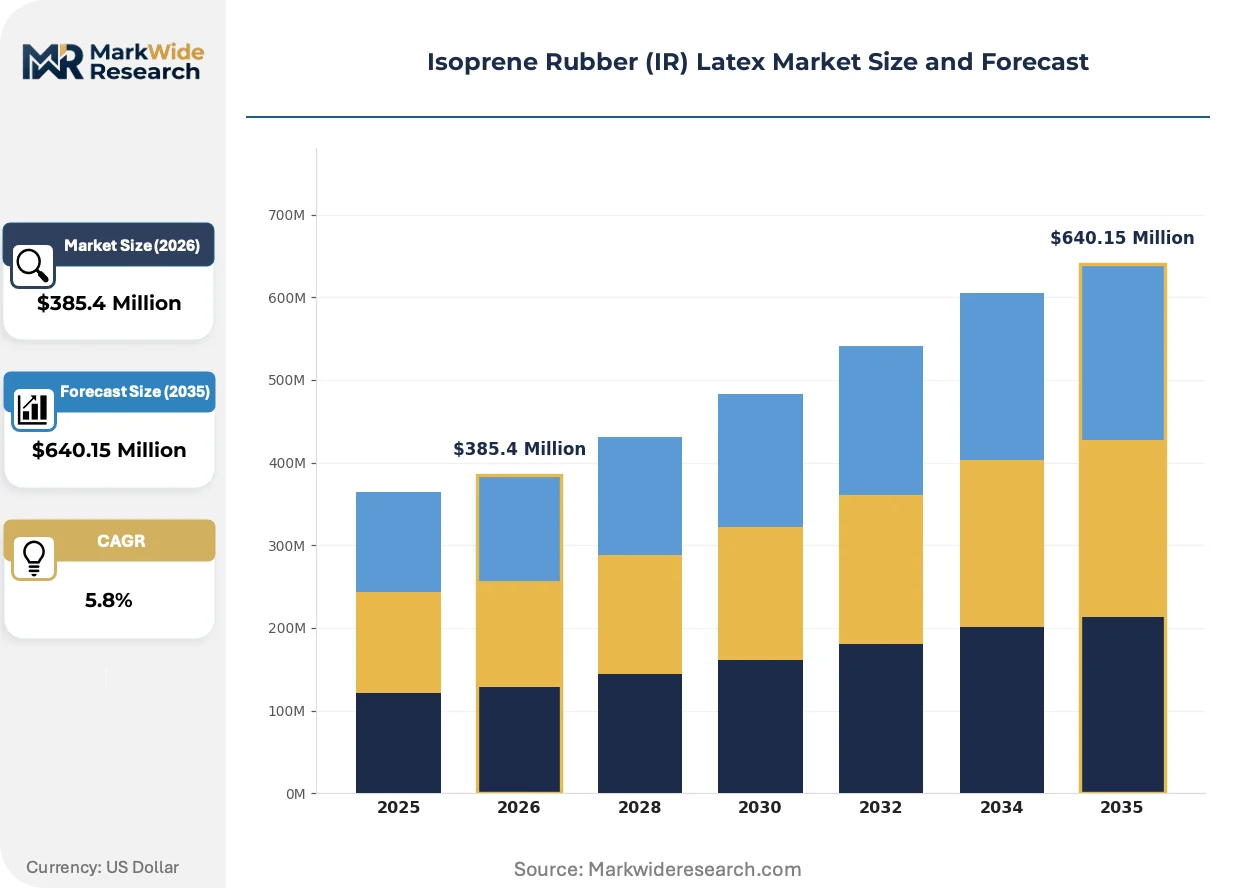
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural IR Latex, Synthetic IR Latex, Emulsion IR Latex, Solution IR Latex Application: Adhesives, Coatings, Foam Products, Medical Supplies, Textile Finishing End User: Footwear Manufacturers, Medical Device Makers, Textile Producers, Adhesive Producers, Foam Fabricators Packaging Type: Bulk Containers, Drums, Totes, Intermediate Bulk Containers |
| Companies Covered | Top Glove Corp Bhd, Kraton Corporation, Kuraray Co., Ltd., Ansell Limited, PJSC SIBUR Holding, JSR Corporation, Hartalega Holdings Bhd, Kossan Rubber Industries Bhd, Zeon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isoprene Rubber (IR) Latex Market Strategic Shifts & Innovations
Waterborne polymerization systems are displacing legacy solvent-based production across elastomer film applications as regulatory pressure and end-use safety requirements converge.
Solution polymerization with metallocene catalysts is displacing Ziegler-Natta systems for high-clarity surgical glove grades. Malaysian and Thai glove makers are retrofitting dipping lines to accommodate these narrower molecular weight distributions. The structural consequence is compressing qualification timelines for mid-tier emulsion suppliers unable to match batch-to-batch consistency.
REACH Annex XVII restrictions on residual monomer content are forcing reformulation of IR latex destined for prolonged skin contact applications. ECHA classification of isoprene as a skin sensitizer above threshold limits has triggered migration toward post-polymerization stripping technologies. German and French medical device distributors now require third-party residual monomer certificates for all imported latex batches.
Hospital procurement departments are consolidating vendor panels around dual-source synthetic latex suppliers with documented FDA master files. Group purchasing organizations in the United States are unbundling glove contracts from broader medical supply agreements to negotiate direct polymer pricing. This concentration is most visible in California and Texas health systems where allergy incident liability has driven zero-natural-latex policies.
Isoprene Rubber (IR) Latex Market Segmentation
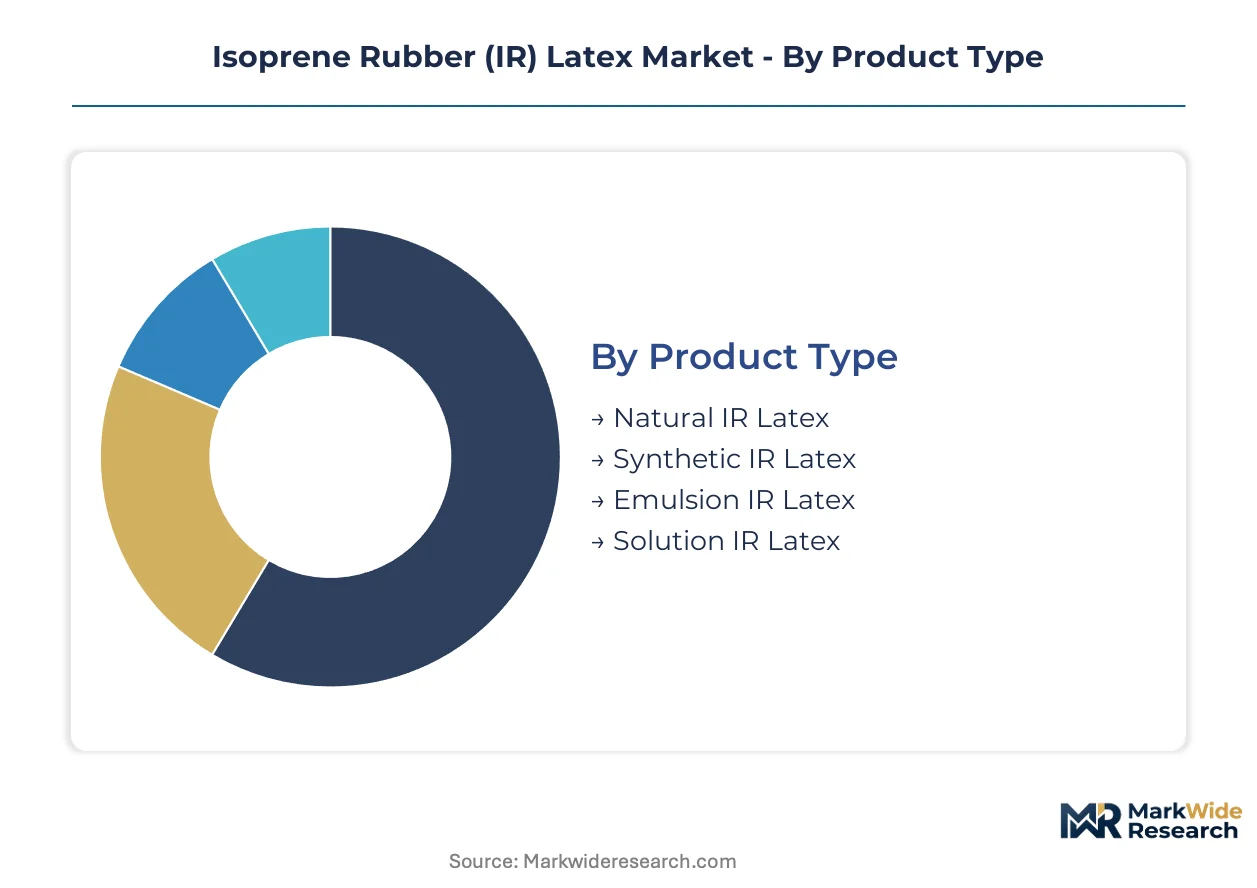
Segmentation in the IR latex market tracks how formulation chemistry, end-use specifications, and logistics configurations split procurement flows across distinct channel systems. Each dimension carries implications for qualification timelines, pricing tiers, and supplier relationship structures.
Product Type:
Channel mix varies sharply by polymerization route, with emulsion grades flowing through distributors serving high-volume glove makers while solution grades move via direct technical sales to surgical device manufacturers.
- Synthetic IR Latex:Protein-free polyisoprene dispersion manufactured via emulsion or solution routes. Malaysian glove manufacturers concentrate procurement here as EU MDR biocompatibility mandates eliminate natural latex from hospital networks.
- Emulsion IR Latex:Waterborne particle system with 40-60% solids content optimized for thin-wall dipping processes. Thai and Indonesian producers are retrofitting lines to accommodate these formulations as VOC regulations displace solvent-based alternatives.
- Natural IR Latex:Hevea brasiliensis-derived material with inherent allergenic proteins. Demand is retreating to specialty adhesive applications where synthetic substitution economics remain unfavorable.
- Solution IR Latex:Solvent-based system yielding high-clarity films for optical-grade surgical applications. Japanese and German device makers specify these grades for procedures requiring visual precision.
Synthetic IR latex dominates installed base. Emulsion IR latex is where expansion concentrates.
Application:
Cost tier stratification separates medical-grade formulations commanding qualification-intensive sales cycles from industrial applications competing on throughput metrics.
- Medical Supplies:Examination and surgical gloves, catheters, and wound care products requiring ISO 10993 biocompatibility certification. FDA master file documentation and EU MDR conformity assessments extend supplier onboarding to 18-24 months.
- Adhesives:Pressure-sensitive and structural bonding formulations where waterborne IR latex displaces solvent-based neoprene under EPA and REACH emission controls. Automotive and construction end-users drive specification here.
- Coatings:Protective and decorative films for textile and industrial substrates. Formulators value IR latex for elasticity retention across temperature cycling.
- Foam Products:Cushioning and insulation materials leveraging polyisoprene resilience. Mattress and automotive seating producers specify density and compression set characteristics.
- Textile Finishing:Fabric coatings imparting water resistance and hand modification. Mills in Bangladesh and Vietnam are trialing IR latex as silicone alternatives face cost pressure.
Medical supplies command premium positioning. Adhesives are climbing the fastest as regulatory pressure accelerates waterborne substitution.
End User:
Customer type determines contract structure, with medical device makers negotiating multi-year supply agreements while foam fabricators purchase on spot markets.
- Medical Device Makers:Glove, condom, and catheter manufacturers requiring batch-to-batch consistency and documented purity. Malaysian clusters around Kuala Lumpur and Penang generate concentrated demand density.
- Adhesive Producers:Formulators blending IR latex with tackifiers and crosslinkers for tape and label applications. These customers prioritize solids content stability and low coagulum levels.
- Footwear Manufacturers:Sole and midsole producers in Vietnam and Indonesia using IR latex for elasticity and abrasion resistance. Specifications center on viscosity and cure characteristics.
- Foam Fabricators:Cushion and insulation molders purchasing on volume metrics with limited technical service requirements. Price sensitivity is highest in this tier.
- Textile Producers:Finishing mills applying coatings for performance apparel and technical fabrics. These users evaluate hand feel and durability under laundering.
Medical device makers anchor long-term contracting. Adhesive producers are where formulation flexibility creates switching opportunities.
Packaging Type:
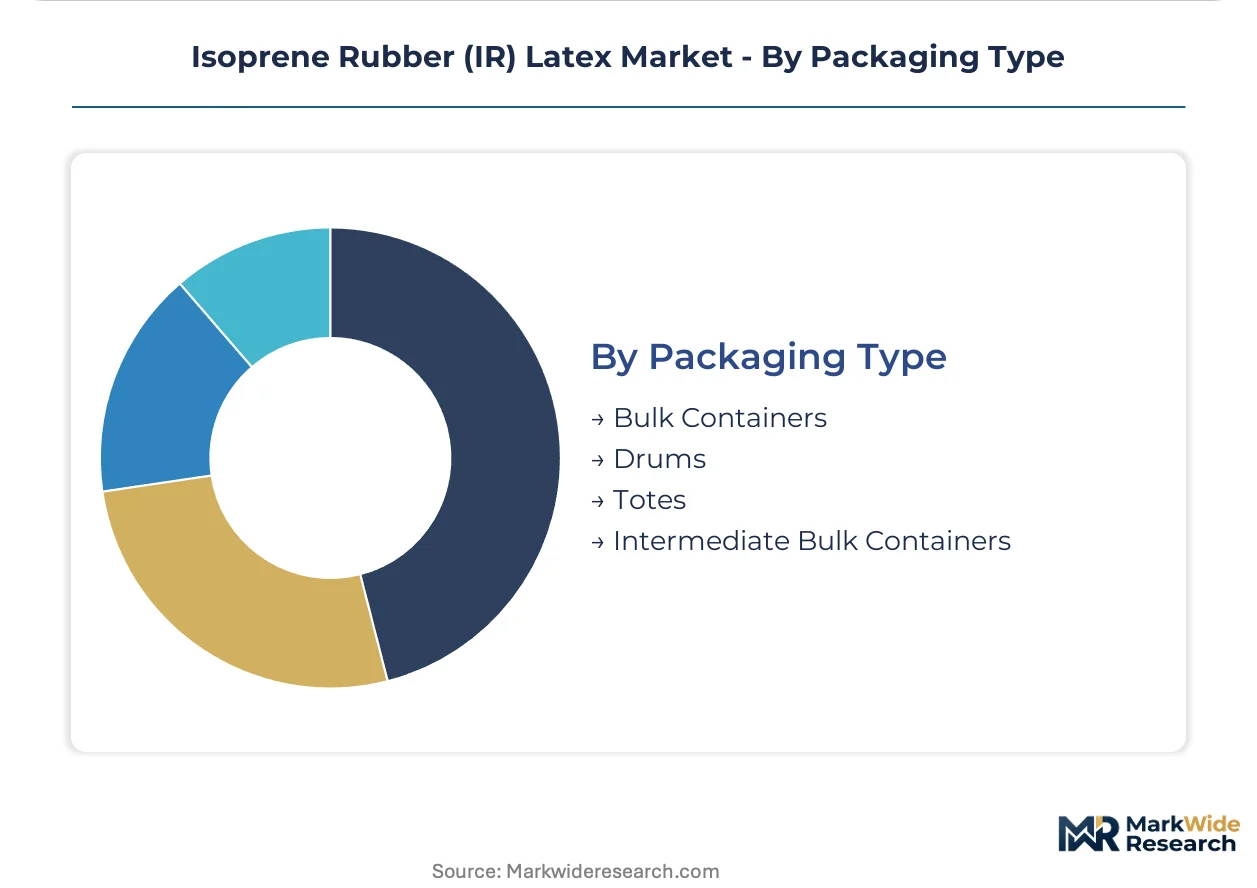
Volume scale and logistics infrastructure dictate packaging selection, with integrated manufacturers favoring bulk configurations while smaller compounders require portable units.
- Bulk Containers:Tank truck and railcar deliveries serving high-throughput dipping lines with dedicated storage and temperature control. Malaysian glove manufacturers with captive polymerization capacity receive monomer in this format.
- Drums:200-liter steel or plastic containers for mid-volume processors without bulk handling infrastructure. These units dominate adhesive and coating formulator procurement.
- Totes:Intermediate flexible or rigid containers offering mobility for batch-scale operations. Textile finishers and specialty foam producers favor this configuration for formulation flexibility.
- Intermediate Bulk Containers:1000-liter rigid or flexible systems bridging bulk and drum economics. Regional distributors stock these for just-in-time delivery to mid-tier manufacturers.
Bulk containers dominate throughput economics. Drums are where distributor channel expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical glove manufacturers concentrate procurement decisions in Malaysia, where vertically integrated supply chains compress qualification timelines for synthetic IR latex entering clinical distribution networks.
Malaysia
Malaysian glove manufacturers around Kuala Lumpur and Penang generate the densest demand concentration for synthetic IR latex formulations. EUDAMED registration requirements under EU MDR are compressing supplier qualification windows to 18 months. Hartalega Holdings and Top Glove operate integrated dipping lines that receive bulk polymer deliveries via dedicated tanker infrastructure.
Thailand
Thai condom and personal health product makers are trialing synthetic IR latex for premium non-allergenic product lines. FDA Thailand medical device registration pathways are aligning with ISO 13485 quality management standards for imported polymer batches. Bangkok-based formulators are retrofitting compounding facilities to handle waterborne emulsion systems displacing solvent-based alternatives.
United States
US hospital group purchasing organizations are unbundling glove contracts to negotiate direct synthetic latex pricing under zero-natural-latex policies. FDA master file documentation requirements extend supplier onboarding cycles for new IR grades. California and Texas health systems are driving procurement consolidation through liability-driven allergen elimination mandates.
Germany
German medical device distributors now require third-party residual monomer certificates for all imported IR latex batches under ECHA skin sensitizer classifications. REACH Annex XVII restrictions on prolonged skin contact applications are forcing reformulation toward post-polymerization stripping technologies. Frankfurt and Munich-based surgical device makers specify high-clarity solution grades for optical-precision procedures.
Japan
Japanese emulsion technology specialists retain concentrated expertise in particle size optimization for thin-wall glove production. PMDA medical device quality system requirements align with MHLW ministerial ordinances for clinical elastomer imports. Osaka and Nagoya polymerization facilities supply metallocene-catalyzed grades with narrow molecular weight distributions for surgical applications.
Isoprene Rubber (IR) Latex Market Key Industry Players
Player mix skews toward petrochemical conglomerates with captive isoprene monomer supply and specialized emulsion compounders serving medical-grade specifications. Structure consolidates around upstream-integrated producers controlling feedstock cracking capacity alongside downstream dipping-line operators with polymer formulation expertise. Three archetypes dominate: naphtha-integrated petrochemical majors, solution polymerization specialists, and medical-device-verticated glove manufacturers. Competitive moves center on backward integration into monomer production and strategic partnerships to secure EUDAMED registration support for EU market access.
Within the petrochemical-integrated tier, PJSC SIBUR Holding and Kuraray Co., Ltd. exemplify upstream control strategies through captive isoprene supply. Kraton Corporation and JSR Corporation occupy positions among solution polymerization specialists leveraging metallocene catalyst expertise. Malaysian manufacturers Top Glove Corp Bhd, Hartalega Holdings Bhd, and Kossan Rubber Industries Bhd anchor the demand-side integration archetype, operating dipping lines that internalize polymer procurement decisions. Zeon Corporation represents Japanese emulsion technology concentration. These named entities collectively illustrate how competitive positioning fragments across feedstock control, polymerization chemistry specialization, and end-use manufacturing integration.
| Leading Market Players |
|---|
| Top Glove Corp Bhd |
| Kraton Corporation |
| Kuraray Co., Ltd. |
| Ansell Limited |
| PJSC SIBUR Holding |
| JSR Corporation |
| Hartalega Holdings Bhd |
| Kossan Rubber Industries Bhd |
| Zeon Corporation |
| Others |
Cost & Logistics Intelligence
EU MDR biocompatibility certification gates both supplier qualification timelines and price differentiation tiers, compressing procurement windows for uncertified entrants while enabling premium positioning for documented purity grades. Medical device manufacturers face dual constraints: regulatory compliance costs and synthetic IR latex scarcity relative to natural latex alternatives.
Pricing Analysis
Metallocene-catalyzed solution grades command substantial premiums over Ziegler-Natta emulsion formulations due to narrow molecular weight distributions essential for thin-wall surgical gloves. Three-tier pricing structure across premium, standard, and economy levels separates FDA master file holders from regional compounders and spot-market suppliers. Pricing pressure stems from isoprene monomer volatility tied to naphtha cracking economics, squeezing non-integrated producers. Foam fabricators exhibit highest price sensitivity, while surgical device makers prioritize batch consistency over unit cost.
Supply Chain Analysis
Port congestion on the Straits of Malacca elevates inbound logistics costs for isoprene monomer shipments bound for Malaysian glove manufacturing clusters. Supply concentrates in Malaysia, Thailand, and Japan, with Malaysian dipping lines drawing from Thai petrochemical feedstock and Japanese emulsion technology. Raw material dependencies center on isoprene monomer, naphtha derivatives, and metallocene catalyst systems. Single-source vulnerability pervades specialized emulsion formulation expertise concentrated among aging Japanese technical specialists. Distribution runs through vertically integrated glove manufacturers with captive tanker infrastructure and regional chemical distributors serving mid-tier compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: EU MDR and FDA master file documentation create switching costs that lock in qualified suppliers across 18-24 month qualification cycles.
For Market Incumbents: Secure backward integration into isoprene monomer production to insulate margin structures from naphtha price volatility. Fortify EUDAMED registration support capabilities for European hospital networks facing compressed supplier onboarding timelines. Capacity expansion in Penang and Kuala Lumpur manufacturing corridors captures demand density from consolidating Malaysian glove producers. For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks offer accelerated pathways into US hospital procurement panels unbundling glove contracts under zero-natural-latex mandates. Adhesives formulation segments present most penetrable white space as VOC regulations displace solvent-based neoprene binders. Target automotive and construction end-users through regional distributor partnerships emphasizing solids content stability. For Investors and Strategic Acquirers: EU MDR full enforcement reshapes the acquisition landscape toward qualified suppliers with documented biocompatibility testing infrastructure. Long-term viability centers on producers with captive feedstock control and metallocene catalyst expertise. Watch for ISO 10993 testing backlog clearance rates as inflection indicator for qualification timeline normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isoprene Monomer | Captive naphtha cracking capacity insulates margin compression from crude oil volatility. |
| EUDAMED Registration Support Investment | Expedited EU MDR conformity assessments compress 18-month supplier qualification windows for hospital networks. |
| Metallocene Catalyst Technology Licensing | Narrow molecular weight distributions enable high-clarity surgical glove grades commanding premium positioning. |
| Adhesives Formulation Partnership Program | Waterborne IR latex displacement of solvent-based neoprene opens automotive and construction specification slots. |
| Post-Polymerization Stripping Infrastructure | REACH Annex XVII residual monomer compliance enables prolonged skin contact applications in German and French markets. |
Research Approach
A spread of perspectives from glove manufacturing procurement directors, emulsion polymerization R&D leads, hospital GPO contracts managers, and Malaysian chemical distributors converged on the working assumptions driving volume and value estimates. Primary fieldwork with these stakeholders combined with secondary validation from FDA master file databases, EUDAMED registration records, ECHA substance volume notifications, and Malaysian customs trade statistics. Bottom-up triangulation across polymerization capacity installations and top-down cross-checks against end-use consumption patterns anchored the analytical framework.
Segmentation dimensions modeled encompass polymerization route, medical certification tier, packaging configuration, and regional manufacturing cluster density across the projection horizon. CAGRs derived from installed base growth rates, qualification timeline compression effects, and substitution elasticity parameters. Forecast inputs incorporated EU MDR implementation phase transitions and isoprene monomer price volatility indices.
Underlying assumptions cover regulatory enforcement continuity, naphtha-isoprene price correlation stability, and biocompatibility testing capacity adequacy, with deviation risk concentrated in REACH Annex XVII threshold revisions and Malaysian manufacturing cluster labor availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Rubber Wear Liners Market
Rubber
Tire and Rubber Lubricants Market
Rubber
Rubber Ropes Market
Rubber
Styrene Butadiene Rubber (E-SBR and S-SBR) Market
Rubber
Rubber Plated Hose Market
Rubber
Polyisoprene Market
Rubber
Global Rubber Process Oil Market
Rubber
Acrylic Based Elastomers Market
Rubber
Styrene Butadiene (SB) Latex Market
Rubber
Hydroxyl Terminated Polybutadiene Market
Rubber
Global Medical Rubber Stopper Market
Rubber
Conductive Silicone Rubber Market
Rubber
Rubber Bulbs Market
Rubber
Tire Softener Market
Rubber
Global Hydraulic Rubber Hose Market
Rubber
Cellular Rubber Market