
 Styrene Butadiene Rubber (E-SBR and S-SBR) Market | 2026-2036
Styrene Butadiene Rubber (E-SBR and S-SBR) Market Size, Share, and Industry Trends Forecast 2026-2036
Styrene Butadiene Rubber (E-SBR and S-SBR) Market Intelligence
The role of specialized chemical distributors for high-performance solution SBR (S-SBR) is reshaping competitive positioning among producers. ARLANXEO leverages its extensive global production network to serve large-volume tire accounts directly. Asahi Kasei Corporation differentiates through its advanced S-SBR technologies for eco-friendly tires. In contrast, Sinopec dominates the high-volume emulsion SBR (E-SBR) segment within the Chinese domestic market.
Styrene Butadiene Rubber is a synthetic copolymer derived from styrene and butadiene monomers. It is produced primarily through two processes: emulsion polymerization (E-SBR), yielding a general-purpose rubber, and solution polymerization (S-SBR), which allows for precise molecular architecture control for high-performance applications. While Emulsion Styrene Butadiene Rubber constitutes the bulk of volume, Solution Styrene Butadiene Rubber represents the higher-margin segment due to its use in performance-critical tire components. Tire manufacturing remains the principal application, absorbing the vast majority of SBR output for tread and sidewall compounds.
Regulatory frameworks such as Europe's REACH, chemical substance rules under the US EPA, and China's GB standards govern monomer handling, production emissions, and finished product safety. These regulations directly impact raw material sourcing and necessitate significant compliance investments by manufacturers. Navigating the divergent requirements for tire labeling and end-of-life vehicle directives will be a critical determinant of market share for polymer producers.
Market Dynamics
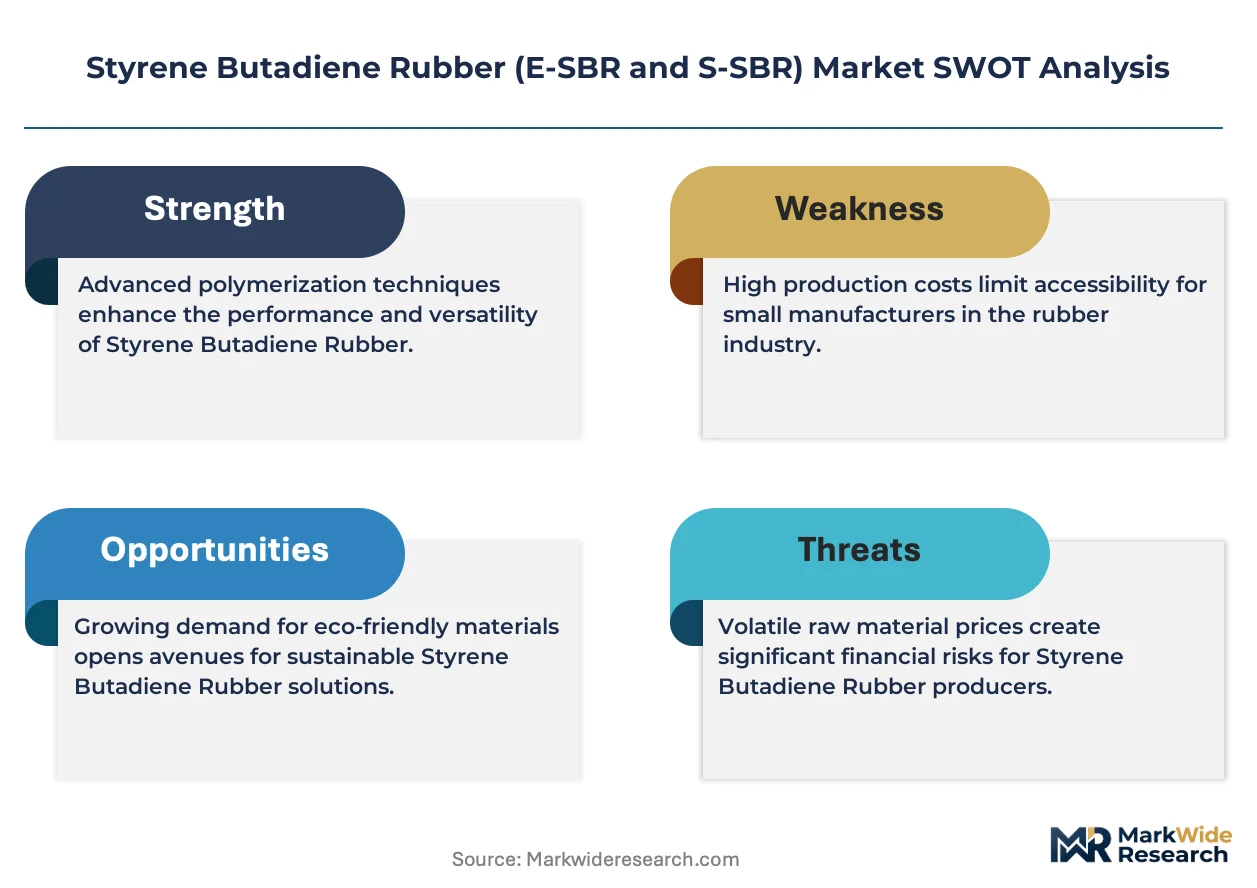
The market's core dynamic is the bifurcation between high-volume E-SBR and high-margin S-SBR. This split is intensified by global tire regulations mandating fuel efficiency, directly favoring advanced S-SBR chemistries and creating a clear value-versus-volume tension for producers.
Growth Catalysts
- EU Tire Labeling:Stricter regulations mandating lower rolling resistance directly compel tire makers to use higher-performance S-SBR grades, particularly in the European market.
- Electric Vehicle Adoption:Demand for specialized tires for EVs, which require low noise and high torque resistance, creates a specific pull for advanced S-SBR formulations.
- Chinese Automotive Production:China’s massive vehicle manufacturing base provides a foundational volume demand for E-SBR while its premium auto segment drives S-SBR consumption.
Market Restraints
- Feedstock Price Volatility:The prices of key monomers, styrene and butadiene, are linked to crude oil markets, introducing significant cost instability for SBR producers.
- Substitution from Natural Rubber:In non-performance tire components and general rubber goods, natural rubber often presents a lower-cost alternative, capping SBR pricing power.
- Regulatory Compliance Burden:Adherence to chemical regulations like Europe's REACH and US EPA rules on monomers requires substantial investment, acting as a barrier to entry.
Strategic Opportunities
- Bio-Based Feedstocks:Developing SBR from bio-derived butadiene or styrene creates a new product class with sustainability credentials, appealing to ESG-focused customers.
- Advanced Polymer Modification:Opportunities exist in creating highly specialized SBR for non-tire applications such as high-impact polystyrene modification and advanced adhesives.
- Indian Automotive Sector Growth:As vehicle production expands in India, there is a significant opportunity to supply advanced S-SBR to meet rising domestic demand for performance tires.
Industry Challenges
- Specialized Talent Scarcity:A lack of chemical engineers and polymer scientists with deep expertise in solution polymerization catalysis hinders new product development cycles for advanced S-SBR.
- High Capital Intensity:The construction of new S-SBR plants or the conversion of E-SBR facilities requires significant upfront capital investment and long lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Styrene Butadiene Rubber (E-SBR and S-SBR) Market |
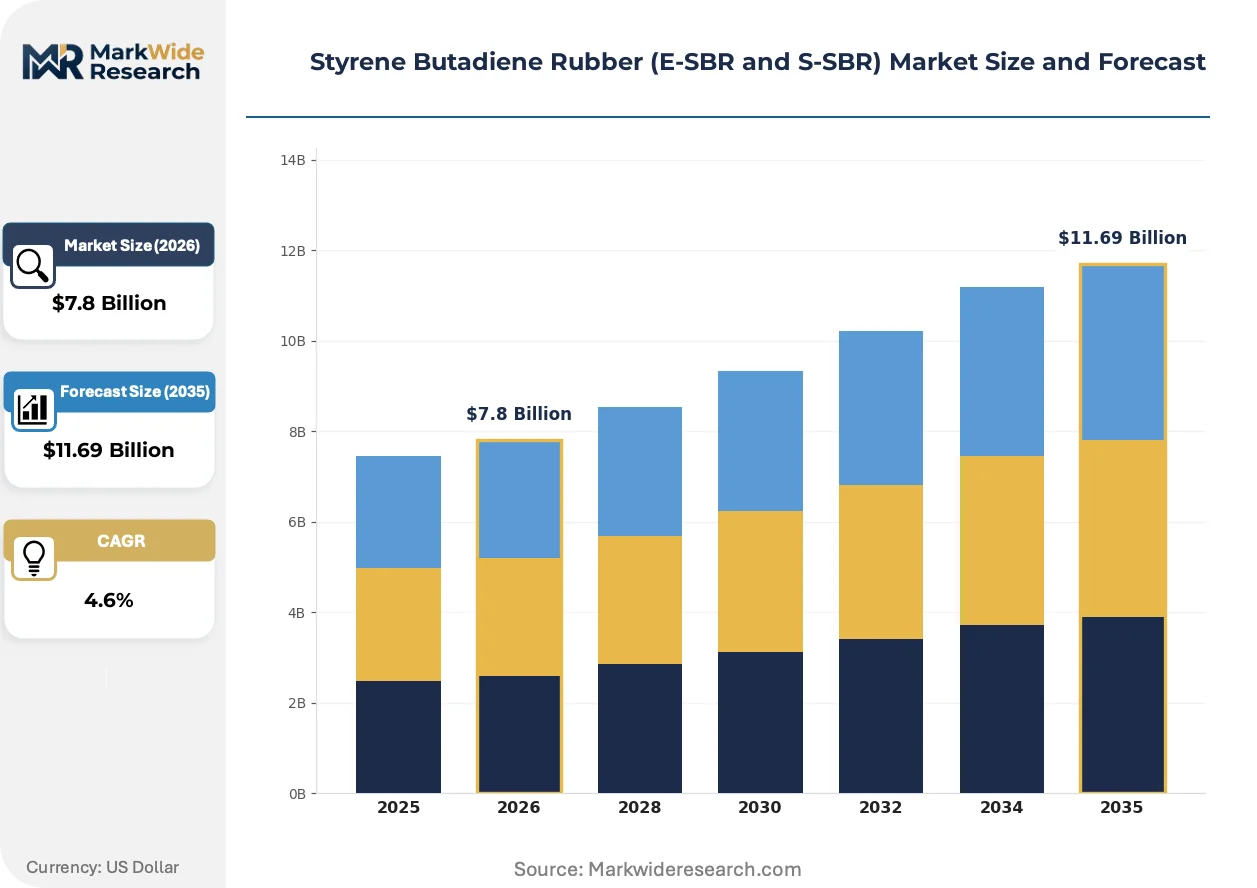
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $11.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Polymer Type: Emulsion Styrene Butadiene Rubber, Solution Styrene Butadiene Rubber, Carboxylated SBR, Epoxidized SBR Application: Tire Manufacturing, Adhesives, Footwear, Conveyor Belts, Hoses & Tubing, Protective Coatings End User Industry: Original Equipment Manufacturers, Aftermarket Suppliers, Footwear Producers, Adhesives Manufacturers, Industrial Fabricators Form: Latex, Solid Polymer, Powders, Masterbatches, Liquid Dispersion |
| Companies Covered | ARLANXEO, LANXESS, Sinopec, LG Chem, Kumho Petrochemical, Asahi Kasei Corporation, JSR Corporation, Trinseo, Versalis S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Styrene Butadiene Rubber (E-SBR and S-SBR) Market Strategic Shifts & Innovations
A fundamental re-evaluation of the polymer lifecycle is underway, driven by demands for circularity and verifiable sustainability metrics. This forces innovation beyond pure performance into feedstock sourcing and end-of-life management for SBR products, altering the competitive landscape.
Functionalized S-SBR incorporates chemical groups onto the polymer chain to enhance its interaction with silica fillers. Major tire producers are adopting these grades for ultra-high-performance and EV-specific tires. This technology is hybridizing polymer science with materials engineering, creating compounds where rubber and filler act as an integrated system.
The European Union's Corporate Sustainability Reporting Directive (CSRD) mandates detailed disclosure of environmental impacts. This forces SBR producers selling into Europe to provide transparent data on carbon footprint and raw material sourcing. The S-SBR segment, with its complex global supply chain, faces the most significant data collection burden.
A shift toward lifecycle-based procurement is altering criteria for large tire manufacturers. Buyers now demand mass-balance certifications for SBR with recycled or bio-based content, moving beyond just technical specifications. This change is most visible in the European and North American automotive supply chains.
Styrene Butadiene Rubber (E-SBR and S-SBR) Market Segmentation
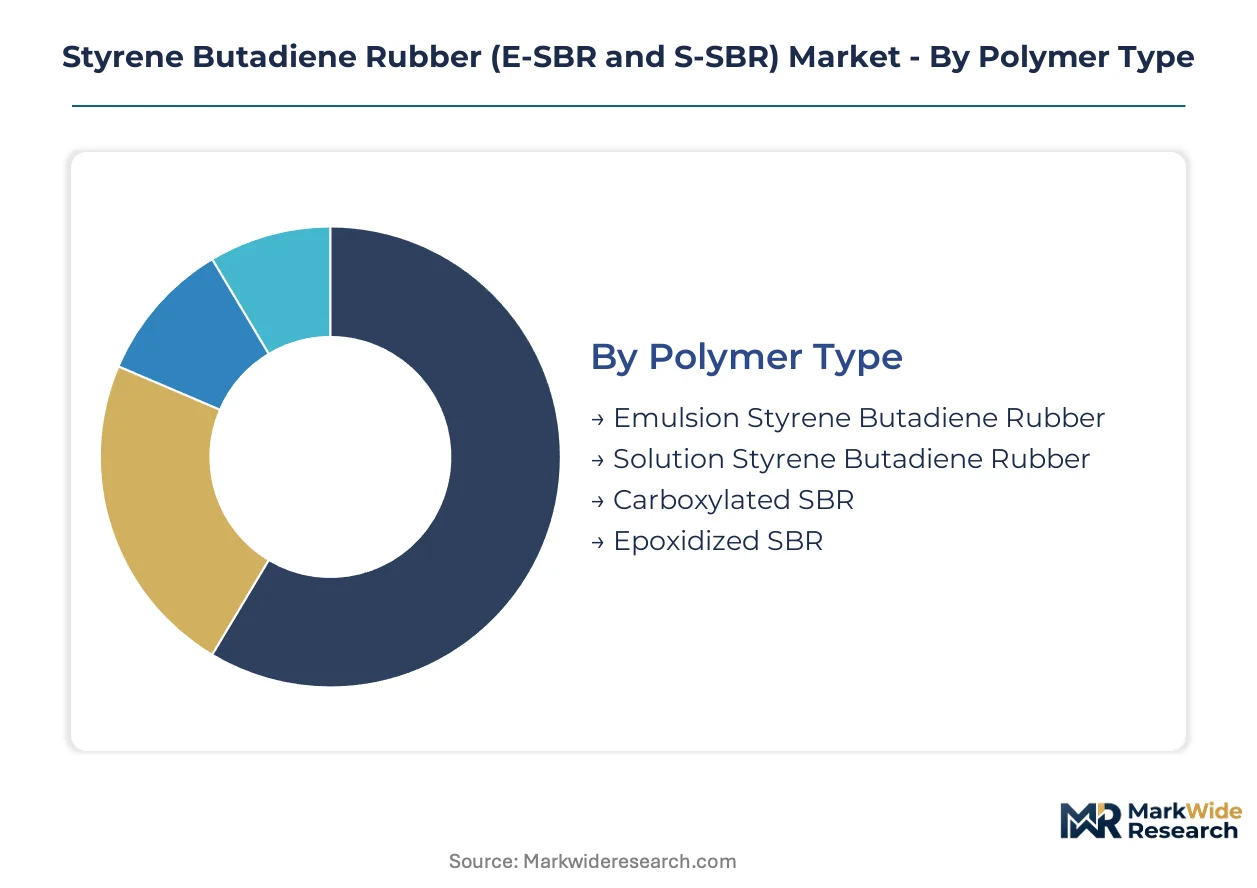
The Styrene Butadiene Rubber market segments reveal distinct value propositions and demand dynamics across its various forms and end-uses. Understanding these classifications is critical for producers to tailor product offerings and navigate the complex regulatory landscapes that govern performance and sustainability.
Polymer Type:
The after-sales service intensity for SBR varies significantly across polymer types, reflecting the performance criticality and technical support required for different applications.
- Solution Styrene Butadiene Rubber (S-SBR):This polymer type offers precise molecular architecture control, enabling superior performance characteristics such as lower rolling resistance and improved wet grip. Demand for S-SBR is concentrating in high-performance and electric vehicle tire manufacturing, driven by European Union tire labeling regulations.
- Emulsion Styrene Butadiene Rubber (E-SBR):Produced through emulsion polymerization, E-SBR serves as a general-purpose synthetic rubber, offering a balance of properties at a lower cost point. Its demand is foundational in volume-driven applications like standard tire segments and general rubber goods, particularly within the Chinese domestic market.
- Carboxylated SBR:This modified SBR variant incorporates carboxylic acid groups, enhancing adhesion and mechanical strength, particularly in textile and paper coatings.
- Epoxidized SBR:Epoxidized SBR provides improved compatibility with polar materials and enhanced barrier properties, finding niche applications in specialized coatings and adhesives.
By volume, Emulsion Styrene Butadiene Rubber leads. By growth pace, Solution Styrene Butadiene Rubber is ahead.
Application:
Margin profiles for SBR applications diverge based on performance requirements and formulation complexity.
- Tire Manufacturing:This application absorbs the vast majority of SBR output, forming critical components for treads, sidewalls, and inner liners. Demand is directly linked to global automotive production and the increasing adoption of specialized tires for electric vehicles in regions like North America and Germany.
- Adhesives:SBR-based adhesives offer strong bonding and flexibility, making them suitable for construction, automotive, and packaging applications. Demand for advanced SBR formulations is rising in lightweighting initiatives within the automotive sector.
- Footwear:SBR contributes to durable and flexible soles for various footwear types, including athletic and industrial safety shoes.
- Conveyor Belts:SBR provides abrasion resistance and strength for heavy-duty conveyor belts used in mining and material handling industries.
- Hoses & Tubing:SBR's resistance to abrasion and heat makes it suitable for various industrial and automotive hoses and tubing.
- Protective Coatings:SBR latex is utilized in protective coatings for its binding properties and resistance to weathering in construction and architectural applications.
Tire Manufacturing remains the largest application segment, while specialized Adhesives demonstrate consistent expansion.
End User Industry:
Customer type dictates procurement volumes and technical specification demands within the SBR market.
- Original Equipment Manufacturers:These manufacturers integrate SBR into new products, primarily tires for new vehicles, but also components for machinery and appliances. This segment's demand is foundational, particularly with the growth of automotive production in China and India.
- Aftermarket Suppliers:This category includes companies providing replacement tires, repair kits, and parts for existing vehicles and industrial equipment. This segment is influenced by the global vehicle parc size and maintenance cycles.
- Footwear Producers:These companies utilize SBR for sole manufacturing, valuing its durability and cost-effectiveness in mass-produced and specialized footwear.
- Adhesives Manufacturers:Formulators in this industry incorporate SBR into various adhesive products, catering to construction, automotive assembly, and consumer goods.
- Industrial Fabricators:These firms use SBR in the production of conveyor belts, hoses, gaskets, and other custom rubber components for diverse industrial sectors.
Original Equipment Manufacturers represent the foundational demand, with Aftermarket Suppliers showing steady, volume-driven uptake.
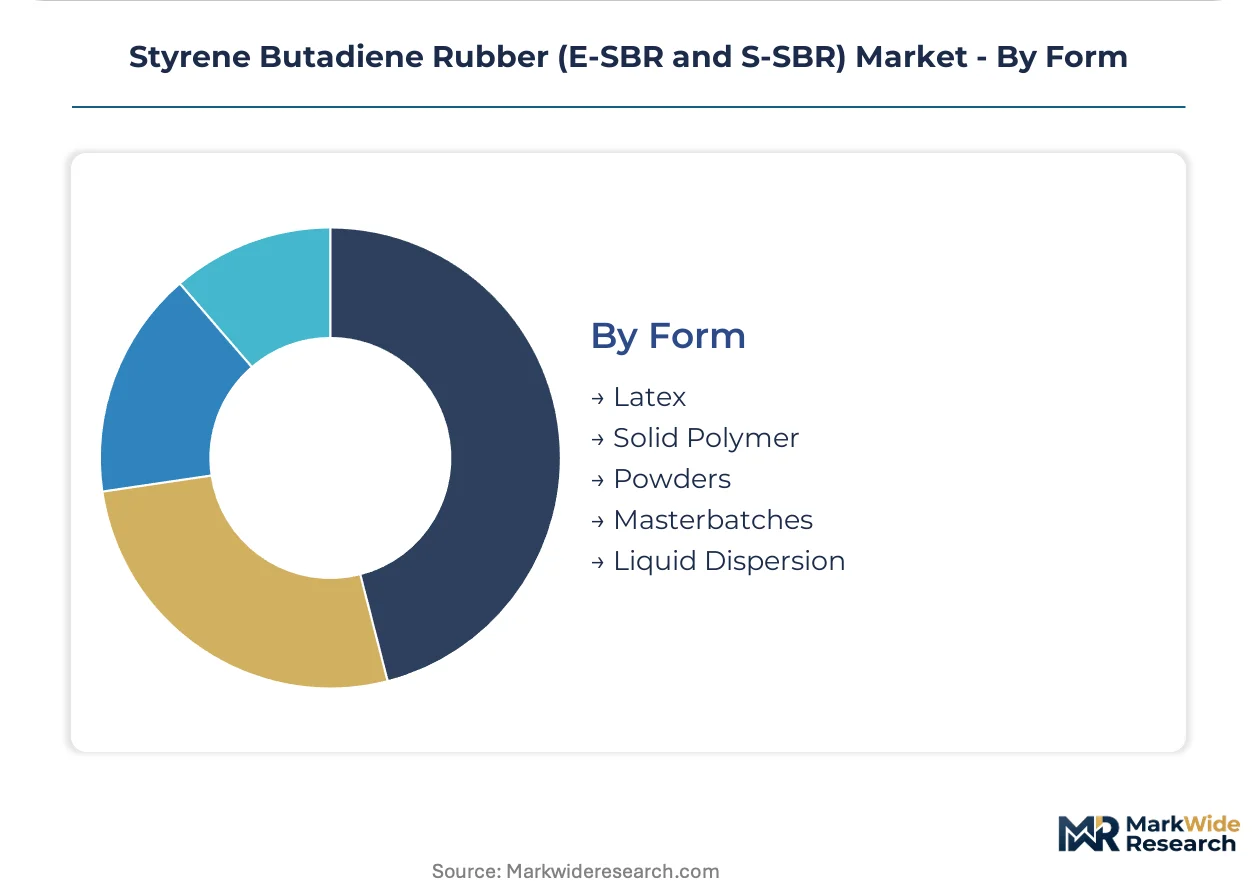
Form:
Supply concentration for SBR forms is influenced by production processes and downstream handling requirements.
- Solid Polymer:This is the most common form of SBR, shipped in bales for direct compounding into rubber products like tires and industrial goods. Its demand dominates the market due to its versatility and established processing infrastructure in major manufacturing hubs such as Germany and Japan.
- Latex:SBR latex is an aqueous dispersion, primarily used in adhesives, coatings, and binders for paper and textiles. Demand for SBR latex is significant in packaging and construction sectors, particularly in North America.
- Powders:SBR powders offer easier handling and mixing for specific applications, including asphalt modification and certain adhesive formulations.
- Masterbatches:These are pre-dispersed SBR compounds containing fillers or additives, simplifying processing for specialized rubber goods manufacturers.
- Liquid Dispersion:Similar to latex, liquid dispersions offer ease of application in coatings and binders, particularly where precise film formation is required.
Solid Polymer constitutes the bulk of SBR supply, with Latex forms experiencing robust demand in specific industrial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry between China and European markets defines the Styrene Butadiene Rubber landscape. China's domestic E-SBR production volume creates downward price pressure, while Europe's stringent tire regulations drive premium S-SBR demand and higher margins. This dynamic influences investment decisions and product portfolio strategies for global SBR producers.
China
China's automotive manufacturing base drives foundational demand for both E-SBR and S-SBR, particularly for domestic vehicle production. The country's GB standards for automotive components and emissions influence material specifications for SBR. Massive production hubs in the Yangtze River Delta and Pearl River Delta consume significant volumes for tire manufacturing and general rubber goods.
Germany
Germany's advanced automotive industry and stringent EU tire labeling regulations create strong pull for high-performance S-SBR grades. European Union REACH regulations necessitate significant compliance investments for SBR producers supplying the German market. The Rhine-Ruhr industrial region, with its chemical and automotive clusters, represents a key center for SBR processing and consumption.
United States
Demand for SBR in the United States stems from its large automotive aftermarket and specialized industrial applications. US EPA chemical substance rules dictate monomer handling and production emissions for domestic SBR manufacturers. Major tire production facilities in states like Ohio and South Carolina require consistent SBR supply for various tire segments.
India
India's expanding automotive sector and infrastructure development projects fuel a rising demand for SBR, particularly for performance tires. The country's BIS standards for rubber products guide material selection and quality control for SBR applications. Industrial clusters in Maharashtra and Gujarat are emerging as significant consumption centers for SBR in tire and industrial rubber fabrication.
Japan
Japan's focus on high-performance and eco-friendly tires drives demand for advanced S-SBR formulations. METI regulations and JIS standards ensure strict quality and environmental compliance for SBR production and use. The Kanto region, including Tokyo and Yokohama, is a hub for research, development, and advanced manufacturing of SBR-based products.
Styrene Butadiene Rubber (E-SBR and S-SBR) Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical raw materials. The market exhibits a tiered structure, with large petrochemical companies dominating the high-volume E-SBR segment, while specialized polymer producers focus on high-margin S-SBR. Strategic partnerships between SBR producers and tire manufacturers are a dominant competitive move, alongside continuous investment in advanced S-SBR production capacity.
Global chemical giants like ARLANXEO, a joint venture between LANXESS and Saudi Aramco, exemplify producers with extensive global production networks for SBR. Chinese state-owned enterprises such as Sinopec anchor the high-volume emulsion SBR segment within their domestic market, leveraging massive scale. Japanese chemical companies like Asahi Kasei Corporation differentiate through advanced S-SBR technologies tailored for eco-friendly and high-performance tires.
| Leading Market Players |
|---|
| ARLANXEO |
| LANXESS |
| Sinopec |
| LG Chem |
| Kumho Petrochemical |
| Asahi Kasei Corporation |
| JSR Corporation |
| Trinseo |
| Versalis S.p.A. |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta and Pearl River Delta production hubs, with their massive E-SBR capacity, exert downward pressure on global pricing for general-purpose grades. This dynamic influences investment decisions and product portfolio strategies for global SBR producers.
Pricing Analysis
The customization-premium spread differentiates pricing for SBR, reflecting the distinct value propositions of its polymer types. Pricing stratifies across high-volume E-SBR, which operates on a more transactional commodity spot basis, and high-performance S-SBR, which commands value-based pricing due to its precise molecular architecture. Performance characteristics like lower rolling resistance and improved wet grip act as key price differentiation drivers. Pricing pressure stems from the high-volume E-SBR segment, particularly within the Chinese domestic market. Buyers in standard tire segments exhibit high price sensitivity, while those in specialized EV tire manufacturing prioritize performance over cost.
Supply Chain Analysis
Regulatory restrictions on chemical flows and production standards, such as Europe's REACH, shape the global SBR supply chain. Geographic supply concentration centers on China for E-SBR and advanced manufacturing regions like Germany and Japan for S-SBR. The supply chain sources critical styrene and butadiene monomers, which are inherently tied to crude oil markets. Feedstock price volatility represents a significant structural risk for SBR producers. Downstream distribution relies on direct sales for large-volume tire manufacturers and specialized chemical distributors for high-performance S-SBR grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Styrene Butadiene Rubber market is experiencing an early-cycle expansion, driven by the increasing adoption of electric vehicles and their specialized tire requirements.
For Market Incumbents: Entrench market leadership by continuous investment in advanced S-SBR production capacity and functionalized polymer R&D. Strengthen strategic partnerships with major tire manufacturers to secure long-term offtake agreements. This proactive stance mitigates the threat of specialized talent scarcity hindering new product development cycles. Compliance investments for regulations like Europe's REACH also protect market access.
For New Entrants and Emerging Players: Pursue niche opportunities in bio-based SBR production to leverage sustainability credentials. Target the rapidly expanding Indian automotive sector with advanced S-SBR formulations for performance tires. Focus on developing highly specialized SBR for non-tire applications, such as advanced adhesives, where performance requirements allow for premium pricing. This approach bypasses direct competition in high-volume E-SBR segments.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized S-SBR producers with proprietary functionalization technologies. The long-term viability of the SBR market, particularly the S-SBR segment, remains strong due to sustained demand from electric vehicles and stringent tire regulations. Investors should seek acquisition targets offering advanced polymer modification capabilities or unique bio-based feedstock integration. The signal to watch is the increasing adoption rates of functionalized S-SBR in major tire manufacturers' new product lines.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion (S-SBR) | Addresses growing demand for high-performance tires, especially from EV manufacturers. |
| Green Manufacturing Transition | Aligns with EU CSRD requirements and appeals to ESG-focused automotive customers. |
| Long-term Supply Agreement | Secures raw material access and stable pricing for key monomers like butadiene. |
| Joint Venture (R&D) | Accelerates development of bio-based SBR formulations with sustainability credentials. |
| Strategic Partnership (Tire OEMs) | Ensures market access and co-development for next-generation tire compounds. |
Research Approach
A standing panel of polymer scientists, plant managers, procurement leads at tire OEMs, and specialized chemical distributors provided ongoing calibration. This primary research was combined with extensive secondary validation from customs and trade data, SEC 10-K filings, and industry association reports. A rigorous bottom-up and top-down triangulation approach ensured data consistency and accuracy.
Scenario-bracketing informed the analytical framework across the analysis window, integrating various macroeconomic and industry-specific assumptions. Segmentation dimensions modeled included polymer type, application, end-user industry, form, and regional production capacity. Compound Annual Growth Rates were derived through a robust regression analysis, incorporating automotive production forecasts and crude oil price projections as key inputs.
Macroeconomic conditions sit as an overlay; deviation in global automotive production or crude oil prices would shift the trajectory. Forecasts reflect a carefully considered set of assumptions regarding regulatory stability and technological advancements. Material shifts in major trade policies or geopolitical events would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Snap on Rubber Stopper Market
Rubber
Europe Neoprene Market
Rubber
Co-Extruded Rubber Profiles Market
Rubber
Chloroprene Rubber Modified Asphalt Emulsion Market
Rubber
Rubber Compound Market
Rubber
Rubber Foam Materials Market
Rubber
Industrial Rubber Market
Rubber
Nitrile Elastomers Market
Rubber
Rubber Foam Market
Rubber
Rubber Sheets Market
Rubber
Recycled Elastomers Market
Rubber
Abrasion-Resistant Rubber Pipe Market
Rubber
Global Rubber Processing Chemicals Market
Rubber
Pre-Dispersed Rubber Chemicals Market
Rubber
Nitrile Butadiene Rubber Market
Rubber
Rubber Gloves Market