
 Rubber Wear Liners Market | 2026-2036
Rubber Wear Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Wear Liners Market Analytics
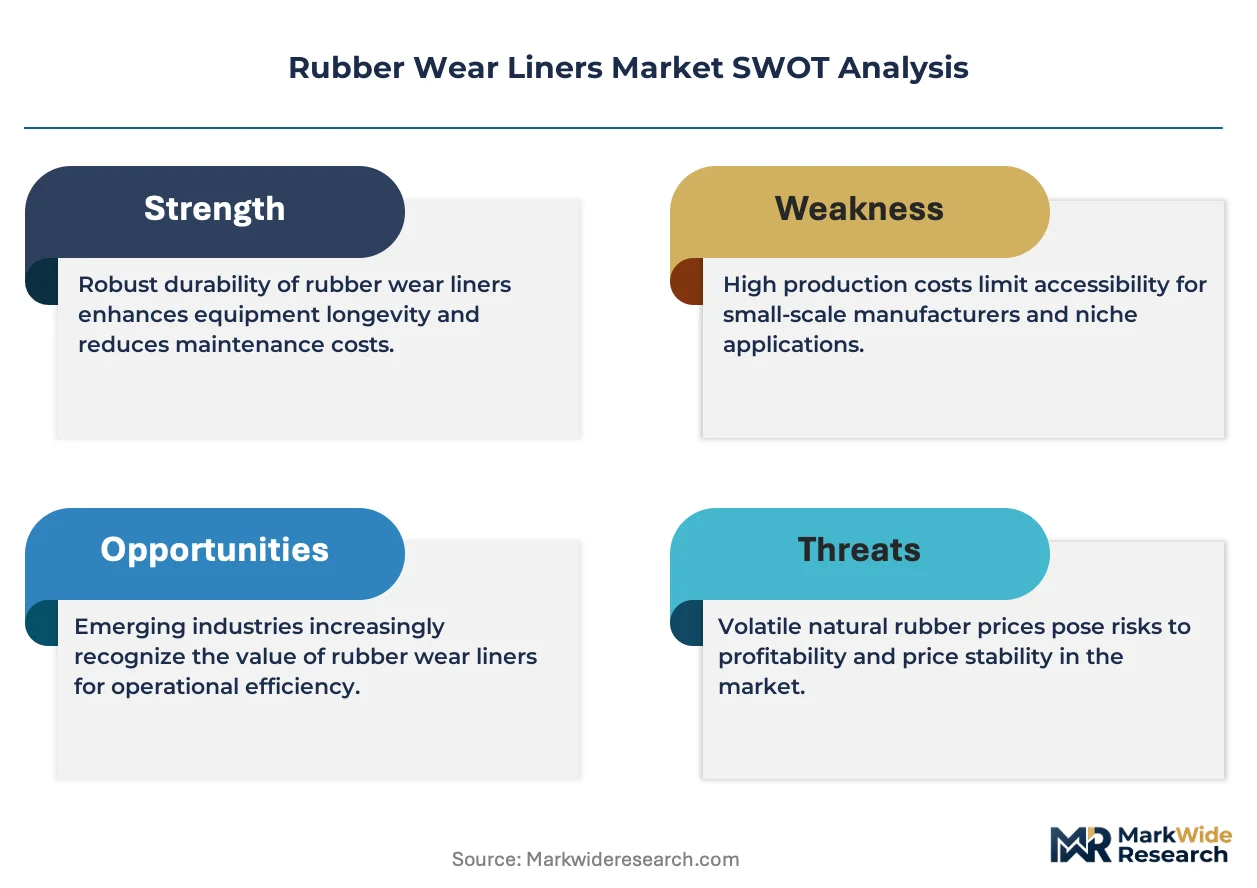
The rubber wear liners market is restructuring around a sharp split between premium engineered compounds and commodity-grade alternatives. Metso Outotec leverages its vertically integrated foundry-to-liner supply chain to dominate high-wear mining installations. Trelleborg competes through advanced polyurethane blends that extend service intervals in slurry pipelines. Weir Group anchors its position with application-specific designs for SAG mill discharge grates.
Rubber wear liners are elastomeric or polymer-based protective sheets bonded to steel substrates, typically formulated with natural rubber, synthetic rubber, or polyurethane and applied at thicknesses from 25 mm to 150 mm to absorb impact and abrasion in bulk material handling systems. Their primary purpose is to extend equipment life in high-wear zones such as chutes, hoppers, and grinding mills while reducing unplanned downtime. Natural rubber formulations command the largest volume share due to their superior resilience in wet abrasion environments, though polyurethane segments are gaining share where oil and chemical resistance matter. Mining applications generate the dominant revenue pool, with aggregate processing representing a faster-growing but smaller margin segment as quarry automation accelerates replacement cycles.
OSHA workplace safety mandates and EPA dust control regulations in the United States shape liner specification requirements by enforcing minimum durability standards that reduce worker exposure to maintenance hazards. ECHA's REACH framework in Europe restricts certain curatives and plasticizers in rubber compounds, pushing reformulation toward compliant polymer systems. Stakeholders must monitor how evolving mine safety codes in major producing jurisdictions and polymer feedstock volatility will reshape supplier qualification criteria and replacement contracting models.
Market Dynamics
The rubber wear liners market is bifurcating around ore grade degradation in major mining belts, forcing operators to process more tonnage per unit of metal extracted and accelerating liner replacement cycles in high-throughput grinding circuits.
Growth Catalysts
- Pilbara Throughput Intensification:Australia's iron ore miners process lower-grade deposits, driving demand for thicker rubber formulations in SAG mill discharge zones.
- REACH Polymer Reformulation:ECHA's restrictions on phthalate plasticizers push suppliers toward compliant curative systems that extend liner fatigue life.
- Polyurethane Blending Advances:Synthetic elastomer compounds with enhanced oil resistance penetrate slurry pipeline applications previously dominated by natural rubber.
Market Restraints
- Natural Rubber Price Volatility:Feedstock costs swing with Southeast Asian latex harvest cycles, compressing margins for commodity-grade liner producers.
- Supplier Concentration in Brazil:Minas Gerais state depends on a narrow import base for engineered compounds, exposing operations to currency-driven supply interruptions.
- Steel Substrate Shortages:Bonding-grade plate availability constrains domestic fabrication capacity in Chile's Antofagasta mining corridor.
Strategic Opportunities
- Quarry Automation in North America:Aggregate processors adopt sensor-integrated liners that signal wear depth, enabling predictive replacement scheduling.
- China's GB Standard Alignment:Industrial safety mandates for bulk handling equipment create compliance-driven replacement demand in domestic cement and coal sectors.
- Modular Liner Systems:Bolt-in segment designs reduce installation downtime, appealing to copper concentrators in Peru seeking maintenance window compression.
Industry Challenges
- Elastomer Compounding Expertise Gap:Mining maintenance departments lack polymer chemistry knowledge to specify optimal hardness grades for specific ore abrasiveness profiles.
- REACH Certification Timelines:European suppliers face extended testing protocols for new curative formulations, delaying product launches by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Wear Liners Market |
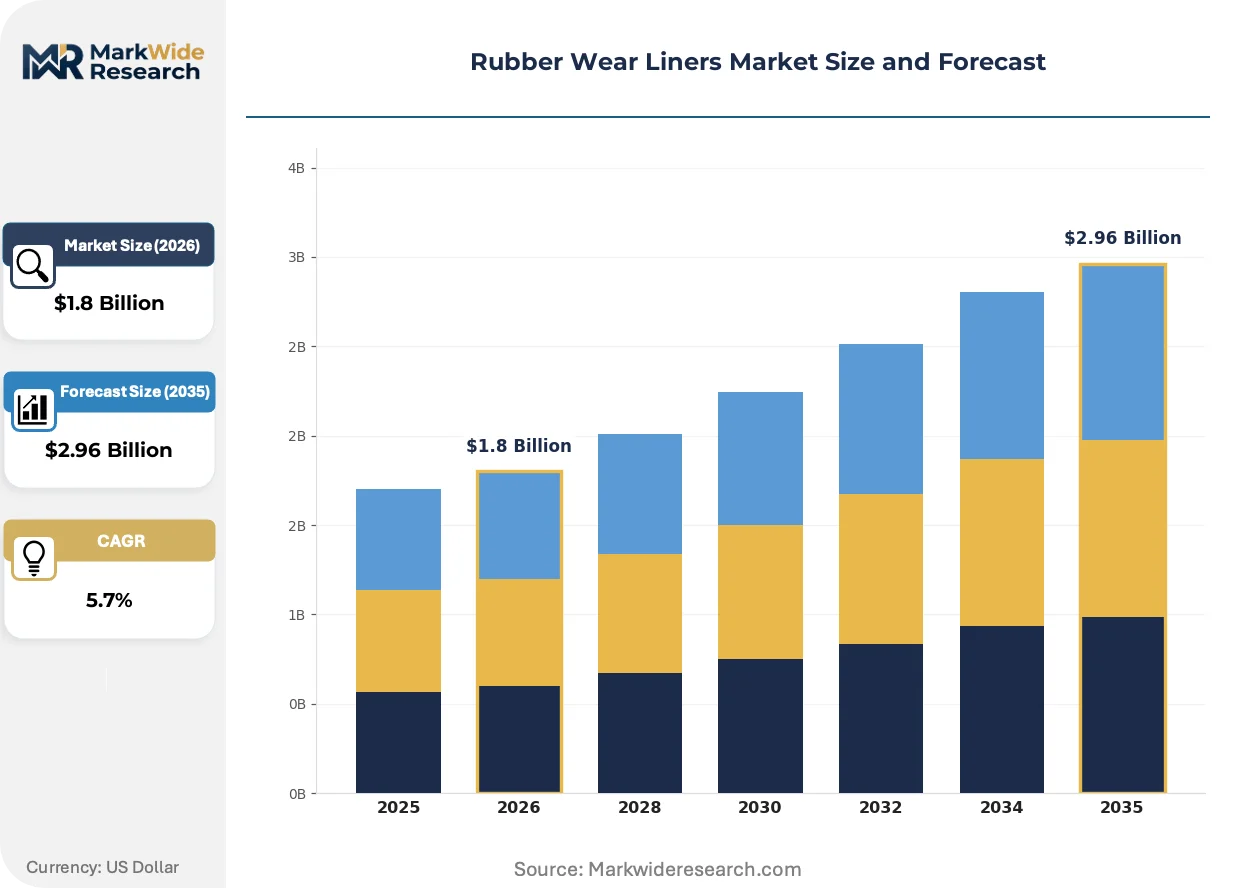
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Rubber, Synthetic Rubber, High-Density Polyethylene, Polyurethane Application: Mining, Construction, Aggregate Processing, Material Handling End User: Mining Companies, Construction Firms, Automotive Manufacturers, Industrial Facilities Distribution Channel: Direct Sales, Distributors, Online Retail, Resellers |
| Companies Covered | Metso Outotec, Trelleborg, Weir Group, Rema Tip Top, FLSmidth, Saint-Gobain, Bridgestone Corporation, Multotec, Tega Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Wear Liners Market Evolving Landscape
Material science advances and regulatory chemistry constraints are converging to redefine liner performance specifications, with durability metrics increasingly tied to environmental compliance rather than purely mechanical wear resistance.
Sensor-embedded rubber wear liners is expanding into high-value mining installations as operators seek real-time thickness monitoring. Rio Tinto's Pilbara operations pilot wireless-enabled liners that transmit abrasion data to maintenance planning systems. This capability is compressing traditional calendar-based replacement schedules toward condition-driven interventions.
REACH Annex XVII restrictions on N-nitrosamines in rubber compounding force reformulation of vulcanization accelerator packages across European supply chains. Mining operators in Sweden and Finland now specify liners certified under updated ECHA substance restrictions. The compliance burden falls heaviest on small domestic fabricators lacking in-house toxicology testing capacity.
Buyer consolidation among tier-one miners has compressed supplier qualification cycles from multi-year trials to 90-day performance benchmarks. Procurement teams at BHP and Vale now demand accelerated wear testing protocols before contract award. This pattern concentrates specification authority with centralized engineering functions in Melbourne and Belo Horizonte.
Rubber Wear Liners Market Segmentation
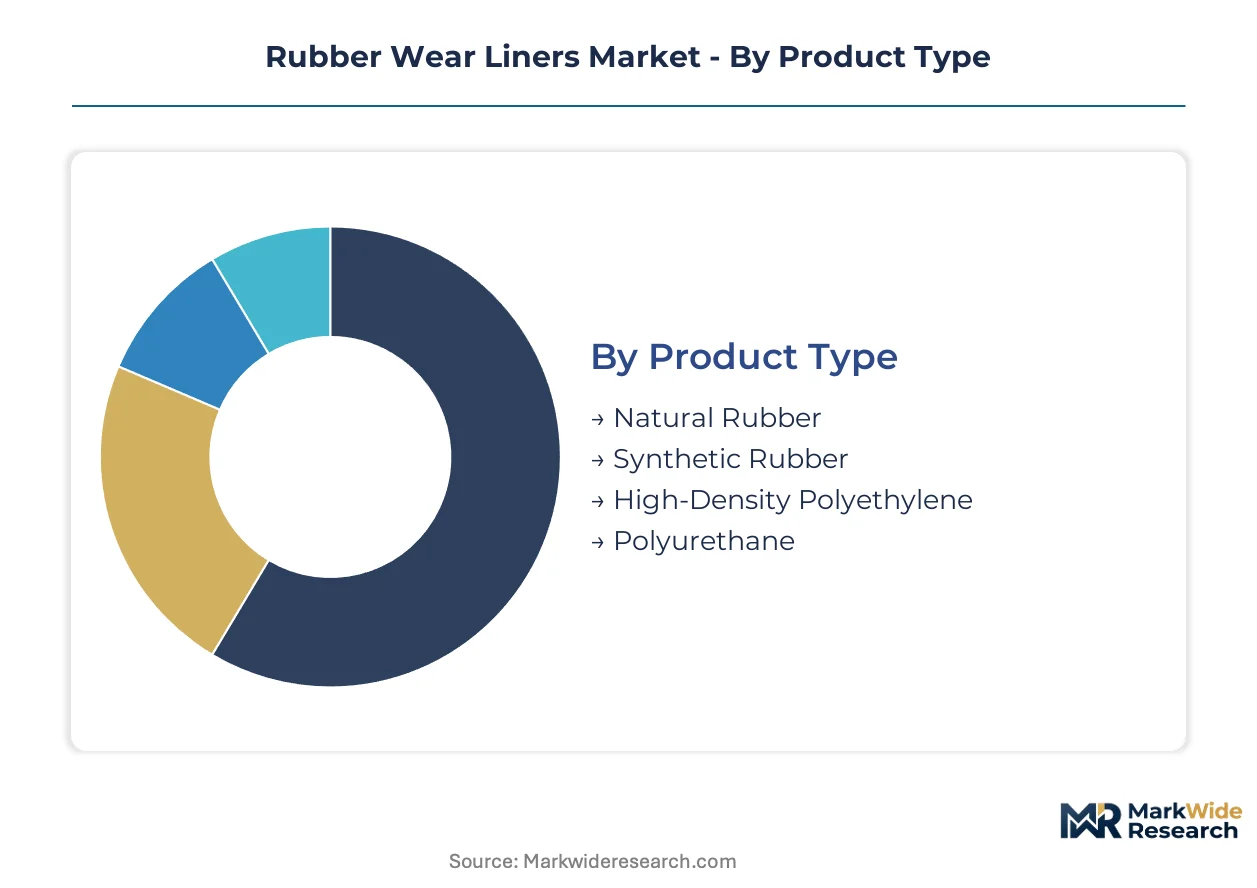
Rubber wear liner procurement patterns diverge sharply across material grades and end-use intensities. Replacement cycle timing and specification authority vary by segment, creating distinct commercial entry points for suppliers.
Product Type:
Upgrade decisions pivot on abrasion environment chemistry and the cost of unplanned downtime in specific process zones.
- Natural Rubber:Formulations based on polyisoprene deliver superior resilience in wet slurry abrasion conditions. Pilbara iron ore operators specify 75-90 Shore A hardness grades for SAG mill discharge applications where ore grade degradation accelerates replacement frequency.
- Polyurethane:Castable elastomer systems with tailored hardness profiles penetrate oil-contaminated slurry pipelines previously served by natural rubber. Trelleborg's advanced blends extend service intervals in Chilean copper concentrator tailings systems where hydrocarbon exposure degrades conventional compounds.
- Synthetic Rubber:SBR and nitrile variants address chemical resistance requirements in phosphate and potash processing circuits with controlled pH exposure.
- High-Density Polyethylene:Thermoplastic liners serve lower-impact, lower-temperature applications in aggregate screening and light-duty material transfer points where cost minimization dominates specification.
Volume placements concentrate in Natural Rubber; the faster expansion belongs to Polyurethane.
Application:
Process intensity and ore abrasiveness index determine liner thickness specification and replacement contracting models.
- Mining:Grinding mill circuits, chute systems, and hopper protection in copper, iron ore, and gold operations generate the dominant revenue pool. Australia's declining ore grades force processing volume increases that compress liner life cycles in primary crushing and SAG mill discharge zones.
- Aggregate Processing:Quarry automation accelerates replacement cycles as sensor-integrated equipment enables predictive maintenance scheduling. North American producers adopt condition-monitoring liners that signal wear depth before failure.
- Construction:Cement plant raw material handling and concrete batching operations specify medium-duty formulations where impact severity remains moderate.
- Material Handling:Port bulk terminals and power plant coal handling systems require fire-resistant grades meeting site-specific safety codes.
Revenue gravity centers on Mining; Aggregate Processing is climbing the fastest as quarry digitization spreads.
End User:
Specification authority and procurement sophistication vary by organizational scale and in-house maintenance capability.
- Mining Companies:Tier-one operators centralize liner qualification through centralized engineering functions in Melbourne and Belo Horizonte. BHP and Vale compress supplier trials from multi-year evaluations to 90-day performance benchmarks.
- Industrial Facilities:Cement, steel, and fertilizer plants balance durability requirements against capital constraint, often favoring modular bolt-in systems that reduce installation downtime.
- Construction Firms:Project-based procurement with limited specification expertise creates price-sensitive demand for standard-grade formulations.
- Automotive Manufacturers:Foundry and stamping plant applications represent a niche segment with specialized heat and oil resistance requirements.
Contract value aggregates with Mining Companies; Industrial Facilities are gaining share fastest as modular system adoption spreads.
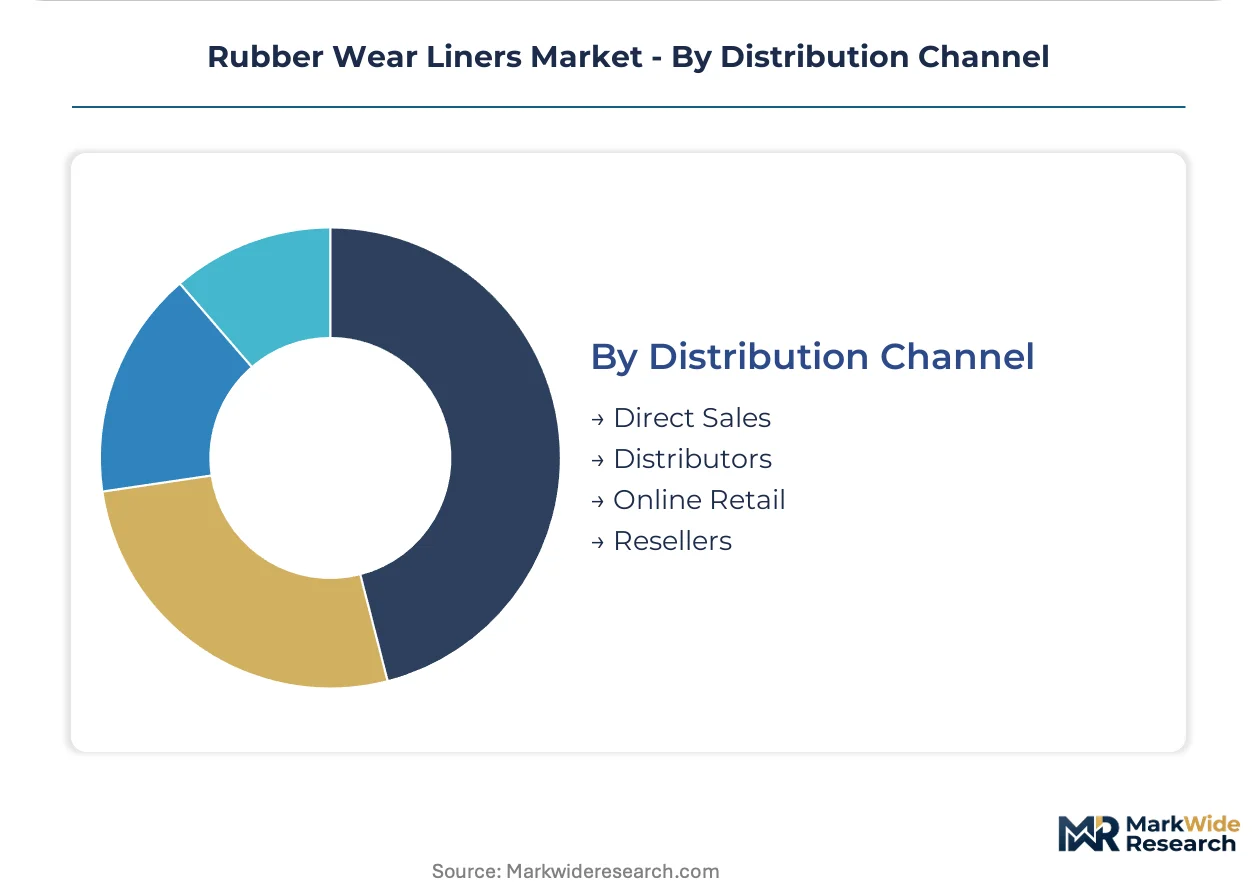
Distribution Channel:
Channel selection reflects buyer technical sophistication and the criticality of application-specific engineering support.
- Direct Sales:Engineered compound suppliers maintain field engineering teams for high-wear mining installations requiring custom thickness profiling and substrate preparation guidance. Metso Outotec leverages vertically integrated supply chains to serve major concentrator projects directly.
- Distributors:Regional stocking locations serve mid-tier mining and aggregate operators needing rapid replacement part availability without direct manufacturer engagement.
- Resellers:Independent fabricators bond imported rubber sheet to locally sourced steel plate, competing on lead time for standard specification orders.
- Online Retail:Catalog-based procurement of cut-to-size sheet stock serves maintenance departments with in-house fabrication capacity and immediate, non-critical replacement needs.
Transaction volume flows through Direct Sales; Distributors are expanding most quickly as regional service networks deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's Pilbara mining corridor anchors global demand for rubber wear liners, with iron ore operators processing declining ore grades that accelerate replacement cycles in SAG mill discharge zones and primary crushing circuits.
Australia
Iron ore throughput intensification in Western Australia's Pilbara region drives specification shifts toward thicker natural rubber formulations. TGA workplace safety mandates enforce minimum durability standards that reduce worker exposure during liner replacement. Perth-based engineering functions at BHP and Rio Tinto centralize procurement authority, compressing supplier qualification to 90-day performance benchmarks.
Chile
Copper concentrators in the Antofagasta mining corridor face steel substrate shortages that constrain domestic fabrication capacity for bonded liner systems. The country's national mining regulator enforces progressive tailings management codes that extend to slurry pipeline integrity requirements. Santiago-based procurement teams specify polyurethane blends for oil-contaminated tailings applications where hydrocarbon exposure degrades conventional compounds.
Brazil
Iron ore operations in Minas Gerais state depend on a narrow import base for engineered rubber compounds, exposing maintenance schedules to currency-driven supply interruptions. ANVISA industrial safety frameworks align with mining sector equipment certification requirements. Belo Horizonte engineering hubs at Vale centralize liner specification authority across South American operations.
China
Domestic cement and coal sectors generate compliance-driven replacement demand under tightening GB standards for industrial bulk handling equipment. MEE environmental enforcement extends to dust control mandates in material transfer operations. The Yangtze River Delta concentration of heavy industry drives specification of fire-resistant grades for port bulk terminals and power plant coal handling systems.
United States
Aggregate processors across the Mountain West and Southwest adopt sensor-integrated liners that signal wear depth for predictive replacement scheduling. OSHA workplace safety mandates and EPA dust control regulations enforce minimum durability standards that reduce maintenance hazards. Denver and Phoenix engineering clusters serve as specification hubs for quarry automation systems that compress traditional calendar-based replacement cycles.
Rubber Wear Liners Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material formulation sophistication and application engineering depth. The market structures around three tiers: vertically integrated mining technology conglomerates with captive foundry-to-liner supply chains; specialized elastomer compounders with advanced polyurethane blending capabilities; and regional fabricators bonding imported sheet stock to locally sourced steel substrates. Dominant competitive moves include backward integration into polymer feedstock processing and geographic expansion through regional stocking locations that compress replacement part lead times.
Among the integrated mining technology providers, Metso Outotec occupies a position exemplifying captive supply chain control over high-wear installations. Specialized elastomer compounders are represented by Trelleborg, which anchors the advanced polyurethane segment where oil resistance specifications displace natural rubber in slurry pipeline applications. Weir Group sits within the application-specific design tier, anchoring competitive positioning through engineered solutions for SAG mill discharge grates and grinding circuit protection zones.
| Leading Market Players |
|---|
| Metso Outotec |
| Trelleborg |
| Weir Group |
| Rema Tip Top |
| FLSmidth |
| Saint-Gobain |
| Bridgestone Corporation |
| Multotec |
| Tega Industries |
| Others |
Value Network & Pricing Analysis
Malaysian SMR 20 natural rubber futures volatility cascades through three distinct pricing tiers as commodity-grade fabricators absorb feedstock swings while engineered compounders lock in multi-year offtake agreements with Southeast Asian latex processors. This divergence concentrates margin pressure on regional bonding shops dependent on spot-market sheet stock while vertically integrated suppliers extract premium pricing through captive polymer supply.
Pricing Analysis
Throughput-guarantee contracts anchor value-based pricing for premium engineered liners, with Metso Outotec and Trelleborg bundling replacement intervals into per-ton processing fees rather than unit sales. Price differentiation separates REACH-certified European formulations from commodity Asian imports, with certification grade and volume scale as twin levers. Cost compression in the standard tier is intensifying because Brazilian import duties on bonded assemblies squeeze mid-market fabricators. Aggregate processors in North America exhibit highest price sensitivity due to project-based procurement, while Pilbara iron ore operators prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from BHP and Vale force qualified suppliers to maintain parallel polymer feedstock relationships across Malaysia, Thailand, and Indonesia. Raw material dependencies center on natural rubber latex, steel bonding plate, and curative chemical packages. Single-source vulnerability concentrates in steel substrate supply for Chilean fabricators, where Antofagasta port congestion intermittently disrupts bonding-grade plate delivery. Distribution runs through direct manufacturer field engineering teams for high-wear mining installations, with regional distributors serving mid-tier replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rubber wear liners market is consolidating around backward integration into polymer feedstock processing as the decisive competitive lever, with captive latex supply separating premium compounders from price-taken fabricators.
For Market Incumbents: Cement specification authority by embedding wireless wear sensors into liner systems, converting hardware sales into predictive maintenance subscriptions. Invest in REACH-compliant curative formulation R&D to outpace European regulatory timelines. Capacity addition in Perth and Belo Horizonte engineering hubs compresses response times for tier-one mining accounts facing accelerated replacement cycles from ore grade degradation. For New Entrants and Emerging Players: Launch via modular bolt-in segment designs targeting Peruvian copper concentrators seeking maintenance window compression. Quarry automation in the US Mountain West represents the most penetrable white space, with sensor-integrated liners commanding specification gaps left by incumbent commodity suppliers. A technical service partnership model with regional steel fabricators bypasses capital-intensive bonding infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized polyurethane compounders with proven oil-resistance formulations in Chile's Antofagasta corridor, where steel substrate shortages constrain domestic competition. Long-term viability hinges on regulatory chemistry adaptation capacity rather than scale economics. The signal to watch is ECHA's expansion of N-nitrosamine restrictions to accelerator packages beyond current Annex XVII scope.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstock | Captive latex supply from Malaysian processing estates locks in formulation cost stability against SMR 20 volatility. |
| Sensor-Embedded Liner Development | Wireless thickness monitoring pilots at Rio Tinto's Pilbara operations validate predictive replacement business models. |
| REACH-Compliant Curative Reformulation | ECHA substance restriction alignment opens Swedish and Finnish mining procurement channels closed to non-certified competitors. |
| Regional Bonding Capacity Expansion | Perth and Belo Horizonte fabrication hubs compress lead times for Australian and Brazilian concentrator maintenance windows. |
| Modular Bolt-In System Design | Segmented liner architectures reduce installation downtime, penetrating Peruvian copper operations with severe maintenance scheduling constraints. |
Research Methodology
Independent corroboration across maintenance directors at Pilbara iron ore operations, procurement leads at Chilean copper concentrators, and technical R&D directors at European elastomer compounders underwrites the qualitative findings. Primary fieldwork with aftermarket service heads and plant engineers in Brazil's Minas Gerais state combined with secondary validation from customs trade data, mining sector maintenance expenditure disclosures, and ECHA regulatory filings. Bottom-up unit demand modeling triangulates against top-down mining capital equipment spend allocation across the analysis window.
Rate-of-change decomposition separates volume effects from price-mix shifts across material grade tiers, application intensity bands, and regional regulatory clusters. Segmentation dimensions span natural rubber versus polyurethane versus synthetic elastomer formulations, mining versus aggregate processing versus construction end-uses, and direct sales versus distributor channel structures. CAGRs derive from replacement cycle compression rates tied to ore grade degradation trajectories and quarry automation penetration curves, with polymer feedstock price elasticity as a cross-cutting sensitivity input.
Natural rubber harvest volatility, REACH regulatory expansion timelines, and mining maintenance budget cyclicality are the dominant revision risks. Deviation in Malaysian latex supply disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Acrylic Rubber Market
Rubber
Plastomers Market
Rubber
Rubber Sand Market
Rubber
Tire Recycling Downstream Products Market
Rubber
Nitrile Butadiene Rubber (NBR) Latex Market
Rubber
Chloroprene Rubber Modified Asphalt Emulsion Market
Rubber
Rubber Plated Hose Market
Rubber
Performance Elastomers Market
Rubber
Snap on Rubber Stopper Market
Rubber
Global Rubber Vulcanization Market
Rubber
Rubber Sheets Market
Rubber
Rubber Masterbatch Market
Rubber
Global Hydraulic Rubber Hose Market
Rubber
Tire Reinforcement Materials Market
Rubber
Rubber Carbon Black Market
Rubber
Rubber Flooring Market