
 Middle East and Africa Flock Adhesives Market | 2026-2036
Middle East and Africa Flock Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Flock Adhesives Market Foresight
Subscription-based technical service contracts for adhesive application equipment is hardening as a revenue layer alongside raw material sales. Henkel AG & Co. KGaA leverages its regional technical centers to anchor aftermarket service relationships with automotive tier suppliers. H.B. Fuller Company competes through localized blending operations that sustain shorter lead times for solvent-based formulations across North African markets. Sika AG specializes in construction-grade flock systems, dominating specification-driven projects in Gulf commercial interiors.
Flock adhesives are fiber-bonding systems, typically formulated from polyurethane, acrylic, or epoxy chemistries with viscosities engineered between 500 and 5000 centipoise for controlled fiber embedding. They function to create velvet-like textured surfaces on substrates ranging from automotive plastics to woven textiles, providing abrasion resistance and tactile properties. Water-based formulations now lead volume share due to tightening volatile organic compound limits, while reactive systems represent the fastest-expanding margin pool as automotive OEMs specify higher durability grades. Hot melt technology occupies the cost-sensitive packaging and toy segments where rapid line speeds override premium performance requirements.
South Africa's National Regulator for Compulsory Specifications enforces adhesive labeling and volatile organic compound thresholds that shape import compliance costs for European and Asian suppliers. Saudi Standards, Metrology and Quality Organization (SASO) technical regulations for building materials indirectly govern flock adhesive performance in interior finishing applications across Gulf Cooperation Council markets. Egypt's environmental compliance directives for industrial chemicals are tightening discharge standards for solvent-based adhesive manufacturing near the Nile Delta chemical corridor. Stakeholders must monitor divergent national certification timelines to optimize regional formulation portfolios without fragmenting supply chains.
Market Dynamics
REACH-aligned chemical compliance is forcing formulation redesigns across imported adhesive systems, while water-based chemistry transitions accelerate procurement requalification cycles for automotive tier suppliers in the Gulf States.
Growth Catalysts
- Automotive Interior Specifications:Premium seating and dashboard applications across Saudi Arabia and the UAE are expanding flock adhesive volumes as OEMs specify higher tactile grades.
- REACH Compliance Harmonization:European chemical standards are reshaping import requirements, creating competitive openings for suppliers with pre-certified water-based portfolios.
- Textile Finishing Expansion:Nigeria's emerging garment sector is adopting flocking for velvet-like surface treatments on synthetic fabrics.
Market Restraints
- Solvent Raw Material Volatility:Petrochemical feedstock fluctuations compress margins for polyurethane-based formulations manufactured near the Nile Delta.
- Import Concentration Risk:Specialty resin supply chains remain anchored to European and Asian chemical producers, exposing North African blenders to currency-driven cost spikes.
- Technical Performance Gaps:Water-based systems still fail to match solvent-grade durability in high-temperature automotive underhood applications.
Strategic Opportunities
- Egyptian Manufacturing Localization:Tightening discharge standards are incentivizing captive blending capacity near the Nile Delta chemical corridor.
- Construction Interior Applications:Commercial fit-out projects across Gulf Cooperation Council markets are specifying flock-finished wall panels and ceiling systems.
- Reactive System Convergence:Epoxy-acrylic hybrid chemistries are opening margin pools in automotive exterior trim segments previously closed to flocking.
Industry Challenges
- Application Equipment Technician Scarcity:Electrostatic flocking line operators with precision viscosity calibration skills command premium wages in South Africa's Eastern Cape cluster.
- Multi-Jurisdiction Certification Timelines:Divergent national labeling requirements between SASO, South Africa's National Regulator for Compulsory Specifications, and Egyptian environmental directives fragment quality assurance workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Flock Adhesives Market |
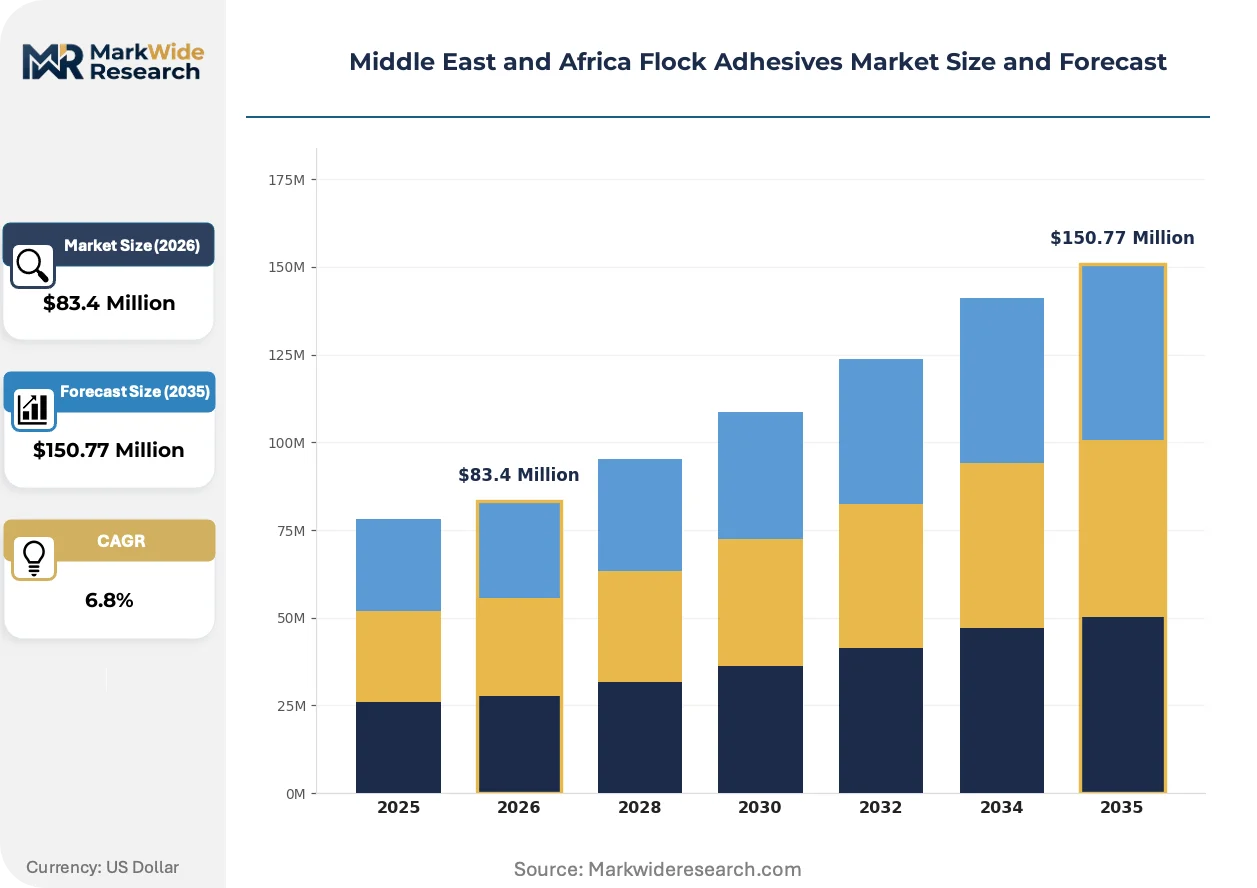
| Market Size in 2026 | $83.4 Million |
| Market Size in 2035 | $150.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Hot Melt, Reactive End User: Textiles, Automotive, Packaging, Construction Application: Upholstery, Wall Coverings, Footwear, Toys Technology: Dispersion, Coating, Spraying, Laminating |
| Companies Covered | Henkel AG & Co. KGaA, H.B. Fuller Company, Sika AG, Dow, Arkema Group, Bostik SA, Huntsman International LLC, Illinois Tool Works Inc., The Industrial Group Ltd., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Flock Adhesives Market Shifts & Advancements
Formulation chemistry is pivoting toward reactive and water-based platforms as regulatory thresholds tighten, while service-based revenue models are anchoring supplier relationships in automotive supply chains.
UV-curable flock adhesives are rewriting application economics for high-speed textile finishing lines. Turkish and Egyptian carpet manufacturers are piloting these systems to eliminate thermal drying stages. The technology is compressing energy costs and floor space requirements for mid-volume producers.
SASO technical regulations for building materials are tightening performance verification for interior finishing adhesives. Gulf-based contractors now demand batch-specific test reports before specification lock-in. Construction-grade flock system suppliers are responding by embedding third-party certification into standard product documentation.
Subscription technical service contracts are displacing transactional equipment support in automotive tier supply relationships. Tier 1 seating manufacturers in the UAE and Saudi Arabia now bundle adhesive procurement with application line maintenance agreements. This pattern concentrates procurement authority with suppliers capable of field engineering deployment.
Middle East and Africa Flock Adhesives Market Segmentation
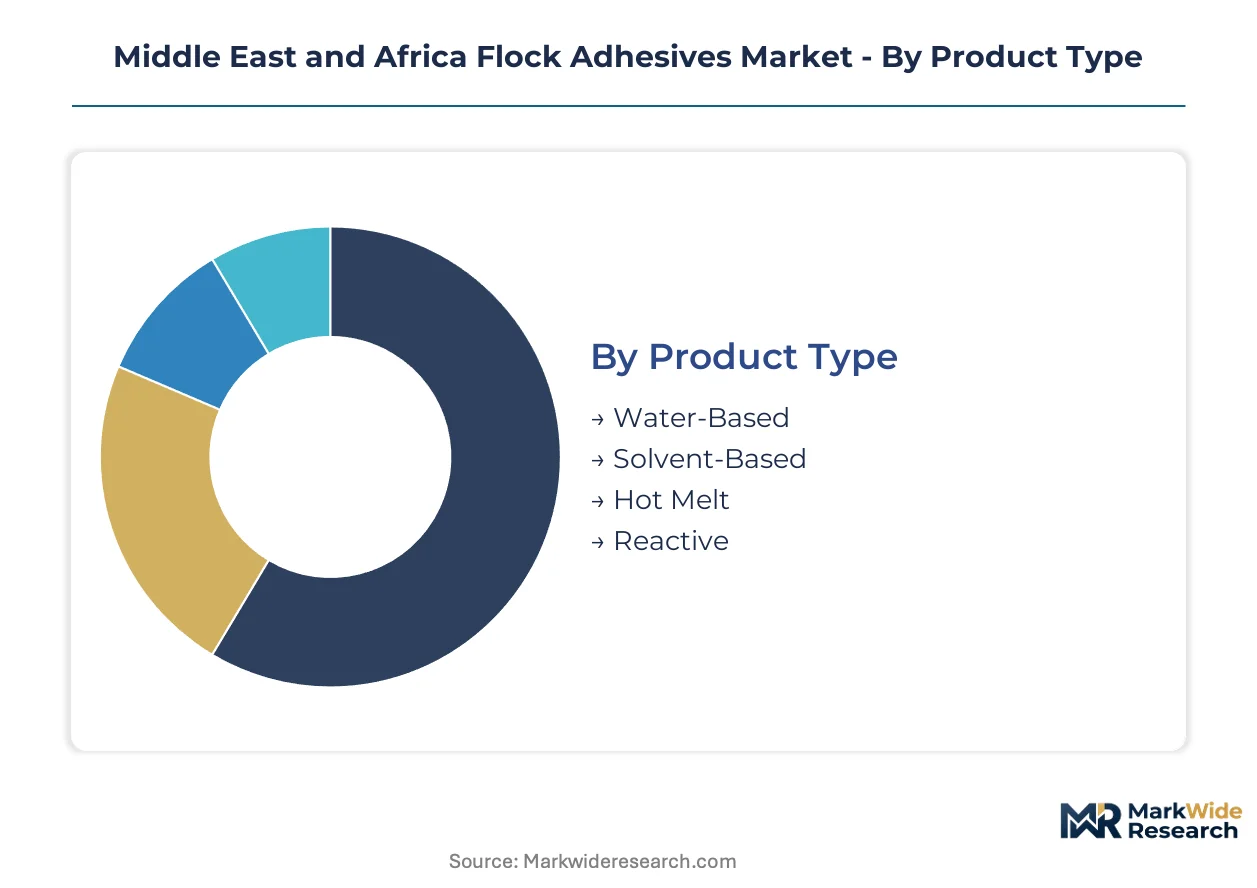
Flock adhesive procurement decisions across the Middle East and Africa diverge sharply by chemistry cost and regulatory tolerance. Buyers in automotive and construction segments prioritize compliance-ready formulations, while textile and packaging operators optimize for line speed and energy efficiency.
Product Type:
Price-performance tradeoffs and volatile organic compound exposure dominate chemistry selection across Egyptian blending facilities and Gulf automotive plants.
- Water-Based:Acrylic and polyurethane dispersions with sub-50 g/L VOC content anchor procurement for Saudi and UAE automotive interior specifications. Egyptian carpet manufacturers are converting drying lines to accommodate extended cure cycles in exchange for discharge compliance.
- Solvent-Based:High-solids polyurethane formulations retain specification in high-temperature automotive underhood applications where water-based durability remains insufficient. Nile Delta blenders face margin compression from petrochemical feedstock volatility and tightening environmental discharge standards.
- Hot Melt:Ethylene-vinyl acetate and polyolefin systems serve Nigerian toy manufacturers and Gulf packaging converters requiring rapid line speeds without thermal curing stages.
- Reactive:Epoxy-acrylic and polyurethane hybrids command premium positioning in exterior automotive trim segments. South African Eastern Cape suppliers are qualifying these systems for dashboard applications previously closed to flocking.
Volume sits with water-based chemistry; growth tilts toward reactive systems.
End User:
Application durability requirements and specification authority concentrate demand in distinct buyer clusters across the region's industrial corridors.
- Automotive:Tier 1 seating and dashboard manufacturers in Saudi Arabia and the UAE specify REACH-aligned adhesive grades with batch certification. Technical service contracts now bundle adhesive supply with electrostatic flocking line maintenance.
- Textiles:Nigerian garment finishers and Turkish-Egyptian carpet producers drive adoption of UV-curable platforms to eliminate thermal drying. Energy cost compression and floor space reduction motivate chemistry transitions.
- Construction:Gulf Cooperation Council commercial fit-out contractors specify flock-finished wall panels and ceiling systems. SASO technical regulations mandate batch-specific test reports before specification lock-in.
- Packaging:Cost-sensitive box and display manufacturers prioritize hot melt systems with minimal viscosity drift across ambient temperature variations in North African logistics corridors.
Automotive commands the highest specification barriers; textile processing expands most quickly.
Application:
Surface area coverage rates and tactile grade requirements determine adhesive viscosity engineering and fiber embedding depth protocols.
- Upholstery:Premium seating applications across Saudi and UAE automotive plants demand 500-1500 centipoise viscosity ranges for controlled nylon fiber embedding. Abrasion resistance testing under SAE standards governs qualification timelines.
- Wall Coverings:Commercial interior projects in Dubai and Riyadh specify flock-finished panels for acoustic dampening and aesthetic texture. Contractors require third-party certification embedded in standard product documentation.
- Footwear:Synthetic leather finishing in South Africa's Eastern Cape supplier cluster employs medium-viscosity systems for velvet-like surface treatments on shoe uppers and linings.
- Toys:Nigerian and Egyptian manufacturers utilize hot melt flocking for rapid production of textured plastic figures and educational products where regulatory scrutiny remains lighter than automotive or construction segments.
Upholstery carries the most stringent performance requirements; wall coverings gain share fastest in Gulf commercial construction.
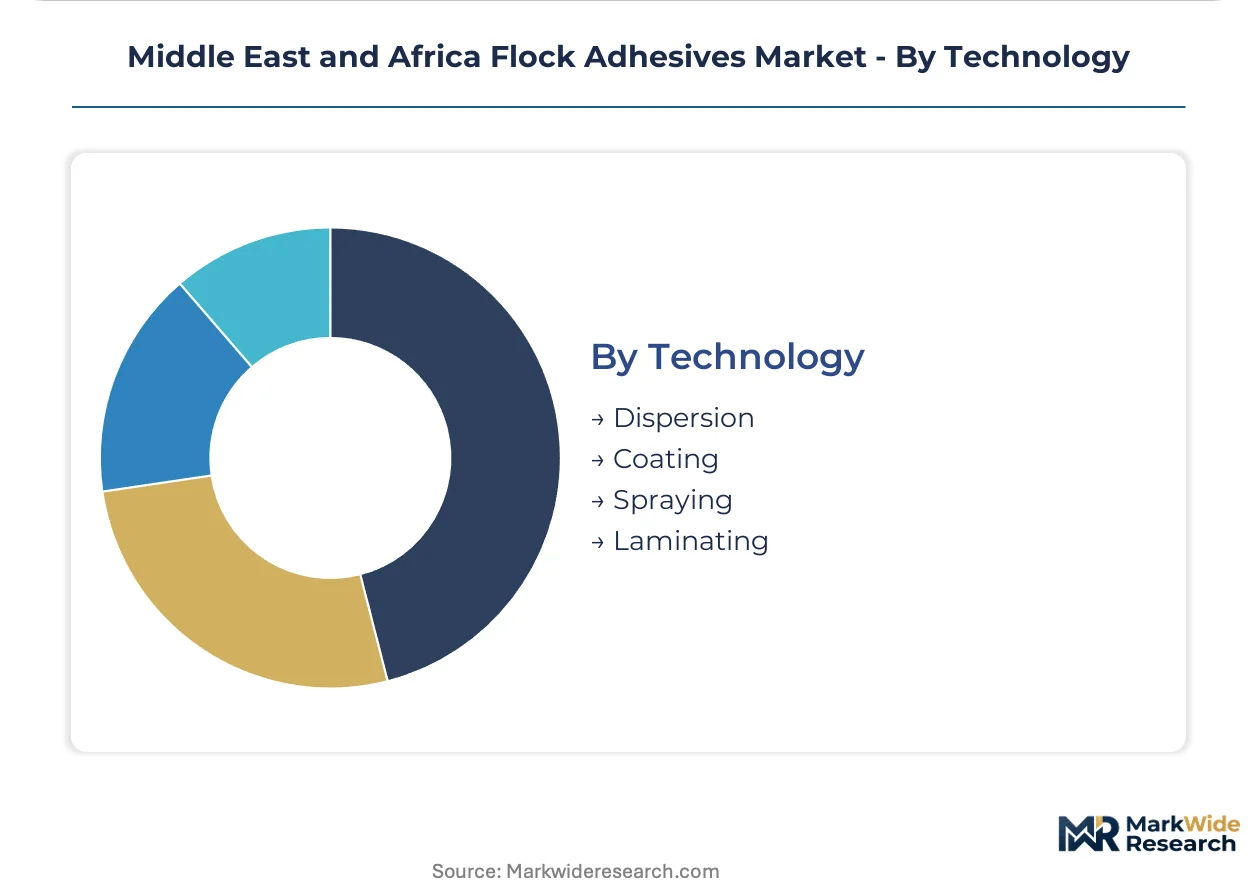
Technology:
Capital equipment availability and technician skill density shape application method adoption across regional manufacturing clusters.
- Dispersion:Water-based and solvent adhesive delivery through gravure or knife-over-roll systems dominates textile finishing in Egypt and Nigeria. Viscosity calibration precision separates qualified operators from commodity competitors.
- Coating:Direct roll application serves high-volume automotive interior production in South Africa's Eastern Cape. Surface preparation protocols and film thickness uniformity determine fiber adhesion strength.
- Spraying:Automated electrostatic spray systems enable complex three-dimensional automotive trim coverage. UAE and Saudi Tier 1 suppliers invest in robotic line integration to reduce technician dependency.
- Laminating:Continuous belt lamination supports carpet backing and wall panel production in Turkish-Egyptian manufacturing corridors. Line speed and thermal profile optimization compress unit economics for mid-volume producers.
Coating holds current volume leadership; spraying climbs the fastest as automotive automation deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle East and Africa Flock Adhesives Market exhibits a pronounced production-consumption divide. Gulf States import specialty resin feedstocks while operating localized blending facilities. North African chemical corridors process petrochemical derivatives into finished adhesive formulations.
Saudi Arabia
Tier 1 automotive seating manufacturers in Riyadh and Jeddah specify REACH-aligned water-based adhesives for premium interior applications. SASO technical regulations for building materials mandate batch-specific test reports for construction-grade flock systems. The Eastern Province industrial corridor hosts electrostatic flocking line installations serving dashboard and trim producers.
United Arab Emirates
Commercial fit-out contractors in Dubai and Abu Dhabi specify flock-finished wall panels for acoustic dampening in luxury developments. MOHAP chemical registration requirements govern adhesive imports for interior finishing applications. Jebel Ali free zone concentration enables re-export blending operations serving Gulf Cooperation Council markets.
South Africa
Eastern Cape automotive supplier clusters employ medium-viscosity systems for synthetic leather finishing on shoe uppers and vehicle upholstery. The National Regulator for Compulsory Specifications enforces adhesive labeling and volatile organic compound thresholds that shape import compliance costs. Port Elizabeth manufacturing corridors concentrate precision viscosity calibration technicians commanding premium wages.
Egypt
Nile Delta carpet manufacturers pilot UV-curable platforms to eliminate thermal drying stages and compress energy costs. Environmental compliance directives tighten discharge standards for solvent-based adhesive manufacturing near the chemical corridor. Alexandria and Damietta port zones facilitate resin importation for captive blending capacity expansion.
Nigeria
Emerging garment finishers in Lagos and Kano adopt flocking for velvet-like surface treatments on synthetic fabrics. The country's national industrial chemical regulator is developing framework standards for adhesive importation and local blending. Apapa port logistics corridors concentrate hot melt system distribution for toy and packaging manufacturers.
Middle East and Africa Flock Adhesives Market Competitive Landscape
Top-tier vendors anchor specification-driven automotive and construction segments, while regional blenders compete on lead-time compression for solvent-based formulations. Market structure tilts toward consolidation in premium reactive systems and fragmentation in commodity hot melt supply. Three archetypes dominate: European chemical majors with pre-certified water-based portfolios, North African blenders leveraging Nile Delta petrochemical feedstock access, and Gulf-based technical service integrators bundling adhesive supply with application equipment maintenance. Competitive moves concentrate on M&A for reactive technology access and strategic partnerships for SASO pre-certification pathways.
Among European-headquartered suppliers, Henkel AG & Co. KGaA and H.B. Fuller Company exemplify the technical service archetype, anchoring aftermarket relationships through regional technical centers and localized blending operations. Sika AG occupies a position representing construction-grade specialization, with specification authority in Gulf commercial interior projects. These three entities collectively illustrate the tiered competitive structure: chemical majors with compliance-ready portfolios, regional blenders with feedstock proximity, and application-integrated service providers.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Sika AG |
| Dow |
| Arkema Group |
| Bostik SA |
| Huntsman International LLC |
| Illinois Tool Works Inc. |
| The Industrial Group Ltd. |
| Others |
Supply & Pricing Matrix
UV-curable platform adoption across Turkish-Egyptian carpet manufacturing corridors simultaneously compresses thermal energy costs and concentrates formulation supply among European chemical majors with certified resin portfolios. This technology transition rewards REACH-aligned suppliers while marginalizing Nile Delta blenders dependent on solvent-based discharge permits.
Pricing Analysis
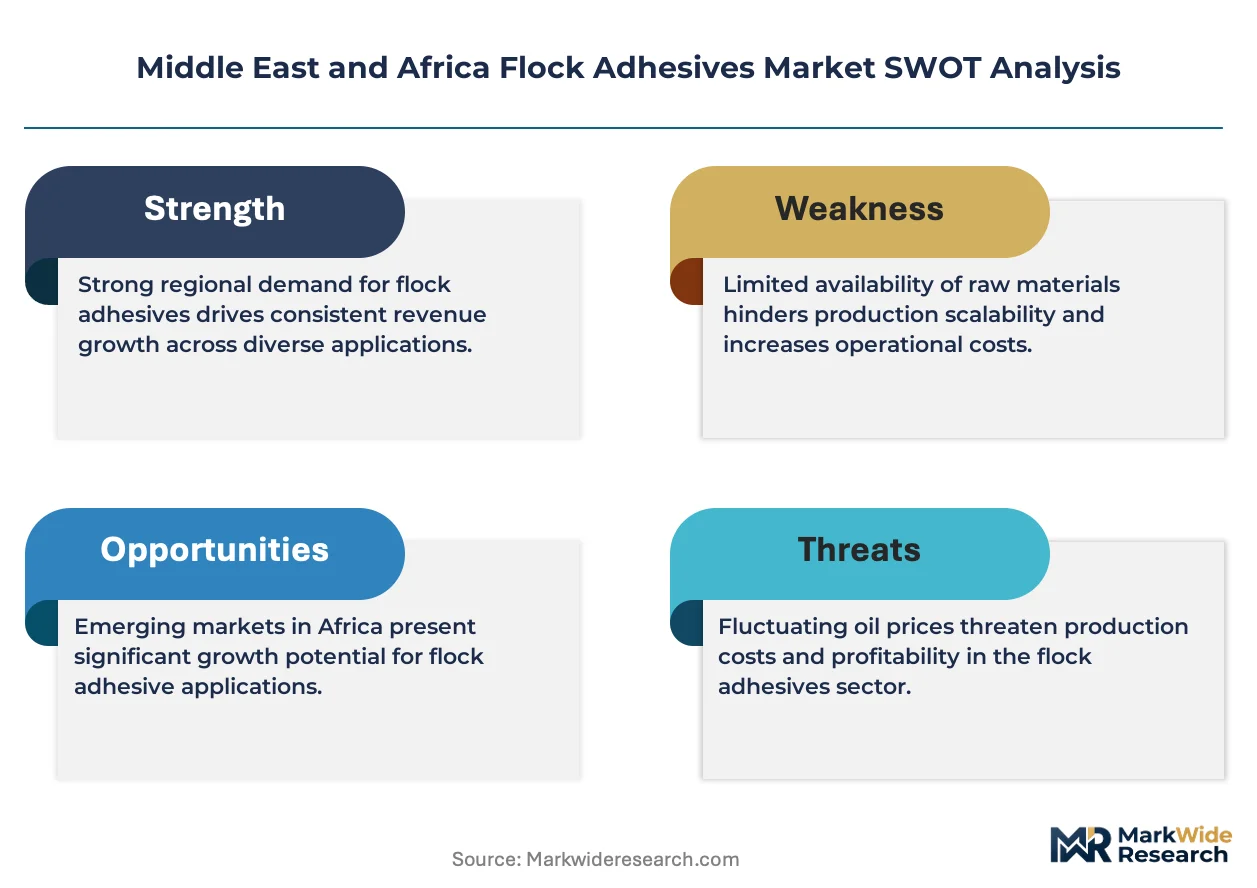
Margin tightening in water-based automotive grades reflects petrochemical feedstock volatility and SASO pre-certification investment recovery timelines. Three-tier pricing structure across premium reactive, standard water-based, and economy hot melt levels separates specification authority in Gulf automotive interiors from cost-optimized Nigerian packaging applications. REACH compliance investment elevates European supplier positioning while Egyptian blenders face pricing softness from currency-driven import cost spikes. Construction-grade buyers in Dubai commercial fit-out projects demonstrate lowest price sensitivity due to batch-specific third-party certification requirements.
Supply Chain Analysis
Precision viscosity calibration technician scarcity in South Africa's Eastern Cape automotive cluster elevates wage costs and constrains electrostatic flocking line expansion. Specialty resin feedstocks draw from German and Belgian chemical producers, with Nile Delta blending facilities processing petrochemical derivatives into finished formulations. Single-source vulnerability concentrates in European epoxy-acrylic hybrid resin supply for reactive automotive exterior trim applications. Distribution runs through Jebel Ali free zone re-export hubs serving Gulf Cooperation Council markets and Alexandria-Damietta port corridors for Egyptian captive blending capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around REACH-aligned formulation portfolios as SASO technical regulations and Egyptian discharge standards force solvent-dependent blenders toward exit or acquisition.
For Market Incumbents: To counter emerging regional blenders with Nile Delta petrochemical feedstock proximity, anchor procurement relationships through subscription technical service contracts bundling adhesive supply with electrostatic flocking line maintenance. Deepen backward integration into water-based acrylic dispersion capacity within Gulf free zones to compress lead times for Saudi and UAE automotive tier suppliers. For New Entrants and Emerging Players: Direct-to-technical-buyer digital channels bypass established distributor relationships in Nigerian garment finishing and Egyptian carpet manufacturing segments. Target UV-curable platform adoption in Turkish-Egyptian manufacturing corridors where energy cost compression motivation exceeds brand loyalty to incumbent suppliers. Position through application equipment leasing bundled with formulation supply to reduce capital barriers for mid-volume textile producers. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to European chemical majors seeking REACH-certified regional production footprints. Long-term viability hinges on water-based and reactive chemistry transition completion before Egyptian environmental discharge standards tighten further. Monitor SASO batch-specific test report mandate enforcement as inflection indicator for construction-grade specification authority consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Dispersion Capacity | Gulf-based captive production compresses lead times for Saudi automotive interior specifications. |
| Long-term Supply Agreement with Tier 1 Seating Manufacturers | UAE and Saudi procurement bundling locks out competitors without field engineering deployment. |
| Joint Venture with Nile Delta Petrochemical Processors | Egyptian blending localization navigates tightening discharge standards near chemical corridors. |
| Green Manufacturing Transition to UV-Curable Platforms | Turkish-Egyptian carpet manufacturers eliminate thermal drying stages and energy cost exposure. |
| Acquisition of Reactive Technology Specialist | Epoxy-acrylic hybrid access opens exterior automotive trim segments previously closed to flocking. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with adhesive plant managers, automotive Tier 1 procurement leads, electrostatic flocking line operators, distribution channel partners, and technical R&D directors. Bottom-up volume modeling triangulated against top-down macroeconomic indicators derived from SASO technical regulations, Egyptian environmental compliance directives, and South African National Regulator for Compulsory Specifications enforcement patterns.
Granularity-level modeling captured chemistry type, end-use industry, application method, and regional production hub dimensions across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by petrochemical feedstock cost indices and automotive OEM specification timelines. Industry-specific inputs included REACH-aligned formulation certification penetration rates and UV-curable platform adoption curves in Turkish-Egyptian carpet manufacturing corridors.
The model holds under stable regulatory enforcement timelines; deviation in SASO batch-testing mandate acceleration or Egyptian discharge standard tightening would shift reactive system premium capture and water-based conversion rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Conductive Adhesive Market
Adhesives & Sealants
Structural Sealants Market
Adhesives & Sealants
Europe Bone Glue Market
Adhesives & Sealants
Bio-Based Adhesives Market
Adhesives & Sealants
Water-Borne Adhesives Market
Adhesives & Sealants
Wearable Skin Adhesives Market
Adhesives & Sealants
US Pressure Sensitive Adhesives Market
Adhesives & Sealants
Asia-Pacific Polyurethane Adhesives Market
Adhesives & Sealants
Rubber Repair Adhesives Market
Adhesives & Sealants
Tile Adhesive Market
Adhesives & Sealants
Europe Polyurethane Adhesives Market
Adhesives & Sealants
Asia-Pacific Epoxy Adhesive Market
Adhesives & Sealants
Metal Glue Market
Adhesives & Sealants
Curing Adhesives Market
Adhesives & Sealants
Dispersion Adhesives Market
Adhesives & Sealants
Wood Glue Market