
 Isoprene Rubber Market | 2026-2036
Isoprene Rubber Market Size, Share, and Industry Trends Forecast 2026-2036
Isoprene Rubber Market Intelligence
The ISO 1629 nomenclature standard for rubber and latices is unwinding the historical separation between natural and synthetic isoprene sources, influencing material selection criteria for engineers. In this environment, The Goodyear Tire & Rubber Company leverages its vast tire manufacturing footprint for significant captive consumption of isoprene rubber. Kraton Corporation, in contrast, specializes in producing high-purity grades for sensitive applications like medical devices and specialty adhesives. PJSC SIBUR Holding competes on the basis of large-scale production capacity and integrated feedstock access.
Isoprene rubber is a synthetic polymer, chemically known as polyisoprene, designed to mimic the structure and properties of natural rubber. It exhibits high tensile strength, resilience, and tack, making it a primary substitute in demanding industrial applications. The market structure shows that high-cis isoprene rubber grades dominate due to their superior performance characteristics required in tire manufacturing. While tires constitute the largest application by volume, specialty adhesives and coatings represent high-value segments with distinct performance requirements.
Regulatory frameworks, including the US EPA's rules on volatile organic compound emissions and the EU's REACH chemical registration requirements, govern production and market access. In parallel, China's GB standards for tire safety and performance directly influence material specifications for domestic consumption. The central strategic decision for producers now revolves around allocating capital between expanding conventional petrochemical-based capacity and scaling up novel bio-isoprene manufacturing technologies.
Market Dynamics
The central structural force shaping the isoprene rubber market is the strategic tension between expanding conventional petrochemical capacity and investing in nascent bio-isoprene technologies, driven by corporate sustainability mandates and feedstock diversification pressures.
Growth Catalysts
- Bio-Based Feedstocks:The development of fermentation technologies to produce bio-isoprene from renewable sugars provides a sustainable alternative, meeting demand from companies with aggressive ESG targets and carbon reduction goals.
- Medical Sector Demand:Rising consumption in medical applications, particularly for high-purity surgical gloves and pharmaceutical stoppers, creates a high-value demand stream that is less cyclical than industrial uses.
- Automotive Growth in China:China's vast automotive industry and its position as the world's largest tire manufacturer create sustained, large-volume demand for high-cis isoprene rubber grades.
Market Restraints
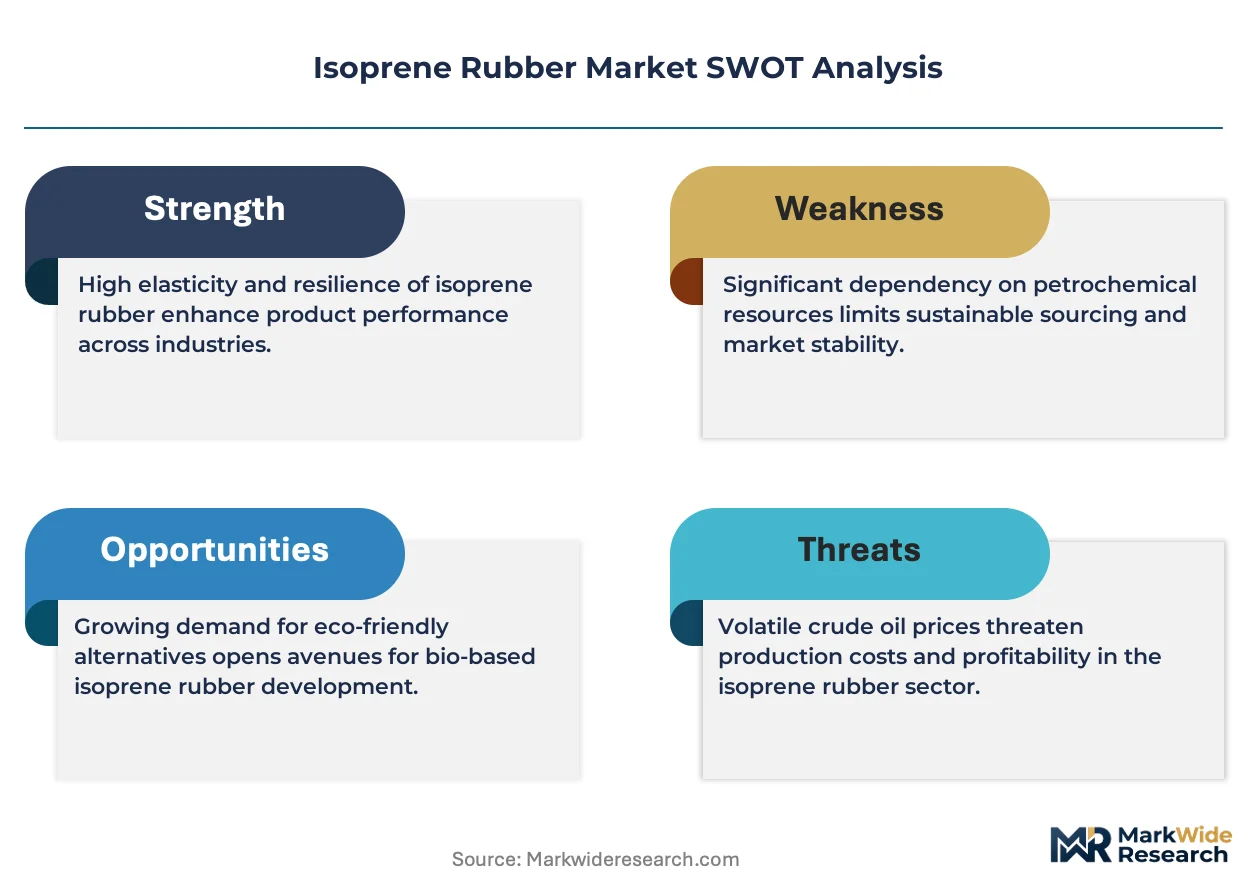
- Feedstock Price Volatility:The market remains highly sensitive to fluctuations in the price of petrochemical feedstocks like naphtha, which can compress producer margins and create price instability for end-users.
- Substitution from SBR:In certain tire applications, particularly for passenger car treads, high-performance grades of styrene-butadiene rubber (SBR) offer competitive performance characteristics, posing a substitution threat.
- European Regulatory Burden:Compliance with the EU's REACH framework requires extensive and costly chemical safety assessments and registration, creating market access barriers and increasing operational overhead for producers.
Strategic Opportunities
- Electric Vehicle Components:The unique vibration damping properties of isoprene rubber create opportunities for new applications in electric vehicle battery casings and motor mounts to reduce noise and enhance ride comfort.
- Southeast Asian Expansion:Underpenetrated markets in Vietnam and Thailand, with their growing automotive assembly and tire manufacturing sectors, present significant geographic expansion opportunities for isoprene rubber producers.
- Advanced Composite Materials:The combination of isoprene rubber with advanced nano-fillers like graphene or carbon nanotubes opens pathways to develop next-generation composites for demanding aerospace and defense applications.
Industry Challenges
- High Capital Intensity:Scaling production, whether through new greenfield petrochemical plants or pioneering bio-based fermentation facilities, requires substantial capital investment and long project lead times.
- Bio-Isoprene Standardization:The absence of globally harmonized standards for bio-based polyisoprene creates uncertainty for material specifiers, slowing adoption in conservative sectors like medical devices and aviation tires.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isoprene Rubber Market |
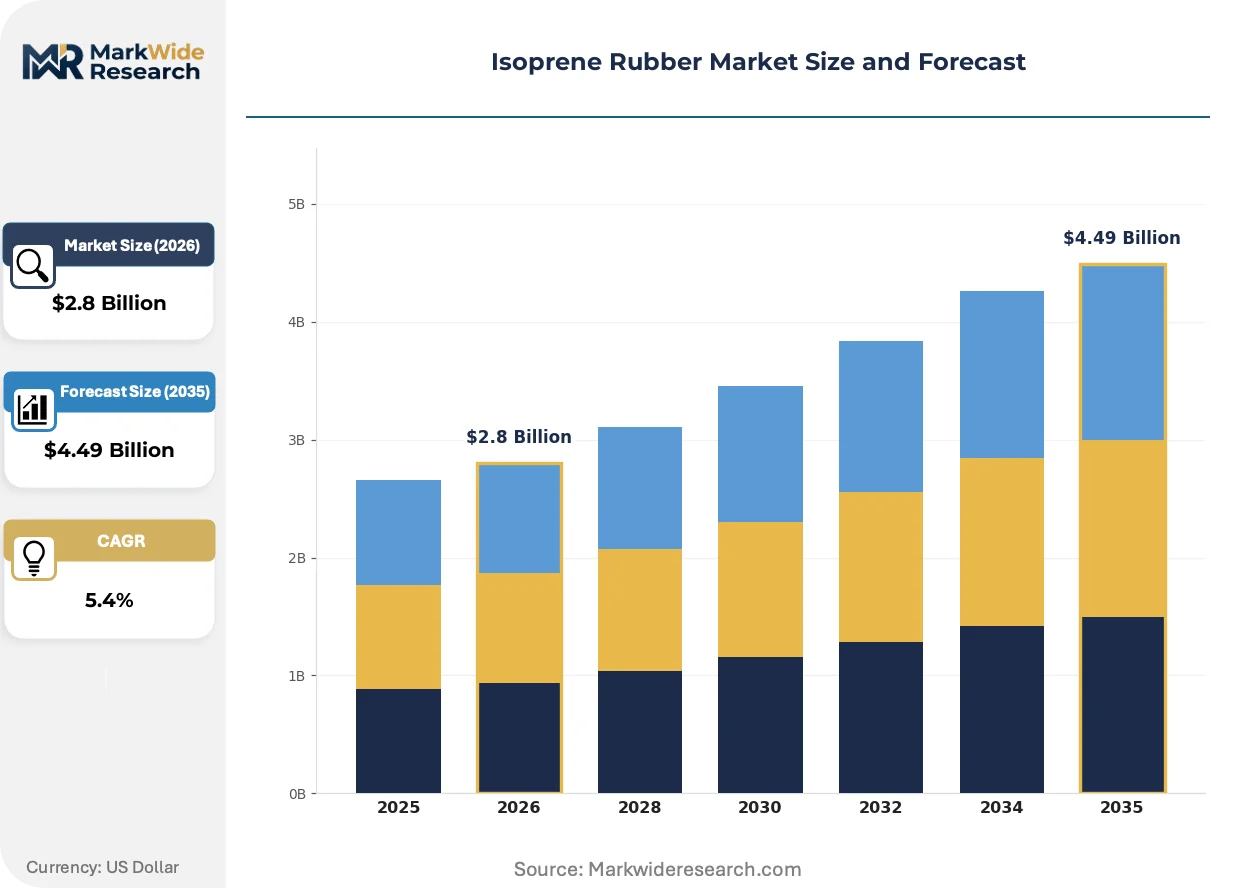
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Cis, Low Cis, Isobutylene Isoprene Rubber, Others End User: Automotive, Footwear, Adhesives, Medical Supplies Application: Tires, Seals, Gaskets, Coatings Form: Liquid, Solid, Powder, Granules |
| Companies Covered | Zeon Corporation, Kraton Corporation, Nizhnekamskneftekhim, Dow Chemical Company, Goodyear Tire & Rubber Company, PJSC SIBUR Holding, Kuraray Co., Ltd., Qingdao Yikesi New Material, JSR Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isoprene Rubber Market Strategic Shifts & Innovations
A fundamental bifurcation defines the market's evolution, pitting sustainability-driven material innovation against the entrenched performance and scale of petrochemical-based production. This dynamic is increasingly arbitrated by global regulatory frameworks and shifting end-user procurement criteria.
Bio-isoprene, produced via fermentation of renewable sugars, offers a chemically identical alternative to petroleum-derived isoprene. Tire manufacturers and medical device firms are adopting it to meet sustainability goals. This drop-in renewable material is supplanting conventional petrochemical feedstocks in premium applications where ESG metrics are a key purchasing criterion.
Regulatory mandates like the European Union's Corporate Sustainability Reporting Directive (CSRD) are forcing greater supply chain transparency. This directive requires companies to quantify and disclose the full lifecycle environmental impact of their products. Consequently, tire and medical device manufacturers now demand verifiable carbon footprint data from their polyisoprene suppliers.
Material specification criteria are evolving as engineers increasingly treat natural and synthetic polyisoprene as interchangeable under the ISO 1629 nomenclature. This change moves procurement decisions away from material origin and toward quantifiable metrics like purity, performance, and supply chain resilience. This trend is most prominent within the high-volume tire industries of China and India.
Isoprene Rubber Market Segmentation
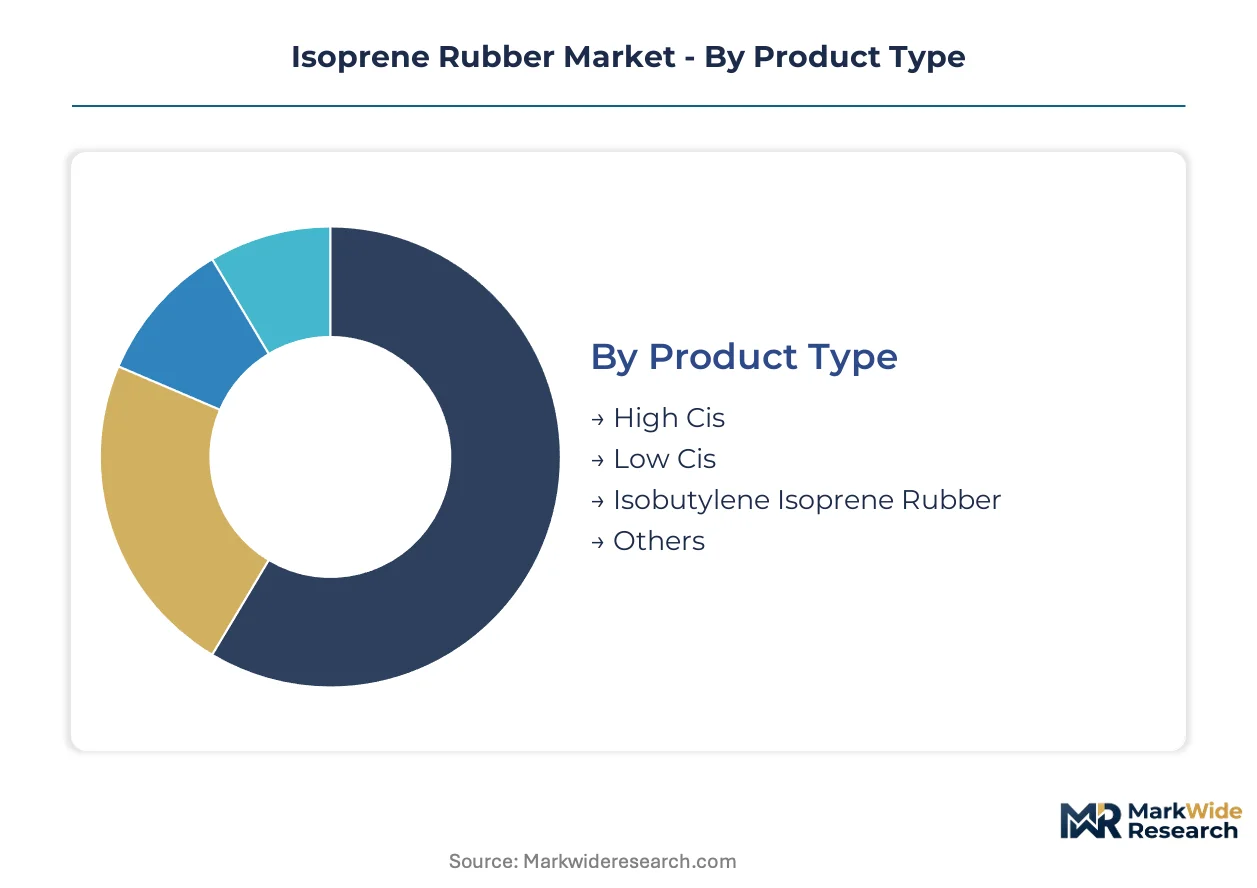
The Isoprene Rubber Market's segmentation reveals distinct demand patterns influencing production strategies and supply chain configurations. Understanding these categories is critical for producers to align product offerings with specific end-user requirements and regulatory compliance. Each segment exhibits unique performance criteria and market dynamics.
Product Type:
Isoprene rubber product types show varied geographic adoption, with certain grades dominating domestic markets in tire manufacturing hubs while others cater to specialized export niches.
- High Cis:High-cis isoprene rubber possesses a stereoregular molecular structure, providing excellent elasticity, high tensile strength, and superior dynamic properties. Demand concentrates in China's automotive industry for high-performance tire manufacturing, driven by stringent safety standards and vehicle production volumes.
- Isobutylene Isoprene Rubber:Isobutylene isoprene rubber, also known as butyl rubber, features low permeability to gases and high damping characteristics, making it suitable for sealing applications. Demand is significant in the US for pharmaceutical stoppers and inner tubes, where its gas barrier properties are critical for product integrity.
- Low Cis:Low-cis isoprene rubber offers good tack and processing characteristics, finding use in adhesives and general rubber goods.
- Others:This category includes modified polyisoprene variants and specialty grades tailored for specific industrial or medical applications.
High Cis commands the established base. The steepest expansion runs through Isobutylene Isoprene Rubber.
End User:
End-user segments reflect distinct volume requirements, ranging from high-volume industrial consumption to niche, high-purity medical applications.
- Automotive:The automotive sector utilizes isoprene rubber for tires, engine mounts, and seals, valuing its resilience, vibration dampening, and wear resistance. Demand is immense in China's vehicle production, where large-scale tire manufacturing consumes substantial volumes of high-cis grades.
- Medical Supplies:Medical supplies require high-purity isoprene rubber for applications like surgical gloves and pharmaceutical stoppers, prioritizing biocompatibility and elasticity. Demand is rising in Europe and the US, driven by increasing healthcare expenditure and stringent regulatory requirements for patient safety.
- Footwear:The footwear industry employs isoprene rubber for shoe soles and components, benefiting from its flexibility and abrasion resistance.
- Adhesives:Adhesives utilize isoprene rubber for its tack and bonding properties, particularly in pressure-sensitive and solvent-based formulations.
Automotive applications represent the largest volume concentration. Medical Supplies exhibit the most rapid value expansion.
Application:
Applications for isoprene rubber span mature, established uses alongside nascent, technologically advanced integrations.
- Tires:Tires represent the primary application for isoprene rubber, leveraging its high resilience, low heat buildup, and excellent traction properties for vehicle performance. Volume demand is anchored in Southeast Asia's tire manufacturing sector, particularly for heavy-duty and off-road vehicle tires.
- Coatings:Isoprene rubber in coatings provides flexibility, water resistance, and adhesion, enhancing the durability and protective qualities of surface finishes. Demand is emerging in Europe for specialized industrial protective coatings, driven by performance requirements in harsh environments.
- Seals:Seals use isoprene rubber for its excellent compression set, resistance to tearing, and effective barrier properties in fluid systems.
- Gaskets:Gaskets utilize isoprene rubber for its ability to create tight seals, withstand temperature variations, and resist chemical degradation in mechanical assemblies.
Tires remain the foundational application. Coatings demonstrate significant innovation potential.
Form:
The forms of isoprene rubber dictate supply chain logistics, with bulk commodity forms contrasting with specialized, high-purity variants.
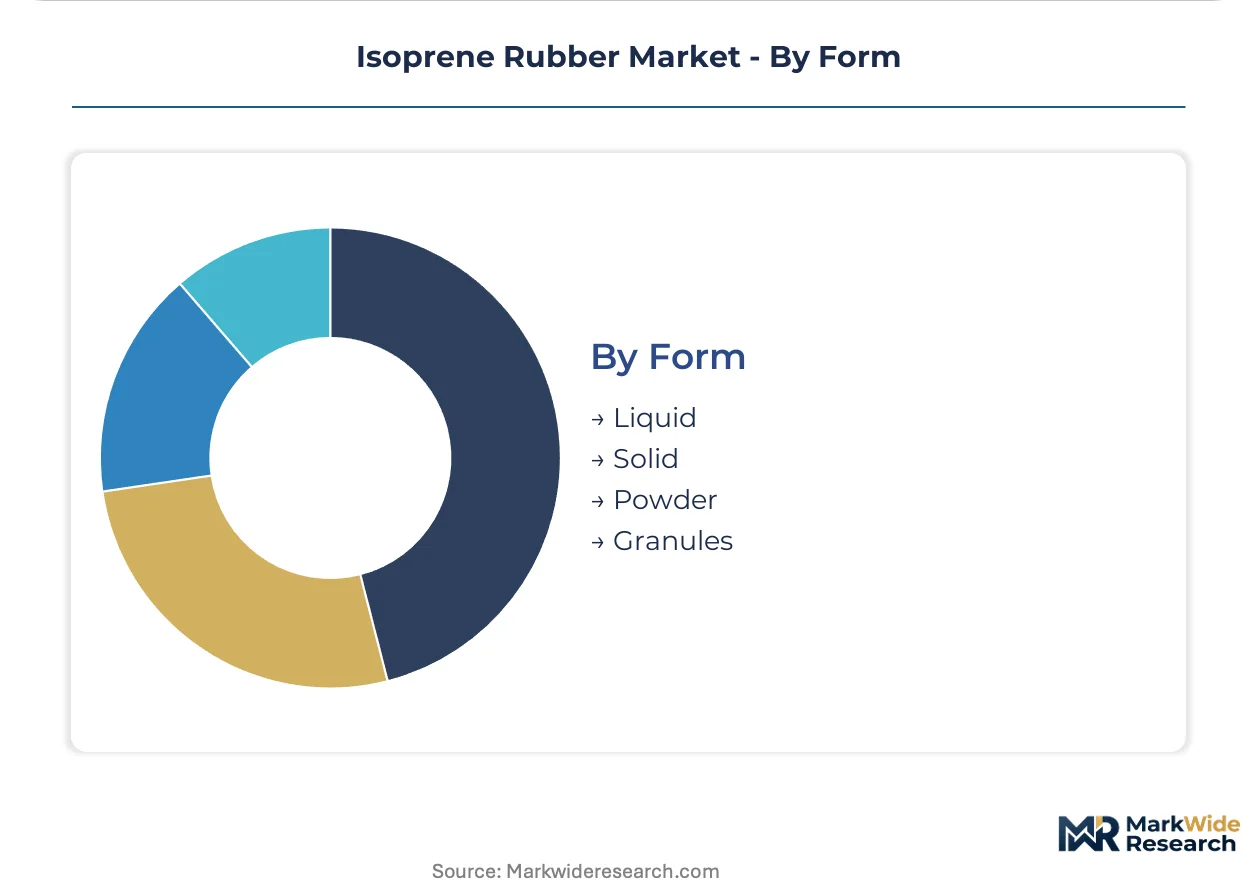
- Solid:Solid isoprene rubber, typically supplied in bales, is the most common form, requiring mastication before compounding for various industrial applications. Demand is concentrated in large-scale rubber product manufacturing facilities in India, where it serves as a primary raw material.
- Granules:Granular isoprene rubber offers improved handling and dispersion characteristics, reducing processing times and energy consumption in mixing operations. Demand is increasing in the US for automated compounding lines in tire and mechanical goods production, seeking efficiency gains.
- Liquid:Liquid isoprene rubber is utilized in specialty adhesives and sealants, providing excellent flow properties and high tack.
- Powder:Powdered isoprene rubber finds niche applications in compounding where fine dispersion and specific rheological properties are required.
Solid forms dominate current consumption. Granules offer enhanced processing efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global policies promoting sustainable manufacturing significantly influence isoprene rubber market dynamics. Regulatory frameworks like the EU's Corporate Sustainability Reporting Directive drive demand for bio-based alternatives. These policies push manufacturers towards transparent supply chains and reduced environmental footprints.
China
China's vast automotive and tire manufacturing industries create sustained demand for high-cis isoprene rubber. The country's GB standards for tire safety directly influence material specifications. The Yangtze River Delta region, a hub for vehicle production, heavily utilizes these specialized rubber compounds.
United States
Medical applications, particularly for high-purity surgical gloves and pharmaceutical stoppers, drive significant demand in the United States. The US EPA's rules on volatile organic compound emissions influence specialty adhesive production. Midwest automotive manufacturing centers integrate isoprene rubber into various vehicle components.
Germany
Germany's automotive industry and emerging demand for specialized industrial protective coatings utilize isoprene rubber. Compliance with the EU's REACH framework requires extensive chemical safety assessments. Bavaria's advanced manufacturing sector demands high-performance isoprene rubber for seals and gaskets.
Vietnam
Underpenetrated markets like Vietnam present significant geographic expansion opportunities for isoprene rubber producers. Government incentives for foreign direct investment bolster local production capabilities. Industrial zones near Ho Chi Minh City are expanding tire production, increasing isoprene rubber intake.
India
India's large-scale rubber product manufacturing facilities concentrate demand for solid isoprene rubber. BIS standards for rubber products ensure quality and safety across applications. Maharashtra's industrial belt, with its tire and general rubber goods factories, consumes substantial solid isoprene rubber.
Isoprene Rubber Market Key Industry Players
Player mix skews toward large, integrated petrochemical companies and specialized high-purity producers. This creates a tiered structure where scale players coexist with niche innovators catering to distinct market needs. Strategic archetypes include diversified chemical conglomerates, dedicated rubber specialists, and vertically integrated tire manufacturers. Key competitive moves involve significant capital allocation towards capacity expansion for both conventional and bio-based production, alongside strategic partnerships for feedstock diversification and market access.
Vertically integrated players like The Goodyear Tire & Rubber Company exemplify captive consumption models, leveraging their extensive tire manufacturing footprint for internal demand. Kraton Corporation represents the archetype of a specialized producer, focusing on high-purity grades tailored for sensitive applications such as medical devices and specialty adhesives. PJSC SIBUR Holding, a major Russian chemical company, anchors the large-scale production segment, benefiting from integrated feedstock access and emphasizing volume. These companies collectively demonstrate the market's bifurcation between volume-driven and specialty-focused strategies, responding to evolving sustainability mandates and performance requirements.
| Leading Market Players |
|---|
| Zeon Corporation |
| Kraton Corporation |
| Nizhnekamskneftekhim |
| Dow Chemical Company |
| Goodyear Tire & Rubber Company |
| PJSC SIBUR Holding |
| Kuraray Co., Ltd. |
| Qingdao Yikesi New Material |
| JSR Corporation |
| Others |
Cost & Logistics Intelligence
Large-scale petrochemical production facilities establish significant scale economies in the isoprene rubber market, concentrating supply and influencing global price floors. This capital intensity creates barriers to entry, shaping the competitive landscape.
Pricing Analysis
Purity and performance certifications for medical-grade isoprene rubber establish the primary spread in market pricing. The market primarily operates on contract-based long-term offtake agreements for high-volume grades. Quality grade, particularly high-cis content, and specialized medical certifications drive significant price differentiation. Geographic delivery costs also factor into final pricing. Feedstock price volatility, specifically naphtha, introduces considerable pricing pressure, compressing producer margins. Automotive manufacturers exhibit high price sensitivity for bulk orders, while medical device producers prioritize consistent quality over marginal cost savings.
Supply Chain Analysis
Geopolitical instability affecting petrochemical feedstock supply underwrites a structural risk in the isoprene rubber supply chain. Production concentrates in China, Russia, and Japan, reflecting integrated petrochemical complexes. The industry relies heavily on naphtha as a primary feedstock, alongside renewable sugars for emerging bio-isoprene production. Feedstock price volatility represents a significant structural risk, directly impacting production costs. Distribution primarily runs through direct sales channels to large-scale tire and automotive manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The isoprene rubber market requires a robust substitution defense against competitive materials like high-performance styrene-butadiene rubber (SBR). Incumbents must strategically counter this threat across various applications.
For Market Incumbents:Compound existing advantages in high-cis grade production by expanding capacity in key automotive manufacturing regions like China. Invest aggressively in bio-isoprene R&D to meet evolving ESG mandates and diversify feedstock sources, mitigating petrochemical price volatility. Deepen vertical integration to secure critical naphtha supplies, fortifying against supply chain disruptions. Leverage R&D to develop advanced composites that outperform substitutes in demanding applications.
For New Entrants and Emerging Players:Anchor in high-value, niche segments like medical supplies and electric vehicle components, where performance and sustainability premiums justify market entry. Target underpenetrated Southeast Asian markets, specifically Vietnam and Thailand, capitalizing on growing automotive assembly. A go-to-market strategy focusing on certified bio-isoprene with strong ESG credentials can differentiate offerings from traditional petrochemical producers. Develop advanced composite materials with nano-fillers for aerospace applications.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors companies with proven bio-isoprene production capabilities or strong intellectual property in sustainable feedstocks. Over the next five to ten years, the market’s long-term viability will depend on successful bio-isoprene commercialization and integration into electric vehicle platforms. Target specialized high-purity producers like Kraton Corporation for their established positions in medical and adhesive markets. Watch for globally harmonized bio-isoprene standards as a key inflection indicator for broader market adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand High-Cis Production | Meets China's sustained automotive and tire manufacturing demand. |
| Scale Bio-Isoprene Manufacturing | Addresses corporate ESG targets and carbon reduction goals. |
| Develop EV-Specific Formulations | Capitalizes on electric vehicle battery casing and motor mount applications. |
| Secure Feedstock Supply Agreements | Mitigates naphtha price volatility for producers like PJSC SIBUR Holding. |
| Pursue Medical Grade Certifications | Accesses high-value demand from Europe's and US's medical supplies sector. |
Research Approach
A standing panel of R&D directors, procurement leads from automotive OEMs, and sustainability officers provided ongoing calibration for market insights. Primary interviews with these industry stakeholders were complemented by extensive secondary validation. Secondary sources included customs and trade data, corporate ESG reports, and regulatory filings from the US EPA and EU REACH. This approach ensured robust bottom-up and top-down triangulation across all data points.
Forecast outputs were consistently checked against external benchmarks like automotive production forecasts and healthcare expenditure trends over the projection horizon. The analytical framework modeled segmentation dimensions including product type, end-user, application, and regional adoption patterns. Compound annual growth rates were derived from historical performance and projected demand drivers. Key inputs included global automotive production volumes and medical device manufacturing growth.
Material uncertainties — particularly feedstock price volatility and bio-isoprene standardization timelines — sit outside the modeled envelope. Forecasts reflect assumptions about technology adoption and regulatory stability. Practitioners should keep alternative scenarios live as global economic conditions and sustainability mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Snap on Rubber Stopper Market
Rubber
Rubber Molding Market
Rubber
Polybutadiene Elastomers Market
Rubber
Rubber Sand Market
Rubber
Rubber Bulbs Market
Rubber
Rubber Accelerators Market
Rubber
Tire Softener Market
Rubber
Polybutadiene Rubber (PBR) Market
Rubber
Performance Elastomers Market
Rubber
Polyisoprene Rubber Market
Rubber
Flexible Rubber Sheets Market
Rubber
Global Thermoplastic Vulcanizate (TPV) Market
Rubber
EMEA and Asia Pacific Electrical Insulating Rubber Gloves Market
Rubber
Chloro-Sulfonated Polyethylene Market
Rubber
Global Rubber Market
Rubber
Global Medical Rubber Stopper Market