
 Conductive Silicone Rubber Market | 2026-2036
Conductive Silicone Rubber Market Size, Share, and Industry Trends Forecast 2026-2036
Conductive Silicone Rubber Market Intelligence
Multi-source procurement is expanding across the conductive silicone rubber value chain as buyers diversify away from concentrated Asian supply bases. Dow Inc. leverages its integrated silicone monomer-to-compound infrastructure to secure feedstock cost advantages in North America. Shin-Etsu Chemical Co., Ltd. anchors its position through captive production of ultra-high-purity silicone polymers for semiconductor-grade conductive grades. Wacker Chemie AG competes via specialized liquid silicone rubber formulations tailored to automotive sensor encapsulation.
Conductive silicone rubber is an elastomeric material comprising polydimethylsiloxane matrices loaded with conductive fillers such as silver-coated copper, carbon black, or nickel-graphite, typically achieving volume resistivity between 10⁻³ and 10⁰ ohm-cm depending on filler loading and dispersion method. It functions primarily as a compliant electrical conductor, EMI shield, and environmental seal in assemblies where metal alternatives fail due to thermal cycling or geometric complexity. Sheet and gasket product types dominate current volume owing to standardized die-cutting workflows and broad retrofit applicability across installed equipment bases. Liquid form silicone is displacing solid compounds in high-precision electronics applications where injection molding enables thinner walls and tighter tolerances for miniaturized connectors.
FDA regulations govern conductive silicone rubber incorporated into medical devices, requiring biocompatibility testing under ISO 10993 protocols that extend development timelines and elevate qualification barriers for new suppliers. EPA oversight of volatile organic compound emissions from silicone curing processes is pressuring manufacturers to adopt addition-cure platinum catalyst systems in lieu of peroxide-cure alternatives. Automotive OEMs must reconcile NHTSA safety standards with FCC electromagnetic compatibility requirements as vehicle architectures integrate more antenna and radar modules. Stakeholders should monitor how evolving RoHS exemption timelines for lead-free solder alternatives redirect demand toward silver-filled conductive silicone interfaces in high-reliability electronics.
Market Dynamics
Electronics miniaturization is compressing form factors below the mechanical tolerance limits of metal EMI shields, forcing designers toward compliant conductive elastomer alternatives that accommodate thermal cycling stress without gasket fatigue.
Growth Catalysts
- Automotive radar proliferation:NHTSA mandates for advanced driver-assistance systems expand antenna module counts per vehicle, multiplying EMI shielding gasket requirements across Tier-1 sensor suppliers.
- REACH substance restrictions:ECHA's tightening controls on halogenated flame retardants redirect electronics OEMs toward silicone-based shielding materials with inherent thermal stability.
- Silver-coated copper filler advances:Improved plating uniformity reduces per-part precious metal loading while maintaining target resistivity, opening cost-competitive substitution paths for pure silver compounds.
Market Restraints
- Platinum catalyst cost volatility:Addition-cure liquid silicone rubber formulations depend on platinum group metal catalysis, exposing compounders to spot market swings in automotive and medical grade production.
- Ultra-high-purity polymer concentration:Semiconductor-grade conductive silicone supply chains concentrate among three Japanese and German producers with captive monomer assets, creating single-source vulnerability for advanced node chip packaging.
- Peroxide-cure regulatory sunset:EPA volatile organic compound enforcement is eliminating conventional curing chemistry without fully mature platinum-cure alternatives for thick-section molding applications.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for mobile phone and component production create localized demand for EMI shielding materials without established domestic silicone compounders.
- Medical wearable integration:FDA biocompatibility pathways for ISO 10993-5 and -10 tested conductive silicones enable stretchable electrode applications in remote patient monitoring devices.
- Thermal-interface-EMI convergence:Dual-function formulations combining boron nitride thermal conductivity with nickel-graphite electrical shielding reduce part count in 5G base station power amplifiers.
Industry Challenges
- Cleanroom molding technician scarcity:Semiconductor-grade conductive silicone fabrication requires ISO Class 7 environment expertise that outpaces vocational training program output in expanding manufacturing regions.
- Multi-jurisdiction qualification overlap:Medical device suppliers face redundant biocompatibility testing under FDA, PMDA, and MDR frameworks without mutual recognition, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conductive Silicone Rubber Market |
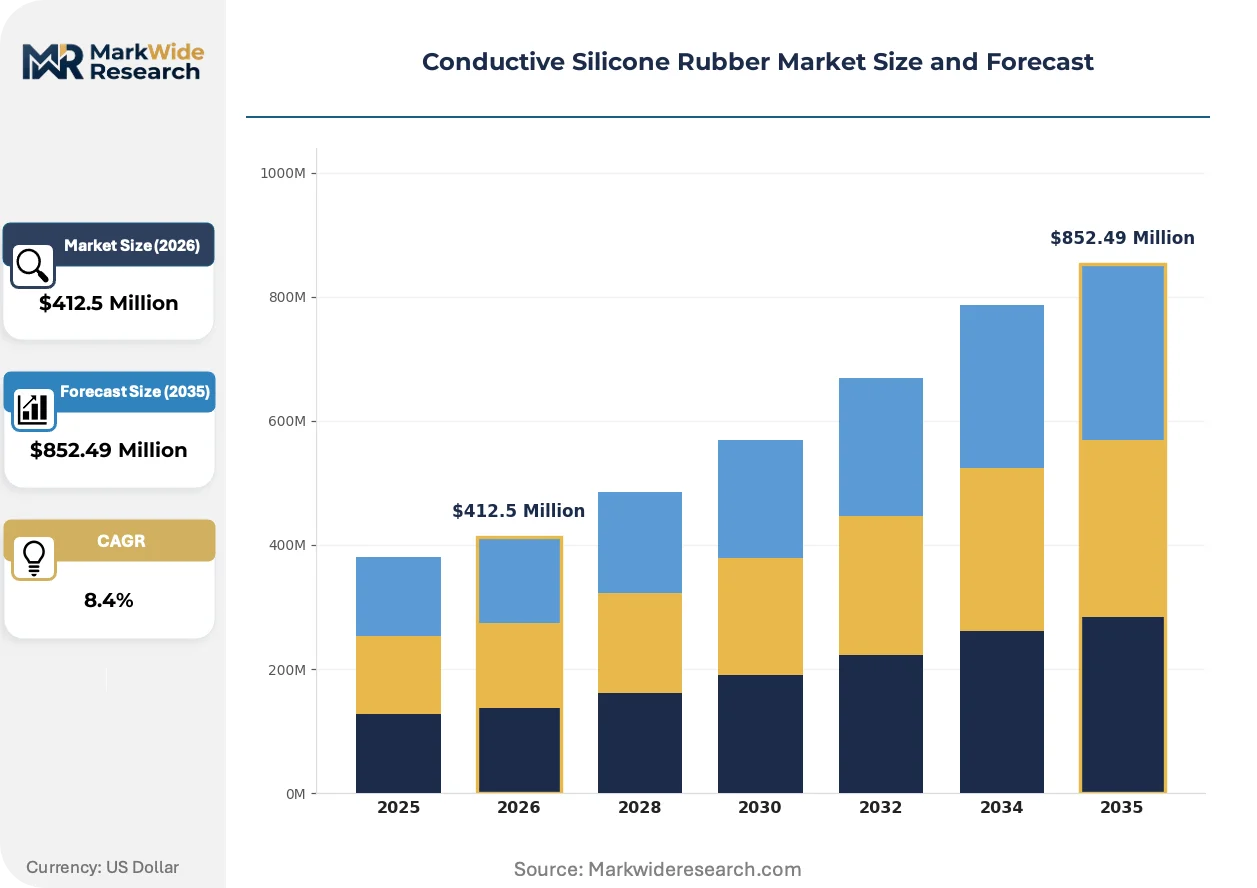
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $852.49 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet, O-Ring, Gasket, Molded Parts Application: Electronics, Automotive Components, Medical Devices, Aerospace Equipment End User: Manufacturers, OEMs, Research Institutions, Contractors Form: Liquid, Solid, Paste, Granular |
| Companies Covered | Shin-Etsu Chemical Co., Ltd., China National Bluestar (Group) Co., Ltd., Dow Inc., Reiss Manufacturing, Inc., KCC Corporation, Momentive Performance Materials Inc., Elkem ASA, Specialty Silicone Products, Inc., Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conductive Silicone Rubber Market Strategic Shifts & Innovations
Formulation chemistry and manufacturing process control are converging to enable thinner, more geometrically complex conductive silicone components that substitute directly for machined metal assemblies in high-density electronics.
Hybrid filler architectures combining carbon nanotube networks with micron-scale silver flakes are unifying electrical conductivity and mechanical compliance in single-compound systems. Automotive sensor module suppliers in Germany and Japan are qualifying these materials for 48V mild-hybrid electrical architectures. This unification eliminates secondary assembly steps previously required to bond separate conductive and sealing elements.
REACH authorization timelines for medium-chain chlorinated paraffins are forcing compounders to reformulate plasticized conductive silicones ahead of 2025 sunset dates. The industrial consequence is accelerated validation of bio-based plasticizer alternatives derived from epoxidized vegetable oils. Medical device manufacturers in Switzerland and the Netherlands are piloting these reformulations to preempt supply disruption.
Consolidated procurement desks at North American telecom infrastructure deployers are compressing supplier qualification cycles from 18 months to 6 months through pre-approved material platform agreements. Distributor technical service teams are displacing traditional field sales roles for specification support. This pattern is most visible in 5G small cell deployments across Texas and California metropolitan markets.
Conductive Silicone Rubber Market Segmentation
Conductive silicone rubber procurement decisions pivot on form-factor compatibility with existing manufacturing workflows and regulatory compliance requirements specific to end-use industries. Technical buyers evaluate volume resistivity specifications against thermal cycling performance, while commercial buyers prioritize supply security and qualification timelines. The segmentation structure reflects these dual technical-commercial decision frameworks.
Product Type:
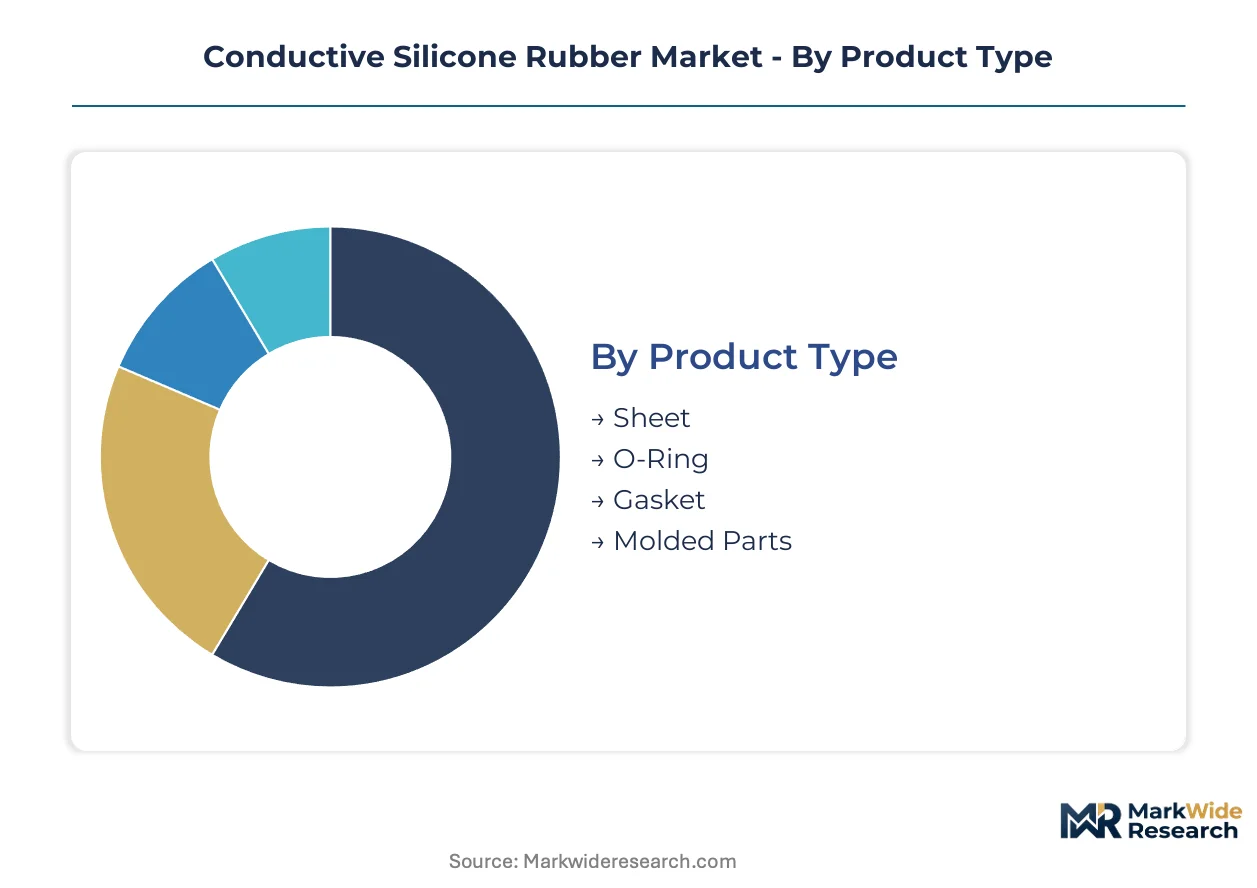
Buyers select product geometries based on assembly method—die-cutting favors sheets, while compression molding demands pre-formed shapes.
- Sheet:Continuous-roll polydimethylsiloxane matrices enable high-throughput die-cutting for EMI shielding gaskets across telecom infrastructure deployments. Demand concentrates in 5G base station manufacturing in China and Germany, where standardized thicknesses reduce tooling costs for Tier-1 contractors.
- Gasket:Pre-formed conductive seals accommodate complex flange geometries in automotive radar modules and medical device enclosures. Automotive OEMs in Japan and the United States specify these for ADAS sensor housings requiring simultaneous environmental sealing and electromagnetic compatibility.
- O-Ring:Circular cross-section profiles serve rotary seal applications in aerospace fuel systems and industrial fluid handling where metal alternatives fail under vibration.
- Molded Parts:Custom geometries produced via liquid injection molding support miniaturized connector housings in semiconductor test equipment.
Volume sits with Sheet; growth tilts toward Gasket.
Application:
Application selection determines the regulatory burden—medical and automotive carry heavier qualification overhead than industrial electronics.
- Electronics:EMI shielding and thermal interface materials for printed circuit board assemblies, smartphones, and telecommunications infrastructure. REACH compliance in Europe and RoHS directives in Asia redirect demand away from halogenated alternatives toward silicone-based solutions in consumer electronics manufacturing.
- Automotive Components:Radar module encapsulation, battery pack seals, and 48V mild-hybrid electrical connectors. NHTSA mandates for advanced driver-assistance systems multiply shielding requirements per vehicle across German and Japanese Tier-1 supplier networks.
- Medical Devices:Biocompatible electrodes and implantable device seals subject to FDA ISO 10993 protocols. Swiss and Dutch manufacturers pilot stretchable conductive formulations for remote patient monitoring wearables.
- Aerospace Equipment:Fuel system seals and avionics shielding meeting FAA flammability standards for cabin interior applications.
Electronics commands current volume; Medical Devices climbs fastest on wearable integration.
End User:
Procurement scale and technical specification authority vary sharply across buyer types.
- OEMs:Original equipment manufacturers in automotive and medical device sectors drive material qualification and set specifications that cascade through supply chains. German automotive OEMs and Japanese electronics OEMs maintain captive material approval lists that restrict supplier choice.
- Manufacturers:Contract manufacturers and component fabricators execute volume procurement against OEM-approved specifications. Chinese domestic silicone producers scale capacity to serve these intermediaries in telecommunications and consumer electronics.
- Research Institutions:Low-volume, high-specification procurement for prototype development and materials characterization studies.
- Contractors:Installation and maintenance service providers sourcing replacement gaskets and seals for retrofit applications.
Specification authority rests with OEMs; procurement volume aggregates at Manufacturers.
Form:
Form selection determines processing equipment requirements and geometric precision capabilities.
- Liquid:Low-viscosity polydimethylsiloxane formulations for injection molding of thin-wall connectors and micro-gaskets. Semiconductor-grade liquid silicone demands ISO Class 7 cleanroom fabrication, concentrating supply among Japanese and German producers with captive monomer assets.
- Solid:High-consistency rubber compounds for compression molding of thick-section seals and extruded profiles. Peroxide-cure regulatory pressure from EPA enforcement is accelerating transition to platinum-cure alternatives.
- Paste:Screen-printable formulations for conformal coating and selective EMI shielding deposition on complex substrates.
- Granular:Feedstock form for custom compounding operations and specialized filler loading adjustments.
Solid dominates tonnage; Liquid expands most quickly on electronics miniaturization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electronics manufacturing clusters in China absorb the largest share of conductive silicone rubber procurement, with automotive sensor demand in Germany and Japan generating secondary volume concentrations. Regional regulatory divergence around REACH, RoHS, and NHTSA mandates reshapes material specification authority across supply chains.
China
Domestic silicone producers scale capacity for 5G base station and electric vehicle battery applications, absorbing silver-coated copper filler imports from Japanese suppliers. MIIT industrial standards for electromagnetic compatibility tighten material traceability requirements for telecommunications infrastructure. Manufacturing concentrates in the Yangtze River Delta around Suzhou and Wuxi, where contract molders serve Huawei and ZTE supply chains.
Germany
Automotive Tier-1 suppliers in Stuttgart and Munich qualify conductive silicone gaskets for radar module encapsulation under NHTSA-aligned ADAS mandates. ECHA REACH restrictions on halogenated flame retardants redirect OEM specifications toward silicone-based shielding alternatives. The Baden-Württemberg cluster hosts formulation R&D for 48V mild-hybrid electrical architectures.
United States
EPA enforcement of volatile organic compound emissions accelerates platinum-cure liquid silicone adoption in medical device manufacturing. FDA ISO 10993 biocompatibility protocols extend qualification timelines for implantable electrode applications. Cleanroom molding capacity concentrates in Minnesota and Massachusetts, serving Medtronic and Boston Scientific supply chains.
Japan
Semiconductor-grade conductive silicone supply chains concentrate among producers with captive monomer assets in the Chubu and Kansai regions. METI industrial policy supports domestic production of ultra-high-purity polymers for advanced node chip packaging. Shin-Etsu Chemical anchors supply for Tokyo Electron and Advantest test equipment manufacturers.
India
PLI scheme incentives for mobile phone assembly create localized EMI shielding demand without established domestic silicone compounders. BIS certification requirements for electronic component imports extend supplier qualification cycles for contract manufacturers. Electronics manufacturing clusters in Tamil Nadu and Karnataka rely on imported sheet and gasket materials from Chinese and Korean sources.
Conductive Silicone Rubber Market Key Industry Players
Capacity expansion dominates the current landscape as integrated chemical conglomerates and specialized silicone compounders race to secure feedstock positions. The vendor base stratifies between captive monomer producers with polymer-to-compound integration and independent formulators dependent on merchant silicone supply. Three archetypes prevail: diversified chemical majors with silicone divisions, pure-play silicone specialists, and regional contract compounders. M&A activity concentrates on filler technology acquisitions, while geographic expansion targets Indian and Southeast Asian electronics manufacturing zones.
Among integrated chemical majors, Dow Inc., Shin-Etsu Chemical Co., Ltd., and Wacker Chemie AG exemplify the captive supply archetype, each controlling upstream monomer production that insulates margin positions from merchant silicone price volatility. These producers occupy positions that independent compounders cannot readily replicate without backward integration into chlorosilane or siloxane production. Specialty Silicone Products, Inc. and Reiss Manufacturing, Inc. represent the independent formulator tier, sourcing base polymers and engineering conductive filler loadings for application-specific performance. China National Bluestar (Group) Co., Ltd. anchors the state-backed expansion vector, leveraging domestic market scale to compress pricing for standard-grade EMI shielding materials.
| Leading Market Players |
|---|
| Shin-Etsu Chemical Co., Ltd. |
| China National Bluestar (Group) Co., Ltd. |
| Dow Inc. |
| Reiss Manufacturing, Inc. |
| KCC Corporation |
| Momentive Performance Materials Inc. |
| Elkem ASA |
| Specialty Silicone Products, Inc. |
| Wacker Chemie AG |
| Others |
Cost & Logistics Intelligence
Semiconductor-grade versus standard EMI shielding grade bifurcation creates a 3-4x cost spread that concentrates supply chain control among Japanese and German producers with captive monomer assets, while commodity sheet grades face margin compression from Chinese domestic scaling. This tier divergence manifests in pricing power asymmetry: ultra-high-purity liquid silicone commands long-term offtake contracts with medical device OEMs, whereas standard gasket materials trade on spot-adjusted volume discounts to contract manufacturers.
Pricing Analysis
Volume-driven sheet and gasket procurement runs through contract manufacturers in China and India, compressing margins through competitive tendering, while semiconductor-grade liquid silicone retains pricing power via ISO 10993 biocompatibility certification requirements that restrict qualified suppliers. Price differentiation hinges on filler purity levels—silver-coated copper formulations trade at premiums to carbon-black alternatives—and on REACH compliance documentation burdens that OEMs pass through as service fees. Cost compression in standard grades intensifies as Chinese domestic silicone producers expand capacity for 5G infrastructure, though platinum catalyst cost volatility constrains margin expansion in addition-cure formulations. Tier-1 automotive suppliers exhibit lowest price sensitivity due to NHTSA-mandated ADAS content requirements, whereas contract electronics manufacturers in India demonstrate highest sensitivity under PLI scheme margin targets.
Supply Chain Analysis
Multi-source qualification mandates from automotive and medical OEMs force buyers to maintain approved supplier lists across at least two geographic regions, typically pairing Japanese or German ultra-high-purity producers with Chinese or Korean standard-grade sources. Supply concentration centers on Japan, Germany, and China, with raw material dependencies spanning silver-coated copper filler from Japanese plating houses, platinum group metal catalysts from South African refiners, and polydimethylsiloxane base polymers from integrated chlorosilane producers. Single-source vulnerability persists for semiconductor-grade polymers where three producers control captive monomer-to-compound pipelines. Distribution feeds from direct OEM technical sales for qualified grades, while standard materials flow through distributor technical service teams that displace field sales in 5G infrastructure deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The conductive silicone rubber market sits in a technology-transition phase as platinum-cure liquid silicone displaces peroxide-cure solid compounds under EPA volatile organic compound enforcement, rendering legacy curing infrastructure stranded.
For Market Incumbents: Deploy captive monomer integration as the primary defensive lever, securing feedstock cost positions that independent compounders cannot replicate without backward integration into chlorosilane production. Shin-Etsu Chemical and Wacker Chemie anchor this model through in-house siloxane supply. Capacity expansion in India addresses PLI-driven electronics manufacturing demand before domestic compounders emerge. Certification investment in ISO 10993 biocompatibility pathways defends medical device segments against emerging entrants lacking cleanroom molding expertise. For New Entrants and Emerging Players: Begin with specialty filler technology licensing as the entry mechanism, targeting silver-coated copper plating uniformity improvements that reduce precious metal loading without conductivity sacrifice. India's electronics manufacturing clusters present the most penetrable geography given absent domestic silicone compounders and BIS certification bottlenecks for imports. Medical wearable stretchable electrodes offer application white-space, with remote patient monitoring device OEMs seeking ISO 10993-5 and -10 tested alternatives to incumbent suppliers. A technical service partnership model with distributor networks bypasses direct OEM qualification barriers. For Investors and Strategic Acquirers: Re-rating potential sits with independent formulators possessing FDA master file registrations and cleanroom molding capabilities, given medical device qualification timelines that deter new capacity entry. Long-term viability favors producers with dual automotive-electronics end-use exposure that buffers segment cyclicality. The inflection signal to monitor is RoHS exemption timeline revisions for lead-free solder alternatives, which would redirect high-reliability electronics demand toward silver-filled conductive silicone interfaces and expand addressable market for qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Monomer Production | Captive supply of polydimethylsiloxane insulates margin positions from merchant polymer price volatility. |
| Platinum-Cure Process Conversion | EPA VOC enforcement eliminates peroxide-cure alternatives, requiring capital deployment to compliant curing infrastructure. |
| ISO 10993 Biocompatibility Certification | FDA master file registration creates 18-24 month qualification barriers for implantable and wearable medical device supply. |
| India Manufacturing Footprint Establishment | PLI scheme incentives for mobile phone assembly create localized demand without incumbent domestic compounder competition. |
| Hybrid Filler Architecture Development | Carbon nanotube-silver flake unification enables single-compound conductive-sealing solutions for automotive 48V architectures. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with silicone compounding plant managers, procurement leads at automotive Tier-1 suppliers, medical device regulatory affairs directors, and distributor technical service heads. SEC 10-K disclosures from integrated chemical majors, ECHA REACH authorization databases, and FDA 510(k) submission logs provided demand-side validation. Bottom-up volume estimates from end-use application modeling triangulated against top-down value projections from producer revenue disclosures across the analysis window.
Data-stream reconciliation across shipment volumes, capacity utilization rates, and price realization metrics informed the analytical framework. Segmentation dimensions modeled include product form, filler composition tier, end-use industry, and regional regulatory cluster. CAGRs derived from log-linear trend fitting to historical volume data, adjusted for capacity expansion announcements and qualification timeline constraints. Industry-specific inputs incorporated platinum group metal price indices and electronics manufacturing purchasing manager sentiment.
Underlying measurement precision varies by segment; semiconductor-grade liquid silicone carries tighter precision than commodity sheet grades due to concentrated producer disclosure. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and automotive electrification content trajectories. Deviation in RoHS exemption renewal decisions or EPA peroxide-cure enforcement acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Ethylene Propylene Rubber Cable Market
Rubber
FKM Elastomers Market
Rubber
Synthetic Polyisoprene Rubber Market
Rubber
Nitrile Butadiene Rubber (NBR) Latex Market
Rubber
Liquid Silicone Rubber Market
Rubber
Rubber Valve Stem Market
Rubber
Silica for S-SBR Market
Rubber
Chloroprene Rubber Modified Asphalt Emulsion Market
Rubber
Global Liquid Synthetic Rubber Market
Rubber
Global Chloroprene Rubber Market
Rubber
Corrosion Protection Rubber Linings and Coatings Market
Rubber
Fast Curing Nitrile Butadiene Rubber (NBR) Market
Rubber
Silicone Rubber Market
Rubber
Global Styrene Butadiene Styrene Market
Rubber
Nitrile Butadiene Rubber Market
Rubber
Reclaimed Rubber Market