
 Styrene Butadiene (SB) Latex Market | 2026-2036
Styrene Butadiene (SB) Latex Market Size, Share, and Industry Trends Forecast 2026-2036
Styrene Butadiene (SB) Latex Market Analysis
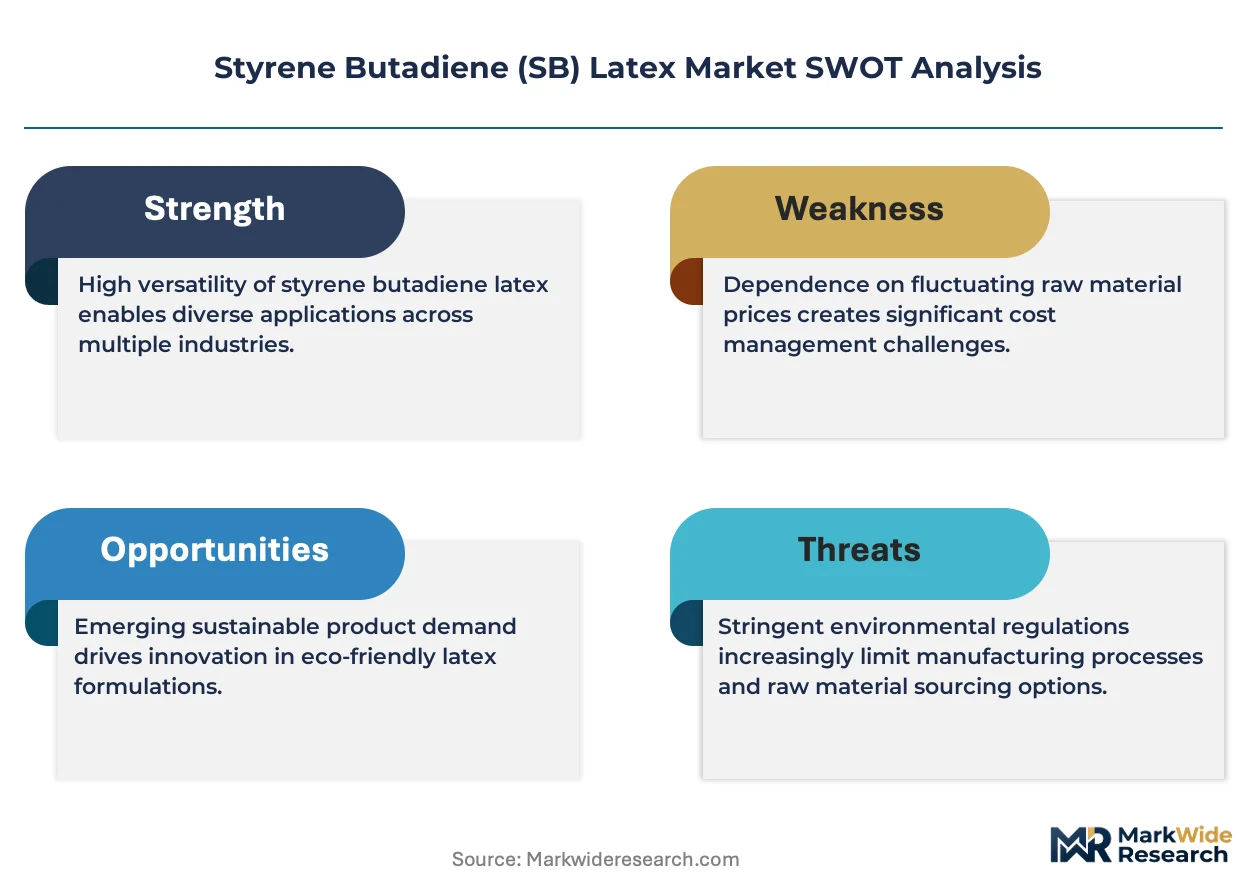
ISO 14001 environmental management certification is bifurcating the supplier base into qualified and non-qualified tiers. Synthomer plc leverages backward integration into butadiene feedstock to sustain margin stability across European coating applications. BASF SE anchors its position through R&D intensity in carboxylated SB latex grades for high-gloss paper. LG Chem Ltd. competes on manufacturing scale in Asia, where it controls regional distribution for footwear adhesives.
Styrene butadiene latex is a synthetic copolymer emulsion produced through free-radical emulsion polymerization of styrene and butadiene monomers at ratios typically ranging from 30:70 to 70:30, yielding film-forming binders with glass transition temperatures between minus 60 and plus 30 degrees Celsius for paper coating, carpet backing, and construction adhesive applications. Emulsion product types dominate volume due to their direct-use formulation compatibility, while powder forms command margin pools in remote construction markets where waterborne shipping costs penalize liquid loads. Paper end users represent the mature demand core, whereas electronics applications in flexible circuit board coatings are gaining fastest as Asian contract manufacturers qualify SB latex dielectric layers.
REACH in Europe and EPA TSCA in the United States both restrict residual styrene monomer content, forcing reformulation investments that favor larger producers with analytical testing infrastructure. China's MEE enforces VOC discharge limits on latex production facilities, raising capital barriers for new entrants in Shandong and Jiangsu provinces. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory when cross-border formulations fail local compliance tests.
Market Dynamics
Paper coating binders face mounting pressure as REACH compliance tightens monomer purity thresholds across European supply chains, forcing reformulation investments that favor producers with captive analytical infrastructure.
Growth Catalysts
- E-commerce packaging demand:Chinese packaging converters are scaling coated paperboard output for fulfillment infrastructure, pulling volume through Asia-Pacific supply chains.
- REACH monomer thresholds:Tighter residual styrene limits in Europe are accelerating supplier qualification protocols that lock in qualified tier relationships.
- Electronics dielectric layers:Asian contract manufacturers are qualifying SB latex formulations for flexible circuit board coatings, opening specification windows beyond traditional paper applications.
Market Restraints
- Butadiene feedstock volatility:Crude-linked naphtha cracking economics transmit price instability through emulsion polymerization cost structures.
- Shandong-Jiangsu production concentration:China's MEE VOC discharge limits have raised capital barriers that consolidate capacity among incumbent producers.
- Acrylic latex substitution:Waterborne acrylic binders are capturing share in premium paper coating segments where gloss requirements permit reformulation.
Strategic Opportunities
- India packaging conversion:Domestic paperboard capacity expansion for consumer goods distribution is creating specification windows for imported emulsion grades.
- EU Green Deal bio-based mandates:Renewable content thresholds in public procurement are opening pilot programs for bio-butadiene pathway development.
- Construction adhesives powder conversion:Spray-dried latex particles are penetrating remote infrastructure markets where liquid freight costs disadvantage waterborne loads.
Industry Challenges
- ISO 14001 certification timelines:Environmental management system audits are extending supplier onboarding cycles by 8-14 months for coating compounders.
- Cross-border formulation compliance:Divergent residual monomer limits between EPA TSCA and REACH jurisdictions are fragmenting inventory pools and stranding working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Styrene Butadiene (SB) Latex Market |
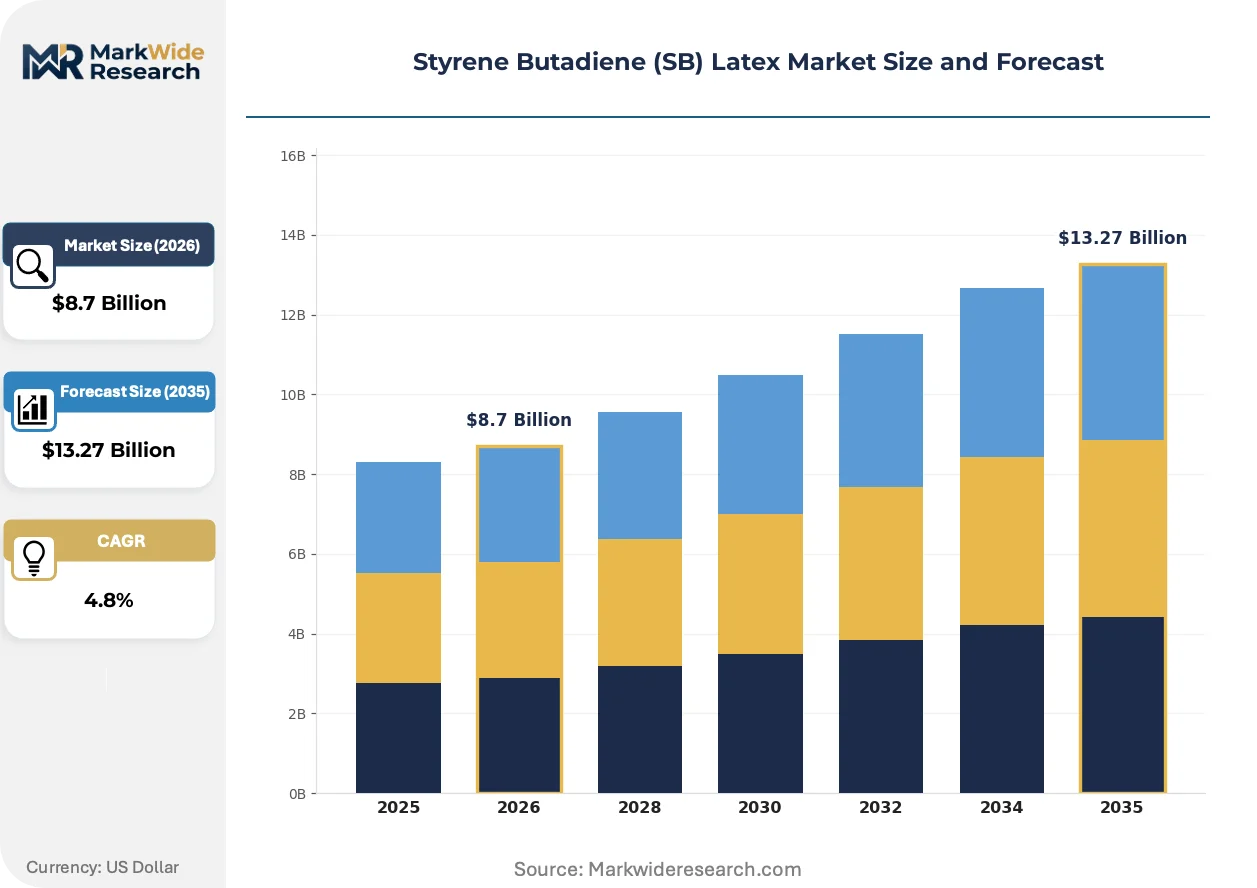
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsion, Powder, Dispersion, Solution End User: Adhesives, Coatings, Paper, Textiles Application: Footwear, Automotive, Construction, Electronics Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Synthomer plc, LG Chem Ltd., BASF SE, Wacker Chemie AG, JSR Corporation, Trinseo, LANXESS AG, Kumho Petrochemical Co., Ltd., Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Styrene Butadiene (SB) Latex Market Emerging Trajectories
Carboxylated latex grades are commanding specification premiums as paper mills reformulate for higher gloss performance, while regulatory pressure on residual monomers is accelerating analytical infrastructure investment across the supply base.
Carboxylated SB latex with elevated acid functionality is supplanting conventional non-carboxylated grades in high-gloss magazine and catalog coatings. European paper mills are adopting these modified binders to meet brightness and printability specifications for luxury packaging segments. The shift is compressing margin pools for standard emulsion grades while rewarding producers with continuous carboxylation process capability.
REACH Annex XVII restrictions on residual styrene monomer are forcing reformulation investments that favor larger producers with in-house gas chromatography testing infrastructure. The regulation's industrial consequence is a bifurcation between qualified suppliers meeting sub-300 ppm thresholds and non-qualified tiers facing exclusion from European coating compounder approved vendor lists. Paper coating applications in Germany and France are responding fastest, with specification lock-in periods extending to 36 months for qualified suppliers.
Specification-driven procurement is consolidating buyer power among multinational paper and packaging groups that centralize binder qualification across regional mill networks. Regional coating compounders are losing specification influence as parent companies mandate approved supplier lists from headquarters technical teams. This concentration is most visible in Scandinavian pulp and paper groups, where centralized R&D functions now control global latex procurement decisions from Stockholm and Helsinki.
Styrene Butadiene (SB) Latex Market Segmentation
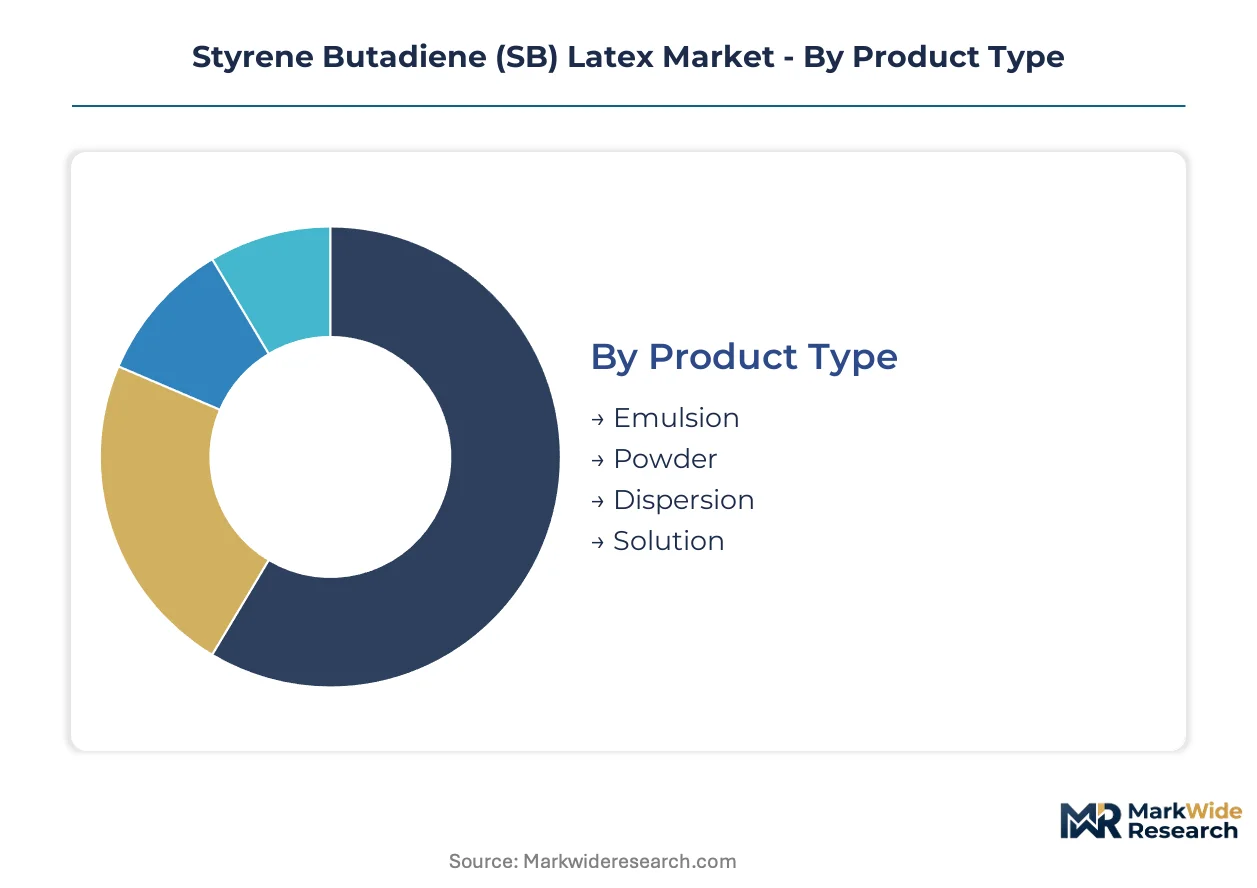
SB latex demand fragments across product forms, end-use specifications, and channel economics that reward different production footprints. Geographic concentration in Asian manufacturing clusters shapes which segments travel as exports versus serve domestic formulation markets.
Product Type:
Emulsion grades dominate regional supply chains serving adjacent paper mills, while powder forms justify freight economics for remote construction markets lacking local polymerization capacity.
- Emulsion:Waterborne copolymer dispersions with 40-60% solids content serve paper coating compounders through direct pipeline delivery in Shandong and Jiangsu provinces. Chinese packaging converters pull volume through Asia-Pacific supply chains for e-commerce fulfillment infrastructure.
- Powder:Spray-dried latex particles reconstitute at job sites where liquid freight costs penalize waterborne loads. Penetration concentrates in remote infrastructure markets across India and Southeast Asia where road networks favor dry bulk handling.
- Dispersion:Pre-stabilized emulsions for adhesive compounders seeking reduced formulation complexity.
- Solution:Solvent-based systems for specialty electronics applications requiring precise film thickness control.
Emulsion commands the established base. The steepest expansion runs through powder conversion for construction adhesives.
End User:
Cost tiers separate commodity binders from performance grades where specification premiums reward reformulation capability.
- Paper:Coating binders face REACH monomer purity thresholds that bifurcate suppliers into qualified and non-qualified tiers. European mills are locking in 36-month supplier relationships for sub-300 ppm residual styrene grades.
- Adhesives:Footwear and construction applications drive specification diversity across carboxylated and non-carboxylated grades. LG Chem controls regional distribution for Asian footwear manufacturers through manufacturing scale.
- Coatings:High-gloss formulations command premium positioning where BASF anchors through R&D intensity in acid-functional binders.
- Textiles:Carpet backing remains a mature volume sink with limited specification differentiation.
Paper coatings absorb the dominant volume share. Adhesives are climbing the fastest on footwear reshoring and construction activity.
Application:
Customer type fragmentation separates specification-driven electronics procurement from price-sensitive construction buying.
- Electronics:Flexible circuit board dielectric layers are gaining fastest as Asian contract manufacturers qualify SB latex formulations beyond traditional paper uses. Specification windows demand sub-50 ppm ionic contamination grades.
- Construction:Cement modification and tile adhesives consume powder grades where freight economics dominate supplier selection. Indian infrastructure spending is creating import demand for spray-dried particles.
- Automotive:Interior trim adhesives and sealant applications require heat-aged performance certification.
- Footwear:Sole bonding and upper lamination specifications favor regional suppliers with rapid formulation turnaround.
Construction anchors the volume base. Electronics represents the fastest-growing trajectory on dielectric qualification programs.
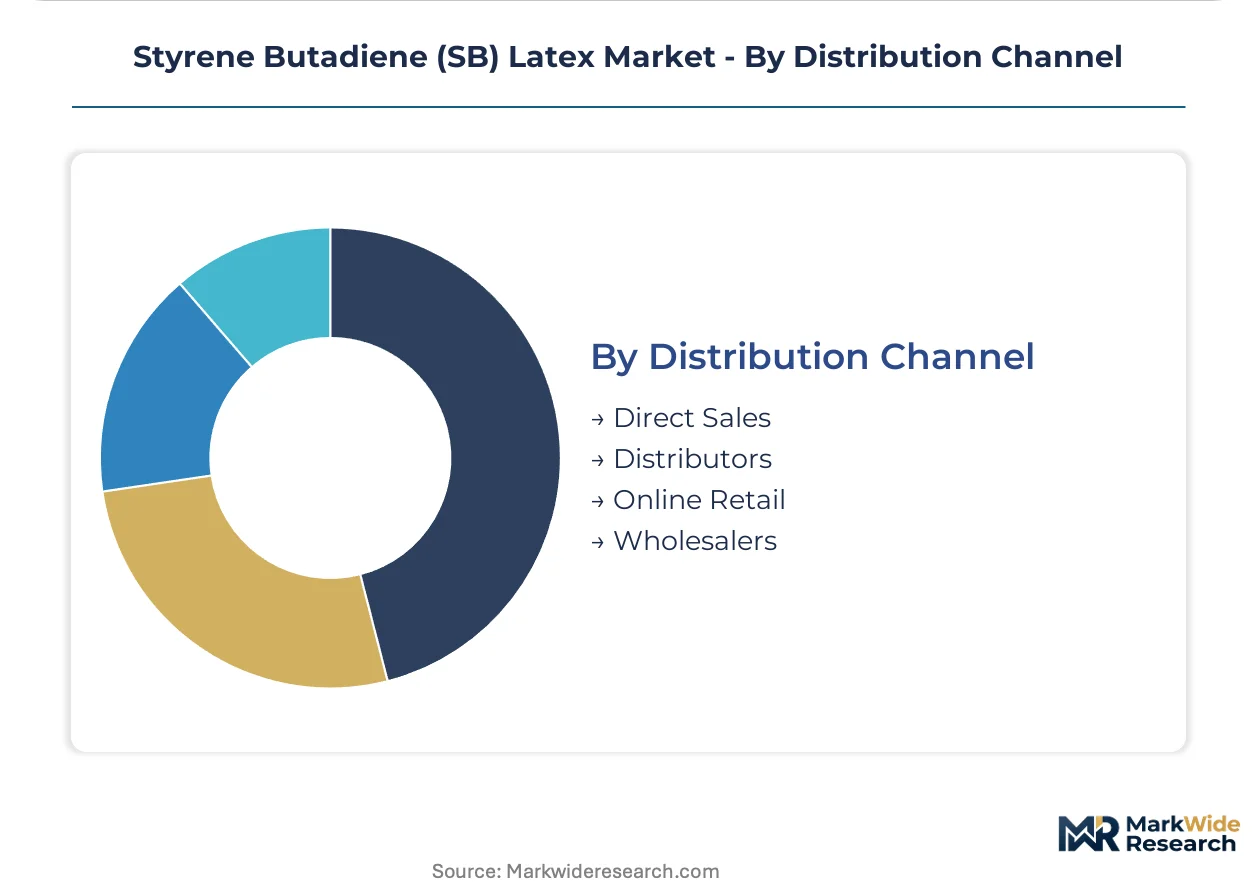
Distribution Channel:
Supply concentration among multinational producers shapes channel leverage differently across qualified and commodity tiers.
- Direct Sales:Multinational paper groups centralize procurement through headquarters technical teams in Stockholm and Helsinki. ISO 14001 certification extends supplier onboarding cycles by 8-14 months for direct relationships.
- Distributors:Regional coating compounders rely on distributor inventory pools to manage cross-border formulation compliance risks between EPA TSCA and REACH jurisdictions.
- Wholesalers:Construction adhesive formulators in secondary Indian cities access powder grades through wholesale networks.
- Online Retail:Small-batch specialty grades for research and pilot-scale electronics manufacturing.
Direct sales commands the established base. Distributor networks are expanding fastest as regional compounders seek compliance risk mitigation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging converters and paper mills concentrate procurement power across four distinct demand centers, each shaped by local regulatory frameworks and industrial cluster economics.
China
E-commerce fulfillment infrastructure drives coated paperboard expansion through packaging converters in Shandong and Jiangsu provinces. MEE VOC discharge limits on latex production facilities have raised capital barriers that consolidate capacity among incumbent producers. Qingdao and Yantai host the dominant emulsion manufacturing clusters serving domestic packaging demand.
Germany
REACH Annex XVII residual styrene thresholds below 300 ppm lock in qualified supplier relationships across paper coating compounders. ECHA compliance protocols extend specification onboarding cycles to 36 months for approved vendor lists. The Ruhr industrial corridor anchors analytical testing infrastructure for monomer purity verification.
United States
EPA TSCA residual monomer limits diverge from REACH thresholds, fragmenting inventory pools for cross-border formulation compliance. Flexible circuit board manufacturers in California and Texas qualify SB latex dielectric layers for electronics applications. Gulf Coast petrochemical corridors supply butadiene feedstock to domestic emulsion polymerization capacity.
India
Domestic paperboard capacity expansion for consumer goods distribution creates specification windows for imported emulsion grades. BIS certification requirements for industrial chemicals extend supplier qualification timelines. Maharashtra and Gujarat packaging clusters drive demand for spray-dried powder grades in remote construction markets.
Japan
METI industrial standards govern emulsion quality specifications for electronics and adhesive applications. Specialty paper manufacturers in the Kanto region source high-purity grades for technical coating segments. Osaka-based chemical distributors manage regional inventory pools for formulated adhesive compounders.
Styrene Butadiene (SB) Latex Market Vendor Landscape
Player mix skews toward integrated petrochemical conglomerates with captive monomer supply and specialized emulsion polymerizers serving specification-driven paper coating segments. The structure bifurcates between qualified tiers meeting sub-300 ppm residual styrene thresholds and commodity suppliers excluded from European approved vendor lists. Strategic archetypes include backward-integrated feedstock controllers, carboxylation process specialists, and regional distribution scale operators. Dominant competitive moves center on analytical infrastructure investment for regulatory compliance and spray-drying capacity expansion for remote construction markets.
Within the qualified-tier vector, Synthomer plc exemplifies European producers leveraging captive butadiene integration to sustain margin stability across coating applications. BASF SE anchors the carboxylated grade specialization segment through R&D intensity in acid-functional binders. LG Chem Ltd. occupies the Asian manufacturing scale position, controlling regional distribution networks for footwear adhesive specifications.
| Leading Market Players |
|---|
| Synthomer plc |
| LG Chem Ltd. |
| BASF SE |
| Wacker Chemie AG |
| JSR Corporation |
| Trinseo |
| LANXESS AG |
| Kumho Petrochemical Co., Ltd. |
| Dow Chemical Company |
| Others |
Supply Flow & Price Mechanics
Capacity utilization rates above 85% in Shandong and Jiangsu emulsion clusters translate directly into price floor elevation for qualified-tier suppliers, while underutilized powder conversion lines in India compress margins for commodity grades serving construction adhesives.
Pricing Analysis
Cost-plus contracts indexed to butadiene spot prices on Singapore and Rotterdam exchanges dominate procurement relationships for paper coating compounders. Three-tier pricing structure across REACH-qualified, ISO-certified, and uncertified grades separates premium carboxylated emulsions from standard binders and economy powder forms. Pricing pressure stems from acrylic latex substitution in high-gloss magazine segments where reformulation flexibility exists. Construction adhesive formulators exhibit highest price sensitivity due to freight economics dominating total delivered cost, while electronics dielectric buyers prioritize ionic purity over unit price.
Supply Chain Analysis
China and Germany anchor emulsion polymerization capacity, with Shandong province hosting captive butadiene crackers serving domestic packaging converters and the Ruhr corridor concentrating REACH-compliant analytical infrastructure for European paper mills. Raw material dependencies center on naphtha-derived butadiene, styrene monomer from ethylbenzene dehydrogenation, and specialty surfactants for emulsion stabilization. Single-source vulnerability concentrates in Shandong-Jiangsu production zones where MEE VOC discharge permits limit new entrant capacity. Distribution runs through direct pipeline delivery to adjacent paper mills, with spray-dried powders moving via dry bulk carriers to remote Indian and Southeast Asian construction markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent SB latex producers face sustained substitution defense against waterborne acrylic binders in premium paper coating segments, requiring qualification investments that lock buyer relationships before reformulation windows close.
For Market Incumbents: Compound analytical infrastructure investment to sustain REACH sub-300 ppm certification as a barrier against commodity entrants, while accelerating spray-drying capacity in India to capture construction adhesive growth ahead of freight-optimized regional competitors. Backward integration into butadiene feedstock anchors margin stability against naphtha price volatility. For New Entrants and Emerging Players: Qualified-tier service gaps in European electronics dielectric qualification programs offer white-space entry, where sub-50 ppm ionic contamination testing capabilities remain scarce outside established Japanese and German suppliers. Target Indian packaging converters through imported emulsion partnerships with domestic distributors holding BIS certification relationships, bypassing direct ISO 14001 audit timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among REACH-qualified suppliers with 36-month specification lock-in periods at Scandinavian paper groups, offering visibility through raw material cycles. Long-term viability centers on carboxylation process capability and captive monomer supply. Monitor acrylic latex pricing spreads as the inflection signal for SB latex share retention in reformulation-sensitive segments.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Infrastructure | Gas chromatography testing capacity locks 36-month supplier relationships with European coating compounders. |
| Backward Integration | Captive butadiene supply from naphtha crackers insulates margin stability against feedstock volatility. |
| Spray-Drying Expansion | Powder conversion capacity in India captures construction adhesive demand where liquid freight costs disadvantage imports. |
| Electronics Dielectric Qualification | Sub-50 ppm ionic contamination grades open specification windows beyond mature paper applications. |
| Carboxylation Process Investment | Acid-functional binder capability commands premium positioning in high-gloss magazine and luxury packaging segments. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with plant managers at emulsion polymerization facilities, procurement leads at downstream paper mills, distribution channel partners in Indian construction markets, and technical R&D directors at coating compounders; alongside secondary validation through customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical producers, and MEE environmental discharge records. Bottom-up capacity estimates triangulated against top-down demand models across end-use segments.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product form, end-use industry, certification tier, and regional production hub. CAGRs derived from weighted average growth rates across segment-level drivers, incorporating butadiene feedstock price elasticity, REACH compliance cost pass-through coefficients, and e-commerce packaging demand intensity in Chinese provincial clusters.
Underlying assumptions cover sustained REACH monomer threshold enforcement and MEE permit scarcity in Shandong-Jiangsu, with deviation risk concentrated in accelerated acrylic substitution timelines or bio-butadiene pathway commercialization. Recalibration cycles align with material shifts in regulatory enforcement intensity and feedstock cracking economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Chloroprene Rubber Modified Asphalt Emulsion Market
Rubber
Global Latex Allergy Market
Rubber
Tire Recycling Downstream Products Market
Rubber
Metallurgical Rubber Roller Market
Rubber
Styrene Butadiene Rubber (E-SBR and S-SBR) Market
Rubber
Rubber Molding Market
Rubber
Global Chloroprene Rubber Market
Rubber
Industrial Rubber Market
Rubber
Global Automotive Elastomers Market
Rubber
Hydroxyl Terminated Polybutadiene Market
Rubber
Global Medical Rubber Stopper Market
Rubber
Global Rubber Vulcanization Market
Rubber
Rubber Bulb Seals Market
Rubber
Recycled Elastomers Market
Rubber
Rubber Gloves Market
Rubber
Global Rubber Coated Fabrics Market