
 Polyisoprene Market | 2026-2036
Polyisoprene Market Size, Share, and Industry Trends Forecast 2026-2036
Polyisoprene Market Intelligence
Asset-light leasing models for polymer production equipment are tilting competitive dynamics toward mid-scale entrants that previously faced capital barriers. JSR Corporation leverages its synthetic rubber technology leadership to sustain premium positioning in medical-grade polyisoprene. Bridgestone Corporation anchors its supply security through backward integration into key feedstocks. Michelin differentiates via proprietary compounding expertise that extends product performance in high-durability tire applications.
Polyisoprene is a synthetic elastomer with the same cis-1,4-polyisoprene chemical structure as natural rubber, produced through stereospecific polymerization of isoprene monomer using Ziegler-Natta or rare-earth catalysts, yielding 92-97% cis content for elasticity comparable to Hevea rubber. It serves as a strategic substitute in applications requiring latex-free certification, consistent quality, and reduced allergen risk. Synthetic polyisoprene dominates value generation due to medical device and automotive demand, while natural rubber retains volume leadership in commodity tire manufacturing. The medical devices end-user segment commands the strongest margin pool as biocompatibility certifications and sterile processing requirements create pricing power for validated suppliers.
FDA biocompatibility standards and EU REACH chemical registration frameworks shape material qualification timelines and market access costs for polyisoprene suppliers serving regulated industries. ISO 10993 testing protocols and EMA medical device regulations further segment the competitive landscape between certified and uncertified producers. Stakeholders must monitor catalyst technology advances and evolving latex substitution mandates across healthcare procurement systems to anticipate demand inflections.
Market Dynamics
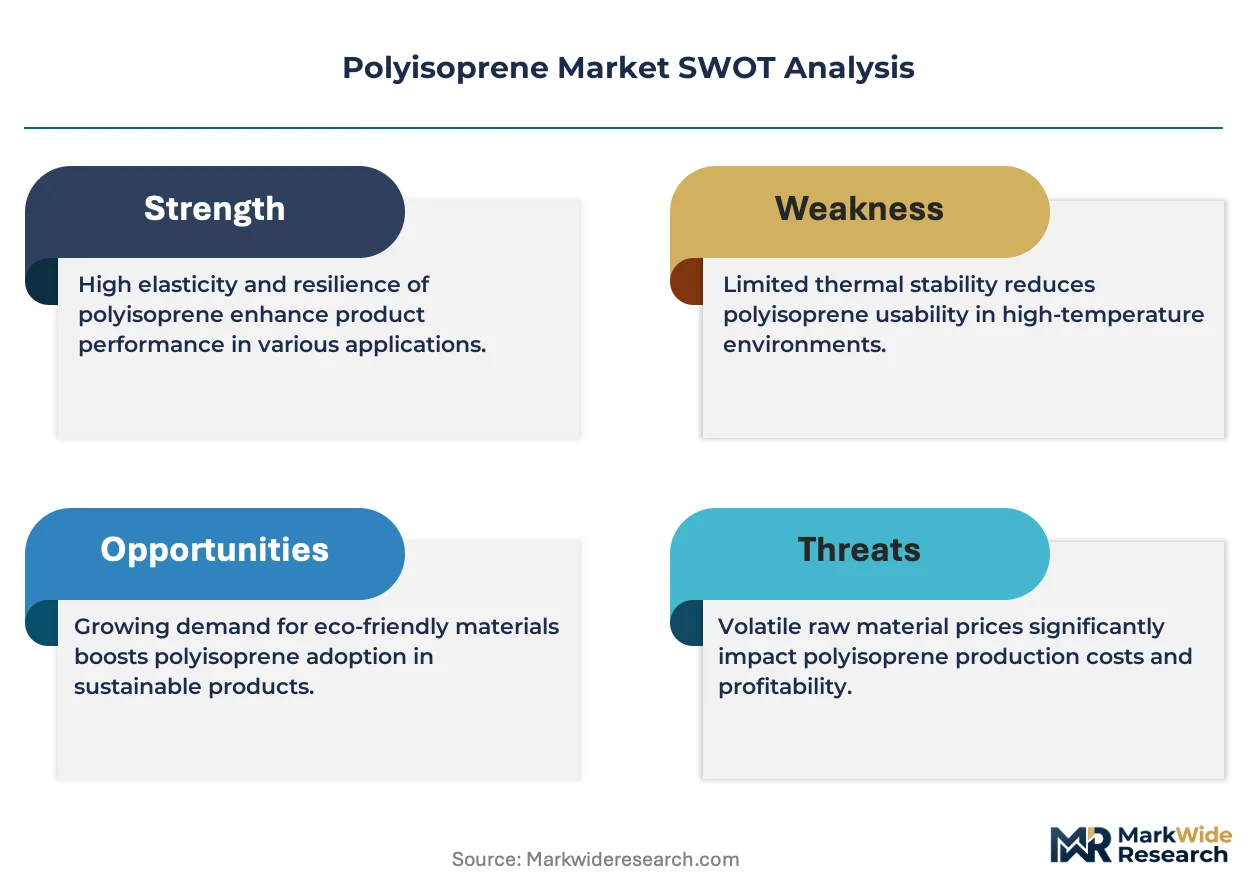
Medical-grade certification requirements are compressing supplier margins while concentrating procurement among validated producers capable of sustaining ISO 10993 compliance across multi-year qualification cycles.
Growth Catalysts
- Latex-free mandates:Healthcare systems in Germany and France are accelerating synthetic substitution in surgical gloves to eliminate allergen exposure risks.
- REACH chemical registration:ECHA's expanded substance evaluation protocols are disqualifying uncertified natural rubber alternatives from EU medical device supply chains.
- Rare-earth catalyst advances:Stereospecific polymerization using neodymium-based systems is achieving cis-content parity with Hevea rubber at production scale.
Market Restraints
- Isoprene monomer volatility:Crude oil price fluctuations directly feed through to feedstock costs, compressing compounder margins during upstream spikes.
- Asian supply concentration:Over 70% of Ziegler-Natta catalyst production sits with Chinese and Japanese specialty chemical houses, creating single-source vulnerability.
- Natural rubber price arbitrage:Hevea plantations in Thailand and Indonesia maintain cost advantages for commodity tire applications, limiting synthetic penetration.
Strategic Opportunities
- Indian medical device manufacturing:CDSCO's streamlined Class C/D device approvals and PLI scheme incentives are attracting polyisoprene compounders to Gujarat and Maharashtra clusters.
- Wearable drug delivery systems:Micropump diaphragms and infusion set tubing represent emerging high-margin applications requiring biocompatibility certification.
- Green chemistry catalysts:Bio-based isoprene feedstocks from lignocellulosic sources are converging with enzymatic polymerization research to unlock circular production pathways.
Industry Challenges
- Sterile processing validation:Gamma irradiation and ethylene oxide sterilization protocols require 18-24 month qualification timelines that delay new product introductions.
- Specialized polymer engineering talent:The intersection of stereospecific catalysis and medical device regulatory science commands premium compensation that mid-scale entrants struggle to match.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyisoprene Market |
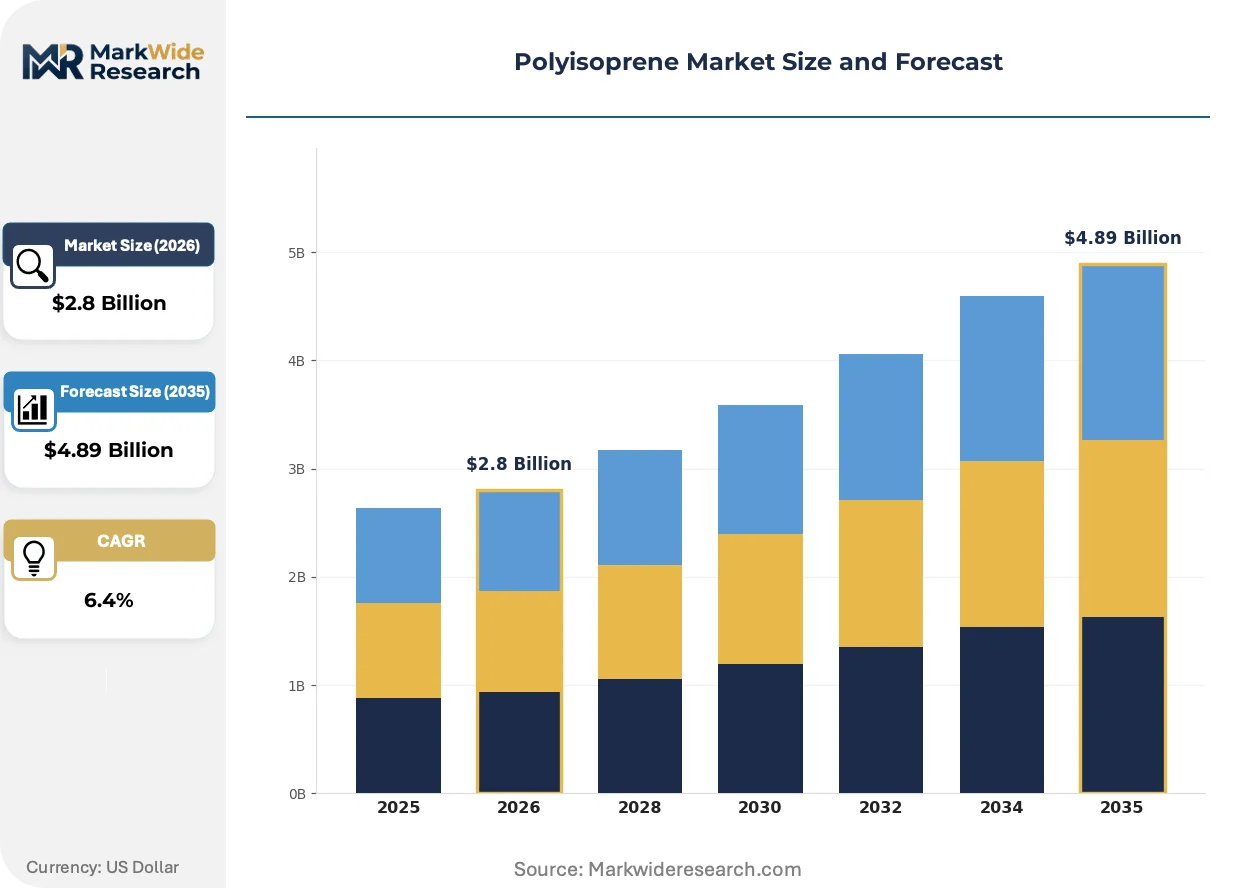
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Rubber, Synthetic Polyisoprene, Gel Polyisoprene, Low Molecular Weight Polyisoprene End User: Medical Devices, Automotive Industry, Consumer Goods, Footwear Manufacturing Form: Sheet, Foam, Liquid, Solid Application: Seals, Adhesives, Coatings, Gaskets |
| Companies Covered | Goodyear Tire & Rubber Company, Bridgestone Corporation, Michelin, JSR Corporation, Zeon Corporation, Kuraray Co., Ltd., Continental AG, Exxon Mobil Corporation, PJSC Nizhnekamskneftekhim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyisoprene Market Strategic Shifts & Innovations
Digital traceability systems and advanced catalyst platforms are compressing development cycles while regulatory convergence across major healthcare markets is standardizing qualification protocols.
Neodymium-based rare-earth catalysis is digitizing production control through real-time molecular weight monitoring and automated cis-content adjustment. Tire manufacturers in Japan and South Korea are adopting these systems to reduce batch-to-batch variation. The technology is digitizing quality assurance workflows that previously required offline chromatography, enabling continuous processing economics.
EU MDR's updated biocompatibility documentation requirements are extending technical file preparation timelines for polyisoprene device components. Manufacturers must now submit exhaustive chemical characterization data including extractables and leachables profiles. The regulation most heavily impacts small-volume catheter producers who lack in-house toxicology expertise, forcing partnerships with specialized testing laboratories.
Hospital procurement consortia are consolidating glove and catheter purchasing through centralized tender platforms that prioritize multi-year supply security over unit cost. Group purchasing organizations in the United States and Germany are displacing fragmented distributor relationships with direct manufacturer contracts. This consolidation is most visible in academic medical centers where supply chain resilience metrics now outweigh price in vendor scorecards.
Polyisoprene Market Segmentation
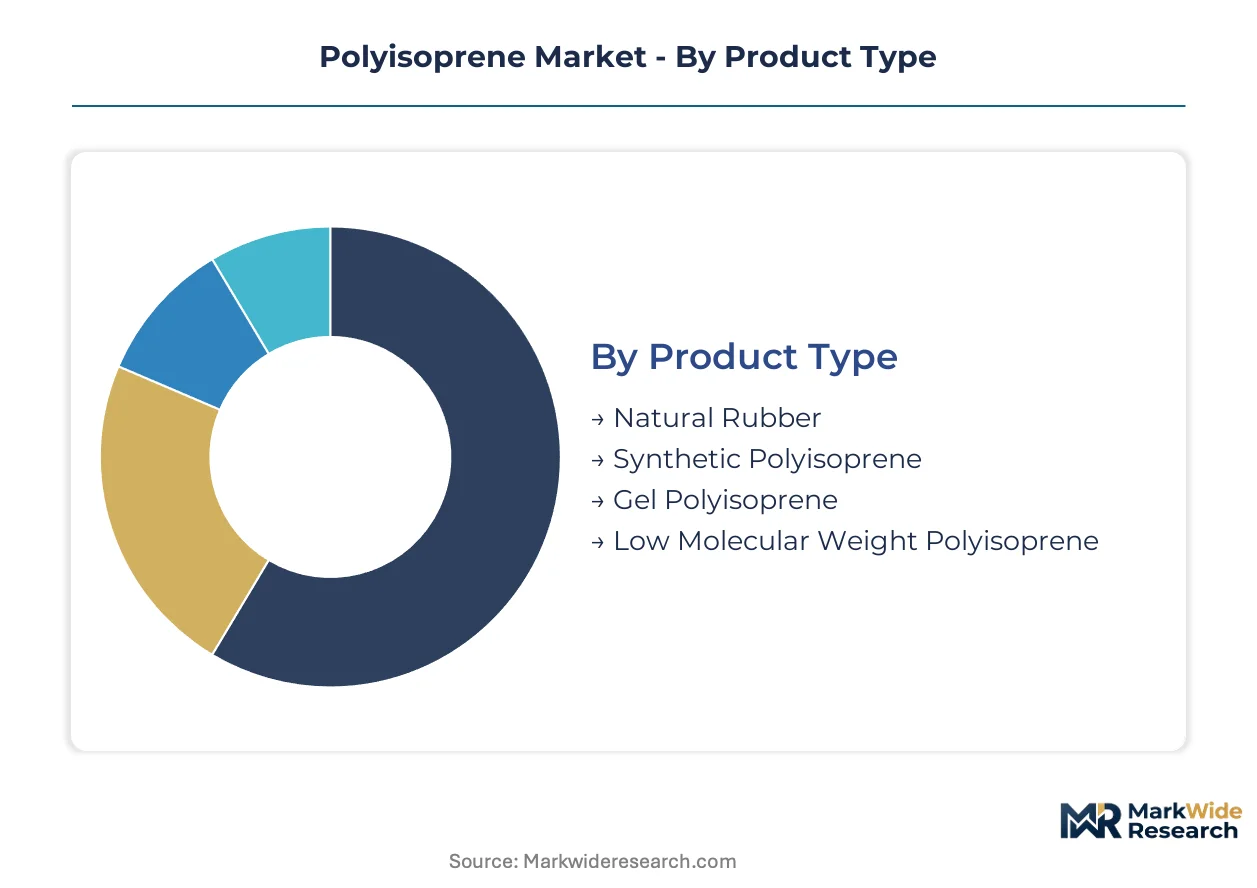
Polyisoprene market segmentation reveals divergent value capture across material grades and end-use certification requirements. Medical-grade synthetic variants command substantial margin premiums over commodity natural rubber, while form factor selection directly determines processing economics and application feasibility.
Product Type:
Mature extraction methods dominate natural rubber supply, while synthetic polymerization technologies are accelerating toward cost parity with Hevea-derived material.
- Synthetic Polyisoprene:Manufactured via Ziegler-Natta or rare-earth catalyzed stereospecific polymerization achieving 92-97% cis-1,4 configuration. Demand concentrates in German and French surgical glove procurement systems where latex-free mandates eliminate allergen exposure risks. REACH chemical registration requirements disqualify uncertified alternatives from EU medical device supply chains.
- Natural Rubber:Harvested from Hevea brasiliensis plantations through coagulation and drying processes yielding variable protein content. Thailand and Indonesian plantations maintain cost advantages for commodity tire applications in emerging Asian automotive markets, though protein variability limits medical-grade qualification.
- Gel Polyisoprene:Crosslinked elastomer networks exhibiting swollen gel-phase behavior for specialized damping applications.
- Low Molecular Weight Polyisoprene:Oligomeric fractions serving adhesive tackifiers and sealant formulations.
Synthetic Polyisoprene retains volume leadership; Gel Polyisoprene holds the steepest expansion curve.
End User:
Application requirements stratify across regulated medical environments, high-volume automotive production, and cost-sensitive consumer manufacturing.
- Medical Devices:Catheters, surgical gloves, and infusion components requiring ISO 10993 biocompatibility certification and sterile processing validation. Gamma irradiation and ethylene oxide sterilization protocols impose 18-24 month qualification timelines that concentrate procurement among validated suppliers capable of sustaining multi-year compliance cycles.
- Automotive Industry:Tire treads, engine mounts, and suspension bushings demanding fatigue resistance across temperature extremes. Japanese and South Korean tire manufacturers are adopting neodymium-based catalysis systems to reduce batch-to-batch variation in high-durability applications.
- Consumer Goods:Ergonomic grips, sporting equipment, and household products where cost sensitivity limits synthetic adoption.
- Footwear Manufacturing:Soling compounds and cushioning layers competing with polyurethane and EVA alternatives.
Automotive Industry retains volume leadership; Medical Devices holds the steepest expansion curve.
Form:
Processing method selection determines material handling economics and finished part dimensional precision.
- Solid:Bales and pellets serving conventional compression and injection molding operations with established compounder infrastructure.
- Liquid:Low-viscosity dispersions enabling cast molding and dip-coating processes for complex geometries.
- Sheet:Calendered rolls for die-cutting gaskets and membrane fabrication in continuous production environments.
- Foam:Expanded cellular structures for cushioning and vibration isolation applications.
Solid retains volume leadership; Liquid holds the steepest expansion curve.
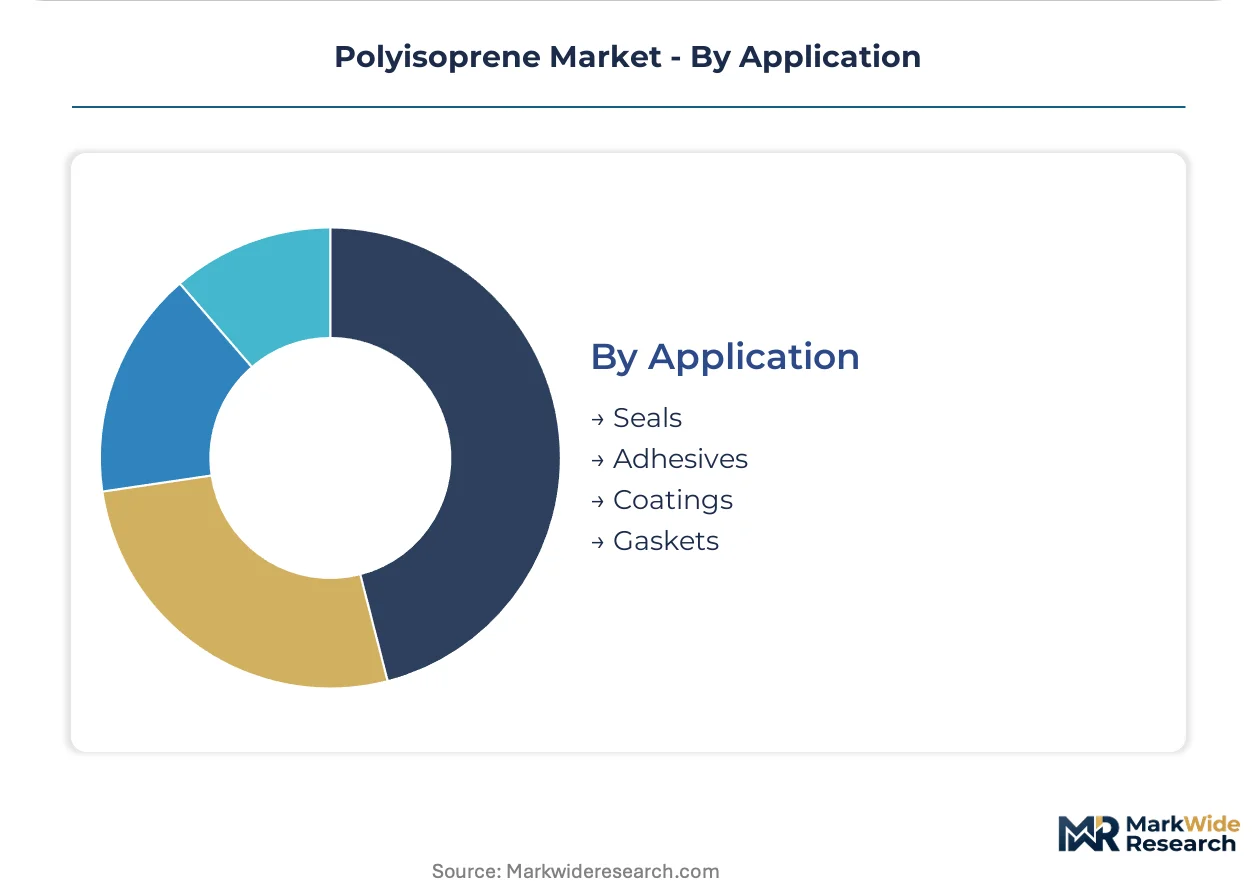
Application:
Functional performance requirements drive material specification across sealing, bonding, and protective coating functions.
- Seals:Dynamic and static sealing elements requiring compression set resistance and fluid compatibility across automotive and industrial machinery.
- Gaskets:Flange and joint sealing components fabricated via die-cutting from calendered sheet stock.
- Adhesives:Pressure-sensitive and structural bonding formulations leveraging tackifier compatibility.
- Coatings:Protective and friction-modifying surface treatments for specialized industrial substrates.
Seals retains volume leadership; Coatings holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU REACH chemical registration and India's PLI scheme for medical devices are redirecting polyisoprene procurement flows toward certified supply hubs. Government procurement mandates in Germany and France accelerate latex-free substitution. China's synthetic rubber capacity expansion anchors feedstock security for tire manufacturers.
China
Domestic Ziegler-Natta catalyst production and automotive tire manufacturing scale are concentrating polyisoprene demand in Shandong and Jiangsu provinces. The Ministry of Ecology and Environment enforces dual carbon goals that tighten emissions standards for petrochemical polymerization facilities. Qingdao's rubber industry cluster hosts integrated isoprene-to-polymer operations serving Bridgestone and Michelin regional tire plants.
Germany
Hospital procurement consortia in Bavaria and North Rhine-Westphalia mandate latex-free surgical gloves through centralized tender platforms. ECHA's expanded REACH substance evaluation protocols disqualify uncertified natural rubber from Class IIa medical device supply chains. Leverkusen's chemical corridor accommodates medical-grade polyisoprene compounders supplying catheter manufacturers under ISO 10993 certification.
United States
Group purchasing organizations at academic medical centers prioritize supply chain resilience metrics over unit cost in vendor scorecards. FDA biocompatibility guidance under 21 CFR Part 820 extends sterile processing validation timelines for new polyisoprene device introductions. Akron's polymer engineering corridor retains specialized talent for stereospecific catalysis and medical device regulatory science.
India
CDSCO streamlined Class C/D device approvals and PLI scheme incentives attract polyisoprene compounders to Gujarat and Maharashtra manufacturing clusters. The Bureau of Indian Standards enforces medical device quality management system certifications for domestic market access. Ahmedabad's medical device special economic zone hosts sterile processing facilities for surgical glove exporters targeting EU and US markets.
Japan
Neodymium-based rare-earth catalysis adoption by tire manufacturers reduces batch-to-batch variation in high-durability applications. METI's chemicals management policy prioritizes sustainable polymerization technologies under national green growth strategy. Osaka's Kansai industrial corridor concentrates synthetic rubber R&D facilities serving domestic automotive OEMs and medical device subcontractors.
Polyisoprene Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered certification requirements. Tire manufacturers with captive polymerization capacity anchor volume procurement through backward integration into isoprene feedstocks. Medical-grade specialists command pricing power via multi-year ISO 10993 qualification cycles that disqualify commodity producers. Dominant competitive moves include strategic partnerships with catalyst technology licensors and geographic expansion into Indian medical device manufacturing clusters.
Within the integrated tire manufacturer tier, Bridgestone Corporation and Michelin exemplify archetypes combining feedstock security with proprietary compounding expertise. JSR Corporation occupies a position representing synthetic rubber technology leadership sustaining premium positioning in medical-grade segments. These three anchors illustrate divergent strategic paths: backward integration for supply security versus technology licensing for high-margin medical applications.
| Leading Market Players |
|---|
| Goodyear Tire & Rubber Company |
| Bridgestone Corporation |
| Michelin |
| JSR Corporation |
| Zeon Corporation |
| Kuraray Co., Ltd. |
| Continental AG |
| Exxon Mobil Corporation |
| PJSC Nizhnekamskneftekhim |
| Others |
Cost & Logistics Intelligence
Single-source dependency on Chinese and Japanese Ziegler-Natta catalyst production determines both pricing tier spreads and supply chain shape, compressing compounder margins during feedstock spikes while concentrating procurement leverage among tire manufacturers with captive isoprene supply.
Pricing Analysis
Certification level creates the primary spread across medical-grade, automotive-grade, and commodity tiers. Pricing stratifies across premium, standard, and economy levels based on ISO 10993 biocompatibility validation and neodymium-based catalyst performance. Cost compression in the commodity tier is intensifying because natural rubber from Thai and Indonesian plantations maintains cost advantages. Hospital procurement consortia exhibit the lowest price sensitivity, while consumer goods manufacturers demonstrate acute cost consciousness.
Supply Chain Analysis
Export-control regimes on rare-earth catalyst technology limit flows from Chinese and Japanese specialty chemical houses to qualified polymerization facilities. Geographic supply concentrates in China, Japan, and Germany, with Shandong province and Osaka's Kansai corridor anchoring catalyst and polymer production. Raw material dependencies rest on isoprene monomer from petrochemical crackers, neodymium catalyst systems, and gamma-irradiation sterilization equipment. Single-source vulnerability in catalyst supply creates structural risk. Distribution runs through tire manufacturer direct procurement and hospital group purchasing organization platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from cyclical feedstock volatility as crude oil price stabilization restores compounder margin visibility across the analysis window.
For Market Incumbents: Pre-empt margin erosion by securing backward integration into isoprene feedstocks through long-term offtake agreements with crackers in Shandong and Jiangsu provinces. Accelerate neodymium-based catalyst adoption to reduce batch-to-batch variation and defend premium positioning against emerging Indian compounders leveraging CDSCO streamlined approvals.
For New Entrants and Emerging Players: Pursue white-space opportunities in wearable drug delivery systems requiring micropump diaphragm certification, where sterile processing validation barriers filter out commodity producers. Target Gujarat and Maharashtra medical device clusters under India's PLI scheme, entering through partnerships with sterile processing facilities in Ahmedabad's special economic zone.
For Investors and Strategic Acquirers: EU MDR's updated biocompatibility documentation requirements reshape the acquisition landscape by extending technical file preparation timelines and forcing partnerships with specialized toxicology laboratories. Long-term viability centers on medical-grade specialists with sustained ISO 10993 compliance cycles. Watch for inflection signals in CDSCO Class C/D device approval velocity indicating Indian manufacturing cluster maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isoprene Feedstocks | Bridgestone and Michelin anchor supply security through captive petrochemical relationships in Qingdao. |
| Neodymium-Based Catalyst Adoption | Japanese tire manufacturers reduce batch-to-batch variation through real-time molecular weight monitoring systems. |
| ISO 10993 Certification Investment | Medical-grade specialists sustain pricing power through 18-24 month sterile processing validation cycles. |
| Indian Manufacturing Cluster Expansion | CDSCO streamlined approvals and PLI incentives attract compounders to Gujarat and Maharashtra. |
| Green Chemistry Catalyst Development | Bio-based isoprene from lignocellulosic sources converges with enzymatic polymerization research. |
Research Approach
Initial hypotheses were tested against primary input from polymer plant managers, medical device procurement leads at German hospital consortia, tire manufacturer R&D directors, and catalyst technology licensors, then refined against secondary validation from customs/trade data, SEC 10-K filings of listed synthetic rubber producers, ECHA REACH registration databases, and CDSCO device approval records. Bottom-up volume modeling triangulated with top-down market sizing across medical device, automotive, and consumer end-use segments.
Demand-supply balance dynamics anchored the analytical framework across the analysis window, with segmentation modeled by material grade tier, end-use certification requirement, form factor, and regional regulatory cluster. CAGRs were derived from regression analysis of historical capacity utilization and forward projection of latex-free substitution mandates. Industry-specific forecast inputs incorporated neodymium catalyst adoption curves and EU MDR implementation timelines.
Sensitivities concentrate around crude oil price volatility, REACH substance evaluation protocol expansions, and rare-earth export license restrictions. Forecasts reflect documented assumptions on catalyst technology diffusion rates and hospital procurement consolidation patterns. Material shifts in isoprene monomer supply geography or gamma-irradiation sterilization capacity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Rubber Choppers Market
Rubber
Rubber Ropes Market
Rubber
Rubber Carbon Black Market
Rubber
Liquid Polybutadiene Market
Rubber
Rubber Sheets Market
Rubber
FKM Elastomers Market
Rubber
Rubber Gloves Market
Rubber
Rubber Coatings Market
Rubber
Chloro-Sulfonated Polyethylene Market
Rubber
EMEA and Asia Pacific Electrical Insulating Rubber Gloves Market
Rubber
EPDM Market
Rubber
Polyisoprene Rubber Market
Rubber
Sterile Rubber Stopper Market
Rubber
Silicone Rubber Market
Rubber
Rubber Chemicals Market
Rubber
Tire Softener Market