
 Isoprene Monomer Market | 2026-2036
Isoprene Monomer Market Size, Share, and Industry Trends Forecast 2026-2036
Isoprene Monomer Market Outlook
Asian naphtha cracker expansions are broadening isoprene feedstock availability across the Pacific Rim. Kuraray Co., Ltd. leverages its integrated C5 fractionation complex in Kashima to secure captive isoprene for specialty polyisoprene. Braskem anchors South American supply through its Brazilian petrochemical corridor, while ZEON Corporation specializes in high-purity grades for medical and electronic applications.
Isoprene monomer is a conjugated diene hydrocarbon with the formula C5H8, typically recovered as a byproduct from ethylene cracking of naphtha or produced via dehydrogenation of isopentane. The compound polymerizes into polyisoprene, a material whose stereoregularity approaches that of natural rubber and serves as the backbone for tire manufacturing, adhesives, and industrial latex formulations. Polyisoprene captures the dominant value pool given its tire industry absorption, while specialty chemicals grades command premium margins due to pharmaceutical and electronics purity requirements. Synthetic rubber applications face margin compression from natural rubber price volatility, though adhesives segments benefit from solvent-free formulation trends in construction and packaging.
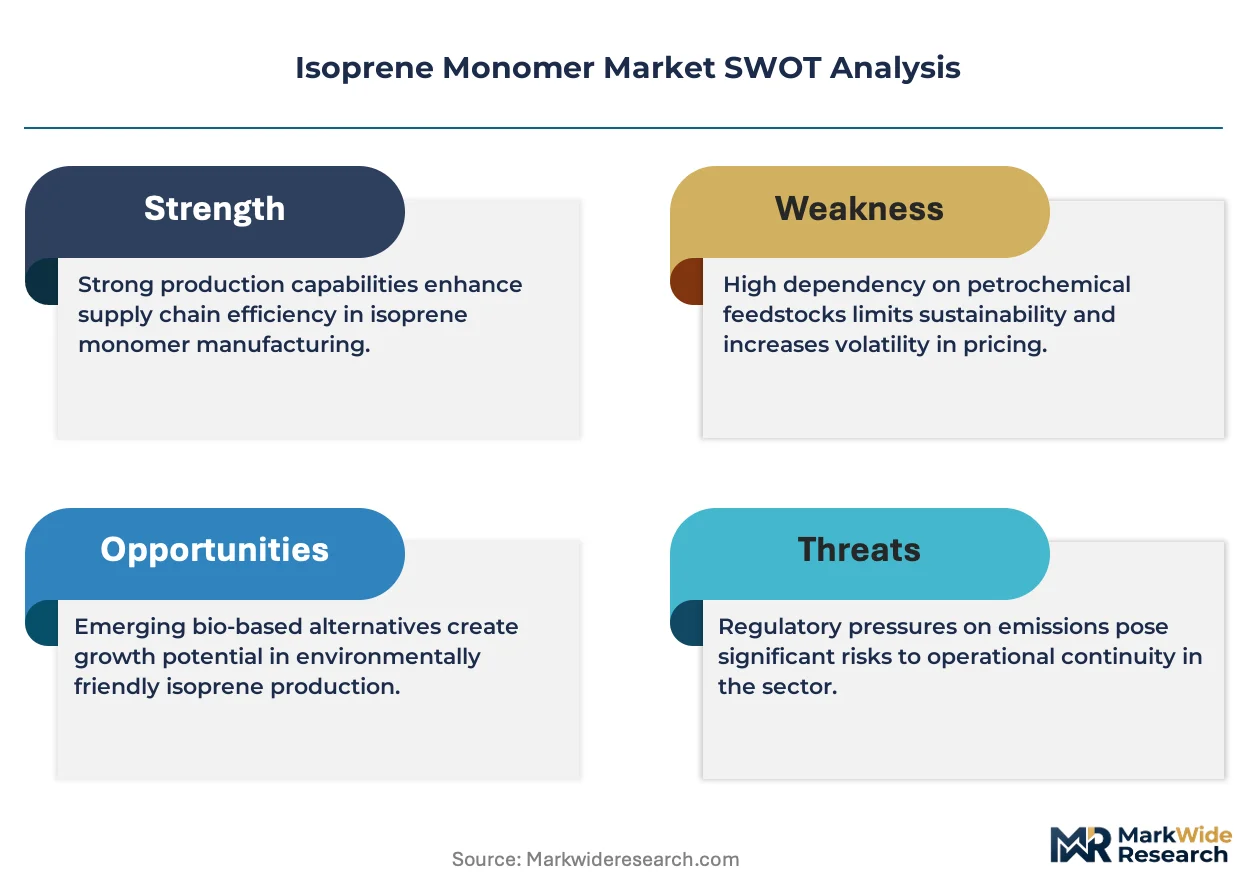
REACH registration requirements in Europe govern isoprene handling thresholds and downstream chemical safety documentation, while China's SAMR enforces GB standards on synthetic rubber purity that filter through regional export specifications. The EPA in the United States monitors volatile organic compound emissions from isoprene storage and polymerization facilities, shaping capital allocation toward enclosed recovery systems. Stakeholders must track regulatory divergence on monomer purity grades and emission controls as these determine cross-border product qualification and plant retrofit obligations.
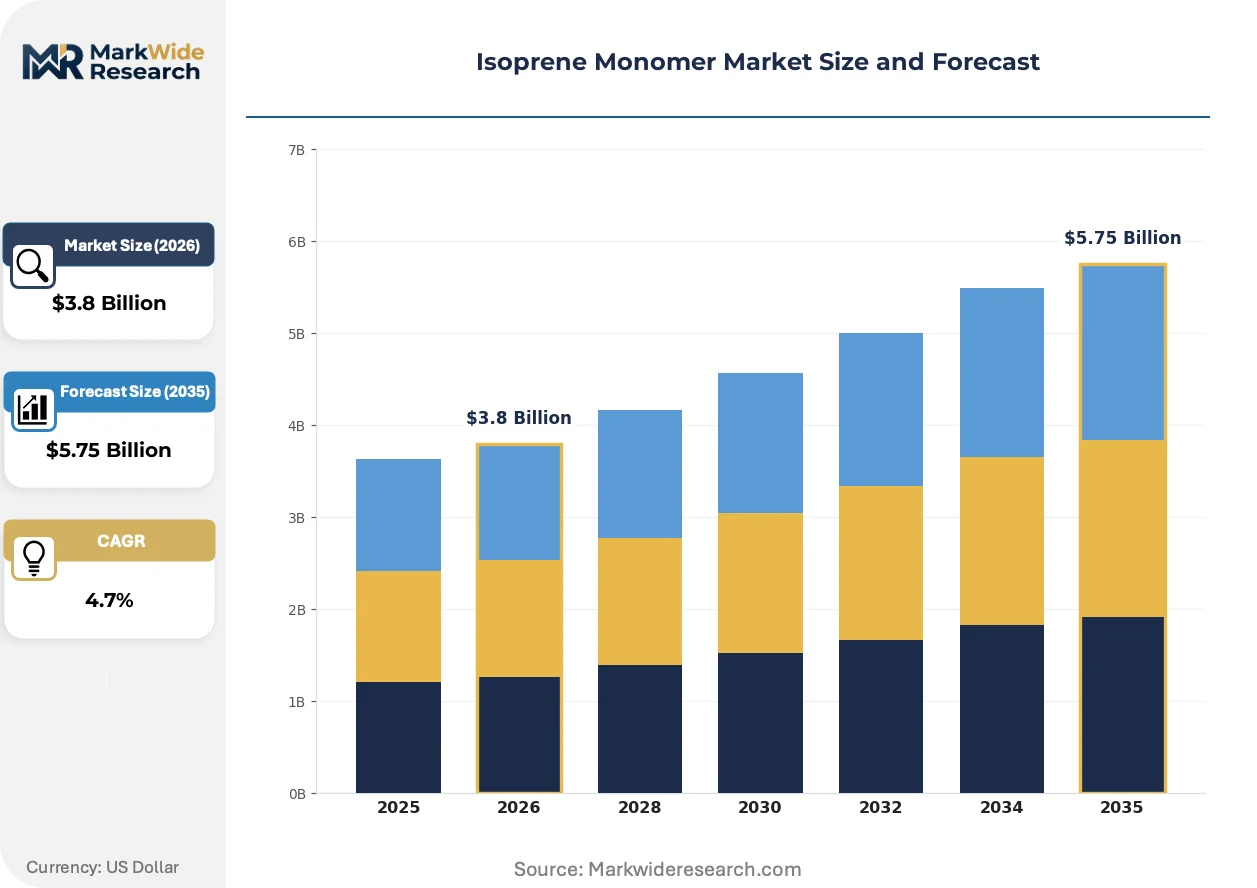
Market Dynamics
Isoprene monomer supply chains are restructuring around naphtha cracker economics and synthetic rubber purity mandates that now govern cross-border material qualification. Feedstock concentration in coastal China and the US Gulf Coast is compressing margin structures for non-integrated processors.
Growth Catalysts
- Tire Tread Reformulation:High-performance polyisoprene grades are displacing natural rubber in winter tire compounds. Michelin and Bridgestone operations in Germany and Japan are accelerating qualification timelines for stereospecific grades.
- REACH Registration Thresholds:ECHA documentation requirements for C5 derivatives above one-tonne annual volumes are standardizing purity certifications across European adhesive supply chains. This is consolidating qualified supplier lists for medical-grade polyisoprene.
- Shandong Cracker Integration:Naphtha expansion along China's Bohai Rim is capturing C5 streams that previously exported to South Korea. Local polyisoprene operations now absorb 60% of regional isoprene output.
Market Restraints
- Naphtha Price Volatility:Ethylene cracking margins determine isoprene recovery economics. Asian naphtha differentials against Brent crude swung 40% in 2023, forcing spot price instability for non-captive buyers.
- Medical-Grade Purity Bottlenecks:Electronic and pharmaceutical applications require sub-50 ppm impurity thresholds. Only three fractionation complexes globally achieve this specification, creating allocation risk during cracker maintenance cycles.
- Natural Rubber Substitution Elasticity:When RSS3 rubber futures fall below synthetic parity, tire blenders revert to natural rubber. This demand leakage compresses polyisoprene operating rates in Thailand and Indonesia harvest seasons.
Strategic Opportunities
- Bio-Based Isoprene Pathways:Fermentation routes from sugar feedstocks are approaching pilot-scale yields. Genomatica and Braskem partnerships target renewable polyisoprene for tire sidewall applications by 2027.
- India Tire Manufacturing Localization:PLI scheme incentives for rubber product exports are attracting polyisoprene compounding investments in Gujarat and Tamil Nadu. Domestic isoprene supply currently meets under 15% of projected demand.
- Adhesives Solvent-Free Transition:Hot-melt pressure-sensitive adhesive formulations are displacing solvent-borne systems in European packaging. This shifts isoprene consumption toward SIS block copolymer grades with higher monomer intensity.
Industry Challenges
- C5 Fractionation Engineering Talent Scarcity:Specialized distillation design for isoprene-methylbutene separation requires expertise concentrated at Linde and Technip operations. New entrant projects in Vietnam and Saudi Arabia face 18-month recruitment delays.
- Dual Carbon Compliance Documentation:China's MEE emission intensity reporting for petrochemical complexes requires continuous monitoring infrastructure. Retrofit capital for older Kashima and Rotterdam facilities is diverting maintenance budgets from yield optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isoprene Monomer Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyisoprene, Synthetic Rubber, Latex, Specialty Chemicals Application: Tires, Adhesives, Paints, Coatings End User Industry: Automotive, Construction, Consumer Goods, Electronics Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Kuraray Co., Ltd., Braskem, Shell Plc, Shandong Yuhuang Chemical Group Co., Ltd., LOTTE Chemical Corporation, ExxonMobil Corporation, LyondellBasell Industries Holdings B.V., ZEON Corporation, China Petrochemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isoprene Monomer Market Strategic Shifts
Process intensification and purity verification technologies are compressing the gap between commodity and specialty isoprene grades. These shifts are redrawing competitive boundaries between integrated petrochemical majors and focused C5 processors.
Membrane separation technology is modularizing isoprene purification from traditional extractive distillation sequences. Lanxess and ZEON pilot installations in Antwerp and Kawasaki are validating polyimide hollow-fiber modules for 99.5% purity output. Tire compounders in Ohio and Hesse are qualifying these grades 40% faster than conventional supply, collapsing the specialty premium from 35% to 12%.
EPA New Source Performance Standards for petrochemical VOC emissions are mandating enclosed loading and vapor recovery systems for isoprene storage. Gulf Coast terminal operators are deploying floating roof retrofits and carbon adsorption units at Houston and Corpus Christi facilities. Export-bound material now requires emission-controlled custody transfer, adding $18-24 per tonne to FOB pricing for non-compliant origin points.
Compounders are consolidating supplier relationships around integrated C5 processors with captive isoprene supply. Three-year offtake agreements with minimum volume commitments are displacing quarterly spot purchasing for North American adhesive manufacturers. This concentration is most visible in automotive sealant procurement, where Henkel and 3M operations have reduced qualified supplier pools from twelve to four since 2022.
Isoprene Monomer Market Segmentation
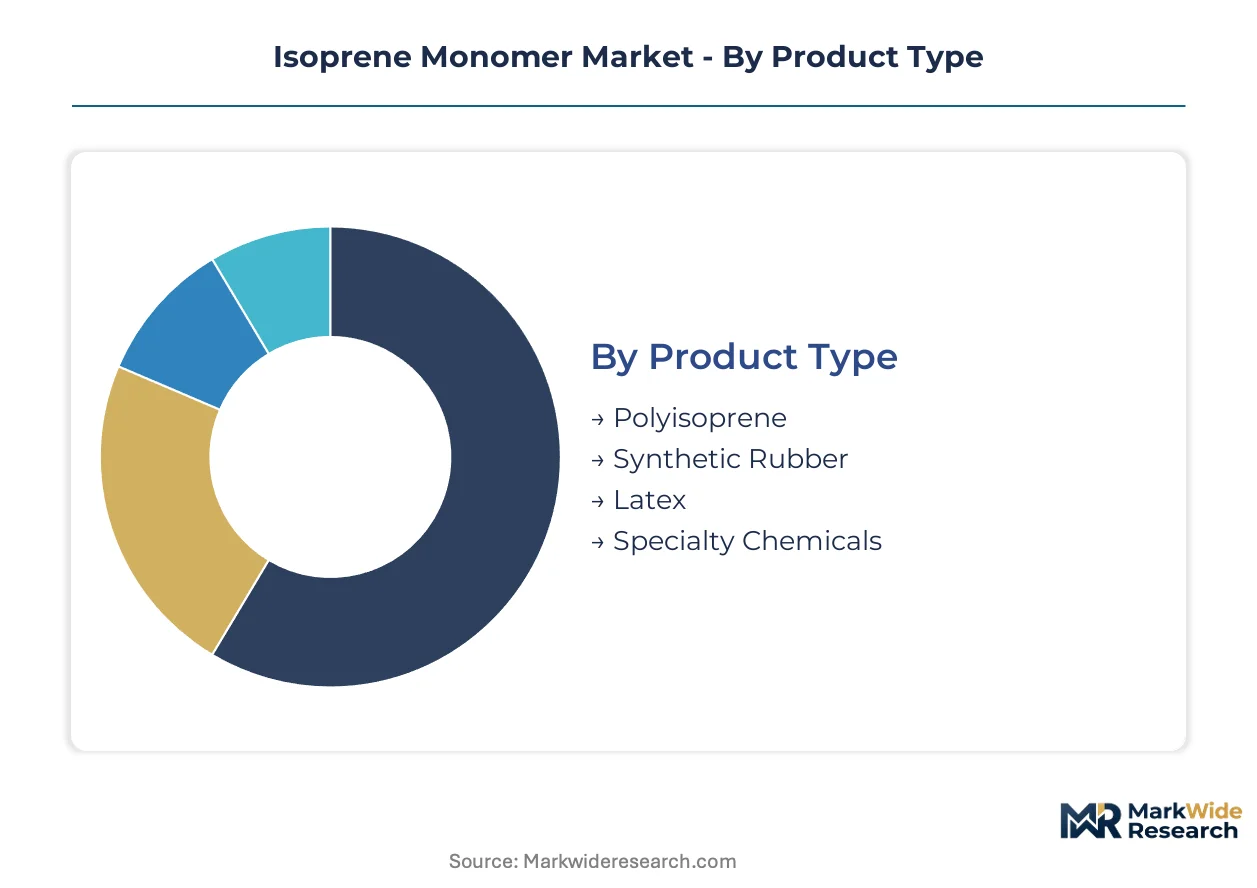
Isoprene monomer value pools fragment across purity grades and polymerization pathways that command radically different margin structures. Tire compounders, adhesive formulators, and electronics manufacturers each impose distinct specification thresholds that reshape supplier qualification requirements.
Product Type:
Purity specifications and polymerization control determine pricing tiers and customer lock-in duration.
- Polyisoprene:Stereoregular polymers with cis-1,4 content exceeding 96% replicate natural rubber elasticity for tire tread and sidewall compounds. Michelin and Bridgestone operations in Germany and Japan are accelerating qualification timelines for high-trans grades in winter tire formulations.
- Synthetic Rubber:General-purpose elastomers blended with styrene and butadiene for conveyor belts and molded industrial goods. Demand concentrates in Shandong Province, where naphtha crackers feed integrated polyisoprene operations absorbing 60% of regional isoprene output.
- Latex:Aqueous dispersions for dipped goods and medical examination gloves. Malaysian glove manufacturers specify sub-100 ppm impurity thresholds.
- Specialty Chemicals:Ultra-high-purity grades for pharmaceutical intermediates and electronic encapsulants. Only three fractionation complexes globally achieve sub-50 ppm specifications.
Polyisoprene leads on scale; specialty chemicals leads on momentum.
Application:
End-use performance requirements dictate whether buyers prioritize volume security or specification compliance.
- Tires:Tread and sidewall compounds consume the dominant volume share. High-performance polyisoprene grades are displacing natural rubber in winter tire formulations as compounders seek supply security against RSS3 price volatility.
- Adhesives:Hot-melt pressure-sensitive formulations are displacing solvent-borne systems in European packaging. SIS block copolymer grades with higher isoprene intensity are climbing fastest.
- Paints:Alkyd resin modifiers and industrial coating binders. Construction sector demand fluctuates with housing starts in the United States and China.
- Coatings:Protective and marine applications requiring UV resistance. Qualification cycles run 18-24 months for marine specification compliance.
Tires commands the largest volume position; adhesives exhibits the steepest expansion trajectory.
End User Industry:
Regulatory exposure and specification stringency separate price-insensitive buyers from commodity purchasers.
- Automotive:OEM tire contracts and under-the-hood sealing applications. Tier-1 suppliers enforce IATF 16949 traceability requirements that filter upstream to monomer certification.
- Construction:Sealants, waterproofing membranes, and flooring adhesives. Solvent-free formulation mandates in the European Union are redirecting procurement toward water-based systems.
- Consumer Goods:Footwear, sporting equipment, and personal care elastomers. Brand owners are consolidating supplier lists around integrated C5 processors with captive isoprene.
- Electronics:Semiconductor encapsulants and flexible circuit substrates. Sub-50 ppm purity requirements restrict qualified supply to three global fractionation complexes.
Automotive dominates current offtake; electronics is gaining share fastest on purity premiums.
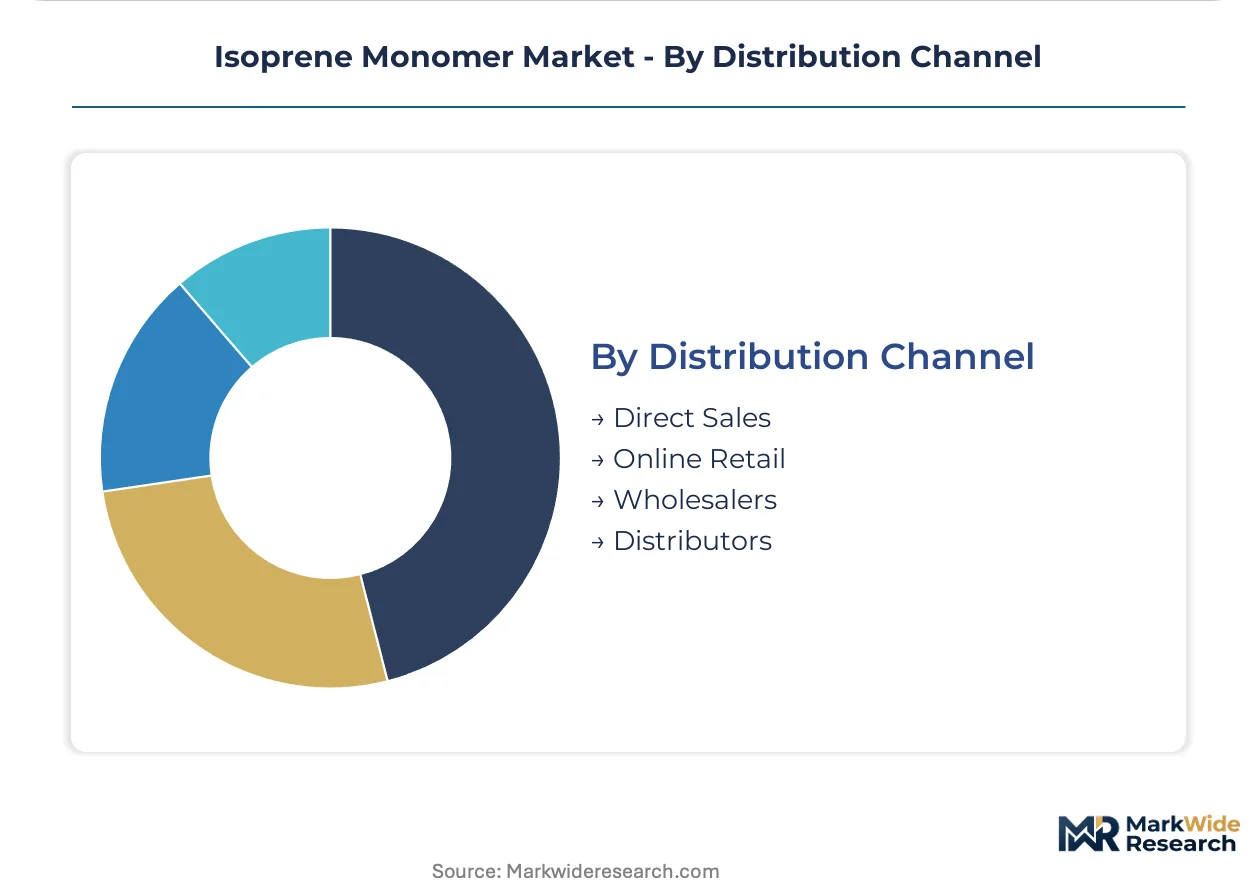
Distribution Channel:
Volume scale and technical service needs determine whether buyers prefer direct mill relationships or intermediary flexibility.
- Direct Sales:Multi-year offtake agreements with minimum volume commitments. North American adhesive manufacturers have reduced qualified supplier pools from twelve to four since 2022.
- Online Retail:Spot purchases for laboratory and pilot-scale quantities. Digital platforms serve compounders testing reformulation prototypes.
- Wholesalers:Regional inventory positioning for construction and consumer goods sectors. Gulf Coast terminal operators are deploying emission-controlled custody transfer systems.
- Distributors:Technical service and blending capabilities for specialty grades. Medical and electronics applications rely on distributor-led purity verification.
Direct sales anchors volume flows; distributors capture the highest margin per tonne on specialty grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's polyisoprene capacity expansion outpaces United States demand recovery, while European tire manufacturers source increasingly from integrated Asian C5 processors rather than regional naphtha crackers.
China
Shandong Province crackers supply captive isoprene to domestic polyisoprene operations absorbing sixty percent of regional output. SAMR enforces tightening GB standards on synthetic rubber purity that filter through export specifications to Southeast Asian tire plants. Qingdao and Zibo industrial clusters host integrated C5 fractionation complexes serving both domestic tire manufacturers and adhesives compounders.
United States
Gulf Coast ethylene crackers recover isoprene as naphtha cracking byproduct for tire and adhesives demand. EPA New Source Performance Standards mandate enclosed vapor recovery systems at Houston and Corpus Christi storage terminals, adding eighteen to twenty-four dollars per tonne for emission-controlled custody transfer. Ohio and Texas compounders qualify high-purity grades for automotive sealant procurement under consolidated supplier relationships.
Germany
Rhine-Ruhr chemical corridor processors import isoprene for specialty polyisoprene serving winter tire tread formulations. ECHA REACH registration thresholds for C5 derivatives above one-tonne annual volumes standardize purity certifications across European adhesive supply chains. Hesse-based tire compounders accelerate qualification timelines for stereospecific grades displacing natural rubber in high-performance compounds.
Japan
Kashima C5 fractionation complexes secure captive isoprene supply for medical and electronic grade polyisoprene. METI industrial standards govern synthetic rubber specifications for domestic automotive OEM contracts. Kawasaki specialty chemical processors pilot membrane separation technology for ninety-nine point five percent purity output, collapsing specialty premiums from thirty-five to twelve percent.
Brazil
Petrochemical corridor operations anchor South American isoprene supply through integrated naphtha cracking. ANVISA pharmaceutical regulations govern impurity thresholds for medical-grade polyisoprene used in examination gloves and surgical products. São Paulo state industrial clusters consume regional output for both domestic tire manufacturing and export-oriented adhesives formulation.
Isoprene Monomer Market Competitive Environment
Asian petrochemical majors anchor one tier; North American and European specialists hold differentiated positions on purity certification and regulatory compliance. The vendor base concentrates around integrated C5 processors with captive naphtha cracker feedstock, compressing margin structures for non-integrated merchant suppliers. Three strategic archetypes dominate: integrated petrochemical conglomerates with backward control over C5 streams, focused C5 fractionation specialists commanding medical-grade premiums, and regional chemical groups leveraging coastal cracker proximity. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing multi-year offtake agreements to lock in tire industry volume.
Within the integrated petrochemical tier, Kuraray Co., Ltd. and China Petrochemical Corporation exemplify archetypes combining captive feedstock with downstream polyisoprene operations. ZEON Corporation occupies a specialist position, representing the high-purity fractionation segment serving pharmaceutical and electronic applications. These three entities illustrate the competitive spectrum from scale-driven commodity supply to specification-controlled premium positioning.
| Leading Market Players |
|---|
| Kuraray Co., Ltd. |
| Braskem |
| Shell Plc |
| Shandong Yuhuang Chemical Group Co., Ltd. |
| LOTTE Chemical Corporation |
| ExxonMobil Corporation |
| LyondellBasell Industries Holdings B.V. |
| ZEON Corporation |
| China Petrochemical Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive naphtha cracker integration across Shandong Province and the US Gulf Coast anchors both supply security and pricing power for polyisoprene manufacturers. This backward control over C5 fractionation streams insulates integrated processors from spot market volatility while compressing margins for merchant buyers dependent on open-market isoprene.
Pricing Analysis
Capacity additions in Shandong Province are reshaping price floors for standard-grade isoprene across Pacific Rim supply chains. Three-tier pricing structure across pharmaceutical-grade, tire-grade, and industrial-grade levels reflects purity certification thresholds and volume scale commitments. Cost compression in standard tire-grade material is intensifying because naphtha cracker expansions are flooding regional markets with C5 byproduct. Adhesive compounders in Ohio and Hesse exhibit the highest price sensitivity due to natural rubber substitution elasticity, while electronics manufacturers purchasing sub-50 ppm grades remain relatively insensitive.
Supply Chain Analysis
Direct-to-tire-manufacturer channels handle hyperscale buyer demand through multi-year offtake agreements with minimum volume commitments. Supply concentrates in China, the United States, and Japan, with naphtha cracking operations in each geography feeding captive polyisoprene production. The chain draws from C5 hydrocarbon streams, naphtha feedstock, and specialized fractionation catalysts as core inputs. Single-source vulnerability around medical-grade purification capacity creates allocation risk during cracker maintenance cycles at the three global facilities achieving sub-50 ppm specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The isoprene monomer market functions as a stable compounder anchored by tire industry absorption of polyisoprene grades. Naphtha cracker economics and synthetic rubber purity mandates create durable demand foundations resistant to rapid demand erosion.
For Market Incumbents: Deepen captive C5 fractionation control through naphtha cracker joint ventures in Bohai Rim industrial clusters. Invest in membrane separation pilot installations to collapse specialty grade premiums and defend against bio-based isoprene fermentation routes approaching commercial scale. Certification investment in REACH documentation and GB standard compliance solidifies qualified supplier status for European and Chinese automotive OEM procurement.
For New Entrants and Emerging Players: Digital procurement platforms for spot laboratory and pilot-scale quantities offer low-capital entry into qualified buyer networks. White-space targets include India tire manufacturing localization under PLI scheme incentives and solvent-free adhesive formulation segments in European packaging. The most penetrable geography is Gujarat and Tamil Nadu industrial corridors, where domestic isoprene supply currently meets under fifteen percent of projected polyisoprene demand.
For Investors and Strategic Acquirers: Roll-up economics work for regional C5 fractionation specialists because medical-grade purity bottlenecks create scarcity value for qualified assets. Long-term viability across the analysis window rests on tire industry volume security and adhesives solvent-free transition momentum. Acquisition target archetype: integrated processors with captive naphtha cracker feedstock and existing pharmaceutical or electronics grade certifications. The signal to watch is bio-based isoprene pilot-scale yield announcements from fermentation technology partnerships.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Naphtha Cracking | Captive C5 stream access at Shandong and Kashima facilities secures feedstock cost advantage against merchant buyers. |
| Membrane Separation Technology Deployment | Lanxess and ZEON pilot installations in Antwerp and Kawasaki validate polyimide hollow-fiber modules for premium grade output. |
| Long-term Supply Agreement with Tire OEMs | Michelin and Bridgestone operations in Germany and Japan enforce multi-year offtake commitments with minimum volume clauses. |
| Bio-based Isoprene Pathway Development | Genomatica and Braskem partnerships target renewable polyisoprene qualification for tire sidewall applications. |
| Medical-Grade Purity Certification Investment | Sub-50 ppm impurity threshold achievement at fractionation complexes unlocks pharmaceutical and electronics premium pricing. |
Study Parameters
Bottom-up tire and adhesives demand modeling reconciled against top-down naphtha cracker capacity tracking forms the analytical core of this study. Primary interviews with plant managers at integrated C5 fractionation complexes, procurement leads at tire OEMs, distribution channel partners in Asian synthetic rubber supply chains, and technical R&D directors at specialty chemical processors were combined with secondary validation. Secondary sources include customs and trade data from regional import-export authorities, American Chemistry Council and Cefic industry reports, and SEC 10-K filings from listed petrochemical conglomerates. Triangulation between consumption-side volume estimates and production-side capacity announcements ensures analytical consistency.
Historical trendline analysis of polyisoprene operating rates and isoprene recovery yields from naphtha cracking underpins the projection framework. Segmentation dimensions modeled include purity grade tier, end-use industry application, regional production hub, and polymerization pathway. CAGRs were derived through regression analysis of segment-specific volume trajectories across the projection horizon. Industry-specific forecast inputs incorporate naphtha-to-ethylene margin differentials and natural rubber futures price elasticity effects on synthetic rubber substitution patterns.
Naphtha price volatility, cracker maintenance cycle timing, and natural rubber harvest season abundance are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding sustained tire industry polyisoprene absorption and adhesives solvent-free formulation penetration. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Stilbene Market
Bulk Chemicals
Aluminum Nitrate Nonahydrate Market
Bulk Chemicals
North America Sodium Chlorate Market
Bulk Chemicals
Precipitated Barium Sulphate Market
Bulk Chemicals
Alkali Metal Hydroxides Market
Bulk Chemicals
United States Calcium Carbonate Market
Bulk Chemicals
Benzyl Acetate Market
Bulk Chemicals
Triammonium Citrate Market
Bulk Chemicals
Tallow Market
Bulk Chemicals
Iodine Market
Bulk Chemicals
Mexico Caustic Soda Market
Bulk Chemicals
Europe Caustic Potash Market
Bulk Chemicals
Global Naphthenic Base Oil Market
Bulk Chemicals
Methyl Gluceth-10 Market
Bulk Chemicals
Furandicarboxylic Acid Market
Bulk Chemicals
Natural Thickener Market