
 Ischemia Reperfusion Injury Therapeutics Market | 2026-2036
Ischemia Reperfusion Injury Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Ischemia Reperfusion Injury Therapeutics Market Outlook
Phase III clinical-grade efficacy thresholds are redrawing competitive expectations for ischemia reperfusion injury therapeutics. Faraday Pharmaceuticals leverages its mitochondrial-targeted small-molecule platform to anchor development in acute myocardial infarction. Stealth BioTherapeutics Inc. specializes in mitochondrial dysfunction biology, sustaining a differentiated position through peptide-based cardiolipin protection. Omeros Corporation competes via its complement inhibition approach, extending its immunology expertise into reperfusion-related inflammatory cascades.
Ischemia reperfusion injury therapeutics comprise pharmacological agents designed to attenuate cellular damage triggered when blood flow resumes to previously oxygen-deprived tissue, typically involving modulation of reactive oxygen species, calcium overload, or inflammatory complement activation. These agents function to preserve organ viability during cardiac surgery, organ transplantation, and acute stroke intervention by interrupting programmed cell death pathways activated upon reperfusion. Monoclonal antibodies capture substantial development investment due to their precision in targeting complement proteins and cytokine mediators of reperfusion inflammation. Intravenous delivery dominates acute clinical settings where rapid therapeutic onset proves critical, though subcutaneous formulations gain traction in transitional care protocols. Organ transplantation represents the fastest-growing application segment, driven by expanded donor pool utilization and machine perfusion technologies that extend the therapeutic window.
The FDA and EMA maintain stringent efficacy benchmarks for cardioprotective agents, shaping trial design through adaptive pathways and requiring biomarker-validated endpoints that extend development timelines but elevate commercial confidence upon approval. The EU MDR framework imposes additional post-market surveillance obligations on advanced therapy medicinal products, directly influencing European market access strategies for novel biologics. Stakeholders must monitor evolving regulatory precedents for combination device-drug platforms in perfusion systems, as these integrated delivery mechanisms will determine next-generation competitive positioning.
Market Dynamics
Machine perfusion technologies are extending viable ischemic windows for donor organs, forcing therapeutic developers to recalibrate dosing protocols and endpoint designs around ex-vivo preservation timelines rather than traditional cold-storage benchmarks.
Growth Catalysts
- Expanded Donor Pool Utilization:United Network for Organ Sharing revised allocation algorithms now prioritize marginal donor organs that require pharmacological reperfusion protection. Transplant centers in Texas, California, and Florida have scaled IRU protocol adoption accordingly.
- EU MDR Adaptive Pathways:The European Medicines Agency's conditional approval framework for advanced therapy medicinal products compresses Phase II-to-III transition timelines. This regulatory architecture accelerates market access for mitochondrial-targeted biologics in Germany and the Netherlands.
- Complement Biology Validation:Academic medical centers at Duke, Stanford, and Toronto have established standardized complement activation biomarker panels. These reference protocols reduce clinical trial variability and de-risk novel therapeutic candidates.
Market Restraints
- Clinical Endpoint Heterogeneity:The FDA and EMA maintain divergent standards for cardioprotective efficacy validation. Trial sponsors face protocol duplication costs when pursuing simultaneous US and European approval.
- Specialized Cold-Chain Requirements:Peptide-based cardiolipin stabilizers require continuous temperature monitoring below minus 20 degrees Celsius. Distribution infrastructure gaps in secondary transplant markets constrain addressable geography.
- Biomarker Manufacturing Concentration:Contract research organizations for complement protein assays cluster in Massachusetts and Switzerland. This geographic concentration creates single-source vulnerability for diagnostic-dependent trials.
Strategic Opportunities
- Stroke Intervention Expansion:Mechanical thrombectomy adoption at comprehensive stroke centers in Pennsylvania, Ohio, and Georgia creates demand for adjunctive neuroprotective agents. IRU therapeutics targeting cerebral reperfusion represent unpenetrated indication territory.
- Japan PMDA Sakigake Designation:Japan's regenerative medicine priority review voucher system offers 50% fee reduction and dedicated consultation. Early entrants gain first-mover positioning in Asia-Pacific's second-largest transplant market.
- Perfusion-Device Convergence:Integration of pharmacological delivery modules into ex-vivo machine perfusion systems from TransMedics and XVIVO enables closed-loop therapeutic administration. Device-therapeutic bundling restructures procurement economics.
Industry Challenges
- Mitochondrial Toxicology Expertise Scarcity:Drug developers struggle to recruit investigators proficient in organelle-specific pharmacokinetic modeling. Academic training programs at Johns Hopkins and Imperial College London cannot scale output to industry demand.
- Multi-Site Protocol Harmonization:Transplant networks spanning the United States, Canada, and Australia require real-time biomarker standardization. Data integration across electronic health record systems creates operational friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ischemia Reperfusion Injury Therapeutics Market |
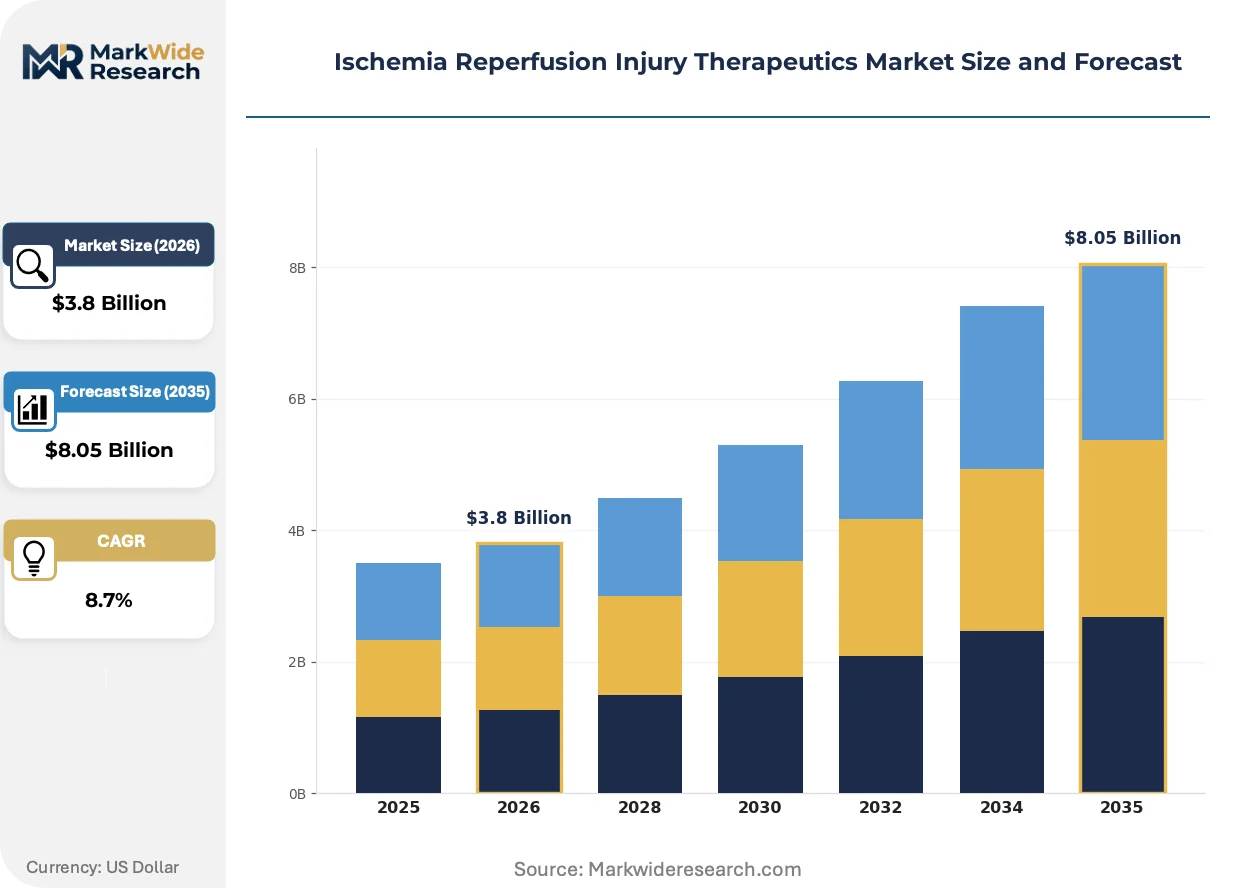
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Cytokine Inhibitors, Antioxidants, Enzyme Replacements Delivery Mode: Intravenous, Oral, Inhalation, Subcutaneous End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Laboratories Application: Cardiac Surgery, Organ Transplantation, Stroke Management, Peripheral Artery Disease |
| Companies Covered | Revive Therapeutics Ltd., Faraday Pharmaceuticals, Abiomed, Omeros Corporation, Pharming Group N.V., Stealth BioTherapeutics Inc., Zealand Pharma A/S, Amyndas Pharmaceuticals LLC, Opsona Therapeutics Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ischemia Reperfusion Injury Therapeutics Market Strategic Shifts
Biomarker-validated adaptive trial designs are compressing development timelines while elevating regulatory scrutiny on mechanistic proof-of-concept data.
Mitochondrial-targeted antioxidants is bifurcating development pathways between acute intravenous administration and sustained-release depot formulations. Academic medical centers in Boston and San Francisco prioritize rapid-onset candidates for myocardial infarction protocols. This technology segmentation is bifurcating competitive positioning between emergency medicine specialists and surgical care platforms.
The FDA's Project Optimus guidance on dose optimization now mandates exposure-response characterization for cardioprotective agents. Sponsors must enroll expanded cohorts to define therapeutic windows rather than relying on maximum tolerated dose paradigms. Early-phase programs in acute kidney injury and liver transplantation have restructured protocol designs to accommodate these evidentiary requirements.
Hospital procurement committees now require health economic modeling alongside clinical efficacy data for formulary inclusion. Transplant pharmacy directors at Cleveland Clinic and Mayo Clinic evaluate cost-per-quality-adjusted-life-year metrics for IRU agents. This purchasing behavior shift concentrates initial adoption at high-volume academic centers with dedicated outcomes research infrastructure.
Ischemia Reperfusion Injury Therapeutics Market Segmentation
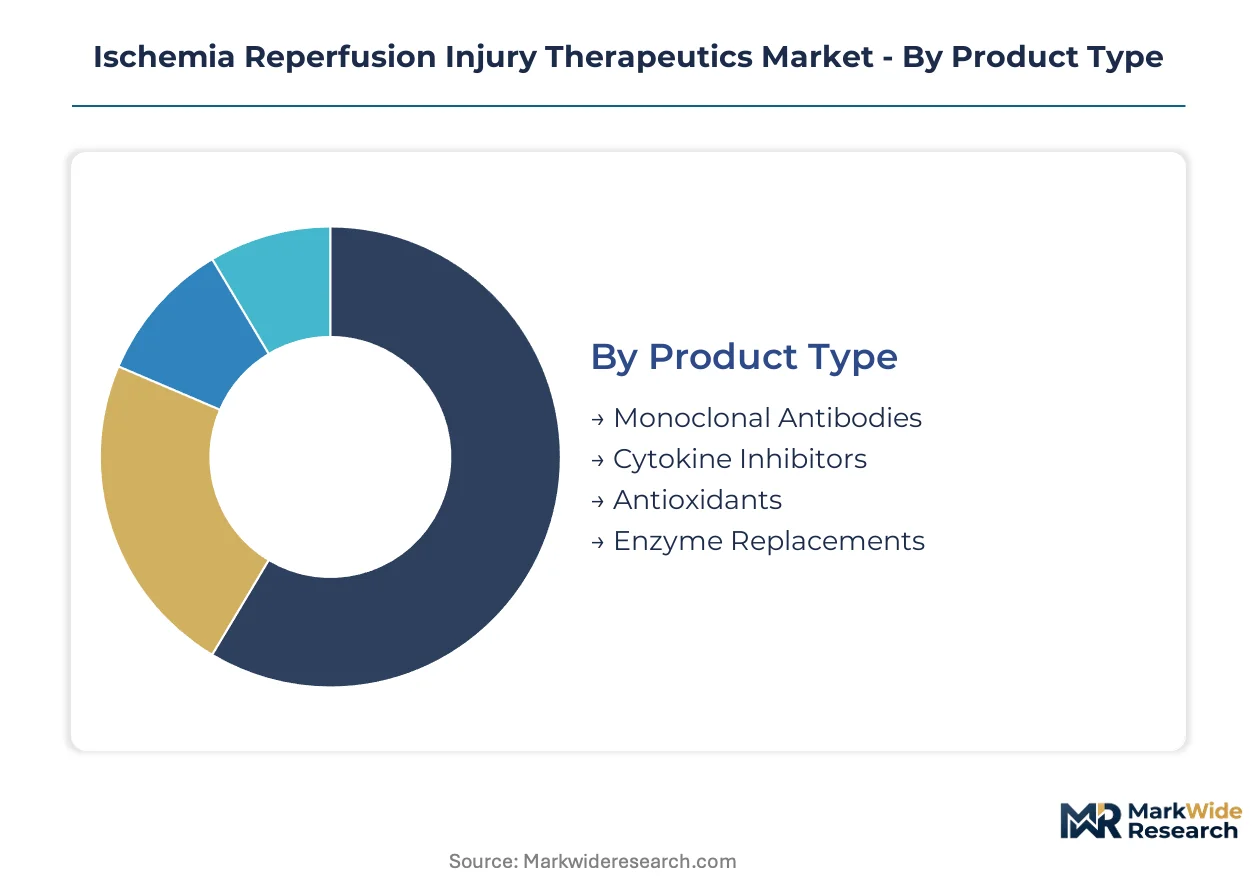
Therapeutic developers calibrate clinical trial designs and manufacturing scale around segment-specific regulatory pathways. Product type and delivery mode selections determine FDA versus EMA filing strategies, while application focus shapes endpoint validation requirements and hospital procurement economics.
Product Type:
FDA's Project Optimus dose-optimization guidance and EMA's adaptive pathway framework create divergent development timelines across molecular platforms.
- Monoclonal Antibodies:Engineered immunoglobulins targeting complement proteins C5a and C3a with high binding affinity. Demand concentrates at Duke, Stanford, and Toronto academic medical centers where standardized biomarker panels reduce trial variability for complement inhibition protocols.
- Antioxidants:Small-molecule scavengers of reactive oxygen species, including mitochondrial-targeted formulations like SS-31 analogs. Cardiac surgery units at Cleveland Clinic and Mayo Clinic prioritize rapid-onset intravenous variants for myocardial infarction protocols.
- Cytokine Inhibitors:Biologics interrupting IL-6 and TNF-alpha signaling cascades in reperfusion inflammation.
- Enzyme Replacements:Recombinant proteins restoring superoxide dismutase and catalase activity in ischemic tissue.
Established volume favors monoclonal antibodies; emerging adoption favors antioxidants.
Delivery Mode:
Route selection determines cold-chain infrastructure investment and acute versus transitional care market access.
- Intravenous:Direct vascular administration enabling immediate systemic distribution. Emergency departments and cardiac catheterization labs at Pennsylvania, Ohio, and Georgia stroke centers require this modality for mechanical thrombectomy adjuvant therapy.
- Subcutaneous:Depot formulations extending therapeutic exposure through sustained release. Transitional care protocols in Texas, California, and Florida transplant networks are climbing the fastest for peptide-based cardiolipin stabilizers requiring minus 20 degrees Celsius distribution.
- Oral:Enteric-coated formulations for outpatient chronic management of peripheral artery disease.
- Inhalation:Pulmonary delivery systems targeting localized reperfusion protection in lung transplantation.
Acute settings concentrate intravenous procurement; transitional protocols expand subcutaneous formulary inclusion.
End User:
Procurement authority and outcomes research infrastructure determine initial adoption sequencing across care settings.
- Hospitals:Integrated delivery networks with dedicated IRU protocols in cardiac surgery and organ transplantation units. United Network for Organ Sharing allocation algorithm changes have scaled adoption at high-volume academic centers with pharmacy and therapeutics committees requiring health economic modeling.
- Ambulatory Surgical Centers:Outpatient facilities performing peripheral vascular interventions with limited reperfusion therapeutic windows.
- Specialty Clinics:Focused stroke and transplant follow-up centers managing chronic immunomodulation.
- Research Laboratories:Contract research organizations in Massachusetts and Switzerland conducting complement protein assay development for diagnostic-dependent trials.
Procurement concentration favors hospitals; protocol innovation favors research laboratories.
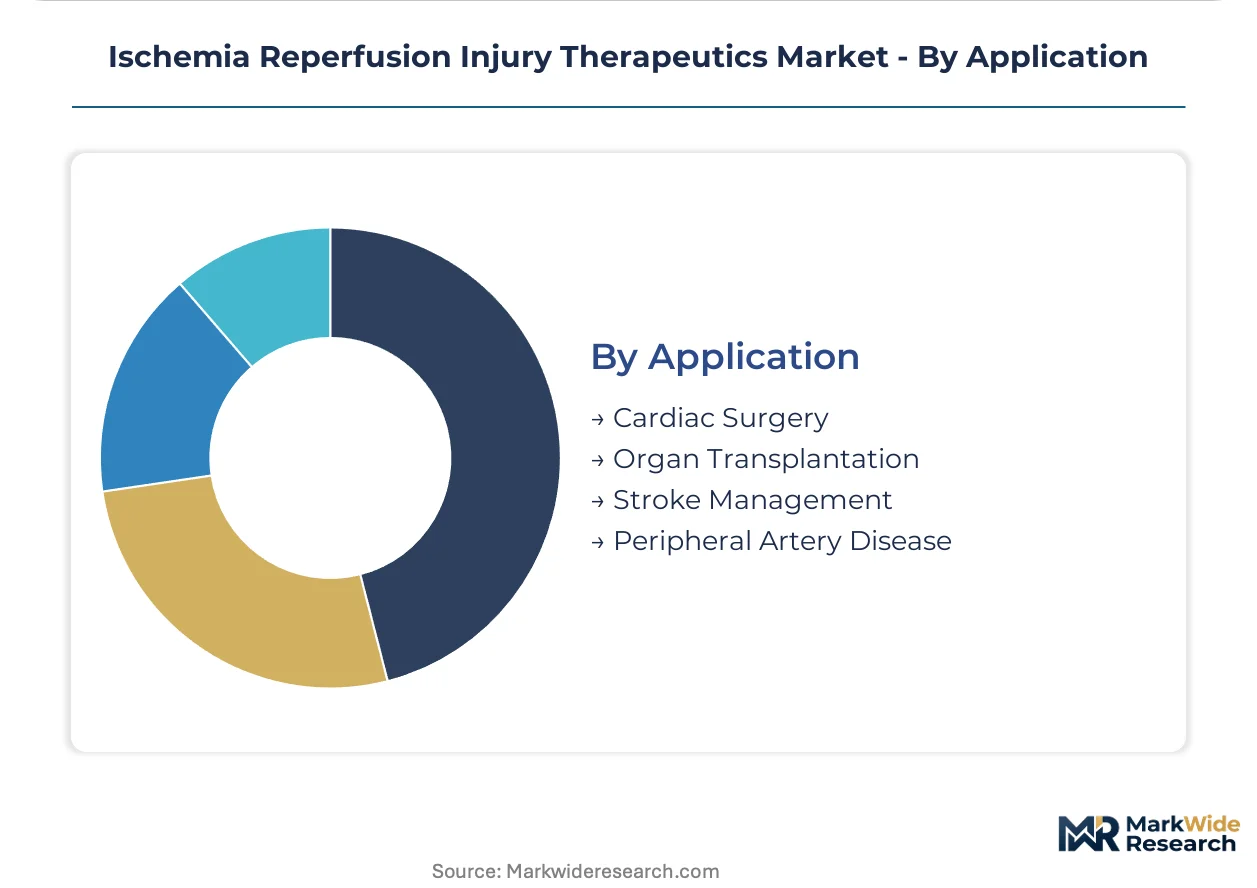
Application:
Ischemic window duration and organ preservation technology maturity reshape therapeutic positioning across clinical indications.
- Organ Transplantation:Pharmacological protection during ex-vivo machine perfusion and implantation reperfusion. Machine perfusion technologies from TransMedics and XVIVO are extending viable ischemic windows, forcing dosing recalibration around preservation timelines rather than cold-storage benchmarks.
- Cardiac Surgery:Myocardial protection during coronary artery bypass grafting and valve replacement procedures. Academic medical centers in Boston and San Francisco prioritize rapid-onset candidates for acute myocardial infarction protocols.
- Stroke Management:Neuroprotective adjuvants to mechanical thrombectomy with unpenetrated indication territory in comprehensive stroke centers.
- Peripheral Artery Disease:Limb salvage interventions requiring sustained reperfusion protection in diabetic and atherosclerotic populations.
Surgical volume anchors cardiac applications; technology convergence drives transplantation expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transplant center density and reimbursement generosity create sharp demand elasticity contrasts across markets. Academic medical centers in the United States absorb premium pricing for experimental biologics, while procurement committees in India and Brazil impose stringent cost-effectiveness thresholds on standard-of-care agents.
United States
UNOS allocation algorithm revisions prioritize marginal donor organs requiring pharmacological reperfusion protection. FDA's Project Optimus dose-optimization guidance mandates expanded exposure-response cohorts for cardioprotective agents. Duke, Stanford, and Cleveland Clinic anchor multi-site trial networks with standardized complement biomarker panels.
Germany
EMA adaptive pathway frameworks compress Phase II-to-III transitions for advanced therapy medicinal products. EU MDR post-market surveillance obligations reshape European market access strategies for novel biologics. Heidelberg and Berlin transplant clusters drive adoption of mitochondrial-targeted therapeutics in cardiac surgery protocols.
Japan
PMDA Sakigake designation offers 50% fee reduction and dedicated consultation for regenerative medicine candidates. METI priority review vouchers accelerate commercial timelines for Asia-Pacific's second-largest transplant market. Tokyo and Osaka academic centers establish reference protocols for complement inhibition in organ transplantation.
United Kingdom
NHS England specialized commissioning frameworks concentrate IRU therapeutic procurement at high-volume transplant centers. MHRA post-Brexit regulatory autonomy enables tailored approval pathways for machine perfusion-integrated drug delivery. Cambridge and London research clusters advance peptide-based cardiolipin stabilizer development.
China
NMPA innovative drug approval channels shorten review timelines for first-in-class mitochondrial protectors. Dual carbon goals drive investment in cold-chain efficiency for temperature-sensitive biologics distribution. Shanghai and Beijing hospital systems scale dedicated IRU protocols in cardiac surgery units.
Ischemia Reperfusion Injury Therapeutics Market Competitive Environment
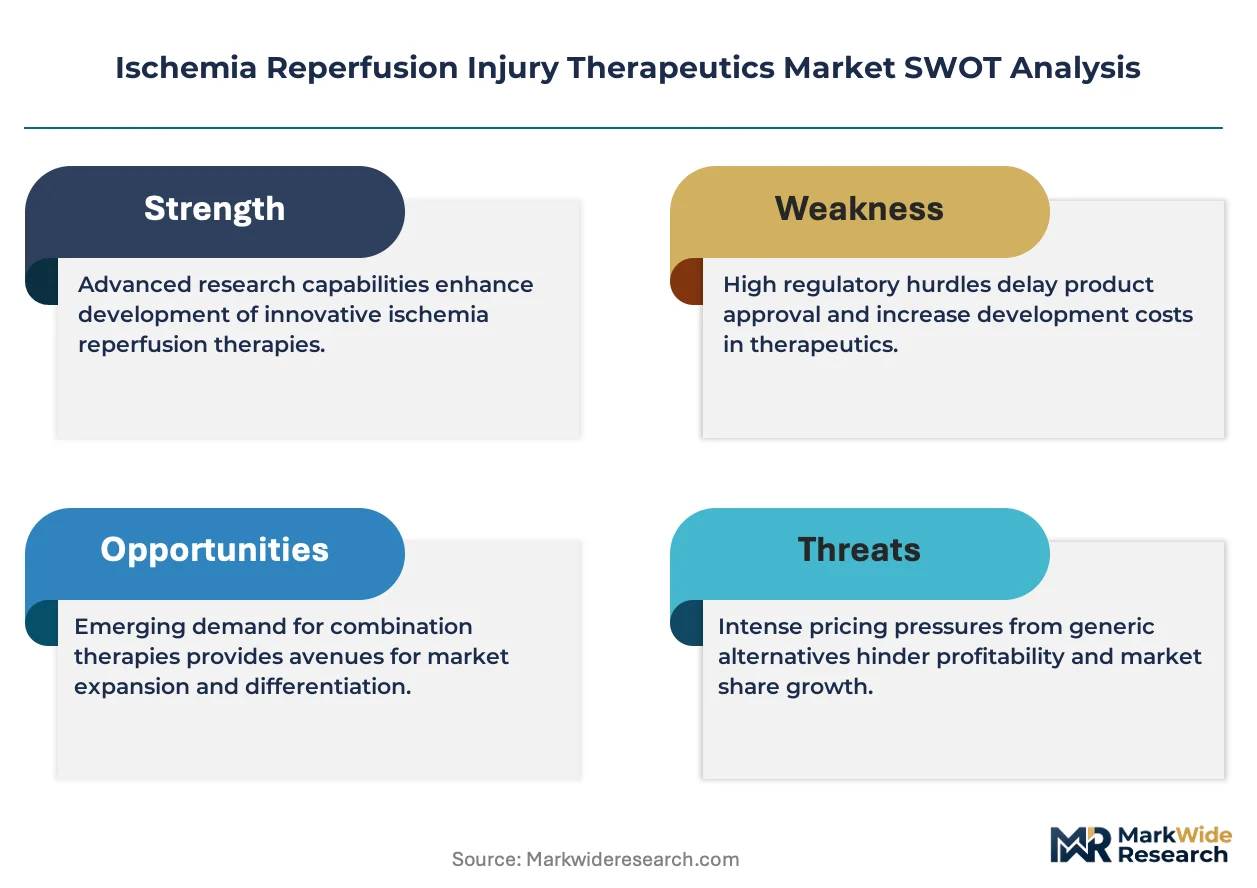
Technology leadership and cost leadership are held by different player archetypes across the ischemia reperfusion injury therapeutics landscape. The market structures around three tiers: large-cap biopharmaceuticals with immunology platforms, mid-cap mitochondrial specialists with peptide engineering capabilities, and emerging biotechs with single-asset complement programs. Dominant competitive moves include strategic partnerships with machine perfusion device manufacturers and portfolio diversification into adjacent organ preservation indications.
Within the mitochondrial-targeted tier, Stealth BioTherapeutics Inc. and Faraday Pharmaceuticals exemplify divergent platform strategies—peptide-based cardiolipin protection versus small-molecule redox modulation. Omeros Corporation occupies a distinct position in complement biology, leveraging immunology expertise to address reperfusion inflammatory cascades. These three entities represent the primary competitive anchors around which clinical trial networks and procurement relationships coalesce.
| Leading Market Players |
|---|
| Revive Therapeutics Ltd. |
| Faraday Pharmaceuticals |
| Abiomed |
| Omeros Corporation |
| Pharming Group N.V. |
| Stealth BioTherapeutics Inc. |
| Zealand Pharma A/S |
| Amyndas Pharmaceuticals LLC |
| Opsona Therapeutics Limited |
| Others |
Value Chain & Pricing Dynamics
Batch-scale fermentation capacity utilization in Massachusetts and Switzerland anchors monoclonal antibody production economics, concentrating manufacturing scale among CMOs serving complement protein assay development and driving price floors for diagnostic-dependent trials through dedicated facility overhead recovery.
Pricing Analysis
FDA's Project Optimus dose-optimization guidance dictates the pricing tier structure for cardioprotective agents, with three-tier pricing separating premium mitochondrial-targeted biologics from standard peptide formulations and economy-grade antioxidant generics. Price differentiation rests on biomarker validation rigor and cold-chain certification grade, with EU MDR post-market surveillance obligations adding compliance premiums to European-bound products. Cost compression in the standard tier intensifies because hospital procurement committees at Cleveland Clinic and Mayo Clinic now mandate health economic modeling for formulary inclusion. Academic medical centers absorb premium pricing for experimental biologics, while secondary transplant markets in Texas and Florida exhibit acute price sensitivity due to limited outcomes research infrastructure.
Supply Chain Analysis
Massachusetts and Switzerland anchor contract research organization capacity for complement protein assays, with peptide synthesis and diagnostic reagent production feeding from these clusters. Raw material dependencies include recombinant protein substrates, specialized chromatography resins, and cryopreservation media for minus 20 degrees Celsius distribution networks. Single-source vulnerability concentrates in Swissmedic-certified assay manufacturing sites serving multi-site transplant protocols across the United States, Canada, and Australia. Distribution runs through dedicated cold-chain logistics providers serving hospital pharmacy and therapeutics committees at high-volume academic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine perfusion technology adoption is driving a cyclical recovery in therapeutic demand, as extended ischemic windows from TransMedics and XVIVO systems recalibrate dosing protocols and expand addressable organ preservation economics.
For Market Incumbents: Compound platform differentiation through backward integration into peptide synthesis capacity and captive supply of cardiolipin stabilizer raw materials. Deepen vertical control over cryopreservation media formulation to defend margin position against emerging biotechs with single-asset complement programs. Prioritize R&D investment in sustained-release depot formulations for transitional care protocols, as subcutaneous delivery gains traction in Texas, California, and Florida transplant networks.
For New Entrants and Emerging Players: Japan's PMDA Sakigake designation offers 50% fee reduction and dedicated consultation for regenerative medicine candidates, creating regulatory fast-track positioning in Asia-Pacific's second-largest transplant market. Target cerebral reperfusion protection in comprehensive stroke centers across Pennsylvania, Ohio, and Georgia, where mechanical thrombectomy adoption has outpaced neuroprotective adjuvant penetration. Pursue hospital system partnership models bundling therapeutic delivery with machine perfusion device procurement to secure formulary access.
For Investors and Strategic Acquirers: Mid-cap mitochondrial specialists with peptide engineering capabilities and established complement biomarker panels represent compelling acquisition targets, as clinical trial network relationships and standardized assay protocols prove difficult to replicate. Long-term viability hinges on portfolio diversification into adjacent organ preservation indications and convergence with perfusion-device platforms. Watch for FDA adaptive pathway approvals for advanced therapy medicinal products as inflection indicators for premium valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA adaptive pathway frameworks compress Phase II-to-III transitions for mitochondrial-targeted biologics in Germany. |
| Manufacturing Scale-Up | Cold-chain infrastructure investment for minus 20 degrees Celsius peptide distribution expands addressable geography in secondary transplant markets. |
| Hospital System Partnership | Procurement relationships with Cleveland Clinic and Mayo Clinic anchor health economic modeling requirements for formulary inclusion. |
| Pipeline Diversification | Stroke intervention expansion into Pennsylvania, Ohio, and Georgia comprehensive stroke centers penetrates unexploited neuroprotective territory. |
| Licensing Agreement | Technology licensing from academic medical centers at Duke and Stanford reduces clinical trial variability through standardized complement biomarker panels. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors at academic medical centers. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up therapeutic demand modeling triangulated against top-down market sizing across product type, delivery mode, and application segments.
Across the analysis window, the quantitative framework modeled patient population flows, treatment protocol adoption curves, and reimbursement pathway maturation by regional regulatory cluster. CAGRs were derived from segment-level volume and value build-ups incorporating dosing protocol evolution around machine perfusion preservation timelines. Forecast inputs included UNOS allocation algorithm revision impacts, EU MDR post-market surveillance cost burdens, and cold-chain infrastructure expansion trajectories.
Decision-makers should treat outputs as directional under assumptions of stable regulatory guidance continuity and machine perfusion technology diffusion; material deviation in FDA Project Optimus enforcement or complement biology validation setbacks would warrant model refresh. Recalibration cycles align with material shifts in transplant center protocol adoption and biomarker panel standardization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Angina Market
Cardiovascular
Peptide-Based Cardiovascular Therapeutics Market
Cardiovascular
Genetic Cardiomyopathies Market
Cardiovascular
Global Deep Vein Thrombosis Market
Cardiovascular
Atherosclerosis Market
Cardiovascular
Venous Thromboembolism Treatment Market
Cardiovascular
Pulmonary Valve Replacement Market
Cardiovascular
Cardiometabolic Disease Market
Cardiovascular
Heart Transplant Market
Cardiovascular
Treatment-Resistant Hypertension Management Market
Cardiovascular
Global Pericarditis Market
Cardiovascular
Chronic Heart Failure Market
Cardiovascular
Global Statin Market
Cardiovascular
Stroke Management Market
Cardiovascular
Atherosclerosis Therapeutics Market
Cardiovascular
Heterozygous Familial Hypercholesterolemia (HEFH) Management Market