
 Global Pericarditis Market | 2026-2036
Global Pericarditis Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pericarditis Market Foresight
European biologics manufacturing is recalibrating its output mix toward inflammation-targeted therapies. Kiniksa Pharmaceuticals leverages its rare-disease infrastructure to anchor recurrent pericarditis therapy development. Pfizer sustains broad commercial reach across acute and chronic indications through established cardiovascular channels. Bayer AG competes on the strength of its NSAID heritage and hospital formulary relationships.
Pericarditis denotes inflammation of the pericardium, the fibroserous sac enveloping the heart, typically presenting with chest pain, friction rub, and characteristic electrocardiographic ST-segment elevation; treatment aims to reduce inflammation, prevent recurrence, and avoid progression to constrictive physiology. Colchicine now dominates first-line maintenance protocols given its efficacy in preventing recurrent episodes, while immunosuppressants represent the fastest-expanding segment as biologic agents gain traction in refractory cases. The end-user landscape tilts toward specialty hospitals, where concentrated cardiac expertise supports complex pericardiectomy decisions and advanced interventional management.
The FDA, EMA, and WHO collectively shape pericarditis therapy standards through cardiovascular safety requirements, pediatric investigation plans, and essential medicines list inclusion criteria that determine market access tiers. These frameworks elevate evidence thresholds for recurrent pericarditis approvals while accelerating pathways for drugs addressing unmet need in constrictive disease. Stakeholders must monitor how payer evidence requirements evolve for biologic therapies versus generic colchicine and NSAID combinations.
Market Dynamics
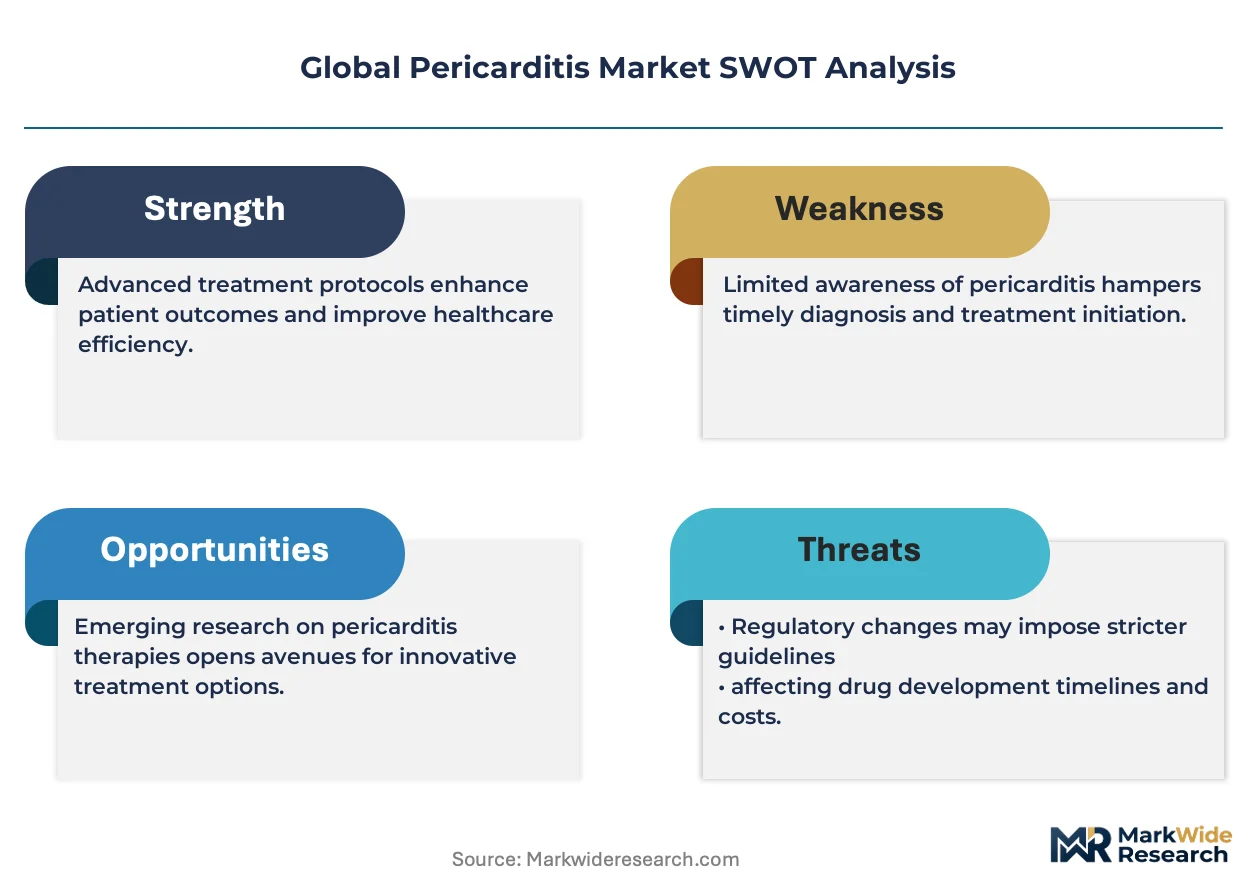
FDA cardiovascular safety guidance is compressing trial timelines for anti-inflammatory therapies while EMA pediatric investigation plans reshape development priorities across the pericarditis pipeline. This regulatory bifurcation forces sponsors to maintain parallel dossier strategies.
Growth Catalysts
- EMA Orphan Designation Pathways:Rare-disease frameworks accelerate market access for refractory pericarditis biologics, reducing regulatory friction for specialty indications.
- Colchicine Genericization:Cost erosion in first-line maintenance therapy expands addressable patient pools and drives volume through cardiology clinics.
- Specialty Hospital Concentration:Dedicated cardiac centers in the United States, Germany, and Japan concentrate procedure expertise and standardize complex pericardiectomy referrals.
Market Restraints
- Biologic Manufacturing Bottlenecks:European inflammation-targeted capacity constraints limit supply elasticity for IL-1 blockade therapies entering late-stage trials.
- Colchicine Supply Concentration:Active pharmaceutical ingredient sourcing clusters in South Asian manufacturing hubs, creating single-point vulnerability for maintenance protocols.
- Diagnostic Coding Fragmentation:ICD-10-CM specificity gaps between acute, recurrent, and constrictive phenotypes obscure epidemiological tracking and reimbursement alignment.
Strategic Opportunities
- Refractory Case Biologics:IL-1 pathway inhibitors address the unmet need segment where NSAID-colchicine combinations fail, commanding premium positioning.
- Telecardiology Integration:Remote monitoring platforms enable post-acute surveillance in rural United States markets underserved by tertiary centers.
- WHO Essential Medicines Inclusion:List placement for pericarditis therapies would unlock procurement pathways across low- and middle-income health systems.
Industry Challenges
- Cardiac Imaging Specialist Scarcity:Interpretation expertise for multimodal pericardial assessment concentrates in academic medical centers, constraining community diagnosis.
- Pericardiectomy Volume Thresholds:Low-frequency high-complexity procedures require sustained caseloads to maintain surgical proficiency, limiting center expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pericarditis Market |
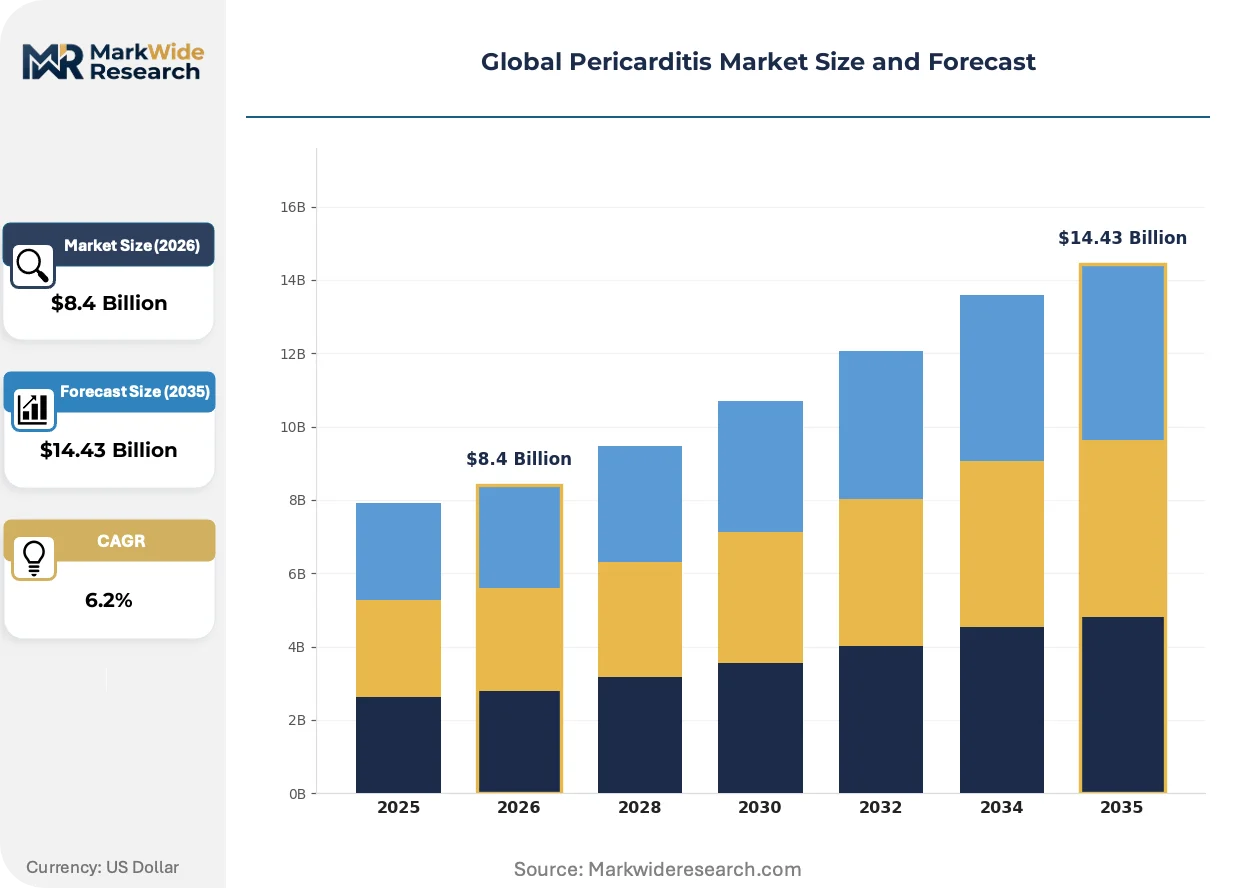
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NSAIDs, Colchicine, Corticosteroids, Antibiotics, Immunosuppressants Therapy Area: Acute Pericarditis, Chronic Pericarditis, Constrictive Pericarditis, Pericardial Effusion End User: Cardiology Clinics, Specialty Hospitals, Ambulatory Surgical Centers, Diagnostic Labs Delivery Mode: Oral Medication, Injectable Therapy, Topical Application, Hospital Administration |
| Companies Covered | Kiniksa Pharmaceuticals, Pfizer, Bayer AG, Takeda Pharmaceutical, AstraZeneca, Merck, Novartis, Teva Pharmaceuticals, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pericarditis Market Shifts & Advancements
Cardiac MRI is displacing echocardiography as the definitive pericardial tissue characterization modality, while biomarker-guided tapering protocols reduce recurrence rates. These shifts compress the diagnostic-to-treatment interval and reshape specialist referral patterns.
Cardiac MRI with tissue mapping sequences is absorbing the diagnostic workload previously assigned to invasive pericardial biopsy. Tertiary cardiology clinics in the United States and Germany are adopting these protocols within 18-month equipment refresh cycles. The technology is absorbing capital allocation from nuclear imaging suites and compressing time-to-diagnosis benchmarks.
REACH authorization requirements for novel anti-inflammatory substances are elevating toxicology documentation burdens for sponsors targeting European markets. Manufacturers must demonstrate cardiovascular safety profiles beyond standard inflammation endpoints. Biologic developers are responding by front-loading cardiac safety cohorts in Phase II trials.
Patient risk stratification is fragmenting the acute-care pathway into observation-versus-admission decision trees. Emergency departments in Japan and the United States are deploying validated scoring systems to identify low-recurrence-risk candidates for outpatient colchicine initiation. This behavioral shift redirects volume from inpatient cardiology services toward clinic-based monitoring.
Global Pericarditis Market Segmentation
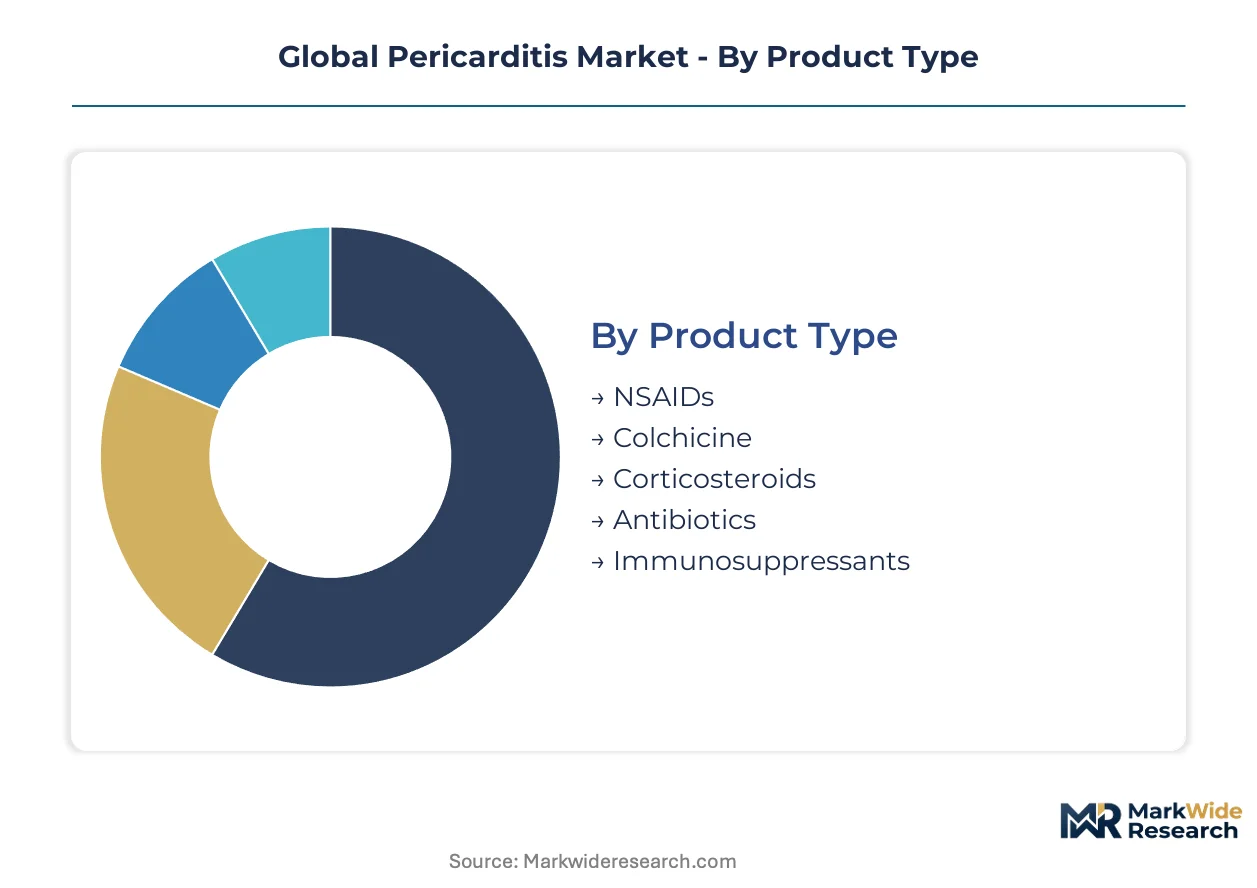
Pericarditis treatment protocols fragment across pharmacological classes, disease phenotypes, and care settings. Each segmentation dimension carries distinct reimbursement logic, regulatory requirements, and patient flow implications that shape commercial strategy.
Product Type:
Volume concentrates in genericized maintenance agents while premium pricing attaches to biologic rescue therapies for refractory cases.
- NSAIDs:First-line anti-inflammatory agents, primarily ibuprofen and aspirin, deliver rapid symptom relief through cyclooxygenase inhibition. Demand clusters in United States emergency departments and German cardiology clinics where rapid chest pain protocols dominate. Pricing compression from commoditization limits margin expansion despite high prescription volumes.
- Colchicine:Microtubule inhibitor with established efficacy in preventing recurrent episodes through anti-inflammatory and anti-fibrotic mechanisms. United States specialty hospital networks and Japanese cardiac centers have standardized this agent in maintenance protocols following acute resolution. Generic manufacturing in South Asian hubs constrains supply security despite clinical dominance.
- Corticosteroids:Systemic immunosuppression reserved for NSAID-colchicine failures or contraindications.
- Antibiotics:Targeted therapy for infectious etiologies including bacterial and tuberculous pericarditis.
- Immunosuppressants:IL-1 pathway inhibitors and other biologics addressing cytokine-driven refractory inflammation.
Mature deployment sits with Colchicine. Newer deployment is concentrated in Immunosuppressants.
Therapy Area:
Disease severity and recurrence risk stratify the addressable patient population into distinct treatment intensity tiers.
- Acute Pericarditis:Initial inflammatory episode presenting with characteristic chest pain, pericardial friction rub, and diffuse ST-elevation on electrocardiogram. United States emergency departments and United Kingdom rapid-access chest pain clinics drive diagnostic volume through standardized algorithms. Outpatient colchicine initiation protocols are redirecting volume from inpatient admissions in Japan and Germany.
- Chronic Pericarditis:Persistent inflammation exceeding three months with risk of progression to constriction. Tertiary cardiac centers in France and Italy concentrate expertise for complex immunomodulatory management.
- Constrictive Pericarditis:End-stage fibrocalcific remodeling requiring surgical pericardiectomy.
- Pericardial Effusion:Fluid accumulation ranging from asymptomatic to hemodynamically significant tamponade physiology.
Volume leadership rests with Acute Pericarditis. Steepest expansion trajectory belongs to Chronic Pericarditis as biologic therapies extend addressable refractory populations.
End User:
Care setting determines reimbursement tier, procedure authorization requirements, and specialist availability for complex interventions.
- Cardiology Clinics:Outpatient facilities managing stable patients through maintenance protocols and recurrence surveillance. German Kassenärztliche Vereinigung contracts and United States Medicare clinic fee schedules shape reimbursement economics. Telecardiology integration is extending reach into rural United States markets underserved by tertiary centers.
- Specialty Hospitals:Concentrated cardiac expertise supporting pericardiectomy decisions, advanced interventional management, and complex biologic therapy administration. Cleveland Clinic, Mayo Clinic, and Charité Berlin anchor referral networks for refractory case management.
- Ambulatory Surgical Centers:Limited role restricted to diagnostic pericardiocentesis in selected stable patients.
- Diagnostic Labs:Biomarker processing and cardiac MRI interpretation supporting risk stratification.
Procedure revenue concentrates in Specialty Hospitals. Diagnostic volume is migrating toward Cardiology Clinics.
Delivery Mode:
Route of administration aligns with disease acuity, hospitalization status, and therapy mechanism requirements.
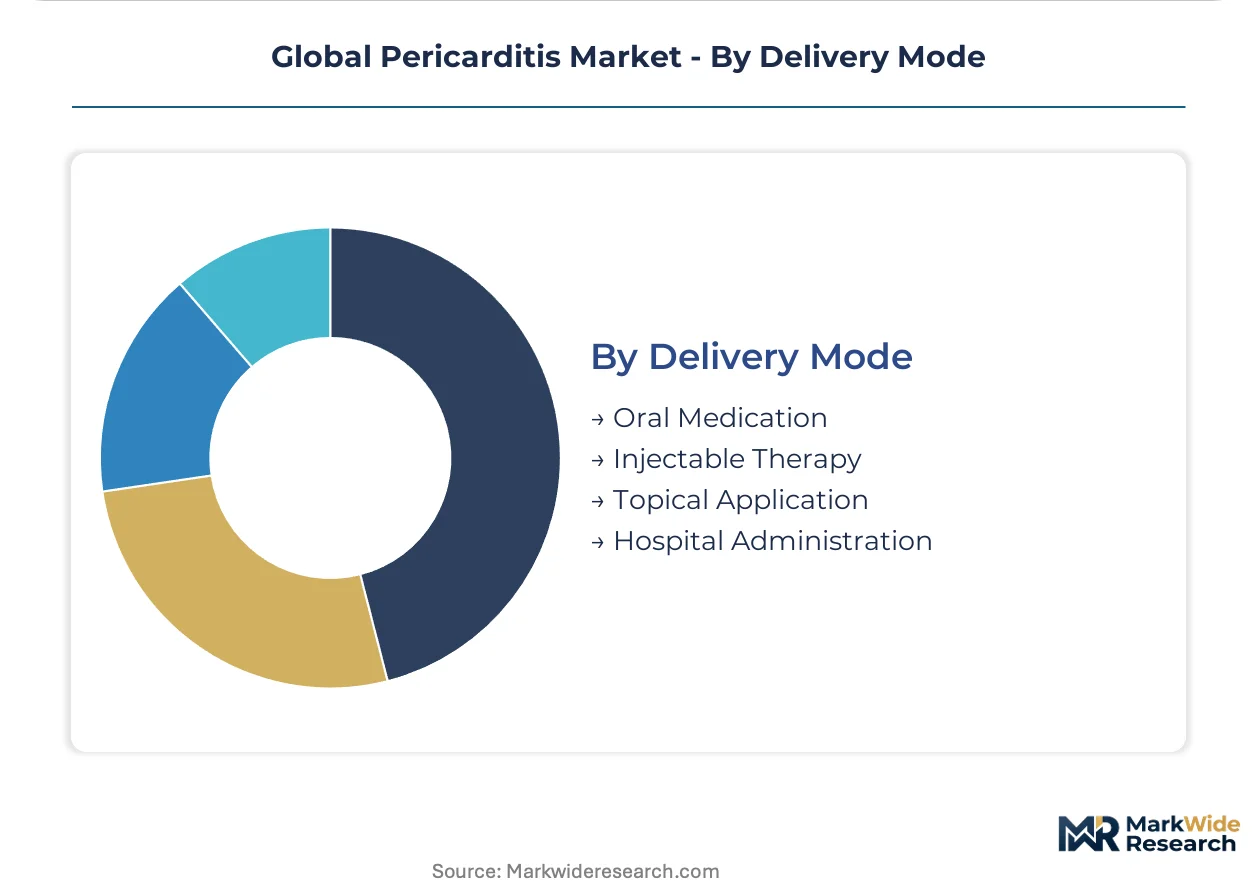
- Oral Medication:Dominant route for maintenance therapy including colchicine and NSAID tapering protocols. Patient adherence monitoring through United States pharmacy benefit managers and Japanese dispensing pharmacy networks influences real-world effectiveness.
- Injectable Therapy:Hospital-based administration for acute rescue, pericardial instillation, and biologic agents requiring parenteral delivery. EMA batch-release requirements for European-manufactured biologics extend preparation timelines.
- Topical Application:Negligible role in pericarditis pharmacotherapy.
- Hospital Administration:Inpatient infusion protocols for cytokine storm management and perioperative immunosuppression.
Cost efficiency favors Oral Medication. Clinical escalation requires Hospital Administration infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient sourcing clusters in South Asian manufacturing hubs anchor maintenance therapy supply chains, while biologic production concentrates in European inflammation-targeted facilities. Demand gravity tilts toward tertiary cardiac centers in the United States, Germany, and Japan where pericardiectomy volume thresholds sustain surgical proficiency.
United States
Specialty hospital networks and dedicated cardiac centers drive protocol standardization across acute and chronic indications. FDA cardiovascular safety guidance compresses trial timelines for anti-inflammatory therapies entering late-stage development. Cleveland Clinic and Mayo Clinic anchor referral networks for refractory case management and complex biologic therapy administration.
Germany
Kassenärztliche Vereinigung contracts shape reimbursement economics for outpatient cardiology clinics managing maintenance protocols. EMA pediatric investigation plans reshape development priorities across the pericardiitis pipeline, forcing parallel dossier strategies. Charité Berlin concentrates expertise for complex immunomodulatory management and pericardiectomy decisions.
Japan
Emergency departments deploy validated scoring systems to identify low-recurrence-risk candidates for outpatient colchicine initiation. METI standards influence diagnostic equipment procurement cycles for cardiac MRI adoption. Cardiac centers in Tokyo and Osaka standardize maintenance protocols following acute resolution, redirecting volume from inpatient admissions.
India
Active pharmaceutical ingredient manufacturing for generic colchicine concentrates in South Asian hubs, creating single-point vulnerability for global maintenance protocols. CDSCO regulatory pathways determine market access for imported biologic therapies. Manufacturing clusters in Maharashtra and Gujarat supply cost-eroded first-line agents expanding addressable patient pools.
United Kingdom
Rapid-access chest pain clinics drive diagnostic volume through standardized algorithms for initial inflammatory episodes. NHS reimbursement frameworks differentiate acute observation from admission pathways. Tertiary centers in London concentrate multimodal pericardial assessment expertise, constraining community diagnosis capacity.
Global Pericarditis Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biologic rescue therapy positioning. The vendor base stratifies across three tiers: legacy pharmaceutical conglomerates with cardiovascular channel breadth, rare-disease specialists leveraging orphan designation infrastructure, and generic manufacturers competing on colchicine supply security. Dominant competitive moves include portfolio diversification into inflammation-targeted biologics and strategic partnerships securing European manufacturing capacity.
Within the rare-disease specialist tier, Kiniksa Pharmaceuticals exemplifies archetype positioning through orphan-disease infrastructure deployment. Among diversified pharmaceutical conglomerates, Pfizer and Bayer AG occupy positions spanning acute and chronic indications; the former sustains broad commercial reach through established cardiovascular channels, while the latter competes on NSAID heritage and hospital formulary relationships. These three anchors represent distinct strategic postures: targeted biologic development, portfolio breadth, and heritage brand leverage.
| Leading Market Players |
|---|
| Kiniksa Pharmaceuticals |
| Pfizer |
| Bayer AG |
| Takeda Pharmaceutical |
| AstraZeneca |
| Merck |
| Novartis |
| Teva Pharmaceuticals |
| Eli Lilly and Company |
| Others |
Supply & Pricing Matrix
Captive colchicine manufacturing in South Asian hubs anchors both supply security and pricing power for first-line maintenance therapy, while European biologics capacity constrains premium-tier elasticity for refractory rescue agents. This integration pattern concentrates cost advantages in genericized maintenance protocols while fragmenting pricing authority across the biologic rescue segment.
Pricing Analysis
Service-bundling separates diagnostic imaging packages from standalone pharmaceutical procurement, with cardiac MRI interpretation fees unbundled from drug acquisition costs in United States specialty hospital networks. Three-tier pricing structure across premium biologics, standard maintenance agents, and economy generic colchicine reflects differentiation by clinical efficacy tier and manufacturing complexity. Pricing pressure stems from South Asian API cost compression, though biologic rescue therapies retain margin insulation due to manufacturing bottlenecks. Emergency departments exhibit highest price sensitivity for acute rescue protocols, while refractory case management in tertiary centers shows lowest sensitivity.
Supply Chain Analysis
Regional distribution centers in Maharashtra and Gujarat feed hub-and-spoke patterns into European and North American wholesale networks, with cold-chain biologics requiring dedicated logistics infrastructure. Active pharmaceutical ingredient sourcing clusters in India and China, with finished dose manufacturing concentrated in European inflammation-targeted facilities. Raw material dependencies include colchicine alkaloid extraction, IL-1 receptor antagonist cell lines, and parenteral formulation excipients. Single-source vulnerability in South Asian API concentration threatens maintenance protocol continuity. Distribution runs through hospital-centric direct purchasing for biologics and pharmacy benefit manager channels for oral maintenance agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around regulatory compliance burdens and manufacturing scale thresholds that force sub-scale generic producers toward exit. FDA cardiovascular safety documentation requirements and EMA batch-release standards elevate fixed costs beyond smaller participant capacity.
For Market Incumbents: Anticipate biologic rescue therapy volume migration toward IL-1 pathway inhibitors by securing European inflammation-targeted manufacturing capacity ahead of competitor lock-up. Defensive moves center on backward integration into colchicine API sourcing to neutralize South Asian supply concentration risk, paired with certification investment in REACH-compliant toxicology documentation for European market maintenance. Kiniksa Pharmaceuticals' orphan-disease infrastructure deployment represents the emerging entrant archetype threatening premium-tier positioning.
For New Entrants and Emerging Players: The price-point gap between premium biologics and economy generic maintenance creates white-space opportunity in mid-tier immunosuppressant positioning for NSAID-colchicine failure cases. Target Japanese cardiac centers and United States rural telecardiology networks as underpenetrated channels where protocol standardization remains incomplete. Go-to-market execution should leverage hospital formulary relationships through bundled diagnostic-therapeutic protocols rather than standalone pharmaceutical procurement.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified pharmaceutical conglomerates seeking inflammation-targeted biologic portfolios. Long-term viability over the five-to-ten year horizon rests on regulatory dossier depth and European manufacturing access rather than single-product revenue concentration. Acquisition target archetype: rare-disease specialists with validated IL-1 pathway assets and established EMA pediatric investigation plans. The signal to watch is FDA guidance evolution on cardiovascular safety endpoints for anti-inflammatory therapies, which would recalibrate late-stage development risk profiles.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA cardiovascular safety cohorts front-loaded in Phase II trials compress development timelines for IL-1 blockade therapies. |
| Regulatory Approval Pathway | EMA Orphan Designation accelerates market access for refractory pericarditis biologics through reduced regulatory friction. |
| Manufacturing Scale-Up | European inflammation-targeted capacity expansion addresses supply elasticity constraints for biologic rescue therapies entering late-stage trials. |
| Pipeline Diversification | Portfolio extension into constrictive pericarditis indications captures unmet need segments beyond recurrent disease management. |
| Strategic Partnership | Hospital system partnerships with Cleveland Clinic and Mayo Clinic anchor referral network control for refractory case management. |
Research Methodology
FDA filings, EMA submission databases, and ClinicalTrials.gov records formed the secondary backbone, cross-referenced with formulary database audits and CMS Medicare reimbursement schedules. Primary interviews with cardiology clinic directors, hospital procurement managers, regulatory affairs leads at biologic developers, and payer access specialists validated secondary findings. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates across the analysis window.
Historical trendline analysis of colchicine prescription volumes, biologic infusion center capacity, and pericardiectomy procedure counts established baseline trajectories. The analytical framework projected forward across the modeling period using epidemiological incidence assumptions, regulatory approval probability weightings, and therapy adoption curve parameters. Segmentation dimensions included pharmacological class, disease phenotype, care setting, and regional regulatory cluster. CAGRs were derived from slope-adjusted trend extrapolation incorporating therapy substitution elasticities.
Inputs from FDA and EMA regulatory databases were available through the study window; gaps in real-world colchicine adherence data from pharmacy benefit managers introduce uncertainty bands around maintenance protocol persistence assumptions. Forecasts reflect documented assumptions regarding biologic manufacturing capacity expansion timelines and cardiovascular safety endpoint evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Cardiovascular Clinical Trials Market
Cardiovascular
Cardiometabolic Disease Market
Cardiovascular
Myocardial Ischemia Market
Cardiovascular
Cardiovascular Disease Drugs Market
Cardiovascular
Myocardial Infarction Market
Cardiovascular
Global Cardiac Rehabilitation Market
Cardiovascular
Cardiac Biomarkers Market
Cardiovascular
Cardiac Valvulotome Market
Cardiovascular
Stable Angina Management Market
Cardiovascular
Middle East and Africa Acute Coronary Syndrome Market
Cardiovascular
Cardiac Arrhythmia Therapeutics Market
Cardiovascular
Aortic Coarctation Market
Cardiovascular
Angina Market
Cardiovascular
Prinzmetal Angina Therapeutics Market
Cardiovascular
Peptide-Based Cardiovascular Therapeutics Market
Cardiovascular
Global Atrial Fibrillation Market