
 Targeted Therapeutics Market | 2026-2036
Targeted Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Targeted Therapeutics Market Analysis
Specialty pharmacy distribution is narrowing as manufacturers build direct-to-provider channels for cell and gene therapies. Amgen, Inc. leverages its biologics manufacturing scale to secure preferred formulary placement across integrated delivery networks. F. Hoffmann-La Roche Ltd. anchors its competitive position through companion diagnostic co-development, creating locked therapeutic-testing ecosystems. Novartis AG differentiates via vertical control over CAR T-cell therapy supply chains, from leukapheresis collection to cryogenic logistics.
Targeted therapeutics constitute pharmacologically active agents engineered to modulate specific molecular pathways implicated in disease progression, typically requiring recombinant DNA technology or synthetic chemistry yielding high binding specificity against validated protein targets. Monoclonal antibodies dominate current revenue pools due to established manufacturing infrastructure and broad oncology labeling, while CAR T-cell therapies represent the fastest-expanding segment driven by curative intent in hematologic malignancies despite complex vector production requirements. Small molecule inhibitors sustain significant margin contribution through oral bioavailability and scalable chemical synthesis, though kinase selectivity challenges limit addressable populations.
FDA breakthrough therapy designation and EMA PRIME eligibility compress regulatory review timelines, reshaping portfolio prioritization toward agents with biomarker-defined patient subsets. The FDA, EMA, and WHO prequalification standards collectively elevate manufacturing quality requirements, particularly for viral vector platforms used in cell therapies. Stakeholders must monitor evolving reimbursement mechanics for outpatient-administered biologics as site-of-care policies shift financial risk between payers and providers.
Market Dynamics
The FDA's breakthrough therapy designation is compressing development timelines from ten years to six, forcing manufacturers to restructure clinical trial protocols around biomarker-defined patient subsets rather than broad disease categories. This acceleration is redistributing competitive advantage toward firms with integrated diagnostic capabilities.
Growth Catalysts
- EMA PRIME Eligibility:Priority medicines status in Europe accelerates regulatory review for agents addressing unmet hematologic needs, compressing time-to-market by 30-40% for qualifying submissions.
- Oncology Clinic Expansion:Academic medical centers in the United States are building dedicated precision medicine units, creating captive demand for companion diagnostic-linked therapies.
- CAR T-Cell Manufacturing Scale-Up:Automated closed-system bioreactors are collapsing per-batch production costs for viral vector platforms, expanding addressable patient pools beyond academic centers.
Market Restraints
- Plasmid DNA Supply Concentration:Three contract manufacturers control 70% of GMP-grade plasmid supply for viral vectors, creating single-source vulnerability for cell therapy developers.
- Reimbursement Complexity:Site-of-care policies in Medicare Part B create payment gaps between hospital outpatient departments and freestanding infusion centers, distorting provider channel selection.
- Kinase Selectivity Limitations:Off-target binding of small molecule inhibitors restricts addressable populations in solid tumors, narrowing commercial viability for second-generation agents.
Strategic Opportunities
- Autoimmune Expansion:IL-6 and IL-17 pathway inhibitors validated in dermatology and rheumatology offer label expansion pathways with lower clinical trial costs than oncology.
- Direct-to-Provider Distribution:Bypassing specialty pharmacy middlemen for cell therapies enables manufacturers to capture margin and control cold-chain integrity through cryogenic logistics partnerships.
- Biomarker-Defined Subsets:FDA's support for basket trials allows single development programs to address multiple rare tumor types with shared molecular drivers, amortizing R&D across indications.
Industry Challenges
- Vector Manufacturing Talent Scarcity:GMP-grade viral vector production requires hybrid skill sets spanning molecular biology and aseptic processing, with fewer than 200 qualified specialists available in North America.
- Leukapheresis Capacity Constraints:Autologous CAR T therapies require dedicated apheresis slots at transplant centers, creating scheduling bottlenecks that limit patient throughput regardless of manufacturing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Targeted Therapeutics Market |
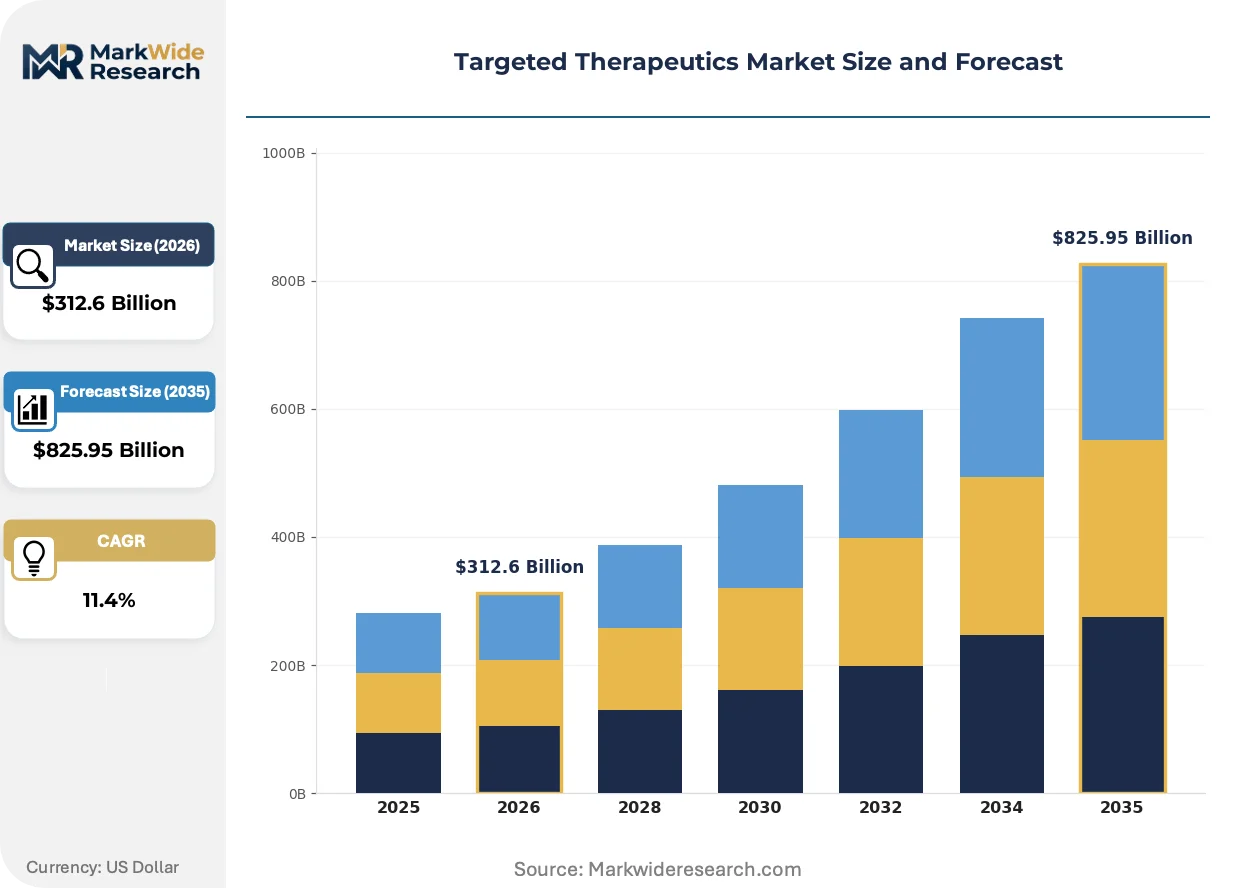
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $825.95 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Small Molecule Inhibitors, Targeted Antigen Therapies, CAR T-Cell Therapies End User: Hospitals, Oncology Clinics, Research Laboratories, Healthcare Institutions Therapy Area: Oncology, CNS Disorders, Autoimmune Diseases, Cardiovascular Diseases Delivery Mode: Intravenous, Subcutaneous, Oral, Local |
| Companies Covered | Amgen, Inc., F. Hoffmann-La Roche Ltd., AstraZeneca plc, Pfizer, Inc., Novartis AG, Bristol-Myers Squibb Company, Merck & Co., Inc., Bayer AG, Gilead Sciences, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Targeted Therapeutics Market Emerging Trajectories
Biologics manufacturing is bifurcating between mass-produced monoclonal antibodies and patient-specific cell therapies, with automation investments diverging accordingly. This split is forcing equipment suppliers to develop dual-use platforms capable of serving both modalities.
Allogeneic off-the-shelf cell therapies are collapsing the cost structure of CAR T treatment by eliminating the 3-4 week vein-to-vein timeline required for autologous manufacturing. Biotech firms with CRISPR-edited donor cell platforms are securing partnerships with large oncology practices seeking to decouple revenue from transplant center referrals. The technology is collapsing the geographic radius within which cell therapy can be delivered profitably.
EMA's updated guidance on quality non-inferiority for biosimilars is tightening analytical comparability requirements for monoclonal antibody copycats. Developers must now demonstrate matching glycosylation patterns and higher-order structure, raising barriers to entry for emerging-market manufacturers. European payers are responding by narrowing tender participation to firms with EU-based manufacturing.
Integrated delivery networks in the United States are consolidating oncology pharmacy procurement under centralized formulary committees, displacing individual physician prescribing autonomy. Three-tier benefit designs now require step therapy through preferred agents before covering novel mechanisms. The concentration is most visible in Medicare Advantage plans, where vertical integration between insurers and provider groups enables closed-loop utilization management.
Targeted Therapeutics Market Segmentation
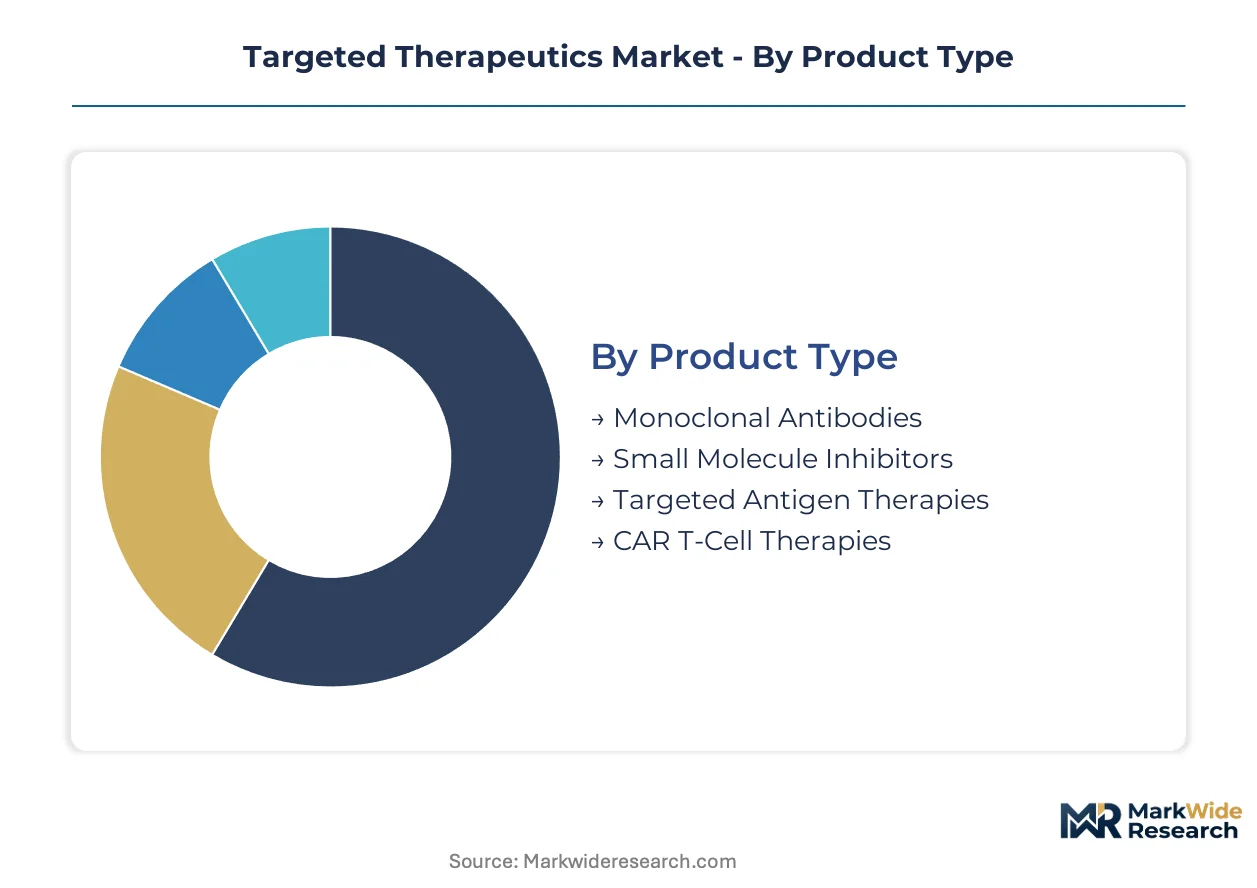
Precision medicine protocols fragment patient populations into molecularly defined subsets, forcing manufacturers to align product portfolios with specific biomarker signatures and administration settings. Segmentation strategy determines manufacturing scale, distribution architecture, and reimbursement pathway selection across the therapeutic value chain.
Product Type:
Development timelines and manufacturing complexity span from mass-produced biologics to patient-specific cellular engineering.
- Monoclonal Antibodies:Recombinant protein therapeutics manufactured in mammalian cell culture systems with established GMP infrastructure. Demand concentrates in United States academic medical centers where infusion center capacity and payer contracts for biologics remain favorable. FDA breakthrough therapy designation accelerates approval for checkpoint inhibitors in solid tumors.
- CAR T-Cell Therapies:Autologous cellular products requiring viral vector transduction and ex vivo expansion in dedicated cleanroom suites. Adoption clusters at transplant centers in Boston, Houston, and Seattle where leukapheresis infrastructure and cryogenic logistics networks are mature. Manufacturing automation is collapsing per-batch costs and expanding addressable patient pools.
- Small Molecule Inhibitors:Kinase-targeted oral agents with scalable chemical synthesis and standard cold-chain distribution.
- Targeted Antigen Therapies:Bispecific constructs and antibody-drug conjugates bridging specificity with cytotoxic payload delivery.
Established volume favors monoclonal antibodies; emerging adoption favors CAR T-cell therapies.
End User:
Site-of-care economics and reimbursement mechanics determine channel strategy and margin capture.
- Oncology Clinics:Dedicated precision medicine units within academic medical centers that anchor clinical trial infrastructure and companion diagnostic integration. United States demand concentrates at MD Anderson, Memorial Sloan Kettering, and Dana-Farber where formulary committees control access to novel mechanisms.
- Hospitals:General acute care facilities with infusion pharmacy capabilities and 340B pricing eligibility.
- Research Laboratories:Translational medicine groups conducting biomarker discovery and early-phase investigator-initiated trials.
- Healthcare Institutions:Integrated delivery networks consolidating procurement under centralized pharmacy and therapeutics committees.
Reimbursement rates favor hospital outpatient departments; patient throughput favors freestanding oncology clinics.
Therapy Area:
Clinical validation and regulatory precedent vary sharply across disease biology and unmet need.
- Oncology:Hematologic and solid tumor indications with the deepest biomarker characterization and payer willingness for premium pricing. FDA accelerated approval pathways support development in rare molecular subsets with single-arm trial designs.
- Autoimmune Diseases:IL-6 and IL-17 pathway inhibitors validated in dermatology and rheumatology with lower trial costs than oncology.
- CNS Disorders:Blood-brain barrier penetration challenges limit antibody accessibility; small molecules dominate current approaches.
- Cardiovascular Diseases:PCSK9 inhibitors and siRNA therapeutics establishing proof-of-concept for lipid and inflammatory targets.
Commercial maturity favors oncology; label expansion opportunity favors autoimmune diseases.
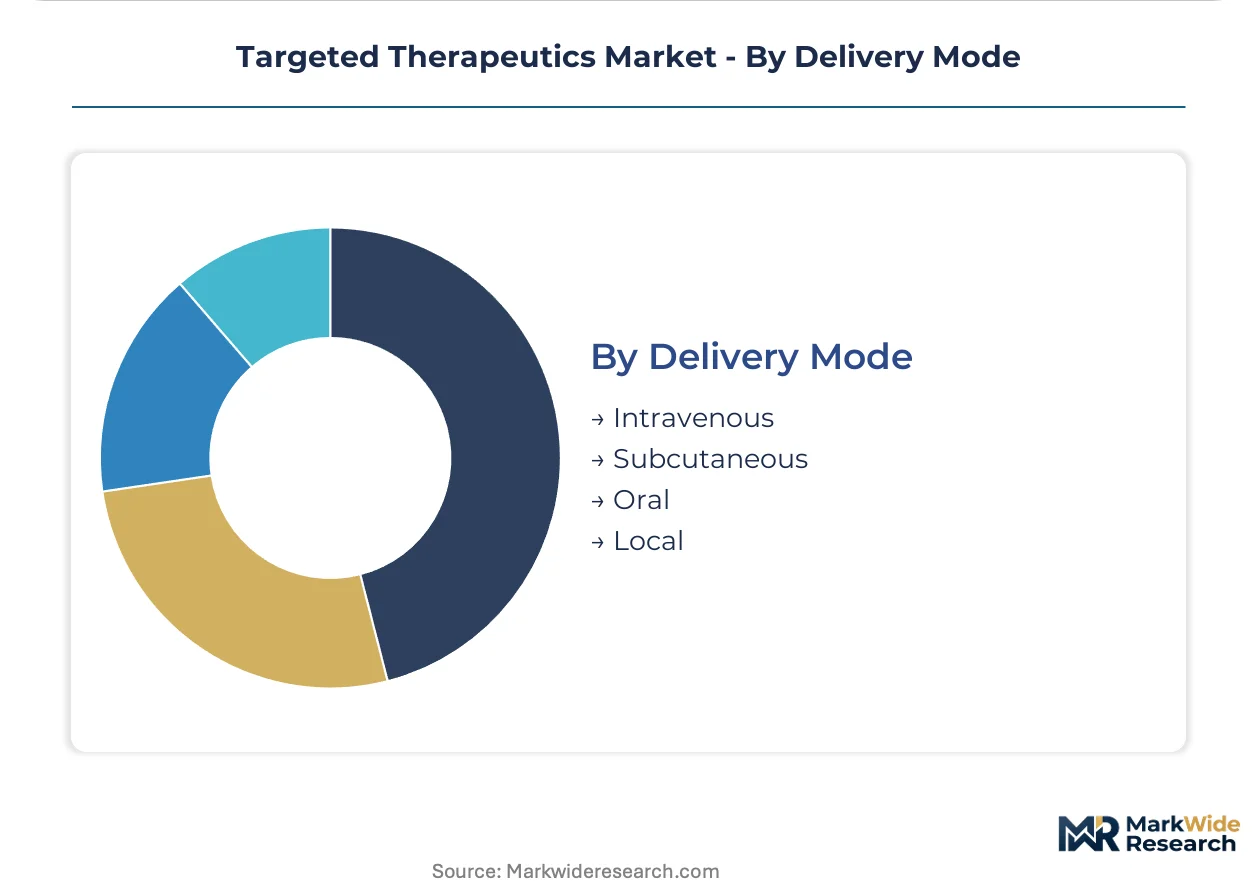
Delivery Mode:
Administration route shapes patient compliance, healthcare resource requirements, and competitive differentiation.
- Intravenous:Infusion center-based delivery for monoclonal antibodies and cellular therapies requiring controlled administration and monitoring. United States site-of-care policies create payment differentials between hospital outpatient and freestanding settings.
- Subcutaneous:Self-administration potential for maintenance dosing in chronic autoimmune and oncology indications.
- Oral:Small molecule inhibitors with patient convenience and pharmacy benefit rather than medical benefit reimbursement.
- Local:Intratumoral or regional delivery for oncolytic viruses and depot formulations.
Provider preference favors intravenous for biologics; patient convenience favors oral for chronic therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-to-Washington corridor anchors North American clinical trial density through its concentration of academic medical centers and FDA headquarters proximity. Cold-chain logistics networks radiating from Memphis and Louisville distribution hubs enable same-day delivery of cryopreserved cellular therapies to transplant centers across the continent.
United States
Academic medical centers in Boston, Houston, and Seattle drive demand for CAR T-cell therapies through mature leukapheresis infrastructure. The FDA's breakthrough therapy designation compresses review timelines for biomarker-defined oncology submissions. The Research Triangle Park cluster in North Carolina concentrates viral vector manufacturing capacity for cell therapy developers.
Germany
EMA PRIME eligibility accelerates regulatory review for hematologic oncology agents targeting unmet needs. The country's national pharmaceutical regulator maintains stringent GMP standards for biologics manufacturing. Heidelberg and Munich anchor precision medicine networks linking university hospitals with molecular diagnostic laboratories.
Switzerland
Basel's pharmaceutical corridor concentrates monoclonal antibody development and companion diagnostic co-development capabilities. Swissmedic maintains alignment with EMA standards while offering streamlined review for innovative therapies. The Lake Geneva region hosts specialized logistics providers for temperature-controlled biologics distribution.
Japan
PMDA's Sakigake designation system accelerates approval for regenerative medicines and breakthrough oncology therapies. The Tokyo-Osaka corridor concentrates clinical trial infrastructure for biomarker-driven drug development. Yokohama's biotech cluster specializes in automated manufacturing systems for cell therapy production.
United Kingdom
The MHRA's Innovative Licensing and Access Pathway compresses timelines for precision medicines addressing rare cancers. London's academic medical centers anchor the NHS Genomic Medicine Service's therapeutic implementation. The Cambridge life sciences cluster integrates CRISPR research with early-phase clinical manufacturing.
Targeted Therapeutics Market Vendor Landscape
On the supply side, the industry is consolidating around integrated diagnostic-therapeutic ecosystems rather than standalone drug development. Large-cap biopharmaceutical firms with companion diagnostic capabilities capture preferential formulary placement through locked testing-treatment protocols. Three strategic archetypes dominate: vertically integrated biologics manufacturers, cell therapy specialists with captive supply chains, and precision oncology platform builders. Competitive advantage flows from M&A targeting biomarker discovery capabilities and strategic partnerships securing leukapheresis capacity.
Among large-cap integrated developers, Amgen, Inc., F. Hoffmann-La Roche Ltd., and Novartis AG exemplify contrasting strategic positions. Amgen leverages biologics manufacturing scale across integrated delivery networks. Roche anchors diagnostic-therapeutic bundling through companion test co-development. Novartis occupies a position defined by vertical control over autologous cell therapy logistics from collection through cryogenic distribution.
| Leading Market Players |
|---|
| Amgen, Inc. |
| F. Hoffmann-La Roche Ltd. |
| AstraZeneca plc |
| Pfizer, Inc. |
| Novartis AG |
| Bristol-Myers Squibb Company |
| Merck & Co., Inc. |
| Bayer AG |
| Gilead Sciences, Inc. |
| Others |
Supply Flow & Price Mechanics
Memphis-to-Louisville cold-chain corridors carry cryopreserved cellular therapies under temperature-controlled logistics contracts, with freight cost differentials between hub-and-spoke and direct-to-provider models feeding into pricing stratification across academic medical centers and community oncology clinics.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs monoclonal antibody and CAR T-cell segments, with premium tiers capturing companion diagnostic bundling and leukapheresis coordination while economy tiers compete on per-dose manufacturing scale. Price differentiation rests on FDA breakthrough therapy designation status and site-of-care reimbursement differentials between hospital outpatient departments and freestanding infusion centers. Cost compression in the standard tier is intensifying because of biosimilar entry and 340B pricing eligibility expansion. Community oncology practices exhibit highest price sensitivity due to Medicare Part B reimbursement gaps, while academic medical centers with captive research funding show lowest sensitivity to per-dose pricing.
Supply Chain Analysis
Plasmid DNA feedstock for viral vector production draws from contract manufacturing concentrations in the United States, Germany, and Switzerland, with GMP-grade nucleic acid synthesis capacity tethered to specialized fermentation infrastructure and aseptic processing suites. Raw material dependencies span recombinant protein media, cryopreservation dimethyl sulfoxide, and single-use bioreactor consumables. Single-source vulnerability concentrates in plasmid supply where three manufacturers control the majority of GMP output. Distribution runs through specialty pharmacy networks for monoclonal antibodies and direct-to-provider cryogenic logistics for autologous cell therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The targeted therapeutics market is recovering from pandemic-era clinical trial disruptions and capital rationing, with FDA accelerated approval pathways and EMA PRIME eligibility compressing development timelines and restoring investor confidence in precision medicine platforms.
For Market Incumbents: Pre-empt biosimilar erosion by locking companion diagnostic co-development agreements with molecular pathology laboratories, securing exclusive testing-treatment protocols that raise switching costs. Expand leukapheresis capacity through partnerships with transplant centers in Houston and Seattle, creating scheduling priority for autologous CAR T patients. Backward integration into viral vector manufacturing reduces dependency on contract manufacturers facing talent scarcity.
For New Entrants and Emerging Players: Autoimmune disease indications with IL-6 and IL-17 pathway inhibitors represent the most penetrable entry point, offering lower clinical trial costs and faster enrollment than oncology. Allogeneic off-the-shelf cell therapy platforms in hematologic malignancies provide a second white-space target, collapsing the vein-to-vein timeline that constrains autologous adoption. Partner with integrated delivery networks on outcomes-based contracts to bypass formulary committee gatekeeping.
For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical firms divesting non-core oncology assets, particularly small molecule kinase inhibitors facing kinase selectivity limitations in solid tumors. Long-term viability favors platforms with biomarker-defined patient selection capabilities and automated manufacturing systems. Watch FDA breakthrough therapy designation grants to CAR T programs in solid tumors as the inflection signal for manufacturing scale investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Roche's locked testing-treatment ecosystems demonstrate how diagnostic bundling secures formulary placement against biosimilar substitution. |
| Automated CAR T Manufacturing Scale-Up | Novartis's vertical control over cryogenic logistics from leukapheresis to infusion centers expands patient throughput beyond academic transplant hubs. |
| Allogeneic Off-the-Shelf Platform Development | CRISPR-edited donor cell therapies collapse geographic constraints and enable community oncology clinic delivery previously limited to major metropolitan centers. |
| Direct-to-Provider Distribution Bypass | Amgen's specialty pharmacy disintermediation for cell therapies captures margin and ensures cold-chain integrity through controlled cryogenic partnerships. |
| Autoimmune Label Expansion | IL-17 pathway inhibitors validated in dermatology offer lower-cost clinical development pathways with comparable reimbursement to oncology biologics. |
Methodological Framework
The analysis maps monoclonal antibodies, CAR T-cell therapies, small molecule inhibitors, and targeted antigen constructs, each validated through drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Primary fieldwork combined structured interviews with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down revenue triangulation anchored segmentation-specific estimates across the analysis window.
Assumptions held fixed include FDA breakthrough therapy designation criteria stability, EMA PRIME eligibility thresholds, and site-of-care reimbursement mechanics under Medicare Part B. Variables tested spanned plasmid DNA supply concentration scenarios, leukapheresis capacity expansion rates, and biosimilar entry timing. The analytical framework modeled product type, therapy area, end user channel, and regional regulatory cluster dimensions. CAGRs derived from segment-level volume builds and pricing trajectory assessments, with viral vector manufacturing automation curves and autoimmune label expansion probabilities as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in biologics reimbursement policy, capital market access for clinical-stage biotech, or trade restrictions on GMP-grade plasmid would shift the trajectory. Cross-checking against CMS Medicare claims data and EMA marketing authorization databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Paracetamol Market
Pharmaceuticals
Anti Obesity Prescription Drugs Market
Pharmaceuticals
Europe Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Anti-Vascular Endothelial Growth Factor Therapeutics Market
Pharmaceuticals
Vaginal Antifungals Market
Pharmaceuticals
Global Non-Alcoholic Fatty Liver Disease (NAFLD) Drug Market
Pharmaceuticals
Global Chemotherapy-Induced Neutropenia (CIN) Treatment Market
Pharmaceuticals
Global Psychotropic Drugs Market
Pharmaceuticals
North America Pharmaceutical Warehousing Market
Pharmaceuticals
Saline Laxative Market
Pharmaceuticals
Europe Meglitinide Market
Pharmaceuticals
Large Molecule Contract Development and Manufacturing Organization Market
Pharmaceuticals
Soft Capsules Drugs Market
Pharmaceuticals
OX40 Receptor Agonist Market
Pharmaceuticals
Cerumenolytic Agents Market
Pharmaceuticals
New Zealand Diabetes Drugs Market