
 Stroke Management Market | 2026-2036
Stroke Management Market Size, Share, and Industry Trends Forecast 2026-2036
Stroke Management Market Analysis
Emergency medical services is reorganizing stroke triage protocols, redirecting high-acuity cases toward comprehensive stroke centers with endovascular capabilities. Medtronic leverages its neurovascular portfolio to anchor thrombectomy market presence across North American hospital networks. Stryker Corporation dominates mechanical retrieval device innovation through sustained R&D investment in next-generation stent retrievers. Johnson & Johnson competes in hemorrhagic stroke management via its cerebrovascular clip and coil specialization.
Stroke management encompasses the coordinated clinical, pharmaceutical, and interventional approaches to acute cerebrovascular events, including intravenous thrombolysis with tissue plasminogen activator administered within 4.5 hours of onset and mechanical thrombectomy performed through femoral arterial access with catheter-based aspiration or stent retrieval systems. Its primary purpose is to restore cerebral perfusion, limit infarct volume, and reduce long-term disability burden. Medical Devices commands the largest revenue pool as thrombectomy systems generate premium pricing and repeat catheter consumption, while Neuroprotective Agents represent the fastest-expanding segment as pharmaceutical developers pursue cytoprotective adjuncts to reperfusion therapy. Acute Ischemic Stroke applications concentrate the majority of procedural volumes, though Rehabilitation services are extending market boundaries into post-acute recovery economics.
FDA breakthrough device designations compress premarket timelines for novel thrombectomy platforms, while EU MDR recertification demands intensify clinical evidence requirements for legacy devices. ISO 13485 quality management standards govern manufacturing consistency across neurovascular catheter production. Stakeholders must monitor reimbursement parity between thrombectomy and thrombolysis as health technology assessment bodies recalibrate cost-effectiveness thresholds for stroke interventions.
Market Dynamics
The Stroke Management Market is undergoing structural reorganization around thrombectomy capability expansion, as emergency medical services redirect high-acuity cases toward comprehensive stroke centers with endovascular suites. This geographic consolidation of procedural demand is reshaping equipment procurement patterns and hospital network investments.
Growth Catalysts
- EU MDR recertification timelines:The Medical Device Regulation's phased implementation is accelerating product development cycles for legacy thrombectomy platforms, compressing time-to-market for next-generation stent retrievers and aspiration catheters.
- Comprehensive stroke center networks:Hospital systems in the United States, Germany, and Japan are deepening thrombectomy capabilities, creating concentrated demand pools for mechanical retrieval devices and neurovascular catheter systems.
- Tissue plasminogen activator protocol standardization:Intravenous thrombolysis administration windows are hardening clinical workflows, driving parallel investment in imaging infrastructure and stroke team activation systems.
Market Restraints
- Premium device cost structure:Thrombectomy systems command pricing that strains hospital capital budgets, particularly in secondary markets lacking volume economics to justify endovascular suite construction.
- Supply concentration in neurovascular catheters:Manufacturing of aspiration catheters and stent retrievers concentrates among specialized contract manufacturers, creating vulnerability to production bottlenecks and quality excursions.
- Technical limitation in distal vessel access:Current catheter designs face physical constraints reaching M2 and M3 segment occlusions, capping addressable patient populations for mechanical thrombectomy.
Strategic Opportunities
- Underpenetrated markets in India and Brazil:Stroke center density remains low relative to disease burden, creating whitespace for mobile stroke unit deployment and telestroke-enabled thrombolysis networks.
- Cytoprotective adjunct convergence:Pharmaceutical developers are pursuing neuroprotective agents as complements to reperfusion therapy, opening device-pharma partnership models for bundled acute stroke protocols.
- Japan's aging demographic mandate:METI and PMDA priorities for reducing long-term disability burden are channeling reimbursement toward technologies demonstrating modified Rankin Scale improvements.
Industry Challenges
- Interventional neuroradiologist training pipelines:The specialized skill set for mechanical thrombectomy—combining neuroimaging interpretation, microcatheter manipulation, and hemodynamic management—faces global shortage relative to procedural demand growth.
- ISO 13485 certification complexity:Quality management system audits for neurovascular catheter production are lengthening supplier qualification timelines, constraining manufacturing scale-up for emerging device developers.
- Health technology assessment parity disputes:Reimbursement bodies in Germany and England are recalibrating cost-effectiveness thresholds, creating uncertainty in pricing negotiations for thrombectomy relative to thrombolysis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stroke Management Market |
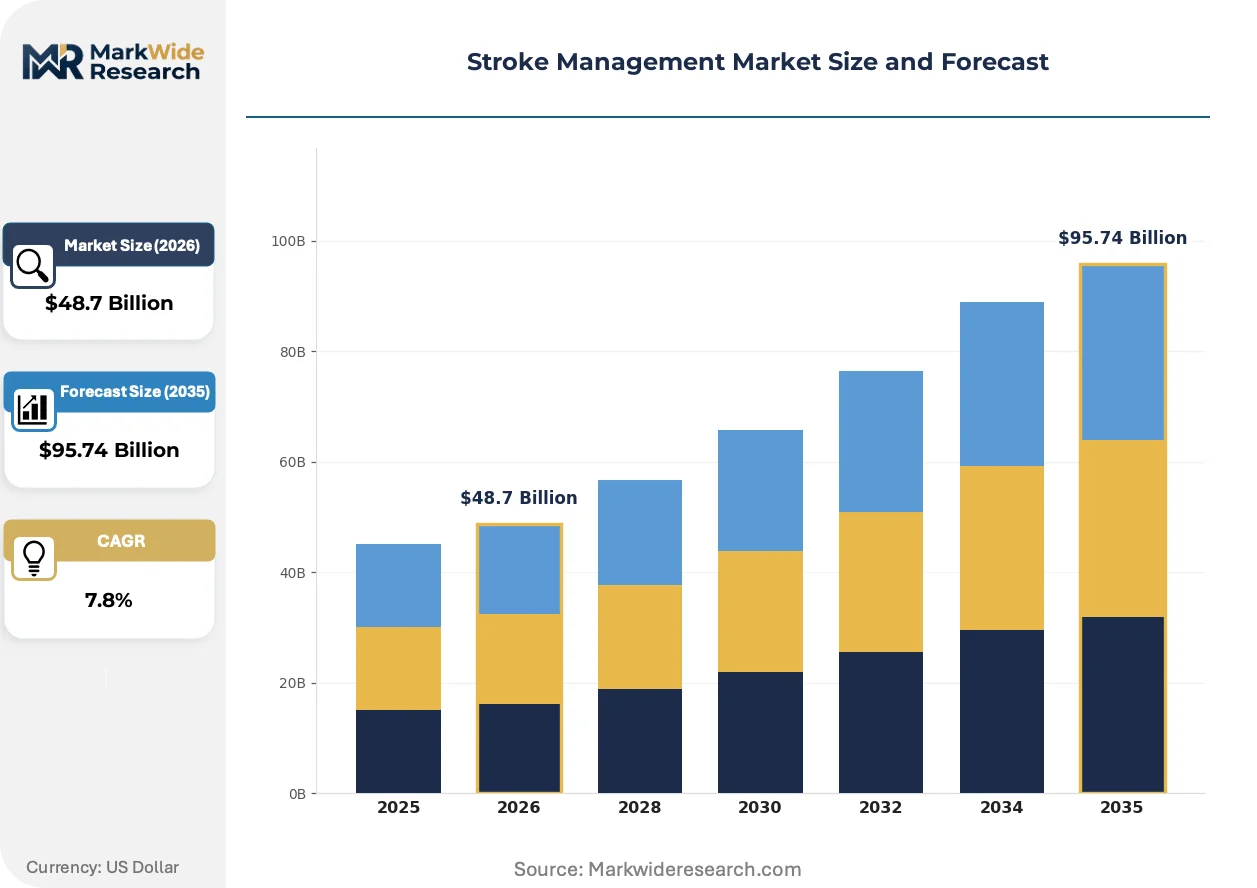
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $95.74 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thrombolytics, Anticoagulants, Neuroprotective Agents, Medical Devices Application: Acute Ischemic Stroke, Hemorrhagic Stroke, Transient Ischemic Attack, Rehabilitation End User: Hospitals, Clinics, Long-term Care Facilities, Home Care Providers Delivery Mode: Intravenous, Oral, Subcutaneous, Intra-arterial |
| Companies Covered | Medtronic, Stryker Corporation, Johnson & Johnson, Penumbra, Boston Scientific Corporation, Abbott Laboratories, Siemens Healthineers, Philips Healthcare, GE HealthCare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stroke Management Market Emerging Trajectories
Thrombectomy technology is fragmenting into specialized device categories, with aspiration catheters and stent retrievers diverging in design philosophy rather than converging on universal platforms. This specialization is compressing product lifecycles and intensifying R&D allocation decisions.
Next-generation aspiration catheters with larger distal lumens and improved trackability are decomposing the historical dominance of stent retriever-first approaches in anterior circulation large vessel occlusions. Comprehensive stroke centers in the United States are adopting these systems for faster first-pass reperfusion, reducing procedure times and anesthesia exposure. The technology is decomposing established market segmentation between aspiration-dominant and stent retriever-dominant operators, forcing device portfolios to cover both modalities.
FDA breakthrough device designations are compressing premarket timelines for novel thrombectomy platforms, particularly those targeting distal vessel indications or hemorrhagic stroke applications. The designation streamlines clinical evidence requirements and facilitates earlier payer engagement, though post-market surveillance obligations intensify. Neurovascular device developers are responding by front-loading regulatory strategy and building FDA interaction cadence into product development roadmaps.
Hospital procurement for stroke systems is consolidating toward integrated capital-equipment contracts that bundle imaging, catheter inventory, and technical support. This shift displaces transactional device purchasing and favors suppliers with service infrastructure depth. The United States exhibits the most pronounced consolidation, as health system centralization creates concentrated buying power and demands outcome guarantees.
Stroke Management Market Segmentation
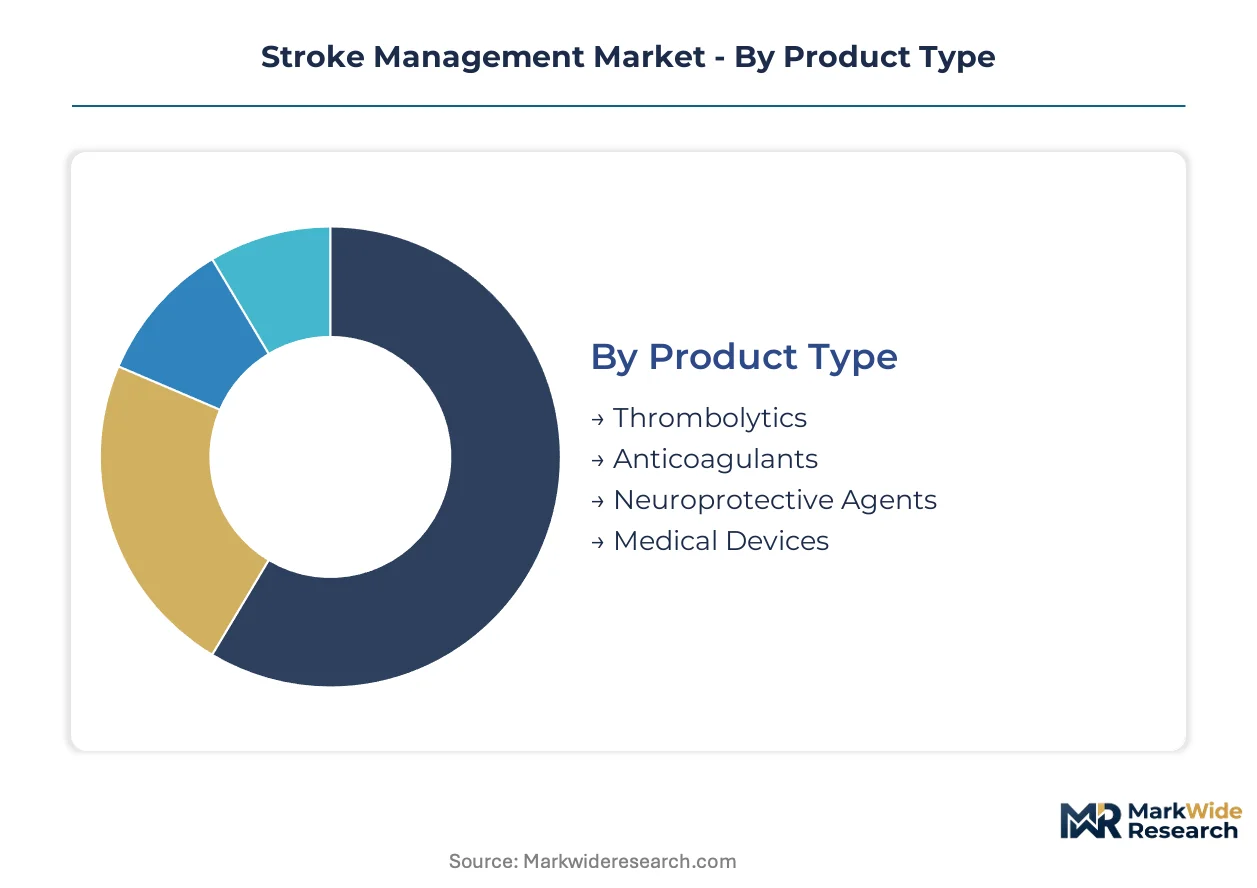
Stroke management segmentation reveals distinct procurement patterns across acute intervention versus chronic care pathways. Product type and application splits determine reimbursement coding, while end-user concentration shapes distribution economics and device servicing requirements.
Product Type:
Domestic production dominates thrombolytics and anticoagulants through established pharmaceutical manufacturing, while medical devices and neuroprotective agents carry heavier import dependence from specialized neurovascular developers.
- Thrombolytics:Intravenous tissue plasminogen activator formulations constitute the pharmacologic foundation of acute ischemic stroke protocols. Demand concentrates in United States comprehensive stroke centers where door-to-needle time metrics drive inventory positioning and cold-chain logistics investment.
- Medical Devices:Mechanical thrombectomy systems encompass aspiration catheters, stent retrievers, and microcatheter delivery platforms requiring precision manufacturing. German and Japanese hospital networks anchor procurement volumes, with METI and PMDA reimbursement pathways favoring technologies demonstrating modified Rankin Scale outcomes.
- Anticoagulants:Oral and parenteral formulations for secondary stroke prevention flow through retail pharmacy and hospital discharge channels.
- Neuroprotective Agents:Cytoprotective drug candidates in clinical development target ischemia-reperfusion injury as adjuncts to mechanical revascularization.
Medical Devices holds the largest share; momentum sits with Neuroprotective Agents.
Application:
Volume distribution tracks the epidemiology of cerebrovascular events, with procedural reimbursement tiers creating margin differentiation across acute versus chronic management phases.
- Acute Ischemic Stroke:Large vessel occlusion cases eligible for mechanical thrombectomy generate the highest procedural reimbursement and device consumption per episode. United States comprehensive stroke centers capture the majority of intervention volumes, with EMS triage protocols hardening geographic demand concentration.
- Rehabilitation:Post-acute recovery services extend market boundaries into physical therapy, speech pathology, and occupational therapy economics. Japan's aging demographic mandate channels public reimbursement toward disability reduction outcomes, expanding addressable spend per stroke episode.
- Hemorrhagic Stroke:Aneurysmal subarachnoid hemorrhage and intracerebral hemorrhage management rely on surgical clipping, endovascular coiling, and blood pressure control protocols.
- Transient Ischemic Attack:Diagnostic workup and secondary prevention protocols drive neuroimaging and antiplatelet pharmaceutical demand.
Acute Ischemic Stroke commands dominant procedure volumes; Rehabilitation exhibits the steepest expansion trajectory.
End User:
Capital equipment requirements and clinical staffing depth stratify end-user segments, with thrombectomy capability serving as the decisive threshold between tiers.
- Hospitals:Comprehensive stroke centers with endovascular suites represent the concentrated demand pool for mechanical thrombectomy devices and neurointerventional support services. United States health system centralization is consolidating procurement authority toward integrated capital-equipment contracts.
- Long-term Care Facilities:Post-acute rehabilitation and secondary prevention management create recurring pharmaceutical demand and therapy service contracts.
- Clinics:Outpatient stroke prevention and TIA assessment centers drive diagnostic imaging and anticoagulation monitoring volumes.
- Home Care Providers:Subcutaneous anticoagulant administration and remote patient monitoring extend care delivery beyond institutional settings.
Hospitals absorb the majority of device expenditure; Long-term Care Facilities are gaining share fastest.
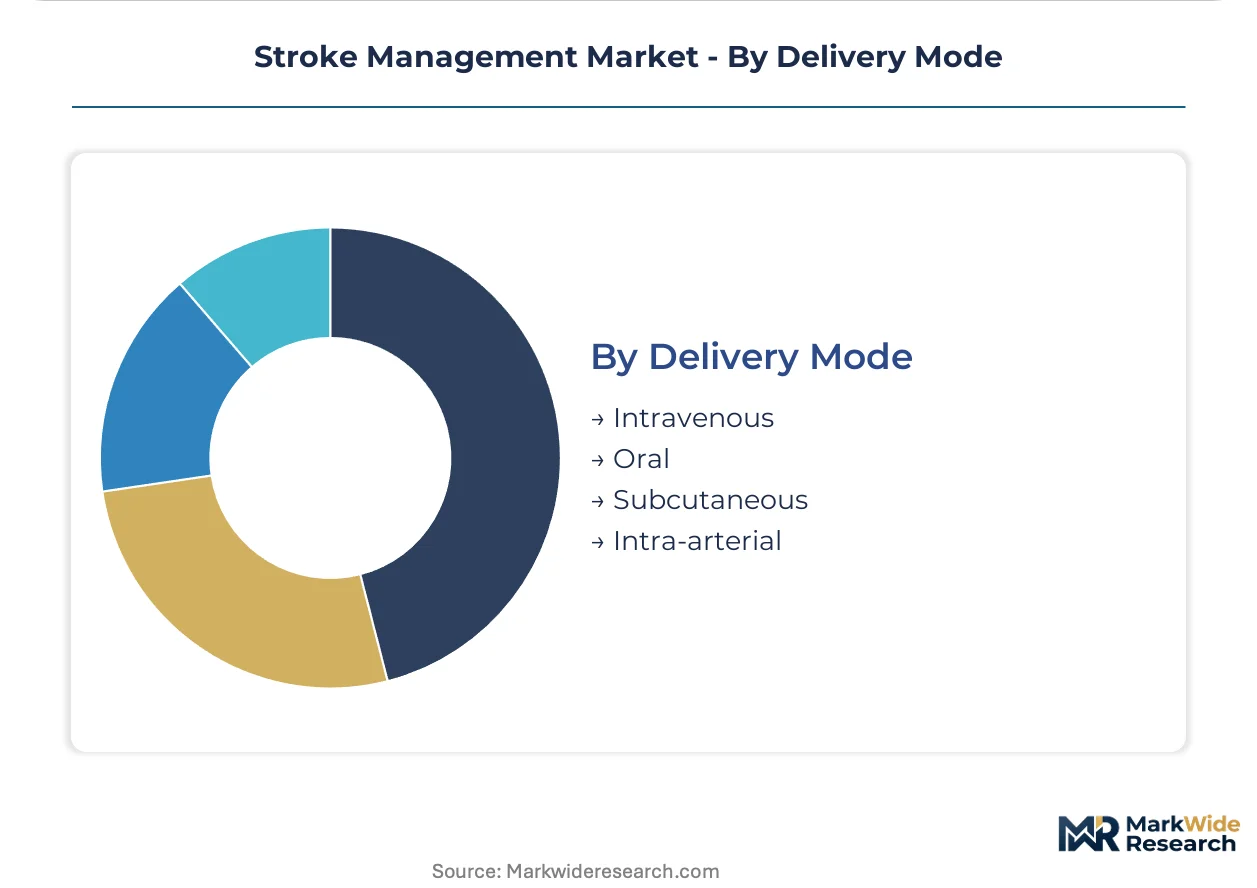
Delivery Mode:
Route of administration determines regulatory pathway, manufacturing complexity, and reimbursement coding granularity across the product portfolio.
- Intravenous:Thrombolytic infusion and neuroprotective agent delivery require acute care setting infrastructure with stroke team activation protocols. FDA breakthrough designations for novel IV cytoprotective candidates are compressing development timelines.
- Intra-arterial:Catheter-based drug delivery and mechanical thrombectomy access demand interventional neuroradiologist specialization and angiography suite capital investment.
- Oral:Anticoagulant and antiplatelet maintenance therapy flows through retail pharmacy distribution with established compliance monitoring programs.
- Subcutaneous:Low-molecular-weight heparin and novel anticoagulant formulations enable outpatient transition from acute to chronic management.
Intravenous maintains the largest procedure volume; Intra-arterial shows the fastest adoption curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Comprehensive stroke centers concentrate procurement authority in the United States, Germany, and Japan, where emergency medical services redirect high-acuity cases toward endovascular-capable facilities. FDA breakthrough designations, EU MDR recertification timelines, and METI aging-mandate priorities accelerate product development cycles across these markets. Each geography shapes distinct reimbursement pathways and regulatory evidence requirements.
United States
Health system centralization creates concentrated buying power for mechanical thrombectomy devices, with integrated capital-equipment contracts displacing transactional purchasing. FDA breakthrough device designations compress premarket timelines for novel platforms targeting distal vessel indications. The Southeast and Midwest hospital networks anchor procedural volume growth as comprehensive stroke center certification expands beyond traditional academic medical centers.
Germany
Health technology assessment bodies recalibrate cost-effectiveness thresholds for thrombectomy relative to thrombolysis, creating pricing negotiation uncertainty for device manufacturers. EU MDR recertification demands intensify clinical evidence requirements for legacy neurovascular catheters. The North Rhine-Westphalia and Bavaria regions concentrate stroke center density, with university hospitals in Cologne and Munich driving adoption of next-generation aspiration systems.
Japan
METI and PMDA priorities for reducing long-term disability burden channel reimbursement toward technologies demonstrating modified Rankin Scale improvements. The aging demographic mandate accelerates regulatory review timelines for neuroprotective agents and mechanical retrieval devices. Kanto and Kansai regions dominate procedural volumes, with Tokyo and Osaka metropolitan stroke centers serving as reference sites for device training and clinical validation.
United Kingdom
NICE health technology assessments create reimbursement parity disputes between thrombectomy and thrombolysis, influencing hospital capital allocation decisions. NHS England's stroke service reconfiguration redirects high-acuity cases toward designated comprehensive centers with 24-hour endovascular capability. The London and Greater Manchester health systems anchor demand concentration, with ambulance triage protocols hardening geographic patient flow patterns.
India
Stroke center density remains low relative to disease burden, creating whitespace for mobile stroke unit deployment and telestroke-enabled thrombolysis networks. The country's national pharmaceutical regulator streamlines pathways for imported neurovascular devices while domestic manufacturing incentives expand. Maharashtra and Karnataka states concentrate private hospital investment in Mumbai and Bangalore, where corporate health chains build thrombectomy capabilities for medical tourism and insured patient segments.
Stroke Management Market Vendor Landscape
Player mix skews toward diversified medical technology conglomerates with neurovascular portfolio anchoring. The market structure concentrates around three to five integrated suppliers controlling mechanical thrombectomy systems, while specialized catheter developers occupy niche positioning. Strategic archetypes include full-stack thrombectomy platform providers, imaging-integrated solution bundlers, and neuroprotective pharmaceutical-device convergence plays. Competitive moves center on hospital procurement consolidation through integrated capital contracts and regulatory pathway acceleration via FDA breakthrough designations.
Within the diversified medical technology tier, Medtronic and Stryker Corporation occupy positions exemplifying full-stack neurovascular platform strategies, while Johnson & Johnson represents the cerebrovascular specialization archetype through hemorrhagic stroke device portfolios. These anchors illustrate how scale-driven service infrastructure and regulatory engagement cadence shape competitive positioning in consolidated hospital procurement environments.
| Leading Market Players |
|---|
| Medtronic |
| Stryker Corporation |
| Johnson & Johnson |
| Penumbra |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Siemens Healthineers |
| Philips Healthcare |
| GE HealthCare |
| Others |
Supply Flow & Price Mechanics
EU MDR recertification timelines gate both neurovascular catheter supplier qualification and price differentiation across legacy versus next-generation thrombectomy platforms simultaneously. Manufacturers face compressed windows to demonstrate clinical equivalence while hospitals exploit procurement consolidation to extract outcome guarantees.
Pricing Analysis
Cost-plus contracts with medical device price indexation dominate hospital procurement for mechanical thrombectomy systems. Three-tier pricing structure across premium aspiration catheters, standard stent retrievers, and economy microcatheter bundles reflects ISO 13485 certification grade and after-sales technical support depth. Pricing pressure stems from health technology assessment bodies recalibrating cost-effectiveness thresholds for thrombectomy relative to thrombolysis. Secondary market hospitals exhibit highest price sensitivity due to volume economics constraints, while comprehensive stroke centers in the United States absorb premium positioning through integrated capital-equipment contracts.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports constrain just-in-time catheter inventory for German hospital networks. Manufacturing of aspiration catheters and stent retrievers concentrates in Ireland, Costa Rica, and Malaysia, drawing from nitinol alloy feedstock and precision polymer extrusion components. Single-source vulnerability in specialized contract manufacturers for neurovascular catheter production creates exposure to quality excursions and ISO 13485 audit delays. Distribution runs through regional distribution centers serving comprehensive stroke center networks, with emergency stockholding obligations shifting to hospital systems under integrated service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stroke management market fragmentation creates entry niches as EMS triage protocols harden geographic demand concentration and device specialization diverges between aspiration and stent retriever modalities.
For Market Incumbents: Fortify service infrastructure depth to defend integrated capital-equipment contract positioning against emerging catheter developers. Deepen vertical integration into nitinol alloy processing to mitigate raw material cost volatility and supplier qualification bottlenecks. Anchor hospital network relationships through outcome-based technical support commitments that lock out transactional competitors. For New Entrants and Emerging Players: Differentiate on distal vessel access catheter designs targeting M2 and M3 segment occlusions currently underserved by incumbent portfolios. Penetrate India's mobile stroke unit deployment whitespace through telestroke-enabled thrombolysis partnerships with corporate health chains in Maharashtra and Karnataka. Pursue FDA breakthrough device designation pathway to compress premarket timelines and facilitate earlier payer engagement. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across neuroprotective agent clinical development as pharmaceutical-device convergence models demand bundled protocol investment. Long-term viability favors acquisition targets with ISO 13485-certified manufacturing infrastructure and established PMDA or FDA regulatory engagement cadence. Watch for modified Rankin Scale outcome data publication as inflection signal for reimbursement pathway expansion in Japan's aging-mandate market.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Pathway | Accelerates clinical evidence generation for legacy thrombectomy platforms seeking European market access. |
| Hospital System Partnership | Locks in procedural volume commitments through integrated capital-equipment and technical service bundling. |
| FDA Breakthrough Device Submission | Compresses premarket review timelines for distal vessel catheter designs and neuroprotective delivery systems. |
| Software Companion Development | Enables real-time imaging integration and stroke team activation workflow optimization for comprehensive centers. |
| Reimbursement Strategy | Secures coverage parity for thrombectomy relative to thrombolysis through health technology assessment engagement. |
Methodological Framework
A standing panel of interventional neuroradiologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA 510(k) filings, EMA medical device registration databases, CMS Medicare procedure volume data, and hospital procurement contract repositories. Bottom-up modeling of catheter consumption per procedure triangulated against top-down manufacturer revenue disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, application, end-user facility tier, and delivery mode, with regional regulatory cluster overlays for FDA, EMA, and PMDA pathways. CAGRs were derived from procedure volume elasticity to comprehensive stroke center network expansion and technology adoption curve analysis for aspiration versus stent retriever modality shifts.
Material uncertainties — regulatory approval delays, reimbursement parity disputes, and interventionalist training pipeline constraints — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding EMS triage protocol implementation and hospital capital budget cycles. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Global Hyperlipidemia Drugs Market
Cardiovascular
Cardiac Valvulotome Market
Cardiovascular
Restrictive Cardiomyopathy Treatment Market
Cardiovascular
Heart Block Therapeutics Market
Cardiovascular
Heterozygous Familial Hypercholesterolemia (HEFH) Management Market
Cardiovascular
Unstable Angina Therapeutics Market
Cardiovascular
Carotid Artery Disease Market
Cardiovascular
Chronic Heart Failure Market
Cardiovascular
Global Advanced Cardiovascular Life Support Market
Cardiovascular
Angina Pectoris Market
Cardiovascular
Myocardial Infarction Market
Cardiovascular
Myocarditis Disease Market
Cardiovascular
Stable Angina Management Market
Cardiovascular
Global Atrial Fibrillation Market
Cardiovascular
Takotsubo Syndrome Therapeutics Market
Cardiovascular
Antihypertensive Market