
 Atherosclerosis Market | 2026-2036
Atherosclerosis Market Size, Share, and Industry Trends Forecast 2026-2036
Atherosclerosis Market Analysis
The atherosclerosis treatment landscape is pivoting between premium biologic therapies and commodity statin generics. Merck & Co. anchors its position through deep vertical integration in active pharmaceutical ingredient manufacturing. Amgen differentiates via sustained R&D intensity in PCSK9 inhibitor platforms. Pfizer competes through geographic dominance in established oral antiplatelet markets.
Atherosclerosis denotes the pathological thickening and hardening of arterial walls driven by lipid accumulation, fibrous plaque formation, and chronic inflammation, with luminal narrowing typically quantified by percent stenosis on angiography. The condition demands continuous clinical management to prevent myocardial infarction, stroke, and peripheral artery occlusion. Stents and drug-eluting platforms capture the largest margin pools in the product type dimension, while vascular surgery represents the fastest-expanding therapy area due to rising diabetic foot and carotid interventions. Injectable delivery modes lead in acute settings, though oral formulations sustain the majority of chronic maintenance prescriptions.
The FDA, EMA, and Japan's PMDA collectively enforce evolving cardiovascular device and pharmaceutical standards that shape trial design, labeling claims, and reimbursement access across major markets. REACH and RoHS frameworks in Europe additionally constrain material selection in catheter and stent manufacturing, elevating compliance costs for suppliers. Stakeholders must monitor how payer consolidation and value-based contracting criteria redefine acceptable efficacy thresholds for new plaque-modifying therapies.
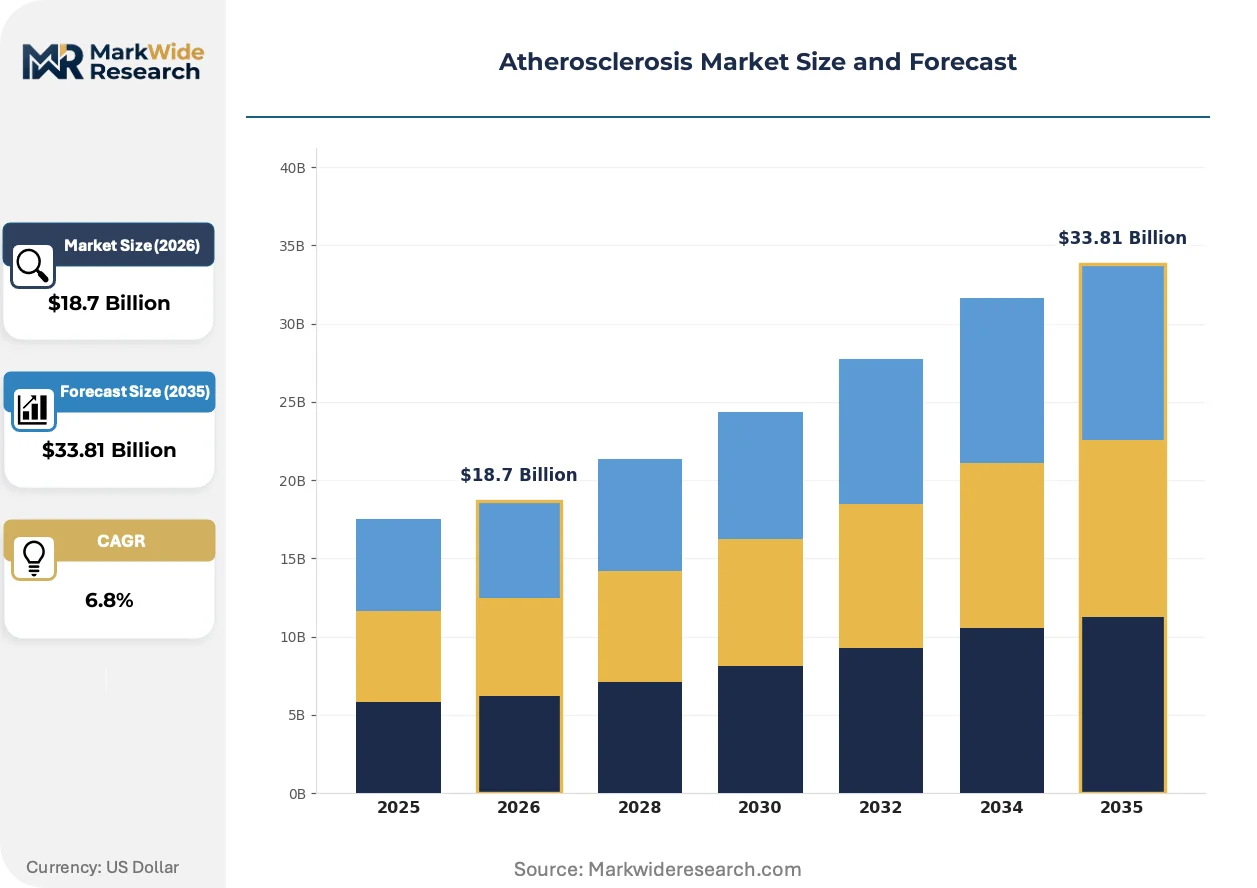
Market Dynamics
Hospital catheterization lab expansion in the United States is compressing device procurement cycles while FDA accelerated approval pathways compress development timelines for plaque-modifying therapies. This dual pressure is reshaping competitive positioning between established statin portfolios and emerging biologic platforms.
Growth Catalysts
- Catheterization Lab Capacity:United States hospital systems are adding interventional suites to address coronary artery disease burden. Device manufacturers capture expanded procurement volumes from these infrastructure investments.
- REACH and RoHS Compliance:European material standards for catheters and stents are elevating technical barriers. Suppliers with certified manufacturing lines gain preferential access to German vascular centers.
- PCSK9 Inhibitor Platforms:Sustained R&D intensity in injectable biologics is creating new maintenance therapy categories. These agents address residual cardiovascular risk in statin-intolerant patients.
Market Restraints
- Active Pharmaceutical Input Concentration:Statins and antiplatelet APIs concentrate in Asian manufacturing clusters. Supply disruptions propagate quickly through generic oral formulation networks.
- Reimbursement Compression:Payer consolidation in Germany and the United States is tightening value-based contracting criteria. New plaque-modifying therapies face elevated evidence thresholds for formulary inclusion.
- Commodity Statin Substitution:Generic atorvastatin and rosuvastatin dominate chronic maintenance prescriptions. Premium biologics struggle to justify cost differentials in primary prevention populations.
Strategic Opportunities
- Diabetic Foot Intervention:Rising diabetes prevalence is expanding vascular surgery volumes for limb salvage. Specialized centers in the United States are integrating advanced imaging with revascularization workflows.
- Japan PMDA Pathways:Japan's pharmaceutical regulator offers streamlined review for cardiovascular devices with prior FDA or EMA approval. Manufacturers can sequence market entry to capture Asia-Pacific demand.
- Drug-Eluting Platform Convergence:Combination devices integrating antiproliferative agents with bioresorbable scaffolds are entering clinical evaluation. These hybrids target restenosis reduction in complex lesions.
Industry Challenges
- Interventional Cardiologist Training Bottlenecks:Complex carotid and peripheral procedures require specialized operator certification. Fellowship programs are not scaling to match catheterization lab expansion.
- Legacy EHR Integration:New imaging and hemodynamic monitoring systems must interface with hospital IT infrastructure. Deployment timelines stretch due to interoperability testing requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atherosclerosis Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Drugs, Catheters, Imaging Devices Therapy Area: Cardiology, Neurology, Endocrinology, Vascular Surgery End User: Clinics, Hospitals, Research Facilities, Homecare Settings Delivery Mode: Injectable, Oral, Transdermal, Intravenous |
| Companies Covered | Merck & Co., Inc., Amgen Inc., Pfizer Inc., Bayer AG, Regeneron Pharmaceuticals, Inc., Novartis AG, Sanofi, Johnson & Johnson, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atherosclerosis Market Emerging Trajectories
Advanced imaging modalities are merging with interventional workflows to enable real-time plaque characterization. This convergence is compressing the gap between diagnostic assessment and therapeutic intervention.
Intravascular ultrasound and optical coherence tomography systems are integrating into catheterization lab standard equipment configurations. United States academic medical centers are adopting these platforms at accelerating replacement cycles. The technology is integrating procedural decision-making with lesion-specific morphology data, reducing reliance on angiographic stenosis estimates alone.
The FDA's accelerated approval pathway for cardiovascular therapies is compressing Phase III trial durations. Sponsors must now construct confirmatory evidence packages prior to initial clearance. Drug-eluting stent manufacturers face the most acute timeline pressure as post-market study commitments accumulate.
Hospital procurement committees are consolidating vendor relationships to simplify service contracting. Integrated device and pharmaceutical purchasing is displacing category-specific sourcing in United States health systems. This concentration is most visible in catheterization lab capital equipment, where single-source agreements now bundle imaging, intervention, and consumable supply.
Atherosclerosis Market Segmentation
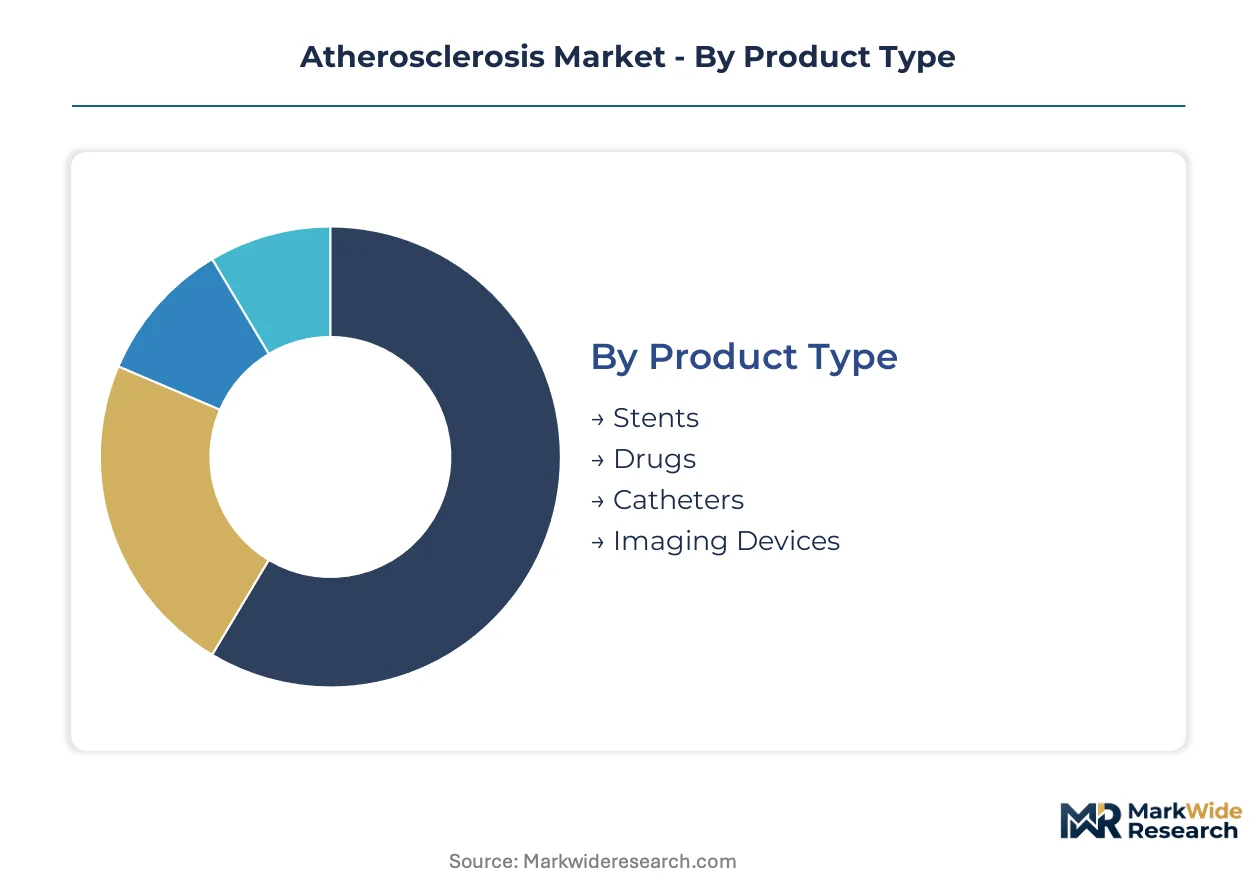
Segmentation in atherosclerosis treatment reveals divergent margin structures between acute intervention devices and chronic pharmaceutical maintenance. Procurement patterns vary sharply across catheterization labs, vascular surgery suites, and outpatient cardiology clinics.
Product Type:
The customization spectrum spans from patient-specific stent sizing to commodity oral formulations with minimal configuration.
- Stents:Drug-eluting and bioresorbable platforms command premium pricing through proprietary polymer coatings and controlled-release kinetics. United States hospital catheterization labs are consolidating procurement around integrated stent-imaging bundles to streamline vendor management.
- Drugs:Statins, antiplatelet agents, and PCSK9 inhibitors range from generic atorvastatin to patented injectable biologics. German vascular centers are prioritizing plaque-modifying therapies with demonstrated LDL reduction in complex patient populations.
- Catheters:Guiding and diagnostic catheters incorporate hydrophilic coatings and torque-responsive shafts for lesion navigation.
- Imaging Devices:Intravascular ultrasound and optical coherence tomography systems enable real-time plaque characterization during intervention.
Leading the category by volume: Drugs. Growing fastest: Stents.
Therapy Area:
Cost tiers separate emergency revascularization from scheduled limb-salvage procedures.
- Vascular Surgery:Carotid endarterectomy, peripheral bypass, and diabetic foot revascularization demand specialized operator training and hybrid operating room infrastructure. United States academic medical centers are expanding fellowship programs to address interventionalist shortages.
- Cardiology:Percutaneous coronary intervention remains the highest-volume atherosclerosis procedure category, with transcatheter approaches displacing open surgical revascularization in select anatomies.
- Neurology:Carotid stenting and intracranial intervention address cerebrovascular atherosclerotic disease.
- Endocrinology:Medical management of diabetic atherosclerosis emphasizes glycemic control alongside lipid modification.
Highest procedural volume: Cardiology. Steepest expansion trajectory: Vascular Surgery.
End User:
Customer type determines capital intensity and reimbursement pathway complexity.
- Hospitals:Catheterization labs and hybrid operating rooms concentrate advanced imaging, interventional devices, and critical care capacity. United States health systems are adding interventional suites to capture transfer volume from community hospitals.
- Clinics:Outpatient cardiology and vascular practices manage chronic pharmaceutical therapy and post-intervention surveillance.
- Research Facilities:Academic centers conduct plaque-modifying therapy trials under FDA accelerated approval pathways.
- Homecare Settings:Subcutaneous PCSK9 inhibitor administration and anticoagulation monitoring extend therapy beyond facility walls.
Dominant revenue share: Hospitals. Gaining share fastest: Homecare Settings.
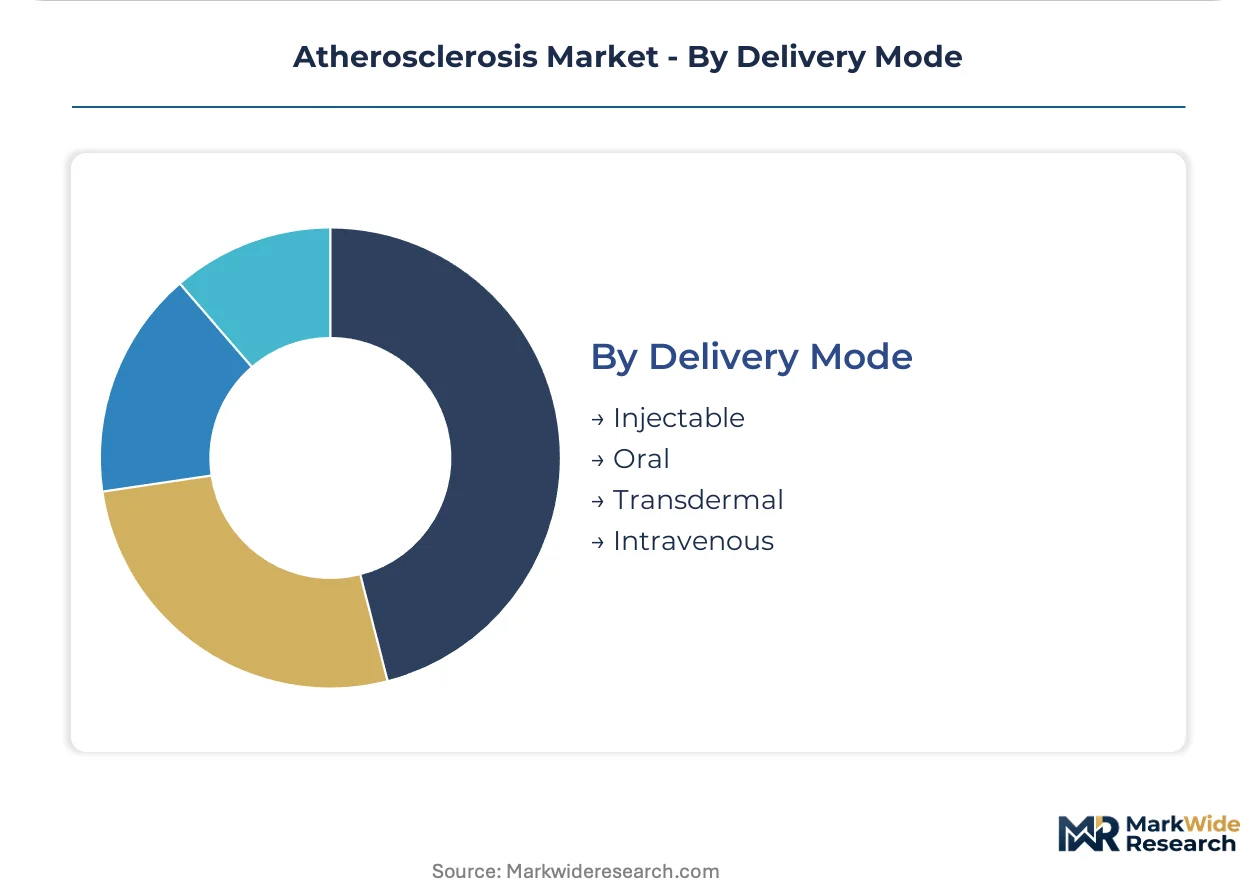
Delivery Mode:
Margin structure inverts between acute parenteral administration and chronic oral maintenance.
- Injectable:PCSK9 inhibitors and anticoagulants require cold-chain distribution and healthcare professional administration. German reimbursement authorities are tightening value-based criteria for biologic access.
- Oral:Statins and antiplatelet agents sustain the majority of chronic prescriptions through retail pharmacy distribution.
- Intravenous:Acute anticoagulation and thrombolytic therapy in coronary and peripheral intervention.
- Transdermal:Nitroglycerin patches for angina prophylaxis represent limited atherosclerosis-specific application.
Largest prescription volume: Oral. Climbing the fastest: Injectable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors North American atherosclerosis research density, hosting multiple academic medical centers conducting plaque-modifying therapy trials under FDA accelerated approval pathways.
United States
Cleveland Clinic and Mayo Clinic catheterization labs are expanding interventional capacity to capture coronary artery disease transfer volume from community hospitals. The FDA's breakthrough device designation streamlines market entry for intravascular imaging platforms. Texas Medical Center in Houston is consolidating vendor relationships around single-source stent-imaging bundles.
Germany
Specialized vascular centers in Munich and Heidelberg are integrating optical coherence tomography with revascularization workflows for complex lesions. REACH and RoHS frameworks elevate material compliance costs for catheter and stent suppliers. The Rhine-Main cluster around Frankfurt concentrates pharmaceutical distribution infrastructure for PCSK9 inhibitor cold-chain logistics.
Japan
Tokyo's academic medical centers are adopting intravascular ultrasound at accelerated replacement cycles for real-time plaque characterization. PMDA offers streamlined review for cardiovascular devices with prior FDA or EMA approval. The Kansai region around Osaka hosts manufacturing facilities for hydrophilic-coated diagnostic catheters.
China
Shanghai's Fudan University-affiliated hospitals are conducting trials for bioresorbable scaffolds targeting restenosis reduction. NMPA cardiovascular device standards are converging with international norms to facilitate import substitution. The Yangtze River Delta concentrates domestic stent manufacturing capacity.
United Kingdom
London's Barts Heart Centre is expanding hybrid operating room infrastructure for carotid and peripheral interventions. NICE value-based assessments tighten reimbursement thresholds for premium biologics against generic statins. The Cambridge life sciences cluster supports R&D partnerships between academic centers and device manufacturers.
Atherosclerosis Market Vendor Landscape
Premium-margin players sit above commodity-margin players across the statin-to-biologic spectrum, with patented injectable therapies commanding price multiples against generic oral formulations. The vendor base stratifies into three tiers: integrated pharmaceutical conglomerates with API manufacturing control, biologic specialists with sustained R&D intensity in PCSK9 platforms, and commodity generic manufacturers competing on volume scale. Consolidation pressures are intensifying through hospital procurement committee vendor rationalization and single-source catheterization lab contracting.
Within the integrated pharmaceutical tier, Merck & Co., Inc. and Pfizer Inc. occupy positions shaped by vertical control over active pharmaceutical ingredient supply chains and geographic dominance in established oral antiplatelet markets. Amgen Inc. exemplifies the biologic specialist archetype through sustained platform investment in injectable cardiovascular therapies. These three anchors illustrate how competitive positioning diverges between backward-integrated scale players and R&D-intensive innovation specialists.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Amgen Inc. |
| Pfizer Inc. |
| Bayer AG |
| Regeneron Pharmaceuticals, Inc. |
| Novartis AG |
| Sanofi |
| Johnson & Johnson |
| AstraZeneca |
| Others |
Supply Flow & Price Mechanics
Hospital catheterization lab procurement committees in the United States concentrate purchasing power through single-source vendor consolidation. This buyer concentration enforces value-based contracting frameworks that tie device reimbursement to demonstrated restenosis reduction and procedural throughput metrics.
Pricing Analysis
Value-based pricing anchors device procurement through outcomes-linked contracts with hospital systems. Three-tier pricing structure across premium drug-eluting stents, standard bare-metal platforms, and economy generic statin formulations separates margin pools. Cost compression in oral maintenance therapies intensifies because payer consolidation demands LDL reduction evidence against commodity atorvastatin. Price sensitivity concentrates among outpatient cardiology clinics managing chronic prescriptions, while academic medical centers demonstrate lower sensitivity for integrated imaging-intervention bundles.
Supply Chain Analysis
Active pharmaceutical ingredient supply rests on concentrated manufacturing clusters in India and China for statin and antiplatelet production. Hydrophilic polymer coatings for catheters, bioresorbable scaffold polymers, and cold-chain distribution infrastructure for PCSK9 inhibitors constitute critical input dependencies. Single-source vulnerability propagates through generic oral formulation networks when Asian API facilities face regulatory inspection backlogs. Distribution runs through hospital GPO contracts in the United States, specialized vascular center direct agreements in Germany, and retail pharmacy networks for chronic maintenance therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The atherosclerosis treatment landscape has become a vertical-integration race. Players pursue backward control over API manufacturing to defend margin position against commodity substitution and supply disruption.
For Market Incumbents: Deploy catheterization lab single-source contracting to lock out competing stent and imaging vendors. Consolidate procurement relationships around bundled capital equipment and consumable supply agreements. Generic statin manufacturers threaten established biologic margins through formulary substitution campaigns in German and United States payer systems. For New Entrants and Emerging Players: Direct-to-physician digital education platforms offer low-friction entry for novel plaque-modifying therapies seeking prescriber awareness. Homecare settings for subcutaneous PCSK9 administration represent the most penetrable delivery mode expansion. Partner with integrated delivery networks for outcomes-based contracting pilots. For Investors and Strategic Acquirers: The window for entry favors biologic specialists with Phase III cardiovascular assets under FDA accelerated review. Long-term viability hinges on demonstrating LDL reduction in statin-intolerant populations against entrenched generic competition. Watch for reimbursement policy shifts in Germany's G-BA assessments as inflection indicators for European biologic access.| Strategic Initiative | Industry Significance |
|---|---|
| Catheterization Lab Single-Source Contracting | Hospital procurement committees in Texas Medical Center and Cleveland Clinic consolidate vendor relationships to streamline service agreements. |
| PCSK9 Inhibitor Outcomes-Based Contracting | Payers in Germany and United States demand LDL reduction evidence to justify premium biologic reimbursement against generic statins. |
| Bioresorbable Scaffold Clinical Advancement | Shanghai's Fudan University-affiliated hospitals evaluate restenosis reduction claims for next-generation vascular scaffolds. |
| API Manufacturing Backward Integration | Merck & Co. anchors competitive position through captive supply of active pharmaceutical ingredients for cardiovascular portfolios. |
| Intravascular Imaging Platform Integration | United States academic medical centers adopt IVUS and OCT systems at accelerated replacement cycles for real-time plaque characterization. |
Methodological Framework
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone for pipeline and regulatory tracking. Primary interviews with interventional cardiologists, hospital procurement managers, formulary directors, and payer access specialists validated market sizing assumptions. Bottom-up procedure volume estimates from catheterization lab expansion data combined with top-down pharmaceutical prescription analytics across the analysis window.
Historical trendline analysis of stent penetration rates and statin prescription volumes informed baseline trajectory construction. Segmentation modeling incorporated product type, therapy area, end user, and delivery mode dimensions alongside regional regulatory cluster differentiation. CAGRs derived from procedure growth projections and pricing elasticity assumptions for biologic versus generic maintenance therapies.
Inputs from hospital procurement databases and GPO contract disclosures were available through the study window; gaps in real-time PCSK9 inhibitor adherence data introduce uncertainty bands around long-term maintenance therapy forecasts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Portal Hypertension Management Market
Cardiovascular
Cardiovascular Disease Drugs Market
Cardiovascular
Aortic Coarctation Market
Cardiovascular
Global Hypotension Treatment Market
Cardiovascular
Cardiopulmonary Disease Diagnostics and Treatment Market
Cardiovascular
Angina Market
Cardiovascular
Pulmonary Valve Replacement Market
Cardiovascular
Cardiovascular Enterprise Viewer Market
Cardiovascular
Cardiac Valvulotome Market
Cardiovascular
Ischemic Cerebral Stroke Prevention Therapeutics Market
Cardiovascular
Bifurcation Lesions Market
Cardiovascular
Acute Coronary Syndrome (ACS) Market
Cardiovascular
Takotsubo Syndrome Therapeutics Market
Cardiovascular
Cardiac Arrhythmia Therapeutics Market
Cardiovascular
Cardiac Troponin Market
Cardiovascular
Peptide-Based Cardiovascular Therapeutics Market