
 Genetic Cardiomyopathies Market | 2026-2036
Genetic Cardiomyopathies Market Size, Share, and Industry Trends Forecast 2026-2036
Genetic Cardiomyopathies Market Foresight
Genetic testing services delivered through subscription-based laboratory partnerships is recalibrating how cardiogenetics reaches patients. Novartis International AG leverages its cardiovascular therapeutic footprint to anchor diagnostic-treatment integration. Bristol Myers Squibb Company sustains R&D intensity in precision cardiology through internal biomarker programs. Roche Holding AG dominates sequencing platform placements across European referral networks.
Genetic cardiomyopathies comprise inherited structural and electrical disorders of the myocardium, including hypertrophic, dilated, restrictive, and arrhythmogenic subtypes, typically diagnosed through DNA analysis of sarcomeric protein genes and desmosomal components. The primary purpose spans early identification of at-risk family members, stratification of sudden cardiac death risk, and guidance of implantable device or pharmacologic intervention decisions. Diagnostic kits and genetic testing services together command the deepest margin pools as laboratories prioritize turnkey workflows over capital-intensive sequencing platform ownership. Next-generation sequencing leads diagnosis approach volume while whole exome sequencing captures the fastest expansion among complex phenotype cases. Hypertrophic screening and arrhythmogenic testing concentrate demand among academic research centers pursuing genotype-phenotype correlation studies.
The FDA oversees in vitro diagnostic and gene therapy pathways for cardiogenetics in the United States, while the EMA governs CE-marked diagnostic kit approvals across European member states; Japan's PMDA maintains distinct pharmacogenomic labeling requirements that shape product registration strategies. These frameworks collectively elevate evidence standards for analytical validity and clinical utility claims, directly filtering which assay designs achieve commercial scale. Stakeholders must monitor how payer coverage policies for cascade family screening evolve relative to regulatory clearance timelines.
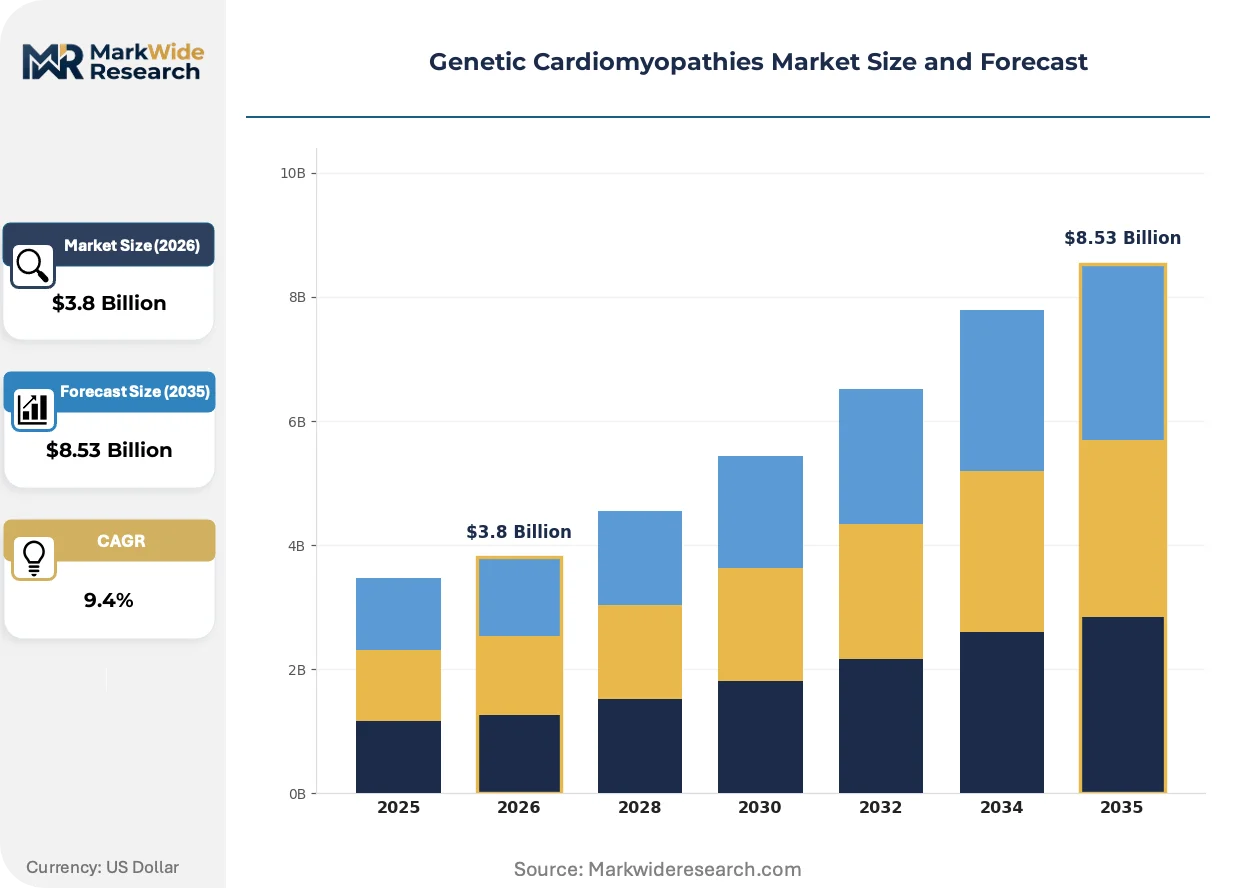
Market Dynamics
Precision diagnostic workflows are compressing the interval between genetic suspicion and therapeutic decision across cardiology referral networks. This compression is restructuring how laboratories, clinicians, and payers coordinate care pathways for inherited cardiac conditions.
Growth Catalysts
- EMA MDR implementation:The Medical Device Regulation's enhanced clinical evidence requirements for CE-marked diagnostic kits is accelerating consolidation among assay developers capable of generating robust analytical validity data.
- Cascade family screening protocols:Cardiogenetics programs in Germany, Japan, and the United States are systematically extending testing to first-degree relatives of index cases, expanding addressable test volume through proband-identified pedigrees.
- Next-generation sequencing cost curves:Platform chemistry improvements and reagent competition are compressing per-sample sequencing costs, enabling broader gene panel deployment in community hospital settings previously restricted to academic centers.
Market Restraints
- Reimbursement fragmentation:Payer coverage policies for genetic cardiomyopathy testing vary substantially across United States commercial plans and Medicare administrative contractors, creating revenue uncertainty for laboratory service providers.
- Variant interpretation complexity:The American College of Medical Genetics and Genomics guidelines for variant classification require specialized molecular pathologist expertise that concentrates in fewer than two dozen North American and European reference laboratories.
- Long-read sequencing substitution:Pacific Biosciences and Oxford Nanopore platforms are displacing short-read methods for structural variant detection in arrhythmogenic cardiomyopathy cases, threatening installed base depreciation for Illumina-dominant facilities.
Strategic Opportunities
- Pharmacogenomic labeling expansion:Japan's PMDA is requiring cardiac drug labels to incorporate CYP2D6 and other pharmacogene information, creating demand for preemptive genotyping panels that include cardiomyopathy risk variants.
- Remote cardiac monitoring convergence:Integration of implantable loop recorders with genetic risk scores is enabling preemptive device therapy in genotype-positive, phenotype-negative patients across United States electrophysiology practices.
- Direct-to-consumer channel development:Telemedicine platforms specializing in cardiovascular genetics are establishing hybrid models combining at-home saliva collection with specialist video consultation, bypassing traditional referral bottlenecks in underserved United States regions.
Industry Challenges
- Cardiovascular genetic counselor scarcity:The National Society of Genetic Counselors reports fewer than 300 professionals with cardiac subspecialty training across all United States clinical settings, constraining informed consent throughput and results disclosure capacity.
- Laboratory information system integration:Electronic health record interoperability gaps between proprietary genetic testing portals and Epic or Cerner installations are forcing manual data entry and delaying critical results to treating cardiologists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Genetic Cardiomyopathies Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Kits, Genetic Testing Services, Biomarker Panels, Sequencing Platforms Diagnosis Approach: Next-Generation Sequencing, PCR-Based Testing, Microarray Analysis, Whole Exome Sequencing Application: Hypertrophic Screening, Dilated Assessment, Restrictive Evaluation, Arrhythmogenic Testing, Unclassified Analysis End User: Medical Genetics Laboratories, Specialty Clinics, Academic Research Centers, Referral Laboratories, Cardiology Institutes |
| Companies Covered | Novartis International AG, Merck & Co., Teva Pharmaceuticals Industries Ltd., Bristol Myers Squibb Company, Mylan N.V., Boston Scientific Corporation, Sanofi S.A., Roche Holding AG, AstraZeneca PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Genetic Cardiomyopathies Market Shifts & Advancements
Cardiovascular genetics is undergoing platform migration toward distributed testing architectures and regulatory frameworks are recalibrating evidence standards for artificial intelligence-assisted variant classification.
Portable sequencing instruments are decentralizing diagnostic capacity from centralized reference laboratories to point-of-care settings in cardiology clinics and catheterization laboratories. Academic medical centers in Germany and the United States are deploying Oxford Nanopore MinION devices for same-day sarcomeric gene analysis in critically ill pediatric cardiomyopathy cases. This capability compression is collapsing the traditional send-out model and enabling real-time peri-procedural decision-making.
The FDA's evolving framework for software as a medical device is reshaping how variant interpretation algorithms achieve regulatory clearance for clinical use. Machine learning tools trained on ClinVar and internal variant databases must now demonstrate analytical validity across specified cardiac gene panels rather than receiving blanket authorization. Diagnostic kit manufacturers are responding by embedding locked algorithm versions with fixed training sets to satisfy premarket submission requirements.
Subscription-based laboratory partnerships are displacing transactional test ordering in United States integrated delivery networks. Health systems in California, Texas, and Florida are contracting multi-year exclusive arrangements with national reference laboratories for cardiogenetics volume in exchange for capitated per-member-per-month fees. This procurement consolidation concentrates negotiating leverage with payers and forces smaller regional laboratories into niche subspecialty positioning or exit.
Genetic Cardiomyopathies Market Segmentation
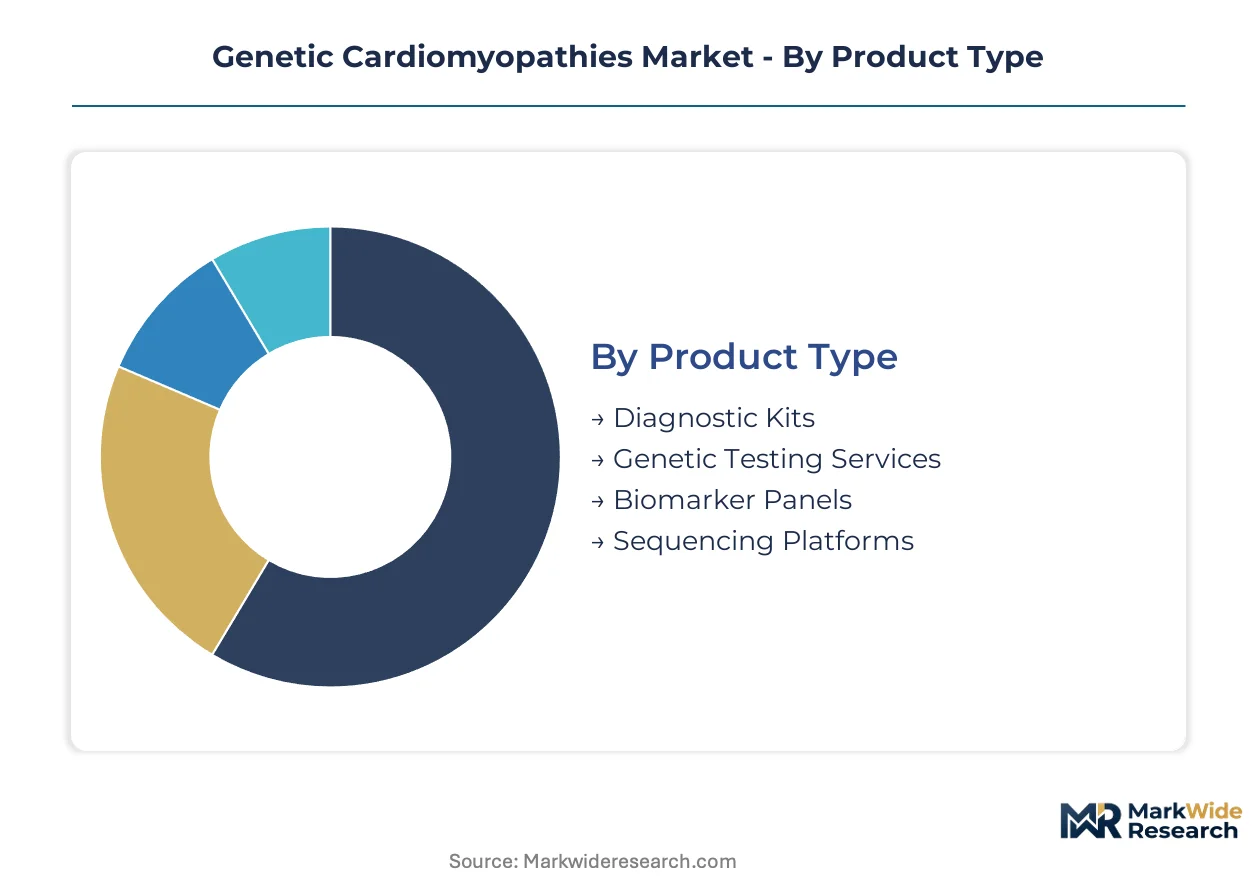
Genetic cardiomyopathies require precise stratification across testing modalities and clinical settings. Each segment reflects distinct technical capabilities, reimbursement pathways, and integration challenges within cardiology workflows.
Product Type:
Replacement cycles for genetic testing infrastructure are shortening as platform chemistry advances and regulatory evidence requirements intensify.
- Diagnostic Kits:Preconfigured reagent sets with validated gene panels for sarcomeric and desmosomal analysis. United States reference laboratories prioritize turnkey workflows to minimize assay development burden and accelerate FDA premarket submission timelines.
- Genetic Testing Services:Comprehensive laboratory processing encompassing sample accessioning, sequencing, variant interpretation, and clinical reporting. Germany's cardiogenetics programs concentrate demand here as cascade family screening protocols expand proband-identified pedigree testing.
- Biomarker Panels:Multiplex protein and nucleic acid assays for phenotype-genotype correlation. Japan's PMDA pharmacogenomic labeling requirements are preemptively driving panel adoption.
- Sequencing Platforms:Capital equipment for in-house next-generation sequencing deployment. Academic medical centers in the United States and Germany dominate placements as community hospitals defer to send-out models.
Diagnostic kits sit at the top of the volume ranking, with genetic testing services climbing the fastest as subscription-based partnerships consolidate procurement.
Diagnosis Approach:
Cost tier differentiation separates high-throughput screening methods from boutique comprehensive analyses.
- Next-Generation Sequencing:Massively parallel short-read analysis of targeted gene panels. Community hospital laboratories in Texas and Florida are adopting NGS as per-sample reagent costs compress below legacy Sanger sequencing thresholds.
- PCR-Based Testing:Rapid amplification for single-gene or hotspot variant detection. Point-of-care cardiology clinics deploy PCR for same-day peri-procedural decisions in critically ill pediatric cases.
- Microarray Analysis:Comparative genomic hybridization for copy number variant detection. Academic research centers utilize microarrays for genotype-phenotype correlation studies in unclassified cardiomyopathy cohorts.
- Whole Exome Sequencing:Comprehensive protein-coding region analysis for complex phenotype cases. United States electrophysiology practices are expanding WES utilization for arrhythmogenic cardiomyopathy with atypical presentation.
Next-generation sequencing dominates current volume, while whole exome sequencing exhibits the steepest expansion trajectory among complex phenotype indications.
Application:
Application segmentation maps directly to cardiomyopathy subtype prevalence and sudden cardiac death risk stratification urgency.
- Hypertrophic Screening:Sarcomeric gene analysis for MYH7, MYBPC3, and TNNT2 variants. Academic research centers in Germany concentrate demand as genotype-phenotype correlation studies advance therapeutic targeting.
- Dilated Assessment:TTN truncating variant and lamin A/C mutation detection. United States integrated delivery networks prioritize dilated cardiomyopathy panels for familial cascade screening.
- Restrictive Evaluation:Transthyretin and desmin gene analysis. Specialty clinics in Japan focus here due to ATTR cardiac amyloidosis prevalence in aging populations.
- Arrhythmogenic Testing:Plakophilin-2 and desmoglein-2 variant detection. Long-read sequencing substitution is displacing short-read methods for structural variant resolution in this segment.
- Unclassified Analysis:Comprehensive gene panel deployment for phenotype-negative, genotype-suspected cases. Referral laboratories with specialized molecular pathologist expertise capture this margin pool.
Hypertrophic screening commands the largest test volume, with arrhythmogenic testing gaining share fastest as implantable device integration with genetic risk scores advances.
End User:
Customer type determines purchasing authority, with integrated delivery networks consolidating negotiating leverage against fragmented independent laboratories.
- Medical Genetics Laboratories:Hospital-affiliated facilities with CLIA certification and genetic counselor staffing. United States academic medical centers anchor this segment with comprehensive cardiogenetics program infrastructure.
- Specialty Clinics:Dedicated cardiovascular genetics practices with embedded electrophysiology. Germany's expanding cardiogenetics infrastructure concentrates demand here through systematic cascade screening protocols.
- Academic Research Centers:Institutions pursuing genotype-phenotype correlation and novel variant discovery. EMA MDR implementation is filtering which assay designs achieve commercial scale from academic spinouts.
- Referral Laboratories:National reference laboratories processing samples from non-affiliated healthcare systems. Subscription-based partnerships in California, Texas, and Florida are consolidating procurement toward exclusive multi-year arrangements.
- Cardiology Institutes:Hospital-based cardiac departments with point-of-care testing ambitions. Portable sequencing instrument deployment is decentralizing capacity to catheterization laboratories in this segment.
Medical genetics laboratories retain the highest throughput position, while specialty clinics are expanding most quickly as precision diagnostic workflows compress suspicion-to-decision intervals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's cascade family screening protocols generate test volume faster than Japan's pharmacogenomic labeling mandates, yet both markets concentrate demand in specialized cardiogenetics infrastructure. The United States anchors commercial scale through integrated delivery network consolidation, while regulatory frameworks across multiple geographies reshape product registration strategies.
United States
Integrated delivery networks in California, Texas, and Florida are contracting exclusive multi-year laboratory partnerships for cardiogenetics volume. The FDA oversees both in vitro diagnostic and gene therapy pathways, elevating evidence standards for analytical validity claims. Academic medical centers in Boston and the Research Triangle deploy portable sequencing instruments for same-day pediatric cardiomyopathy analysis.
Germany
Systematic cascade screening protocols extend testing to first-degree relatives of index cases, expanding proband-identified pedigree volume. The EMA's Medical Device Regulation accelerates consolidation among assay developers capable of generating robust clinical evidence. Cardiogenetics programs in Munich and Heidelberg concentrate infrastructure for genotype-phenotype correlation studies.
Japan
The PMDA requires cardiac drug labels to incorporate CYP2D6 and other pharmacogene information, creating demand for preemptive genotyping panels. Specialty clinics in Tokyo and Osaka focus on restrictive cardiomyopathy evaluation due to ATTR cardiac amyloidosis prevalence in aging populations. Regulatory distinctiveness shapes product registration strategies divergent from Western frameworks.
United Kingdom
Referral laboratories with specialized molecular pathologist expertise capture unclassified cardiomyopathy analysis margins. The NHS England commissioning framework determines coverage policies for cascade family screening relative to regulatory clearance timelines. London and Cambridge academic clusters anchor genotype-phenotype research programs with commercial spinout potential.
Switzerland
Swissmedic maintains alignment with EMA pathways while preserving distinct pharmacovigilance requirements for gene therapy oversight. Basel and Zurich host concentrated pharmaceutical R&D infrastructure supporting diagnostic-treatment integration. The country's precision medicine ecosystem attracts cardiovascular genetics platform developers seeking European anchor markets.
Genetic Cardiomyopathies Market Competitive Landscape
Top-tier vendors anchor sequencing platform placements and therapeutic-diagnostic integration, while mid-tier reference laboratories compete for subscription-based partnership contracts. The vendor base stratifies across three tiers: multinational pharmaceutical conglomerates with cardiovascular footprints, national reference laboratories with CLIA-certified genetic testing capacity, and emerging assay developers pursuing CE-marked kit approvals. Consolidation pressures intensify as EMA MDR implementation filters commercial scale toward evidence-rich developers. Dominant competitive moves include strategic partnerships between platform manufacturers and laboratory service providers, plus portfolio diversification into pharmacogenomic panel expansion.
Within the multinational pharmaceutical tier, Novartis International AG and Bristol Myers Squibb Company represent integrated diagnostic-treatment positioning, while Roche Holding AG exemplifies sequencing platform dominance across European referral networks. These three companies occupy positions reflecting distinct strategic archetypes: cardiovascular therapeutic anchoring, precision cardiology R&D intensity, and diagnostic infrastructure control.
| Leading Market Players |
|---|
| Novartis International AG |
| Merck & Co. |
| Teva Pharmaceuticals Industries Ltd. |
| Bristol Myers Squibb Company |
| Mylan N.V. |
| Boston Scientific Corporation |
| Sanofi S.A. |
| Roche Holding AG |
| AstraZeneca PLC |
| Others |
Supply & Pricing Matrix
Captive laboratory partnerships in United States integrated delivery networks anchor supply positioning while compressing price discovery across genetic cardiomyopathy testing tiers. This integration pattern concentrates negotiating leverage with payers and forces smaller regional laboratories into niche subspecialty positioning or exit, directly shaping margin distribution between turnkey diagnostic kits and comprehensive genetic testing services.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for CE-marked diagnostic kits as EMA MDR implementation filters commercial scale toward evidence-rich developers. Subscription-based contracting dominates the pricing structure, with capitated per-member-per-month fees differentiating by test volume scale and analytical validity certification tier. Cost compression in community hospital NGS adoption is intensifying because per-sample reagent curves have fallen below legacy Sanger thresholds. Academic medical centers exhibit the least price sensitivity due to bundled research funding, while independent cardiology clinics face acute margin pressure.
Supply Chain Analysis
Japan's PMDA pharmacogenomic labeling mandates are reshaping sourcing patterns for preemptive genotyping panels across Asia-Pacific distribution networks. Sequencing platform manufacturing concentrates in the United States, Germany, and Japan, with reagent production drawing from specialized chemical synthesis facilities in Switzerland and Singapore. Supply chain risk centers on single-source vulnerability for long-read sequencing instruments in arrhythmogenic cardiomyopathy applications. Distribution runs through national reference laboratories with CLIA certification rather than direct hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Genetic cardiomyopathies represent a geographic-arbitrage play between Germany's cascade screening infrastructure and Japan's pharmacogenomic labeling mandates, with regulatory compliance costs diverging substantially across these jurisdictions.
For Market Incumbents: Extend sequencing platform placement contracts into exclusive multi-year laboratory partnerships before EMA MDR implementation consolidates assay developer tiers. Defend against Pacific Biosciences and Oxford Nanopore substitution in arrhythmogenic testing by embedding algorithm-locked variant interpretation tools with fixed training sets. Capacity addition in United States academic medical centers for portable instrument deployment anchors peri-procedural decision-making workflows. For New Entrants and Emerging Players: Telemedicine platforms specializing in cardiovascular genetics offer the most penetrable channel for bypassing traditional referral bottlenecks in underserved United States regions. White-space targets include direct-to-consumer hybrid models combining at-home saliva collection with specialist video consultation, and pharmacogenomic panel expansion for Japan's CYP2D6 labeling requirements. A go-to-market angle through cardiogenetics program infrastructure in Texas and Florida integrated delivery networks accelerates volume capture. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier reference laboratories because EMA MDR implementation is filtering commercial scale toward evidence-rich developers with robust analytical validity data. Long-term viability over a multi-year horizon rests on consolidation of genetic testing services under subscription-based procurement. Acquisition targets with specialized molecular pathologist expertise and CLIA-certified cardiac gene panel capacity offer defensive positioning. The signal to watch is payer coverage policy evolution for cascade family screening relative to FDA premarket clearance timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EMA MDR compliance separates commercial-scale assay developers from academic spinouts in European markets. |
| Hospital System Partnership | Exclusive multi-year contracts with California and Texas integrated delivery networks concentrate cardiogenetics procurement volume. |
| Software Companion Development | FDA software-as-medical-device frameworks require locked algorithm versions with fixed training sets for variant interpretation clearance. |
| Reimbursement Strategy | Medicare administrative contractor coverage policies for cascade family screening determine laboratory service provider revenue stability. |
| Platform Integration | Oxford Nanopore MinION deployment in German and United States academic centers collapses send-out models for same-day pediatric analysis. |
Research Methodology
Bottom-up cardiogenetics testing volume modeling reconciled against top-down sequencing platform placement tracking forms the analytical core of this study. Primary interviews with genetic counselors, molecular pathologists, hospital procurement managers, and payer access specialists were combined with secondary validation from FDA premarket submissions, EMA MDR technical documentation, CMS Medicare coverage determinations, and GPO contract databases. Triangulation between demand-side utilization patterns and supply-side capacity expansion ensures statistical integrity across geographic clusters.
Input-output matrices map genetic testing service revenue against diagnostic kit and sequencing platform capital expenditure flows across the projection horizon. Segmentation dimensions modeled include product type, diagnosis approach, cardiomyopathy subtype application, and end-user facility category. CAGRs were derived from regression analysis of historical test volume expansion and platform placement trajectories. Forecast inputs incorporate cascade family screening protocol adoption rates and pharmacogenomic labeling mandate implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA gene therapy pathway evolution and payer coverage policy shifts for preemptive genotyping. Forecasts reflect documented assumptions regarding regulatory clearance timelines and laboratory consolidation patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Carotid Stenosis Market
Cardiovascular
Paroxysmal Supraventricular Tachycardia (PSVT) Market
Cardiovascular
Global Statin Market
Cardiovascular
Global Cardiac Rehabilitation Market
Cardiovascular
Myocardial Infarction Market
Cardiovascular
Heart Block Therapeutics Market
Cardiovascular
Angina Pectoris Treatment Market
Cardiovascular
Middle-East and Africa Ischemic Heart Disease Market
Cardiovascular
Ischemic Cerebral Stroke Prevention Therapeutics Market
Cardiovascular
Myocardial Infarction Therapeutics Market
Cardiovascular
Treatment-Resistant Hypertension Management Market
Cardiovascular
Asia-Pacific Acute Coronary Syndrome Market
Cardiovascular
Heart Blocks Treatment Market
Cardiovascular
Ventricular Tachycardia Market
Cardiovascular
Unstable Angina Therapeutics Market
Cardiovascular
High-Sensitivity Cardiac Biomarker Market