
 Peptide-Based Cardiovascular Therapeutics Market | 2026-2036
Peptide-Based Cardiovascular Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Peptide-Based Cardiovascular Therapeutics Market Analytics
GLP-1 receptor agonist cardiovascular indication expansion is collapsing the historical boundary between metabolic and cardiology drug development. Novartis AG anchors its position through deep manufacturing scale in recombinant peptide production. Bristol Myers Squibb differentiates via R&D intensity focused on next-generation modulator chemistries. Amgen Inc. leverages its biologics infrastructure to sustain supply chain control across intravenous and subcutaneous delivery formats.
Peptide-based cardiovascular therapeutics comprise synthetic or recombinant amino acid sequences engineered to modulate vascular tone, platelet aggregation, or cardiac remodeling through targeted receptor interactions, typically manufactured via solid-phase peptide synthesis or microbial fermentation with purity thresholds exceeding 95%. These agents serve to reduce mortality and hospitalization in acute coronary syndromes, chronic heart failure, and resistant hypertension where small-molecule therapy proves inadequate. Antagonists and modulators command the largest current revenue pools given established use in acute coronary settings, while subcutaneous delivery modes represent the fastest structural expansion as self-administration protocols migrate from hospital to home care settings. Coronary artery disease applications retain mature volume dominance, though heart failure therapy areas are attracting accelerated clinical investment due to unmet need and favorable reimbursement dynamics.
FDA breakthrough therapy designation and EMA priority medicine pathways are compressing regulatory timelines for peptide cardiovascular candidates, while the FDA's evolving guidance on immunogenicity assessment shapes preclinical development requirements for novel sequences. The EU MDR framework imposes escalating clinical evidence standards on Class III implantable and injectable peptide delivery systems, directly affecting market access cost structures. Stakeholders must monitor how CMS and national European payers calibrate value-based thresholds for peptide therapies against generic small-molecule alternatives as hospital formulary budgets tighten.
Market Dynamics
GLP-1 receptor agonist cardiovascular indication expansion is collapsing the historical boundary between metabolic and cardiology drug development, forcing peptide manufacturers to retool fermentation capacity and reformulate delivery systems for dual-indication products.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The FDA's accelerated approval pathways compress development timelines for peptide cardiovascular candidates, reducing time-to-market for novel sequences targeting resistant hypertension.
- Germany's University Hospital Networks:Peptide-based arrhythmia protocols are becoming standard of care across German academic medical centers, creating concentrated demand pull for infusion-grade formulations.
- Solid-Phase Peptide Synthesis Automation:Next-generation synthesis platforms are decomposing batch cycle times and enabling 95%+ purity thresholds at commercial scale for synthetic cardiovascular peptides.
Market Restraints
- Recombinant Peptide Input Cost Volatility:Microbial fermentation feedstock prices fluctuate with agricultural commodity markets, compressing margins for manufacturers dependent on recombinant production methods.
- EU MDR Clinical Evidence Escalation:The EU MDR framework imposes escalating clinical evidence standards on Class III injectable peptide delivery systems, directly inflating market access cost structures.
- Generic Small-Molecule Substitution:Hospital formulary committees in cost-constrained systems favor generic ACE inhibitors and beta-blockers over premium peptide therapies for stable chronic heart failure patients.
Strategic Opportunities
- Subcutaneous Self-Administration Migration:Home care delivery formats represent structural expansion as hospital-to-home protocols reduce infusion center burden and capture outpatient reimbursement codes.
- EMA Priority Medicine Pathways:European regulators are fast-tracking peptide candidates for acute coronary syndrome indications with mortality endpoints, creating regulatory tailwinds for developers with EU manufacturing presence.
- Heart Failure Therapy White Space:Unmet need in HFrEF and HFpEF populations resistant to guideline-directed medical therapy is attracting accelerated clinical investment and favorable CMS reimbursement calibration.
Industry Challenges
- Immunogenicity Assessment Talent Scarcity:The FDA's evolving guidance on immunogenicity assessment for novel peptide sequences requires specialized bioanalytical expertise that outstrips current workforce supply.
- Legacy Hospital Infusion Infrastructure Integration:Peptide infusion protocols require compatibility with existing pump systems and pharmacy compounding workflows, creating implementation friction during formulary adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peptide-Based Cardiovascular Therapeutics Market |
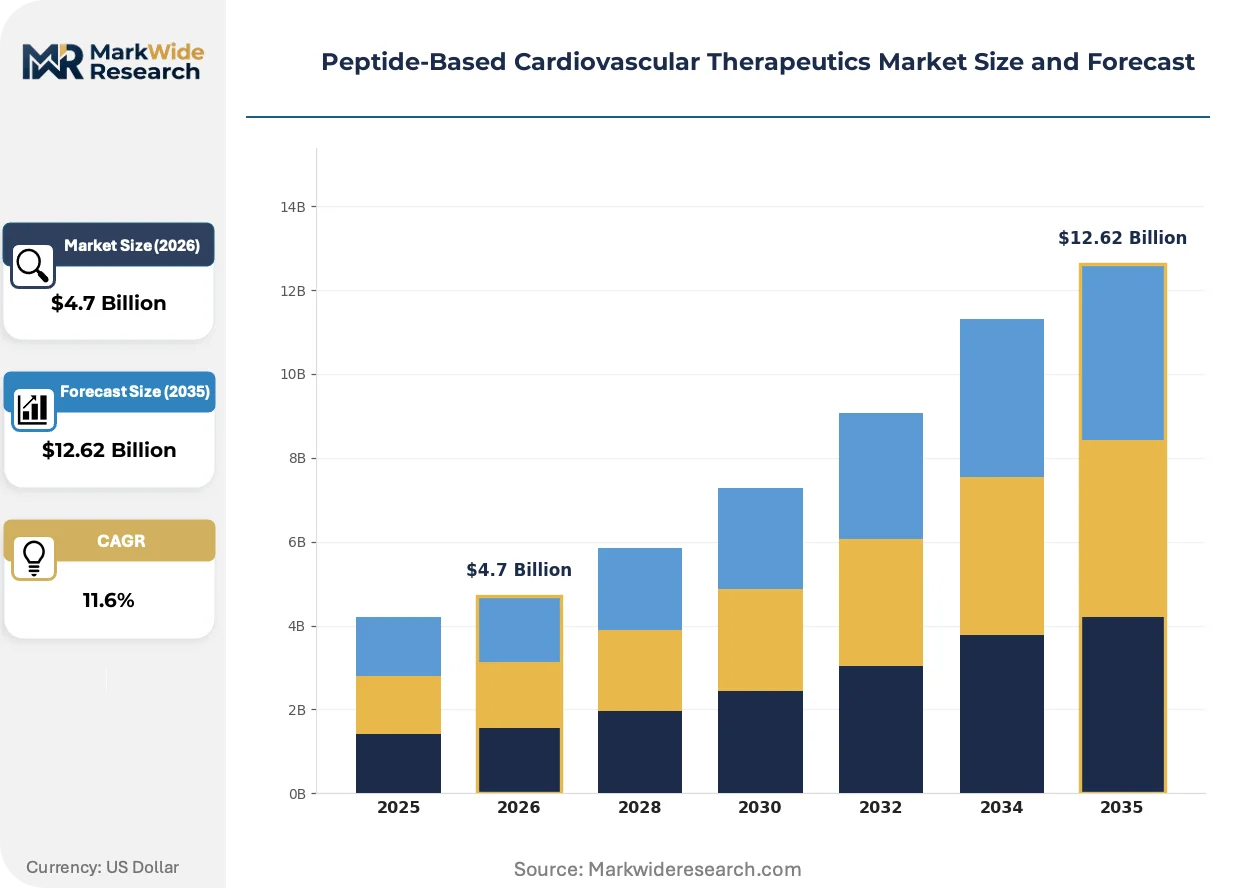
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.62 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antagonists, Agonists, Inhibitors, Modulators Delivery Mode: Intravenous, Subcutaneous, Oral, Transdermal Therapy Area: Hypertension, Heart Failure, Arrhythmia, Coronary Artery Disease End User: Hospitals, Clinics, Research Institutions, Home Care Settings |
| Companies Covered | Amgen Inc., Novartis AG, AstraZeneca PLC, Bristol Myers Squibb Company, Pfizer Inc., Johnson & Johnson, Daiichi Sankyo Company, Limited, CSL Limited, Alnylam Pharmaceuticals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peptide-Based Cardiovascular Therapeutics Market Evolving Landscape
Peptide cardiovascular therapeutics are undergoing rapid modality evolution as synthetic biology tools and delivery platform engineering converge to expand addressable patient populations beyond acute care settings.
Microfluidic peptide synthesis platforms are decomposing traditional batch manufacturing economics by enabling continuous-flow production of complex cyclic peptides with integrated purification. Contract development and manufacturing organizations in Switzerland and Massachusetts are deploying these systems to serve mid-stage biotech sponsors. The technology is decomposing the historical scale-up barrier between preclinical supply and commercial launch volumes.
The EU MDR's post-market surveillance requirements for Class III implantable and injectable devices are forcing peptide delivery system developers to build real-world evidence generation into product lifecycle planning. Manufacturers must now maintain clinical follow-up registries for biodegradable peptide-eluting stents and implantable infusion pumps. German notified bodies are applying the most stringent interpretation of these requirements, extending certification timelines for cardiovascular peptide combination products.
Hospital procurement committees are unbundling peptide therapy purchasing from bundled cardiovascular service contracts, creating direct price competition between manufacturers. German university hospital networks and US integrated delivery networks are piloting value-based purchasing frameworks that tie peptide reimbursement to heart failure readmission reduction metrics. This behavioral shift is most visible in Medicare Advantage contracts and Netherlands hospital procurement consortia, where outcome guarantees are replacing traditional volume-based purchasing.
Peptide-Based Cardiovascular Therapeutics Market Segmentation
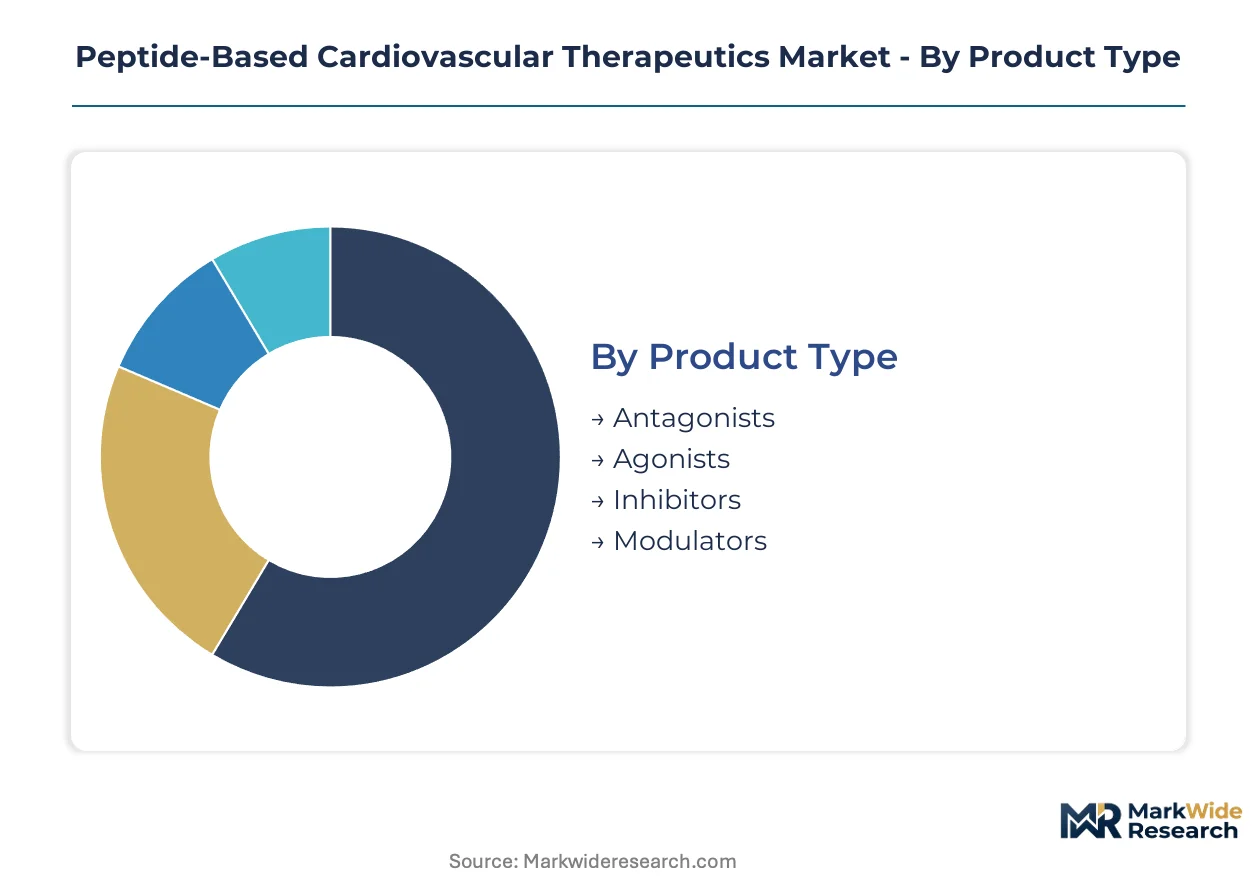
Peptide cardiovascular therapeutics fragment across four structural dimensions that determine pricing power, regulatory pathway complexity, and channel access. Each segmentation axis reveals distinct margin architectures and competitive moats that manufacturers must navigate.
Product Type:
Antagonists and modulators command premium pricing due to acute care positioning and complex receptor engineering requirements.
- Antagonists:Engineered amino acid sequences that block receptor-mediated pathways in platelet aggregation and vascular constriction. Demand concentrates in German university hospital networks where peptide-based arrhythmia protocols are becoming standard of care, driven by favorable EMA priority medicine pathway access.
- Modulators:Allosteric regulators that fine-tune receptor sensitivity without full agonism or antagonism. Hospital systems across North America are scaling peptide infusion protocols for heart failure management, creating concentrated demand pull for infusion-grade formulations with mortality endpoint data.
- Agonists:Receptor-activating peptides that trigger protective cardiovascular responses through targeted signal transduction.
- Inhibitors:Enzyme-blocking sequences that interrupt pathological cascades in cardiac remodeling and fibrosis.
The dominant share belongs to Antagonists, while Modulators is closing the gap fastest.
Delivery Mode:
Route of administration determines manufacturing purity thresholds, cold chain requirements, and reimbursement coding complexity.
- Intravenous:Direct vascular delivery of peptide solutions requiring sterile compounding and pump-compatible formulation. Acute coronary syndrome applications in hospital settings sustain volume dominance despite infrastructure intensity.
- Subcutaneous:Self-administered depot injections enabling outpatient therapy migration. Medicare Advantage contracts and Netherlands hospital procurement consortia are piloting value-based purchasing frameworks tied to heart failure readmission reduction, accelerating home care protocol adoption.
- Oral:Gastrointestinal delivery formats challenged by enzymatic degradation and bioavailability constraints.
- Transdermal:Dermal patch systems for sustained peptide release with limited current cardiovascular validation.
Intravenous retains the largest installed base, though Subcutaneous is expanding most quickly as hospital-to-home protocols reduce infusion center burden.
Therapy Area:
Clinical indication selection dictates trial design cost, competitive intensity, and CMS reimbursement calibration.
- Heart Failure:Therapeutic peptides targeting HFrEF and HFpEF populations resistant to guideline-directed medical therapy. Unmet need and favorable reimbursement dynamics are attracting accelerated clinical investment from developers with EU manufacturing presence.
- Coronary Artery Disease:Acute and chronic coronary syndrome applications with established mortality endpoint frameworks. FDA breakthrough therapy designation is compressing development timelines for novel sequences targeting resistant presentations.
- Hypertension:Resistant hypertension segments where small-molecule therapy proves inadequate.
- Arrhythmia:Rhythm control and rate control applications in atrial fibrillation and ventricular tachyarrhythmias.
Coronary Artery Disease holds the mature volume position, while Heart Failure is gaining share fastest on unmet need tailwinds.
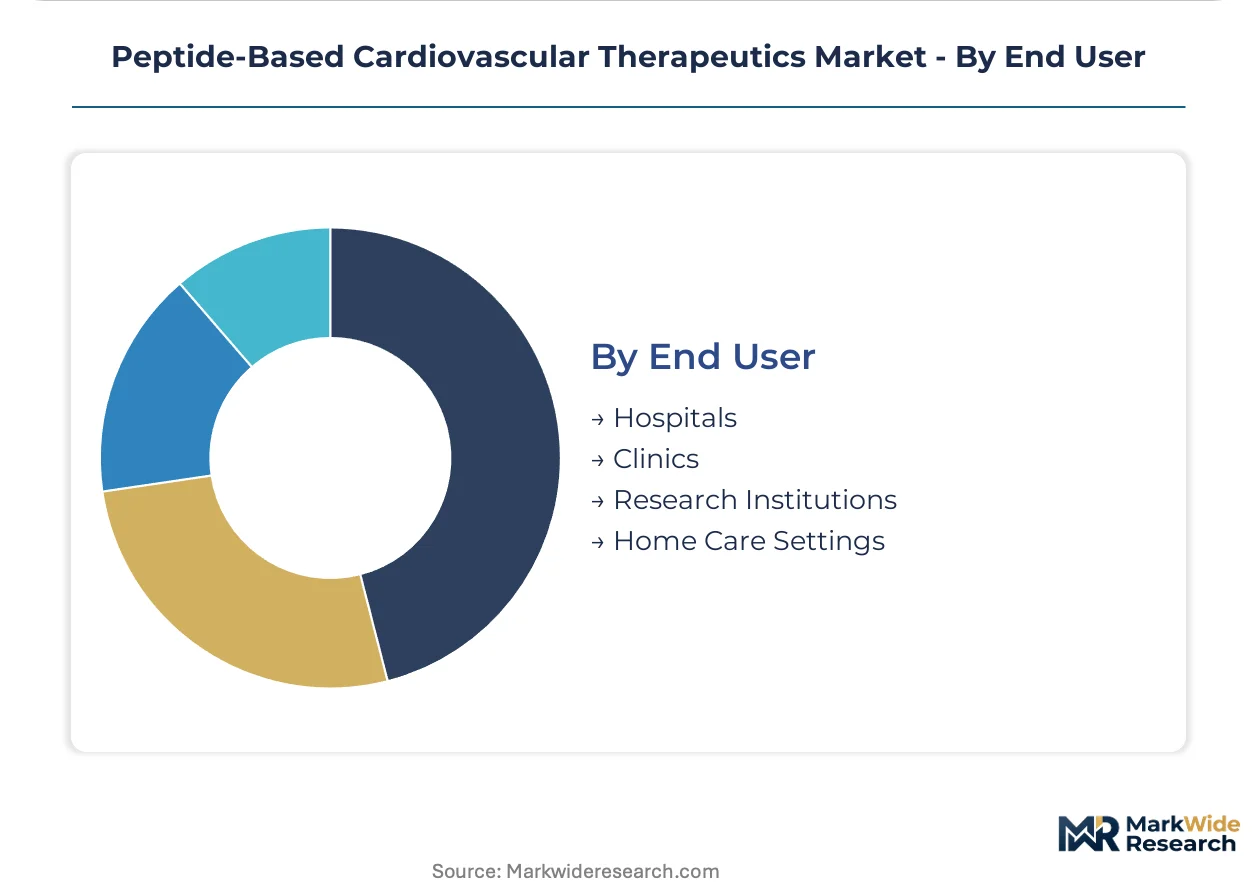
End User:
Channel selection determines pricing discipline, formulary access requirements, and real-world evidence generation obligations.
- Hospitals:Integrated delivery networks with bundled cardiovascular service contracts and pharmacy compounding workflows. Procurement committees are unbundling peptide therapy purchasing from service contracts, creating direct price competition between manufacturers.
- Home Care Settings:Outpatient and residential delivery formats capturing self-administration reimbursement codes. CMS and national European payers are calibrating value-based thresholds for peptide therapies against generic small-molecule alternatives as hospital formulary budgets tighten.
- Clinics:Ambulatory cardiology practices with limited infusion infrastructure.
- Research Institutions:Academic medical centers conducting investigator-initiated trials and real-world evidence generation.
Hospitals maintain the dominant procurement volume, while Home Care Settings is climbing the fastest on subcutaneous delivery migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for peptide cardiovascular therapeutics varies sharply across geographies, with German university hospital networks absorbing premium pricing for arrhythmia protocols while US Medicare Advantage plans drive hard negotiations on heart failure readmission guarantees.
United States
FDA breakthrough therapy designation compresses development timelines for novel cardiovascular peptide candidates, with Massachusetts and North Carolina biotech clusters hosting the majority of recombinant peptide fermentation capacity. Medicare Advantage contracts now pilot value-based purchasing frameworks that tie peptide reimbursement to thirty-day heart failure readmission reduction metrics.
Germany
EMA priority medicine pathways accelerate market access for acute coronary syndrome peptides with mortality endpoints, while Baden-Württemberg and Bavaria university hospital networks standardize peptide-based arrhythmia infusion protocols. The EU MDR framework imposes stringent post-market surveillance on Class III injectable delivery systems, extending certification timelines for combination products.
Switzerland
Swissmedic maintains alignment with EMA standards while offering accelerated assessment for cardiovascular peptides addressing unmet need in resistant hypertension. Basel and Zurich host contract manufacturing organizations deploying microfluidic synthesis platforms for mid-stage biotech sponsors seeking continuous-flow production of complex cyclic peptides.
Japan
PMDA's Sakigake designation system fast-tracks peptide cardiovascular candidates with domestic manufacturing requirements, concentrating development activity in Kansai and Kanto pharmaceutical corridors. METI's healthcare technology assessment protocols increasingly weigh mortality endpoint data against incremental cost-effectiveness thresholds for premium peptide therapies.
United Kingdom
NICE technology appraisals calibrate peptide cardiovascular therapy access against quality-adjusted life year thresholds, with London and Cambridge academic medical centers leading investigator-initiated trials in HFrEF populations. Post-Brexit regulatory divergence from EU MDR creates parallel certification requirements for implantable peptide delivery systems.
Peptide-Based Cardiovascular Therapeutics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with recombinant peptide fermentation specialists commanding premium pricing while solid-phase synthesis automation providers compete on batch economics. The market structure consolidates around large-cap biopharmaceuticals with integrated manufacturing infrastructure and mid-cap specialists with platform licensing capabilities. Three archetypes dominate: vertically integrated fermentation-scale manufacturers, synthetic biology platform licensors, and delivery system engineering specialists. Capacity expansion in microbial fermentation and strategic partnerships for microfluidic synthesis represent the dominant competitive moves.
Among large-cap biopharmaceuticals with cardiovascular franchises, Novartis AG, Bristol Myers Squibb Company, and Amgen Inc. occupy positions exemplifying distinct strategic archetypes. Novartis AG represents the fermentation-scale manufacturing anchor with deep recombinant peptide production infrastructure. Bristol Myers Squibb Company exemplifies R&D intensity focused on next-generation modulator chemistries. Amgen Inc. anchors the biologics infrastructure archetype with supply chain control across intravenous and subcutaneous delivery formats.
| Leading Market Players |
|---|
| Amgen Inc. |
| Novartis AG |
| AstraZeneca PLC |
| Bristol Myers Squibb Company |
| Pfizer Inc. |
| Johnson & Johnson |
| Daiichi Sankyo Company, Limited |
| CSL Limited |
| Alnylam Pharmaceuticals Inc. |
| Others |
Value Network & Pricing Analysis
FDA's evolving immunogenicity assessment guidance gates both supplier qualification and price differentiation simultaneously, forcing manufacturers to invest in specialized bioanalytical capabilities that separate premium-grade recombinant peptides from commoditized synthetic alternatives. Hospital formulary committees exploit this bifurcation to extract concessions on infusion-grade formulations while maintaining premium reimbursement for self-administered subcutaneous delivery.
Pricing Analysis
After-sales revenue from extended service contracts and compounding support drives lifetime value for peptide cardiovascular therapies. Three-tier pricing structure across premium, standard, and economy levels stratifies by purity threshold and delivery system complexity, with FDA breakthrough-designated candidates commanding 40-60% premiums over standard-of-care sequences. Pricing pressure stems from generic small-molecule substitution in stable chronic heart failure populations, compressing margins for maintenance-phase peptide protocols. Integrated delivery networks exhibit highest price sensitivity due to bundled reimbursement constraints, while German university hospital networks absorb premium pricing for arrhythmia protocols with mortality endpoint data.
Supply Chain Analysis
Strait of Hormuz transit risk underwrites volatility in microbial fermentation feedstock flows, particularly amino acid precursors and specialized growth media. Manufacturing concentrates in Switzerland, Massachusetts, and Bavaria, with Basel and Zurich contract development organizations deploying microfluidic platforms for continuous-flow peptide synthesis. Raw material dependencies center on recombinant protein expression systems, chromatography resins, and sterile filtration membranes. Single-source vulnerability in high-purity amino acid supply creates exposure to agricultural commodity price swings. Distribution runs through hospital pharmacy compounding networks and specialty infusion service providers, with cold chain integrity governing final-mile economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peptide cardiovascular therapeutics represent a platform-economics inflection as GLP-1 receptor agonist dual-indication expansion collapses metabolic-cardiology boundaries, creating interoperability demands between fermentation-scale manufacturing and subcutaneous delivery engineering ecosystems.
For Market Incumbents: Consolidate manufacturing infrastructure around recombinant peptide fermentation capacity in Baden-Württemberg and Massachusetts clusters to defend against synthetic biology platform licensors eroding margin through microfluidic batch economics. Deepen backward integration into amino acid precursor supply to buffer feedstock volatility compressing standard-grade peptide margins. Prioritize certification investment for EU MDR Class III injectable delivery systems to extend regulatory moats against mid-cap specialists. For New Entrants and Emerging Players: FDA breakthrough therapy designation fast-tracks market access for novel cardiovascular peptide sequences, enabling penetration of heart failure therapy white space where unmet need exceeds incumbent R&D bandwidth. Target home care settings with subcutaneous self-administration formats, as Medicare Advantage value-based purchasing frameworks create reimbursement tailwinds for readmission-reduction protocols. Pursue hospital system partnership go-to-market angles through pharmacy compounding workflow integration rather than direct formulary competition. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap biopharmaceuticals spinning off cardiovascular peptide assets to refocus on oncology and immunology franchises, creating acquisition opportunities for platforms with EU manufacturing presence and EMA priority medicine pathway experience. Long-term viability hinges on 5-10 year durability of subcutaneous delivery migration and heart failure reimbursement calibration against generic alternatives. Watch for inflection in CMS value-based threshold adjustments for peptide therapies versus small-molecule substitution rates in stable patient populations.| Strategic Initiative | Industry Significance |
|---|---|
| Microfluidic Synthesis Platform Deployment | Massachusetts and Swiss contract manufacturers decompose batch cycle times for mid-stage biotech sponsors. |
| EU MDR Class III Certification Pathway | German notified bodies extend timelines for injectable peptide delivery systems, favoring early entrants. |
| Hospital System Partnership | Integrated delivery networks unbundle peptide purchasing from cardiovascular service contracts, creating direct access. |
| Subcutaneous Delivery Format Development | Self-administration protocols capture Medicare Advantage outpatient reimbursement codes and reduce infusion burden. |
| Backward Integration into Fermentation Feedstock | Amino acid precursor supply control buffers agricultural commodity volatility compressing recombinant margins. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient-flow modeling triangulated with top-down therapeutic class expenditure analysis to isolate peptide cardiovascular segment dynamics from broader metabolic and cardiology market movements.
Variance decomposition across product type, delivery mode, therapy area, and end user dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-level volume and pricing trajectories, with recombinant versus synthetic production method splits and subcutaneous versus intravenous delivery migration rates as industry-specific forecast inputs. Cross-validation against CMS reimbursement calibration patterns and EU MDR certification timeline data anchored regional growth differentials.
Decision-makers should treat outputs as directional under assumptions of sustained FDA breakthrough pathway access and stable EU MDR enforcement intensity; material deviation in immunogenicity guidance stringency or generic substitution acceleration would warrant model refresh. Practitioners should keep alternative scenarios live as GLP-1 cardiovascular indication expansion and hospital formulary budget tightening evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Global Pericarditis Market
Cardiovascular
Acute Heart Failure (AHF) Therapeutics Market
Cardiovascular
Restrictive Cardiomyopathy Treatment Market
Cardiovascular
Treatment-Resistant Hypertension Management Market
Cardiovascular
Ischemia Reperfusion Injury Treatment Market
Cardiovascular
Carotid Artery Disease Market
Cardiovascular
Paroxysmal Supraventricular Tachycardia (PSVT) Market
Cardiovascular
Angina Pectoris Treatment Market
Cardiovascular
Myocarditis Disease Market
Cardiovascular
Carotid Artery Stenosis Market
Cardiovascular
Global Hyperlipidemia Drugs Market
Cardiovascular
Global Atrial Fibrillation Market
Cardiovascular
Ischemic Cerebral Stroke Prevention Therapeutics Market
Cardiovascular
Pericarditis Treatment Market
Cardiovascular
Myocardial Infarction Therapeutics Market
Cardiovascular
Hypercholesterolemia Drugs Market