
 Angina Market | 2026-2036
Angina Market Size, Share, and Industry Trends Forecast 2026-2036
Angina Market Analysis
Hospital-based acute care is rebalancing toward outpatient clinic management as healthcare systems prioritize cost containment and early intervention. Pfizer Inc. leverages its established cardiovascular portfolio to sustain formulary positions across integrated delivery networks. AstraZeneca PLC anchors its presence through R&D intensity in novel antiplatelet mechanisms. Novartis AG competes on manufacturing scale for generic nitrates and branded calcium channel blockers.
Angina constitutes chest pain or discomfort arising from myocardial ischemia due to insufficient oxygen supply relative to demand, typically measured by Canadian Cardiovascular Society grading and exercise tolerance thresholds. Its primary commercial purpose centers on symptom relief, event prevention, and quality-of-life maintenance across chronic coronary syndrome management. The stable angina segment dominates prescription volumes through long-acting nitrate and beta blocker maintenance therapy, while the microvascular angina category represents the fastest-growing addressable population as diagnostic angiography with coronary flow reserve testing expands. Antiplatelet agents command concentrated margin pools due to dual-therapy requirements post-acute coronary syndrome and patent-protected P2Y12 inhibitor options.
The FDA, EMA, and Japan's PMDA enforce divergent evidentiary standards for antianginal efficacy endpoints, with FDA requiring symptom-driven outcomes and PMDA emphasizing hard cardiovascular event reductions. These frameworks shape trial design costs, label indications, and ultimately market access timelines for new molecular entities. Stakeholders must monitor how evolving pharmacoeconomic thresholds in major markets redefine reimbursement for symptomatic versus prognostic therapy claims.
Market Dynamics
Healthcare systems in the United States, Germany, and Japan are redirecting angina treatment from inpatient coronary care units toward ambulatory clinics and community cardiology centers, compressing reimbursement for acute episodes while expanding coverage for preventive pharmacotherapy.
Growth Catalysts
- Japan's PMDA cardiovascular event reduction standards:Manufacturers designing trials around hard endpoints gain faster approval timelines for prognostic antianginal claims, differentiating from symptom-only competitors.
- Coronary flow reserve testing expansion:Cardiology practices in tertiary hospitals are adopting invasive microvascular assessment protocols, creating addressable patient pools previously classified as non-obstructive coronary artery disease.
- Integrated delivery network formulary consolidation:Hospital systems in the United States are centralizing cardiovascular drug procurement, favoring suppliers with broad portfolio breadth across antiplatelet, antihypertensive, and lipid-lowering categories.
Market Restraints
- Generic nitrate price compression:Manufacturing scale concentration in Indian API suppliers has collapsed margins for long-acting nitrate formulations, forcing branded competitors toward combination products.
- FDA symptom-driven endpoint requirements:The agency's insistence on exercise treadmill testing outcomes for antianginal efficacy creates trial design costs that disadvantage novel mechanism programs against established beta-blocker benchmarks.
- Statin-lipid therapy substitution:Aggressive LDL-lowering protocols are reducing recurrent ischemic event rates, shrinking the maintenance antianginal patient pool in populations with comprehensive cardiovascular risk management.
Strategic Opportunities
- German ambulatory cardiology center expansion:The country's 2023 healthcare regionalization reforms are licensing independent cardiac diagnostic facilities, creating new prescription channels outside hospital pharmacy control.
- EMA adaptive licensing frameworks:Conditional approval pathways for medicines addressing unmet need in refractory angina allow earlier revenue generation with post-marketing confirmatory study obligations.
- Digital therapeutics convergence with pharmacotherapy:Prescription digital health applications for cardiac rehabilitation are integrating with antianginal regimens, enabling outcome-based contracting models with payers.
Industry Challenges
- Coronary physiology specialist training gaps:Microvascular angina diagnosis requires interventional cardiologists with intracoronary Doppler wire expertise, a skill set concentrated in academic medical centers.
- Legacy EHR integration complexity:Ambulatory clinic adoption of new antianginal protocols faces workflow friction from electronic health record systems optimized for acute coronary syndrome documentation templates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Angina Market |
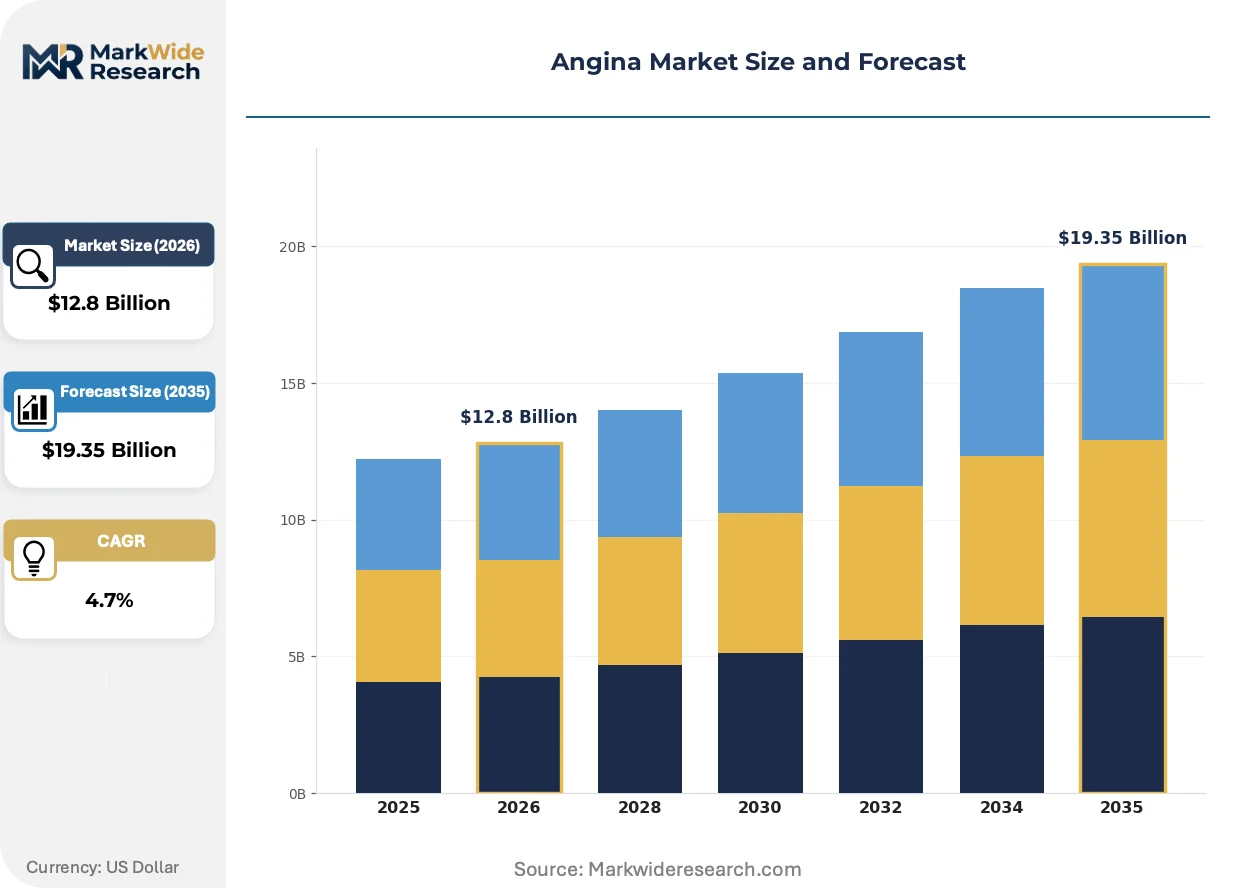
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.35 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Stable Angina, Unstable Angina, Microvascular Angina, Prince Metal Angina Drug Type: Nitrates, Beta Blockers, Calcium Channel Blockers, Antiplatelet Agents Care Setting: Hospital, Outpatient Clinic, Home Care, Emergency Department Delivery Mode: Oral, Injectable, Transdermal, Sublingual |
| Companies Covered | Merck & Co Inc., AstraZeneca PLC, Pfizer Inc., Gilead Sciences Inc., GlaxoSmithKline Plc, Bayer AG, Novartis AG, Amgen Inc., Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Angina Market Emerging Trajectories
Diagnostic technology and care delivery models are restructuring how angina is identified, classified, and treated across outpatient settings. These shifts are redrawing competitive boundaries between device manufacturers, pharmaceutical suppliers, and healthcare providers.
Coronary computed tomography angiography with fractional flow reserve derivation is decentralizing anatomical assessment from catheterization laboratories to community imaging centers. Cardiology groups in the United States are installing CT-FFR workstations in outpatient facilities, enabling same-day ischemia evaluation without invasive procedure scheduling. This capability is compressing the diagnostic pathway for stable chest pain patients and redirecting referral patterns toward sites with integrated imaging-pharmacy services.
The European Union's Medical Device Regulation (MDR) is elevating clinical evidence requirements for coronary diagnostic catheters and intracoronary pressure wires. Manufacturers must now submit prospective registry data for class III device renewals, extending certification timelines by eighteen to twenty-four months. Interventional cardiology device suppliers are responding by consolidating post-market surveillance infrastructure and withdrawing marginal product lines from the European market.
Patient cost-sharing obligations are reshaping pharmacy benefit design for chronic cardiovascular therapy. Employer-sponsored plans in the United States are tiering P2Y12 inhibitors based on therapeutic substitution protocols, steering stable angina patients toward generic clopidogrel unless acute coronary syndrome history triggers preferred branded access. This behavioral shift is visible in Medicare Part D claims data, where generic antiplatelet dispensing rates have climbed in non-post-ACS maintenance populations.
Angina Market Segmentation
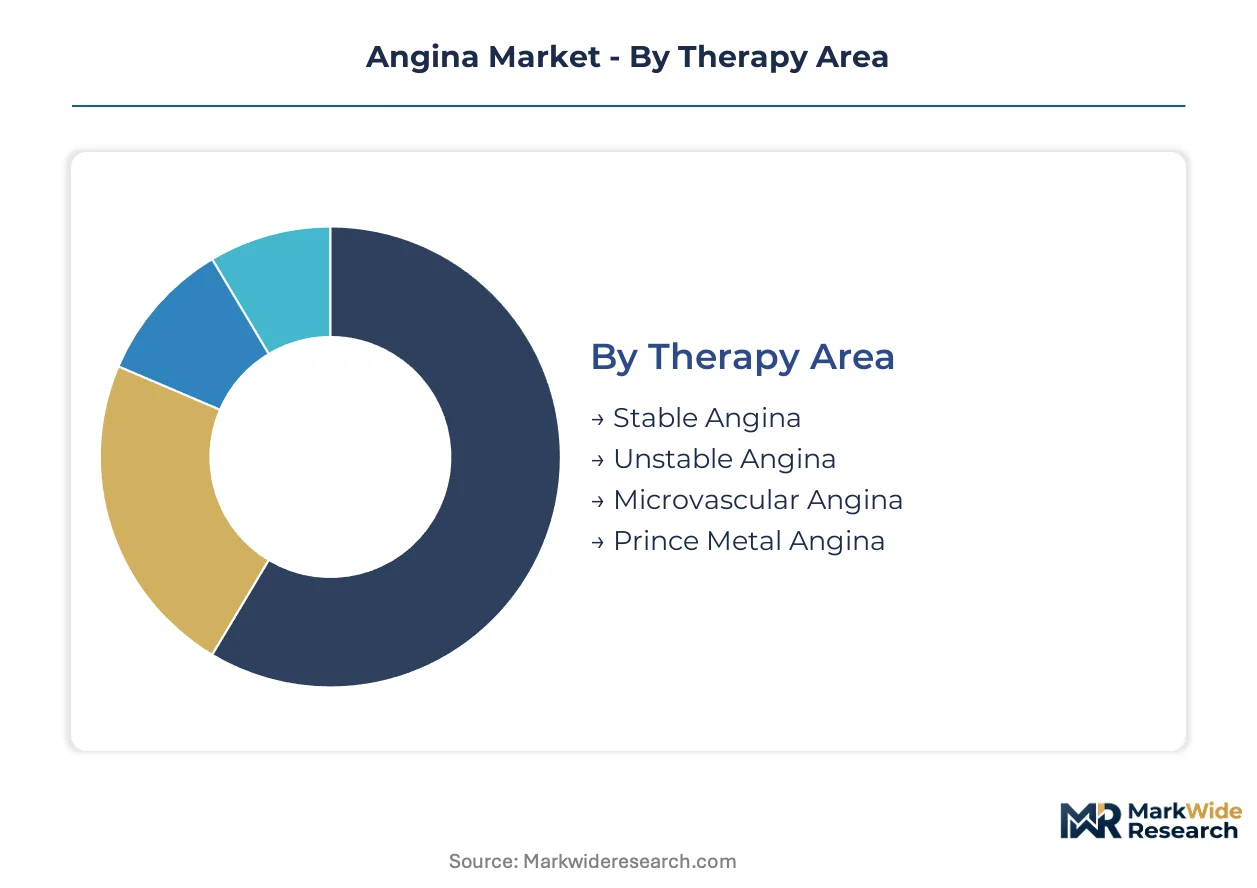
Angina market segmentation reveals how treatment protocols fragment across diagnostic categories, therapeutic mechanisms, and care delivery infrastructure. Manufacturers must align portfolio development with the specific efficacy endpoints and reimbursement pathways governing each segment.
Therapy Area:
Standardized diagnostic criteria dominate the high-volume stable angina segment, while microvascular angina demands customized diagnostic workflows with coronary flow reserve testing.
- Stable Angina:Chronic chest pain with predictable exertional triggers, managed through long-acting nitrate and beta-blocker maintenance regimens. Demand concentrates in United States ambulatory cardiology centers as integrated delivery networks expand preventive pharmacotherapy coverage.
- Microvascular Angina:Ischemic symptoms without obstructive coronary artery disease, diagnosed via invasive coronary flow reserve assessment. Tertiary hospitals in Germany and Japan are driving fastest adoption as angiography protocols incorporate microvascular dysfunction screening.
- Unstable Angina:Acute coronary syndrome presentation requiring immediate antiplatelet loading and revascularization evaluation.
- Prinzmetal's Angina:Vasospastic disorder with circadian symptom patterns, treated with calcium channel blockers and nitrates.
Leading the category by volume: Stable Angina. Expanding most quickly: Microvascular Angina.
Drug Type:
Margin concentration varies sharply across this category, with patent-protected antiplatelet agents capturing premium pricing against commoditized generic nitrates.
- Antiplatelet Agents:P2Y12 inhibitors and aspirin combinations preventing thrombotic events in acute and chronic coronary syndromes. Dual-therapy requirements post-ACS sustain concentrated margin pools in United States and Japanese markets with differentiated branded access tiers.
- Beta Blockers:First-line antianginal therapy reducing myocardial oxygen demand through heart rate and contractility suppression. German ambulatory cardiology centers prioritize cost-effective generic metoprolol and carvedilol in maintenance protocols.
- Nitrates:Vasodilator therapy for acute and prophylactic angina symptom relief, facing severe price compression from Indian API manufacturing scale.
- Calcium Channel Blockers:Alternative first-line or combination therapy, particularly for vasospastic and microvascular angina variants.
Highest margin capture: Antiplatelet Agents. Steepest price erosion: Nitrates.
Care Setting:
Reimbursement compression in acute settings is redirecting patient volumes toward lower-cost ambulatory alternatives with equivalent clinical outcomes.
- Outpatient Clinic:Community cardiology and diagnostic facilities managing stable angina diagnosis, risk stratification, and maintenance therapy. Germany's 2023 healthcare regionalization reforms are licensing independent cardiac diagnostic centers outside hospital pharmacy control.
- Hospital:Inpatient coronary care units handling acute coronary syndrome presentations, revascularization procedures, and high-risk unstable angina. United States integrated delivery networks are centralizing cardiovascular procurement across remaining acute episodes.
- Emergency Department:Initial triage and rule-out protocols for chest pain presentations.
- Home Care:Post-discharge medication adherence monitoring and cardiac rehabilitation support.
Volume leader: Hospital (acute episodes). Fastest structural shift: Outpatient Clinic.
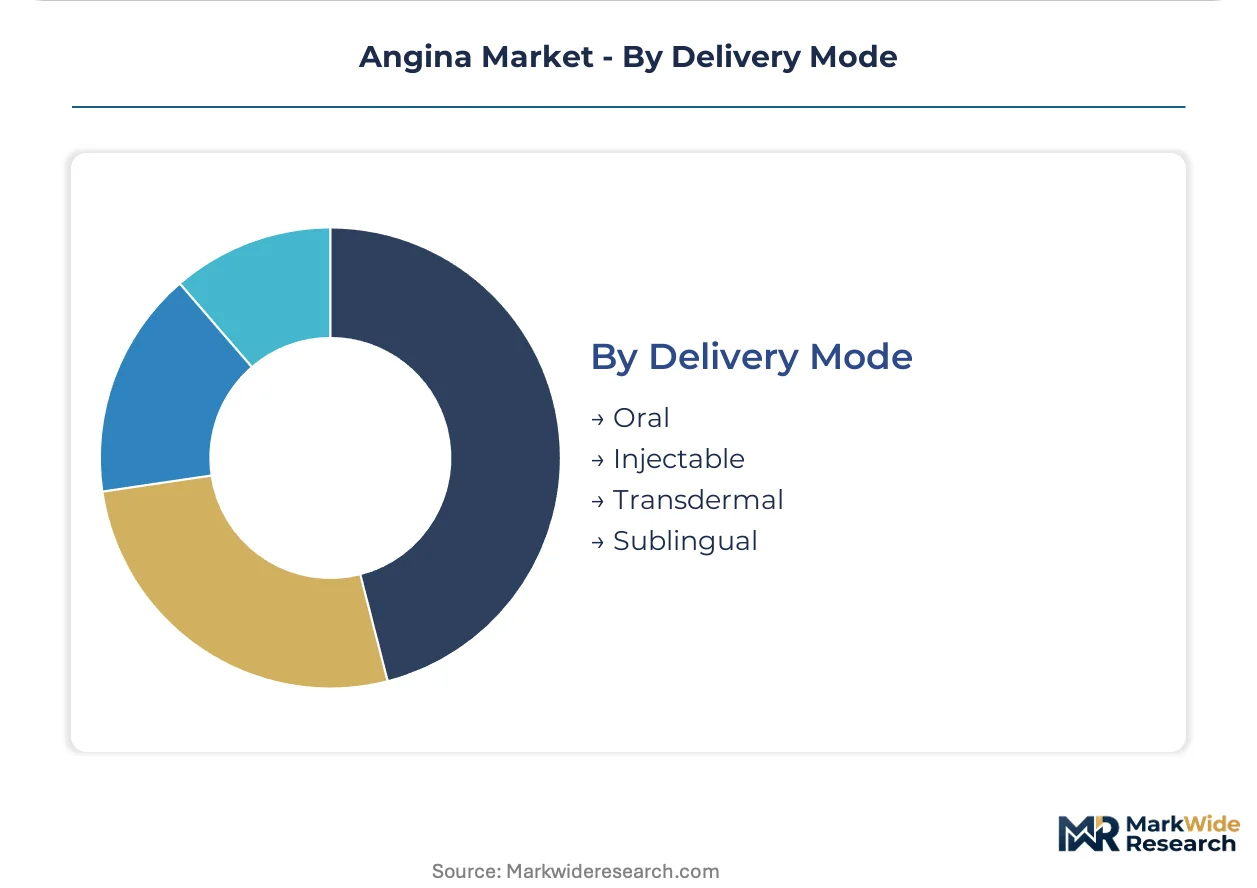
Delivery Mode:
Patient adherence profiles and onset speed requirements determine formulation selection across chronic maintenance versus acute rescue scenarios.
- Oral:Sustained-release tablets and capsules for chronic beta-blocker, nitrate, and antiplatelet maintenance therapy. United States pharmacy benefit designs tier oral P2Y12 inhibitors based on ACS history, steering stable angina patients toward generic clopidogrel.
- Sublingual:Rapid-onset nitroglycerin for acute angina rescue, with standardized patient education protocols across all care settings.
- Transdermal:Nitrate patches providing continuous prophylactic coverage with nitrate-free intervals to prevent tolerance.
- Injectable:Intravenous antiplatelet loading and anticoagulant co-therapy in acute coronary syndrome management.
Dominant by prescription volume: Oral. Narrowest clinical niche: Injectable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cardiovascular research zones in Massachusetts and North Carolina concentrate Phase III trial infrastructure, while Germany's medical technology clusters anchor European diagnostic device manufacturing for angina assessment.
United States
Integrated delivery networks in Texas and Florida drive ambulatory cardiology expansion as hospital systems consolidate procurement. The FDA's accelerated approval pathways compress development timelines for novel antianginal mechanisms. Boston's Longwood Medical Area hosts the highest density of interventional cardiology training programs, producing specialists in coronary flow reserve assessment.
Germany
Ambulatory cardiology centers in Bavaria and Baden-Württemberg absorb patient volumes shifting from acute hospital settings under 2023 regionalization reforms. EMA adaptive licensing frameworks enable conditional market entry for refractory angina therapies. The Heidelberg-Mannheim corridor concentrates catheter manufacturing for intracoronary diagnostic devices.
Japan
Aging demographics in Tokyo and Osaka sustain maintenance antianginal prescription volumes among the world's oldest patient populations. PMDA cardiovascular event reduction standards favor hard-endpoint trial designs over symptom-only claims. Yokohama's pharmaceutical manufacturing zone supplies generic nitrate API to domestic formulation facilities.
United Kingdom
NHS England's integrated care systems in London and Manchester redirect stable angina management toward community diagnostic hubs. NICE technology appraisals define cost-effectiveness thresholds for new antianginal entries. The Cambridge-Oxford arc concentrates early-stage cardiovascular biotechnology venture formation.
India
Hypertension and diabetes prevalence in Maharashtra and Karnataka expands the addressable angina patient pool among younger demographics than Western markets. CDSCO manufacturing facility inspections enforce quality standards for export-oriented generic nitrate production. Hyderabad's active pharmaceutical ingredient cluster supplies long-acting nitrate intermediates to European formulation sites.
Angina Market Vendor Landscape
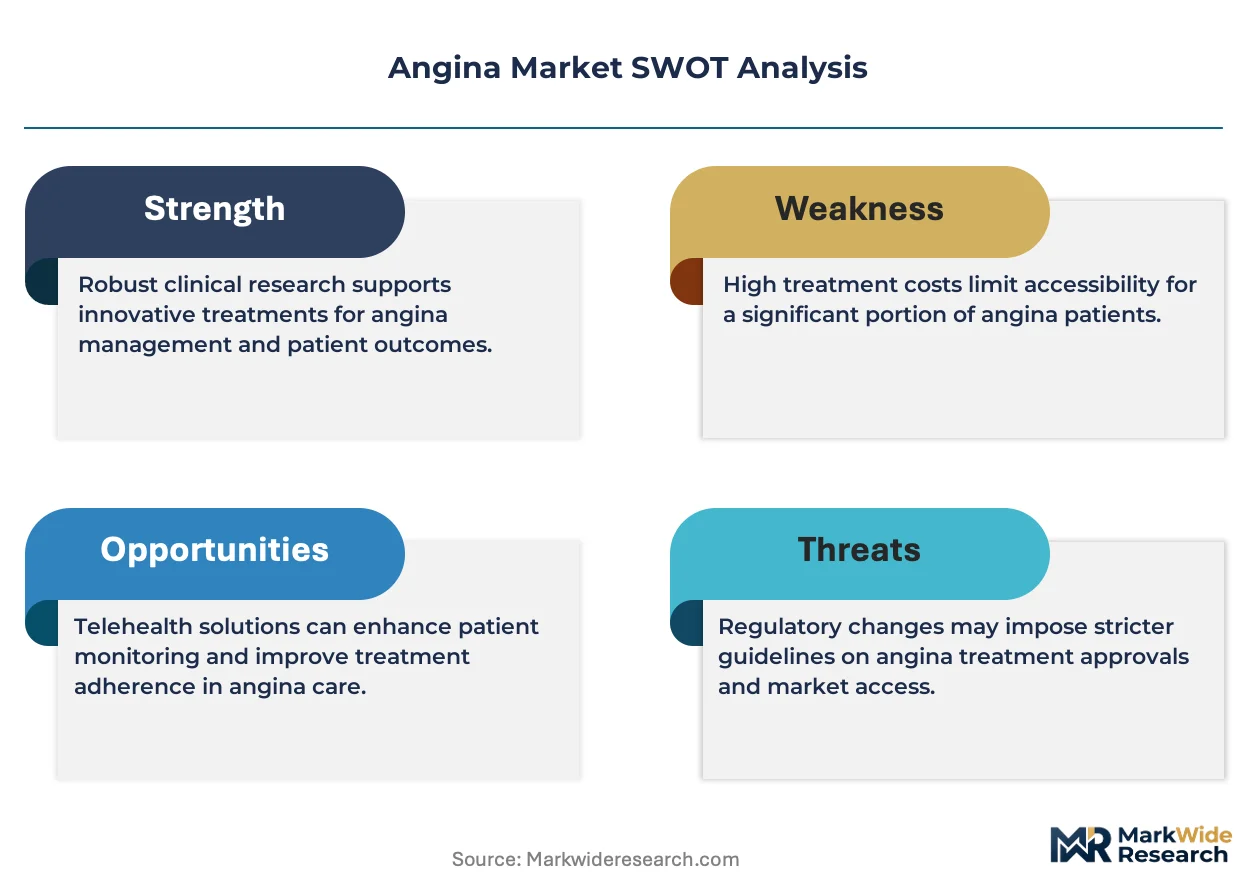
Branded specialists and contract manufacturers split share differently across segments, with patent-protected antiplatelet developers capturing concentrated margins against commoditized generic nitrate suppliers. The vendor base organizes into three tiers: multinational pharmaceutical conglomerates with cardiovascular portfolios, mid-cap regional generics manufacturers, and specialized diagnostic device producers. Consolidation pressures favor players with breadth across antiplatelet, antihypertensive, and lipid-lowering categories. Strategic moves center on formulary position defense through integrated delivery network contracting and diagnostic-pharmacy service bundling.
Among multinational pharmaceutical conglomerates, Pfizer Inc., AstraZeneca PLC, and Novartis AG occupy positions exemplifying distinct competitive archetypes. Pfizer leverages established cardiovascular portfolio relationships to sustain integrated delivery network formulary presence. AstraZeneca anchors through research intensity in novel antiplatelet mechanisms. Novartis competes on manufacturing scale for both generic nitrates and branded calcium channel blockers. Each represents a viable strategic posture: incumbent relationship monetization, innovation-driven differentiation, or operational scale exploitation.
| Leading Market Players |
|---|
| Merck & Co Inc. |
| AstraZeneca PLC |
| Pfizer Inc. |
| Gilead Sciences Inc. |
| GlaxoSmithKline Plc |
| Bayer AG |
| Novartis AG |
| Amgen Inc. |
| Johnson & Johnson |
| Others |
Supply Flow & Price Mechanics
EMA MDR clinical evidence requirements for coronary diagnostic catheters gate qualified supply for European device manufacturers while compressing premium-tier pricing access for intracoronary pressure wire systems. Indian API manufacturing scale for long-acting nitrate intermediates feeds downstream formulation cost structures across generic maintenance therapy markets.
Pricing Analysis
Short lead-time premiums attach to coronary flow reserve testing equipment as tertiary hospitals in Germany and Japan accelerate microvascular angina diagnostic protocol adoption. Three-tier pricing structure across premium, standard, and economy levels separates patent-protected P2Y12 inhibitors from branded calcium channel blockers and commoditized generic nitrates. Cost compression in the nitrate segment intensifies because Hyderabad API suppliers have consolidated manufacturing scale. Integrated delivery networks in the United States exhibit highest price sensitivity for maintenance antianginal therapy, while Japanese acute coronary syndrome populations show lowest sensitivity due to dual-therapy requirements.
Supply Chain Analysis
Domestic-content mandates in India's pharmaceutical sector are reshaping sourcing patterns for export-oriented generic nitrate production. Active pharmaceutical ingredient concentration rests on India, China, and domestic Japanese suppliers for cardiovascular therapy inputs. Raw material dependencies center on nitrate intermediates, calcium channel blocker precursors, and antiplatelet synthesis reagents. Single-source vulnerability concentrates in Indian API clusters supplying European formulation sites. Distribution runs through hospital pharmacy procurement in acute settings and ambulatory cardiology center dispensing for maintenance populations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The angina market is transitioning from symptom-driven pharmacotherapy toward coronary physiology-guided precision treatment, with coronary flow reserve testing displacing exercise treadmill protocols as the diagnostic anchor for microvascular angina identification.
For Market Incumbents: Hedge against generic nitrate margin collapse by accelerating combination product development and securing coronary diagnostic device bundling contracts with integrated delivery networks. Backward integration into Indian API supply chains mitigates raw material cost volatility for long-acting nitrate formulations. Investment in intracoronary Doppler wire training programs defends interventional cardiology device positions against CT-FFR workstation displacement. For New Entrants and Emerging Players: Launch via ambulatory cardiology center partnerships in Germany's newly licensed independent cardiac diagnostic facilities, bypassing entrenched hospital pharmacy procurement controls. Microvascular angina represents the most penetrable segment as diagnostic angiography protocols expand coronary flow reserve testing. Outcome-based contracting models with prescription digital health applications for cardiac rehabilitation integration offer differentiated go-to-market positioning. For Investors and Strategic Acquirers: FDA accelerated approval pathway utilization for novel antianginal mechanisms is the leading indicator that prognostic therapy claims will command premium reimbursement tiers over symptom-only competitors. Acquisition targets should concentrate on mid-cap diagnostic device manufacturers with CE marking pathway progress for intracoronary pressure wire systems. Watch PMDA cardiovascular event reduction standard adoption rates as the inflection signal for hard-endpoint trial design preference over symptom-driven benchmarks.| Strategic Initiative | Industry Significance |
|---|---|
| Coronary Flow Reserve Testing Expansion | Tertiary hospitals in Germany and Japan are adopting invasive microvascular assessment protocols, creating new addressable patient pools. |
| EMA Adaptive Licensing Framework Utilization | Conditional approval pathways enable earlier revenue generation for refractory angina therapies with post-marketing confirmatory obligations. |
| Integrated Delivery Network Formulary Consolidation | Hospital systems in the United States are centralizing cardiovascular drug procurement across antiplatelet, antihypertensive, and lipid-lowering categories. |
| Digital Therapeutics Convergence | Prescription digital health applications for cardiac rehabilitation integrate with antianginal regimens, enabling outcome-based payer contracting. |
| Diagnostic-Pharmacy Service Bundling | Cardiology groups installing CT-FFR workstations redirect referral patterns toward sites with integrated imaging-pharmacy capabilities. |
Methodological Framework
Document review covered FDA filings, EMA submissions, ClinicalTrials.gov registry data, and formulary databases, complemented by interviews with drug development executives, regulatory affairs leads, formulary directors at integrated delivery networks, and hospital procurement managers. Secondary validation drew from CMS Medicare claims data, Japanese PMDA approval documentation, and German healthcare regionalization policy records. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored market size estimation across therapy segments and regional clusters.
Market value outputs combined epidemiological prevalence projections with treatment rate assumptions and pricing tier allocations across the analysis window. Segmentation dimensions modeled include angina subtype classification, therapeutic mechanism of action, care setting infrastructure, and regional regulatory pathway clustering. CAGRs were derived from fitted growth curves incorporating demographic aging trajectories, diagnostic technology diffusion rates, and reimbursement policy evolution inputs specific to cardiovascular therapy markets.
The model assumes a particular technology adoption path for coronary flow reserve testing; alternative pathways emphasizing CT-FFR workstation deployment would alter the diagnostic device outlook and downstream antianginal prescribing patterns. Forecasts reflect assumptions regarding PMDA cardiovascular event reduction standard maintenance, EMA adaptive licensing framework utilization rates, and integrated delivery network formulary consolidation velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Acute Heart Failure (AHF) Therapeutics Market
Cardiovascular
Pericarditis Treatment Market
Cardiovascular
Coronary Artery Disease Therapeutics Market
Cardiovascular
Carotid Stenosis Market
Cardiovascular
Global Cardiac Rehabilitation Market
Cardiovascular
Cardiac Arrhythmia Therapeutics Market
Cardiovascular
Eisenmenger Syndrome Treatment Market
Cardiovascular
Cardiovascular Pledgets Market
Cardiovascular
Stable Angina Management Market
Cardiovascular
Cardiac Biomarkers Market
Cardiovascular
United States Cardiometabolic Fixed-Dose Combinations Market
Cardiovascular
Myocardial Infarction Therapeutics Market
Cardiovascular
Myocardial Ischemia Market
Cardiovascular
Peripheral Artery Disease Market
Cardiovascular
Ischemia Reperfusion Injury Therapeutics Market
Cardiovascular
Angina Pectoris Treatment Market