
 Atherosclerosis Therapeutics Market | 2026-2036
Atherosclerosis Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Atherosclerosis Therapeutics Market Analysis
Next-generation biologic efficacy standards are redrawing competitive boundaries in atherosclerosis care. Amgen Inc. leverages its PCSK9 inhibitor manufacturing scale to anchor the high-efficacy segment. Novartis AG differentiates through sustained R&D intensity in lipid-lowering innovation. Pfizer Inc. competes on oral statin brand strength and extensive hospital formulary placement across North America and Europe.
Atherosclerosis therapeutics comprise pharmacological agents targeting arterial plaque formation, lipid metabolism modulation, and thrombotic risk reduction, with functional parameters including LDL-C lowering magnitude and cardiovascular event rate suppression. These therapies serve the primary industrial purpose of reducing myocardial infarction, stroke, and peripheral artery disease incidence in at-risk populations. The statin category occupies the mature volume base, while PCSK9 inhibitors represent the fastest-growing margin pool due to superior LDL-C reduction in familial hypercholesterolemia and statin-intolerant patients. Injectable delivery modes command premium positioning against oral formulations, particularly in secondary prevention settings where compliance monitoring drives provider preference.
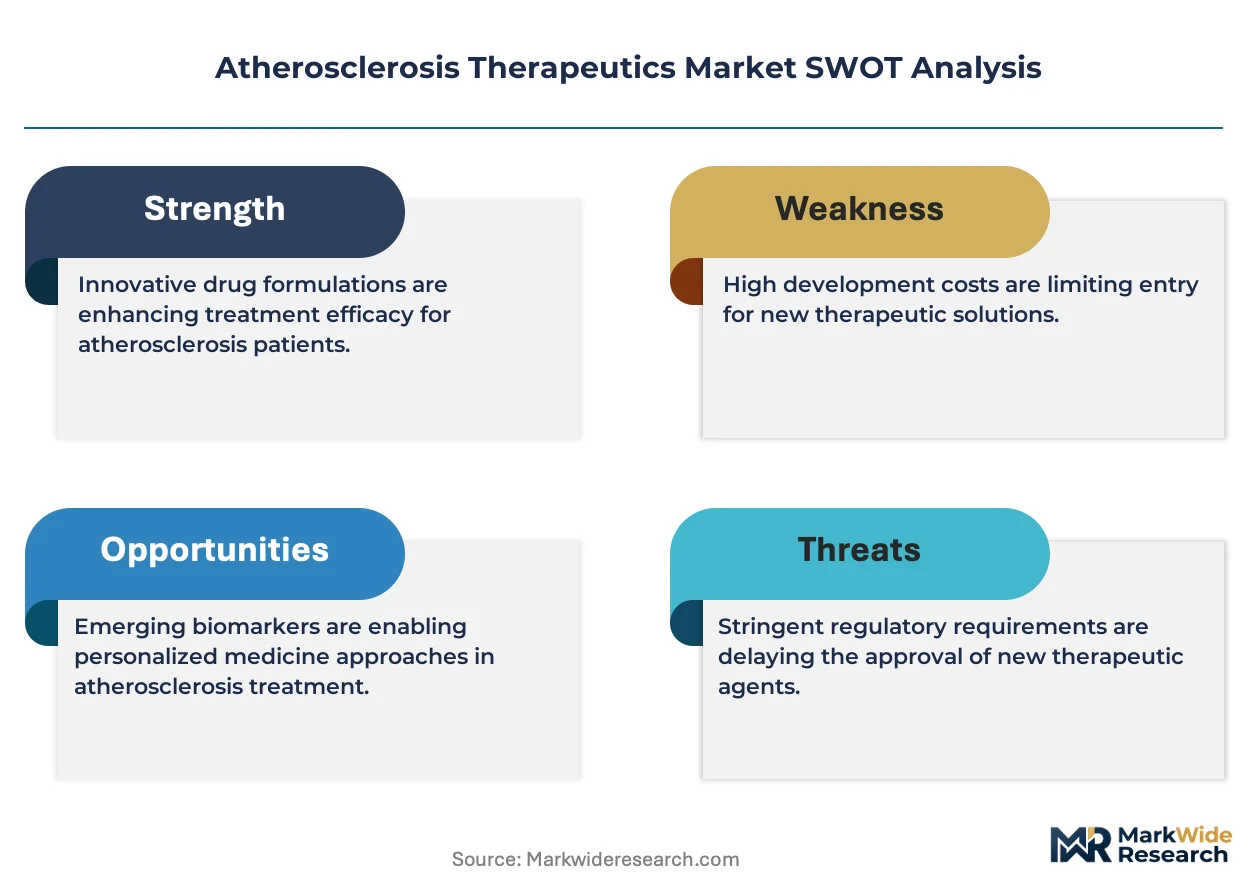
The FDA, EMA, and WHO cardiovascular guidelines collectively shape demand by establishing LDL-C target thresholds that determine reimbursement eligibility and prescribing protocols. FDA accelerated approval pathways and EMA conditional marketing authorizations compress development timelines for novel mechanisms, while WHO essential medicines lists influence procurement patterns in emerging health systems. Stakeholders must monitor evolving payer evidence requirements for cardiovascular outcome trials as gatekeeping mechanisms tighten around premium-priced biologic therapies.
Market Dynamics
PCSK9 inhibitor manufacturing scale is concentrating competitive advantage among biologics producers, while oral statin commoditization squeezes margin pools across mature cardiovascular portfolios.
Growth Catalysts
- FDA accelerated approval pathways:Compressed cardiovascular outcome trial timelines enable faster market entry for novel LDL-C lowering mechanisms. Developers gain competitive velocity against entrenched statin portfolios.
- Familial hypercholesterolemia patient identification:Cascade screening programs in tertiary cardiovascular centers expand addressable populations for high-efficacy biologic therapy. Genetic testing integration drives prescriber awareness.
- Medicare preventive therapy reimbursement:Favorable coverage determinations for statin therapy in at-risk beneficiaries reduce out-of-pocket barriers. Primary care prescribing volumes respond to risk-based payment incentives.
Market Restraints
- Biologic cold chain infrastructure:Injectable PCSK9 inhibitors require continuous temperature-controlled distribution, limiting pharmacy dispensing flexibility. Rural and ambulatory settings face capacity constraints.
- Statin generic saturation:Atorvastatin and rosuvastatin commoditization has collapsed oral pricing power, deflating revenue per prescription across primary prevention segments.
- Cardiovascular outcome trial burden:FDA and EMA evidence requirements for novel mechanisms demand multi-year, high-enrollment studies that compress development economics.
Strategic Opportunities
- Statin-intolerant patient protocols:Biologic alternatives capture non-adherent populations failing oral therapy due to myalgia side effects. Specialty pharmacy networks enable targeted patient support.
- Oral PCSK9 small molecules:Non-injectable delivery formats under development eliminate cold chain dependency and expand retail pharmacy access. Patient preference data favors oral administration.
- Secondary prevention compliance monitoring:Digital health integration with injectable regimens creates adherence data streams that justify premium reimbursement to payers.
Industry Challenges
- Biostatistics talent scarcity:Cardiovascular outcome trial design requires specialized expertise in adaptive trial methodologies and regulatory biostatistics. Competition for experienced personnel intensifies across CROs and sponsors.
- Legacy EHR integration:Automated LDL-C risk scoring and therapy recommendation engines face interoperability barriers with hospital system record architectures. Implementation timelines extend deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atherosclerosis Therapeutics Market |
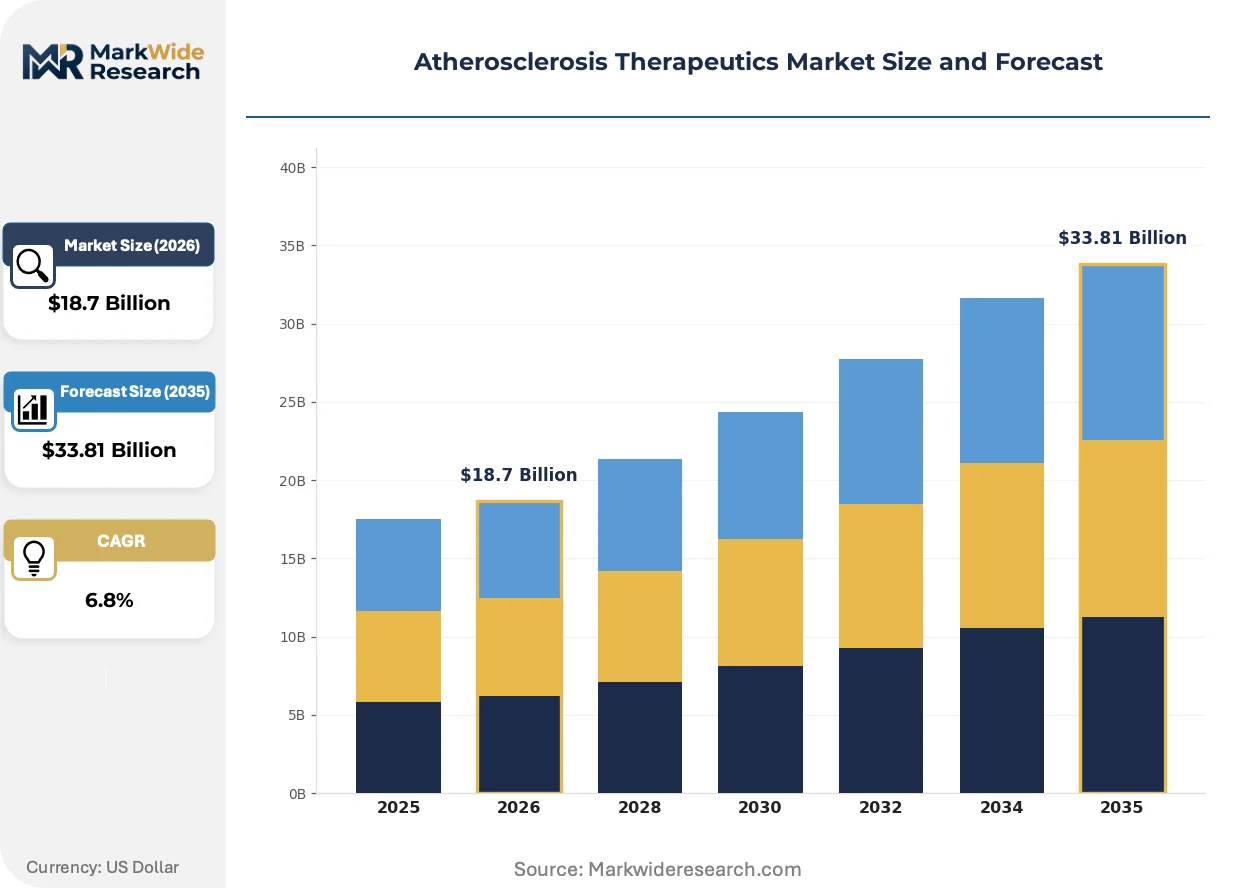
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Statins, PCSK9 Inhibitors, Antiplatelet Agents, Omega-3 Fatty Acids Therapy Area: Primary Prevention, Secondary Prevention, Acute Management, Chronic Treatment End User: Hospitals, Clinics, Homecare Settings, Rehabilitation Centers Delivery Mode: Oral, Injectable, Transdermal, Intravenous |
| Companies Covered | Amgen Inc., Novartis AG, Pfizer Inc., Sanofi, AstraZeneca, Merck & Co., Inc., GlaxoSmithKline, Bayer AG, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atherosclerosis Therapeutics Market Emerging Trajectories
Next-generation lipid-lowering modalities are fragmenting the historical statin monopoly, with delivery format innovation and real-world evidence generation emerging as decisive competitive differentiators.
Oral PCSK9 small molecule inhibitors are supplanting injectable monoclonal antibodies in development pipelines, eliminating cold chain burdens and enabling retail pharmacy dispensing. Cardiovascular specialists in United States academic medical centers are prioritizing these candidates for patient preference trials. The format shift is compressing biologics infrastructure advantages and reopening competitive positioning for traditional oral-focused manufacturers.
EMA conditional marketing authorizations for cardiovascular therapies are shortening time-to-reimbursement in European Union member states, contingent on post-approval outcome study completion. Developers gain earlier revenue streams but assume regulatory risk of indication withdrawal. High-efficacy biologic segments in Germany and France are responding with accelerated access agreements tied to performance guarantees.
Specialty pharmacy distribution is displacing traditional hospital outpatient dispensing for injectable atherosclerosis therapies, concentrating patient data capture and adherence monitoring with PBM-affiliated networks. United States Medicare Part D plans are steering volume toward preferred pharmacy arrangements with outcome measurement capabilities. The channel migration is most visible in secondary prevention populations requiring ongoing injection training support.
Atherosclerosis Therapeutics Market Segmentation
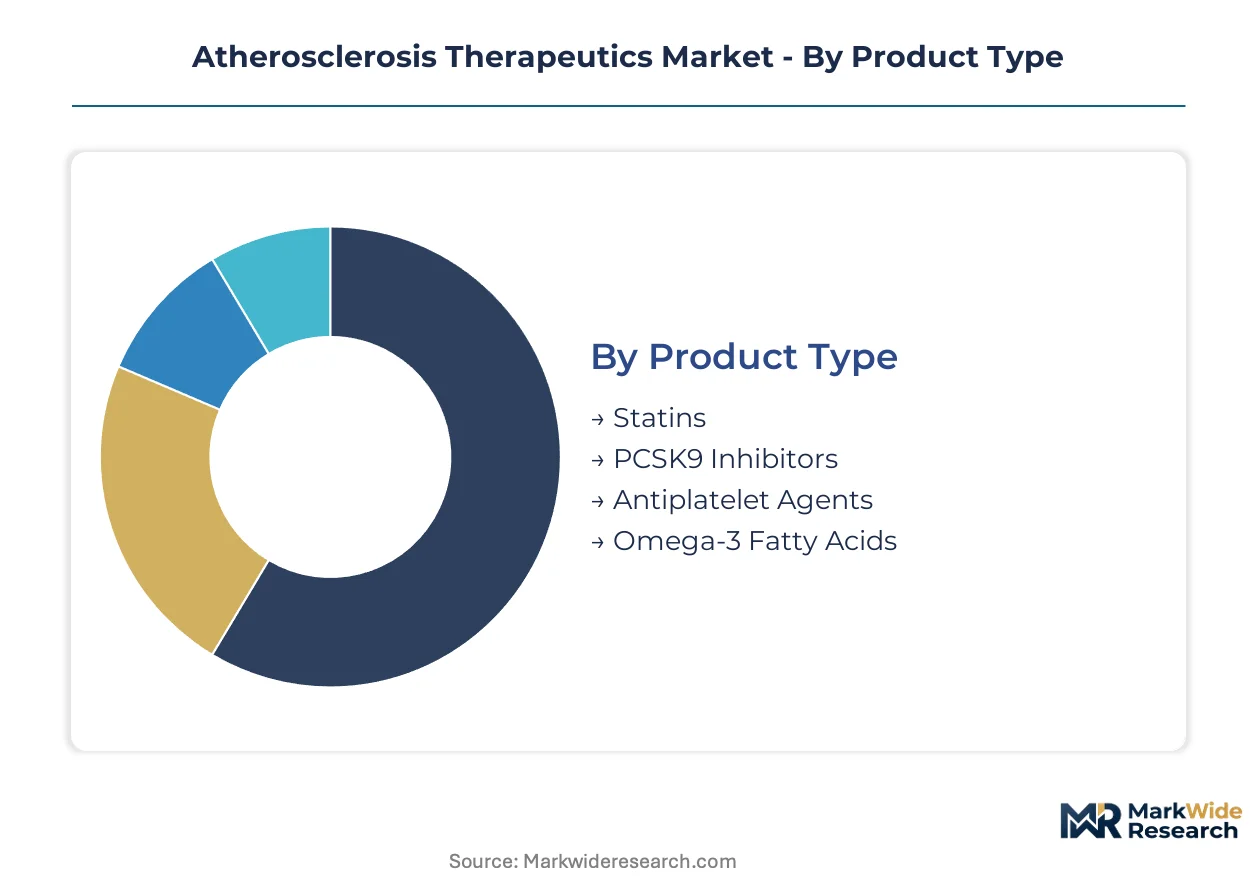
Atherosclerosis therapeutics fragment across multiple dimensions that determine channel economics and prescriber access. Product format, care setting, and delivery mechanism each create distinct margin pools and distribution requirements.
Product Type:
Channel mix varies sharply by molecular format, with oral small molecules flowing through retail pharmacy networks and biologics concentrating in specialty distribution.
- Statins:Oral HMG-CoA reductase inhibitors dominate primary care prescribing through retail pharmacy channels. Medicare Part D reimbursement and generic atorvastatin availability anchor volume in United States outpatient settings, though pricing compression has collapsed manufacturer margins.
- PCSK9 Inhibitors:Monoclonal antibodies delivered via subcutaneous injection require cold chain infrastructure and specialty pharmacy networks. Tertiary cardiovascular centers in Germany and academic medical centers in the United States concentrate demand for familial hypercholesterolemia populations.
- Antiplatelet Agents:Thrombotic risk reducers including aspirin and P2Y12 inhibitors flow through hospital outpatient and retail channels.
- Omega-3 Fatty Acids:Prescription icosapent ethyl and dietary supplements compete for lipid management adjunct therapy positioning.
By volume, Statins leads. By growth pace, PCSK9 Inhibitors is gaining share fastest.
Therapy Area:
Cost tier stratification separates acute intervention from chronic management, with reimbursement intensity scaling to cardiovascular event risk.
- Primary Prevention:Asymptomatic risk factor modification targets elevated LDL-C in patients without established cardiovascular disease. United States preventive services coverage and employer wellness programs drive screening volumes, though statin generic saturation limits revenue per patient.
- Secondary Prevention:Post-event therapy reduction targets myocardial infarction and stroke survivors with aggressive lipid goals. Hospital systems in France and integrated delivery networks in the United States prioritize these populations for PCSK9 inhibitor access.
- Acute Management:In-hospital initiation of lipid-lowering therapy during coronary events.
- Chronic Treatment:Long-term maintenance protocols for established atherosclerotic cardiovascular disease.
By patient count, Primary Prevention leads. By therapy intensity, Secondary Prevention commands premium positioning.
End User:
Customer type determines procurement sophistication, with hospital systems negotiating formulary placement and homecare requiring patient self-administration support.
- Hospitals:Tertiary cardiovascular centers perform cascade screening and initiate high-efficacy biologic therapy. Academic medical centers in the United States and university hospitals in Germany anchor PCSK9 inhibitor adoption through specialist prescriber concentration.
- Clinics:Primary care and cardiology outpatient settings manage stable patients on oral regimens.
- Homecare Settings:Self-administered injectable therapy requires nursing support and adherence monitoring.
- Rehabilitation Centers:Post-acute facilities manage secondary prevention protocol transitions.
By prescription volume, Clinics leads. By biologic adoption rate, Hospitals is expanding most quickly.
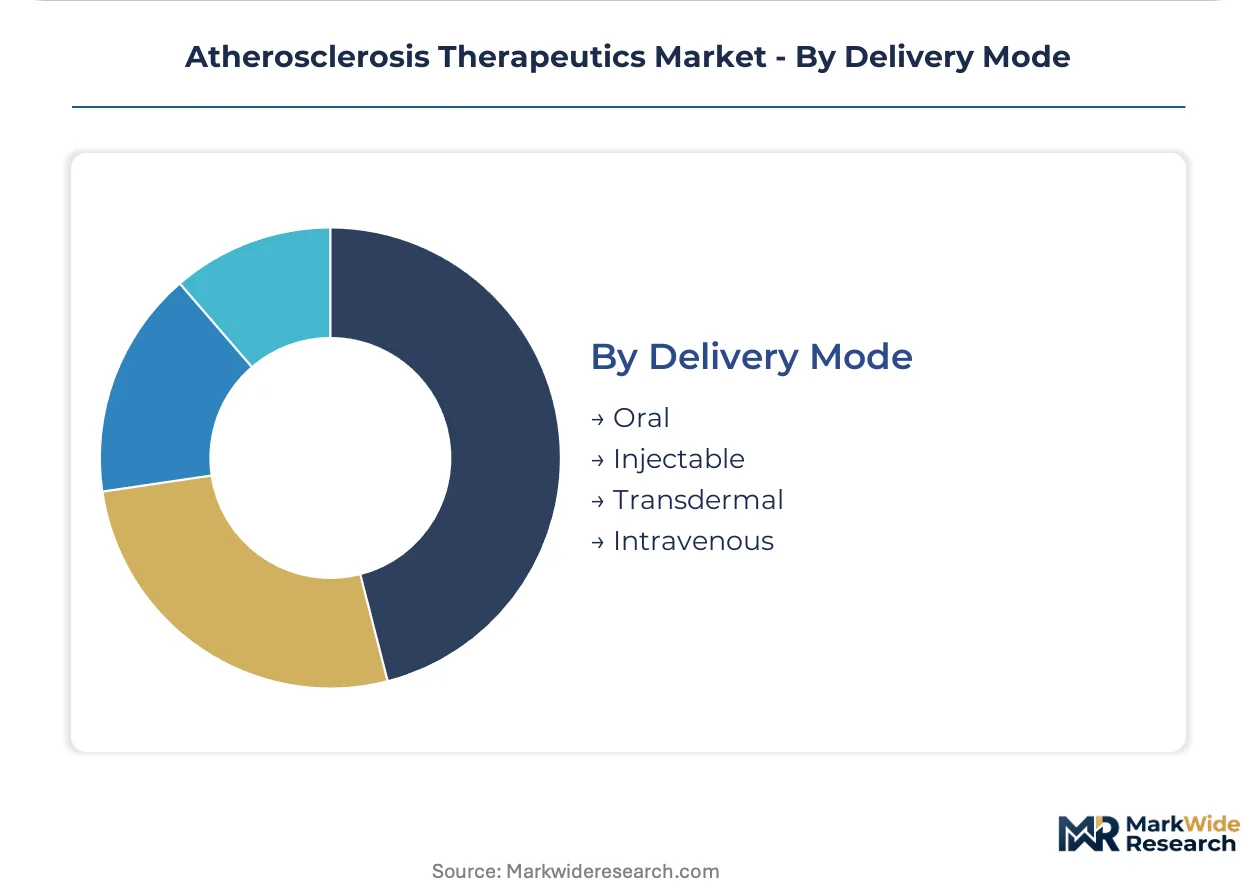
Delivery Mode:
Supply concentration and margin structure hinge on formulation complexity, with parenteral formats requiring manufacturing capabilities that oral generics cannot replicate.
- Oral:Tablet and capsule formulations dominate primary prevention through retail pharmacy dispensing. Atorvastatin and rosuvastatin commoditization has eliminated pricing power, though patient preference for non-injectable administration sustains volume.
- Injectable:Subcutaneous monoclonal antibodies and emerging small molecules command specialty pharmacy distribution. Cold chain requirements limit dispensing flexibility to PBM-affiliated networks with temperature-controlled infrastructure.
- Transdermal:Patch-based delivery remains experimental for lipid-lowering applications.
- Intravenous:Hospital-administered formulations for acute coronary syndrome settings.
By prescription count, Oral leads. By revenue per dose, Injectable shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologics manufacturing capacity clusters in the United States and Germany, creating regional supply advantages for injectable PCSK9 therapies. Hospital formulary placement and reimbursement policy variance drive demand fragmentation across national boundaries.
United States
Medicare Part D preventive therapy coverage and cardiovascular center expansion at Cleveland Clinic and Mayo Clinic anchor statin volume. FDA accelerated approval pathways compress novel mechanism timelines. Massachusetts and California academic medical centers lead PCSK9 inhibitor adoption through specialist prescriber density.
Germany
Statutory health insurance lipid-lowering therapy budgets and university hospital cascade screening programs expand familial hypercholesterolemia identification. EMA conditional marketing authorizations enable earlier reimbursement access. Bavaria and North Rhine-Westphalia cardiovascular networks concentrate biologic prescribing through integrated care contracts.
Japan
Aging demographics and stroke prevention protocols drive aggressive LDL-C target adoption in tertiary hospitals. PMDA consultation programs streamline cardiovascular outcome trial design for domestic sponsors. Tokyo and Osaka metropolitan areas anchor specialist prescriber concentration for high-efficacy therapy.
United Kingdom
NICE technology appraisals and NHS England specialized commissioning frameworks gate PCSK9 inhibitor access to high-risk secondary prevention populations. Genomic England cascade screening expands familial hypercholesterolemia detection. London and Manchester cardiovascular centers concentrate biologic therapy initiation.
France
HAS transparency committee assessments and hospital-university institute lipid clinic networks shape reimbursement for injectable therapies. ANSM pharmacovigilance requirements influence post-market evidence generation. Paris and Lyon academic hospital clusters lead PCSK9 adoption through research-active prescriber bases.
Atherosclerosis Therapeutics Market Vendor Landscape
Concentration sits with biologics manufacturers commanding injectable manufacturing scale and statin incumbents defending oral volume bases. The competitive structure splits between high-efficacy biologic specialists and broad cardiovascular portfolio holders. Two archetypes dominate: monoclonal antibody scale players and oral small molecule brand managers. Competitive moves center on specialty pharmacy network partnerships and outcome-based contracting with payers.
Within the biologics scale tier, Amgen Inc. and Novartis AG occupy positions anchored by manufacturing infrastructure and sustained R&D intensity in lipid-lowering innovation. Pfizer Inc. represents the oral-focused archetype, competing through statin brand strength and hospital formulary placement breadth across North America and Europe.
| Leading Market Players |
|---|
| Amgen Inc. |
| Novartis AG |
| Pfizer Inc. |
| Sanofi |
| AstraZeneca |
| Merck & Co., Inc. |
| GlaxoSmithKline |
| Bayer AG |
| Johnson & Johnson |
| Others |
Supply Flow & Price Mechanics
Oral PCSK9 small molecule development is displacing monoclonal antibody production in late-stage pipelines, simultaneously shifting manufacturing geography toward traditional small-molecule strongholds and collapsing the cold-chain premium that previously anchored injectable pricing power. This substitution dynamic fragments historical supply concentration while reopening margin pools for manufacturers with oral formulation expertise.
Pricing Analysis
Medicare Part D preventive therapy coverage dictates the pricing tier structure across the atherosclerosis therapeutics landscape, separating premium biologic reimbursement from commoditized statin tiers. Price differentiation rests on LDL-C lowering magnitude and cardiovascular outcome trial completion status, with statin-intolerant patient protocols commanding the least price sensitivity due to limited therapeutic alternatives. Cost compression in primary prevention oral segments is intensifying because atorvastatin and rosuvastatin generic saturation has eliminated brand pricing power.
Supply Chain Analysis
Inventory lead times for monoclonal antibody production extend substantially beyond small-molecule chemical synthesis, creating working capital intensity that favors scaled biologics manufacturers. Active pharmaceutical ingredient supply concentrates in the United States, Germany, and Switzerland for injectable therapies, while oral statin production draws from India and China. Cold chain infrastructure requirements for PCSK9 inhibitors introduce single-source vulnerability through temperature-controlled distribution networks. Distribution runs through specialty pharmacy channels for biologics and retail pharmacy networks for oral formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The atherosclerosis therapeutics market represents an early-cycle expansion story, with oral PCSK9 small molecule penetration still below twenty percent of addressable familial hypercholesterolemia populations and significant runway remaining before format substitution matures.
For Market Incumbents: Compound manufacturing scale advantages in injectable biologics by securing long-term specialty pharmacy network exclusivity before oral small molecules achieve FDA approval. Prioritize backward integration into cold chain distribution infrastructure to defend margin position against imminent format disruption. Accelerate real-world evidence generation through digital adherence monitoring to justify premium reimbursement as payers tighten cardiovascular outcome trial requirements.
For New Entrants and Emerging Players: FDA accelerated approval pathway designation offers the fastest route to commercial presence without requiring full cardiovascular outcome trial completion before market entry. Target statin-intolerant patient populations in United States academic medical centers where prescriber concentration supports rapid adoption of novel mechanisms. Pursue licensing agreements with established specialty pharmacy networks rather than building independent distribution infrastructure.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors oral small molecule development platforms over legacy injectable manufacturing assets. Long-term viability over the next decade hinges on pipeline positioning for non-injectable delivery formats and regulatory relationships with FDA cardiovascular division leadership. Monitor EMA conditional marketing authorization withdrawal rates as an inflection indicator for post-approval outcome study success probability.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Adaptive cardiovascular outcome trial designs compress development timelines for novel LDL-C lowering mechanisms. |
| Regulatory Approval Pathway | FDA accelerated approval and EMA conditional marketing authorization enable earlier revenue generation contingent on post-market study completion. |
| Manufacturing Scale-Up | Biologics production capacity expansion in Massachusetts and Bavaria anchors supply security for injectable PCSK9 inhibitors. |
| Pipeline Diversification | Oral small molecule development reduces cold chain dependency and expands addressable pharmacy dispensing channels. |
| Strategic Partnership | Specialty pharmacy network alliances concentrate patient data capture and adherence monitoring capabilities. |
Methodological Framework
Cross-validation between primary interviews with cardiovascular specialists and secondary validation through FDA filings anchors the qualitative findings in this study. The research team conducted structured discussions with drug development executives, formulary directors at integrated delivery networks, payer access specialists, and hospital procurement managers across the United States, Germany, and Japan. Secondary sources include EMA submission databases, ClinicalTrials.gov protocol records, Medicare Part D formulary data, and statutory health insurance reimbursement schedules. Bottom-up prescription volume modeling and top-down manufacturer revenue triangulation ensure consistency across estimation approaches.
Sensitivity analysis around patient identification rates for familial hypercholesterolemia and PCSK9 inhibitor adherence assumptions informs the forecast confidence intervals across the projection horizon. The analytical framework segments by product type, therapy area, delivery mode, and regional regulatory cluster, with CAGRs derived from epidemiological trend extrapolation and pricing scenario modeling. Key forecast inputs include cascade screening program expansion timelines and oral small molecule approval probability assessments.
Decision-makers should treat outputs as directional under assumptions of stable Medicare reimbursement policy and continued FDA accelerated pathway availability; material deviation in payer evidence requirements or regulatory withdrawal rates would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Global Cardiac Rehabilitation Market
Cardiovascular
Bifurcation Lesions Market
Cardiovascular
Tachycardia Market
Cardiovascular
Atherosclerosis Market
Cardiovascular
Acute Heart Failure (AHF) Therapeutics Market
Cardiovascular
Global Hyperlipidemia Drugs Market
Cardiovascular
Carotid Artery Disease Market
Cardiovascular
Cardiovascular Disease Drugs Market
Cardiovascular
Heart Health Products Market
Cardiovascular
Brugada Syndrome Treatment Market
Cardiovascular
Paroxysmal Supraventricular Tachycardia (PSVT) Market
Cardiovascular
Dilated Cardiomyopathy Market
Cardiovascular
Cardiac Valvulotome Market
Cardiovascular
Heart Block Therapeutics Market
Cardiovascular
Coronary Artery Disease Therapeutics Market
Cardiovascular
Global Hypotension Treatment Market