
 Non-Terrestrial IoT Gateway Hardware and Software Market | 2026-2036
Non-Terrestrial IoT Gateway Hardware and Software Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Terrestrial IoT Gateway Hardware and Software Market Analytics
Satellite-to-ground distribution channels are rewriting how IoT data reaches enterprise backends. Vodafone Group leverages its cellular-satellite convergence infrastructure to dominate European gateway provisioning. Eutelsat Communications anchors its position through geostationary capacity leased to maritime and aero integrators. ORBCOMM competes across dual-mode hardware stacks that bridge cellular dead zones with LEO satellite bursts.
Non-Terrestrial IoT Gateway Hardware and Software encompasses edge-computing devices, signal processors, and protocol translators that bridge terrestrial LPWAN endpoints to satellite constellations, operating across sub-1 GHz and L-band frequencies with radiation-hardened components for orbital resilience. Ruggedized Gateways lead product-type revenue due to defense and polar logistics specifications, while Cloud-Based deployment models capture the fastest expansion as fleet operators virtualize ground-segment management. Satellite Communication technology occupies the deepest margin pools where proprietary waveform stacks differentiate vendor offerings.
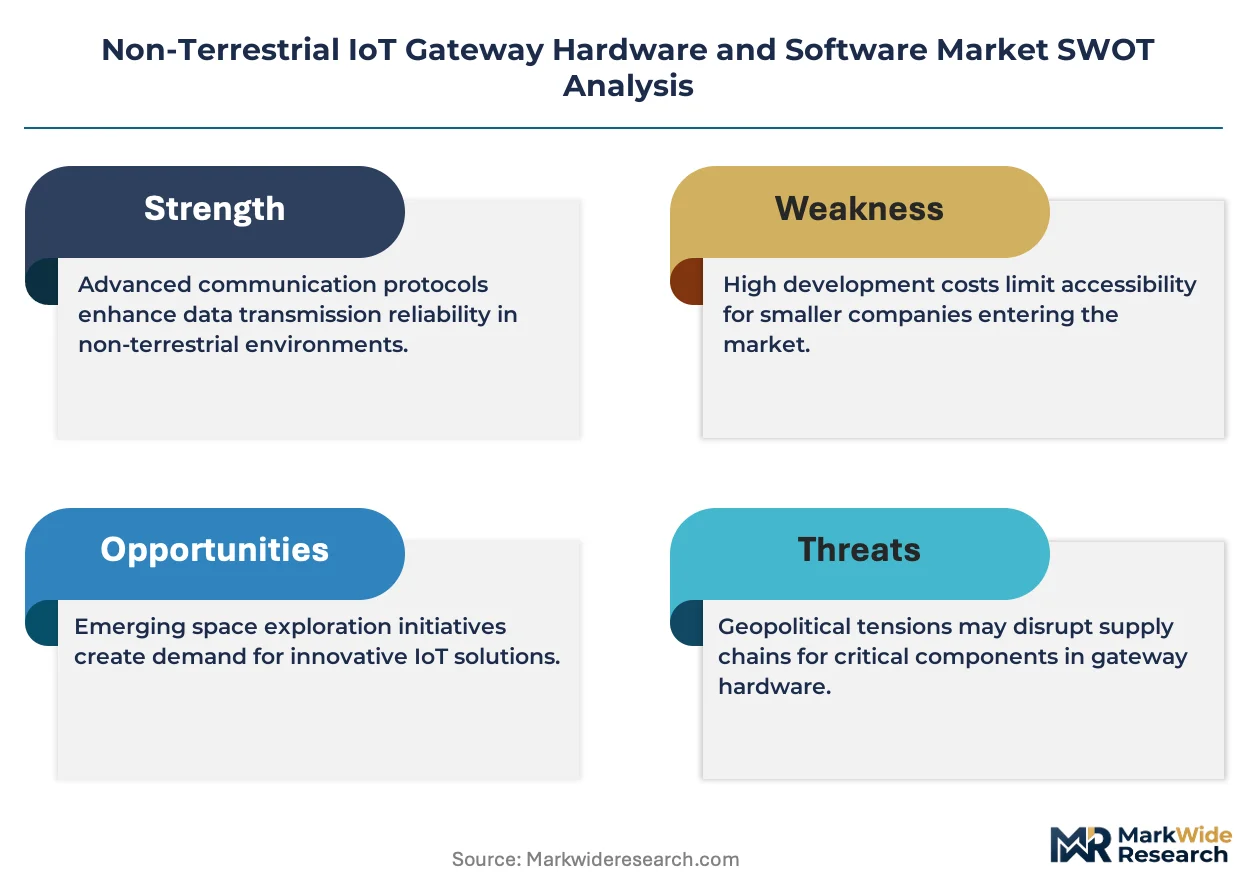
FCC Part 25 licensing governs US gateway earth-station authorizations, while EU Space Programme frameworks and ETSI standards shape European terminal certification requirements, collectively elevating compliance costs for cross-border hardware vendors. Japan's MIC radio equipment rules add a third certification layer for Asia-Pacific market entry. Stakeholders must monitor spectrum reallocation proceedings across these jurisdictions to anticipate hardware redesign cycles and lock in module supplier relationships before regulatory windows narrow.
Market Dynamics
Satellite constellation densification is compressing gateway refresh cycles as LEO operators deploy mesh architectures that demand protocol-flexible edge hardware capable of handoffs across orbital planes.
Growth Catalysts
- FCC Part 25 Streamlining:Expedited earth-station licensing timelines reduce certification bottlenecks for US gateway manufacturers targeting maritime and aero integrators.
- Maritime Fleet Digitization:Container shipping operators mandate real-time cargo monitoring across Pacific and Atlantic corridors, pulling ruggedized gateway deployments into deep-water routes.
- LEO-MEO Constellation Interoperability:Multi-orbit handoff protocols enable single-gateway coverage redundancy that terrestrial cellular cannot match for polar logistics.
Market Restraints
- Radiation-Hardened Component Costs:FPGA and GaN amplifier supply concentrates among three qualified foundries, creating input price volatility for orbital-grade signal processors.
- Tri-Jurisdictional Certification Burden:FCC, ETSI, and Japan MIC testing requirements impose parallel compliance costs that lock smaller hardware vendors out of cross-border contracts.
- Terrestrial 5G-NR Coverage Expansion:Private network deployments in mining and agriculture reduce addressable dead zones for satellite-backhauled IoT endpoints.
Strategic Opportunities
- EU Space Programme Funding Windows:Horizon Europe and EUSPA procurement incentives favor gateway vendors with manufacturing footprints in Germany, France, or Italy.
- Cloud-Native Ground Segment Virtualization:Containerized network function deployment allows fleet operators to shift gateway management from capex-heavy appliances to opex-based orchestration layers.
- Defense Dual-Use Specifications:NATO-aligned interoperability standards create a premium tier for gateways meeting MIL-STD-810G shock and EMC requirements.
Industry Challenges
- Orbital Mechanics Expertise Scarcity:Gateway firmware teams lack sufficient talent in Doppler compensation algorithms and link-budget modeling for non-geostationary constellations.
- Legacy SCADA Integration Friction:Industrial IoT adopters in oil and gas face protocol translation complexity when bridging Modbus and DNP3 endpoints to satellite IP backhauls.
- Module Supplier Lock-In Risks:Proprietary waveform stacks from satellite operators create hardware design dependencies that complicate second-source strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Terrestrial IoT Gateway Hardware and Software Market |
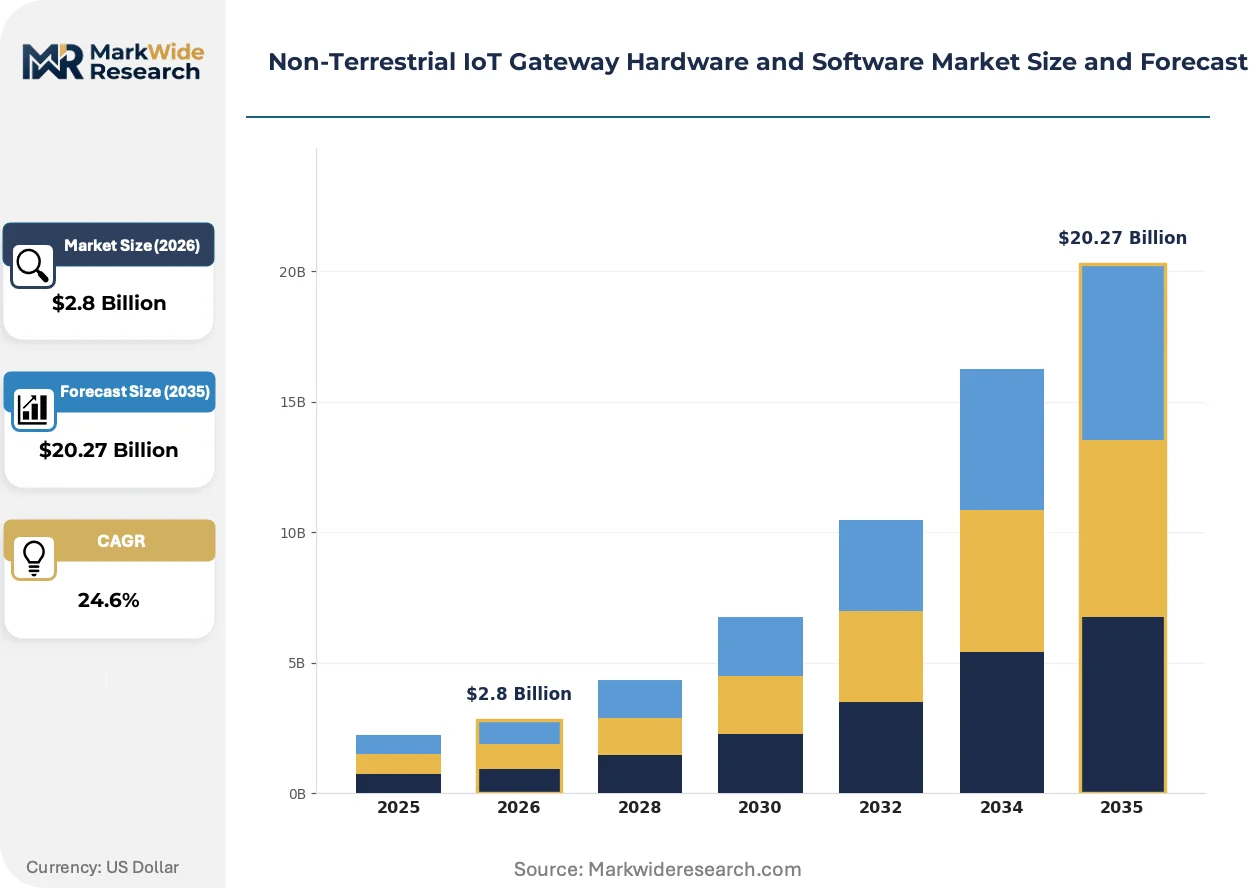
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $20.27 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ruggedized Gateways, Communication Processors, Signal Amplifiers, Edge Devices Deployment Model: On-Premise, Cloud-Based, Edge Computing, Hybrid End User: Aerospace, Maritime, Environmental Monitoring, Automotive Technology: LoRaWAN, Satellite Communication, NB-IoT, Zigbee |
| Companies Covered | Vodafone Group, Eutelsat Communications, ORBCOMM, Lacuna Space, Kineis, Wyld Networks, Satel Benelux, WTE Limited, GateHouse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Terrestrial IoT Gateway Hardware and Software Market Evolving Landscape
Gateway architectures are bifurcating between ultra-ruggedized edge appliances for defense and polar logistics versus lightweight virtualized stacks for commercial fleet management, with software-defined radio cores enabling both paths.
Software-defined radio basebands are hybridizing cellular and satellite waveforms into unified signal chains. Mining operators in Australia and Canada are adopting these converged modems to collapse separate cellular and satellite gateway estates into single hardware footprints. This compression is eroding the addressable market for single-mode cellular-only gateways in remote extraction sites.
EU Space Programme security certification mandates are tightening terminal resilience requirements for critical infrastructure applications. Hardware vendors must now demonstrate anti-tamper enclosures and firmware integrity attestation to qualify for energy and transport sector contracts. German industrial integrators are responding by pre-integrating secure element chips from qualified semiconductor suppliers before system-level testing.
Buyer preference is gravitating toward subscription-based gateway provisioning that bundles hardware, connectivity, and cloud orchestration into unified service agreements. Maritime fleet operators are displacing capital purchase models with per-vessel monthly fees that scale with active sensor counts. This behavioral shift is most pronounced in Singapore-flagged and Greek-owned shipping fleets operating under tight working capital constraints.
Non-Terrestrial IoT Gateway Hardware and Software Market Segmentation
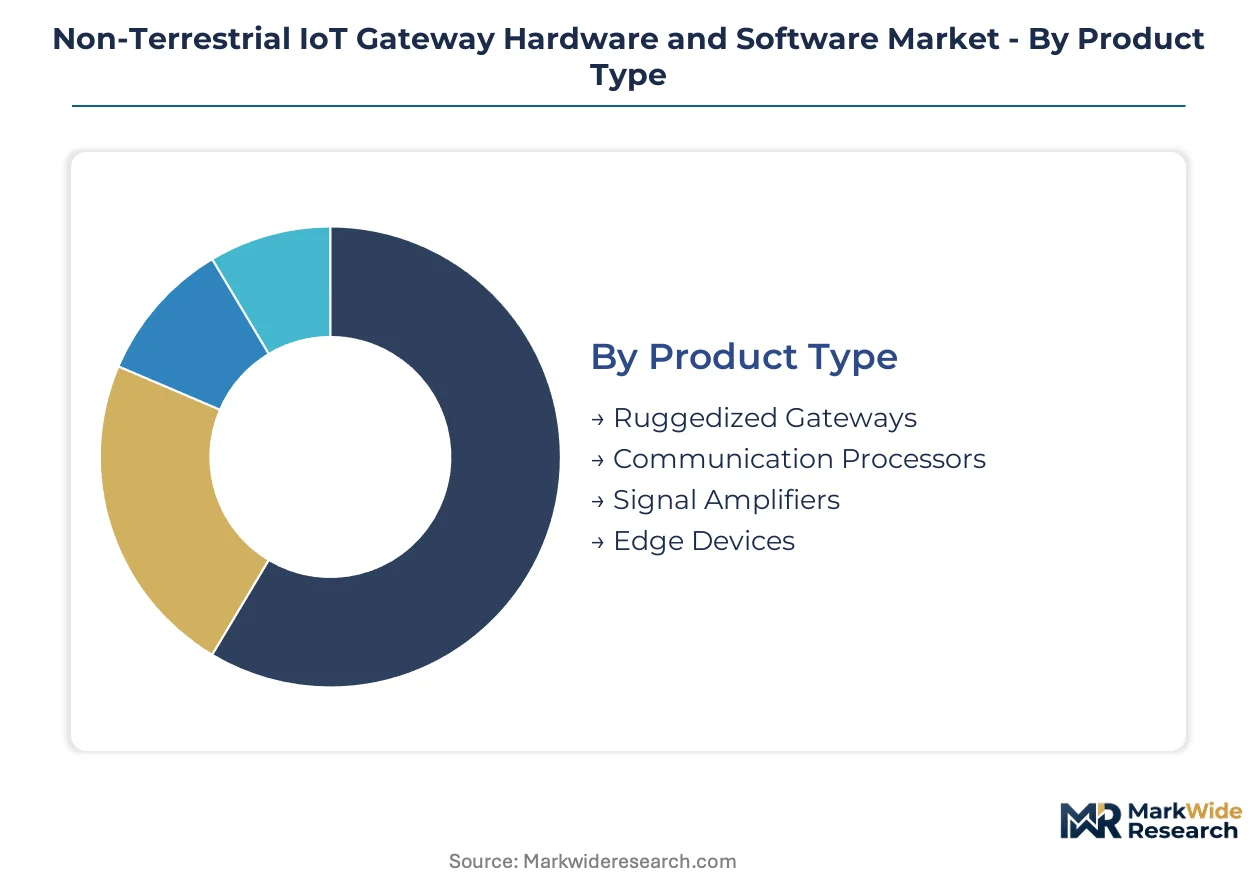
Gateway architectures diverge sharply across operating environments, from radiation-hardened orbital hardware to virtualized cloud stacks. Segmentation reveals where procurement budgets concentrate and which technology layers command premium positioning.
Product Type:
Cost tier stratification separates defense-grade specifications from commercial fleet deployments, with component hardening driving material cost multiples.
- Ruggedized Gateways:MIL-STD-810G compliant enclosures with shock-mounted FPGA arrays and conformal-coated PCBs withstand polar logistics temperatures from -40°C to +85°C. Defense procurement in Germany and maritime integrators in Singapore anchor demand for these specifications.
- Communication Processors:Multi-protocol baseband SoCs integrate Doppler compensation firmware for LEO handoffs. These processors concentrate in gateway refresh cycles tied to Starlink and OneWeb constellation densification.
- Signal Amplifiers:GaN-based L-band power modules from qualified foundries.
- Edge Devices:Containerized compute nodes with local analytics pipelines.
Ruggedized Gateways command the established base. The steepest expansion runs through Communication Processors.
Deployment Model:
Application architecture determines whether operators absorb capital equipment or shift to operational expenditure models.
- Cloud-Based:Kubernetes-orchestrated ground segments virtualize waveform processing and fleet management dashboards. Greek and Singapore-flagged maritime operators are displacing on-premise appliances with per-vessel subscriptions that scale sensor counts dynamically.
- Hybrid:Split architectures keep latency-sensitive protocol translation at the edge while pushing analytics to centralized clouds. Australian mining operators deploy these configurations to collapse separate cellular and satellite gateway estates.
- On-Premise:Capex-heavy appliances for sovereign data requirements.
- Edge Computing:Autonomous processing for disconnected operations.
On-Premise retains the installed base. Cloud-Based is climbing the fastest.
End User:
Volume concentration varies by sector-specific regulatory mandates and connectivity dead-zone severity.
- Maritime:Container shipping operators across Pacific and Atlantic corridors mandate real-time cargo monitoring. Greek-owned fleets under tight working capital constraints are driving subscription-based gateway provisioning.
- Aerospace:Cabin and cargo IoT backhaul for narrow-body retrofit programs.
- Environmental Monitoring:Arctic and Antarctic sensor networks.
- Automotive:Connected vehicle telemetry in cellular shadow zones.
Maritime anchors procurement volume. Environmental Monitoring is gaining share fastest.
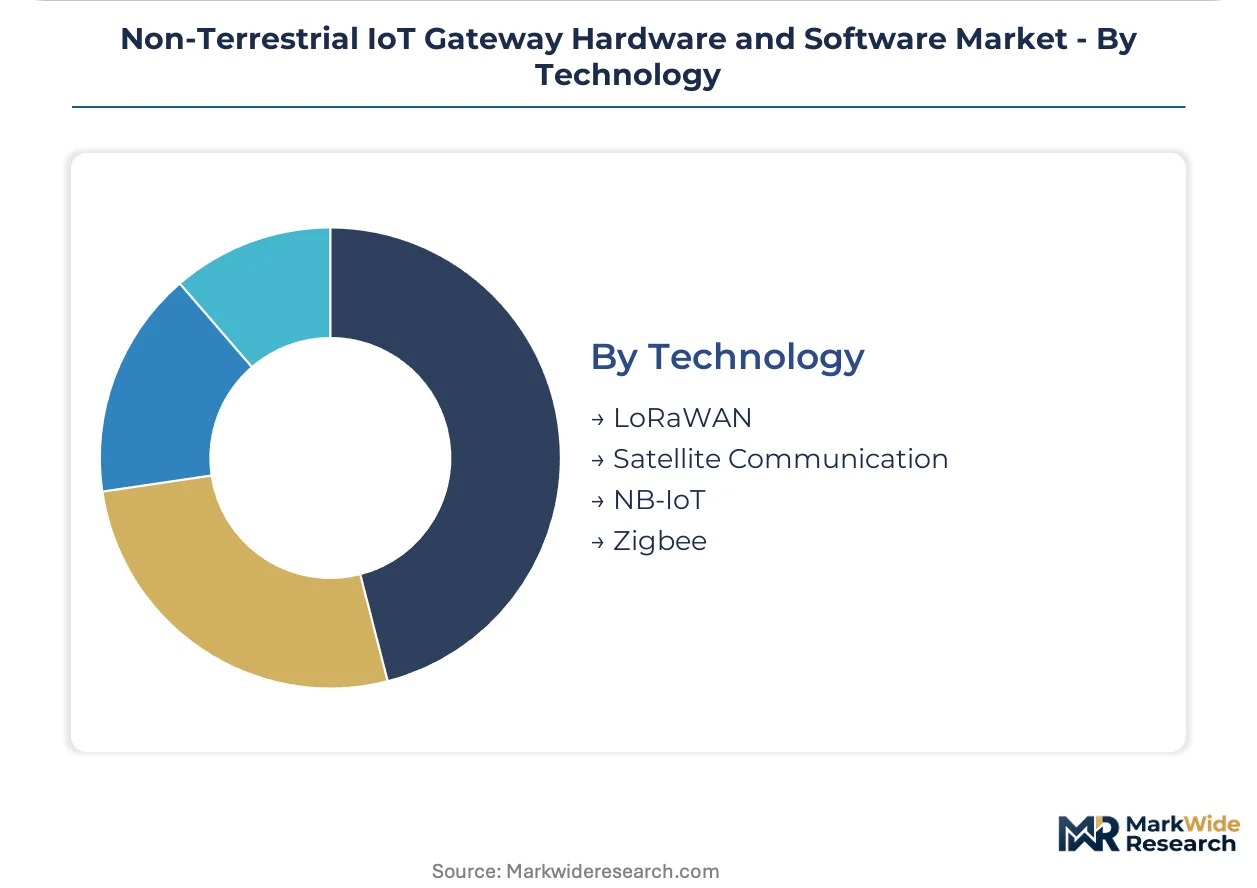
Technology:
Margin pools concentrate where proprietary waveform stacks create differentiation against commodity LPWAN alternatives.
- Satellite Communication:Proprietary LEO and GEO waveforms with radiation-hardened modems command the deepest margins. Eutelsat and ORBCOMM stack deployments in maritime and aero integrators favor vendors with multi-orbit handoff capabilities.
- LoRaWAN:Sub-GHz unlicensed spectrum for low-power sensor aggregation.
- NB-IoT:Licensed cellular fallback in hybrid architectures.
- Zigbee:Short-range mesh for localized device clustering.
Satellite Communication holds the premium tier. LoRaWAN is expanding most quickly in cost-constrained deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC Part 25 licensing governs US gateway earth-station authorizations, while EU Space Programme frameworks and ETSI standards shape European terminal certification requirements. Japan's MIC radio equipment rules add a third certification layer for Asia-Pacific market entry. Stakeholders must monitor spectrum reallocation proceedings across these jurisdictions to anticipate hardware redesign cycles.
United States
Maritime logistics operators across Pacific and Atlantic corridors mandate real-time cargo monitoring, pulling ruggedized gateway deployments into deep-water routes. FCC Part 25 streamlining expedites earth-station licensing timelines for manufacturers targeting maritime and aero integrators. Defense procurement in California and Texas anchors demand for MIL-STD-810G compliant enclosures with radiation-hardened components.
Germany
Industrial IoT integrators anchor early satellite-terrestrial hybrid networks, with Horizon Europe and EUSPA procurement incentives favoring gateway vendors with manufacturing footprints in Bavaria or North Rhine-Westphalia. ETSI standards shape terminal certification requirements for cross-border hardware vendors. Stuttgart and Munich industrial clusters concentrate secure element chip pre-integration for energy and transport sector contracts.
Singapore
Greek-owned and Singapore-flagged shipping fleets under tight working capital constraints drive subscription-based gateway provisioning with per-vessel monthly fees. The Maritime and Port Authority of Singapore regulates vessel communication systems for cargo monitoring compliance. Port operators and maritime integrators cluster around the city-state's container terminals, displacing capital purchase models with opex-based orchestration layers.
Japan
METI industrial digitization programs accelerate LEO-MEO constellation interoperability testing for polar logistics coverage redundancy. MIC radio equipment rules impose certification requirements that lock smaller hardware vendors out of cross-border contracts. Nagoya and Osaka manufacturing corridors concentrate multi-protocol baseband SoC production for gateway refresh cycles tied to Starlink and OneWeb densification.
Australia
Mining operators in Western Australia and Queensland adopt converged cellular-satellite modems to collapse separate gateway estates into single hardware footprints. The Australian Communications and Media Authority governs satellite earth station licensing for remote extraction sites. Perth and Brisbane industrial technology clusters drive hybrid deployment configurations that keep latency-sensitive protocol translation at the edge.
Non-Terrestrial IoT Gateway Hardware and Software Market Competitive Landscape
Telecom infrastructure conglomerates and specialized satellite communications firms split the market into distinct capability tiers. Tier-one positioning concentrates among cellular-satellite convergence providers with established spectrum holdings, while tier-two specialists compete on waveform flexibility and maritime application expertise. Three archetypes dominate: integrated telecom-satellite hybrids, pure-play satellite gateway vendors, and industrial IoT system integrators. Competitive intensity manifests through constellation partnership exclusivity and cloud-native ground segment virtualization licensing.
Within the integrated telecom-satellite tier, Vodafone Group and Eutelsat Communications exemplify scale-driven positioning through cellular-satellite convergence infrastructure and geostationary capacity leasing respectively. ORBCOMM occupies a specialist position bridging cellular dead zones with LEO satellite bursts through dual-mode hardware stacks. These three entities represent contrasting strategic paths—terrestrial network extension, orbital capacity aggregation, and application-specific protocol bridging—without implying equivalent market presence or resource commitment.
| Leading Market Players |
|---|
| Vodafone Group |
| Eutelsat Communications |
| ORBCOMM |
| Lacuna Space |
| Kineis |
| Wyld Networks |
| Satel Benelux |
| WTE Limited |
| GateHouse |
| Others |
Value Network & Pricing Analysis
Pacific and Atlantic shipping corridor freight economics compress gateway procurement budgets while concentrating supplier power among radiation-hardened component foundries, creating asymmetric price differentiation between standard commercial units and defense-grade configurations.
Pricing Analysis
The customization-premium spread separates configured-to-order ruggedized gateways from standard commercial units by a factor tied to MIL-STD-810G certification tier and GaN amplifier sourcing. Subscription-based SaaS-tiered provisioning now dominates maritime deployments, compressing upfront capital outlays into per-vessel operational expenditure. Price differentiation rests on FCC Part 25 certification status and secure element chip integration for EU Space Programme compliance. Cost compression in commercial fleet tiers intensifies as Greek and Singapore-flagged operators consolidate purchasing through managed service agreements. Defense integrators exhibit lowest price sensitivity due to NATO interoperability mandates, while commercial mining operators in Australia demonstrate highest elasticity to hardware unit costs.
Supply Chain Analysis
Contract manufacturing concentration for radiation-hardened FPGAs and GaN L-band modules sits with qualified foundries in the United States, Germany, and Japan, creating captive supply dependencies for orbital-grade signal processors. Raw material feeds draw from specialty semiconductor substrates, conformal coating compounds, and shock-mount alloys. Single-source vulnerability runs through the three qualified radiation-hardened foundries serving defense and polar logistics specifications. Distribution runs through maritime integrators in Singapore, industrial IoT system houses in Germany, and defense procurement channels in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gateway vendor fragmentation creates acquisition and partnership opportunities as satellite constellation densification splinters demand across LEO, MEO, and GEO protocol requirements.
For Market Incumbents: Entrench position through backward integration into secure element chip supply and captive GaN amplifier sourcing from qualified foundries. Lock in exclusive waveform licensing with Starlink and OneWeb operators before second-source hardware proliferates. Priority lever: manufacturing footprint expansion into Bavaria or North Rhine-Westphalia to capture Horizon Europe procurement preference. For New Entrants and Emerging Players: Arctic and Antarctic environmental monitoring networks present the most penetrable white-space as legacy SCADA integrators struggle with Modbus-to-satellite IP protocol translation. Target subscription-based managed service models for Greek-owned shipping fleets under working capital constraints. Go-to-market angle: cloud-native ground segment virtualization bundled with per-sensor pricing. For Investors and Strategic Acquirers: Dual-use gateway specialists with MIL-STD-810G certification and existing NATO supply chain relationships represent the priority acquisition archetype for defense portfolio buildout. Long-term viability hinges on multi-orbit handoff firmware capabilities across LEO-MEO constellation interoperability. Signal to watch: FCC Part 25 expedited licensing application volumes as predictor of maritime gateway refresh cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Ground Segment Virtualization | Enables Greek and Singapore-flagged fleets to shift from capex appliances to per-vessel subscription models. |
| Multi-Orbit Waveform Licensing Agreement | Secures proprietary handoff protocols with Starlink and OneWeb for gateway refresh cycle capture. |
| Secure Element Chip Pre-Integration | Qualifies hardware for EU Space Programme energy and transport sector contracts through anti-tamper certification. |
| Defense Dual-Use Certification Investment | Opens NATO-aligned procurement channels for MIL-STD-810G shock and EMC compliant gateway tiers. |
| Manufacturing Footprint Expansion | Positions vendors for EUSPA procurement incentives in Germany, France, or Italy. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FCC licensing databases, EU Space Programme procurement records, and satellite operator constellation deployment disclosures. Interviews with maritime fleet operations directors, industrial IoT system integrators, defense procurement officers, and gateway hardware engineering leads inform demand-side validation. Customs and trade data, ETSI certification registries, and satellite operator service agreements provide supply-side triangulation. Bottom-up unit shipment estimates and top-down addressable market sizing converge through iterative reconciliation.
Forecast inputs include constellation densification schedules, regulatory certification timeline changes, and end-user procurement model shifts across the projection horizon. Segmentation dimensions encompass product type ruggedization tier, deployment model architecture, end-use sector regulatory mandate intensity, and technology waveform proprietary status. CAGRs derive from logistic curve modeling of gateway refresh cycles against satellite operator capacity expansion trajectories. Industry-specific inputs incorporate Doppler compensation algorithm development costs and radiation-hardened component foundry capacity constraints.
The forecast holds incumbent behavior within observed patterns; aggressive moves by LEO constellation operators into direct gateway manufacturing would shift outcomes substantially. Regulatory reallocation proceedings across FCC, ETSI, and Japan MIC jurisdictions present revision risk to hardware certification timelines. Quarterly review of earth-station licensing application backlogs and secure element chip supplier allocation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Smart Remote Market
Internet of Things (IoT)
Wifi IoT Market
Internet of Things (IoT)
Europe IoT Device Market
Internet of Things (IoT)
Massive Machine Type Communication Market
Internet of Things (IoT)
Maritime Internet of Things Market
Internet of Things (IoT)
IoT Operating System Market
Internet of Things (IoT)
IoT Utilities Market
Internet of Things (IoT)
Internet of Things (IoT) in Utilities Market
Internet of Things (IoT)
Internet of Things (IoT) Connected Cars Market
Internet of Things (IoT)
Internet of Things (IoT) Platform Market
Internet of Things (IoT)
IoT at Workplace Market
Internet of Things (IoT)
Cellular M2M Market
Internet of Things (IoT)
LPWAN in the Consumer IoT Market
Internet of Things (IoT)
Global IoT Battery Market
Internet of Things (IoT)
North America Industrial IoT Market
Internet of Things (IoT)
Massive IoT Market