
 Internet of Things (IoT) Market | 2026-2036
Internet of Things (IoT) Market Size, Share, and Industry Trends Forecast 2026-2036
Internet of Things (IoT) Market Analysis
Smart manufacturing is hardening as the dominant end-use vertical for industrial IoT spending. Siemens anchors European factory automation with embedded edge analytics platforms. Microsoft leverages Azure IoT cloud services to compete in predictive maintenance deployments across North American automotive plants. Huawei Technologies navigates geopolitical restrictions while sustaining dominance in Asia-Pacific smart city infrastructure.
The Internet of Things denotes networked physical objects embedded with sensors, actuators, and software enabling data exchange over IP-based connectivity with latency thresholds below 100 milliseconds for real-time control loops. Its primary purpose spans asset tracking, process optimization, and autonomous decision-making across commercial and industrial environments. Cloud-based deployment leads solution architecture due to elastic scalability, though edge computing represents the fastest-expanding segment for latency-sensitive applications. Platform solutions capture concentrated margin pools while security offerings grow fastest as breach costs escalate across manufacturing and healthcare end users.
The FCC governs spectrum allocation for unlicensed IoT protocols in the United States, directly shaping device interoperability and market access for LPWAN technologies. ETSI and the EU Cyber Resilience Act mandate baseline security standards for connected products entering European markets, forcing firmware update capabilities into hardware design cycles. Stakeholders must monitor evolving fragmentation between regional certification regimes when scaling cross-border deployments.
Market Dynamics
Industrial IoT deployments are accelerating as factory automation demands sub-100-millisecond latency for real-time control loops, forcing architecture shifts from cloud-centric to edge-distributed processing models. This structural pressure is compressing hardware design cycles and fragmenting certification requirements across regulatory jurisdictions.
Growth Catalysts
- EU AI Act compliance mandates:Connected device manufacturers must embed firmware update capabilities and risk management systems, expanding addressable market for security-integrated hardware platforms.
- Smart manufacturing automation:Automotive and electronics assembly lines in Germany and Japan are deploying sensor networks for predictive maintenance and quality control at scale.
- LPWAN spectrum allocation:Unlicensed protocol expansion under FCC Part 15 rules is lowering connectivity costs for asset tracking applications across North American logistics networks.
Market Restraints
- Semiconductor supply concentration:Edge AI chip fabrication depends on Taiwan-based foundry capacity, exposing hardware vendors to geopolitical disruption risk.
- EU Cyber Resilience Act friction:Mandatory vulnerability disclosure and update support timelines extend product development cycles by 8-14 months for European market entry.
- Cellular module cost volatility:5G RedCap chipset pricing remains 40-60% above LTE-M equivalents, constraining adoption in price-sensitive agricultural monitoring segments.
Strategic Opportunities
- India industrial corridor expansion:PLI scheme incentives for electronics manufacturing are creating greenfield deployment opportunities for connected factory infrastructure.
- Digital twin convergence:Integration of physics-based simulation with live sensor streams is opening new service revenue models in process industries.
- NIS2 Directive tailwinds:Critical infrastructure operator mandates across EU member states are accelerating procurement of certified IoT security gateways.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for resource-constrained devices requires specialized real-time operating system expertise that outpaces graduate pipeline output.
- Multi-protocol integration complexity:Brownfield deployments must bridge proprietary industrial fieldbuses with IP-based standards, extending commissioning timelines.
- Cross-certification timeline compression:Simultaneous FCC, CE, and MIC approvals for global product launches strain regulatory affairs capacity at mid-scale vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internet of Things (IoT) Market |
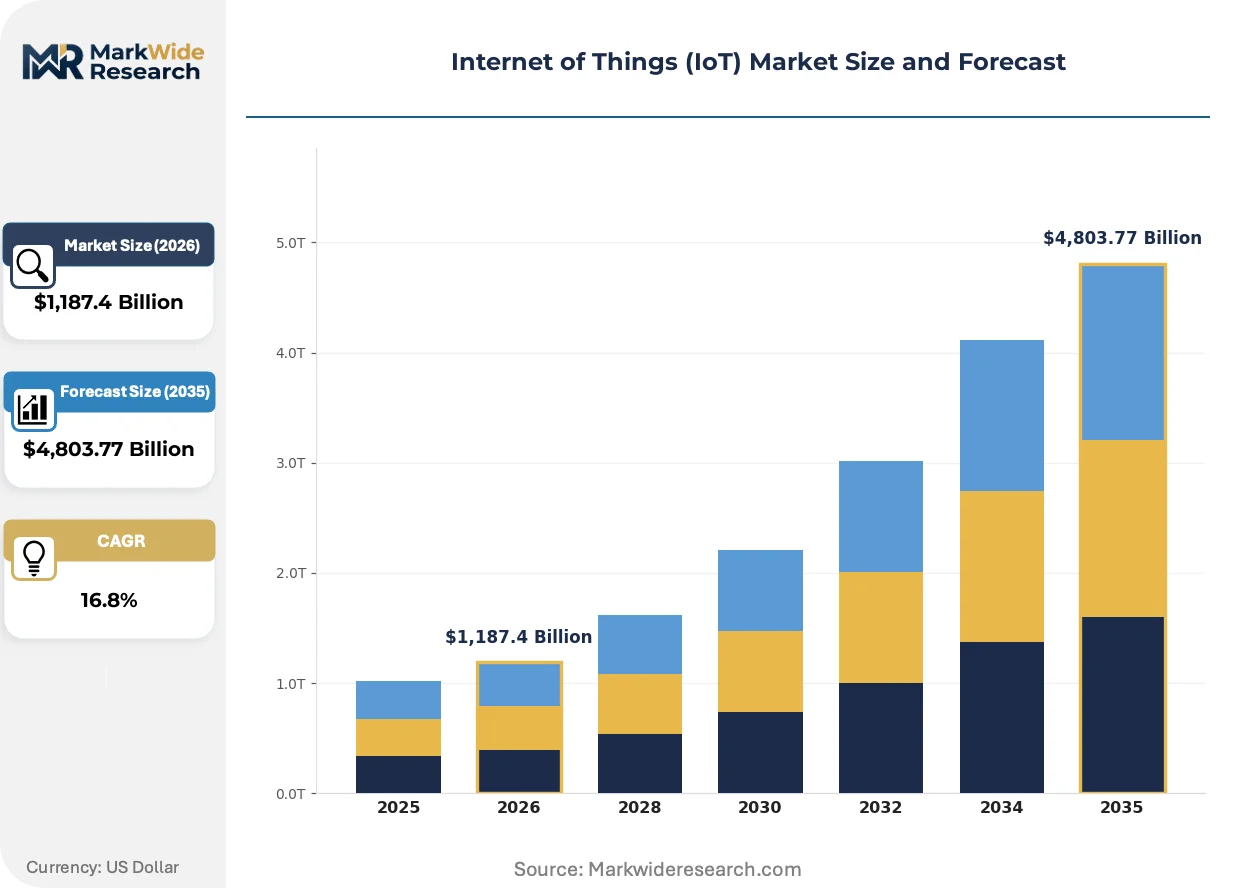
| Market Size in 2026 | $1,187.4 Billion |
| Market Size in 2035 | $4,803.77 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Type: On-Premise, Cloud-Based, Hybrid, Edge Solution Type: Platform, Device Management, Security, Analytics End User: Manufacturing, Healthcare, Transportation, Agriculture Connectivity: Wi-Fi, Cellular, LPWAN, Zigbee |
| Companies Covered | Amazon Web Services, Microsoft, Cisco Systems, IBM, Intel, Huawei Technologies, Siemens, Google, PTC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internet of Things (IoT) Market Emerging Trajectories
Edge-native AI inference is displacing cloud-dependent analytics in latency-critical applications, while regulatory fragmentation is forcing modular hardware architectures. Procurement patterns are simultaneously shifting toward outcome-guaranteed service contracts.
Time-sensitive networking over 5G is rewriting factory floor communication standards. Automotive plants in South Korea are deploying deterministic wireless for robotic coordination. This convergence is compressing the traditional three-tier automation hierarchy into flat, software-defined architectures.
The EU Cyber Resilience Act mandates baseline security standards for all connected products entering European markets. Hardware vendors must now design firmware update mechanisms into initial product specifications. Medical device and industrial control segments are responding by pre-certifying platform modules rather than custom designs.
Asset-as-a-service contracting is displacing capital equipment purchases in mid-scale manufacturing. German machine builders now offer sensor-enabled presses and CNC equipment on per-output pricing. This shift concentrates procurement authority with operations executives rather than traditional engineering buyers.
Internet of Things (IoT) Market Segmentation
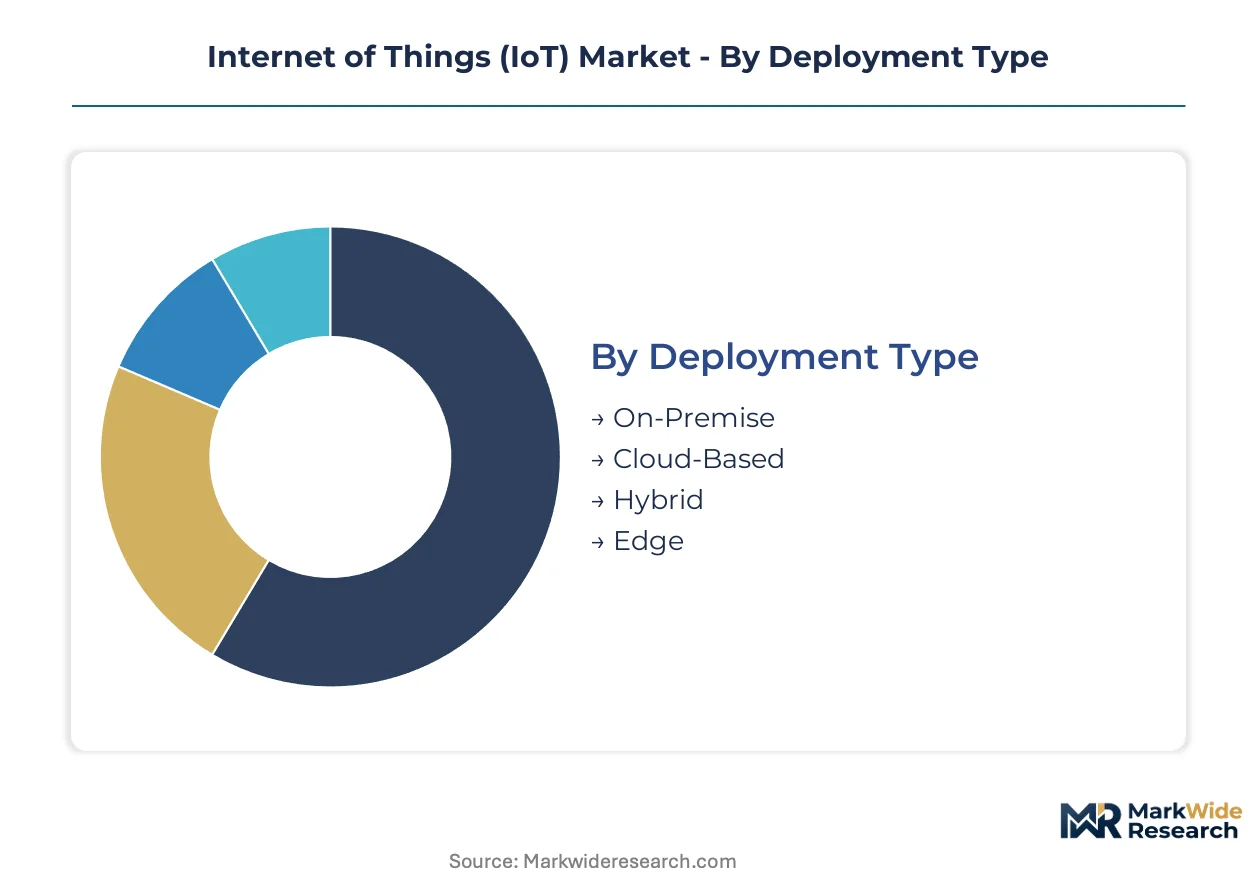
IoT market segmentation reveals how deployment architecture, solution stack, and connectivity protocol choices determine integration complexity and margin capture. Procurement patterns diver sharply between standalone device rollouts and deeply embedded industrial systems requiring sub-100-millisecond latency guarantees.
Deployment Type:
Standalone deployments dominate asset tracking and facility monitoring where latency tolerance exceeds one second, while embedded edge systems penetrate robotic coordination and autonomous process control.
- On-Premise:Local server infrastructure hosting sensor data processing within facility firewalls. Demand concentrates in German automotive plants and Japanese electronics assembly lines where data sovereignty requirements block cloud egress under METI and BIS industrial security guidelines.
- Cloud-Based:Elastic compute resources scaling with connected device volumes. Azure IoT and AWS IoT Core capture manufacturing predictive maintenance contracts across North American automotive plants, though latency floors constrain real-time control applications.
- Hybrid:Split architectures processing time-critical workloads locally while archiving analytics to cloud tiers. German machine builders deploy hybrid stacks for CNC equipment monitoring under EU AI Act data governance requirements.
- Edge:Distributed compute nodes embedding inference engines directly on gateways or sensors. South Korean automotive plants deploy deterministic wireless edge nodes for robotic coordination, compressing control loop latency below 50 milliseconds.
Volume placements concentrate in Cloud-Based deployments; the faster expansion belongs to Edge architectures.
Solution Type:
Margin pools concentrate in platform layers that abstract hardware heterogeneity, while security offerings expand fastest as breach costs escalate across manufacturing and healthcare endpoints.
- Platform:Middleware stacks enabling device provisioning, data ingestion, and application hosting. Siemens MindSphere and PTC ThingWorx anchor European factory automation with embedded edge analytics, capturing multi-year service contracts.
- Device Management:Firmware orchestration, over-the-air updates, and lifecycle monitoring tools. EU Cyber Resilience Act mandates extend development cycles by 8-14 months, forcing vendors to pre-certify platform modules rather than custom designs.
- Security:Encryption, identity management, and threat detection for resource-constrained endpoints. NIS2 Directive procurement mandates across EU member states accelerate certified IoT security gateway deployments for critical infrastructure operators.
- Analytics:Machine learning pipelines converting sensor streams into operational insights. Physics-based digital twin convergence opens service revenue models in German process industries, integrating live data with simulation engines.
Platform solutions capture the deepest margin pools; Security is climbing the fastest as regulatory compliance hardens.
End User:
Application maturity varies sharply by sector, with manufacturing automation demanding deterministic performance while agricultural monitoring tolerates higher latency at lower price points.
- Manufacturing:Predictive maintenance, quality control, and robotic coordination on factory floors. Germany and Japan anchor industrial IoT spending through smart manufacturing programs, with automotive and electronics assembly lines deploying sensor networks at scale.
- Healthcare:Remote patient monitoring, connected medical devices, and clinical asset tracking. FDA and EMA cybersecurity guidance for connected medical devices drives firmware update capabilities into hardware specifications.
- Transportation:Fleet telematics, cargo tracking, and autonomous vehicle infrastructure. FCC Part 15 unlicensed protocol expansion lowers connectivity costs for North American logistics networks.
- Agriculture:Soil monitoring, livestock tracking, and irrigation automation. 5G RedCap chipset pricing 40-60% above LTE-M equivalents constrains adoption in price-sensitive precision agriculture segments.
Manufacturing commands the largest installed base; Healthcare is gaining share fastest through regulatory tailwinds.
Connectivity:
Protocol selection hinges on range, power budget, and latency requirements, with spectrum allocation decisions by national regulators directly shaping device interoperability.
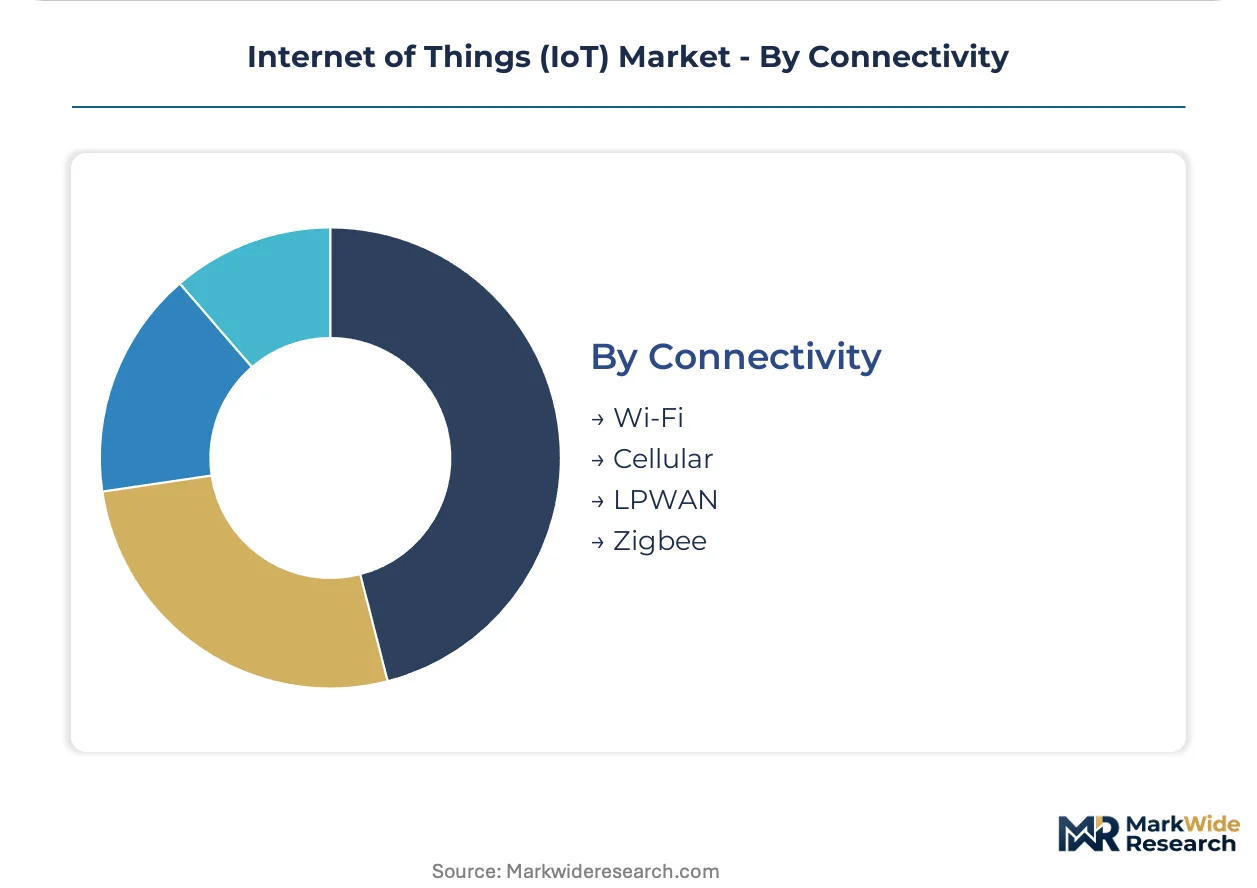
- Wi-Fi:High-throughput local area networking for indoor asset tracking and video analytics. Manufacturing facilities in Germany and South Korea deploy Wi-Fi 6E for AGV coordination, though range limitations constrain outdoor applications.
- Cellular:Wide-area coverage through licensed spectrum with guaranteed quality of service. 5G time-sensitive networking rewrites factory floor standards in South Korean automotive plants, enabling deterministic wireless for robotic coordination.
- LPWAN:Low-power wide-area protocols for intermittent data transmission across extended ranges. FCC Part 15 rules govern unlicensed LPWAN deployment in US logistics networks, lowering connectivity costs for pallet and container tracking.
- Zigbee:Mesh networking for building automation and smart home ecosystems. ETSI harmonization with EU Cyber Resilience Act baseline security standards forces firmware update mechanisms into initial product specifications.
Cellular connections dominate revenue value; LPWAN is expanding most quickly in asset tracking applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's Special Investment Region program and Shenzhen's Qianhai Economic Zone concentrate electronics manufacturing infrastructure that feeds sensor module production. Germany's Industrie 4.0 tax incentives and South Korea's smart city special districts accelerate deployment velocity. These policy-driven concentrations reshape procurement geography for connected systems.
United States
Automotive plants in Michigan and Tennessee deploy predictive maintenance sensor networks at scale. FCC Part 15 spectrum rules govern unlicensed LPWAN protocols for logistics asset tracking. Silicon Valley clusters anchor edge AI chip design while Boston's Route 128 corridor concentrates medical device IoT development under FDA cybersecurity guidance.
Germany
Bavarian automotive assembly lines and Baden-Württemberg machine tool builders drive industrial IoT spending. EU AI Act compliance mandates embed firmware update capabilities into hardware specifications. The Stuttgart manufacturing belt deploys deterministic wireless for robotic coordination under METI-aligned data sovereignty protocols.
China
MIIT smart manufacturing directives accelerate sensor deployment across Yangtze River Delta electronics corridors. Shenzhen's Qianhai zone concentrates module fabrication while Beijing-Tianjin-Hebei clusters anchor cloud platform development. GB standards harmonization with cybersecurity baselines extends product certification timelines for European market entry.
Japan
Chubu region automotive plants and Kansai electronics assembly lines deploy time-sensitive networking for quality control. METI industrial security guidelines block cloud data egress, forcing on-premise edge architectures. Nagoya manufacturing clusters integrate live sensor streams with physics-based digital twins for process optimization.
South Korea
Seoul Capital Area smart city infrastructure and Busan-Ulsan automotive corridors drive 5G RedCap adoption. Government digitalization programs mandate deterministic wireless for factory floor robotic coordination. Daegu-Gyeongbuk clusters deploy sub-50-millisecond edge nodes for real-time control loops in electronics manufacturing.
Internet of Things (IoT) Market Vendor Landscape
Top-tier vendors anchor platform and cloud infrastructure layers, while specialized hardware fabricators occupy mid-tier positions with concentrated geographic footprints. The vendor base stratifies across three functional tiers: hyperscale cloud providers, industrial automation incumbents, and connectivity module specialists. Strategic archetypes include vertically integrated automation platforms, cloud-native IoT service stacks, and regional infrastructure champions navigating export restrictions. Competitive moves center on edge computing acquisitions and cross-border certification partnerships.
Within the cloud infrastructure tier, Amazon Web Services and Microsoft exemplify platform-scale deployment models, while Siemens occupies a position representing industrial automation incumbents with embedded edge analytics capabilities. These anchors illustrate divergent strategic vectors: hyperscale elasticity versus factory-floor deterministic performance. Regional specialists like Huawei Technologies sit within geopolitically constrained market segments, sustaining Asia-Pacific infrastructure dominance through captive supply chains. The competitive dynamic hinges on latency architecture choices and regulatory compliance breadth rather than price positioning alone.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| Cisco Systems |
| IBM |
| Intel |
| Huawei Technologies |
| Siemens |
| PTC |
| Others |
Supply Flow & Price Mechanics
EU AI Act firmware update mandates are compressing hardware design cycles and forcing procurement teams toward pre-certified platform modules, which concentrates supplier power among vendors with established CE marking pathways and widens price spreads between compliant and non-compliant tiers.
Pricing Analysis
Lead-time premiums dominate IoT hardware transactions, with automotive OEMs in Germany paying substantial markups for sub-10-week delivery of edge AI gateways while logistics operators capture spot discounts on surplus LPWAN module inventory. Three-tier pricing structure across premium, standard, and economy levels separates CE-RED certified industrial units from uncertified development kits and consumer-grade sensors. Pricing pressure stems from 5G RedCap chipset cost volatility, which constrains margins in agricultural monitoring segments. Transportation fleet operators exhibit highest price sensitivity due to thin logistics margins, whereas healthcare device manufacturers absorb premiums for FDA-cleared security-integrated platforms.
Supply Chain Analysis
Edge AI chip fabrication rests on Taiwan-based foundry capacity, with advanced node production concentrated alongside South Korean memory suppliers and Japanese specialty substrate producers. Raw material dependencies span silicon wafers, rare earth magnets for sensor actuators, and high-purity copper for antenna substrates. Single-source vulnerability in EUV lithography equipment exposes hardware vendors to geopolitical disruption risk. Distribution runs through Shenzhen module aggregators for Asia-Pacific volume, while European machine builders source direct from Stuttgart and Munich automation distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around platform-scale vendors with certification breadth, as EU Cyber Resilience Act compliance timelines force mid-scale hardware specialists into distressed exits or acquisition.
For Market Incumbents: Extend firmware update service revenue through long-term device management contracts, locking in automotive OEM relationships before NIS2 Directive procurement mandates accelerate. Acquire edge AI chip design teams in South Korea to secure deterministic wireless capabilities for robotic coordination applications. Backward integration into Taiwan foundry partnerships reduces exposure to single-source wafer supply. For New Entrants and Emerging Players: Begin with India industrial corridor deployments under PLI scheme incentives, where greenfield electronics manufacturing lacks incumbent platform relationships. Target precision agriculture monitoring as the most penetrable segment, where LTE-M fallback acceptance overrides 5G RedCap cost barriers. Pursue outcome-based equipment contracting with German machine builders shifting from capital sales to per-output pricing. For Investors and Strategic Acquirers: Re-rating potential sits with edge-native AI inference specialists given automotive plant demand for sub-50-millisecond control loops. Long-term viability favors vendors with simultaneous FCC, CE, and MIC certification capacity spanning the full projection horizon. Watch NIS2 Directive enforcement variance across EU member states as the inflection signal for security gateway procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Chip Design Acquisition | Secures deterministic wireless capabilities for South Korean automotive robotic coordination deployments. |
| EU Cyber Resilience Act Pre-Certification | Compresses product launch timelines by 8-14 months versus custom hardware development cycles. |
| India PLI Scheme Manufacturing Footprint | Captures greenfield electronics corridor demand without incumbent platform entrenchment. |
| Outcome-Based Equipment Contracting | Aligns revenue with German machine builder shifts from capital sales to per-output pricing. |
| NIS2 Directive Security Gateway Development | Positions for critical infrastructure operator mandates across EU member state procurement. |
Methodological Framework
Independent corroboration across plant engineer interviews, OEM procurement team discussions, and regulatory affairs director consultations underwrites the qualitative findings. Primary fieldwork engaged automation platform architects, LPWAN network operators, and medical device cybersecurity leads. Secondary validation drew from FCC Part 15 rulemakings, EU AI Act implementation guidance, METI industrial security circulars, and SEC filings of listed automation vendors. Bottom-up device shipment estimates triangulated against top-down cloud platform revenue disclosures.
Comparable-period anchoring tied projection models to historical industrial automation spending cycles and cellular module adoption curves. Segmentation dimensions spanned deployment architecture, solution stack layer, connectivity protocol, and end-use vertical intensity. CAGRs derived from elasticity-adjusted penetration rates across manufacturing, healthcare, and transportation verticals. Forecast inputs incorporated foundry capacity expansion announcements and spectrum allocation timelines from national regulators.
Underlying measurement precision varies by segment; cloud platform revenue carries tighter precision than edge hardware unit estimates given disclosure practices. Forecasts reflect assumptions about regulatory enforcement timing and semiconductor supply normalization. Geopolitical disruption to Taiwan foundry operations and EU AI Act implementation variance warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT Development Kit Market
Internet of Things (IoT)
5G Internet of Things Market
Internet of Things (IoT)
LPWAN in the Consumer IoT Market
Internet of Things (IoT)
IoT at Workplace Market
Internet of Things (IoT)
IoT in Chemical Industry Market
Internet of Things (IoT)
IoT Operating System Market
Internet of Things (IoT)
Airline IoT Market
Internet of Things (IoT)
Internet of Things (IoT) in Utilities Market
Internet of Things (IoT)
Smart Pool Systems Market
Internet of Things (IoT)
Narrowband-Internet of Things (NB-IoT) Market
Internet of Things (IoT)
Europe IoT Services Market
Internet of Things (IoT)
Smart Tracker Market
Internet of Things (IoT)
Private Narrowband IoT Market
Internet of Things (IoT)
Global Military IoT Market
Internet of Things (IoT)
Bluetooth Smart Plugs Market
Internet of Things (IoT)
North America IoT Software Market