
 Global 5G Industrial IOT Market | 2026-2036
Global 5G Industrial IOT Market Size, Share, and Industry Trends Forecast 2026-2036
Global 5G Industrial IOT Market Foresight
Automotive OEM demand is shifting toward predictive maintenance and real-time quality control systems that require sub-10 millisecond latency. Qualcomm Technologies leverages its modem-RF system leadership to anchor premium chipset supply for industrial gateways. Siemens competes through its private 5G network deployments integrated with factory automation software. Huawei Technologies dominates radio access infrastructure across Asian manufacturing corridors despite Western market restrictions.
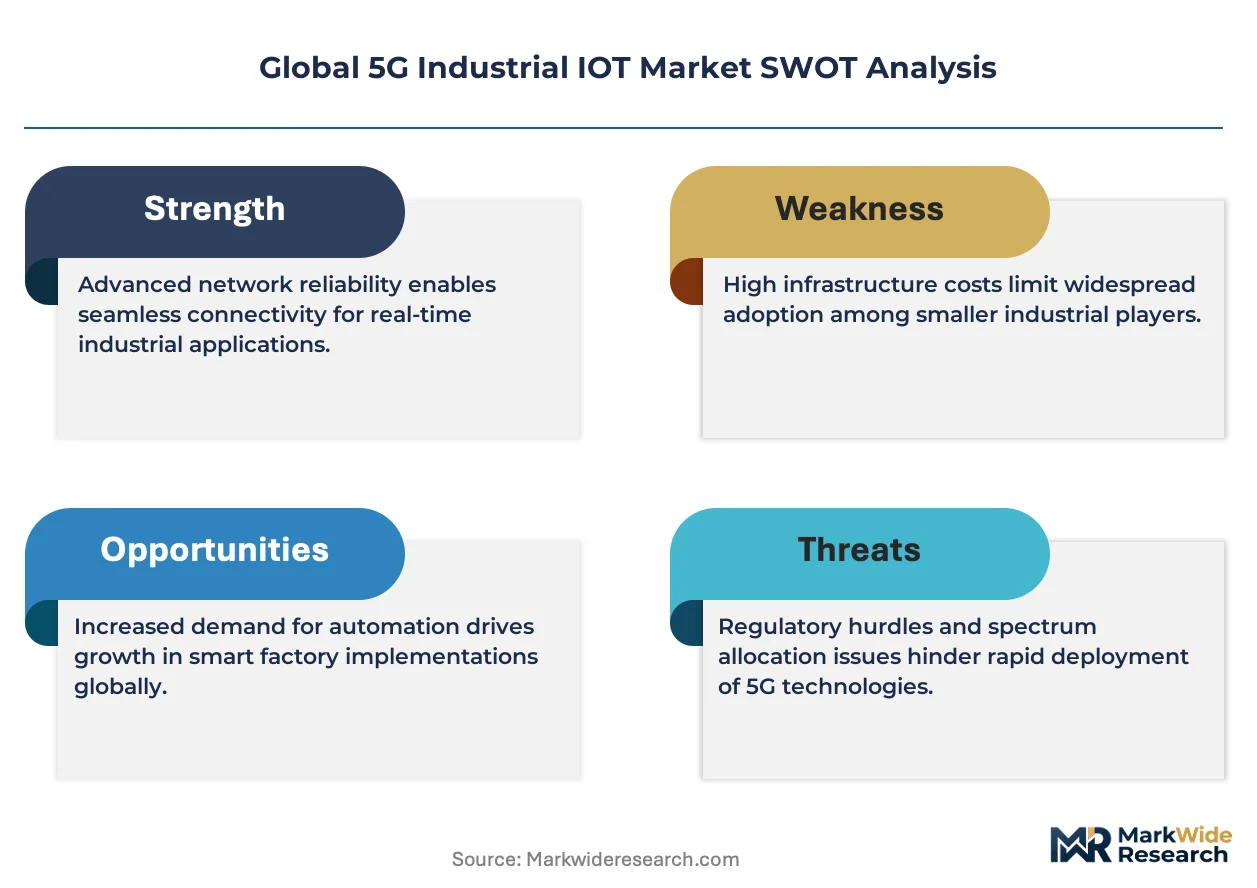
5G Industrial IOT denotes the deployment of ultra-reliable low-latency communication infrastructure connecting sensors, edge devices, and cloud platforms within operational technology environments, typically operating in sub-6 GHz and millimeter-wave spectrum bands with 99.999% reliability targets. Network slicing allows manufacturers to partition bandwidth between safety-critical robotics and non-essential monitoring streams on shared infrastructure. Edge Devices and Gateways capture the dominant hardware margin pool as data preprocessing requirements intensify. Predictive Maintenance applications expand fastest among the application set as unplanned downtime costs drive sensor density on rotating equipment. Massive MIMO technology leads the technology segmentation due to its spectral efficiency gains in dense factory floor deployments.
The FCC governs spectrum auctions and device certification timelines that determine when industrial frequencies become commercially accessible in the United States. ETSI and 3GPP standards bodies in Europe shape interoperability mandates that equipment vendors must satisfy for CE marking and cross-border deployment. China's MIIT enforces domestic security protocols and GB standards that influence product architecture decisions for vendors serving Chinese state-owned enterprises. Stakeholders must monitor evolving national security screening regimes that restrict vendor eligibility for critical infrastructure contracts across multiple jurisdictions.
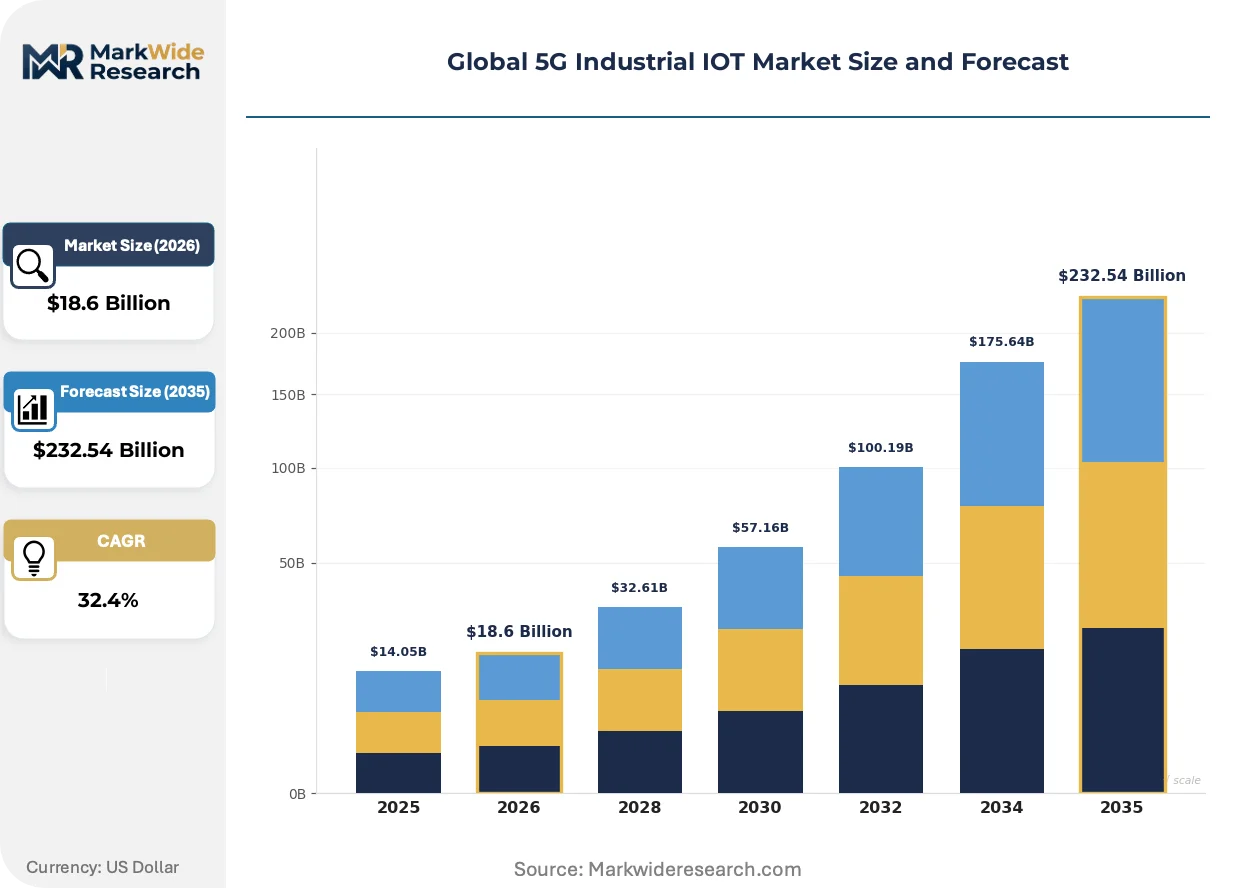
Market Dynamics
Network slicing is compressing deployment timelines for manufacturers seeking to partition safety-critical robotics traffic from non-essential monitoring streams on shared 5G infrastructure.
Growth Catalysts
- EU AI Act compliance mandates:European manufacturers accelerate edge AI deployments to satisfy algorithmic transparency requirements for automated quality control systems.
- Automotive OEM predictive maintenance:German and South Korean vehicle producers expand sensor density on rotating equipment to eliminate unplanned downtime costs.
- Millimeter-wave spectrum allocation:The FCC's industrial frequency auctions unlock sub-10 millisecond latency capabilities for real-time robotic coordination.
Market Restraints
- Radio access equipment supply concentration:Asian manufacturing corridors depend on a narrowing vendor base for massive MIMO antenna arrays.
- GB standards compliance costs:China's MIIT domestic security protocols force architectural redesigns for multinational equipment suppliers.
- Legacy OT-IT integration friction:Brownfield factories face protocol translation complexity between decades-old SCADA systems and 5G-native architectures.
Strategic Opportunities
- Private 5G network deployment in India:TRAI's enterprise spectrum liberalization creates white space for captive industrial networks outside licensed operator frameworks.
- Edge gateway data preprocessing:Intensifying computational demands at the factory floor level expand hardware margin pools for specialized gateway vendors.
- ISO/IEC 27001 convergence:Unified cybersecurity certification frameworks reduce duplication costs for multi-jurisdictional industrial IoT deployments.
Industry Challenges
- Multi-vendor interoperability testing:ETSI and 3GPP standards implementation gaps create certification bottlenecks before CE marking approval.
- Radio frequency engineering talent scarcity:Millimeter-wave propagation expertise concentrates among a limited pool of specialists in Germany, China, and South Korea.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 5G Industrial IOT Market |
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $232.54 Billion |
| CAGR (2026 – 2036) | 32.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Edge Devices, Sensors, Gateways, Routers, Modems Technology: Massive MIMO, Beamforming, Network Slicing, Low Latency Communications, Enhanced Mobile Broadband Application: Smart Manufacturing, Predictive Maintenance, Supply Chain Automation, Quality Control, Asset Tracking End User: Automotive OEMs, Energy Producers, Aerospace Firms, Agricultural Tech Companies, Mining Operators |
| Companies Covered | Huawei Technologies, Ericsson, Nokia Corporation, Qualcomm Technologies, Cisco Systems, Siemens, AT&T, Samsung Electronics, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 5G Industrial IOT Market Shifts & Advancements
Three forces are restructuring competitive positioning: silicon integration is compressing gateway form factors, spectrum policy is redrawing vendor eligibility, and procurement accountability is shifting from capital expenditure to operational outcome metrics.
Integrated modem-RF systems are electrifying industrial gateway design by collapsing discrete component stacks into single-chip solutions. Automotive OEMs and energy producers in Germany and South Korea are transitioning procurement specifications toward these consolidated architectures. Component consolidation is compressing bill-of-materials costs while accelerating time-to-deployment for private network rollouts.
The EU AI Act is mandating algorithmic audit trails for automated decision systems deployed in safety-critical manufacturing environments. European industrial software vendors are embedding explainability modules into edge AI inference engines to satisfy conformity assessment requirements. German automotive clusters face the steepest compliance burden due to dense concentrations of robotic welding and painting automation.
Buyer accountability structures are migrating from capital expenditure ownership to guaranteed uptime service agreements. Energy producers and process manufacturers in South Korea now contract private 5G network performance on availability-based pricing rather than infrastructure procurement. This shift is displacing traditional system integrator relationships with long-term operational partnerships anchored in service-level guarantees.
Global 5G Industrial IOT Market Segmentation
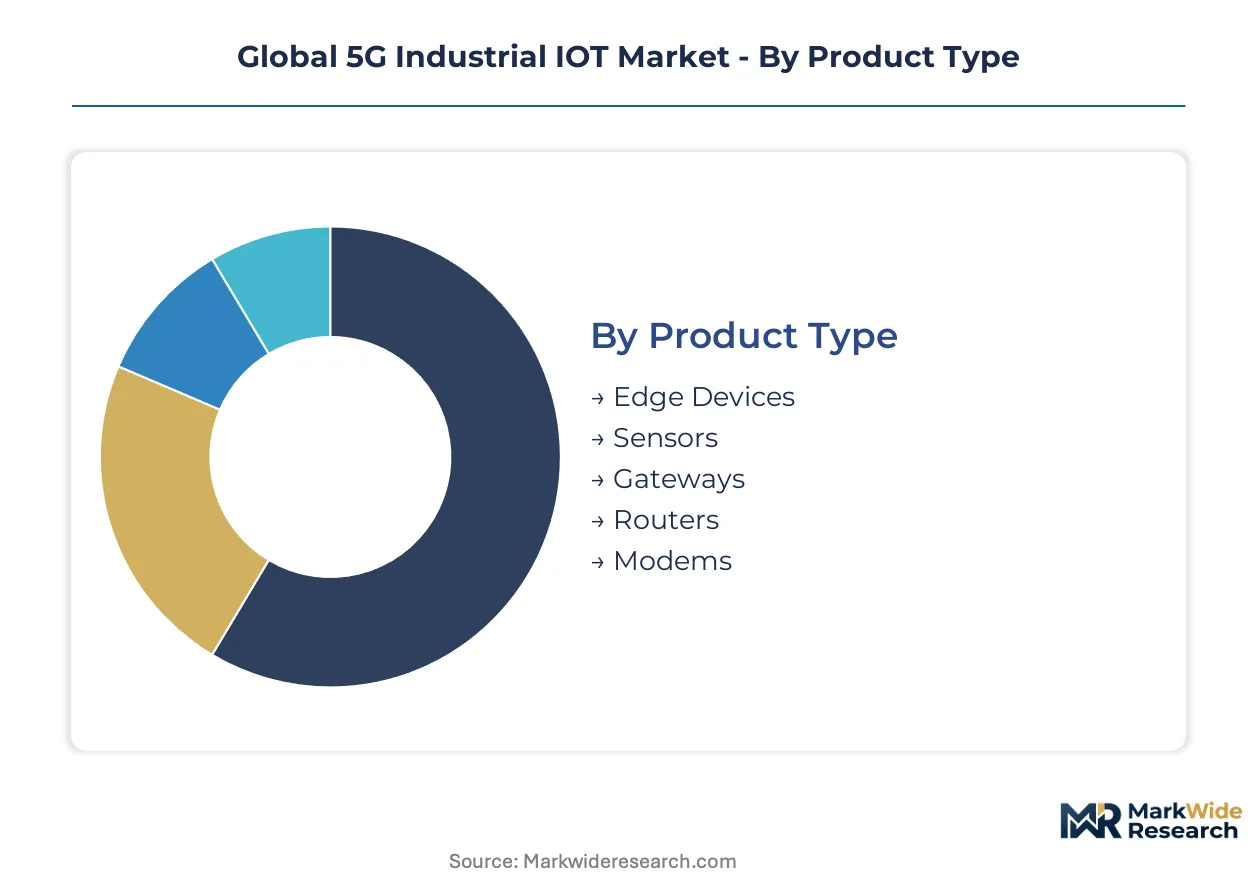
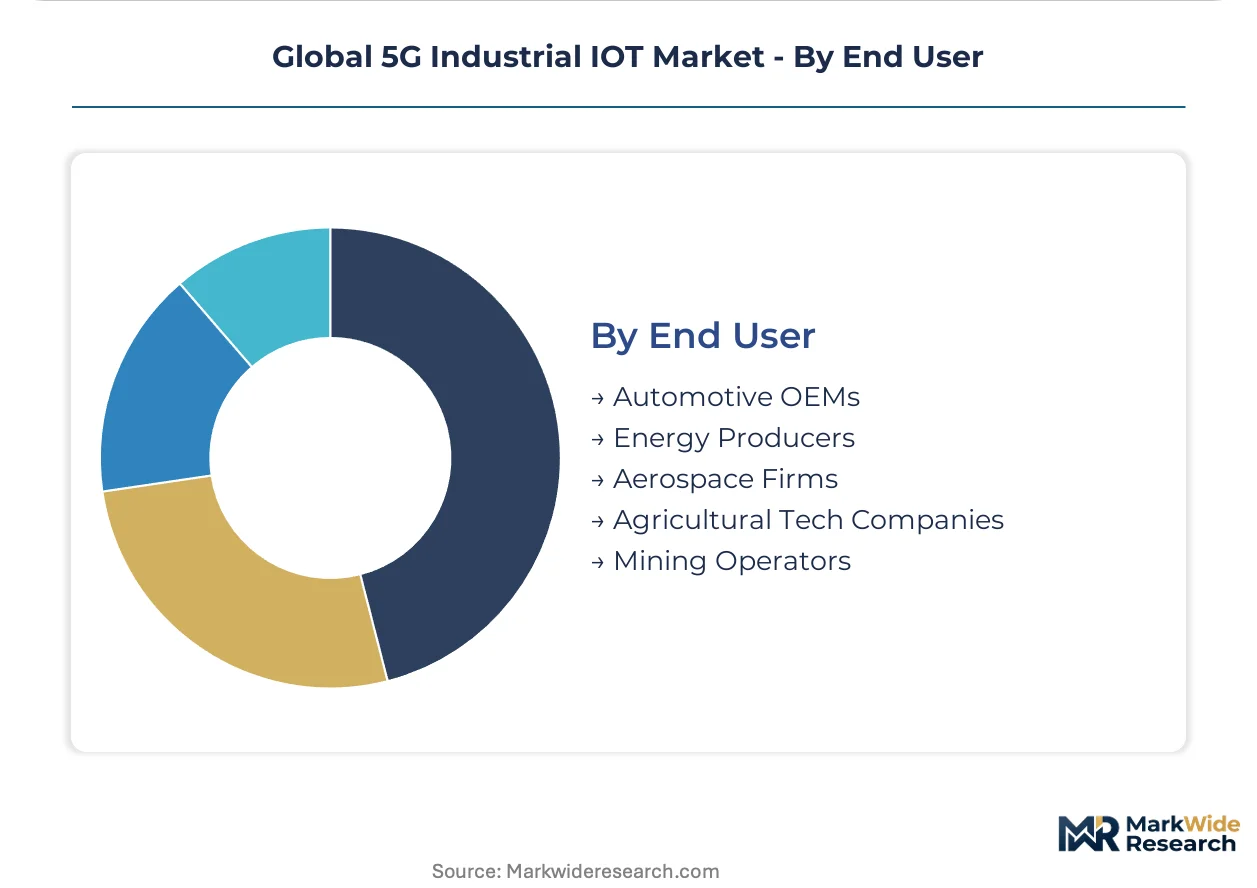
5G Industrial IoT segmentation reveals how hardware form factors, radio technologies, and operational use cases align with distinct procurement budgets and deployment timelines. Upgrade cycles vary dramatically between brownfield sensor retrofits and greenfield private network builds.
Product Type:
Replacement cycles for industrial connectivity hardware are compressing as integrated modem-RF architectures displace multi-component gateway designs.
- Edge Devices:These units perform local data preprocessing and protocol translation between OT sensors and 5G radios. German automotive OEMs and South Korean energy producers are driving demand for ruggedized edge computers capable of running AI inference engines for real-time quality control.
- Gateways:Industrial-grade gateways aggregate sensor streams and manage network slicing policies at the factory floor level. Procurement is concentrating among mining operators in Australia and process manufacturers in Saudi Arabia seeking to partition safety-critical traffic from monitoring data on shared infrastructure.
- Sensors:Vibration, temperature, and pressure sensors with embedded 5G modems eliminate wiring complexity in rotating equipment monitoring.
- Routers:These devices provide backhaul connectivity between private 5G cores and enterprise WANs.
- Modems:Standalone cellular modems serve retrofit applications where existing industrial PCs require connectivity upgrades.
Gateways sit at the top of the volume ranking, with Edge Devices climbing the fastest.
Technology:
Technology selection follows spectrum availability and latency requirements, with millimeter-wave capabilities commanding premium positioning.
- Massive MIMO:This antenna architecture deploys hundreds of radiating elements to achieve spectral efficiency in dense factory environments. China's MIIT has prioritized massive MIMO infrastructure across state-owned manufacturing corridors, while Germany's industrial clusters leverage the technology for high-density robotic coordination.
- Network Slicing:Virtual network partitioning allows manufacturers to guarantee bandwidth for safety systems while sharing physical infrastructure. The EU AI Act is accelerating slicing deployments among French and Italian automotive suppliers needing isolated lanes for algorithmic audit trails.
- Beamforming:Directional signal focusing extends millimeter-wave coverage in obstructed industrial settings.
- Low Latency Communications:URLLC protocols target sub-10 millisecond response times for closed-loop control systems.
- Enhanced Mobile Broadband:eMBB supports high-bandwidth applications including augmented reality maintenance guidance.
Massive MIMO dominates current deployment value, though Network Slicing is gaining share fastest among new installations.
Application:
Application prioritization reflects unplanned downtime costs, with high-asset industries leading sensor density investments.
- Predictive Maintenance:Vibration and thermal monitoring of rotating equipment prevents catastrophic failures in continuous-process industries. Energy producers in Texas and chemical manufacturers in the Netherlands are expanding sensor density on compressors and pumps to eliminate unplanned shutdowns.
- Smart Manufacturing:Integrated 5G connectivity enables flexible production lines with mobile robots and wireless programmable logic controllers. South Korean electronics assemblers and German automotive OEMs are retrofitting brownfield facilities with private 5G to avoid production halts during reconfiguration.
- Supply Chain Automation:Real-time inventory tracking and autonomous vehicle coordination optimize logistics throughput.
- Quality Control:Machine vision systems with 5G backhaul enable sub-millimeter defect detection at production speeds.
- Asset Tracking:Indoor positioning systems locate tools, work-in-progress inventory, and personnel across sprawling industrial campuses.
Predictive Maintenance commands the largest implementation budget, while Smart Manufacturing shows the steepest expansion trajectory.
End User:
End-user investment intensity correlates with asset criticality and regulatory pressure for operational transparency.
- Automotive OEMs:Vehicle manufacturers deploy private 5G for robotic welding coordination and paint shop automation. German producers face the steepest EU AI Act compliance burdens for algorithmic decision systems in safety-critical environments.
- Energy Producers:Power utilities and oil & gas operators monitor distributed generation assets and pipeline infrastructure. Saudi Aramco and Texas-based independent producers are contracting availability-based service agreements rather than capital procurement for network infrastructure.
- Aerospace Firms:Defense and commercial aviation manufacturers track tooling and enforce digital thread compliance.
- Mining Operators:Open-pit and underground extraction sites deploy 5G for autonomous haulage and remote equipment operation.
- Agricultural Tech Companies:Precision farming operations utilize 5G for autonomous machinery and livestock monitoring.
Automotive OEMs anchor current spending levels, with Energy Producers expanding most quickly through outcome-based contracting models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive clusters anchor industrial 5G deployment intensity. Regulatory frameworks and spectrum policy across multiple jurisdictions are compressing deployment timelines for private network rollouts.
United States
Texas energy producers and California electronics assemblers drive private 5G procurement for predictive maintenance and flexible manufacturing. The FCC's industrial frequency auctions in the 3.5 GHz CBRS band and millimeter-wave spectrum unlock sub-10 millisecond latency capabilities. Houston's petrochemical corridor contracts availability-based service agreements rather than capital procurement for network infrastructure.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg expand sensor density on robotic welding equipment to eliminate unplanned downtime. The EU AI Act mandates algorithmic audit trails for automated quality control systems, accelerating edge AI deployments. Stuttgart's manufacturing cluster faces the steepest compliance burden due to dense concentrations of safety-critical automation.
China
State-owned manufacturing corridors in the Yangtze River Delta and Pearl River Delta prioritize massive MIMO infrastructure for high-density robotic coordination. The MIIT enforces domestic security protocols and GB standards that influence product architecture decisions. Shenzhen's electronics assemblers retrofit brownfield facilities with private 5G to avoid production halts during reconfiguration.
South Korea
Electronics manufacturers and energy producers in the Seoul Capital Area transition procurement specifications toward integrated modem-RF architectures. Government-backed 5G testbeds have matured industrial automation clusters with sub-6 GHz and millimeter-wave deployment. Busan-Ulsan's shipbuilding and petrochemical complexes contract private network performance on availability-based pricing models.
India
Process manufacturers in Maharashtra and Gujarat seek captive industrial networks outside licensed operator frameworks. TRAI's enterprise spectrum liberalization creates white space for private 5G deployment. The Pune industrial corridor attracts specialized gateway vendors expanding hardware margin pools through edge data preprocessing capabilities.
Global 5G Industrial IOT Market Competitive Landscape
Strategic partnerships dominate the current landscape as equipment vendors align with systems integrators and cloud platforms. The vendor base concentrates around three tiers: integrated infrastructure providers, specialized component suppliers, and telecom operators with enterprise service arms. Two archetypes define competitive positioning — modem-RF system leaders anchoring premium chipset supply, and automation software vendors bundling private network deployments. M&A activity and spectrum policy lobbying represent the dominant competitive moves as players secure industrial frequency access across jurisdictions.
Within the integrated infrastructure tier, Huawei Technologies and Nokia Corporation exemplify contrasting geographic positioning strategies. Qualcomm Technologies occupies a distinctive position anchoring premium chipset supply for industrial gateways through modem-RF system leadership. Siemens represents the automation-software-bundling archetype, competing through private 5G network deployments integrated with factory automation platforms. These three anchors illustrate how vendor eligibility for critical infrastructure contracts varies across national security screening regimes.
| Leading Market Players |
|---|
| Huawei Technologies |
| Ericsson |
| Nokia Corporation |
| Qualcomm Technologies |
| Cisco Systems |
| Siemens |
| AT&T |
| Samsung Electronics |
| ABB |
| Others |
Supply & Pricing Matrix
Integrated modem-RF system adoption is collapsing gateway bill-of-materials costs while compressing supplier tiers toward semiconductor foundries in Taiwan and South Korea. This silicon consolidation simultaneously reduces unit economics for buyers and concentrates upstream pricing power among RF component specialists.
Pricing Analysis
Input-cost pass-through from gallium nitride substrate shortages and advanced packaging capacity constraints shapes tiered pricing across gateway hardware. Three-tier pricing structure across premium, standard, and economy levels separates URLLC-certified industrial units from commercial-grade alternatives. Cost compression in the economy tier is intensifying because Chinese gateway vendors are absorbing margin erosion to secure volume contracts with state-owned enterprises. Automotive OEMs in Germany exhibit the least price sensitivity due to downtime cost exposure, while Indian process manufacturers demonstrate acute budget constraints.
Supply Chain Analysis
Massive MIMO antenna array supply rests on Japanese specialty chemical producers for high-frequency laminates and Taiwanese substrate manufacturers for RF front-end modules. Raw material dependencies span gallium arsenide wafers, ceramic filter substrates, and millimeter-wave connector assemblies. Single-source vulnerability concentrates in 28 GHz beamforming chipsets where Qualcomm Technologies anchors global supply. Distribution runs through authorized industrial automation distributors in Germany, direct enterprise contracts in China, and systems integrator partnerships in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in 5G Industrial IoT hardware hinges on silicon integration economics displacing discrete component stacks, while premium-tier demand concentrates among German automotive clusters facing EU AI Act compliance deadlines.
For Market Incumbents: Cement modem-RF system leadership through captive supply of millimeter-wave front-end modules, insulating against emerging Chinese gateway vendors capturing price-sensitive segments in India and Southeast Asia. Prioritize certification investment for EU AI Act algorithmic audit trail requirements to defend premium positioning in Stuttgart and Munich manufacturing corridors. For New Entrants and Emerging Players: TRAI's enterprise spectrum liberalization in India opens a window for specialized gateway vendors targeting Maharashtra process manufacturers seeking captive networks outside licensed operator frameworks. Focus white-space entry on edge data preprocessing hardware for brownfield retrofit applications, leveraging outcome-based contracting models to bypass incumbent system integrator relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among industrial automation software vendors lacking private 5G network deployment capabilities. Long-term viability centers on convergence between OT software platforms and radio infrastructure ownership. Watch for FCC industrial frequency auction timing as inflection signal for North American gateway hardware demand.| Strategic Initiative | Industry Significance |
|---|---|
| Modem-RF System Integration | Single-chip architectures collapse gateway form factors for German automotive OEMs. |
| Private 5G Network Deployment | Siemens leverages factory automation software bundling across Bavarian manufacturing clusters. |
| Edge Gateway Data Preprocessing | AI inference capabilities expand hardware margins for South Korean energy producers. |
| EU AI Act Compliance Certification | Algorithmic audit trail modules satisfy conformity assessment for robotic welding automation. |
| Millimeter-Wave Spectrum Acquisition | FCC industrial frequency access unlocks sub-10 millisecond latency for Texas petrochemical corridors. |
Research Methodology
Coverage spans Germany, China, South Korea, the United States, and India, with primary inputs from each market gathered through structured interviews with private 5G network deployment directors, industrial automation procurement leads, RF engineering specialists, and regulatory affairs managers at equipment vendors. Secondary validation draws from FCC spectrum auction records, ETSI standardization documents, MIIT GB standard filings, 3GPP release documentation, and customs trade data for industrial gateway hardware. Bottom-up unit shipment estimates triangulate against top-down infrastructure investment forecasts.
Granularity-level modeling distinguishes product type, technology architecture, application use case, and end-user industry across the projection horizon. Segment-level CAGRs derive from deployment timeline assumptions, replacement cycle compression, and regulatory compliance deadlines. Industry-specific forecast inputs include private network spectrum allocation schedules, EU AI Act implementation phases, and brownfield retrofit penetration rates in German automotive facilities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged semiconductor supply constraints or accelerated national security screening regimes restricting vendor eligibility. Assumptions reflect current regulatory trajectories for spectrum policy and data governance. A small set of named triggers warrants ongoing watch: FCC millimeter-wave auction timing, MIIT domestic security protocol enforcement, and EU AI Act conformity assessment body accreditation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Internet of Things (IoT) Market
Internet of Things (IoT)
Smart Sprinkler Controller Market
Internet of Things (IoT)
Lora and Lorawan IoT Connectivity Market
Internet of Things (IoT)
North America Industrial IoT Market
Internet of Things (IoT)
North America IoT Software Market
Internet of Things (IoT)
IoT Network Management Market
Internet of Things (IoT)
Internet of Things (IoT) in Healthcare Market
Internet of Things (IoT)
Middle East and Africa IoT Node and Gateway Market
Internet of Things (IoT)
Smart Home M2M Market
Internet of Things (IoT)
IOT in Aviation Market
Internet of Things (IoT)
Industrial IoT Market
Internet of Things (IoT)
IoT Cloud Platform Market
Internet of Things (IoT)
IoT Market
Internet of Things (IoT)
IoT Operating System Market
Internet of Things (IoT)
UK IoT Software Market
Internet of Things (IoT)
Europe Industrial IoT Market