
 North America IoT Node and Gateway Market | 2026-2036
North America IoT Node and Gateway Market Size, Share, and Industry Trends Forecast 2026-2036
North America IoT Node and Gateway Market Analytics
Smart manufacturing is recalibrating the North America IoT Node and Gateway Market as automotive and aerospace OEMs shift from cloud-centric to edge-heavy architectures. Cisco Systems leverages its networking heritage to dominate industrial gateway deployments with hardened security stacks. Intel Corporation anchors the semiconductor layer with x86-based edge processors purpose-built for real-time analytics. NXP Semiconductors specializes in automotive-grade connectivity modules that sustain long lifecycle commitments from Detroit and Stuttgart transplant suppliers.
IoT nodes and gateways are physical compute and communication endpoints that aggregate sensor telemetry, execute local preprocessing, and bridge field devices to upstream networks via protocols such as MQTT or OPC-UA over sub-1 GHz or 5 GHz radio bands. Their primary purpose is to reduce latency, bandwidth costs, and cloud dependency in distributed operational environments. Gateway nodes currently occupy the largest margin pool because they bundle processing, storage, and protocol translation in a single hardware layer that commands premium pricing over simpler sensor endpoints. Cellular connectivity is displacing Wi-Fi in remote oilfield and agricultural monitoring applications where terrestrial infrastructure proves unreliable. Edge nodes represent the fastest-expanding category as manufacturers push inferencing closer to vibration, thermal, and vision sensors on production lines.
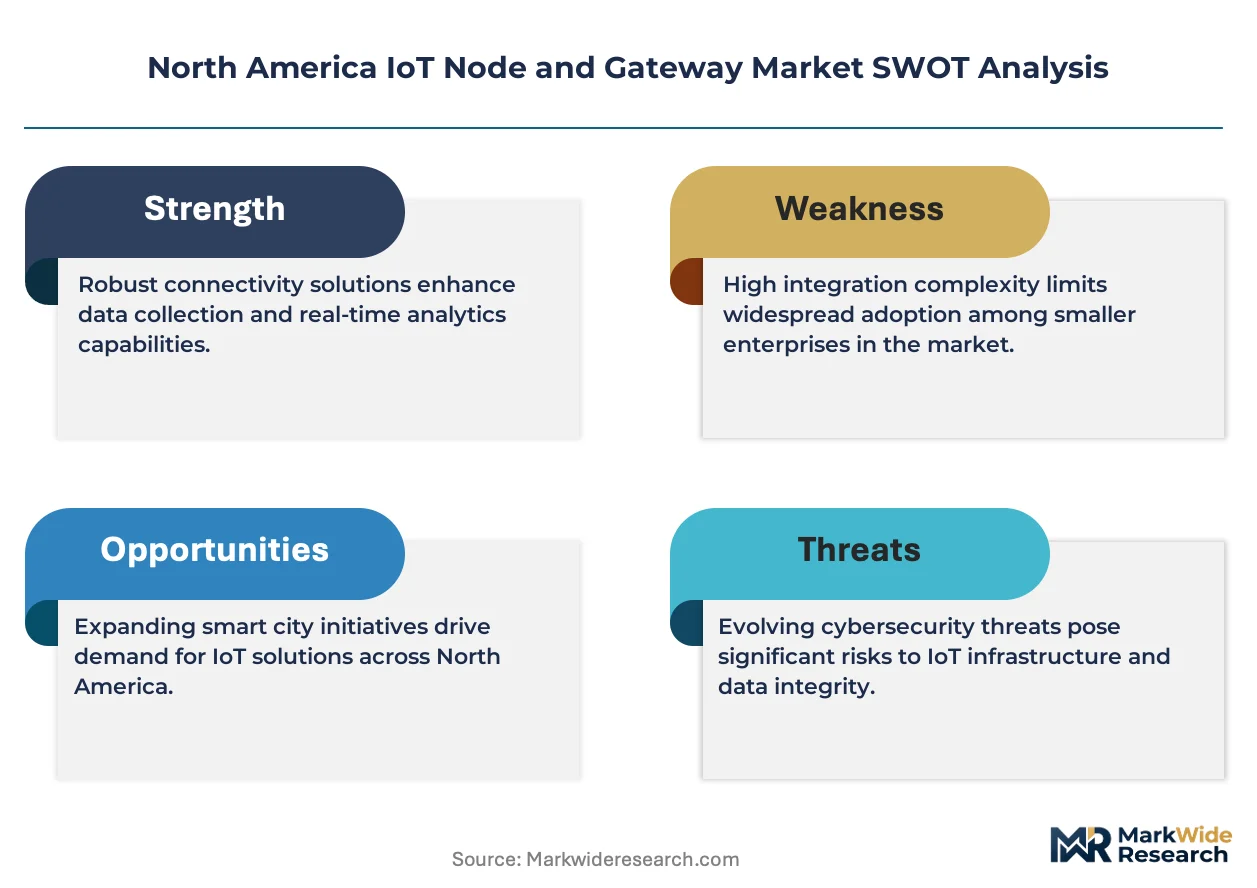
FCC Part 15 rules govern unlicensed spectrum use for Zigbee and LoRaWAN deployments, while NIST cybersecurity frameworks mandate zero-trust architectures for federal IoT procurements. FDA guidance on connected medical devices further shapes healthcare gateway requirements around data integrity and patient safety. Stakeholders must monitor how the US EPA embeds emissions-linked IoT mandates into stationary source permits and whether CSA Group standards harmonize with NIST to unlock cross-border Canadian deployment.
Market Dynamics
Edge computing architectures are compressing decision latency in automotive and aerospace production lines across the US Great Lakes industrial belt, forcing gateway vendors to embed inferencing silicon directly into ruggedized field hardware.
Growth Catalysts
- NIST Cybersecurity Framework:Federal zero-trust mandates for IoT procurements are accelerating security-hardened gateway deployments in defense and critical infrastructure applications.
- Automotive OEM Edge Migration:Detroit-area manufacturers are pushing vision and vibration analytics to factory-floor nodes to reduce cloud round-trip latency below 10 milliseconds.
- FCC Part 15 Spectrum Access:Unlicensed sub-1 GHz allocations enable long-range LoRaWAN sensor networks in remote agricultural and oilfield monitoring without carrier subscription costs.
Market Restraints
- Semiconductor Supply Concentration:Advanced edge processors depend on Taiwan-based foundry capacity, exposing North American gateway manufacturers to geopolitical disruption risk.
- Copper and Lithium Price Volatility:Battery-backed cellular gateways face input cost swings from Chilean lithium carbonate and Chilean-Peruvian copper concentrate markets.
- Legacy Protocol Persistence:Modbus and Profibus installations in aging US industrial plants create friction for OPC-UA native gateway rollouts.
Strategic Opportunities
- Canadian Prairie Agriculture:Saskatchewan and Alberta grain operations remain underpenetrated for soil-moisture and equipment-telemetry cellular gateways.
- 5G Private Network Convergence:Integration of time-sensitive networking with localized 5G cores creates new deployment models for smart manufacturing campuses.
- US EPA Emissions-Linked Permitting:Stationary source monitoring mandates in refinery and chemical plant permits are driving continuous emissions monitoring gateway demand.
Industry Challenges
- Embedded Security Engineering Talent:Shortage of firmware developers with hardware-root-of-trust expertise delays product certification cycles.
- Multi-Agency Certification Overlap:Gateways for medical and automotive applications face simultaneous FDA, FCC, and NHTSA compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America IoT Node and Gateway Market |
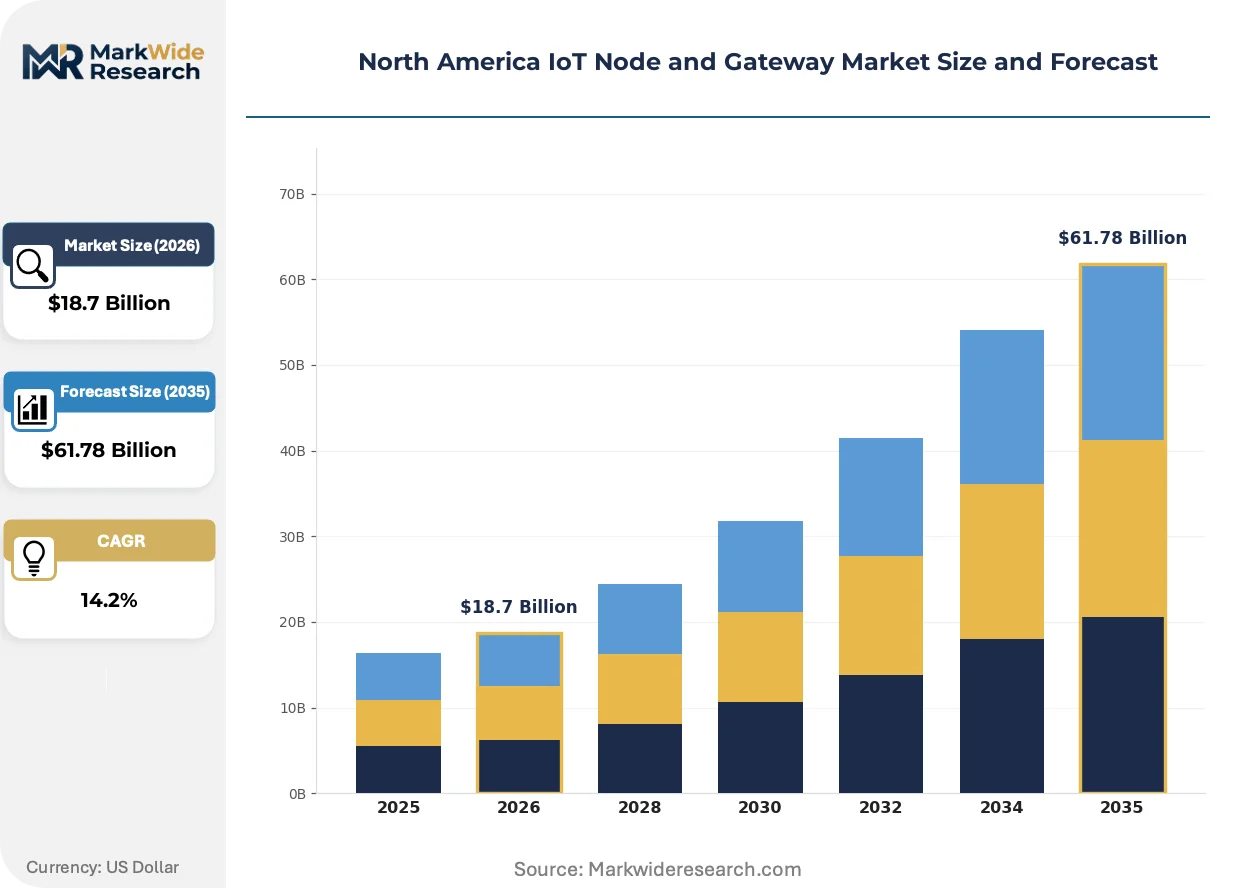
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Node Type: Sensor Nodes, Actuator Nodes, Gateway Nodes, Edge Nodes Connectivity Technology: Wi-Fi, Zigbee, LoRaWAN, Cellular Application Sector: Smart Home, Industrial Automation, Healthcare, Agriculture End User: Consumer Electronics, Commercial, Government, Transportation |
| Companies Covered | Cisco Systems, Inc., Intel Corporation, NXP Semiconductors, Advantech Co., Ltd., Texas Instruments Incorporated, Qualcomm Technologies, Inc., Dell Technologies Inc., STMicroelectronics, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America IoT Node and Gateway Market Evolving Landscape
Hardware-software disaggregation is reshaping how industrial buyers procure and maintain field infrastructure, with containerized workloads now portable across heterogeneous gateway silicon.
Time-sensitive networking over Ethernet is decentralizing motion control and safety systems in automotive assembly plants. Tier-1 suppliers in Ohio and Michigan are deploying TSN-enabled gateways to synchronize robotic welding cells without proprietary fieldbus hardware. This convergence is compressing vendor lock-in and opening socket competition for industrial Ethernet switch silicon.
NIST's zero-trust architecture mandates for federal IoT procurements are forcing gateway firmware redesigns around hardware security modules and attestation protocols. Defense contractors and critical infrastructure operators must now demonstrate continuous device integrity verification. Healthcare gateway vendors face parallel FDA guidance on connected medical device data integrity, creating cross-vertical security engineering investments.
Buyers in the US Great Lakes manufacturing belt are unbundling hardware procurement from software subscription services, treating gateways as capex items while purchasing analytics capabilities as annual licenses. This split separates equipment finance from operational technology budgets, enabling faster refresh cycles for compute-heavy edge nodes without full hardware replacement.
North America IoT Node and Gateway Market Segmentation
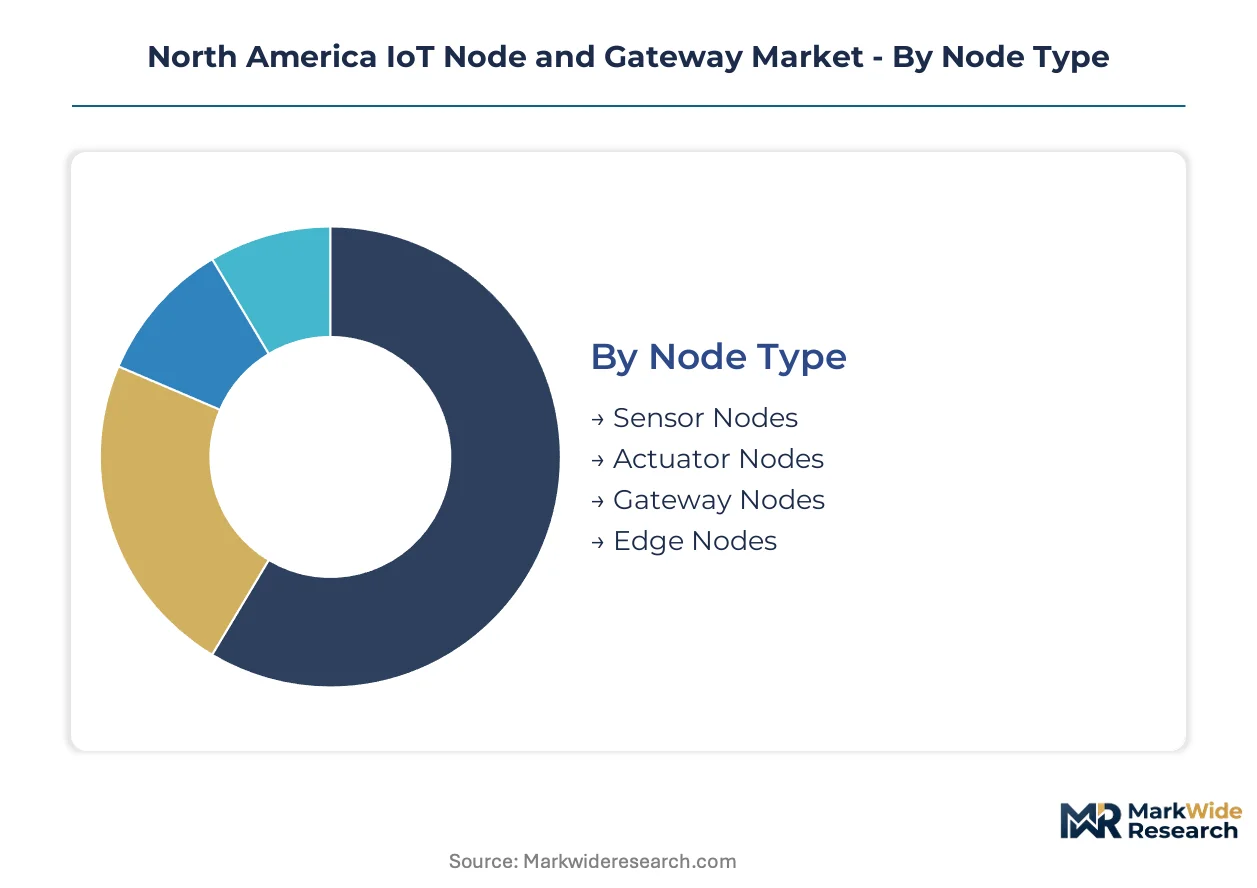
Gateway architectures fragment across power budgets, radio protocols, and processing hierarchies. Procurement teams in the US Great Lakes industrial belt weight ruggedization and FCC certification timelines more heavily than consumer buyers prioritizing cost per node.
Node Type:
Volume concentrates in simple telemetry endpoints, but premium margins pool where preprocessing silicon reduces cloud egress fees.
- Sensor Nodes:Compact, battery-powered devices capturing temperature, vibration, or ambient light data with minimal onboard logic. Michigan automotive plants deploy thousands per facility for predictive maintenance, though battery replacement labor erodes lifetime cost advantages.
- Gateway Nodes:Ruggedized compute platforms bundling protocol translation, local storage, and cellular backhaul in IP67-rated enclosures. These command the highest unit economics in oilfield and agricultural monitoring across Texas and Alberta where terrestrial infrastructure fails.
- Actuator Nodes:Closed-loop control endpoints executing valve adjustments or motor commands based on upstream telemetry.
- Edge Nodes:Inferencing-capable hardware running TensorFlow Lite or ONNX models directly on vibration or vision inputs.
Today's leader: Gateway Nodes. Tomorrow's challenger: Edge Nodes.
Connectivity Technology:
Radio selection hinges on range, penetration, and carrier subscription economics rather than raw throughput.
- Cellular:LTE-M and NB-IoT modules with carrier-agnostic SIM provisioning dominate remote monitoring in Saskatchewan grain operations and Permian Basin oilfields where Wi-Fi backhaul is uneconomical. Module costs have compressed below ten dollars at volume, though recurring data plans shift TCO toward operational budgets.
- LoRaWAN:Sub-gigahertz spread-spectrum protocol enabling ten-kilometer range at milliwatt power draws. Private network deployments accelerate across USDA-monitored agricultural districts where sensor density justifies gateway infrastructure investment.
- Wi-Fi:High-throughput, short-range connectivity saturating smart home and commercial building automation.
- Zigbee:Mesh-native protocol entrenched in lighting and HVAC control systems with proven interoperability stacks.
Cellular holds the installed base. LoRaWAN climbs fastest in greenfield industrial deployments.
Application Sector:
Smart manufacturing and precision agriculture drive hardware refresh cycles, while healthcare and residential segments lag on security certification timelines.
- Industrial Automation:Time-sensitive networking gateways synchronizing robotic welding cells in Ohio and Michigan assembly plants. OPC-UA over TSN is displacing proprietary fieldbus hardware, compressing vendor lock-in and opening socket competition for industrial Ethernet silicon.
- Agriculture:Soil moisture, equipment telemetry, and livestock monitoring across the Canadian Prairies and US Corn Belt. Cellular gateways with solar charging dominate where grid power is unavailable, though LoRaWAN private networks gain traction in large consolidated operations.
- Smart Home:Consumer-grade hubs bridging Zigbee and Z-Wave sensor ecosystems.
- Healthcare:FDA-guided connected medical devices with hardware security module requirements for patient data integrity.
Industrial Automation generates the hardware revenue. Agriculture offers the steepest expansion trajectory.
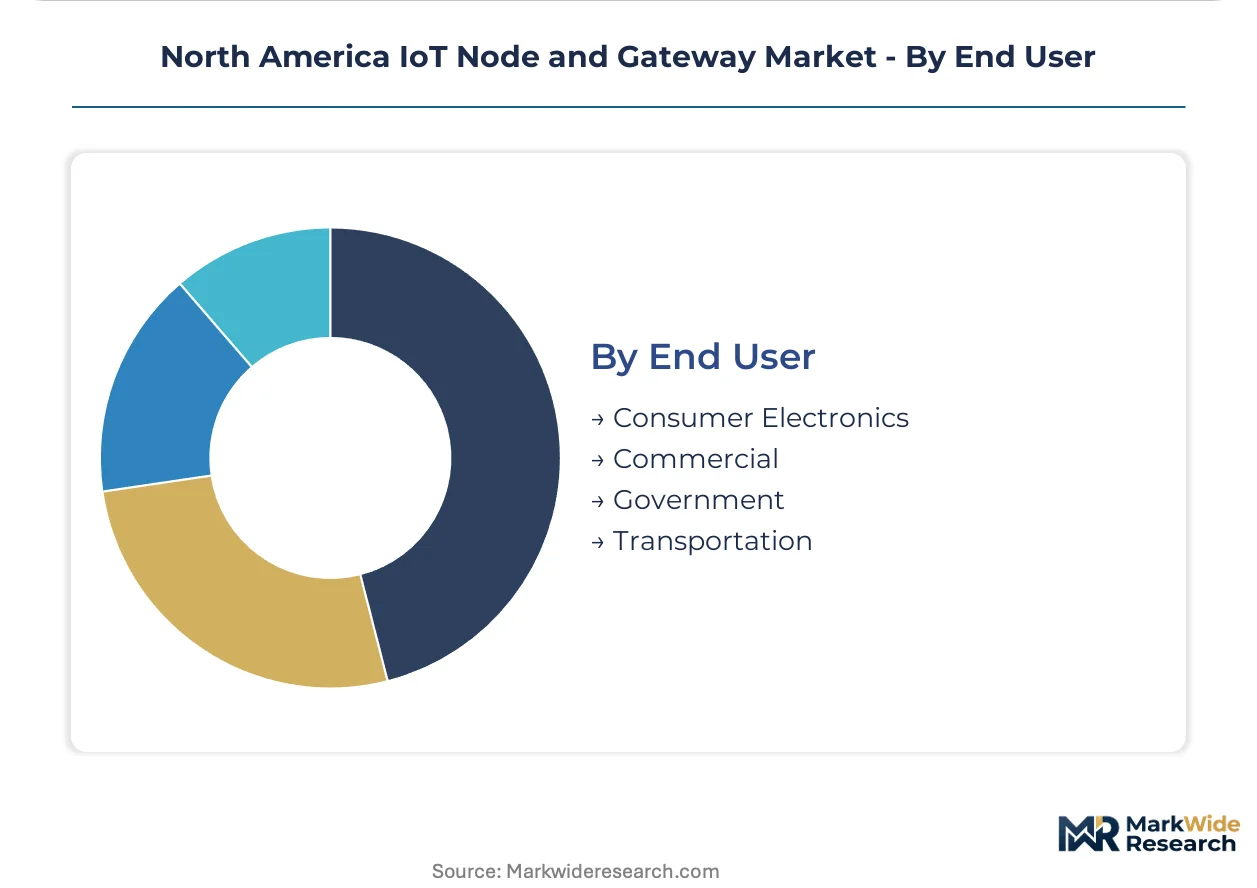
End User:
Budget authority and security compliance requirements diverge sharply across procurement contexts.
- Commercial:Building automation, retail inventory, and logistics tracking with three-to-five-year depreciation schedules. Multi-site operators in the US Sun Belt prioritize standardized gateway platforms to reduce technician training overhead across distributed facilities.
- Government:NIST zero-trust mandates and FIPS 140-2 cryptographic requirements for federal IoT procurements. Defense and critical infrastructure deployments demand hardware root-of-trust and continuous attestation, extending certification cycles but locking in premium pricing.
- Consumer Electronics:Price-sensitive smart home hubs with minimal margin and rapid obsolescence.
- Transportation:Fleet telematics and connected vehicle infrastructure with NHTSA and FCC dual compliance burdens.
Commercial buyers move volume. Government buyers lock in margin through security requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Great Lakes industrial belt anchors North American demand for IoT nodes and gateways, with automotive and aerospace OEMs driving edge-heavy deployments across Michigan and Ohio factory corridors.
United States
Detroit-area automotive manufacturers and Silicon Valley cloud providers generate concentrated gateway demand for predictive maintenance and real-time analytics. FCC Part 15 rules govern unlicensed spectrum allocations for Zigbee and LoRaWAN deployments in agricultural and industrial settings. Michigan's robotic welding corridors and Texas Permian Basin oilfields represent the densest node installation clusters.
Canada
Saskatchewan and Alberta grain operations present underpenetrated opportunities for soil-moisture and equipment-telemetry cellular gateways. Health Canada and PMRA coordinate device certification with FCC standards to unlock cross-border deployment harmonization. Toronto-Waterloo tech corridor hosts gateway software development while Prairie Provinces drive agricultural IoT hardware adoption.
Mexico
Nuevo León and Baja California manufacturing hubs attract automotive Tier-1 suppliers deploying edge nodes for quality control and supply chain visibility. Mexico's federal telecommunications regulator IFT manages spectrum coordination with US FCC allocations for cross-border industrial zones. Mexico City Metro concentrates system integrator and distribution capabilities serving Latin American export markets.
North America IoT Node and Gateway Market Competitive Landscape
Strategic partnerships dominate the current landscape as semiconductor suppliers, networking specialists, and industrial automation firms combine capabilities to capture smart manufacturing contracts. The vendor base organizes into three tiers: diversified technology conglomerates with end-to-end portfolios, specialized connectivity chipmakers with automotive-grade certifications, and regional system integrators with deployment expertise. Competitive positioning hinges on security certification velocity under NIST frameworks and hardware-software disaggregation to capture recurring software revenue.
Within the diversified technology tier, Cisco Systems and Intel Corporation exemplify archetypes combining networking heritage with edge processing silicon. NXP Semiconductors anchors the specialized automotive connectivity segment with long lifecycle commitments from Detroit transplant suppliers. These three entities represent distinct strategic positions: infrastructure incumbents leveraging installed base relationships, semiconductor architects defining processor roadmaps, and automotive-grade specialists securing decade-long design wins.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Intel Corporation |
| NXP Semiconductors |
| Advantech Co., Ltd. |
| Texas Instruments Incorporated |
| Qualcomm Technologies, Inc. |
| Dell Technologies Inc. |
| STMicroelectronics |
| IBM Corporation |
| Others |
Value Network & Pricing Analysis
Backward integration into edge processor silicon anchors supply position and pricing power for gateway vendors serving NIST-certified federal deployments. Cisco Systems and Intel Corporation leverage captive semiconductor design capabilities to command premium positioning against fabless competitors dependent on Taiwan-based foundry allocation.
Pricing Analysis
Input-cost pass-through from Taiwanese foundry capacity constraints and Chilean lithium carbonate volatility is compressing margins on battery-backed cellular gateways. Pricing stratifies across FIPS 140-2 certified, FCC Part 15 compliant, and uncertified economy tiers, with government buyers absorbing security premiums while agricultural operators in Saskatchewan and Alberta drive standard-tier price erosion through volume consolidation.
Supply Chain Analysis
Dual-sourcing requirements from automotive OEMs in Michigan and Ohio are forcing gateway vendors to qualify secondary foundry partners beyond Taiwan. Advanced edge processors draw from Taiwan, South Korea, and USA fabrication capacity, while LoRaWAN radio modules rest on Chinese and Malaysian assembly. Single-source vulnerability in TSMC leading-edge nodes creates tariff-exposed disruption risk. Distribution runs through regional system integrators in Detroit, Dallas, and Toronto-Waterloo.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: Canadian Prairie agriculture offers lower customer acquisition costs than saturated US Great Lakes manufacturing, while FCC-Health Canada certification harmonization reduces regulatory duplication expense.
For Market Incumbents: Acquire firmware engineering teams with hardware-root-of-trust expertise to compress NIST certification cycles. Defend against modular gateway startups by embedding time-sensitive networking silicon directly into ruggedized enclosures, locking in automotive welding cell deployments through proprietary synchronization protocols.
For New Entrants and Emerging Players: System integrators with EPA emissions monitoring relationships represent the fastest channel to refinery and chemical plant gateway deployments. White-space concentrates in Saskatchewan grain operations lacking soil-moisture telemetry infrastructure. Target private 5G network convergence projects at Ohio and Michigan smart manufacturing campuses.
For Investors and Strategic Acquirers: Roll-up economics work for regional system integrators with Health Canada certification capabilities because cross-border deployment harmonization creates scalable platform value. Long-term viability hinges on software subscription attachment rates exceeding hardware depreciation schedules. Watch EPA stationary source permit issuance velocity as inflection indicator for emissions-linked gateway demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Hardware-Security Module Integration | NIST zero-trust mandates require FIPS 140-2 cryptographic certification for federal IoT procurements. |
| Time-Sensitive Networking Deployment | OPC-UA over TSN displaces proprietary fieldbus in Michigan robotic welding corridors. |
| Cellular Gateway Certification | FCC Part 15 and IFT spectrum coordination unlocks cross-border Mexico-US industrial zones. |
| Edge Inferencing Silicon Roadmap | TensorFlow Lite on-gateway execution reduces cloud egress fees for vibration analytics. |
| Software Subscription Unbundling | Annual analytics licenses separate from capex hardware enable faster edge node refresh cycles. |
Research Methodology
Multiple input streams — semiconductor supply chain databases, FCC equipment authorization filings, and EPA stationary source permit records — were reconciled against primary interviews with industrial automation procurement directors, gateway firmware engineering leads, and agricultural operations managers across Michigan, Ohio, and the Canadian Prairies. Secondary validation drew from NIST cybersecurity framework documentation, SEC 10-K hyperscaler capex disclosures, and customs import records for cellular module shipments. Bottom-up node installation counts triangulated against top-down OEM edge architecture spending forecasts.
Cross-referencing historical gateway shipment patterns against panel input from Tier 1 automotive supplier engineering directors established the analytical framework. Segmentation dimensions modeled include node type, connectivity technology, application sector, and end-user procurement authority across the projection horizon. CAGRs were derived from installed base replacement cycles and greenfield deployment velocity in precision agriculture. Forecast inputs incorporated LoRaWAN private network buildout rates and 5G private spectrum allocation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Taiwan foundry capacity allocation and Chilean lithium contract pricing. Deviation in EPA emissions monitoring mandate enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Asia-Pacific IoT Device Market
Internet of Things (IoT)
Location of Things Market
Internet of Things (IoT)
IoT Middleware Market
Internet of Things (IoT)
IoT Application Enablement Market
Internet of Things (IoT)
IoT in Warehouse Management Market
Internet of Things (IoT)
Global IoT Based Asset Tracking and Monitoring Market
Internet of Things (IoT)
Consumer Internet of Things (IoT) Market
Internet of Things (IoT)
Global IoT Routers Market
Internet of Things (IoT)
IoT Application Development Services Market
Internet of Things (IoT)
IoT Monetization Market
Internet of Things (IoT)
Global Internet of Things Technology Market
Internet of Things (IoT)
Internet of Things (IoT) Market
Internet of Things (IoT)
Middle East and Africa IoT Node and Gateway Market
Internet of Things (IoT)
North America Industrial IoT Market
Internet of Things (IoT)
Connected IoT Devices Market
Internet of Things (IoT)
Global IoT in Automobile Market