
 Massive Machine Type Communication Market | 2026-2036
Massive Machine Type Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Massive Machine Type Communication Market Foresight
The direct-to-module distribution channel is narrowing as chipset vendors consolidate relationships with systems integrators. Qualcomm anchors its position through R&D intensity in NB-IoT modem design. Huawei Technologies Co., Ltd. competes aggressively on manufacturing scale across Asia-Pacific base station deployments. Samsung Electronics differentiates through vertical integration from semiconductor foundry to network equipment.
Massive Machine Type Communication denotes cellular-based connectivity architectures designed to support ultra-high device densities exceeding one million nodes per square kilometer with extended battery lifecycles. These systems operate within licensed spectrum bands using power levels below 200 milliwatts to enable decade-long sensor deployments without maintenance. Smart Cities applications currently lead deployment value as municipalities integrate environmental sensing, traffic management, and public safety monitoring onto unified platforms. Industrial Automation represents the fastest-expanding segment where 5G network slicing delivers deterministic latency guarantees for robotic coordination and predictive maintenance workflows.
The Federal Communications Commission in the United States governs spectrum allocation for LTE-M and NB-IoT deployments through Part 90 and Part 95 rules, directly shaping carrier rollout timelines and device certification requirements. The European Telecommunications Standards Institute coordinates 3GPP compliance frameworks that determine market access for module manufacturers across EU member states. China's Ministry of Industry and Information Technology mandates GB standard adherence for domestic IoT deployments, creating a dual-track certification environment for foreign vendors. Stakeholders must monitor spectrum harmonization negotiations between regional regulators to anticipate module design standardization or fragmentation.
Market Dynamics
3GPP Release 17 network slicing capabilities are compressing latency guarantees for industrial automation clusters while fragmenting module certification requirements across regional spectrum allocations.
Growth Catalysts
- Smart Grid Mandates:Utilities in Germany and Japan are accelerating sensor density requirements for grid modernization, directly expanding NB-IoT module procurement volumes.
- REACH Compliance Deadlines:The EU's RoHS and REACH frameworks are forcing module redesigns that eliminate conflict minerals, creating replacement cycles across installed industrial bases.
- Private 5G Deployments:Manufacturing clusters in Bavaria and Baden-Württemberg are driving dedicated spectrum acquisitions that bypass carrier infrastructure limitations.
Market Restraints
- Lithium Battery Cost Volatility:Raw material price swings for coin-cell chemistries are compressing margin structures on decade-lifecycle sensor designs.
- Base Station Supply Concentration:Asia-Pacific equipment fabrication bottlenecks are extending lead times for small-cell densification projects in Western Europe.
- Spectrum Fragmentation:Divergent national allocations for LTE-M guard bands are forcing multi-mode radio designs that inflate unit costs.
Strategic Opportunities
- Agricultural Monitoring White Space:Brazil's ANVISA and rural connectivity programs are opening precision farming applications with minimal incumbent competition.
- RedCap Convergence:5G Reduced Capability specifications are hybridizing with existing LPWAN architectures to enable wearable health monitoring at intermediate data rates.
- Direct-to-Integrator Channels:Chipset vendors are bypassing traditional distribution to capture margin through embedded design partnerships with industrial OEMs.
Industry Challenges
- RF Engineering Talent Scarcity:Specialized antenna design expertise for sub-gigahertz propagation is concentrating among a narrow pool of semiconductor firms.
- Multi-Regulatory Certification Timelines:Simultaneous FCC Part 90, CE marking, and MIIT GB standard approvals are extending product launch cycles by 8-14 months.
- Legacy SCADA Integration Friction:Brownfield industrial sites require protocol translation layers that complicate deterministic latency guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Massive Machine Type Communication Market |
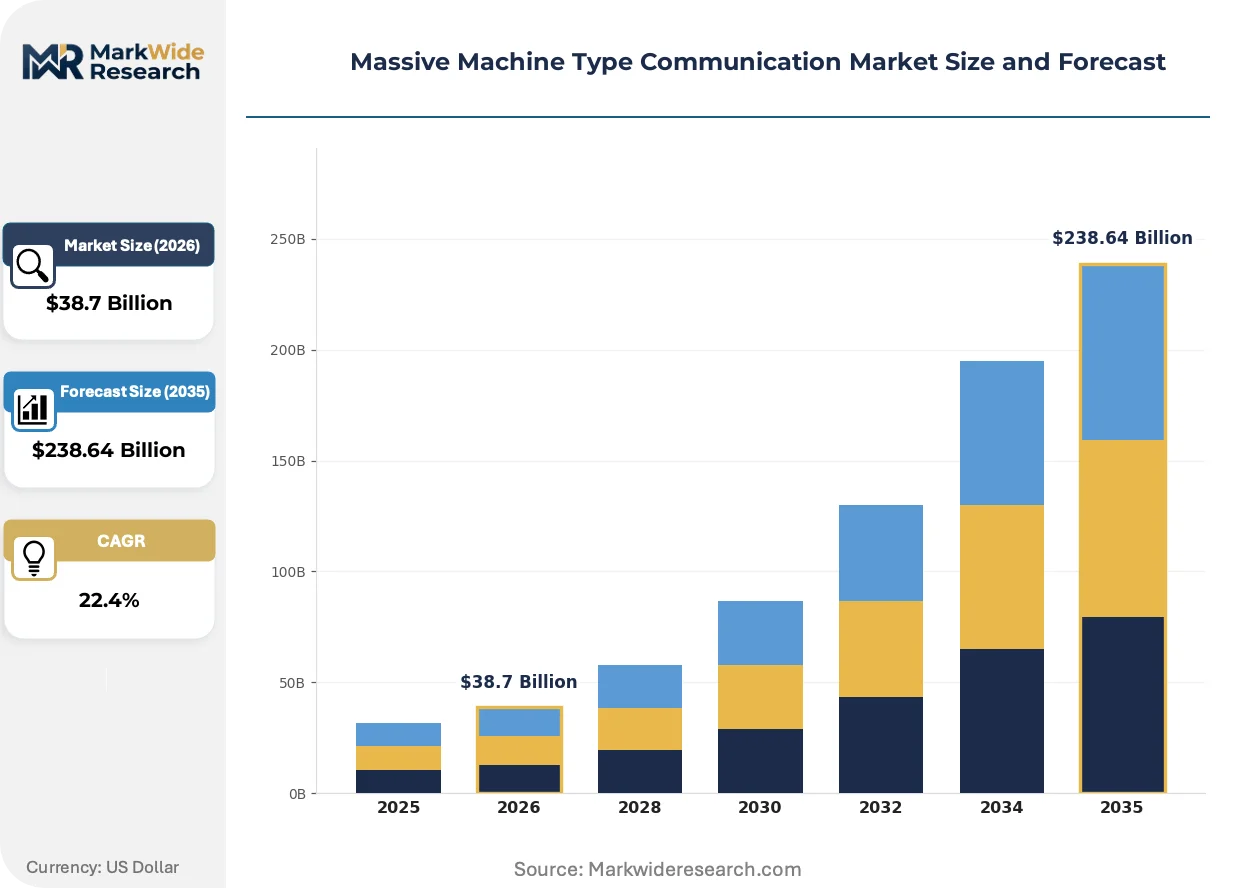
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $238.64 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Smart Cities, Industrial Automation, Remote Monitoring, Smart Agriculture Technology: Narrowband IoT, Sigfox, LTE-M, 5G End User: Agriculture, Logistics, Smart Grid, Healthcare Deployment: Public Network, Private Network, Hybrid Network, On-Premises |
| Companies Covered | Cisco Systems, Inc., Qualcomm, Huawei Technologies Co., Ltd., Samsung Electronics, Intel, Telefonaktiebolaget LM Ericsson, Panasonic Holdings Corporation, ZTE, Nokia Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Massive Machine Type Communication Market Shifts & Advancements
Cellular LPWAN architectures are fragmenting into specialized variants as end-use requirements diverge on latency, mobility, and power budgets.
Non-Terrestrial Networks (NTN) via satellite backhaul is hybridizing coverage models for remote asset tracking in maritime and energy sectors. Shipping operators in the North Sea and Gulf of Mexico are piloting dual-mode NB-IoT/NTN modules to eliminate terrestrial dead zones. This convergence is compressing the addressable market for pure-satellite IoT providers while expanding total connected device forecasts.
The FCC's Part 95 rule revisions for unlicensed spectrum adjacent to licensed LTE-M bands are enabling private network overlays without carrier coordination. Industrial facilities in Texas and Ohio are exploiting these guard-band allocations for campus-wide sensor meshes. Equipment vendors are responding with software-defined radios that dynamically switch between licensed and unlicensed modes based on signal quality.
Outcome-based connectivity contracts are displacing per-module pricing in smart city deployments. Municipal procurement offices in Barcelona and Singapore are negotiating availability guarantees rather than hardware volumes. This shift is forcing module manufacturers to absorb operational risk through managed service wrappers while capturing recurring revenue streams.
Massive Machine Type Communication Market Segmentation
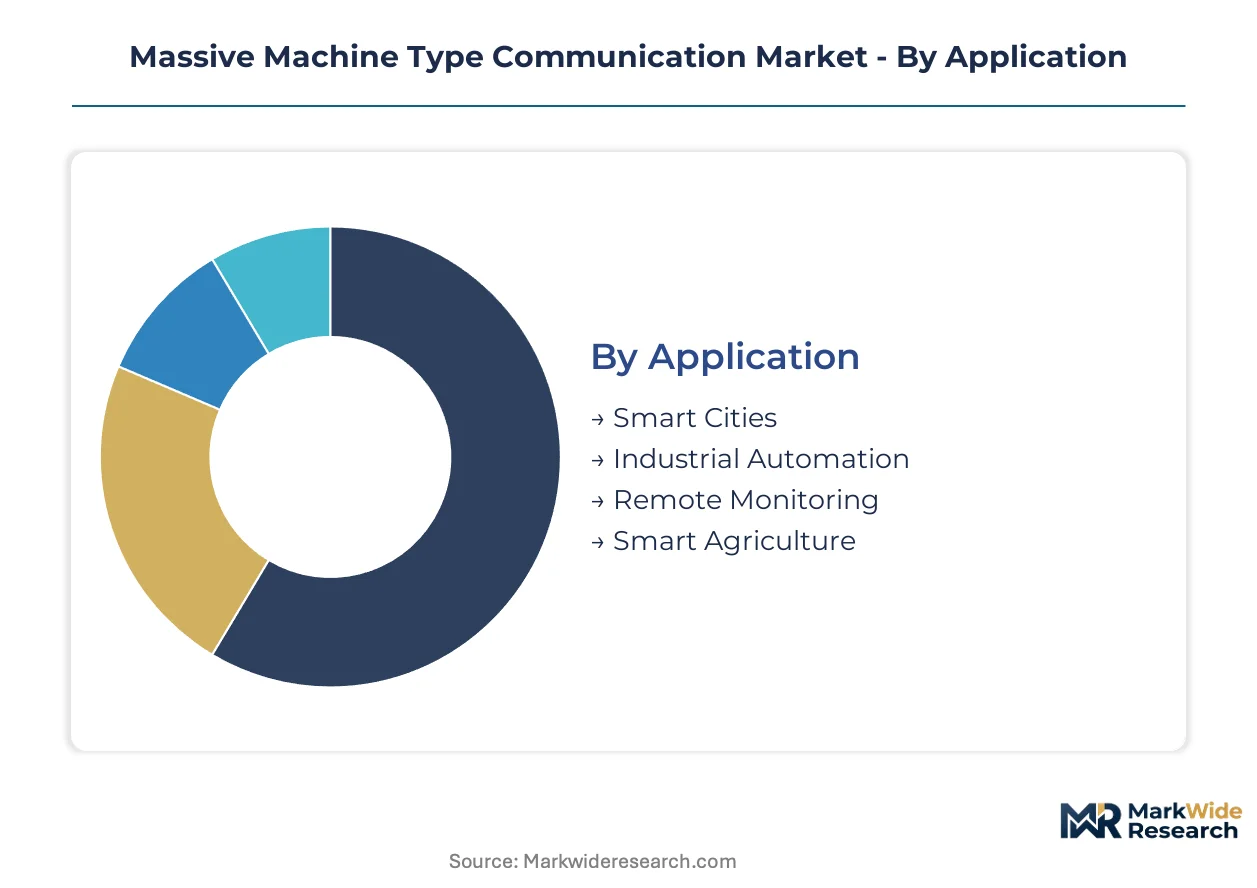
Massive Machine Type Communication deployments fragment across four distinct dimensions, each governing procurement cycles and margin structures differently. Application segmentation determines sensor lifecycle requirements, while technology choice locks in spectrum access and certification pathways. Deployment models and end-user verticals further stratify vendor relationships and integration complexity.
Application:
Replacement cycles vary dramatically across use cases, with environmental sensors in municipal infrastructure turning over every 8-12 years while industrial automation modules face 3-5 year refresh pressures from protocol evolution.
- Smart Cities:Municipal deployments integrate air quality monitoring, intelligent street lighting, and waste management sensors onto unified management platforms. Barcelona and Singapore procurement offices are negotiating availability-based contracts rather than hardware purchases, forcing module vendors into managed service wrappers. Demand concentrates where FCC Part 95 guard-band revisions enable private overlays without carrier coordination.
- Industrial Automation:Factory-floor robotics and predictive maintenance systems require deterministic latency guarantees that 5G network slicing now delivers. Bavarian and Baden-Württemberg manufacturing clusters are driving private spectrum acquisitions that bypass public infrastructure limitations entirely.
- Remote Monitoring:Asset tracking across maritime and energy sectors pairs NB-IoT with satellite backhaul to eliminate terrestrial dead zones. North Sea shipping operators pilot dual-mode modules for continuous connectivity.
- Smart Agriculture:Precision farming applications in Brazil's rural connectivity zones exploit minimal incumbent competition and favorable ANVISA regulatory frameworks for environmental sensor deployments.
Smart Cities dominates installed base. Industrial Automation is where expansion concentrates.
Technology:
Module cost tiers stratify sharply based on radio complexity, with single-mode NB-IoT designs at the economy end and multi-band 5G RedCap configurations commanding premium positioning.
- Narrowband IoT:Ultra-narrow 180 kHz channel bandwidth enables decade-long battery life on coin-cell chemistries, though lithium raw material volatility compresses margin structures. German utilities are accelerating procurement volumes for grid modernization sensor density requirements.
- LTE-M:Supports voice and mobility at higher data rates than NB-IoT, making it suitable for wearable health monitoring and connected vehicle applications. FCC Part 90 and Part 95 rules directly shape carrier rollout timelines and device certification requirements.
- Sigfox:Proprietary ultra-narrowband technology operating in unlicensed ISM bands with minimal subscription costs. Deployment concentrates in French utility and agriculture sectors where the ecosystem originated.
- 5G:Reduced Capability specifications hybridize with existing LPWAN architectures to enable intermediate data rate applications previously unserved. 3GPP Release 17 network slicing capabilities compress latency guarantees for deterministic industrial workloads.
Narrowband IoT anchors volume shipments. 5G is climbing the fastest on value contribution.
End User:
Customer procurement sophistication varies from standardized tender processes in public healthcare to embedded design partnerships in logistics, reshaping channel economics.
- Agriculture:Brazil's ANVISA and rural connectivity programs are opening precision farming applications with minimal incumbent competition. Sensor deployments focus on soil moisture, livestock tracking, and equipment monitoring.
- Logistics:Fleet management and cold-chain monitoring drive demand for mobile-enabled modules with seamless handover capabilities. Direct-to-integrator channels are displacing traditional distribution as chipset vendors capture margin through embedded design partnerships.
- Smart Grid:Utilities in Germany and Japan are accelerating sensor density requirements for grid modernization, directly expanding NB-IoT module procurement volumes. REACH and RoHS compliance deadlines force module redesigns that eliminate conflict minerals.
- Healthcare:Wearable monitoring and remote patient tracking applications are emerging as 5G RedCap specifications enable intermediate data rates with power budgets between NB-IoT and full 5G.
Smart Grid commands the largest committed volumes. Healthcare is gaining share fastest on application expansion.
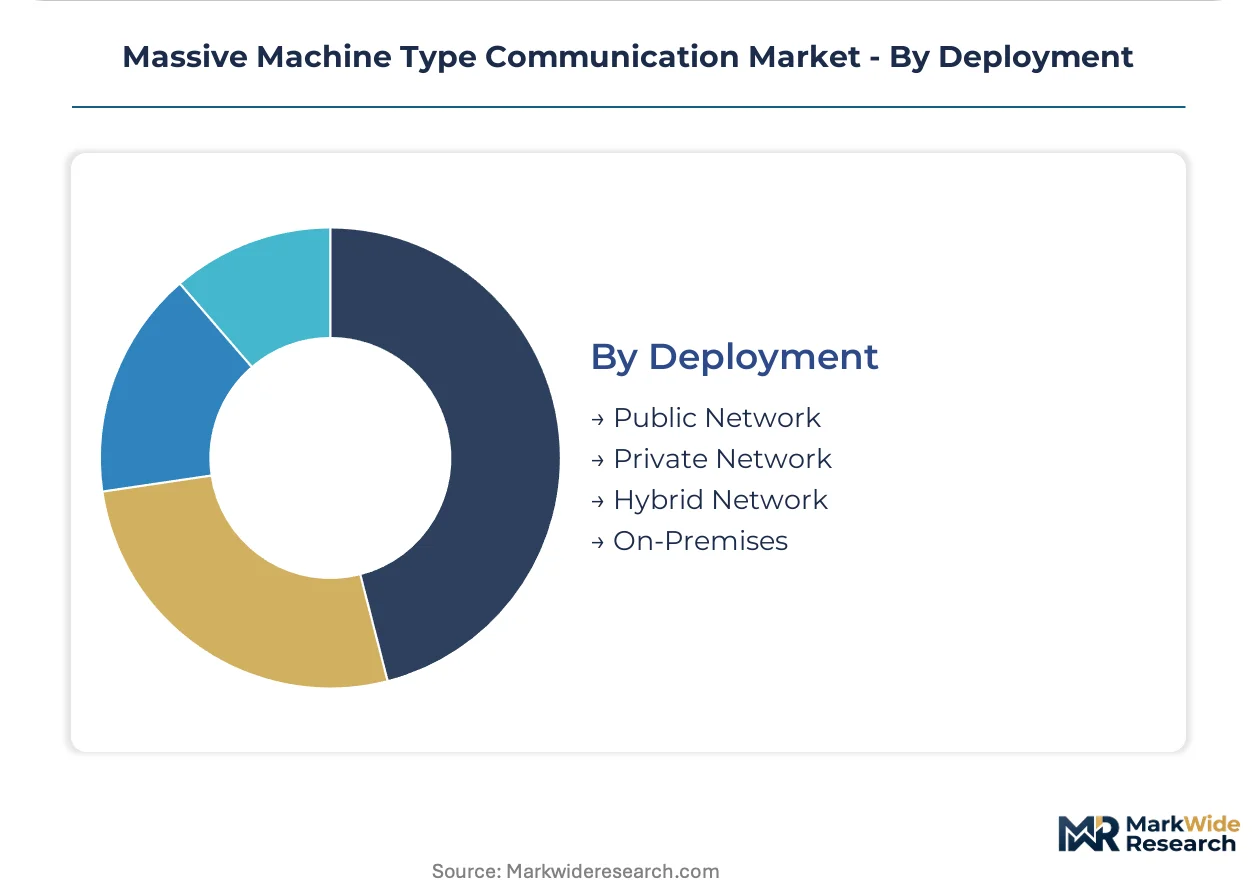
Deployment:
Supply concentration in base station fabrication creates lead time differentials, with public network deployments facing 8-14 month extensions versus on-premises alternatives.
- Public Network:Carrier-managed infrastructure requires multi-regulatory certification timelines spanning FCC Part 90, CE marking, and MIIT GB standards. Asia-Pacific equipment fabrication bottlenecks extend lead times for Western European densification projects.
- Private Network:Dedicated spectrum acquisitions bypass carrier infrastructure limitations entirely. Manufacturing clusters in Bavaria and Baden-Württemberg are driving this model for deterministic latency guarantees.
- Hybrid Network:Combines terrestrial cellular with satellite backhaul for continuous coverage in remote asset tracking. Shipping operators in the Gulf of Mexico pilot dual-mode NB-IoT/NTN modules.
- On-Premises:Campus-wide sensor meshes exploit FCC Part 95 guard-band allocations without carrier coordination. Industrial facilities in Texas and Ohio deploy software-defined radios that dynamically switch between licensed and unlicensed modes.
Public Network carries the historical installed base. Private Network is where deployment momentum concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC governs spectrum allocation for LTE-M and NB-IoT deployments through Part 90 and Part 95 rules, directly shaping carrier rollout timelines across the United States. Germany's industrial automation clusters in Bavaria and Baden-Württemberg are driving private 5G network acquisitions that bypass public infrastructure. Japan's METI coordinates smart grid modernization mandates that accelerate sensor density requirements for utilities.
United States
Industrial facilities in Texas and Ohio exploit FCC Part 95 guard-band allocations for campus-wide sensor meshes without carrier coordination. The FCC's unlicensed spectrum revisions enable private network overlays that compress deployment timelines for manufacturing automation. Equipment vendors deploy software-defined radios that dynamically switch between licensed and unlicensed modes based on signal quality.
Germany
Manufacturing clusters in Bavaria and Baden-Württemberg are acquiring dedicated spectrum for deterministic latency guarantees in robotic coordination workflows. The EU's REACH and RoHS frameworks force module redesigns that eliminate conflict minerals, creating replacement cycles across installed industrial bases. KBA regulatory alignment with ETSI standards streamlines certification pathways for automotive-integrated modules.
China
MIIT mandates GB standard adherence for domestic IoT deployments, creating a dual-track certification environment for foreign module vendors. The Yangtze River Delta and Pearl River Delta concentrate base station fabrication capacity that extends lead times for Western European densification projects. Smart city procurement in Shenzhen and Shanghai integrates environmental sensing onto unified management platforms.
Japan
METI smart grid mandates accelerate sensor density requirements for utility modernization in Tokyo and Osaka metropolitan zones. JIS standards coordination with 3GPP Release 17 specifications compresses latency guarantees for industrial automation clusters. Kanto region manufacturing facilities pilot predictive maintenance workflows using 5G network slicing capabilities.
Brazil
ANVISA regulatory frameworks and rural connectivity programs open precision farming applications with minimal incumbent competition. São Paulo and Minas Gerais agricultural zones deploy soil moisture and livestock tracking sensors exploiting favorable certification timelines. The country's national telecommunications regulator coordinates spectrum harmonization negotiations that determine module design standardization for Latin American markets.
Massive Machine Type Communication Market Competitive Landscape
Semiconductor specialists and network equipment fabricators split the market along technology ownership vectors. Consolidation pressures concentrate among chipset vendors seeking captive supply of radio frequency components. Three archetypes dominate: integrated platform providers controlling foundry-to-network stacks, modular specialists focusing on single-mode LPWAN designs, and systems integrators assembling multi-vendor configurations. Competitive moves center on backward integration into semiconductor fabrication and strategic partnerships with industrial OEMs for embedded design wins.
Within the integrated platform tier, Qualcomm and Samsung Electronics exemplify archetypes spanning modem design through network equipment deployment. Huawei Technologies Co., Ltd. occupies a position representing manufacturing scale across Asia-Pacific infrastructure rollouts. These three entities anchor competitive dynamics through divergent geographic footprints and regulatory compliance strategies, with each exemplifying distinct approaches to spectrum harmonization and certification pathway management.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Qualcomm |
| Huawei Technologies Co., Ltd. |
| Samsung Electronics |
| Intel |
| Telefonaktiebolaget LM Ericsson |
| Panasonic Holdings Corporation |
| ZTE |
| Nokia Corporation |
| Others |
Supply & Pricing Matrix
The Yangtze River Delta and Pearl River Delta concentrate base station fabrication capacity that shapes downstream module pricing power through supply rationing during densification cycles. Equipment vendors in these clusters translate silicon shortages into tiered availability guarantees that compress margins on decade-lifecycle sensor designs.
Pricing Analysis
Price spreads between German industrial automation clusters and Brazilian agricultural zones reflect divergent certification burdens and volume scales. Three-tier pricing structure across premium RedCap configurations, standard LTE-M modules, and economy NB-IoT designs stratifies sharply on radio complexity and multi-regulatory approval status. Cost compression in the economy tier is intensifying because lithium raw material volatility squeezes coin-cell chemistry margins. Municipal procurement offices exhibit highest price sensitivity through outcome-based contract negotiations, while private 5G manufacturing clusters absorb premium positioning for deterministic latency guarantees.
Supply Chain Analysis
Export control regimes limiting radio frequency component flows between the United States and China fragment semiconductor sourcing strategies for multi-mode radio designs. Module production draws from Taiwan for advanced foundry services, South Korea for memory integration, and domestic China facilities for base station assembly. Lithium carbonate, ceramic antenna substrates, and power management integrated circuits anchor raw material dependencies. Single-source vulnerability concentrates in sub-gigahertz RF engineering talent pools. Distribution runs through systems integrators consolidating direct relationships with industrial OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from unlicensed LPWAN alternatives exploiting FCC Part 95 guard-band revisions for private network overlays without carrier coordination.
For Market Incumbents: Insulate module margin structures through backward integration into power management semiconductor fabrication, capturing value from lithium battery cost volatility rather than absorbing it. Deepen embedded design partnerships with Bavarian manufacturing clusters to lock in private 5G spectrum acquisition workflows. Prioritize CE marking and FCC Part 90 certification pre-positioning to compress multi-regulatory approval timelines that currently extend launch cycles. For New Entrants and Emerging Players: Build out precision agriculture sensor portfolios targeting Brazil's ANVISA-regulated rural connectivity zones where incumbent competition remains minimal. Exploit the agricultural monitoring white space through soil moisture and livestock tracking applications with favorable certification timelines. Pursue direct-to-integrator channel strategies that bypass traditional distribution markups and capture margin through embedded design partnerships with equipment OEMs. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded IoT module divisions lacking 5G RedCap roadmap investment. Frame long-term viability around 5G network slicing penetration in deterministic latency applications over a multi-year industrial automation upgrade cycle. Target acquisition candidates with captive RF engineering talent pools and existing CE marking infrastructure. Watch for inflection in private spectrum auction volumes as signal of deployment momentum acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| 5G RedCap Module Development | Enables intermediate data rate applications for wearable health monitoring and industrial predictive maintenance workflows. |
| Private Network Spectrum Acquisition | Bypasses carrier infrastructure limitations for Bavarian manufacturing clusters requiring deterministic latency guarantees. |
| Multi-Regulatory Certification Pre-Positioning | Compresses FCC Part 90, CE marking, and MIIT GB standard approval timelines that currently extend product launches. |
| Direct-to-Integrator Channel Bypass | Captures margin through embedded design partnerships with industrial OEMs rather than traditional distribution markups. |
| Satellite-Terrestrial Hybrid Integration | Eliminates coverage dead zones for North Sea shipping operators through dual-mode NB-IoT and non-terrestrial network modules. |
Research Methodology
A spread of perspectives from RF engineering directors at semiconductor firms, procurement leads at German utility operators, regulatory affairs specialists navigating FCC Part 95 revisions, and systems integrators assembling industrial sensor meshes converged on the working assumptions. Primary interview insights combined with secondary validation from 3GPP specification documents, ETSI compliance frameworks, FCC docket filings, and carrier capex disclosures. Bottom-up module shipment estimates triangulated against top-down network densification projections.
Demand-supply balance framing anchored the analytical approach across the analysis window, modeling adoption curves against base station deployment constraints. Segmentation dimensions included application lifecycle requirements, technology radio complexity tiers, deployment model infrastructure ownership, and end-user vertical procurement sophistication. CAGRs derived from curve-fitting observed penetration rates against saturation thresholds. Forecast inputs incorporated smart grid mandate acceleration timelines and private spectrum auction velocity indicators.
The forecast holds incumbent behavior within observed patterns; aggressive moves by unlicensed LPWAN challengers exploiting guard-band allocations would shift outcomes beyond modeled ranges. Material shifts in lithium raw material cost trajectories or 3GPP Release 18 specification timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT Gateway Hardware and Software Market
Internet of Things (IoT)
Intelligent IoT Market
Internet of Things (IoT)
IoT Utilities Market
Internet of Things (IoT)
Industrial IoT Platform Market
Internet of Things (IoT)
Global Satellite Enabled IoT Software Market
Internet of Things (IoT)
Connected Bottles Market
Internet of Things (IoT)
Narrow Band IoT Tracker Market
Internet of Things (IoT)
IoT Platform Market
Internet of Things (IoT)
Smart Connected Device Market
Internet of Things (IoT)
Industrial Internet of Things (Iiot) Market
Internet of Things (IoT)
Europe IoT Device Market
Internet of Things (IoT)
Global Machine-To-Machine (M2M) Connections Market
Internet of Things (IoT)
IoT Integration Services Market
Internet of Things (IoT)
IoT Application Enablement Market
Internet of Things (IoT)
5G Internet of Things Market
Internet of Things (IoT)
Private Narrowband IoT Market