
 Global IoT in Aerospace and Defense Market | 2026-2036
Global IoT in Aerospace and Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Global IoT in Aerospace and Defense Market Foresight
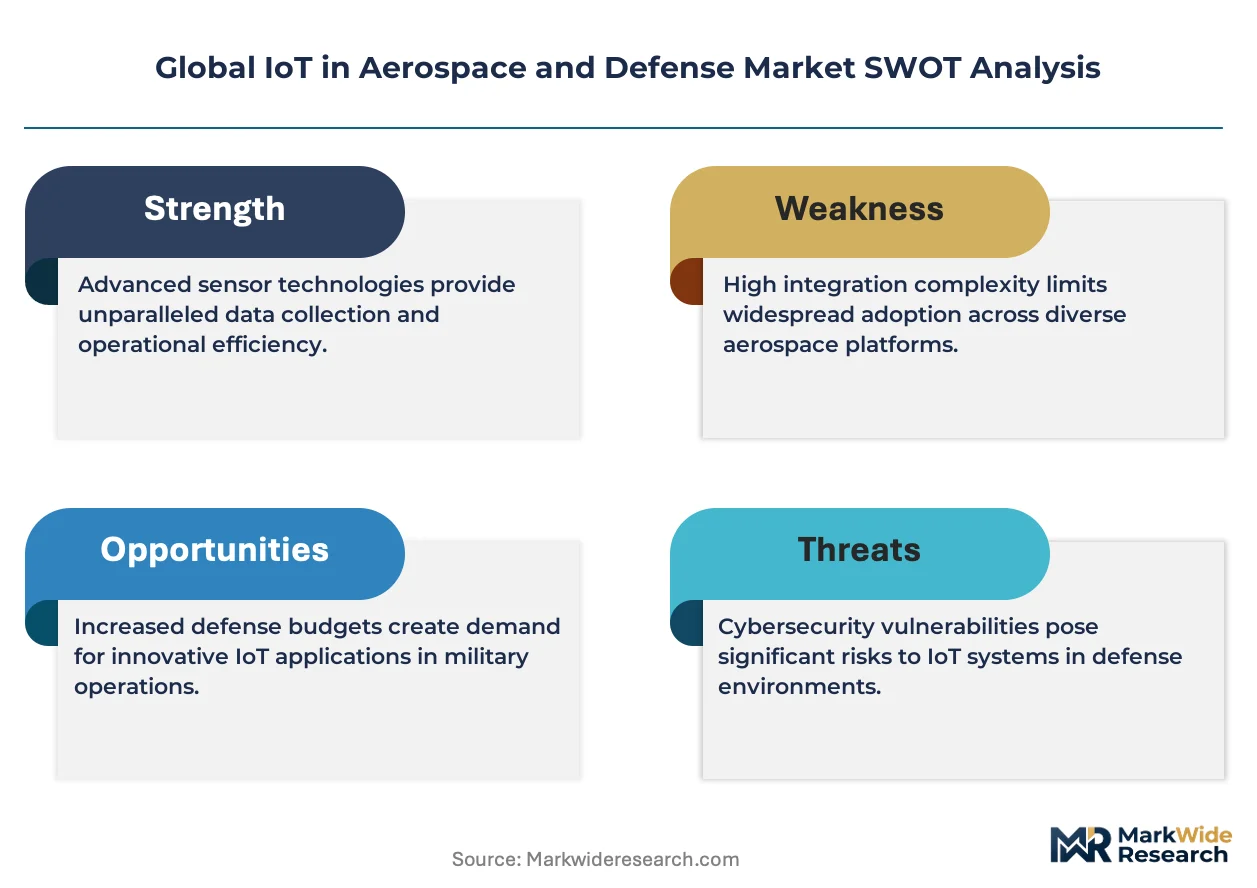
The EU Green Deal is rebalancing procurement criteria across NATO-aligned defense ministries toward energy-efficient connected platforms. Lockheed Martin Corporation leverages its satellite IoT infrastructure to sustain long-haul military communications contracts. Northrop Grumman Corporation anchors unmanned systems programs with embedded sensor networks for autonomous surveillance missions.
IoT in aerospace and defense encompasses networked sensor arrays, telemetry systems, and edge-computing nodes that collect, transmit, and process operational data across aircraft, spacecraft, and ground-based military assets. These systems typically operate on encrypted low-latency protocols with redundancy thresholds measured in milliseconds to ensure mission continuity under contested electromagnetic conditions. Fleet management applications currently dominate procurement volumes as airlines and air forces prioritize fuel optimization and route efficiency through real-time engine diagnostics. Predictive maintenance is expanding fastest among technology segments because sensor-driven failure prediction reduces aircraft-on-ground downtime and extends component life cycles beyond traditional scheduled intervals.
FAA airworthiness standards, EU AI Act algorithmic accountability frameworks, and NIST cybersecurity guidelines collectively shape product certification timelines and data governance architectures for connected defense systems. EMA and ECHA play indirect but material roles where IoT-enabled medical evacuation platforms and hazardous materials monitoring intersect with aerospace logistics. Stakeholders must weigh interoperability investments against the fragmentation risk posed by divergent national encryption standards and spectrum allocation regimes.
Market Dynamics
Military command centers are accelerating procurement of connected mission systems as contested electromagnetic environments demand millisecond-redundant encrypted protocols for operational continuity.
Growth Catalysts
- EU AI Act mandates:Algorithmic transparency requirements for autonomous defense platforms are compelling defense ministries to upgrade legacy systems with auditable sensor networks.
- Predictive maintenance protocols:Sensor-driven failure prediction is compressing aircraft-on-ground downtime across commercial and military fleets.
- Fuel optimization imperatives:Real-time engine diagnostics through telemetry arrays are anchoring procurement decisions for airlines and air forces prioritizing route efficiency.
Market Restraints
- Semiconductor supply concentration:Advanced sensor fabrication capacity clusters in East Asian foundries, exposing defense procurement to single-point vulnerability.
- Spectrum allocation fragmentation:Divergent national encryption standards and frequency regimes are forcing redundant hardware configurations for cross-border operations.
- Legacy integration costs:Retrofitting analog-era aircraft with IP-native sensor buses requires extensive airworthiness recertification under FAA Part 25 standards.
Strategic Opportunities
- India defense modernization:The country's PLI scheme for electronics manufacturing is attracting component suppliers to establish captive production for aerospace sensor modules.
- Medical evacuation platforms:IoT-enabled patient monitoring during aeromedical transport represents underpenetrated demand within NATO logistics networks.
- Edge-AI convergence:Onboard inference chips combined with satellite IoT backhaul are enabling autonomous threat detection without ground station dependency.
Industry Challenges
- Cleared workforce scarcity:Security-cleared embedded systems engineers with TS/SCI credentials command premium compensation and extended recruitment cycles.
- Multi-jurisdiction certification:Simultaneous FAA, EASA, and NIST compliance for connected platforms extends development timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IoT in Aerospace and Defense Market |
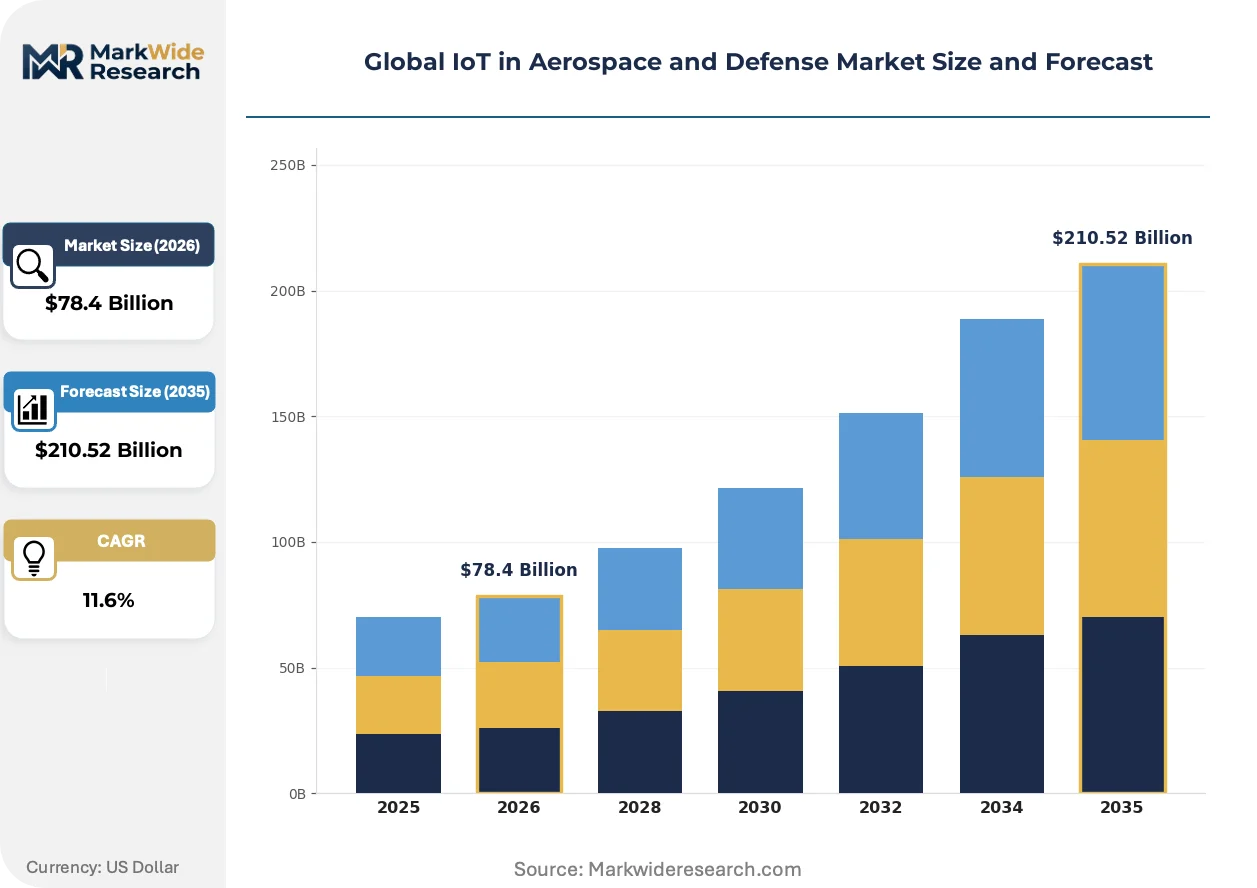
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $210.52 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, Edge Computing, On-Premises, Hybrid Solutions Technology: Wireless Sensor Networks, Satellite IoT, RFID, Telemetry, AI Integration Application: Fleet Management, Predictive Maintenance, Security Monitoring, Mission Control, Logistics Tracking End User: Aircraft Manufacturers, Defense Contractors, Air Traffic Control, Space Agencies, Military Command Centers |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, Boeing, Honeywell International Inc., Raytheon Technologies, General Dynamics Corporation, Elbit Systems Ltd., AeroVironment Inc., L3Harris Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IoT in Aerospace and Defense Market Shifts & Advancements
Defense procurement corridors are reconfiguring around software-defined platforms where firmware updates determine capability more than hardware refresh cycles.
Autonomous surveillance swarms are automating perimeter security for forward operating bases. United States Special Operations Command is field-testing these systems across African and Middle Eastern theaters. The technology is automating sensor-to-shooter timelines while compressing manpower requirements for persistent area denial.
REACH chemical disclosure rules are mandating material traceability for aerospace composites containing hazardous substances. European suppliers must now document full substance flows from raw polymer to finished airframe component. Military contractors serving NATO are responding by qualifying alternative resin systems ahead of sunset dates for restricted compounds.
Performance-based logistics contracts are displacing traditional spare-part sales for military engine programs. United Kingdom Ministry of Defence and Royal Australian Air Force have adopted availability-guarantee structures where contractors bear uptime risk. This shift concentrates supplier selection in the United States, United Kingdom, and Australia where prime contractors maintain integrated sustainment infrastructure.
Global IoT in Aerospace and Defense Market Segmentation
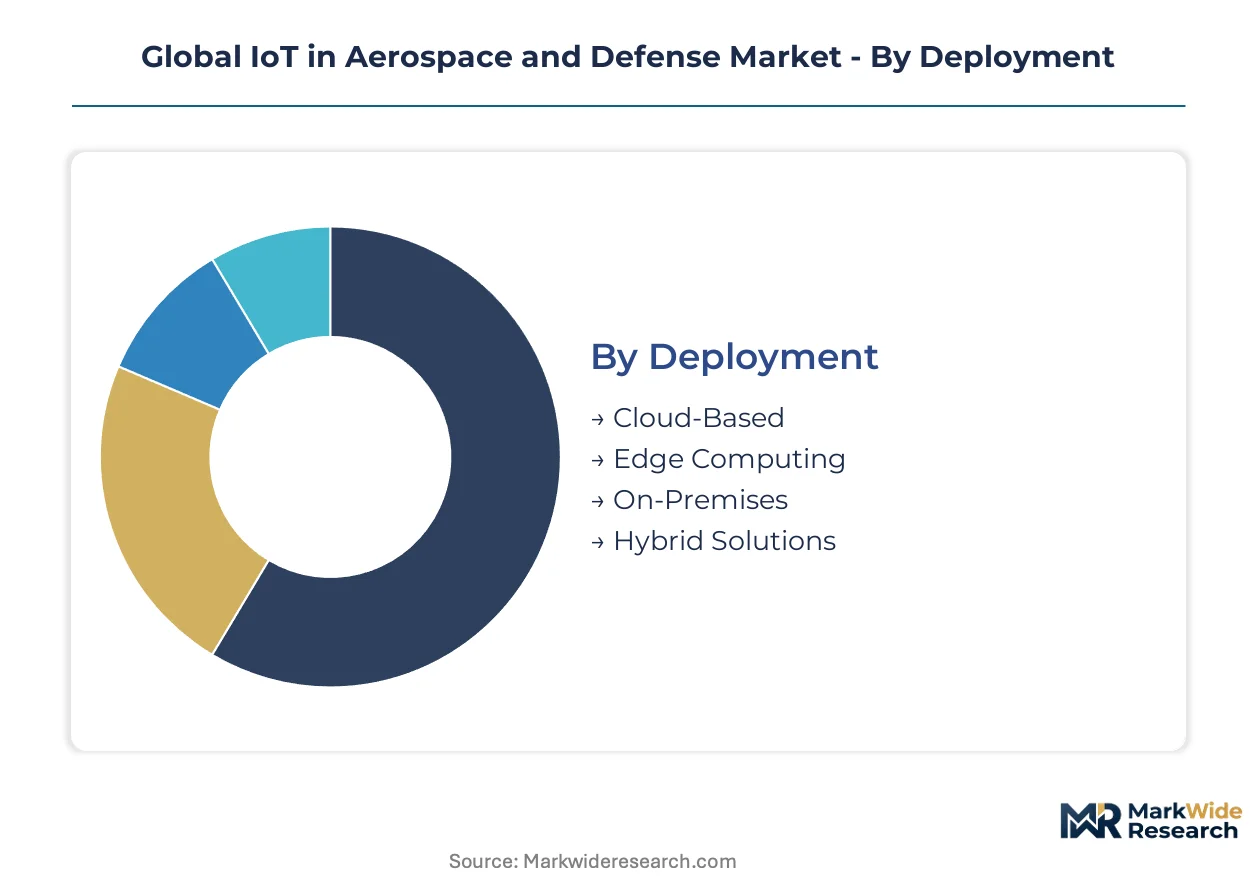
Segmentation in aerospace and defense IoT reveals how procurement priorities diverge between mission-critical military specifications and commercial aviation efficiency mandates. Understanding these fault lines helps suppliers align certification investments with actual deployment pathways.
Deployment:
Standardization dominates at the infrastructure layer while customization intensifies at the application tier across this category.
- Cloud-Based:Centralized data lakes aggregate telemetry from dispersed fleets through encrypted backhaul to defense-accredited facilities. United States Air Mobility Command contracts favor this model for strategic airlift visibility across CONUS and European staging bases. Latency tolerances here reach 500ms, acceptable for non-time-critical logistics.
- Edge Computing:Onboard inference nodes process sensor streams locally, enabling autonomous threat response when satellite links degrade. Forward operating bases in contested electromagnetic environments drive procurement here. Sub-50ms decision loops separate viable platforms from rejected bids.
- On-Premises:Air-gapped installations serve nuclear command-and-control networks with zero external connectivity.
- Hybrid Solutions:Tiered architectures route routine traffic through commercial cloud while reserving classified processing for sovereign infrastructure.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Edge Computing.
Technology:
Cost tier stratification separates proven radio-frequency stacks from emerging satellite constellations requiring substantial capital commitment.
- Wireless Sensor Networks:Mesh architectures of low-power nodes monitor structural health across airframes and ground vehicles. Honeywell and BAE Systems dominate retrofit programs for legacy platforms where wiring harness replacement proves cost-prohibitive. Battery life extension to 10-year cycles remains the primary competitive battleground.
- Satellite IoT:Low-earth-orbit constellations provide beyond-line-of-sight connectivity for maritime patrol and polar operations. United Kingdom Royal Navy submarine communication programs and Australian border surveillance contracts anchor demand here. Terminal miniaturization below 5kg unlocks tactical unmanned aerial vehicle integration.
- RFID:Passive tags track high-value components through maintenance depots and supply chains.
- Telemetry:Flight-test instrumentation streams structural and performance data during envelope expansion programs.
- AI Integration:Neural network inference at the edge enables predictive failure modes not captured by threshold-based alarms.
Wireless Sensor Networks carry the largest installed base. Satellite IoT is climbing the fastest as constellation density reaches operational thresholds.
Application:
Customer type divides this category between commercial operators prioritizing unit economics and defense agencies optimizing mission assurance.
- Fleet Management:Real-time position, fuel burn, and route optimization dominate commercial airline procurement decisions. Delta Air Lines and Lufthansa Group have standardized on unified dashboards integrating engine health with flight operations. Regulatory pressure from EU ETS carbon accounting accelerates sensor deployment for emissions verification.
- Predictive Maintenance:Vibration and thermal signatures identify bearing degradation and compressor fouling before functional failure. United States Navy aviation maintenance centers report 30% reduction in unscheduled removals following sensor suite installation. Component life extension justifies premium pricing against traditional scheduled overhaul.
- Security Monitoring:Perimeter intrusion detection and access control for airside facilities.
- Mission Control:Command-and-control networks coordinating distributed strike packages.
- Logistics Tracking:Condition monitoring for sensitive munitions and medical supplies in transit.
Fleet Management absorbs the greatest procurement volume. Predictive Maintenance is gaining share fastest as availability-based contracts displace traditional spares purchasing.
End User:
Maturity gradients separate long-established certification relationships from emerging procurement channels with abbreviated vendor histories.
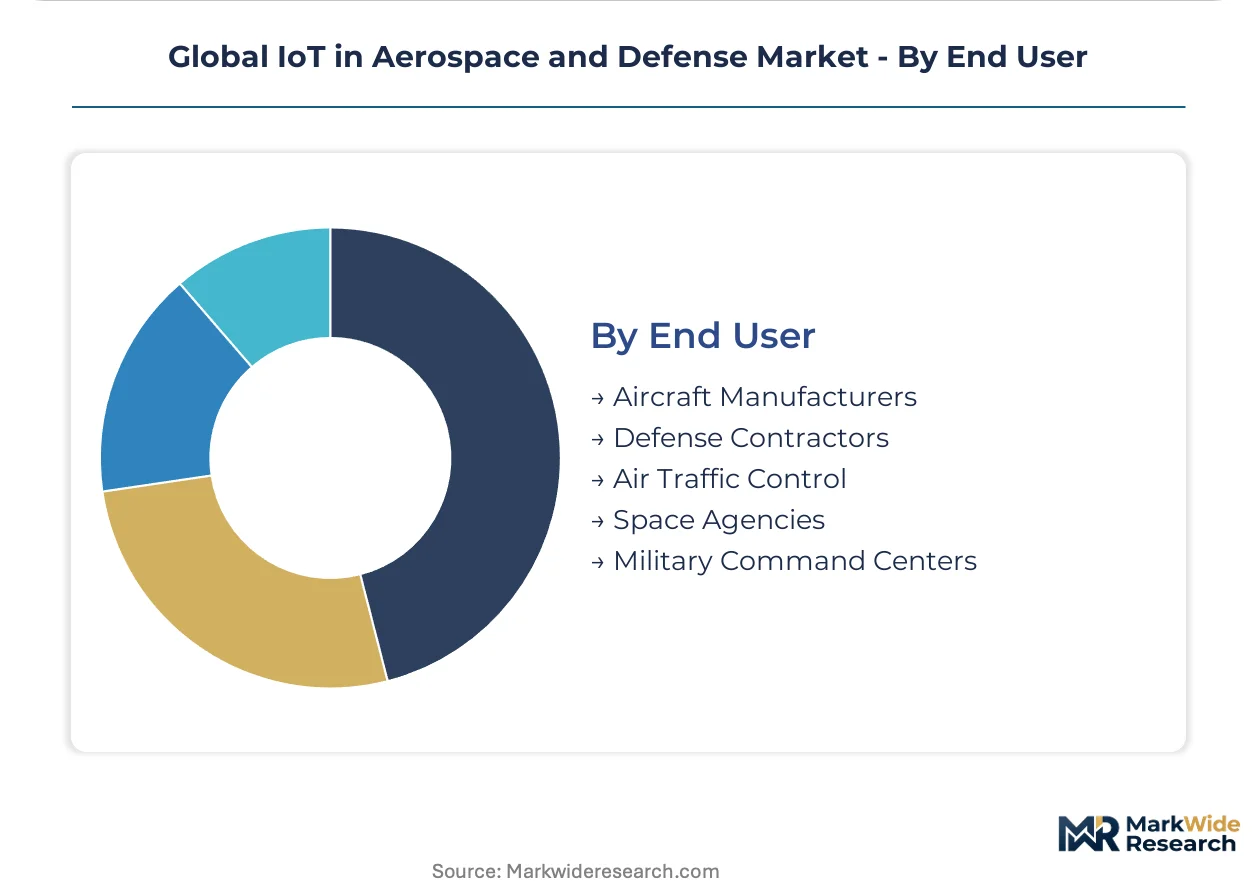
- Aircraft Manufacturers:Original equipment integration at the production line level locks in decade-long supply agreements. Boeing and Airbus specify IoT architectures for new platforms, with supplier selection occurring 4-6 years before first flight. Airworthiness certification burden favors incumbents with established FAA and EASA technical standard order approvals.
- Defense Contractors:Systems integrators embed sensor networks within weapon platforms and command infrastructure. Lockheed Martin F-35 sustainment contracts and Northrop Grumman Global Hawk programs demonstrate performance-based logistics structures where contractor uptime guarantees replace transactional spare part sales.
- Air Traffic Control:National aviation authorities modernize surveillance and communication infrastructure.
- Space Agencies:NASA and ESA mission operations require radiation-hardened components with extended qualification cycles.
- Military Command Centers:Joint operations centers integrate multi-domain sensor feeds for battlespace awareness.
Aircraft Manufacturers channel the most installed systems. Defense Contractors show the steepest expansion trajectory as availability contracting proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States pioneered satellite-based military communications infrastructure during Cold War programs. Defense procurement corridors in Virginia, California, and Texas now concentrate connected mission system integration. NATO interoperability requirements are extending US technical standards across allied defense ministries.
United States
FAA airworthiness certification and NIST cybersecurity guidelines govern connected platform deployment across military and commercial aviation. The Virginia-California-Texas defense corridor hosts prime contractor integration facilities for satellite IoT backhaul systems. United States Special Operations Command field-tests autonomous surveillance swarms across African and Middle Eastern theaters.
Germany
REACH chemical disclosure rules mandate material traceability for aerospace composites containing hazardous substances. The EU AI Act algorithmic accountability framework compels defense ministries to upgrade legacy systems with auditable sensor networks. Bavaria and Baden-Württemberg host precision sensor fabrication clusters serving NATO airframe programs.
United Kingdom
Performance-based logistics contracts displace traditional spare-part sales across Royal Air Force engine programs. Ministry of Defence availability-guarantee structures concentrate supplier selection among integrated sustainment providers. The UK Royal Navy submarine communication programs anchor demand for low-earth-orbit satellite IoT terminals.
Israel
Autonomous threat detection systems drive edge-AI convergence for contested electromagnetic environments. National encryption standards exceed NATO baseline requirements, creating specialized hardware demand. Tel Aviv and Haifa metropolitan areas concentrate unmanned systems engineering for perimeter security applications.
India
The PLI scheme for electronics manufacturing attracts component suppliers establishing captive production for aerospace sensor modules. Defense modernization programs prioritize indigenous connectivity standards for command-and-control networks. Karnataka and Telangana host emerging fabrication facilities for wireless sensor network modules.
Global IoT in Aerospace and Defense Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and airworthiness approval portfolios. The vendor base stratifies between prime contractors holding decade-long sustainment agreements and subsystem specialists supplying sensor modules under annual contracts. Three archetypes dominate: integrated systems houses with performance-based logistics franchises, component specialists with FAA technical standard order approvals, and emerging edge-AI chip vendors targeting autonomous platform retrofit. Competitive moves concentrate on strategic partnerships for constellation access and backward integration into radiation-hardened component fabrication.
Within the integrated systems tier, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify prime contractor positioning through satellite infrastructure and unmanned program franchises. Honeywell International Inc. occupies a distinct archetype as a retrofit specialist with established technical standard order pathways. These three entities represent the certification-heavy end of competitive positioning where airworthiness approval history determines contract access.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Boeing |
| Honeywell International Inc. |
| Raytheon Technologies |
| General Dynamics Corporation |
| Elbit Systems Ltd. |
| AeroVironment Inc. |
| L3Harris Technologies |
| Others |
Supply & Pricing Matrix
Captive sensor fabrication in South Korea and Taiwan anchors tiered pricing structures across defense-grade and commercial IoT modules. Prime contractors leverage in-house radiation-hardened component production to sustain premium positioning against subsystem specialists dependent on East Asian foundry access.
Pricing Analysis
Performance-based logistics contracts dominate procurement structures where contractor uptime guarantees replace transactional spare-part sales. Price differentiation rests on airworthiness certification depth and TS/SCI-cleared workforce access rather than hardware specifications alone. Cost compression in commercial aviation sensor tiers is intensifying because airlines prioritize fuel-optimization dashboards over structural health monitoring. Defense agencies show lowest price sensitivity as availability-guarantee structures transfer operational risk to suppliers.
Supply Chain Analysis
Dual-sourcing mandates from United States defense procurement corridors compel redundant qualification of East Asian and domestic sensor fabricators. Advanced semiconductor production clusters in Taiwan, South Korea, and Japan supply radiation-hardened inference chips and encrypted telemetry processors. Gallium arsenide substrates and rare-earth magnet materials draw from concentrated extraction zones in China and Myanmar. Single-source vulnerability in sub-6GHz RF component supply threatens program timelines. Distribution runs through defense-accredited logistics networks with air-gapped custody chains for classified hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act algorithmic accountability framework compounds procurement demand as defense ministries retrofit legacy platforms with auditable sensor networks.
For Market Incumbents: Deepen backward integration into radiation-hardened semiconductor fabrication to offset foundry concentration risk in East Asia. Expand captive production of edge-AI inference chips in United States defense corridors to defend margin position against emerging fabless entrants. Lockheed Martin and Northrop Grumman sustainment franchises demonstrate how performance-based logistics contracts create switching-cost barriers. For New Entrants and Emerging Players: EU AI Act mandates in Germany and France open a window for specialist compliance-software vendors serving algorithmic transparency requirements. Target medical evacuation platform retrofits within NATO logistics networks as the most penetrable application white-space. Pursue partnership structures with established prime contractors rather than direct platform competition to accelerate airworthiness certification. For Investors and Strategic Acquirers: Roll-up economics work for subsystem specialists with FAA technical standard order approvals because certification timelines deter greenfield entry. Five-to-ten-year viability favors component vendors qualifying alternative resin systems ahead of REACH sunset dates. Watch India PLI scheme electronics manufacturing incentives as inflection signal for supply chain geographic diversification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Radiation-Hardened Fabrication | Captive semiconductor production insulates Lockheed Martin and Northrop Grumman from East Asian foundry concentration risk. |
| Performance-Based Logistics Contract Expansion | United Kingdom Ministry of Defence availability guarantees concentrate supplier selection among integrated sustainment providers. |
| EU AI Act Compliance Software Development | Algorithmic audit trail capabilities unlock retrofit contracts across NATO-aligned defense ministries. |
| India PLI Scheme Manufacturing Localization | Karnataka and Telangana fabrication facilities reduce tariff exposure for wireless sensor network modules. |
| REACH Alternative Resin Qualification | European suppliers documenting full substance flows ahead of sunset dates secure long-term NATO airframe contracts. |
Research Methodology
Coverage spans United States, Germany, United Kingdom, Israel, and India, with primary inputs from each defense procurement corridor. Primary interviews with program managers at United States Special Operations Command, procurement officers at United Kingdom Ministry of Defence, and engineering leads at Bavaria sensor fabrication clusters combined with secondary validation. FAA airworthiness directives, EU AI Act implementation guidance, NIST cybersecurity frameworks, and India PLI scheme notifications anchored bottom-up and top-down triangulation.
Rate-of-change decomposition across deployment modes, technology stacks, and end-user segments structured the analytical framework. Segmentation dimensions modeled include cloud-edge-hybrid architectures, wireless-satellite-RFID-telemetry-AI technology tiers, and aircraft manufacturer-defense contractor-military command center customer types. CAGRs derived from installed base expansion trajectories and replacement cycle compression. Satellite constellation density thresholds and edge-AI inference chip miniaturization curves served as industry-specific forecast inputs across the projection horizon.
Revisions become necessary when semiconductor supply concentration shifts, REACH chemical disclosure enforcement tightens, or spectrum allocation fragmentation accelerates. Forecasts reflect assumptions about defense budget continuity and NATO interoperability standard adoption. Deviation in EU AI Act implementation timelines or India PLI scheme incentive structures would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Smart Sprinkler Controller Market
Internet of Things (IoT)
North America Narrowband-Internet of Things (NB-IoT) Market
Internet of Things (IoT)
Maritime Internet of Things Market
Internet of Things (IoT)
Connected Bottles Market
Internet of Things (IoT)
Global IoT Routers Market
Internet of Things (IoT)
IoT Data Governance Market
Internet of Things (IoT)
Wireless Smart Plug Market
Internet of Things (IoT)
North America IoT Node and Gateway Market
Internet of Things (IoT)
IoT Lpwans Market
Internet of Things (IoT)
Europe Industrial IoT Market
Internet of Things (IoT)
Connected IoT Devices Market
Internet of Things (IoT)
Massive Machine Type Communication Market
Internet of Things (IoT)
Global Open IoT Platform Market
Internet of Things (IoT)
Europe IoT Device Market
Internet of Things (IoT)
IoT Monetization Market
Internet of Things (IoT)
IoT IAM Market