
 Intelligent IoT Market | 2026-2036
Intelligent IoT Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent IoT Market Foresight
South Korea's semiconductor foundry expansion is fragmenting as multiple governments subsidize domestic chip capacity for IoT edge processors. Microsoft leverages its Azure IoT platform to anchor enterprise deployments across industrial verticals. Cisco Systems specializes in secure gateway hardware that controls network entry points for distributed sensor arrays. Huawei Technologies dominates 5G-enabled IoT infrastructure in markets where its equipment meets national spectrum certifications.
Intelligent IoT denotes networked physical devices embedded with sensors, software, and connectivity protocols that enable autonomous data exchange and decision-making without human intervention, typically operating on sub-second latency thresholds for real-time control loops. Smart sensors and edge computing nodes constitute the hardware backbone, while machine learning algorithms process telemetry streams to trigger actuators or alert maintenance systems. Cloud-based deployment models currently capture the largest revenue pool due to enterprise preference for scalable analytics infrastructure, though edge computing architectures are expanding fastest as latency-sensitive applications multiply in autonomous systems and precision agriculture.
The EU AI Act classifies certain IoT decision systems as high-risk, mandating conformity assessments before CE marking permits market entry. The FCC in the United States manages spectrum allocation for unlicensed IoT bands, directly constraining device density and transmission power in dense urban deployments. China's MIIT enforces GB standards for networked product cybersecurity, creating divergent compliance obligations for multinational hardware suppliers. Stakeholders must monitor regulatory fragmentation across these jurisdictions when architecting product roadmaps and certification budgets.
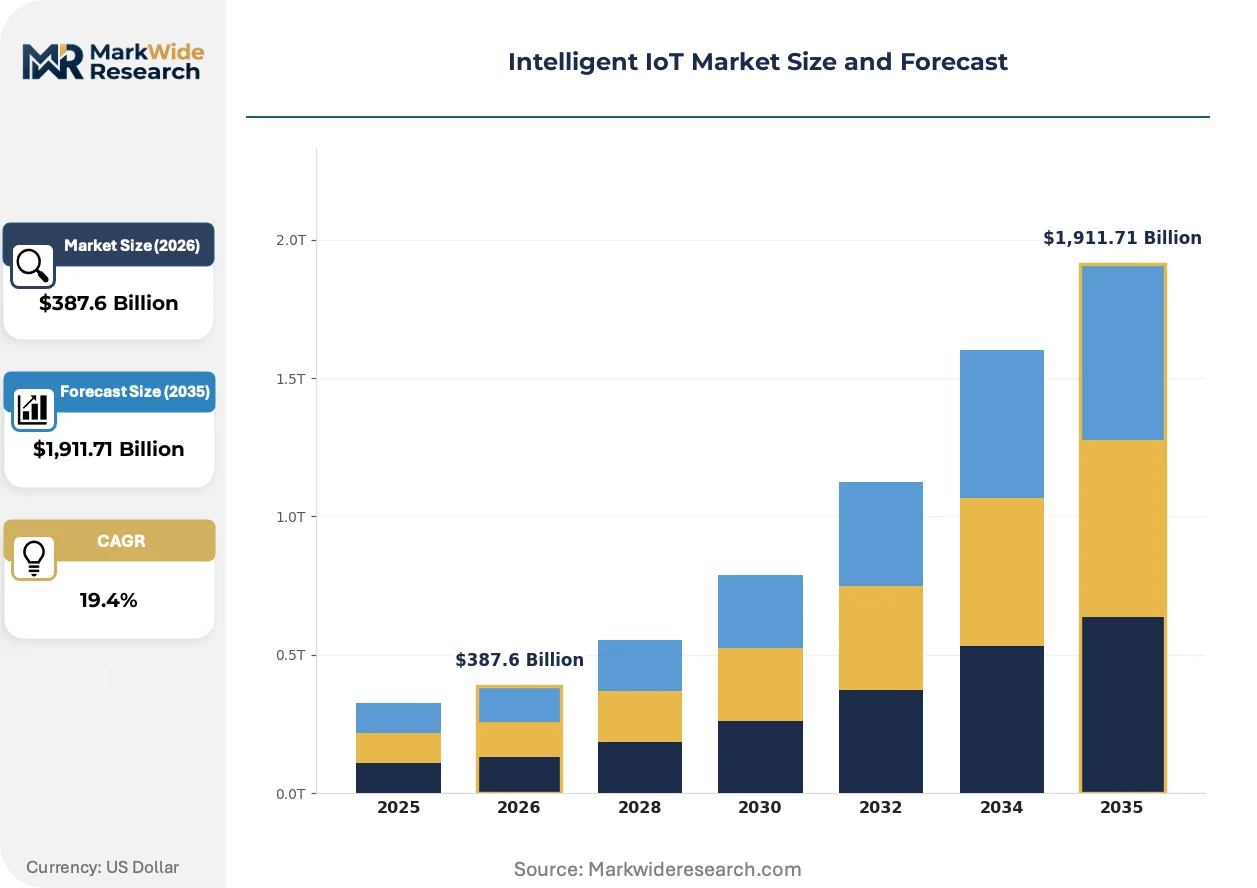
Market Dynamics
The Intelligent IoT market is compressing around latency requirements as autonomous control loops demand sub-second response times, forcing architectural trade-offs between cloud analytics and edge processing that reshape hardware procurement patterns and software licensing models.
Growth Catalysts
- Predictive maintenance mandates:Automotive and machinery producers in Germany's industrial corridor are deploying sensor arrays to preempt equipment failures, creating pull for vibration-analysis edge processors and digital-twin software stacks.
- EU AI Act compliance:High-risk classification of certain IoT decision systems triggers conformity assessment demand, expanding the addressable market for certified hardware and audit-ready firmware.
- Spectrum allocation:FCC management of unlicensed IoT bands in dense urban deployments enables higher device density, supporting smart city infrastructure buildouts and industrial campus networks.
Market Restraints
- Semiconductor supply concentration:Foundry capacity for IoT edge processors fragments across subsidized domestic programs, creating allocation uncertainty for fabless designers dependent on specific process nodes.
- Silicon input volatility:Wafer pricing fluctuations compress margins on high-volume sensor modules, particularly for cost-constrained smart agriculture and building automation deployments.
- Cybersecurity standard divergence:China's MIIT GB standards create parallel certification tracks that lengthen product development cycles and inflate compliance budgets for multinational hardware suppliers.
Strategic Opportunities
- Precision agriculture expansion:Soil-moisture and crop-health monitoring systems remain underdeployed in Brazilian and Australian farming regions, offering white space for solar-powered, low-bandwidth sensor networks.
- 5G infrastructure retrofit:National spectrum certifications in select markets create first-mover advantage for equipment vendors meeting localized radio-access requirements.
- Edge-cloud convergence:Hybrid architectures that split inference between field nodes and regional data centers are displacing pure cloud deployments in autonomous vehicle testing facilities and robotic manufacturing lines.
Industry Challenges
- Embedded systems talent scarcity:Firmware engineering for real-time operating systems competes with consumer electronics and automotive ECU development for limited specialist pools.
- Legacy protocol integration:Brownfield industrial sites running Modbus and PROFIBUS require gateway layers that add latency, cost, and failure points to greenfield IoT architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent IoT Market |
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,911.71 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
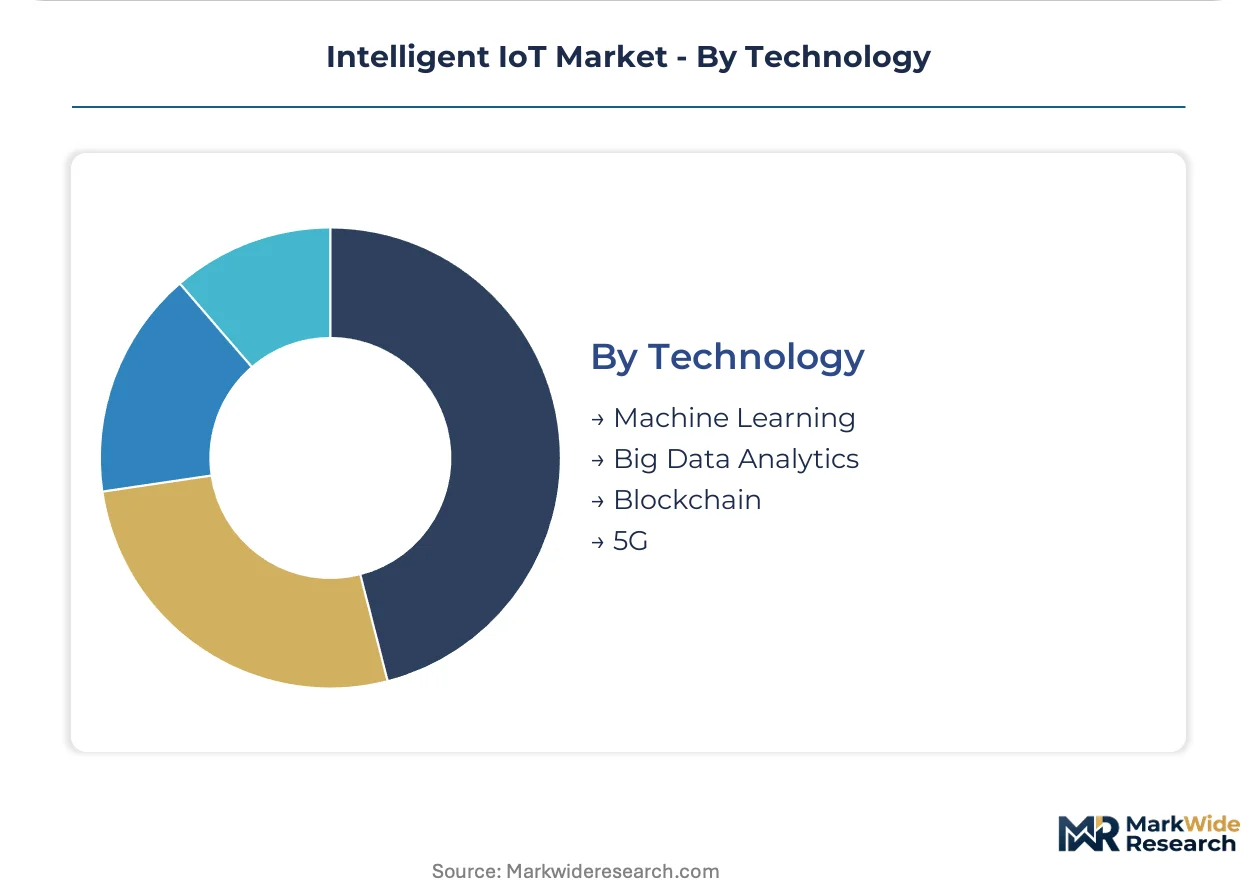
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Product Type: Smart Sensors, Actuators, Gateways, Controllers End User: Manufacturing, Healthcare, Transportation, Agriculture Technology: Machine Learning, Big Data Analytics, Blockchain, 5G |
| Companies Covered | Amazon Web Services, Microsoft, Google, IBM, Cisco Systems, Intel, Huawei Technologies, Siemens, SAP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent IoT Market Shifts & Advancements
Digital-twin virtualization is compressing the physical-to-software feedback loop across industrial verticals, enabling simulation-driven optimization that reduces prototype cycles and field-deployment risks.
TinyML inference engines are embedding directly into microcontroller-class devices, enabling anomaly detection and classification without cloud round-trips. Automotive suppliers are integrating these accelerators into tire-pressure and battery-management modules at accelerated procurement cadences. This architecture is digitizing maintenance workflows by shifting decision authority from centralized platforms to the sensor node itself.
The EU AI Act's high-risk system classification is mandating algorithmic transparency documentation and human-in-the-loop overrides for safety-critical IoT deployments. Industrial machinery OEMs must now maintain model provenance records and bias-testing protocols to secure CE marking. German automotive and robotics manufacturers are restructuring firmware development processes to embed conformity checkpoints earlier in release cycles.
Buying committees are unbundling hardware procurement from analytics software subscriptions, reversing prior bundled-service preferences. Industrial buyers now source sensors through distribution channels while negotiating cloud-platform contracts separately, compressing vendor lock-in and expanding multi-vendor architectures. This pattern is most pronounced in North American manufacturing and logistics verticals where procurement functions have centralized technology spend authority.
Intelligent IoT Market Segmentation

Architectural choices in deployment mode and product configuration determine latency budgets, certification pathways, and procurement cycles for intelligent IoT systems. Segmentation reveals where hardware commoditization pressures concentrate versus where software differentiation commands pricing power.
Deployment:
Cloud-based architectures turn over slowest due to entrenched enterprise SaaS contracts, while edge computing nodes refresh fastest as autonomous control loops demand iterative silicon upgrades.
- Cloud-Based:Centralized infrastructure hosts telemetry analytics and model training workloads on hyperscaler platforms. German automotive manufacturers anchor demand here for digital-twin simulation farms that require elastic compute pools. Procurement cycles stretch 36-48 months due to multi-year enterprise agreements and data residency requirements under GDPR.
- Edge Computing:Distributed inference nodes process sensor streams locally to hit sub-second latency thresholds for robotic control loops. Precision agriculture deployments in Australian farming regions and autonomous vehicle testing facilities in the United States drive fastest refresh rates as neural accelerator chips iterate annually. FCC spectrum allocations for unlicensed bands directly constrain device density in these deployments.
- On-Premises:Air-gapped installations serve defense and critical infrastructure operators with sovereign data requirements. BIS certification mandates in India and GB standards enforcement by China's MIIT lengthen procurement cycles for foreign equipment vendors.
- Hybrid:Split architectures partition inference between field nodes and regional data centers, common in brownfield industrial retrofits where Modbus gateway layers bridge legacy PROFIBUS networks.
Cloud-based deployment anchors the volume base while edge computing gains share at the steepest rate.
Product Type:
Margin structures diverge sharply: commodity sensor modules compete on silicon cost while gateway hardware extracts premiums from cybersecurity certification stacks.
- Smart Sensors:Microelectromechanical devices capture vibration, temperature, and environmental telemetry with embedded analog-to-digital conversion. South Korean foundry capacity expansion for MEMS wafers is fragmenting supply concentration, though allocation uncertainty persists for fabless designers targeting automotive tire-pressure monitoring modules.
- Gateways:Secure network entry points aggregate heterogeneous protocol streams and enforce segmentation policies. EU AI Act high-risk system classifications mandate conformity assessments for safety-critical gateway firmware, expanding addressable market for audit-ready hardware stacks. German machinery producers anchor premium procurement here.
- Actuators:Electromechanical output devices translate digital commands into physical motion for valve control, robotic joints, and HVAC damper positioning. Building automation in North American commercial real estate concentrates demand for low-cost, high-volume linear actuators.
- Controllers:Programmable logic units execute real-time control algorithms on deterministic operating systems. Embedded systems talent scarcity for RTOS firmware engineering constrains supplier expansion in this segment.
Smart sensors anchor the volume base while gateways gain share at the steepest rate.
End User:
Application maturity varies: manufacturing runs decade-old brownfield protocols while agriculture presents greenfield white space with minimal legacy integration burden.
- Manufacturing:Predictive maintenance mandates in Germany's industrial corridor drive sensor array deployment for vibration analysis and thermal monitoring. Brownfield sites running Modbus and PROFIBUS require gateway layers that add latency and failure points to IoT architectures.
- Agriculture:Soil-moisture and crop-health monitoring systems remain underdeployed in Brazilian and Australian farming regions. Solar-powered, low-bandwidth sensor networks face silicon input volatility that compresses margins on cost-constrained modules.
- Healthcare:Connected medical devices fall under FDA premarket notification pathways in the United States and MDR conformity assessment routes in Europe. HIPAA and GDPR data residency requirements constrain cloud deployment preferences.
- Transportation:Fleet telematics and autonomous vehicle testing facilities demand sub-second latency for control loop closure. NHTSA safety standards and EU AI Act algorithmic transparency mandates create divergent compliance tracks for decision-system hardware.
Manufacturing anchors the volume base while agriculture gains share at the steepest rate.
Technology:
Supply concentration sits upstream: machine learning frameworks depend on hyperscaler cloud infrastructure while 5G radio access equipment faces national spectrum certification fragmentation.
- Machine Learning:TinyML inference engines embed directly into microcontroller-class devices for anomaly detection without cloud round-trips. Automotive suppliers integrate these accelerators into battery-management modules at accelerated procurement cadences.
- 5G:Radio access infrastructure enables massive machine-type communications with guaranteed latency bounds. National spectrum certifications in select markets create first-mover advantage for equipment vendors meeting localized requirements; Huawei dominates where its equipment meets these certifications.
- Big Data Analytics:Stream processing platforms aggregate telemetry from distributed sensor fleets into actionable maintenance alerts. Procurement unbundling trends separate hardware sensor sourcing from cloud-platform contract negotiation.
- Blockchain:Distributed ledger protocols supply audit trails for supply chain provenance and device identity attestation. Adoption concentrates in pharmaceutical cold-chain monitoring where FDA 21 CFR Part 11 compliance demands immutable record-keeping.
Big data analytics anchors the volume base while 5G gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor consumes intelligent IoT through predictive maintenance arrays for automotive and machinery production, while the United States deploys identical hardware for autonomous vehicle testing and precision agriculture with divergent latency requirements.
United States
Fleet telematics operators and autonomous vehicle testing facilities in Arizona and California drive demand for sub-second control loop hardware. The FCC manages spectrum allocation for unlicensed IoT bands, constraining device density in dense urban deployments. Greater Boston anchors cloud-platform procurement for healthcare and logistics verticals under HIPAA data residency requirements.
Germany
Automotive OEMs and machinery producers in Baden-Württemberg and Bavaria deploy vibration-analysis sensor arrays for predictive maintenance mandates. The EU AI Act's high-risk system classification triggers conformity assessment demand for safety-critical gateway firmware. Stuttgart's industrial cluster concentrates procurement of audit-ready hardware stacks and digital-twin software platforms.
China
Smart factory investments in the Yangtze River Delta and Pearl River Delta absorb edge processors for robotic manufacturing lines. The MIIT enforces GB standards for networked product cybersecurity, creating divergent compliance tracks for multinational suppliers. Shenzhen's electronics corridor concentrates 5G-enabled infrastructure deployment where Huawei equipment meets national spectrum certifications.
South Korea
Semiconductor foundries in the Seoul Capital Area and Busan-Ulsan region expand MEMS wafer capacity for IoT edge processors. Government subsidy programs fragment domestic chip capacity allocation across multiple process nodes. Samsung's home market anchors accelerated procurement of TinyML accelerators for battery-management modules in automotive applications.
Australia
Precision agriculture deployments in New South Wales and Victoria drive solar-powered, low-bandwidth sensor network demand for soil-moisture monitoring. The TGA regulates connected medical devices under parallel pathways to FDA and EU frameworks. Queensland's farming regions present white space for crop-health monitoring systems with minimal legacy integration burden.
Intelligent IoT Market Competitive Landscape
Capability concentration sits with hyperscaler cloud platforms; scale advantage sits with semiconductor foundries and network infrastructure vendors. The market structures around three tiers: cloud analytics providers hosting telemetry workloads, secure gateway specialists controlling network entry points, and edge silicon fabricators supplying neural accelerators. Strategic moves center on hybrid architecture partnerships and national spectrum certification capture.
Within the cloud-platform tier, Amazon Web Services and Microsoft exemplify the infrastructure-as-a-service archetype that anchors enterprise SaaS contracts across industrial verticals. Cisco Systems occupies a position among secure gateway specialists, representing the network-hardware archetype that aggregates heterogeneous protocol streams. Huawei Technologies sits within the telecommunications-infrastructure tier, anchoring 5G-enabled deployment in markets where its equipment meets localized radio-access requirements.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| IBM |
| Cisco Systems |
| Intel |
| Huawei Technologies |
| Siemens |
| SAP |
| Others |
Supply & Pricing Matrix
The Yangtze River Delta freight corridor's container throughput cost dynamics compress margins on MEMS sensor modules while amplifying price differentiation between audit-ready gateway hardware and commodity edge processors. Supply concentration in South Korean foundries and Chinese electronics manufacturing feeds downstream tiering where EU AI Act-certified firmware commands substantial premiums over uncertified alternatives.
Pricing Analysis
Long-term offtake agreements dominate enterprise cloud-platform procurement, while spot-market transactions govern high-volume sensor module sourcing through Asian electronics distributors. Pricing stratifies across premium, standard, and economy tiers based on cybersecurity certification grade and after-sales service bundling. Cost compression in economy-tier smart sensors is intensifying because South Korean foundry allocation uncertainty forces fabless designers to absorb wafer pricing volatility. Automotive OEMs in Germany exhibit lowest price sensitivity due to predictive maintenance mandates, whereas Brazilian agricultural cooperatives face acute budget constraints for solar-powered monitoring networks.
Supply Chain Analysis
US export-control restrictions on advanced semiconductor manufacturing equipment limit foundry capacity expansion for neural accelerator chips in certain jurisdictions. Supply concentrates in Taiwan for leading-edge silicon, South Korea for MEMS wafer fabrication, and China for final assembly of cost-constrained sensor modules. Raw material dependencies span silicon wafers, rare-earth elements for magnetics, and lithium compounds for battery-backed edge devices. Single-source vulnerability pervades 5G radio-access equipment where national spectrum certifications create geographic vendor lock-in. Distribution runs through authorized distributors for enterprise gateways and direct OEM relationships for high-volume actuator procurement.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Intelligent IoT market functions as a service-attach opportunity where firmware update subscriptions and predictive maintenance analytics expand faster than hardware replacement cycles. Recurring revenue from digital-twin software platforms now outpaces sensor module sales growth in German automotive deployments.
For Market Incumbents: Pre-empt margin erosion in commodity sensor modules by securing captive MEMS wafer supply through foundry partnership structures in South Korea. Invest in EU AI Act conformity assessment capabilities ahead of CE marking enforcement waves. Threat substitution from open-source TinyML frameworks demands proprietary accelerator IP development. Channel control through authorized distributor networks remains essential for gateway hardware pricing power. For New Entrants and Emerging Players: Establish a beachhead in Australian precision agriculture where soil-moisture monitoring networks remain underdeployed and legacy integration burden is minimal. Target Brazilian farming cooperatives with solar-powered, low-bandwidth sensor architectures that bypass cellular infrastructure dependency. Go-to-market through agricultural equipment OEMs with bundled crop-health analytics subscriptions accelerates customer acquisition without direct enterprise sales overhead. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors edge-computing silicon specialists with established automotive qualification pathways over pure-play cloud analytics vendors. Long-term viability across the projection horizon hinges on hybrid architecture deployment share expansion. Acquisition target archetype: secure gateway vendors with EU AI Act audit-ready firmware stacks and existing German machinery OEM relationships. Signal to watch: FCC spectrum reallocation decisions for unlicensed IoT bands that would reshape device density economics in dense urban deployments.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Cloud Hybrid Architecture Development | Splits inference workloads between field nodes and regional data centers for sub-second latency compliance. |
| EU AI Act Conformity Certification Investment | Secures CE marking pathway for high-risk gateway firmware in German automotive and robotics verticals. |
| Secure Gateway Hardware Acquisition | Consolidates network entry point control and cybersecurity certification stack differentiation. |
| TinyML Accelerator IP Development | Embeds anomaly detection directly into microcontroller-class devices without cloud dependency. |
| Precision Agriculture Channel Partnership | Penetrates Brazilian and Australian farming regions through agricultural equipment OEM bundling. |
Research Methodology
A spread of perspectives from IoT platform engineers, industrial maintenance directors, semiconductor procurement leads, and regulatory compliance officers converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with firmware development executives at edge-processor vendors and procurement managers at German automotive OEMs. Secondary validation drew from FCC spectrum allocation filings, EU AI Act implementation guidance, MIIT GB standard enforcement notices, and hyperscaler IoT platform capex disclosures. Bottom-up sensor shipment estimates and top-down enterprise software spend analysis were triangulated to anchor volume and value projections.
Demand-supply balance dynamics across deployment modes, product configurations, and end-use verticals structured the analytical framework throughout the forecast period. Segmentation dimensions modeled include architectural deployment mode, hardware product type, end-user industry, and underlying technology stack. CAGRs were derived from iterative convergence of shipment-based volume trajectories and pricing trend assumptions. Industry-specific forecast inputs encompassed South Korean foundry capacity expansion schedules and EU AI Act conformity assessment timeline projections.
Stress conditions across semiconductor allocation volatility, spectrum reallocation scenarios, and cybersecurity standard divergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding enterprise cloud-platform contract renewal rates and edge-computing refresh cadences. Material shifts in US export-control scope or EU AI Act enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Cellular Machine to Machine Market
Internet of Things (IoT)
LAMEA Bluetooth 5.0 Market
Internet of Things (IoT)
Global IoT Managed Services Market
Internet of Things (IoT)
IIOT Gateway for Utility Market
Internet of Things (IoT)
US Smart Thermostat Market
Internet of Things (IoT)
Europe Industrial IoT Market
Internet of Things (IoT)
IoT Network Management Market
Internet of Things (IoT)
Satellite IoT Communication Market
Internet of Things (IoT)
Wireless Smart Plug Market
Internet of Things (IoT)
UK IoT Software Market
Internet of Things (IoT)
IoT in Retail Market
Internet of Things (IoT)
Airport Internet of Things Market
Internet of Things (IoT)
Narrowband-Internet of Things (NB-IoT) Market
Internet of Things (IoT)
IoT in Chemical Industry Market
Internet of Things (IoT)
Global IoT Node and Gateway Market
Internet of Things (IoT)
Solar Based Internet of Things (IoT) Market