
 IoT Services Market | 2026-2036
IoT Services Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Services Market Intelligence
The shift from on-premise hardware to cloud-based infrastructure is shifting the economic models for IoT deployments. This transition favors hyperscale cloud providers and integrated service firms. Amazon Web Services dominates the underlying infrastructure-as-a-service layer for many IoT platforms. Microsoft leverages its vast enterprise software ecosystem to bundle IoT services with existing business applications. Meanwhile, IBM specializes in providing complex integration and consulting services for hybrid cloud environments in regulated industries.
IoT services encompass the professional and managed offerings required to design, deploy, and operate large-scale networks of connected devices. These services manage the data pipeline from sensor data acquisition to network transport, cloud storage, and final analysis. The primary purpose is to convert raw device data into actionable business intelligence for applications like predictive maintenance. Within service types, Data Analytics and Security Services command the highest value. Industrial Automation and Smart Cities applications represent the largest segments for service expenditure.
Data governance and security standards are critical regulatory considerations shaping the market. Frameworks like the EU's GDPR and upcoming AI Act impose strict rules on data processing and algorithmic transparency. In the United States, guidelines from NIST provide a baseline for cybersecurity practices in critical infrastructure deployments. Vendor success depends on the ability to deliver solutions that comply with this fragmented, evolving landscape of international and national data privacy laws.
Market Dynamics
The primary structural force shaping the IoT services market is the tension between the push for standardized, interoperable platforms and the persistent demand for highly customized solutions tailored to specific industrial workflows and legacy system constraints.
Growth Catalysts
- 5G and Edge Computing:The rollout of 5G networks and edge computing infrastructure provides the low-latency, high-bandwidth connectivity essential for real-time data processing in applications like industrial automation and autonomous vehicles.
- Smart City Mandates:Government initiatives across countries like India and Germany are funding large-scale smart city projects, creating systemic demand for integrated services in traffic management, public safety, and utility monitoring.
- Predictive Maintenance Demand:A strong pull from the manufacturing sector for predictive maintenance services aims to reduce equipment downtime and optimize operational efficiency, directly converting sensor data into measurable cost savings.
Market Restraints
- Interoperability Gaps:A lack of universal standards between competing IoT ecosystems and legacy operational technology (OT) systems creates significant integration friction, increasing deployment complexity and total cost of ownership.
- Fragmented Data Regulations:The complex and evolving web of data privacy laws, including the EU's GDPR and various state-level regulations in the United States, imposes significant compliance burdens on service providers.
- High Initial Investment:The substantial upfront capital required for deploying extensive sensor networks, gateways, and private communication infrastructure acts as a barrier for many small and medium-sized enterprises.
Strategic Opportunities
- Precision Agriculture Services:IoT services for precision agriculture, including soil moisture sensing and automated irrigation, represent a significant growth area, particularly in regions facing water scarcity and pressure to improve crop yields.
- AIoT for Autonomy:The convergence of artificial intelligence with IoT (AIoT) opens opportunities for advanced services that enable autonomous decision-making in logistics, robotics, and energy grid management without human intervention.
- SME Digitization in Southeast Asia:Small and medium-sized enterprises in developing economies, especially within Southeast Asia, represent an underpenetrated market for scalable, cloud-based IoT service packages as they begin their digital transformation.
Industry Challenges
- Cybersecurity and Data Science Talent Scarcity:A critical shortage of professionals with expertise in both cybersecurity for connected devices and data science for analytics hinders the ability of service providers to scale operations securely.
- Legacy System Integration:Integrating modern IoT service platforms with entrenched, proprietary legacy systems in industrial environments without causing operational disruption remains a major technical and logistical challenge for deployment teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Services Market |
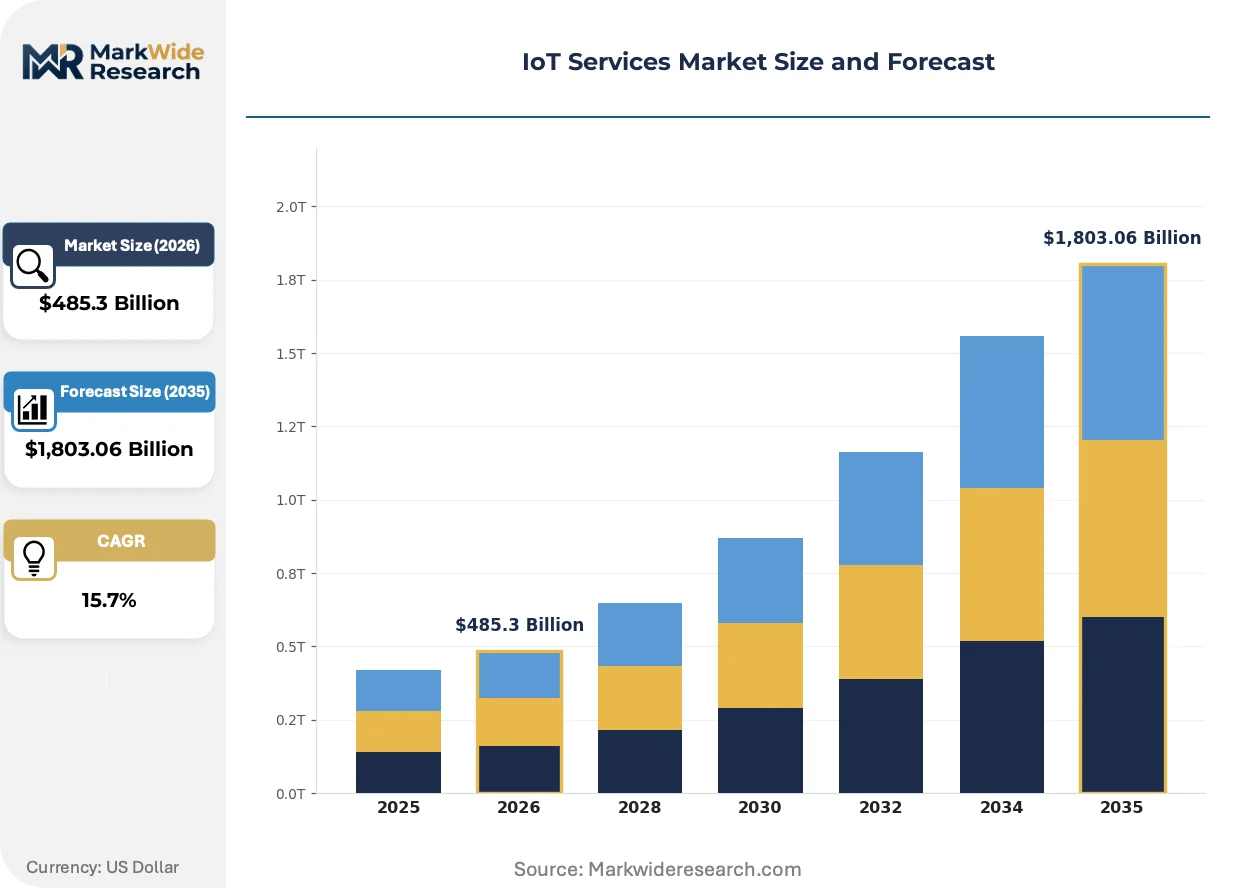
| Market Size in 2026 | $485.3 Billion |
| Market Size in 2035 | $1,803.06 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Connectivity Management, Data Analytics, Device Management, Security Services, Consulting Deployment: Cloud-Based, Edge Computing, On-Premise, Hybrid Application: Smart Cities, Smart Agriculture, Industrial Automation, Connected Logistics, Building Management End User: Manufacturing Enterprises, Energy Operators, Public Transport Providers, Telecommunications Firms, Utilities Operators |
| Companies Covered | Amazon Web Services, Microsoft, IBM, Cisco Systems, Accenture, Deloitte, Tata Consultancy Services, AT&T, Capgemini, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Services Market Strategic Shifts & Innovations
The market's evolution is defined by the push to embed intelligence directly into connected endpoints and the strategic shift toward monetizing continuous data streams. This transition moves the value proposition from simple connectivity to delivering automated, data-driven outcomes.
Digital Twin technology creates a dynamic, virtual replica of a physical asset, system, or process, updated in real time with sensor data. Heavy industry sectors, including aerospace and automotive manufacturing, are the primary adopters. This sophisticated modeling is automating complex tasks like stress-test simulations, predictive failure analysis, and supply chain optimization, reducing the need for physical prototypes and manual inspections.
Legislation like the European Union's AI Act establishes a risk-based legal framework for artificial intelligence systems. This regulation imposes stringent requirements for transparency, data governance, and human oversight on high-risk AI applications, many of which are central to IoT services. Service providers operating in sectors like critical infrastructure and healthcare are now re-architecting their analytics platforms to ensure documented compliance and algorithmic fairness.
Enterprises are increasingly moving away from large, one-time project investments toward subscription and consumption-based models for acquiring IoT capabilities. This "as-a-Service" approach replaces capital expenditure with predictable operational costs, lowering the barrier to entry. The shift is most pronounced in the smart buildings and industrial asset management segments, where customers pay for guaranteed outcomes like energy savings or equipment uptime.
IoT Services Market Segmentation
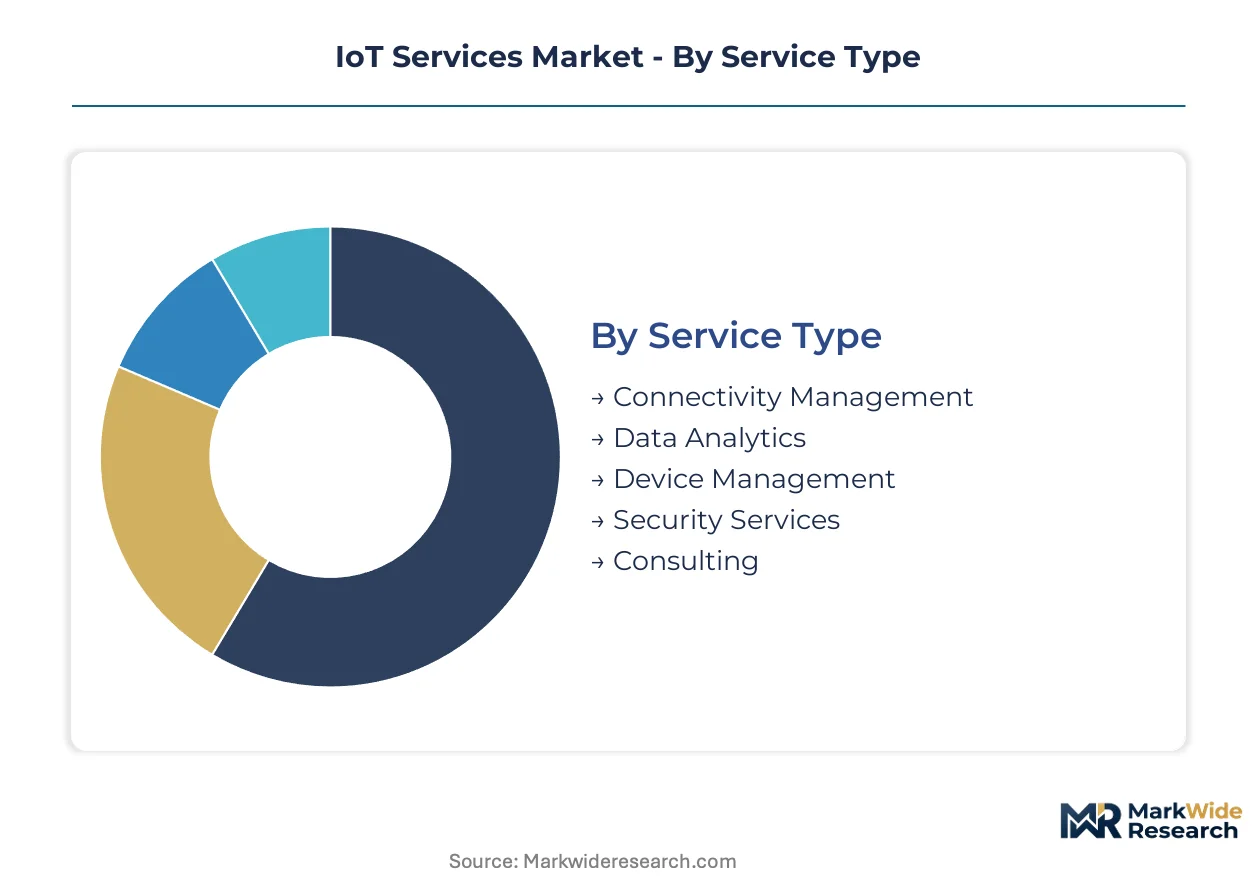
Segmentation provides a granular understanding of the IoT services market, revealing distinct needs and growth trajectories across various dimensions. This detailed breakdown helps stakeholders identify high-value opportunities and tailor service offerings to specific industry requirements.
Service Type:
Compliance burdens heavily influence the service type segmentation, particularly concerning regulatory approvals and data governance frameworks.
- Data Analytics:Data analytics services transform raw sensor data into actionable business intelligence, enabling applications like predictive maintenance. Demand concentrates in technology hubs within the United States and Germany, driven by the need for operational efficiency.
- Security Services:Security services protect connected devices, networks, and data from cyber threats, ensuring system integrity and data privacy. Stringent frameworks like the EU's GDPR and NIST guidelines in the United States drive significant investment in these offerings.
- Connectivity Management:Connectivity management services oversee the communication links between IoT devices and cloud platforms, optimizing network performance.
- Device Management:Device management offerings handle the provisioning, monitoring, and updating of IoT endpoints across large-scale deployments.
- Consulting:Consulting services provide expert guidance for IoT strategy, solution design, and complex system integration in regulated industries.
Connectivity Management sits at the top of the volume ranking, with Data Analytics climbing the fastest.
Deployment:
Cost structures and infrastructure requirements define the deployment segmentation, influencing initial capital outlay and operational expenditure.
- Cloud-Based:Cloud-based deployment leverages hyperscale providers like Amazon Web Services for scalable data storage and processing, reducing on-premise hardware needs. This model attracts enterprises seeking lower upfront investment and flexible resource allocation for their IoT initiatives.
- Edge Computing:Edge computing processes data closer to the source of generation, minimizing latency for real-time applications in industrial automation and autonomous systems. The rollout of 5G networks provides essential low-latency, high-bandwidth connectivity for these deployments.
- On-Premise:On-premise deployments maintain data and infrastructure within the user's physical control, often preferred by regulated industries for security.
- Hybrid:Hybrid deployments combine elements of cloud and on-premise solutions, balancing scalability with specific data sovereignty needs.
Cloud-Based solutions lead in new deployments, while Edge Computing shows significant momentum in critical infrastructure applications.
Application:
The application segmentation highlights diverse use cases, each presenting unique operational challenges and data monetization opportunities.
- Industrial Automation:Industrial automation applications utilize IoT services to optimize manufacturing processes, monitor equipment health, and enhance operational efficiency. A strong pull from the manufacturing sector drives demand for predictive maintenance services.
- Smart Cities:Smart cities applications integrate IoT for traffic management, public safety, and utility monitoring, enhancing urban livability. Government initiatives in countries like India and Germany fund large-scale projects, creating systemic demand.
- Smart Agriculture:Smart agriculture services, including soil moisture sensing, optimize crop yields and resource usage in regions facing water scarcity.
- Connected Logistics:Connected logistics solutions track assets, monitor supply chains, and optimize delivery routes for improved efficiency and transparency.
- Building Management:Building management systems use IoT for energy optimization, security, and occupant comfort within commercial and residential structures.
Industrial Automation and Smart Cities applications collectively account for the largest service expenditure, driving significant market expansion.
End User:
Customer type dictates specific service requirements, ranging from large-scale industrial operations to public sector infrastructure management.
- Manufacturing Enterprises:Manufacturing enterprises deploy IoT services for asset tracking, predictive maintenance, and quality control across production lines. The need to reduce equipment downtime and optimize operational efficiency drives investment in these technologies.
- Telecommunications Firms:Telecommunications firms are essential enablers of IoT connectivity, providing network infrastructure and managed services for various deployments. Their role in 5G rollout and edge computing infrastructure development is central to market growth.
- Energy Operators:Energy operators leverage IoT for grid management, smart metering, and remote monitoring of power generation assets.
- Public Transport Providers:Public transport providers utilize IoT for fleet management, passenger information systems, and infrastructure maintenance in urban environments.
- Utilities Operators:Utilities operators implement IoT for water management, waste collection optimization, and smart grid solutions across municipal networks.
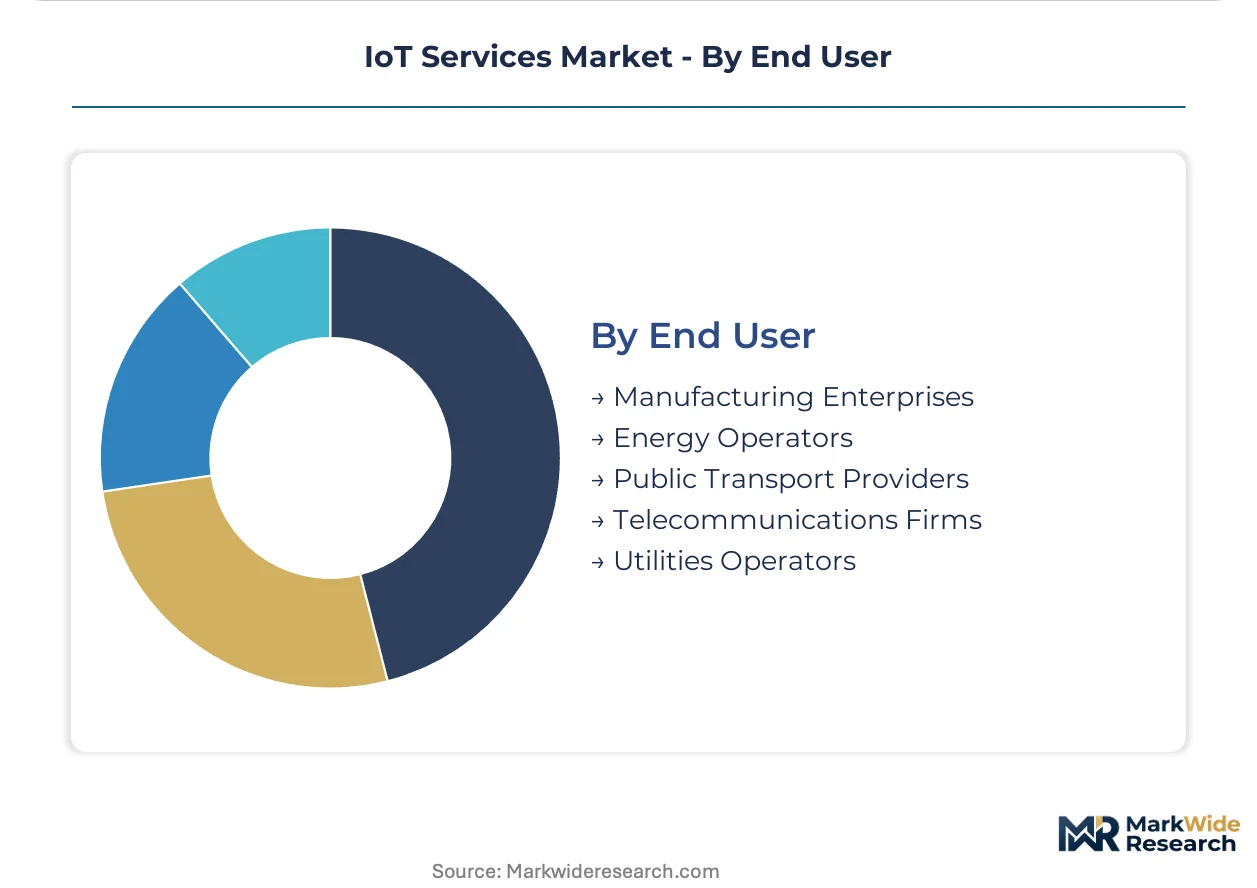
Manufacturing Enterprises represent a foundational customer base, while Telecommunications Firms are strategically positioned for future growth as connectivity demands increase.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technology hubs worldwide drive the IoT services market, where regional variations in digital infrastructure and regulatory frameworks significantly influence adoption. Compliance burdens and infrastructure development shape market expansion. Specific national policies and government initiatives accelerate market growth in key economies.
United States
Robust demand for data analytics and security services characterizes the United States market. NIST guidelines provide a baseline for cybersecurity practices in critical infrastructure deployments. Major technology centers, including Silicon Valley and Boston, concentrate innovation in AIoT and advanced analytics applications.
Germany
Industrial automation and smart city initiatives propel the IoT services market in Germany. The EU AI Act and GDPR impose strict rules on data processing, influencing service provider offerings. Manufacturing clusters in Bavaria and North Rhine-Westphalia are early adopters of predictive maintenance solutions.
India
Large-scale smart city projects and digitization efforts drive demand for integrated IoT services across India. Government initiatives actively fund infrastructure development for traffic management and public safety. Technology hubs in Bengaluru and Hyderabad are experiencing significant growth in cloud-based IoT deployments.
China
Industrial automation and 5G-enabled applications are significant growth areas for IoT services in China. Policies from the Ministry of Industry and Information Technology (MIIT) support digital transformation across manufacturing sectors. The Yangtze River Delta region demonstrates strong adoption of smart factory solutions.
Japan
The demand for predictive maintenance and advanced manufacturing solutions underpins the IoT services market in Japan. METI initiatives encourage smart factory development and industrial IoT adoption. Major manufacturing centers in Tokyo and the Kansai region leverage IoT for operational efficiency.
IoT Services Market Key Industry Players
Global majors compete with regional champions across service specialization and geographic reach within the IoT services market. The market features a blend of hyperscale cloud providers, integrated IT service firms, and specialized consultants. Strategic partnerships and portfolio diversification are dominant competitive moves among market participants.
Technology platform providers like Amazon Web Services and Microsoft exemplify the hyperscale approach, offering extensive cloud infrastructure for IoT deployments. IBM occupies a position as a specialist in complex integration and consulting services for hybrid cloud environments in regulated industries.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| IBM |
| Cisco Systems |
| Accenture |
| Deloitte |
| Tata Consultancy Services |
| AT&T |
| Capgemini |
Cost & Logistics Intelligence
Cloud computing instance pricing directly influences the cost structures for IoT service providers, cascading into varied service pricing tiers. This dynamic impacts offerings from basic connectivity to advanced data analytics, shaping market competitiveness.
Pricing Analysis
Input-cost pass-through is evident as hyperscale cloud infrastructure expenses directly affect IoT service pricing. The dominant pricing model is consumption-based, often structured as "as-a-Service" subscriptions, where customers pay for guaranteed outcomes like energy savings. Price differentiation stems from customization levels for industrial workflows and the stringency of service level agreements. Pricing softness reflects intense competition among providers and the drive for market share, particularly for standardized offerings. Small and medium-sized enterprises (SMEs) exhibit the highest price sensitivity, favoring scalable, lower-cost packages.
Supply Chain Analysis
Domestic-content mandates, particularly in critical infrastructure projects, are reshaping sourcing for IoT hardware components. Geographic supply concentration for core IoT devices, including sensors and communication modules, remains heavily centered in China and Taiwan. The industry relies on a consistent supply of specialized semiconductors and robust networking equipment. Geopolitical tensions and trade restrictions represent a structural risk to hardware availability. Distribution runs through a hybrid model, combining direct sales to large enterprises with channel partnerships and cloud marketplace integrations for broader market reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a geographic-arbitrage play, as the cost of cybersecurity and data science talent significantly varies between established technology hubs in the United States and emerging markets in Southeast Asia. Service providers can leverage these differentials to optimize operational expenditures.
For Market Incumbents:Anticipate regulatory divergence, particularly between the EU AI Act and US guidelines, by building flexible compliance frameworks into platform architectures. Consolidate market share through strategic acquisitions of specialized AIoT firms to counter emerging niche competitors. The talent scarcity in cybersecurity and data science poses a significant threat to scaling operations. Invest in internal R&D for advanced security protocols and integration tools to deepen vertical integration.
For New Entrants and Emerging Players:Small and medium-sized enterprises (SMEs) in Southeast Asia represent an underserved buyer archetype with significant growth potential for IoT services. Target precision agriculture solutions and smart building management as white-space opportunities. The most penetrable segment involves cloud-based, scalable packages with clear, outcome-based pricing. A go-to-market angle focusing on rapid deployment and measurable ROI will resonate strongly with these businesses.
For Investors and Strategic Acquirers:Consolidation pressure builds where interoperability gaps and fragmented regulatory landscapes create integration challenges for customers. Long-term viability over the next decade favors providers offering comprehensive, compliant, and integrated AIoT platforms. Target acquisition archetypes include specialized data analytics firms with strong intellectual property in algorithmic transparency or edge computing solution providers. The signal to watch is the widespread adoption of digital twin technology across new industrial verticals, indicating maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen AIoT Integration | Enhances autonomous decision-making capabilities for industrial automation applications. |
| Expand Compliance-as-a-Service | Mitigates regulatory burdens for enterprises navigating the EU AI Act and GDPR. |
| Invest in Edge Computing Infrastructure | Provides low-latency processing essential for real-time applications like autonomous vehicles. |
| Develop Outcome-Based Pricing Models | Lowers entry barriers for SMEs by shifting from CAPEX to predictable operational costs. |
| Form Regional Cybersecurity Partnerships | Addresses the critical talent scarcity in cybersecurity for connected devices. |
Research Approach
Multiple input streams — industry white papers, regulatory filings, and financial reports — were reconciled to build a comprehensive view of the IoT services market. Primary interviews with CTOs, enterprise procurement leads, data privacy officers, and industrial automation engineers provided granular insights. Secondary data from government technology initiatives, cloud provider disclosures, and academic research validated market trends. This approach employed both bottom-up market sizing and top-down validation for robust data triangulation.
Historical market data was cross-referenced with expert panel input to project market trajectories across the analysis window. The analytical framework modeled segmentation dimensions including service type, deployment, application, and end-user, alongside regional regulatory impacts. Compound Annual Growth Rates were derived from a multi-variant regression analysis. Key forecast inputs included 5G rollout schedules and smart city project funding commitments.
Underlying measurement precision varies by segment; Industrial Automation and Smart Cities applications carry tighter precision than others due to established project metrics. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Geopolitical shifts impacting semiconductor supply chains represent a significant risk factor for revisions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Wireless Connected Devices Market
Internet of Things (IoT)
Global Open IoT Platform Market
Internet of Things (IoT)
North America Internet of Things Devices Market
Internet of Things (IoT)
Global IoT Managed Services Market
Internet of Things (IoT)
Global IoT Connectivity Market
Internet of Things (IoT)
Telecom Internet of Things (IoT) Market
Internet of Things (IoT)
IoT Data Management Market
Internet of Things (IoT)
Internet of Things (IoT) Platform Market
Internet of Things (IoT)
Global IoT Solutions and Services Market
Internet of Things (IoT)
IoT Utilities Market
Internet of Things (IoT)
LPWAN in the Consumer IoT Market
Internet of Things (IoT)
Global IoT in Smart Cities Market
Internet of Things (IoT)
IoT Application Development Services Market
Internet of Things (IoT)
Industrial IoT Market
Internet of Things (IoT)
Europe IoT Services Market
Internet of Things (IoT)
Wireless Smart Plug Market