
 Telecom Internet of Things (IoT) Market | 2026-2036
Telecom Internet of Things (IoT) Market Size, Share, and Industry Trends Forecast 2026-2036
Telecom Internet of Things (IoT) Market Analytics
3GPP Release 17 certification for reduced capability (RedCap) devices is unwinding the vendor landscape by restricting early movers to a narrower pool of qualified chipset suppliers. AT&T leverages its nationwide LTE-M footprint to anchor enterprise contracts in fleet and utility verticals. Huawei Technologies Co., Ltd. sustains integrated baseband-to-cloud stacks that dominate domestic Chinese deployments. Deutsche Telekom AG differentiates through multi-national eSIM orchestration across European manufacturing corridors.
Telecom Internet of Things denotes cellular-enabled machine-to-machine communication architectures where sensors, actuators, and gateways transmit telemetry over licensed spectrum with defined latency bounds, typically sub-100 milliseconds for LTE-M and sub-10 seconds for NB-IoT, to enable remote monitoring, predictive maintenance, and automated control in distributed industrial systems. NB-IoT and LTE-M connectivity categories now capture the bulk of new subscription additions as utilities and municipalities favor licensed spectrum reliability over unlicensed alternatives. Smart Home and Industrial Automation application segments lead current revenue pools, though Asset Tracking shows the steepest trajectory as cold-chain logistics operators mandate real-time location verification.
FCC spectrum auctions in the United States and the EU Cybersecurity Act's IoT certification framework in Europe are tightening device compliance requirements before network authorization. China's MIIT enforces GB/T national standards for IoT terminal interoperability that shape procurement specifications for state-connected infrastructure. India's TRAI machine-to-machine communication guidelines mandate embedded SIM registration protocols that filter out non-compliant module vendors. Stakeholders must monitor evolving national certification reciprocity agreements that will determine which device portfolios qualify for cross-border deployment without redundant testing cycles.
Market Dynamics
3GPP Release 17 RedCap certification is compressing the qualified chipset supplier pool and forcing module vendors to requalify hardware designs against tighter latency and power benchmarks.
Growth Catalysts
- 5G Network Slicing:3GPP standards now enable service-level agreements with guaranteed latency bounds for mission-critical industrial automation, attracting automotive and electronics manufacturers to cellular IoT over unlicensed alternatives.
- China Smart City Directives:State-backed infrastructure deployment under MIIT national standards creates concentrated procurement pull for NB-IoT metering and environmental monitoring across municipal utilities.
- EU Cybersecurity Act:The IoT certification framework mandates baseline security requirements that filter out low-cost non-compliant vendors, improving average contract values for qualified device suppliers.
Market Restraints
- RedCap Qualification Bottleneck:Early movers face 12-18 month hardware redesign cycles as only a narrowed pool of baseband suppliers achieves 3GPP Release 17 certification.
- Spectrum Auction Costs:FCC mid-band auctions in the United States have raised carrier capex commitments, delaying rural LTE-M densification timelines.
- Silicon Supply Concentration:Advanced node fabrication for low-power wide-area chipsets concentrates among Taiwan and South Korea foundries, exposing module vendors to geopolitical disruption risk.
Strategic Opportunities
- India TRAI M2M Guidelines:Embedded SIM registration protocols are filtering out non-compliant module vendors, creating first-mover advantage for carriers with pre-certified eSIM orchestration platforms.
- Cold-Chain Asset Tracking:Pharmaceutical and perishable logistics operators now mandate real-time location verification, opening premium subscription tiers for multi-mode cellular-satellite hybrids.
- RedCap-LTE Convergence:Reduced capability devices bridging NB-IoT power efficiency with LTE-M throughput are enabling new predictive maintenance applications in distributed renewable energy infrastructure.
Industry Challenges
- Embedded Security Engineering Talent:Shortage of firmware developers with hardware-level cryptography expertise delays product launches for vendors targeting EU Cybersecurity Act certification.
- Legacy SCADA Integration:Industrial automation buyers require protocol translation layers between cellular IoT gateways and decades-old Modbus or PROFIBUS plant networks, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telecom Internet of Things (IoT) Market |
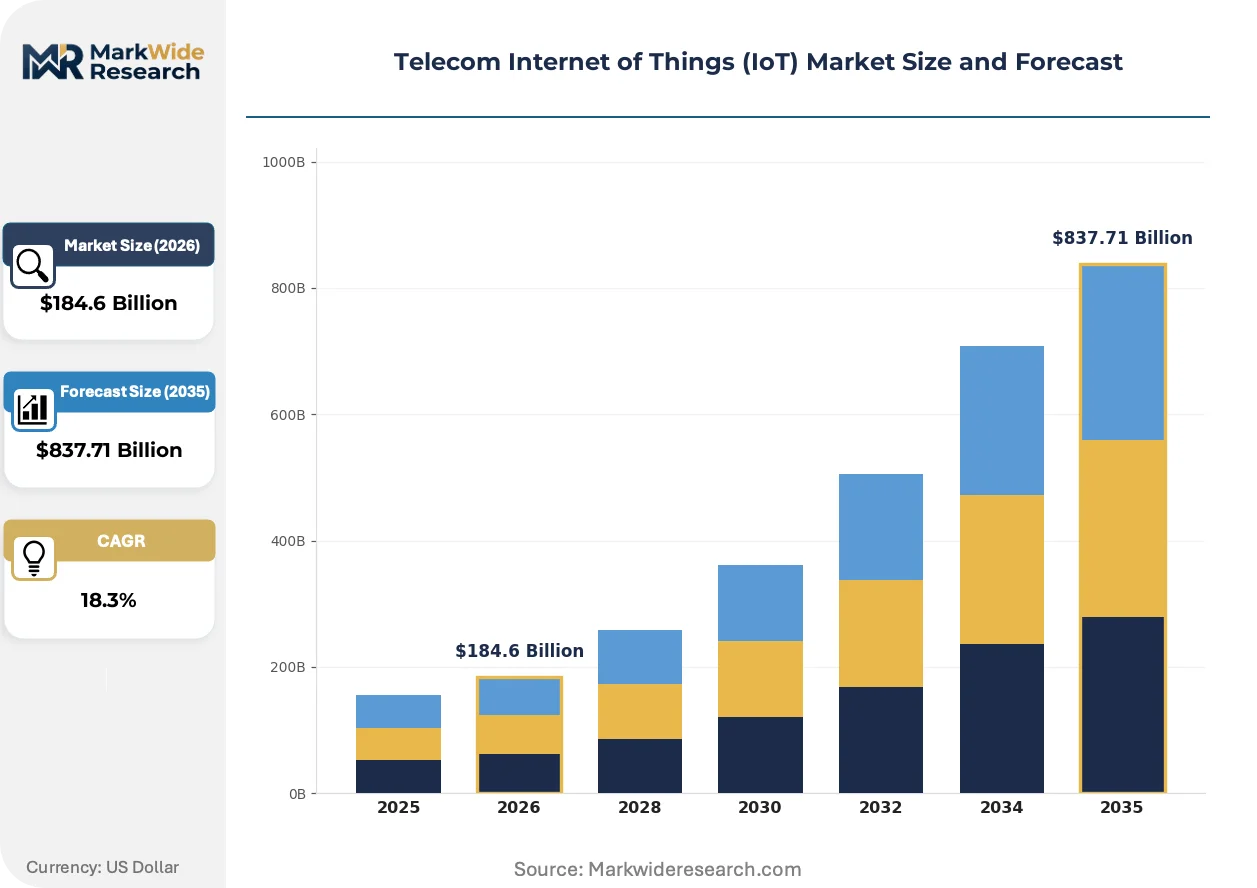
| Market Size in 2026 | $184.6 Billion |
| Market Size in 2035 | $837.71 Billion |
| CAGR (2026 – 2036) | 18.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Smart Home, Industrial Automation, Healthcare Monitoring, Asset Tracking Connectivity: NB-IoT, LTE-M, Sigfox, LoRaWAN Device Type: Sensors, Actuators, Gateways, Modules End User: Transportation, Utilities, Manufacturing, Retail |
| Companies Covered | AT&T, Verizon, Vodafone Group, Deutsche Telekom AG, Huawei Technologies Co., Ltd., Telefonaktiebolaget LM Ericsson, China Mobile Limited, BT Group, Aeris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telecom Internet of Things (IoT) Market Evolving Landscape
Cellular IoT architectures are fragmenting into specialized connectivity tiers as RedCap, LTE-M, and NB-IoT each find distinct latency-throughput niches, forcing module vendors to maintain parallel hardware roadmaps.
Reduced capability (RedCap) chipsets are decomposing the traditional LTE-M hardware stack by stripping carrier aggregation and MIMO layers while retaining mobility management, allowing automotive telematics suppliers to halve bill-of-materials costs for mid-tier fleet tracking units without sacrificing handover reliability on highways.
EU Cybersecurity Act IoT certification frameworks are mandating secure boot chains and cryptographic attestation for network authorization, compelling module vendors to redesign firmware architectures and partner with specialized hardware security module suppliers before CE marking approval.
Enterprise buyers in Germany and France are unbundling connectivity from platform subscriptions, negotiating direct carrier contracts for LTE-M data pools while sourcing device management software from independent cloud vendors, compressing margins for integrated stack providers that previously captured both layers.
Telecom Internet of Things (IoT) Market Segmentation
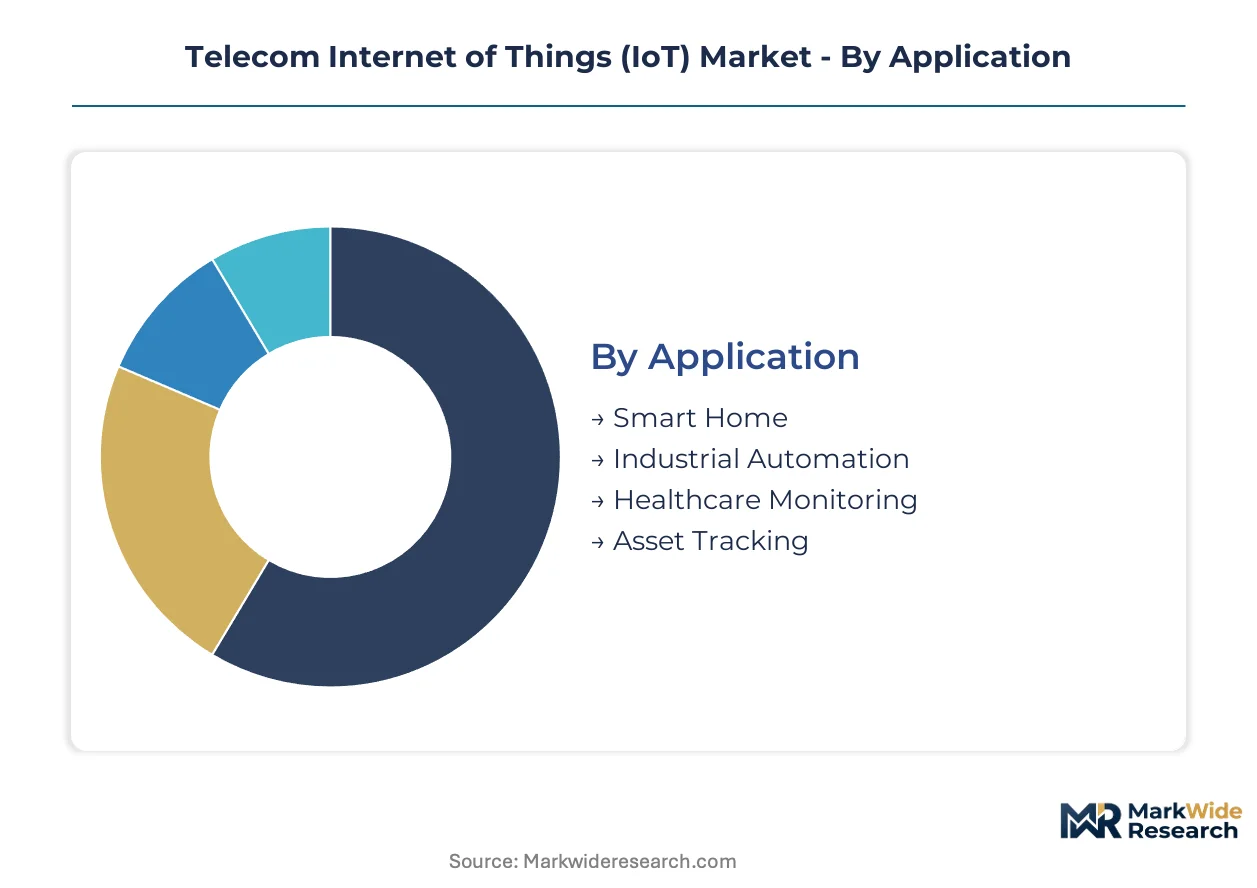
Telecom IoT procurement patterns diverge sharply across application contexts and connectivity tiers. Understanding these fault lines reveals where module vendors must maintain parallel certification roadmaps versus where single-technology specialization suffices.
Application:
Demand spreads across domestic infrastructure builds and export-led industrial contracts with uneven geographic concentration.
- Smart Home:Connected thermostats, security systems, and appliance controllers rely on Wi-Fi and Zigbee fallback with cellular backup for out-of-home monitoring. Chinese OEMs dominate hardware supply while European service providers bundle subscription management, creating bifurcated value capture.
- Industrial Automation:Predictive maintenance sensors and robotic controllers require sub-100 millisecond latency bounds that LTE-M and 5G RedCap now deliver. German automotive suppliers and South Korean electronics manufacturers drive specification-setting for multi-site deployment templates.
- Healthcare Monitoring:Remote patient wearables and chronic disease trackers transmit biometric telemetry over licensed spectrum to satisfy HIPAA and GDPR data residency requirements.
- Asset Tracking:Cold-chain logistics operators mandate real-time location verification across pharmaceutical and perishable supply chains, opening premium tiers for cellular-satellite hybrid connectivity.
Industrial Automation commands the established base. The steepest expansion runs through Asset Tracking.
Connectivity:
Cost tier separation determines whether deployments prioritize battery longevity, bandwidth, or spectrum licensing economics.
- NB-IoT:Narrowband protocols optimize for decade-long battery life in stationary metering applications. Chinese municipal utilities under MIIT directives deploy tens of millions of units for smart gas and water infrastructure.
- LTE-M:Machine-type communication retains mobility management and voice fallback for fleet telematics. AT&T's nationwide footprint anchors enterprise contracts across United States transportation corridors.
- Sigfox:Ultra-narrowband unlicensed service operates in proprietary regional networks with limited interoperability, constraining cross-border logistics applications.
- LoRaWAN:Long-range unlicensed protocol serves private campus deployments and agricultural monitoring where carrier subscription costs outweigh self-managed gateway capital expenditure.
NB-IoT holds the volume base. LTE-M gains share fastest as mobility requirements proliferate.
Device Type:
Supply concentration varies by component complexity and security certification burden.
- Sensors:Temperature, pressure, and vibration transducers dominate unit shipments with commoditized hardware margins.
- Actuators:Motor controllers and valve positioners integrate power electronics that concentrate qualified supplier pools in Taiwan and South Korea.
- Gateways:Edge aggregation devices require protocol translation layers for legacy SCADA integration, extending deployment timelines in German and French manufacturing plants.
- Modules:Certified cellular radios face 12-18 month RedCap requalification cycles that compress vendor margins until 3GPP Release 17 certification spreads.
Modules absorb the certification complexity. Sensors scale fastest on unit economics.
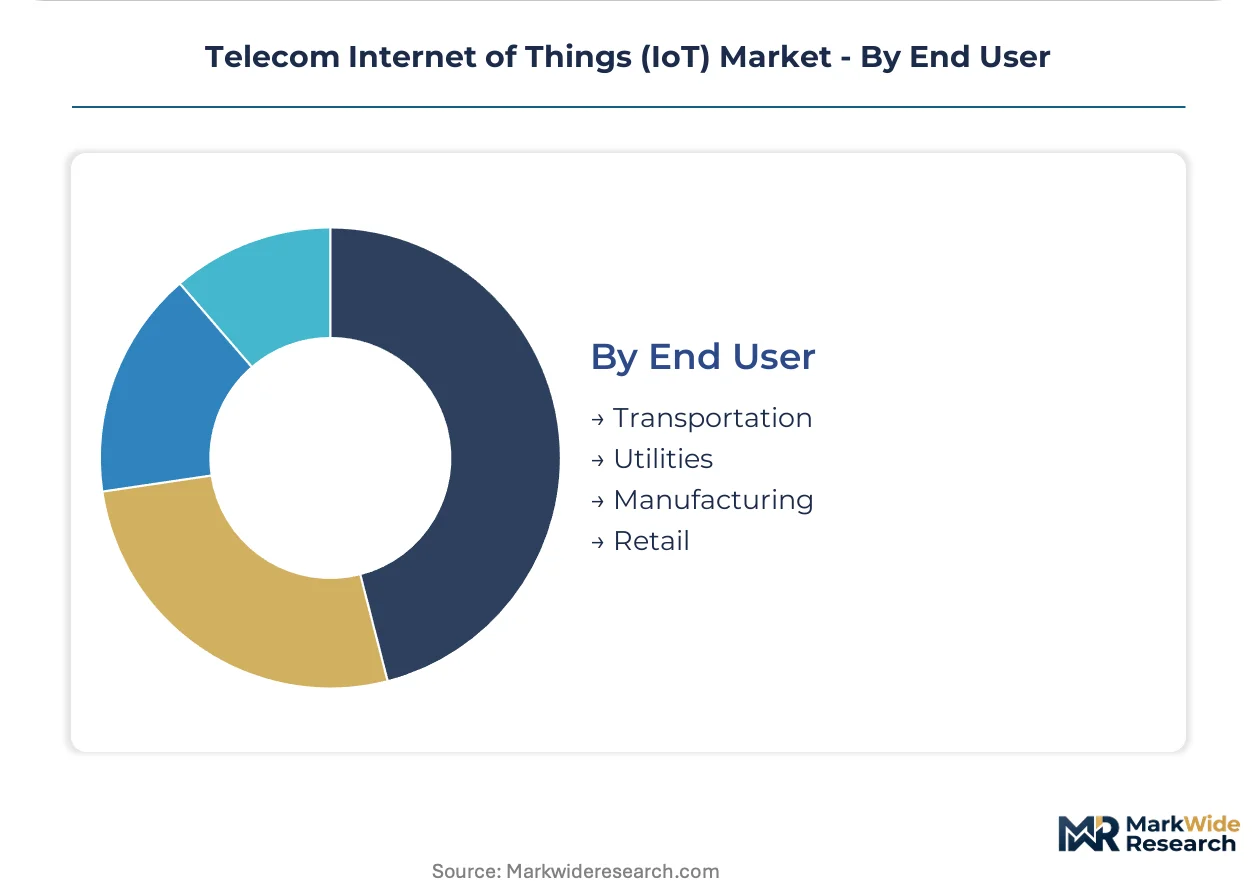
End User:
Customer procurement maturity separates specification-heavy industrial buyers from price-sensitive consumer-facing deployers.
- Transportation:Fleet operators negotiate direct carrier contracts for pooled LTE-M data across multi-country routes, unbundling connectivity from platform software.
- Utilities:State-backed infrastructure programs in China and regulated rate-base recovery in the United States create stable demand for NB-IoT metering with decade-long amortization horizons.
- Manufacturing:Discrete and process industries require protocol translation between cellular gateways and legacy Modbus or PROFIBUS networks, favoring vendors with systems integration partnerships.
- Retail:Cold-chain and inventory tracking applications prioritize rapid deployment over customization, accepting standardized SaaS dashboards from connectivity providers.
Utilities anchor recurring revenue. Manufacturing shows the steepest technology upgrade trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers concentrate procurement pull in state-backed infrastructure programs and automotive manufacturing corridors. Municipal utilities anchor volume demand through decade-long metering deployments. Electronics assembly lines and cold-chain logistics operators drive premium connectivity subscriptions.
China
MIIT national standards shape procurement specifications for smart city infrastructure across municipal utilities. State-backed directives mandate NB-IoT interoperability for gas and water metering systems. Shenzhen and Shanghai manufacturing clusters deploy integrated baseband-to-cloud stacks for domestic electronics assembly automation.
United States
FCC mid-band spectrum auctions raised carrier capital commitments while fleet operators negotiate direct LTE-M contracts. The national regulator enforces device authorization protocols that filter non-compliant module vendors. Detroit automotive corridors and Dallas-Fort Worth logistics hubs anchor enterprise subscription growth for predictive maintenance and asset tracking.
Germany
EU Cybersecurity Act certification frameworks mandate secure boot chains for CE marking approval. Industrial automation buyers in Baden-Württemberg and Bavaria require protocol translation between cellular gateways and legacy PROFIBUS networks. Munich and Stuttgart manufacturing clusters unbundle connectivity from platform software, compressing margins for integrated stack providers.
India
TRAI machine-to-machine communication guidelines mandate embedded SIM registration protocols that filter non-compliant vendors. Bangalore and Hyderabad technology corridors drive demand for certified eSIM orchestration platforms. National smart city missions in Delhi-NCR and Mumbai Metropolitan Region accelerate municipal procurement for environmental monitoring infrastructure.
South Korea
Advanced node fabrication for low-power wide-area chipsets concentrates in domestic foundries, exposing module vendors to geopolitical disruption risk. Seoul Capital Area electronics manufacturers drive specification-setting for multi-site deployment templates. Busan-Ulsan industrial zones deploy 5G network slicing for mission-critical robotic controllers with guaranteed latency bounds.
Telecom Internet of Things (IoT) Market Competitive Landscape
Player mix skews toward integrated national carriers with spectrum holdings and specialized module vendors with certification expertise. The vendor base separates into three tiers: full-stack infrastructure providers, connectivity-focused carriers, and component-specialized hardware suppliers. Strategic differentiation runs through eSIM orchestration capabilities, multi-national roaming agreements, and 3GPP Release 17 RedCap qualification timelines. Competitive moves center on hardware redesign cycles for certification compliance and direct enterprise contract negotiations that bypass traditional distribution channels.
Among integrated infrastructure providers, Huawei Technologies Co., Ltd. and Telefonaktiebolaget LM Ericsson occupy positions spanning baseband silicon through cloud orchestration layers. AT&T exemplifies the connectivity-carrier archetype with nationwide LTE-M footprint anchoring fleet and utility verticals. Deutsche Telekom AG represents the multi-national orchestration tier with cross-border eSIM management across European manufacturing corridors. These three anchors illustrate how qualification bottlenecks and spectrum access separate sustainable competitive positions from marginal vendor status.
| Leading Market Players |
|---|
| AT&T |
| Verizon |
| Vodafone Group |
| Deutsche Telekom AG |
| Huawei Technologies Co., Ltd. |
| Telefonaktiebolaget LM Ericsson |
| China Mobile Limited |
| BT Group |
| Aeris |
| Others |
Value Network & Pricing Analysis
Twelve-to-eighteen-month RedCap requalification cycles compress module vendor margins while concentrating pricing power among qualified baseband suppliers. This lead-time band shapes procurement negotiations as buyers with decade-long utility amortization horizons absorb premium pricing for certified hardware, whereas fleet operators with shorter replacement cycles demand cost-plus contracts indexed to silicon wafer costs.
Pricing Analysis
Cost-plus contracts with silicon wafer indexation dominate enterprise procurement for LTE-M modules, insulating vendors from raw material volatility while capping upside. Price differentiation rests on 3GPP Release 17 certification tier and volume scale, with RedCap-qualified suppliers commanding premiums over legacy LTE-M vendors. Cost compression in unlicensed alternatives intensifies as LoRaWAN gateways undercut cellular subscriptions for private campus deployments. Municipal utilities exhibit lowest price sensitivity due to state-backed rate-base recovery, whereas retail cold-chain operators prioritize rapid deployment over hardware customization and negotiate aggressively on per-unit module costs.
Supply Chain Analysis
Taiwan Strait transit routes underwrite advanced node fabrication for low-power wide-area chipsets, exposing module vendors to geopolitical disruption risk. Supply concentrates in Taiwan, South Korea, and mainland China foundries, with EUV lithography equipment dependencies feeding from Dutch ASML installations. Raw material inputs draw from neon gas extraction in Ukraine, high-purity silicon from Germany, and rare earth processing in China. Single-source vulnerability concentrates at 7nm and 5nm fabrication nodes. Distribution runs through carrier-direct contracts for enterprise fleets and module vendor OEM partnerships for smart city integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
3GPP Release 17 RedCap certification compresses the qualified vendor pool and accelerates market consolidation around certified baseband suppliers. This regulatory inflection creates asymmetric returns for first-movers who secure hardware qualification before competitor redesign cycles complete.
For Market Incumbents: Compound spectrum holdings into multi-national roaming agreements that lock in fleet operator contracts across European and North American transportation corridors. Invest in embedded security engineering talent to accelerate EU Cybersecurity Act certification timelines before 12-18 month qualification bottlenecks widen. Defend against unlicensed LoRaWAN alternatives by bundling guaranteed latency SLAs with predictive maintenance software subscriptions. For New Entrants and Emerging Players: eSIM orchestration platform gaps in India's TRAI-compliant vendor pool offer first-mover positioning for carriers with pre-certified embedded SIM registration protocols. Target cold-chain asset tracking applications where pharmaceutical logistics operators mandate real-time location verification and accept premium cellular-satellite hybrid subscriptions. Pursue direct municipal utility contracts in China's MIIT-directed smart city deployments rather than competing for saturated automotive telematics volumes. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated carriers spinning off non-core device management software units to focus on core spectrum monetization. Long-term viability favors vendors with backward integration into secure boot chain firmware and hardware security module partnerships. Monitor 3GPP Release 18 timeline announcements as the inflection signal determining which module vendors escape the current RedCap qualification bottleneck.| Strategic Initiative | Industry Significance |
|---|---|
| RedCap Hardware Requalification | 3GPP Release 17 certification timelines separate sustainable vendors from margin-compressed laggards. |
| Multi-National eSIM Orchestration | Deutsche Telekom's cross-border European manufacturing corridor contracts demonstrate platform value capture. |
| EU Cybersecurity Act Certification | Secure boot chain mandates filter non-compliant module vendors and improve qualified supplier contract values. |
| Carrier-Direct Enterprise Contracts | AT&T's nationwide LTE-M footprint anchors fleet and utility verticals bypassing traditional distribution. |
| Cellular-Satellite Hybrid Connectivity | Cold-chain pharmaceutical logistics operators mandate real-time location verification opening premium tiers. |
Research Methodology
Operator-level perspectives from carrier network planning officers, module vendor hardware engineering leads, smart city procurement managers, and industrial automation systems integrators anchored the qualitative base. Primary interviews combined with secondary validation from 3GPP release documentation, FCC spectrum auction records, MIIT national standard filings, and EU Cybersecurity Act certification databases. Bottom-up subscription forecasts triangulated against top-down infrastructure capex projections across connectivity tiers and application segments.
Sensitivity analysis tested forecast robustness across varying 5G network slicing adoption rates and RedCap certification diffusion timelines. The analytical framework modeled segmentation dimensions including connectivity protocol, device type, application vertical, end-user procurement maturity, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to carrier-reported subscription additions and infrastructure deployment pipelines. Industry-specific inputs incorporated baseband supplier qualification timelines and municipal utility amortization horizons.
Forecasts assume regulatory continuity in FCC device authorization protocols, EU Cybersecurity Act certification frameworks, and China's MIIT national standards; material policy shifts would require re-modeling subscription growth trajectories and vendor qualification pipelines. Practitioners should keep alternative scenarios live as 3GPP Release 18 standardization timelines and geopolitical disruption risks to Taiwan foundry capacity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT in Warehouse Management Market
Internet of Things (IoT)
Smart Connected Device Market
Internet of Things (IoT)
Global Agile IoT Market
Internet of Things (IoT)
Automotive Internet of Things (IoT) Market
Internet of Things (IoT)
North America IoT Software Market
Internet of Things (IoT)
Internet of Things (IoT) in Manufacturing Market
Internet of Things (IoT)
Wireless Smart Plug Market
Internet of Things (IoT)
Global IoT Node and Gateway Market
Internet of Things (IoT)
Smart Remote Market
Internet of Things (IoT)
IoT Device Management Platform Market
Internet of Things (IoT)
Global Machine-To-Machine (M2M) Connections Market
Internet of Things (IoT)
IoT Utilities Market
Internet of Things (IoT)
IoT Network Management Market
Internet of Things (IoT)
AI in IoT Market
Internet of Things (IoT)
Internet of Medical Things (Iomt) Market
Internet of Things (IoT)
Consumer IoT Market