
 Asia-Pacific Warehouse Management Systems Market | 2026-2036
Asia-Pacific Warehouse Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Warehouse Management Systems Market Insights
India's PLI scheme for electronics manufacturing is realigning the cost-of-entry calculus for warehouse automation vendors seeking Indian industrial contracts. SAP SE leverages its localized cloud infrastructure to sustain dominance among India's expanding electronics contract manufacturers. Manhattan Associates Inc competes through specialized yard management modules that anchor its position in Japan's precision-driven automotive parts distribution networks.
Asia-Pacific Warehouse Management Systems encompass software platforms that orchestrate inventory tracking, labor allocation, and facility workflow optimization through real-time data capture via barcode scanning, RFID, and IoT sensor integration. These systems serve commercial and industrial operators by reducing fulfillment latency and inventory carrying costs across multi-node distribution networks. Cloud-based deployments now lead product type adoption as operators prioritize scalable subscription models over capital-intensive on-premises installations. AI-enabled technology segments represent the fastest-growing capability layer, with demand concentrating in automated demand forecasting and dynamic slotting optimization where margin pools deepen for specialized vendors.
China's MIIT enforces GB standards for industrial software interoperability, while Japan's METI promotes smart logistics through JIS-aligned facility certification programs. India's BIS mandates data localization protocols that shape foreign vendor market access and domestic partnership requirements. Stakeholders must monitor how fragmented national standards across the region influence platform architecture decisions and localization investment thresholds.
Market Dynamics
Cloud-native warehouse management architectures are compressing deployment cycles across Asia-Pacific fulfillment networks, forcing incumbent vendors to restructure pricing models and localization strategies around subscription elasticity rather than perpetual license structures.
Growth Catalysts
- India's PLI scheme for electronics manufacturing:Contract manufacturers in Tamil Nadu and Karnataka are mandating WMS upgrades to meet traceability requirements for smartphone and component exports, creating immediate procurement pipelines for tier-1 software vendors.
- Cross-border e-commerce fulfillment clusters:Smart warehouse concentrations in China's eastern coastal provinces—particularly Zhejiang and Jiangsu—are driving synchronized demand for multi-tenant WMS platforms capable of handling fragmented SKU portfolios across disparate regulatory jurisdictions.
- RFID-IoT sensor convergence:Real-time inventory positioning systems are displacing manual cycle-counting protocols in Japan's pharmaceutical cold chain, reducing labor allocation costs while tightening compliance documentation for METI-tracked distribution networks.
Market Restraints
- Data localization mandates:India's BIS protocols require domestic server infrastructure for warehouse operational data, elevating foreign vendor compliance costs and forcing partnership structures with local cloud providers that fragment platform standardization.
- Semiconductor input volatility:Edge computing hardware essential for warehouse IoT deployments faces supply concentration risk from Taiwan and South Korean foundries, compressing hardware refresh cycles and delaying automation timelines for mid-tier 3PL operators.
- Interoperability friction:China's MIIT-enforced GB standards for industrial software create technical barriers against foreign WMS architectures, necessitating costly middleware development that erodes margin structures for non-domestic platform providers.
Strategic Opportunities
- Vietnam's manufacturing corridor expansion:Northern industrial zones around Hai Phong and Bac Ninh remain underpenetrated by integrated WMS providers, offering first-mover positioning as electronics and textile contract manufacturers relocate from China.
- AI-enabled demand forecasting modules:Machine learning convergence with legacy WMS cores is creating white-space revenue streams for specialized vendors targeting Japan's automotive parts distributors seeking dynamic slotting optimization.
- Australia's cold chain certification programs:TGA-aligned temperature monitoring mandates for pharmaceutical logistics are driving replacement demand for WMS platforms with embedded compliance documentation and automated deviation reporting.
Industry Challenges
- Integration complexity with legacy ERP:Southeast Asian 3PL operators running SAP ECC 6.0 or older Oracle installations face protracted API mapping exercises that delay cloud WMS go-live dates and inflate professional services budgets.
- Multi-language localization requirements:Platform vendors must maintain simultaneous Simplified Chinese, Japanese, Korean, Hindi, and Thai interface support, fragmenting development resources and complicating version control across distributed engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Warehouse Management Systems Market |
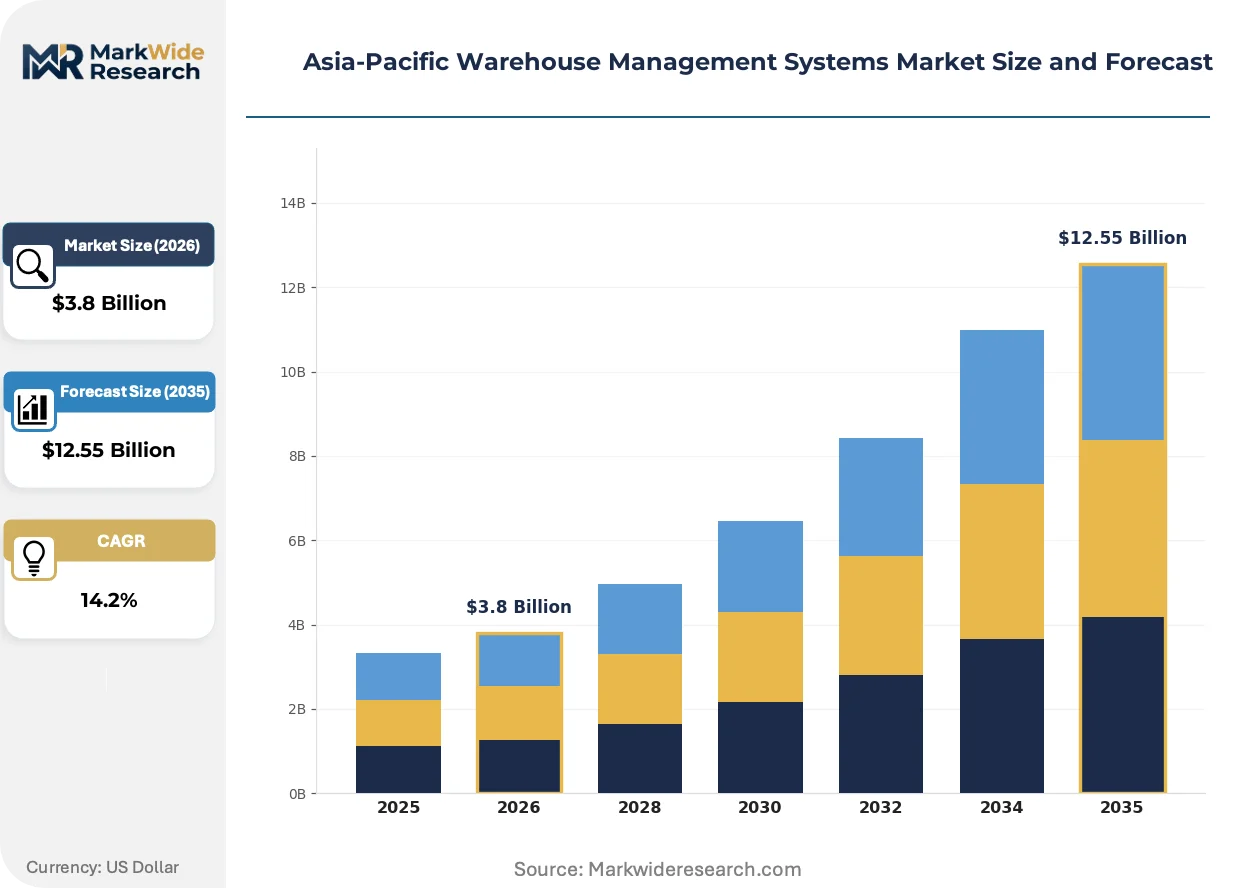
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, Mobile End User: Retail, E-Commerce, Manufacturing, Logistics Deployment Model: Private Cloud, Public Cloud, Multi-Tenant, Single-Tenant Technology: RFID, Barcode Scanning, IoT, AI |
| Companies Covered | Oracle Corporation, SAP SE, Manhattan Associates Inc, Infor Inc, Blue Yonder Group, Inc., International Business Machines Corp, Epicor Software Corp, Softeon Inc, Panasonic Holdings Corp, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Warehouse Management Systems Market Trends and Innovations
Artificial intelligence layers are migrating from peripheral analytics tools into core warehouse execution systems, compressing decision latency from batch-processed reports to real-time autonomous adjustments. This architectural shift is redrawing competitive boundaries between pure-play WMS vendors and broader supply chain platform providers.
Digital twin technology is unifying physical warehouse layouts with simulation environments that model labor deployment, equipment routing, and inventory positioning before operational changes commit to live systems. Japanese automotive parts distributors are adopting these platforms at accelerated rates to minimize disruption in precision-timed just-in-sequence delivery networks. This unifying capability is compressing the traditional pilot-to-production timeline from quarters to weeks, forcing implementation partners to restructure project methodologies around continuous deployment rather than waterfall milestones.
China's MIIT enforcement of GB/T 38557-2020 interoperability standards for industrial software is mandating standardized data exchange protocols across warehouse automation equipment. Domestic WMS providers are capturing incremental market access by pre-certifying platform modules against these specifications, while foreign vendors face extended validation timelines that delay competitive positioning in state-owned enterprise procurement cycles. Electronics manufacturing facilities in Shenzhen and Dongguan are responding fastest, driven by state-mandated smart factory certification deadlines.
Subscription-based procurement models are displacing perpetual license structures across mid-market 3PL operators in Southeast Asia, compressing upfront capital requirements while elongating vendor revenue recognition timelines. Australian and Singaporean logistics providers are leading this transition, prioritizing operational expenditure flexibility over balance-sheet asset ownership. The shift is most visible in cross-border e-commerce fulfillment, where seasonal volume volatility makes fixed-cost infrastructure commitments economically untenable for emerging market entrants.
Asia-Pacific Warehouse Management Systems Market Segmentation
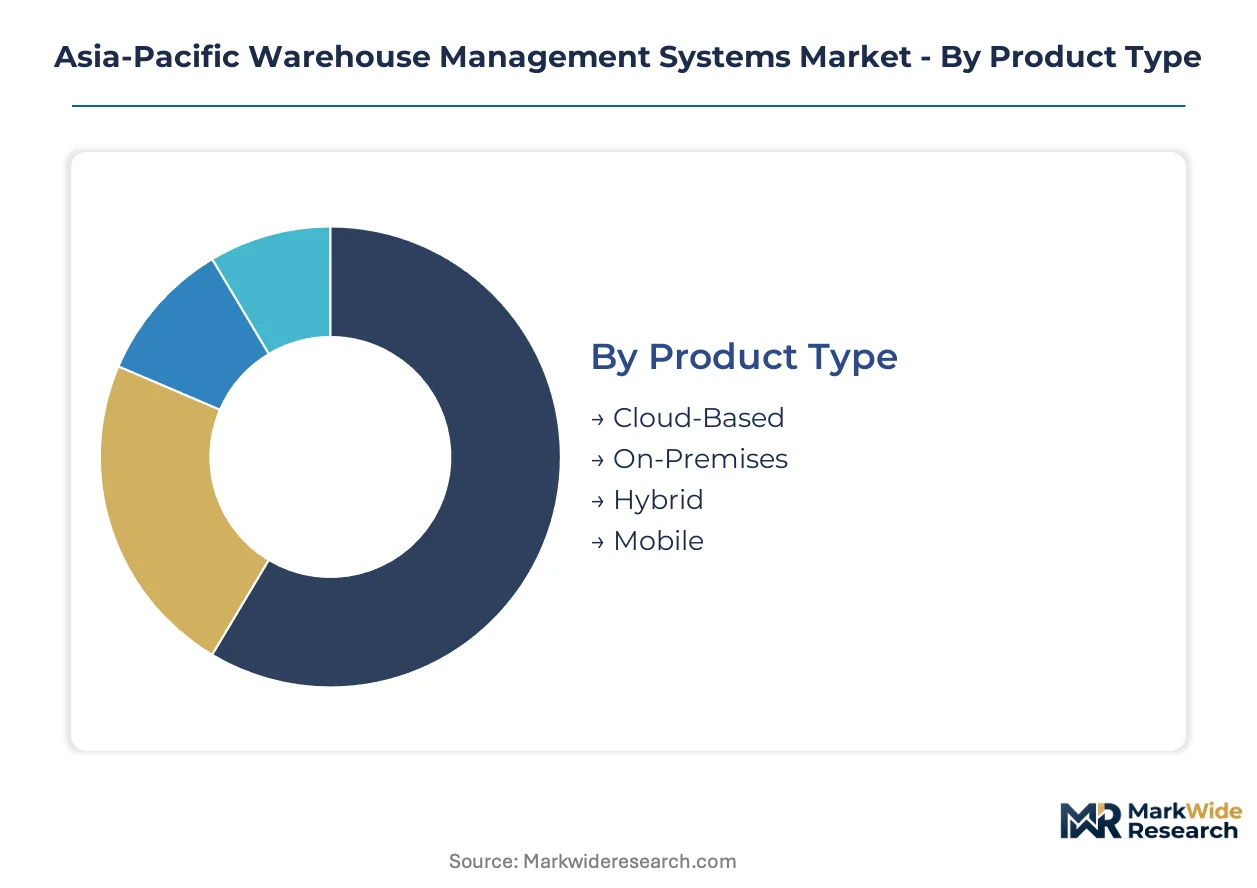
Warehouse management systems fragment across multiple technical and commercial dimensions that determine integration complexity, capital intensity, and vendor selection criteria. Understanding how these segments interlock reveals why cloud-native architectures now dominate procurement conversations while legacy on-premises installations persist in regulated environments.
Product Type:
Standalone WMS deployments differ fundamentally from modules embedded within broader ERP suites, with integration depth dictating implementation timelines and total cost of ownership.
- Cloud-Based:Subscription architectures eliminate server infrastructure requirements and compress deployment cycles from months to weeks. India's electronics contract manufacturers under PLI scheme mandates favor this model for rapid traceability compliance without capital expenditure approval delays.
- On-Premises:Perpetual license structures with captive server infrastructure persist where data sovereignty regulations or legacy ERP entanglements block cloud migration. Japan's pharmaceutical cold chain operators maintain these installations to satisfy METI audit trail requirements without third-party data exposure.
- Hybrid:Split architectures keep sensitive transactional data on local servers while pushing analytics workloads to cloud environments. Australian logistics providers deploy this pattern to balance TGA pharmaceutical compliance with AI-enabled demand forecasting flexibility.
- Mobile:Handheld and wearable form factors extend WMS functionality to yard management and remote inventory positioning. Southeast Asian 3PL operators adopt these for container tracking at port-adjacent fulfillment clusters.
Volume placements concentrate in Cloud-Based; the faster expansion belongs to Mobile.
End User:
Customer sophistication and margin pressure create divergent requirements across vertical applications, with traceability mandates and velocity targets driving specification divergence.
- Retail:Omnichannel fulfillment networks require real-time inventory visibility across store, warehouse, and drop-ship nodes. China's eastern coastal smart warehouse clusters serve this segment through multi-tenant platforms handling fragmented SKU portfolios.
- E-Commerce:Seasonal volatility and same-day delivery promises demand elastic capacity scaling without fixed infrastructure commitments. Cross-border operators in Zhejiang and Jiangsu provinces drive synchronized procurement for platforms supporting disparate regulatory jurisdictions.
- Manufacturing:Just-in-sequence and just-in-time workflows mandate precise material availability timing with minimal safety stock. India's Tamil Nadu and Karnataka electronics facilities under PLI scheme mandates upgrade these systems for component traceability.
- Logistics:Multi-client operations require tenant isolation and flexible billing structures across shared warehouse infrastructure. Third-party providers across Vietnam's northern industrial zones seek first-mover positioning as manufacturing relocates from China.
Revenue concentration sits with Retail; steepest expansion trajectory belongs to E-Commerce.
Deployment Model:
Infrastructure control and isolation requirements segment procurement patterns, with regulatory pressure and competitive differentiation shaping cloud architecture choices.
- Private Cloud:Dedicated virtualized environments within operator-controlled data centers balance scalability with data residency compliance. India's BIS data localization protocols elevate this model for foreign vendors seeking market access without domestic partnership structures.
- Public Cloud:Shared infrastructure with hyperscaler-managed security and availability targets minimizes operational overhead. Singaporean and Australian logistics providers lead regional adoption for operational expenditure flexibility.
- Multi-Tenant:Single software instances serving multiple clients with data isolation at the application layer reduce per-customer infrastructure costs. Southeast Asian 3PL operators favor this for mid-market customer segments.
- Single-Tenant:Dedicated software instances per customer eliminate neighbor risk and support deep customization. Japan's automotive parts distributors specify these for precision-timed delivery network reliability.
Adoption gravity centers on Public Cloud; the premium positioning belongs to Single-Tenant.
Technology:
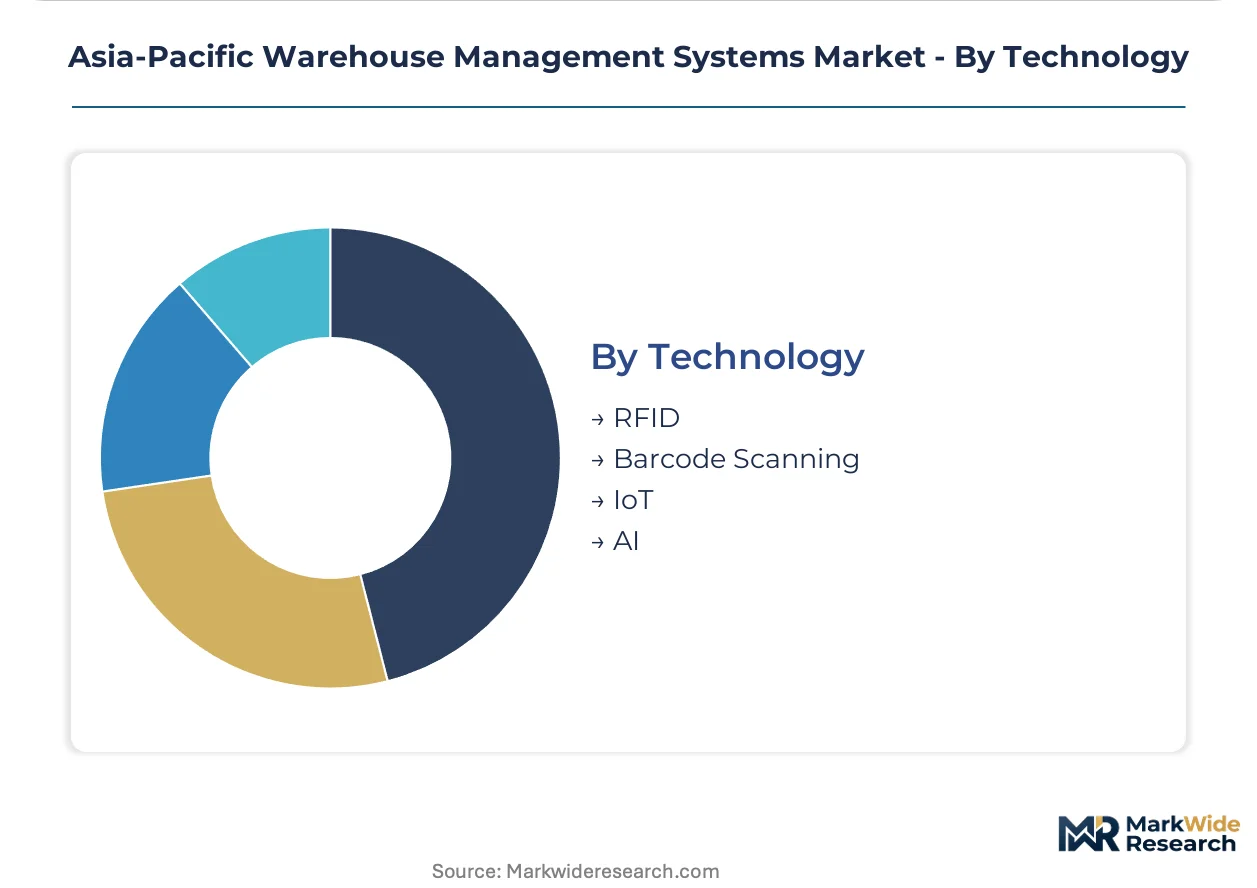
Data capture and decision automation layers determine operational accuracy and labor displacement potential, with convergence between identification technologies and predictive analytics reshaping competitive requirements.
- RFID:Radio-frequency identification enables non-line-of-sight inventory tracking and automated cycle counting without manual barcode scanning. Japan's pharmaceutical cold chain deploys these systems to reduce labor allocation costs while tightening METI compliance documentation.
- Barcode Scanning:Optical data capture remains the cost baseline for inventory verification and picking confirmation. Legacy facilities across Southeast Asia retain this technology where RFID infrastructure investment cannot be justified.
- IoT:Sensor networks extend visibility to environmental conditions, equipment health, and asset location in real time. Australia's TGA-aligned temperature monitoring mandates for pharmaceutical logistics drive embedded sensor integration.
- AI:Machine learning modules enable dynamic slotting optimization and automated demand forecasting that compresses decision latency. Japan's automotive parts distributors seek this capability for margin pool deepening in precision distribution networks.
Installed base dominance remains with Barcode Scanning; the capability gaining share fastest belongs to AI.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern coastal special economic zones concentrate smart warehouse infrastructure serving cross-border e-commerce fulfillment networks. India's PLI scheme for electronics manufacturing is redirecting capital toward Tamil Nadu and Karnataka facility automation. Japan's METI-certified logistics corridors anchor precision distribution technology adoption.
China
Zhejiang and Jiangsu province smart warehouse clusters drive multi-tenant WMS procurement for fragmented SKU portfolios across disparate regulatory jurisdictions. MIIT enforces GB/T 38557-2020 interoperability standards that mandate standardized data exchange protocols across warehouse automation equipment. Shenzhen and Dongguan electronics manufacturing facilities respond fastest to state-mandated smart factory certification deadlines.
India
Tamil Nadu and Karnataka contract manufacturers mandate WMS upgrades to meet traceability requirements for smartphone and component exports under PLI scheme incentives. BIS data localization protocols require domestic server infrastructure for warehouse operational data, elevating foreign vendor compliance costs. Electronics manufacturing facilities in Bengaluru and Chennai create immediate procurement pipelines for tier-1 software vendors.
Japan
Automotive parts distributors seek AI-enabled demand forecasting modules for dynamic slotting optimization in precision-timed just-in-sequence delivery networks. METI promotes smart logistics through JIS-aligned facility certification programs that shape vendor qualification requirements. Pharmaceutical cold chain operators in the Kanto region deploy RFID-IoT sensor convergence to reduce labor allocation costs while tightening compliance documentation.
Australia
TGA-aligned temperature monitoring mandates for pharmaceutical logistics drive replacement demand for WMS platforms with embedded compliance documentation. Cold chain certification programs require automated deviation reporting capabilities that reshape software specification priorities. Sydney and Melbourne logistics providers lead subscription-based procurement transitions prioritizing operational expenditure flexibility.
Vietnam
Northern industrial zones around Hai Phong and Bac Ninh remain underpenetrated by integrated WMS providers as electronics and textile contract manufacturers relocate from China. Third-party logistics operators seek first-mover positioning in multi-client warehouse infrastructure serving relocated manufacturing capacity. Port-adjacent fulfillment clusters drive mobile WMS adoption for container tracking applications.
Asia-Pacific Warehouse Management Systems Market Competitive Landscape
United States-based enterprise software vendors anchor one tier; German and Japanese specialists hold differentiated positions in precision logistics segments. The vendor base organizes around three strategic archetypes: cloud-native platform providers with hyperscaler partnerships, legacy ERP-integrated suite vendors, and vertical specialists targeting pharmaceutical cold chain or automotive sequencing requirements. Dominant competitive moves include M&A activity consolidating mid-market SaaS capabilities and strategic partnerships with domestic cloud providers to satisfy data localization mandates.
Within the enterprise suite tier, Oracle Corporation and SAP SE exemplify archetypes for contrasting localization strategies. Oracle leverages cloud infrastructure investments to address India's BIS data residency requirements through domestic partnership structures. SAP SE sustains dominance among India's expanding electronics contract manufacturers through localized cloud infrastructure. Manhattan Associates Inc occupies a specialist position exemplifying yard management module differentiation that anchors presence in precision-driven distribution networks. These three entities represent how geographic adaptation, vertical specialization, and compliance architecture determine competitive positioning across fragmented national standards.
| Leading Market Players |
|---|
| Oracle Corporation |
| SAP SE |
| Manhattan Associates Inc |
| Infor Inc |
| Blue Yonder Group, Inc. |
| International Business Machines Corp |
| Epicor Software Corp |
| Softeon Inc |
| Panasonic Holdings Corp |
| Others |
Pricing and Supply Chain Analysis
Edge computing hardware costs cascade through subscription pricing tiers as Taiwan and South Korean foundry output constraints compress hardware refresh cycles for mid-tier 3PL operators seeking IoT-enabled warehouse automation.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid deployment commitments with subscription discounts while spot procurement of on-premises licenses commands premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled forecasting modules from basic inventory tracking and legacy barcode systems. Cost compression in the economy tier intensifies as domestic Chinese vendors leverage GB/T 38557-2020 pre-certification to undercut foreign platform pricing. Small and mid-market 3PL operators in Southeast Asia exhibit highest price sensitivity, while Japan's automotive parts distributors prioritize precision reliability over cost minimization.
Supply Chain Analysis
RFID-IoT sensor hardware supply rests on Taiwanese semiconductor foundries, South Korean memory component producers, and Chinese sensor packaging facilities. Critical inputs span edge computing processors, industrial-grade memory modules, and temperature-resistant sensor housings. Single-source vulnerability concentrates in advanced node semiconductor fabrication, where geopolitical friction threatens equipment refresh timelines. Distribution runs through hyperscaler cloud infrastructure partnerships for software delivery, with hardware components flowing via regional electronics distributors into warehouse automation integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud infrastructure capacity constraints among India's domestic data center operators prop subscription pricing power for foreign vendors navigating BIS localization mandates.
For Market Incumbents: Deepen partnership structures with local cloud providers in India to satisfy BIS data residency requirements without fragmenting platform architecture. Fortify position in Japan's METI-certified logistics corridors through JIS-aligned module certification investments. SAP SE and Oracle Corporation must accelerate domestic infrastructure deployment before emerging cloud-native competitors capture PLI-driven procurement windows in Tamil Nadu electronics facilities. For New Entrants and Emerging Players: India's PLI scheme for electronics manufacturing opens a window for specialized traceability module vendors to penetrate contract manufacturer upgrade cycles in Karnataka and Tamil Nadu. Vietnam's northern industrial zones around Hai Phong and Bac Ninh present first-mover positioning as manufacturing relocates from China. Target mid-market 3PL operators through mobile-first deployment models that compress implementation timelines against incumbent complexity. For Investors and Strategic Acquirers: Accelerated procurement timelines among India's electronics contract manufacturers signal the leading indicator that AI-enabled forecasting capabilities will command acquisition premiums. Long-term viability centers on vendors with pre-certified interoperability against fragmented national standards across the region. Target acquisition archetypes include vertical specialists with embedded pharmaceutical cold chain compliance modules and domestic Chinese vendors with MIIT GB standard pre-approval. Monitor METI smart logistics certification program expansion rates as the inflection signal for Japan market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
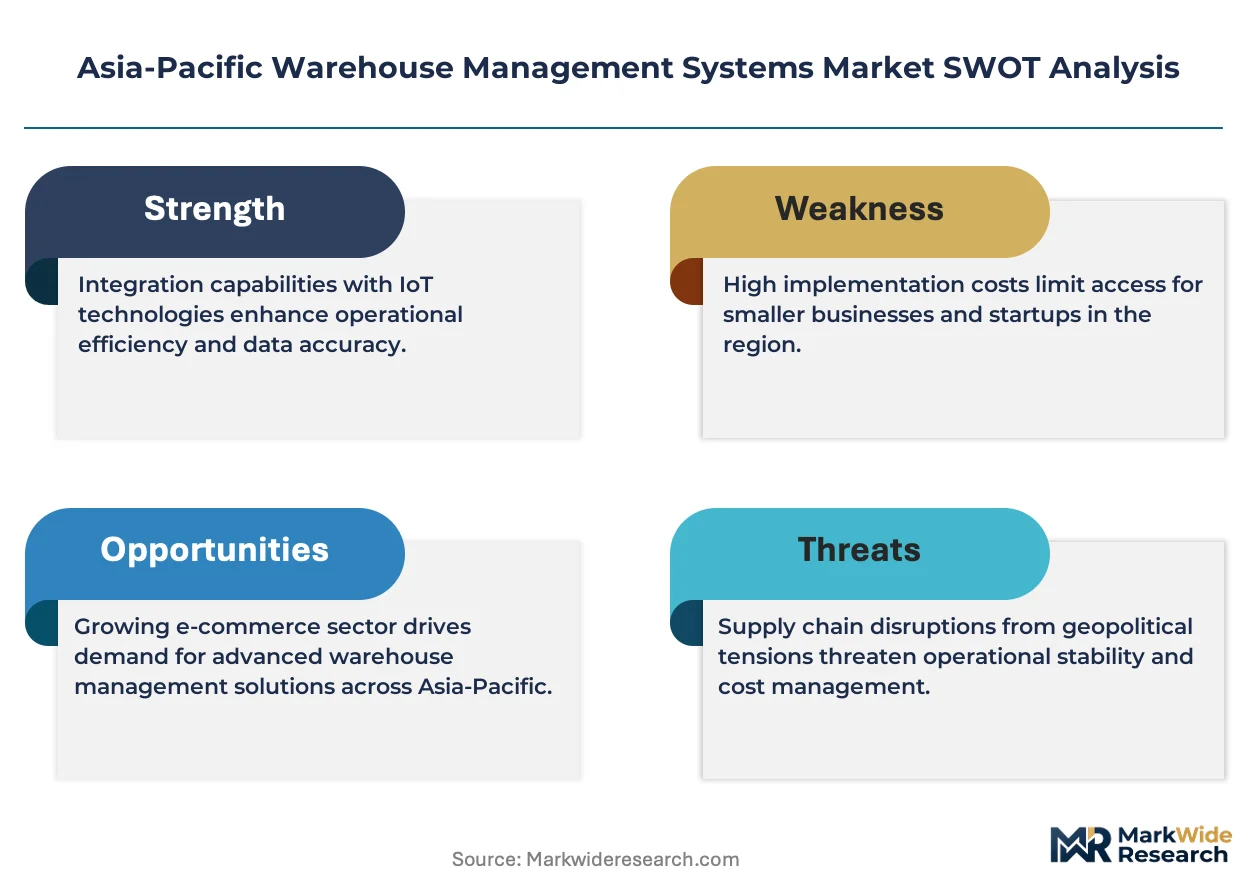
| Domestic Cloud Partnership Formation | India's BIS mandates force foreign vendors into local infrastructure alliances to maintain market access. |
| AI Module Integration | Japanese automotive distributors seek machine learning convergence with legacy WMS cores for dynamic slotting. |
| GB Standard Pre-Certification | China's MIIT enforcement creates competitive moat for domestic vendors in state-owned enterprise procurement. |
| Mobile-First Platform Launch | Southeast Asian 3PL operators adopt handheld and wearable form factors for port-adjacent container tracking. |
| Vertical Specialist Acquisition | Pharmaceutical cold chain compliance capabilities deepen margin pools in TGA-aligned Australian logistics. |
Research Methodology
Regulatory filings from MIIT, METI, and BIS, alongside customs data on warehouse automation equipment imports and hyperscaler capex disclosures, formed the secondary backbone for market sizing validation. Primary interviews with logistics CTOs, 3PL procurement officers, warehouse operations directors, and systems integration specialists supplemented secondary intelligence. Bottom-up and top-down triangulation reconciled vendor revenue disclosures with end-user deployment counts across cloud-native and on-premises architectures.
Bottom-up modeling traced individual deployment values through segmentation dimensions spanning deployment model, organization size, vertical application, and regional adoption pattern. Top-down validation anchored aggregate market estimates against macroeconomic indicators and logistics sector capital expenditure trends. CAGRs were derived through regression analysis of historical procurement patterns and projected PLI scheme incentive disbursement timelines. Forecast inputs incorporated electronics manufacturing relocation trajectories and cross-border e-commerce fulfillment cluster expansion rates.
Caveats apply where semiconductor supply disruptions, abrupt data localization enforcement shifts, or GB standard revision timelines could materially shift the outlook. Forecasts reflect assumptions regarding sustained PLI scheme funding continuity and stable geopolitical conditions affecting Taiwan Strait logistics. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Asia-Pacific Contingent Workforce Management Market
Enterprise Services
Global Enterprise Data Warehouse (EDW) Market
Enterprise Services
Digital Talent Acquisition Market
Enterprise Services
Enterprise A2P SMS Market
Enterprise Services
Proactive Services Market
Enterprise Services
Enterprise Data Loss Prevention (DLP) Services Market
Enterprise Services
Qatar Cloud Managed Services Market
Enterprise Services
Mobile Enterprise Application Market
Enterprise Services
Global Enterprise High-Productivity Application Platform As a Service Market
Enterprise Services
Asia Pacific Field Service Management Market
Enterprise Services
HR Tech Consulting Market
Enterprise Services
Global AWS Managed Services Market
Enterprise Services
Enterprise Web Development Outsourcing Services Market
Enterprise Services
United States Managed Services Market
Enterprise Services
Europe IT Services Market
Enterprise Services
Cloud Enterprise Management Market