
 Enterprise Data Management Market | 2026-2036
Enterprise Data Management Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Data Management Market Intelligence
Healthcare provider reliance on unified patient records is hardening as clinical data volumes surge. Microsoft leverages its Azure Purview architecture to anchor healthcare data governance deployments across North American hospital networks. Oracle competes through specialized master data management suites tuned for provider interoperability standards. SAP sustains its position in European healthcare systems through deep ERP integration with clinical workflow modules.
Enterprise Data Management encompasses the architectural frameworks, software platforms, and operational protocols that govern data ingestion, storage, quality assurance, and lineage tracking across distributed organizational environments, typically deployed through metadata-driven catalogs that automate schema discovery and policy enforcement. Its primary commercial purpose is to eliminate data silos, ensure regulatory compliance, and enable real-time analytics for operational decision-making. Data governance solutions dominate current spending as organizations confront fragmented regulatory requirements, while multi-cloud deployment models represent the fastest-expanding configuration as enterprises distribute workloads across AWS, Azure, and Google Cloud to avoid vendor lock-in and meet data residency obligations.
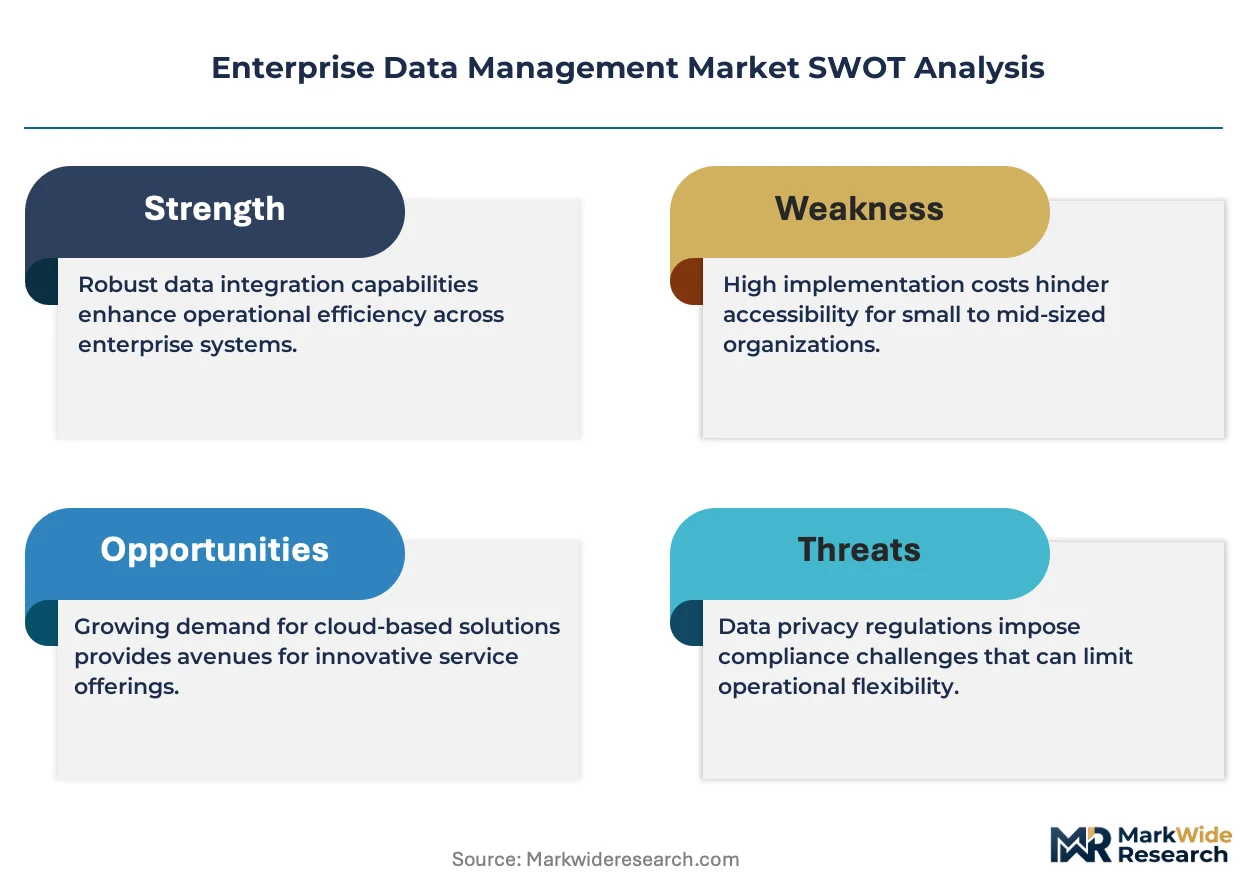
The US SEC mandates structured data disclosures through its Inline XBRL requirements, while the EU AI Act imposes strict documentation standards for training data provenance, compelling enterprises to invest in auditable metadata management infrastructure. India's Digital Personal Data Protection Act establishes consent-layer obligations that reshape how multinational firms architect cross-border data flows. Organizations must monitor the divergence between US risk-based disclosure frameworks and EU precautionary data governance standards when selecting platform vendors and deployment geographies.
Market Dynamics
Cloud migration mandates from the EU AI Act and SEC disclosure rules are accelerating replacement cycles across financial services and healthcare, forcing enterprises to retire legacy data architectures before end-of-life.
Growth Catalysts
- EU AI Act documentation standards:The regulation's strict training data provenance requirements compel enterprises to invest in auditable metadata management infrastructure for compliance.
- Healthcare unified patient records:Clinical data volume surges are hardening provider reliance on integrated data platforms for operational decision-making.
- India's sovereign data infrastructure:The Digital Personal Data Protection Act establishes consent-layer obligations that reshape cross-border data flow architectures for multinational firms.
Market Restraints
- Multi-cloud integration complexity:Distributing workloads across AWS, Azure, and Google Cloud creates schema harmonization bottlenecks that inflate implementation timelines.
- Specialized talent scarcity:Shortages of data governance architects and metadata engineers constrain deployment velocity for enterprise-scale projects.
- Legacy system entrenchment:Decades of on-premise data warehouse investments create technical debt that resists cloud-native migration without costly middleware layers.
Strategic Opportunities
- Real-time analytics enablement:Streaming data pipelines combined with automated lineage tracking open new operational intelligence applications in manufacturing and logistics.
- India's data localization requirements:The country's Digital Personal Data Protection Act creates captive demand for domestic-hosted data governance platforms serving multinational subsidiaries.
- Regulatory divergence arbitrage:Vendors can architect dual-compliance solutions bridging US risk-based disclosure frameworks and EU precautionary governance standards.
Industry Challenges
- Cross-border data flow fragmentation:Divergent national data residency laws complicate unified platform architectures for multinational enterprises.
- Metadata standardization delays:Absence of industry-wide schema discovery protocols forces redundant custom integration work across deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Data Management Market |
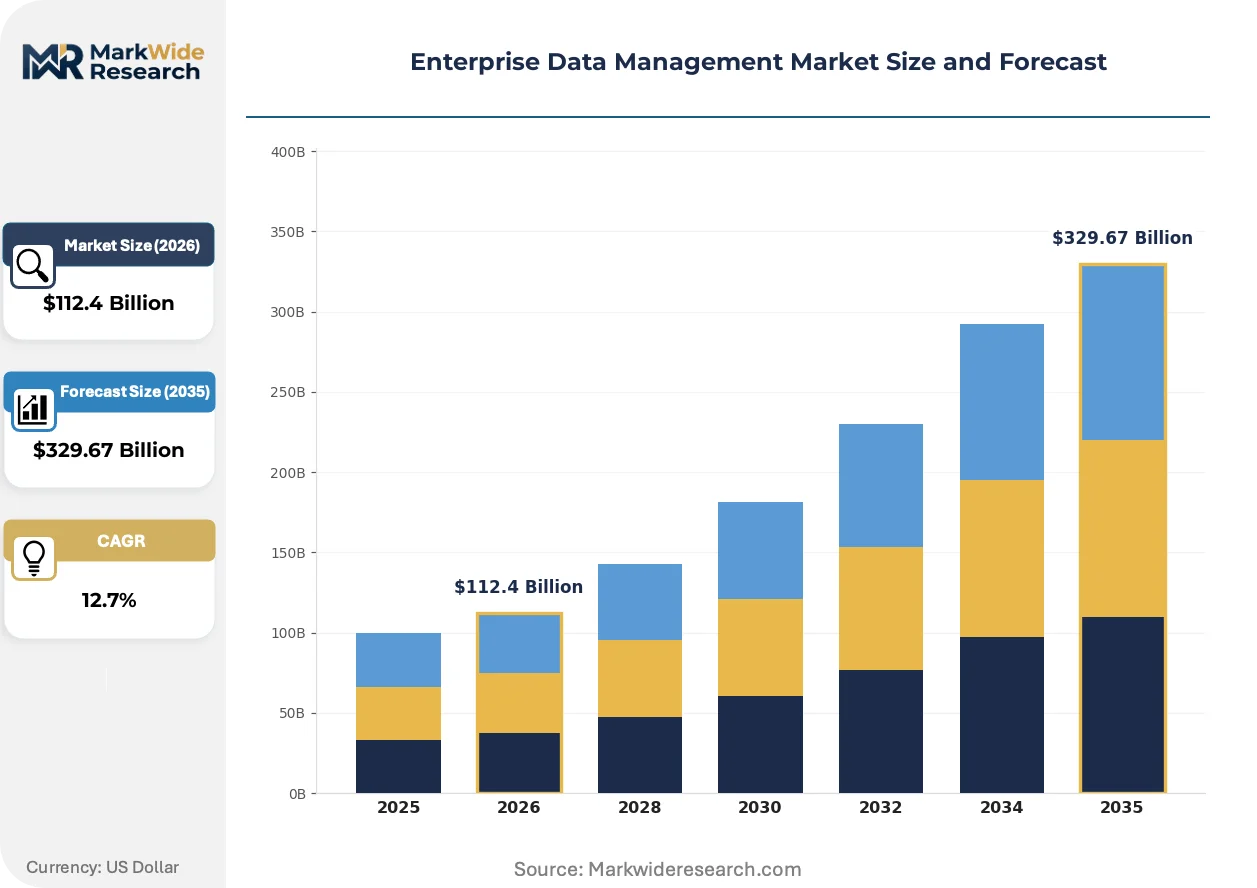
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $329.67 Billion |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Data Governance, Master Data Management, Data Integration, Data Quality, Metadata Management, Reference Data Management Deployment Model: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Industry Vertical: BFSI, Telecommunications, Manufacturing, Healthcare Providers, Energy & Utilities, Government Agencies End User Type: Data Analysts, IT Managers, Business Executives, Compliance Officers, Data Scientists |
| Companies Covered | Microsoft, IBM, Oracle, SAP, Amazon Web Services, Informatica, Teradata Corporation, Cloudera, Talend, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Data Management Market Strategic Shifts & Innovations
Automated schema discovery and policy enforcement through metadata-driven catalogs is actively displacing manual data stewardship models, compressing time-to-insight while expanding governance coverage.
Active metadata management is rewriting how enterprises maintain data quality at scale. The technology continuously ingests operational signals to auto-update lineage graphs and policy rules without human intervention. Financial services firms in the United States are deploying these capabilities fastest, driven by SEC Inline XBRL mandates. This compression of governance overhead is enabling real-time regulatory reporting that was previously batch-processed monthly.
The EU AI Act's training data documentation requirements are forcing structural investment in provenance-tracking infrastructure. Industrial consequence spans model development pipelines, where auditable metadata must accompany every dataset from ingestion through deployment. Healthcare AI developers in Germany face the steepest compliance burden, responding by embedding automated lineage capture into clinical data workflows before model training begins.
Buyer procurement patterns are consolidating vendor relationships around integrated platform suites rather than point solutions. Enterprises are displacing best-of-breed data quality tools with unified governance catalogs that bundle discovery, lineage, and policy enforcement. This concentration is most visible in United States hospital networks, where CIOs prioritize single-vendor accountability over specialized functionality to reduce integration risk.
Enterprise Data Management Market Segmentation
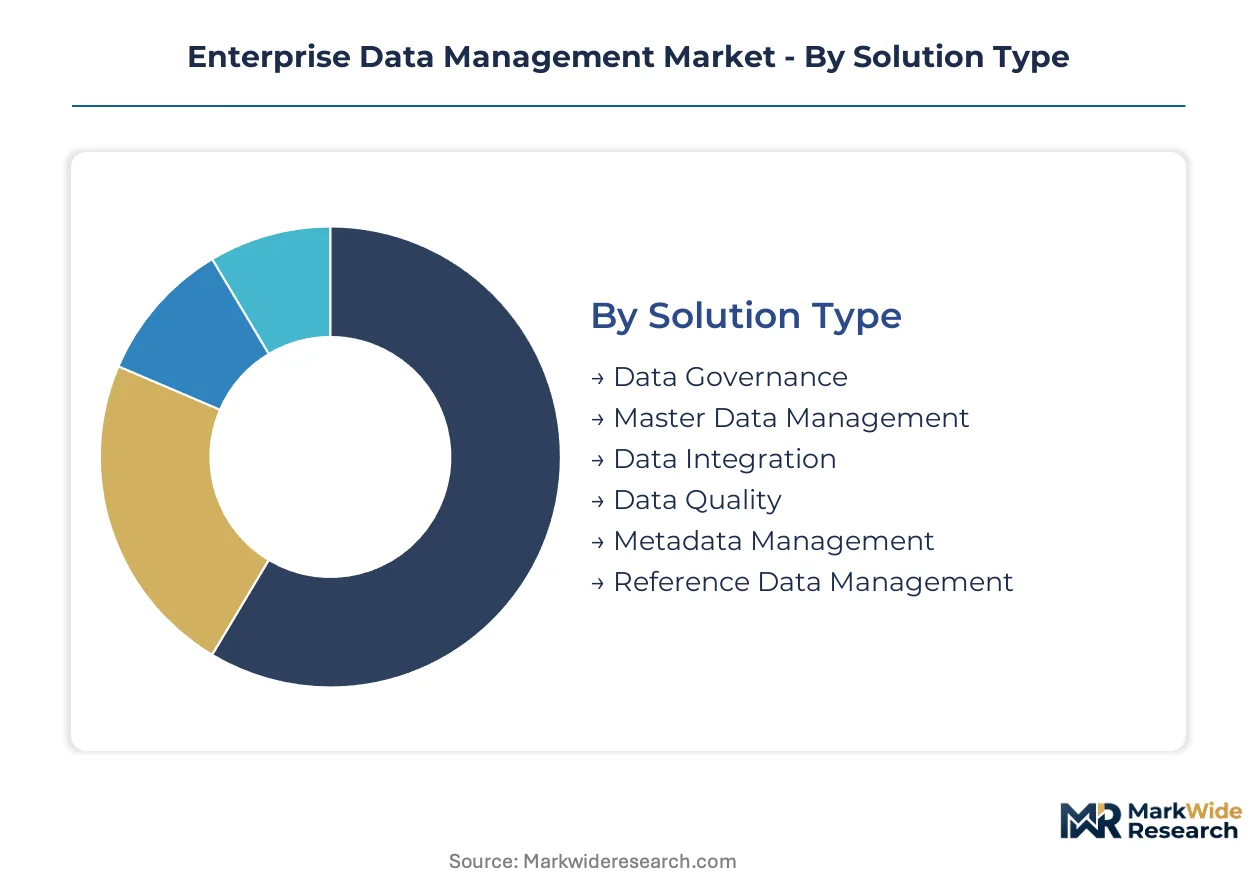
Enterprise Data Management platforms must align solution architecture with specific workload characteristics, compliance postures, and user technical sophistication. Segmentation reveals where capital deployment concentrates and which configurations face the steepest integration complexity.
Solution Type:
Capital intensity varies sharply across solution types, with governance infrastructure requiring sustained investment in policy engines and audit trails while quality tools demand less upfront commitment.
- Data Governance:Policy orchestration platforms enforce regulatory compliance through automated classification and access controls. Financial services firms in the United States absorb the bulk of enterprise deployments as SEC Inline XBRL mandates harden documentation requirements.
- Master Data Management:Golden record systems unify customer, product, and supplier identifiers across operational silos. Healthcare providers in Germany prioritize these investments to satisfy EU AI Act training data provenance rules for clinical AI development.
- Data Integration:ETL and streaming pipeline tools connect heterogeneous source systems.
- Data Quality:Profiling and cleansing modules standardize formats and eliminate duplicates.
- Metadata Management:Automated lineage tracking captures schema evolution and transformation logic.
- Reference Data Management:Centralized repositories maintain authoritative code lists and hierarchies.
Data Governance absorbs the bulk of installed capacity; Master Data Management is expanding most quickly as AI training data requirements proliferate.
Deployment Model:
Deployment choice hinges on data residency obligations and existing infrastructure amortization schedules, with cloud-native configurations demanding re-architecture investment that on-premise extensions avoid.
- On-Premises:Self-managed infrastructure retains physical control over sensitive datasets. India's Digital Personal Data Protection Act is hardening domestic hosting requirements for multinational subsidiaries operating in Mumbai and Bangalore.
- Public Cloud:Shared-tenant platforms from AWS, Azure, and Google Cloud deliver elastic compute for variable workloads. Healthcare networks in the United States are migrating here fastest to escape datacenter refresh cycles.
- Private Cloud:Dedicated single-tenant environments isolate regulated workloads.
- Hybrid Cloud:Split architectures maintain core systems on-premise while bursting analytics to cloud.
- Multi-Cloud:Distributed deployments across multiple hyperscalers mitigate vendor concentration risk.
On-Premises retains the largest legacy footprint; Public Cloud is climbing the fastest as EU AI Act documentation standards accelerate replacement timelines.
Industry Vertical:
Vertical specialization determines integration depth, with regulated industries requiring embedded compliance modules that manufacturing sectors can implement more lightly.
- BFSI:Banking and insurance platforms reconcile transactional records with risk analytics and regulatory reporting. Institutions in the United States and Germany dominate procurement as Basel III and SEC disclosure rules converge.
- Telecommunications:Subscriber data unification across billing, network operations, and customer service systems. Indian carriers are investing heavily to comply with TRAI data localization directives.
- Manufacturing:Supply chain and IoT sensor data integration for predictive maintenance.
- Healthcare Providers:Clinical and operational data convergence for population health management.
- Energy & Utilities:Smart grid and asset performance data harmonization.
- Government Agencies:Inter-agency data sharing with citizen privacy safeguards.
BFSI commands the deepest per-customer investment; Healthcare Providers are gaining share fastest as clinical data volumes surge past storage and governance capacity.
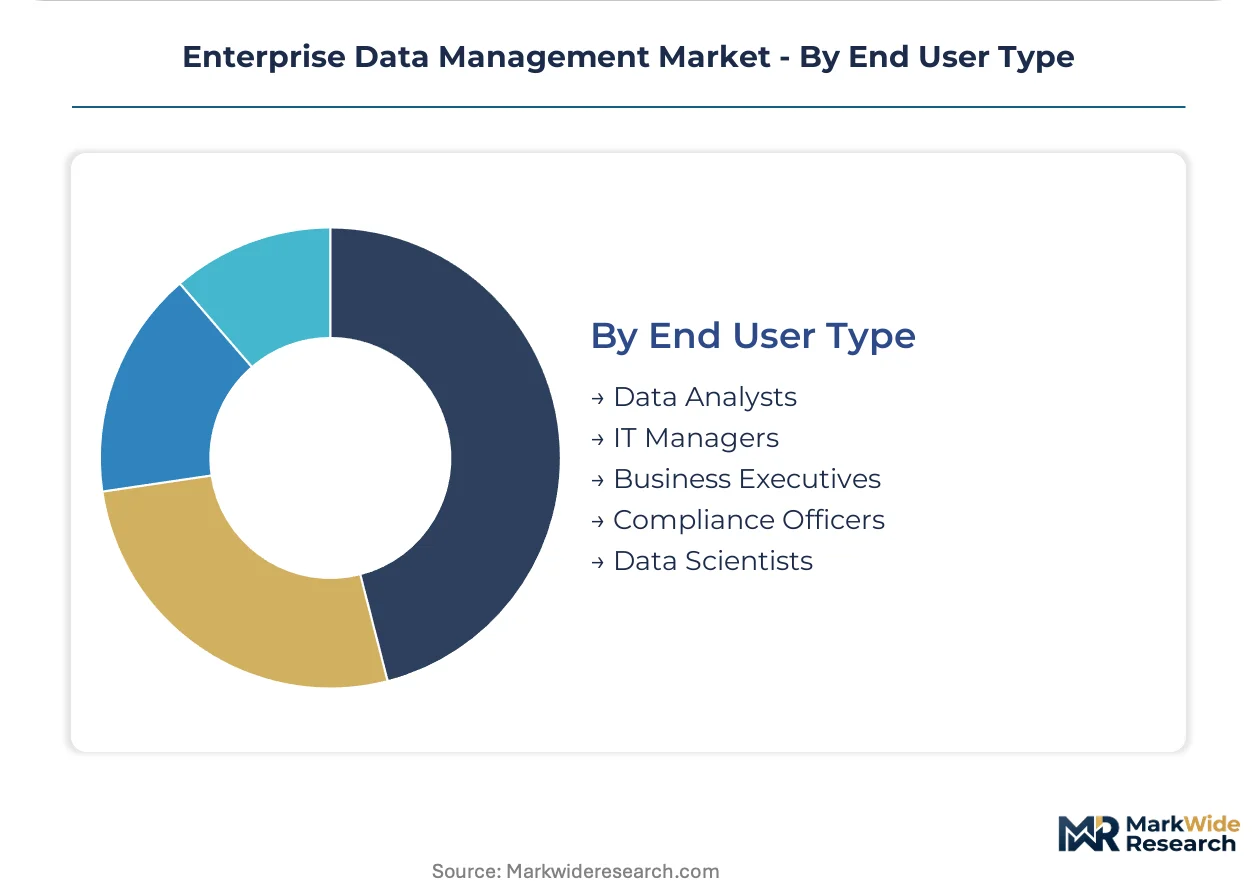
End User Type:
User technical sophistication shapes interface complexity and automation requirements, with technical roles demanding programmatic access while business users require governed self-service.
- Data Analysts:SQL-native users exploring curated datasets through semantic layers. These practitioners in United States hospital networks drive demand for integrated catalog and quality tooling.
- IT Managers:Infrastructure owners responsible for platform uptime, security, and cost optimization. Their procurement authority in German manufacturing firms favors vendors with deep ERP integration credentials.
- Business Executives:Dashboard consumers requiring trusted metrics without technical mediation.
- Compliance Officers:Audit and risk personnel validating data lineage for regulatory submissions.
- Data Scientists:Model developers sourcing training datasets with documented provenance.
Data Analysts represent the largest active user base; Compliance Officers are expanding most quickly as EU AI Act and SEC mandates broaden accountability for data documentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Software Technology Parks of India (STPI) scheme and Special Economic Zones have concentrated data management infrastructure investment in Bengaluru and Hyderabad, drawing multinational subsidiaries seeking compliant hosting environments for sovereign data requirements.
United States
Financial services institutions in New York and Chicago drive governance platform procurement to satisfy SEC Inline XBRL disclosure mandates. Healthcare networks across the Midwest and Pacific Northwest are consolidating vendor relationships around unified catalog suites. Microsoft's Azure Purview deployments anchor hospital data governance architectures in the Boston metropolitan cluster.
Germany
Industrial manufacturers in Baden-Württemberg and Bavaria prioritize master data management for supply chain traceability under EU AI Act documentation standards. Healthcare AI developers in Berlin face steep compliance burdens for clinical training data provenance. SAP sustains platform dominance through deep ERP integration with provider workflow modules.
India
Multinational subsidiaries in Mumbai and Bengaluru reshape cross-border data architectures to comply with Digital Personal Data Protection Act consent-layer obligations. Domestic carriers invest heavily in subscriber data unification to satisfy TRAI localization directives. The country's sovereign data infrastructure buildout creates captive demand for domestic-hosted governance platforms.
United Kingdom
London-based banking groups reconcile transactional records with risk analytics under converging Basel III and emerging UK AI regulatory frameworks. Telecommunications operators in Manchester and Birmingham consolidate billing and network operations data. NHS trusts evaluate cloud migration pathways for patient record unification.
Japan
Automotive manufacturers in the Nagoya industrial corridor deploy streaming data pipelines for IoT sensor integration and predictive maintenance analytics. METI guidance on data governance accelerates enterprise investment in automated lineage tracking. Tokyo-based financial institutions modernize legacy warehouse architectures to escape costly refresh cycles.
Enterprise Data Management Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with hyperscale cloud providers and enterprise software incumbents commanding governance infrastructure while open-source analytics vendors capture specialized integration workloads. The vendor landscape organizes into three strategic archetypes: cloud-native platform operators with metadata automation capabilities, legacy ERP-integrated suite providers with deep workflow embedding, and best-of-breed quality specialists facing consolidation pressure. Dominant competitive moves include vertical capability expansion through embedded AI governance modules and geographic localization partnerships to satisfy data residency mandates.
Within the cloud-native platform tier, Microsoft and Amazon Web Services represent the scale-driven architecture approach, while Oracle occupies a position exemplifying ERP-anchored suite consolidation. IBM anchors the hybrid multi-cloud integration archetype for enterprises distributing workloads across hyperscalers. These three entities collectively illustrate how vendor selection increasingly hinges on existing infrastructure entrenchment rather than standalone feature differentiation.
| Leading Market Players |
|---|
| Microsoft |
| IBM |
| Oracle |
| SAP |
| Amazon Web Services |
| Informatica |
| Teradata Corporation |
| Cloudera |
| Talend |
| Others |
Cost & Logistics Intelligence
EU AI Act documentation standards for training data provenance govern qualified supply access and premium-tier pricing for governance platforms serving financial services and healthcare buyers. Vendors meeting these audit-trail requirements command subscription premiums while non-compliant providers face exclusion from regulated procurement channels.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent deployment premiums from standard-schedule discounts in enterprise data management procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth and geographic data residency compliance. Price differentiation hinges on EU AI Act audit-readiness and multi-cloud schema harmonization capabilities. Cost compression in economy tiers is intensifying because hyperscaler-native alternatives commoditize basic governance functionality. Mid-market healthcare providers in Germany exhibit highest price sensitivity; US financial institutions absorbing SEC mandates show lowest.
Supply Chain Analysis
India's Digital Personal Data Protection Act domestic-content mandates reshape sourcing for multinational subsidiaries operating sovereign data infrastructure. Software development concentrates in India, Germany, and the United States for policy engine and metadata automation components. Cloud compute capacity draws from hyperscaler regions in Ireland, Singapore, and Virginia. Single-source vulnerability persists where specialized lineage-tracking IP rests with boutique vendors. Distribution runs through direct enterprise sales teams supplemented by systems integrator partnerships for complex multi-cloud deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise data management has become a vertical-integration race where control over metadata automation IP and cloud infrastructure anchors margin defense. Players are pursuing downstream embedding into ERP and clinical workflow systems to lock in switching costs.
For Market Incumbents: Deepen ERP integration partnerships to entrench workflow embedding against cloud-native challengers. Expand India-based delivery capacity to capture Digital Personal Data Protection Act-mandated localization demand. Prioritize EU AI Act certification investment to maintain premium pricing access in German healthcare and financial services procurement. For New Entrants and Emerging Players: Cloud service provider marketplaces offer the fastest channel to bypass incumbent sales cycles and reach mid-market buyers. Target India's domestic-hosted governance segment where multinational subsidiaries require compliant alternatives to global platforms. Lead with automated schema discovery differentiation to displace manual stewardship contracts in US hospital networks. For Investors and Strategic Acquirers: EU AI Act enforcement actions against non-compliant training data pipelines are the leading indicator that provenance-tracking specialist valuations will decouple from generic data quality tools. Five-to-ten-year viability favors vendors with hybrid multi-cloud orchestration capabilities and embedded AI governance modules. Watch for SEC Inline XBRL mandate expansion into private company disclosures as signal for governance platform demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified catalog suites displace point solutions in US hospital network consolidation. |
| Geographic Expansion | India data center buildouts capture Digital Personal Data Protection Act localization requirements. |
| Strategic Partnership | Hyperscaler alliances accelerate multi-cloud deployment velocity for financial services. |
| Acquisition of Specialist Firm | Automated lineage tracking IP addresses EU AI Act provenance compliance gaps. |
| Product Launch | Real-time streaming governance modules enable operational intelligence in manufacturing. |
Research Approach
SEC disclosure filings, EU regulatory guidance documents, and hyperscaler infrastructure investment reports formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with data governance architects, healthcare CIOs, financial services compliance officers, and cloud platform engineers validated deployment patterns and procurement criteria. Bottom-up and top-down triangulation reconciled vendor revenue disclosures with end-user spending surveys across the analysis window.
Bottom-up modeling aggregated individual country-level deployments by solution type, deployment model, and vertical, while top-down analysis cross-checked against aggregate IT spending benchmarks. Segmentation dimensions included governance versus quality versus integration solutions, on-premise versus public cloud versus multi-cloud configurations, and BFSI versus healthcare versus telecommunications verticals. CAGRs derived from regression analysis of historical replacement cycles and regulatory mandate acceleration effects, with EU AI Act and SEC disclosure timelines as primary inflection inputs.
Caveats apply where regulatory enforcement intensity, cloud migration cost volatility, or talent scarcity constraints could materially shift the outlook. Forecasts reflect documented assumptions about compliance timeline adherence and infrastructure refresh cyclicality. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Community Engagement Platform Market
Digital Solutions
Online Hyper-Local Services Market
Digital Solutions
Agent-Oriented Enterprise Architecture Market
Digital Solutions
File Sharing Market
Digital Solutions
Manufacturing Execution System Market
Digital Solutions
IT Asset Management Solutions (ITAM) Market
Digital Solutions
Product Data Management Market
Digital Solutions
Remote Integration Solutions Market
Digital Solutions
Artificial Intelligence (AI) in Marketing Market
Digital Solutions
Qatar ICT Market
Digital Solutions
Europe IT Asset Disposition Market
Digital Solutions
Global Data Quality Tool Market
Digital Solutions
Global Parking Reservation System Market
Digital Solutions
Japan E-Invoicing Market
Digital Solutions
Global E-Signature Platform Market
Digital Solutions
Global Mobile Workforce Management Market