
 Europe Cellular IoT Market | 2026-2036
Europe Cellular IoT Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cellular IoT Market Intelligence
A shift from multi-source component procurement toward integrated platform solutions is expanding across the European market. This trend favors large industrial conglomerates and software providers. Siemens leverages its deep industrial automation expertise to offer end-to-end systems for manufacturing clients. SAP SE competes on the strength of its enterprise data management and analytics platforms, integrating IoT data into business workflows.
Europe Cellular IoT involves connecting physical objects and sensors to the internet using licensed cellular networks. These technologies, such as NB-IoT, are characterized by low power consumption, enabling long-term deployments in remote or inaccessible locations. While LTE-M and NB-IoT technologies currently lead in smart metering applications, the rollout of 5G connectivity creates opportunities in the transportation sector. Gateways and sensors constitute the primary device types deployed across these industries.
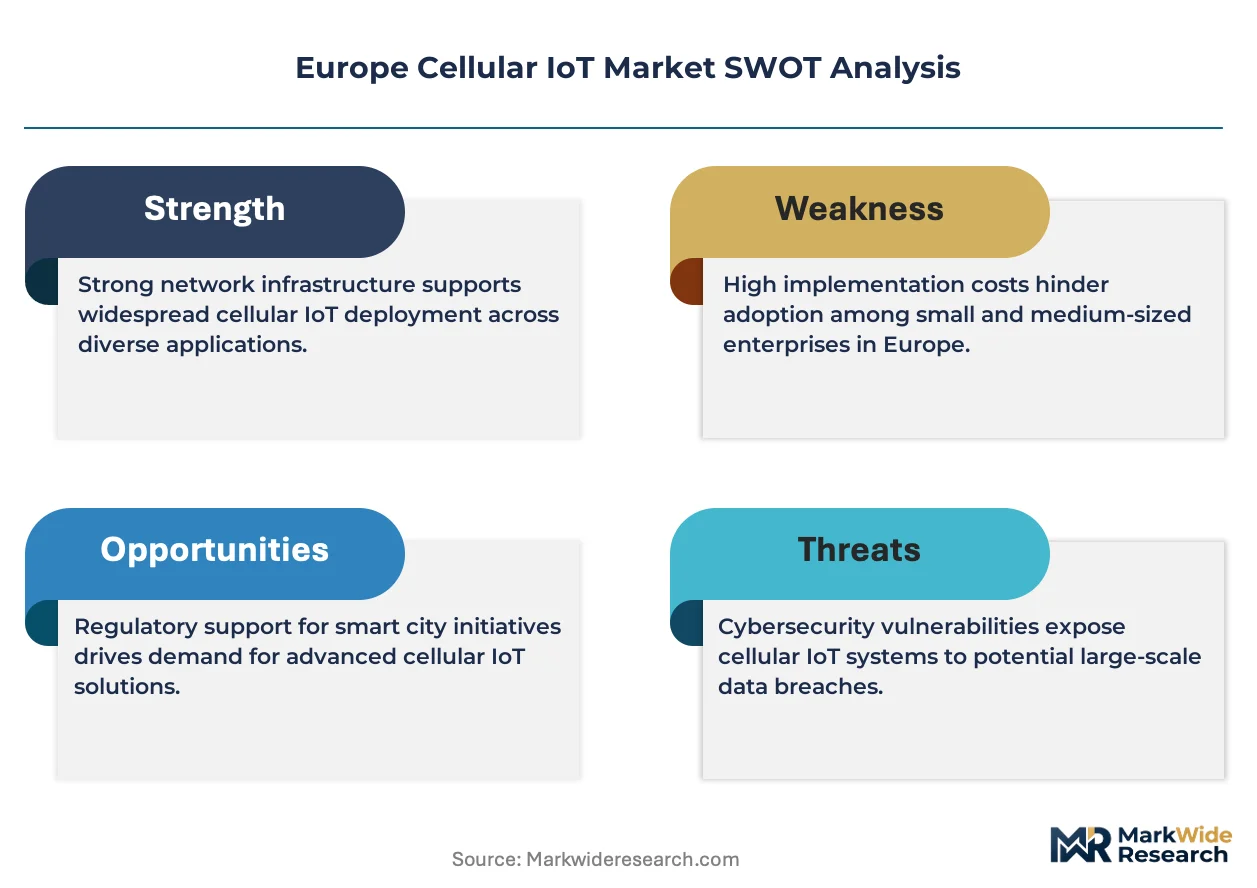
The General Data Protection Regulation (GDPR) imposes strict rules on how personal data from connected devices is collected and processed across the EU. Concurrently, compliance with CE marking and standards from the EU Cybersecurity Act is mandatory for market access. Navigating the fragmented spectrum allocation and evolving data sovereignty laws remains a critical consideration for module manufacturers and service providers.
Market Dynamics
The imperative for energy efficiency, driven by the EU Green Deal, is the central force shaping the Europe Cellular IoT market. This regulatory pressure accelerates the adoption of smart metering and grid modernization technologies across the continent.
Growth Catalysts
- Regulatory Mandates:The EU's energy efficiency directives and Green Deal initiatives create a direct requirement for utilities to deploy smart meters and grid management systems, which depend on reliable cellular connectivity.
- Technology Maturation:The low power consumption and wide coverage of NB-IoT and LTE-M technologies make them technically and economically viable for long-term deployments in remote utility infrastructure and logistics assets.
- Industrial Modernization:Germany's large industrial base and its commitment to Industrie 4.0 principles create sustained demand for cellular IoT solutions to enable smart factories, predictive maintenance, and automated supply chains.
Market Restraints
- Data Privacy Compliance:The stringent requirements of the General Data Protection Regulation (GDPR) create complexity in designing and deploying pan-European IoT solutions, particularly those handling personal or sensitive data.
- Spectrum Fragmentation:Varying cellular spectrum allocations and licensing rules across different EU member states present a persistent hurdle for module manufacturers aiming to develop single, unified products for the entire European market.
- Alternative Technologies:In specific, localized applications like smart agriculture or private campus networks, non-cellular LPWAN technologies such as LoRaWAN remain a competitive alternative, limiting cellular IoT's total addressable market.
Strategic Opportunities
- 5G in Mobility:The continued rollout of 5G networks opens new service opportunities for low-latency applications, particularly in the transportation and logistics sectors for connected vehicle fleets and advanced driver-assistance systems.
- Edge Computing Integration:Combining cellular IoT with edge computing allows for real-time data processing on gateways and devices, creating value in industrial automation where low latency and data reduction are critical.
- Eastern Europe Expansion:Catch-up investments in grid modernization and smart city infrastructure in countries across Central and Eastern Europe represent a significant, underpenetrated geographic market for cellular IoT deployments.
Industry Challenges
- Legacy System Integration:A primary operational hurdle is the complexity and cost associated with integrating modern IoT platforms with aging, proprietary operational technology (OT) systems common in the utilities and manufacturing sectors.
- Cybersecurity Certification:Navigating the evolving requirements of the EU Cybersecurity Act adds a significant layer of compliance overhead, potentially delaying time-to-market for new IoT devices and platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cellular IoT Market |
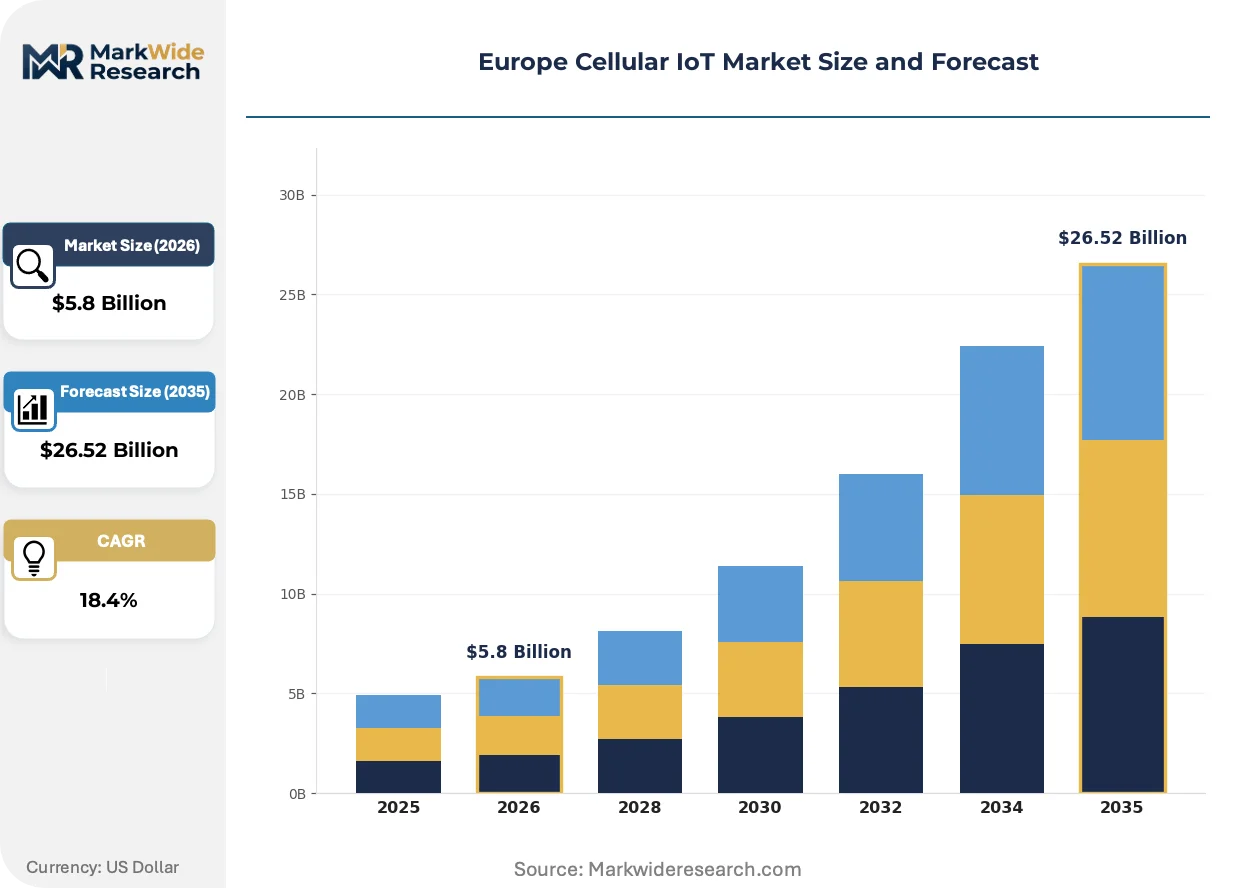
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $26.52 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Connectivity Type: NB-IoT, LTE-M, 5G, Cat-1, Cat-M2 Application: Smart Metering, Fleet Management, Asset Tracking, Smart Agriculture, Environmental Monitoring Device Type: Wearables, Gateways, Sensors, Meters, Trackers End User Industry: Transportation, Energy & Utilities, Agriculture, Manufacturing, Public Safety |
| Companies Covered | Cavli Wireless, Siemens, Quectel Wireless Solutions, Robert Bosch GmbH, SAP SE, Fibocom Wireless, STMicroelectronics, NXP Semiconductors, Nordic Semiconductor, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cellular IoT Market Strategic Shifts & Innovations
The convergence of hardware, connectivity, and software into unified offerings is a defining market characteristic. This evolution favors providers capable of delivering end-to-end platforms rather than discrete components, fundamentally altering the competitive landscape.
Low Power Wide Area (LPWA) technologies, specifically NB-IoT and LTE-M, provide the foundation for massive-scale IoT. Utilities, logistics firms, and smart city operators are rapidly adopting these standards for long-life, battery-powered devices. This widespread implementation is consolidating the market around licensed cellular standards, reducing the influence of fragmented, proprietary communication protocols.
The EU Green Deal establishes firm targets for carbon reduction and energy efficiency. This policy framework directly incentivizes and, in some cases, mandates investment in smart grid infrastructure to manage renewable energy sources and monitor consumption. Consequently, the energy and utilities sector is a primary adopter of cellular IoT for smart metering and distribution automation to meet these regulatory obligations.
A notable shift in enterprise buying patterns favors the adoption of integrated IoT platforms over the procurement of individual components. This trend disrupts the traditional, hardware-focused sales model, creating an advantage for suppliers that bundle sensors, connectivity, and analytics into a single service. The move toward platform-based solutions is most advanced within the industrial manufacturing and automotive sectors of Western Europe.
Europe Cellular IoT Market Segmentation
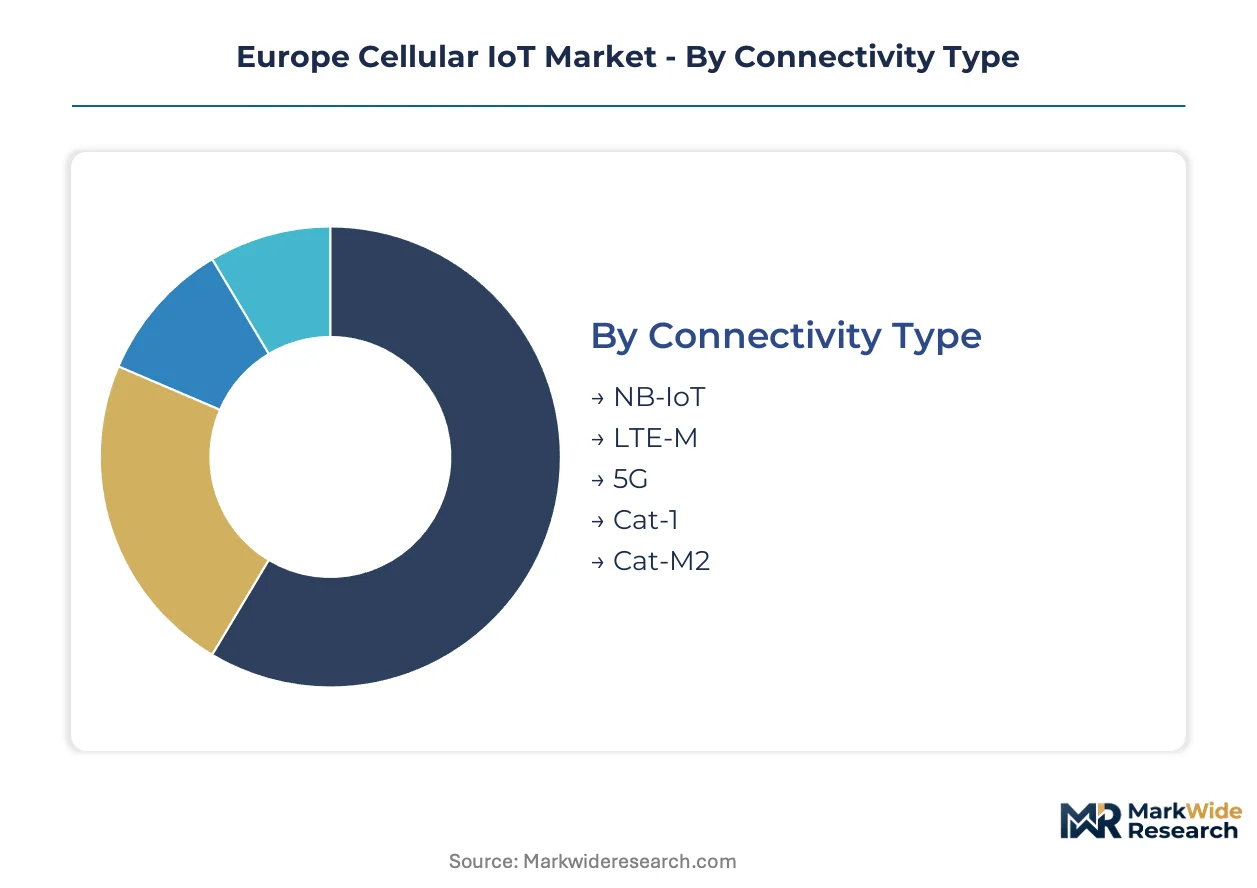
The Europe Cellular IoT market is highly diversified, with segmentation providing critical insights into technology adoption patterns and end-user requirements. Analyzing these segments helps stakeholders understand where investment is concentrating and how various cellular technologies address specific industrial challenges. This granular view is essential for developing tailored solutions and navigating the complex regulatory landscape across European Union member states.
Connectivity Type:
Cellular IoT connectivity types range from highly integrated, low-power embedded solutions to more versatile, higher-bandwidth options for diverse applications across Europe.
- NB-IoT:This narrowband technology offers extensive coverage and deep penetration, ideal for static, low-data applications requiring long battery life. Demand for NB-IoT is particularly strong in smart metering deployments across the utilities sector, driven by EU energy efficiency directives.
- 5G:The fifth generation of cellular technology provides ultra-low latency, high bandwidth, and massive connectivity, enabling real-time applications such as autonomous vehicles and industrial automation. Opportunities for 5G are expanding in the transportation sector for connected vehicle fleets and advanced driver-assistance systems.
- LTE-M:Optimized for IoT devices, LTE-M supports higher data rates than NB-IoT and voice capabilities, making it suitable for mobile assets and more complex data transmission.
- Cat-1:This category supports higher data rates than LPWAN technologies, often used for applications requiring moderate bandwidth and voice support like alarm systems or point-of-sale terminals.
- Cat-M2:Also known as LTE-M2, this is an evolution of LTE-M, designed for even lower power consumption and extended coverage for a new generation of IoT devices.
Volume placements concentrate in NB-IoT; the faster expansion belongs to 5G.
Application:
The diverse applications of Europe Cellular IoT reflect various operational demands across sectors, each presenting unique deployment challenges and opportunities.
- Smart Metering:Cellular IoT enables automated collection of utility consumption data, facilitating efficient billing, demand-side management, and grid optimization. This application is a primary contributor to market growth, accelerated by the EU Green Deal's focus on energy efficiency.
- Fleet Management:This application involves tracking and managing vehicle fleets using cellular connectivity for real-time location, diagnostics, and route optimization. The transportation sector is leveraging 5G's low latency for enhanced fleet coordination and safety features.
- Asset Tracking:Cellular IoT provides real-time location and status monitoring for high-value assets, improving logistics efficiency and reducing loss.
- Smart Agriculture:This segment utilizes cellular connectivity for remote monitoring of crop conditions, livestock, and farm equipment, optimizing resource use.
- Environmental Monitoring:Cellular IoT devices are deployed to collect data on air quality, water levels, and other environmental parameters, supporting regulatory compliance and conservation efforts.
Smart Metering currently drives significant demand; Fleet Management is gaining share fastest.
Device Type:
Cellular IoT device types categorize by their primary function and deployment environment, ranging from simple sensors to complex gateways that aggregate data.
- Gateways:These devices act as central hubs, aggregating data from multiple sensors and transmitting it to the cloud via cellular networks. Gateways are crucial for edge computing integration in industrial automation, processing data locally to reduce latency.
- Sensors:Cellular IoT sensors collect specific environmental or operational data, such as temperature, pressure, or movement, and transmit it wirelessly. These devices are foundational for long-term deployments in remote utility infrastructure due to their low power consumption.
- Meters:Specialized devices for measuring consumption of utilities like electricity, gas, or water, often integrating cellular modules for automated data transmission.
- Trackers:Compact, battery-powered devices designed specifically for location tracking of assets, vehicles, or even people, using cellular networks for communication.
- Wearables:Cellular-enabled wearable devices provide connectivity for personal safety, health monitoring, or specialized industrial applications.
Gateways and Sensors represent the core of current deployments, while Meters show a steep expansion trajectory.
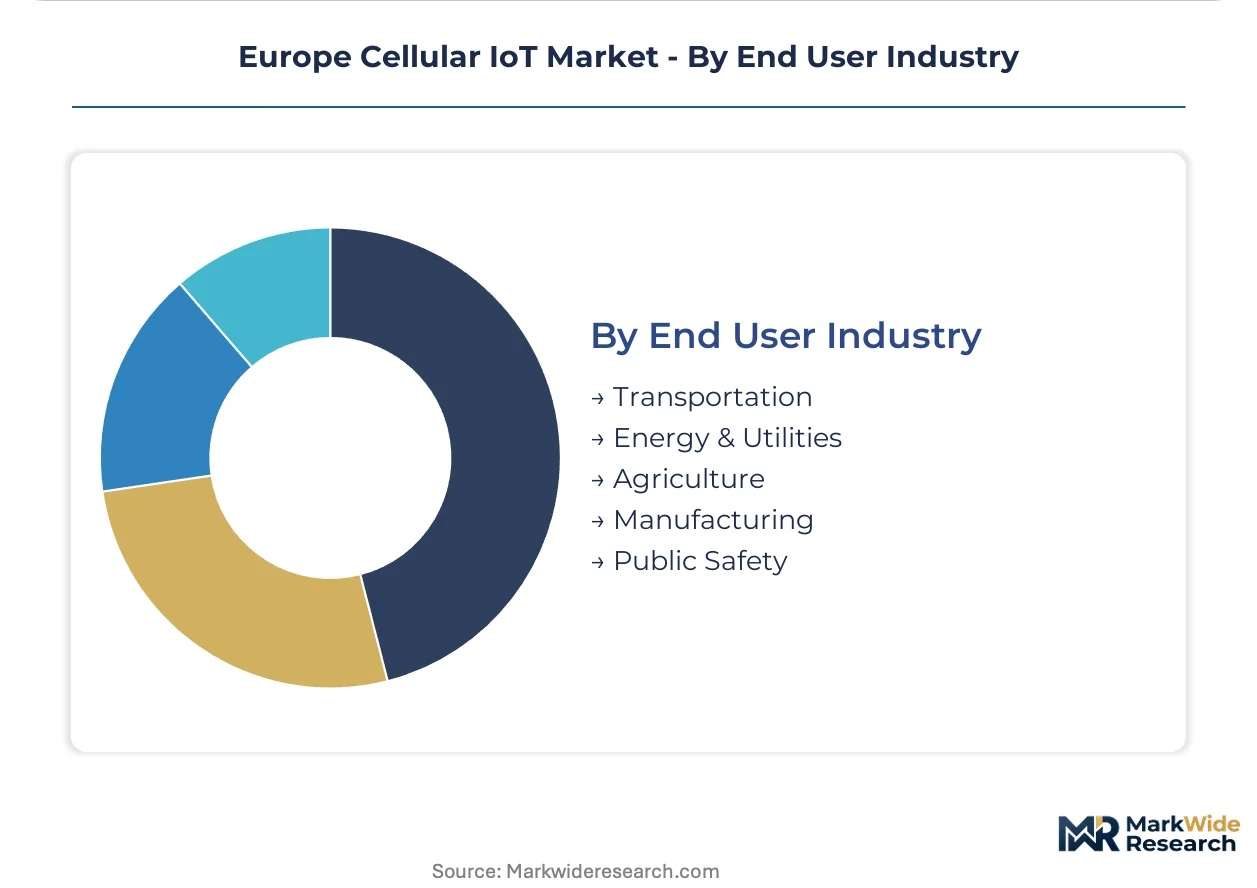
End User Industry:
End user industries define specific requirements for cellular IoT deployments, from critical infrastructure management to mobile asset oversight.
- Energy & Utilities:This sector utilizes cellular IoT for smart grid modernization, smart metering, and remote monitoring of energy infrastructure. The EU Green Deal and national energy efficiency directives are primary drivers for cellular IoT adoption in this industry.
- Manufacturing:Industrial manufacturers deploy cellular IoT for smart factory initiatives, predictive maintenance, and automated supply chain management, aligning with Industrie 4.0 principles. Germany's large industrial base represents a significant demand center for these solutions.
- Transportation:Cellular IoT supports fleet management, logistics, and connected vehicle applications, enhancing efficiency and safety.
- Agriculture:Farmers employ cellular IoT for precision agriculture, including crop monitoring, irrigation management, and livestock tracking.
- Public Safety:This sector uses cellular IoT for emergency response, remote surveillance, and critical infrastructure protection, ensuring reliable communication in challenging environments.
Energy & Utilities remains a dominant segment, with Manufacturing exhibiting rapid adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The strong regulatory framework of the EU, particularly the EU Green Deal, anchors the European Cellular IoT market. This policy environment mandates energy efficiency and grid modernization, directly stimulating demand for smart metering solutions. Germany's robust industrial base further solidifies the region's position as a core adoption hub.
Germany
Germany's industrial modernization and commitment to Industrie 4.0 principles drive significant demand for cellular IoT in smart factories. The EU Green Deal further accelerates the deployment of smart grid technologies across the nation. Industrial clusters in Bavaria and North Rhine-Westphalia actively integrate cellular IoT for predictive maintenance and automated supply chains.
United Kingdom
The United Kingdom prioritizes smart metering rollouts and digital transformation across its utility sector, creating substantial cellular IoT demand. Government mandates for smart meter installations directly support this market expansion. Cities like London and industrial centers in the Midlands are implementing cellular IoT for urban infrastructure management and logistics optimization.
France
French energy transition goals and smart agriculture initiatives stimulate cellular IoT adoption for resource management. National policies supporting renewable energy integration align with the broader EU Green Deal objectives. The Île-de-France region and agricultural areas leverage cellular IoT for smart city applications and precision farming solutions.
Italy
Italy's utility grid modernization efforts and industrial automation projects generate consistent demand for cellular IoT solutions. Italian energy efficiency directives, alongside the EU Cybersecurity Act, shape market requirements for secure deployments. Manufacturing hubs in Lombardy and Emilia-Romagna utilize cellular IoT for asset tracking and process optimization.
Poland
Poland represents a significant growth area due to catch-up investments in grid modernization and smart city infrastructure. EU cohesion funds and the national digital agenda support widespread cellular IoT deployments. Major urban centers like Warsaw and emerging industrial zones are implementing cellular IoT for public services and logistics.
Europe Cellular IoT Market Key Industry Players
Global majors compete with regional champions across technology integration and end-to-end solution delivery. The European Cellular IoT market exhibits a tiered structure, with large industrial conglomerates and specialized software providers dominating the integrated platform segment. Connectivity module manufacturers and sensor developers form a distinct tier focusing on hardware components. Key strategic archetypes include end-to-end solution providers, connectivity specialists, and data analytics platforms. Strategic partnerships and portfolio diversification are common competitive moves observed among market participants.
Within the integrated platform segment, Siemens and SAP SE exemplify distinct approaches to the European Cellular IoT market. Siemens leverages its deep industrial automation expertise to offer end-to-end systems for manufacturing clients, representing the industrial conglomerate archetype. SAP SE, a German company, anchors the enterprise data management and analytics platform segment, integrating IoT data into business workflows with robust analytics capabilities. Quectel Wireless Solutions, a prominent module manufacturer, sits within the connectivity specialist archetype, providing foundational hardware for diverse deployments across the region.
| Leading Market Players |
|---|
| Cavli Wireless |
| Siemens |
| Quectel Wireless Solutions |
| Robert Bosch GmbH |
| SAP SE |
| Fibocom Wireless |
| STMicroelectronics |
| NXP Semiconductors |
| Nordic Semiconductor |
Cost & Logistics Intelligence
Cellular module component costs, influenced by semiconductor fabrication and logistics, directly impact the final pricing of integrated cellular IoT platforms and end-device solutions across Europe. These upstream pressures translate into varying pricing strategies for different service tiers.
Pricing Analysis
Warranty and service bundling often differentiate cellular IoT offerings, with premium platforms including extensive after-sales support and data analytics. The dominant pricing model for integrated solutions is subscription-based, while hardware components like modules are typically per-unit transactional. Customization for specific industrial applications and guaranteed service level agreements drive price differentiation. Pricing softness reflects intense competition for basic connectivity, making utilities and smart city operators highly price-sensitive buyers.
Supply Chain Analysis
Single-source vulnerability sits with specialized semiconductor foundries, primarily in Asia, for critical cellular IoT module components. The overall supply chain for hardware components draws heavily from East Asian manufacturing hubs like China and South Korea. Geopolitical tensions and logistics chokepoints present a structural risk to module availability. Distribution runs through direct sales channels for integrated platform providers like Siemens, while module manufacturers often rely on a network of European distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Cellular IoT market remains a supply-constrained story, with specialized semiconductor fabrication capacity for low-power modules propping pricing for foundational hardware. This bottleneck underscores the strategic importance of secure component sourcing.
For Market Incumbents: To counter the commoditization of basic cellular connectivity and the rise of specialized software entrants, large industrial conglomerates must deepen their end-to-end platform integration. Investing in advanced cybersecurity certification under the EU Cybersecurity Act provides a critical differentiation lever. Siemens, for instance, should prioritize R&D into edge computing capabilities for industrial automation clients.
For New Entrants and Emerging Players: Begin with targeted deployments in underpenetrated Central and Eastern European markets, focusing on grid modernization and smart city infrastructure. Niche applications like smart agriculture also present accessible entry points due to less entrenched competition. Offering outcome-based solutions, where payment aligns with achieved energy savings or operational efficiency, provides a compelling go-to-market angle for utilities.
For Investors and Strategic Acquirers: Accelerated 5G rollout across major European transportation corridors is the leading indicator that new mobility applications are gaining traction. The market demonstrates long-term viability, anchored by the EU Green Deal's sustained regulatory tailwinds. Acquisition targets should prioritize specialized software providers with deep vertical expertise in industrial automation or fleet management, offering high-margin analytics capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Bundling hardware, software, and connectivity streamlines deployment for industrial clients. |
| Cybersecurity Certification | Attaining EU Cybersecurity Act compliance builds trust and ensures market access for devices. |
| 5G Application Development | Focusing on low-latency transport solutions captures new revenue streams in mobility. |
| Eastern Europe Market Entry | Expanding into underpenetrated regions leverages catch-up investments in grid modernization. |
| Edge Computing R&D | Developing real-time data processing capabilities reduces latency for critical industrial tasks. |
Research Approach
Multi-period observation of IoT device deployments, cellular network coverage expansion, and regulatory policy changes anchored the trend analysis, supplemented by interviews with industry stakeholders. We engaged utility planning officers, industrial automation engineers, telecom network architects, and cybersecurity specialists. Secondary validation drew from EU Commission reports, national regulatory filings, and technology vendor whitepapers, triangulating insights through both bottom-up and top-down approaches.
An input-output matrix structured the quantitative analytical framework, modeling volume and value across the analysis window. Segmentation dimensions included connectivity type, application, device type, end-user industry, and regional regulatory clusters. Compound annual growth rates derived from historical data, expert consensus, and projected market drivers. Key inputs included 5G rollout projections, smart meter deployment mandates, and industrial IoT investment trends.
Geopolitical shifts affecting component supply, unforeseen regulatory changes in data privacy, and rapid technological disruption are the dominant revision risks to forecasts. Projections reflect current policy trajectories and anticipated market adoption rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Global IoT Node and Gateway Market
Internet of Things (IoT)
UK IoT Software Market
Internet of Things (IoT)
Connected IoT Devices Market
Internet of Things (IoT)
Europe IoT Market
Internet of Things (IoT)
LAMEA Bluetooth 5.0 Market
Internet of Things (IoT)
Connected Bottles Market
Internet of Things (IoT)
IoT in Energy Market
Internet of Things (IoT)
Global IoT Devices Market
Internet of Things (IoT)
IoT Gateway Hardware and Software Market
Internet of Things (IoT)
Massive Machine Type Communication Market
Internet of Things (IoT)
Cellular IoT Module Market
Internet of Things (IoT)
Global IoT Connectivity Market
Internet of Things (IoT)
Lora and Lorawan IoT Connectivity Market
Internet of Things (IoT)
Massive IoT Market
Internet of Things (IoT)
Cellular Internet of Things (IoT) Devices Market
Internet of Things (IoT)
North America Narrowband-Internet of Things (NB-IoT) Market