
 IoT Infrastructure Market | 2026-2036
IoT Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Infrastructure Market Analysis
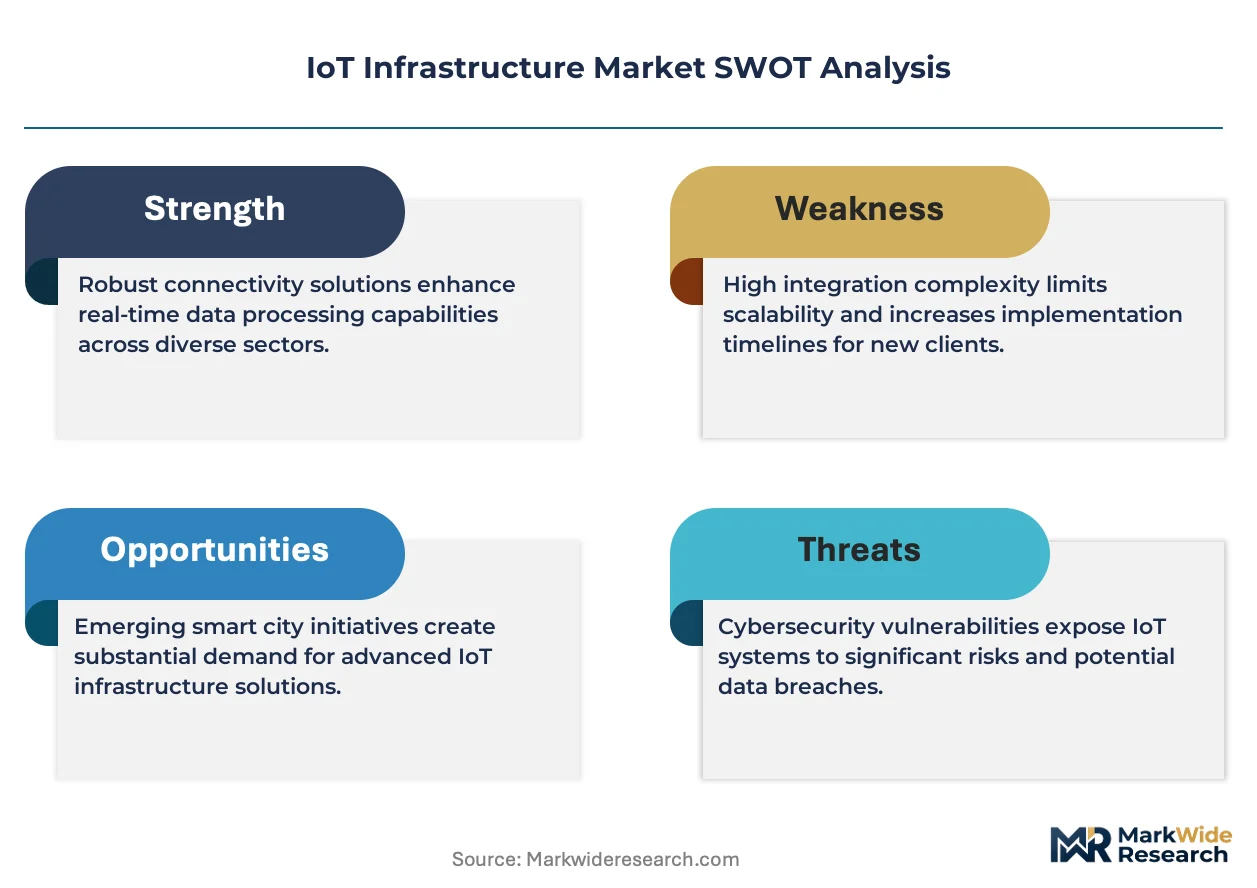
Cloud service provider alliances is reshaping how enterprises procure IoT infrastructure stacks. Cisco controls enterprise networking channels through deep hardware-software integration. Amazon extends its position via AWS IoT Core connectivity services spanning edge to cloud. Microsoft anchors industrial workloads through Azure IoT Hub partnerships with manufacturing OEMs.
IoT infrastructure comprises the layered hardware, software, and communication systems enabling device interconnection, data ingestion, and real-time analytics across distributed environments. Edge nodes typically operate with sub-50 millisecond latency thresholds to support time-critical automation decisions. Network infrastructure leads current deployment spending as organizations retrofit factory floors with industrial Ethernet and private cellular. Managed services represents the fastest-expanding service category as enterprises outsource fleet monitoring and security patching to specialized operators.
EU AI Act classification rules now shape how connected device manufacturers design algorithmic transparency into IoT platforms. FCC spectrum allocations for CBRS and 5G private networks directly determine deployment feasibility across US industrial campuses. NIST cybersecurity frameworks mandate baseline encryption standards for federal IoT procurements. Stakeholders must weigh sovereign data requirements against cloud economics when selecting deployment architectures.
Market Dynamics
Private 5G network rollouts across German industrial zones are compressing deployment timelines for edge-native architectures, forcing infrastructure vendors to pre-integrate radio access network elements with on-premises compute nodes.
Growth Catalysts
- EU Green Deal factory mandates:Germany's industrial decarbonization requirements accelerate sensor density targets for energy monitoring systems. Facility operators must retrofit legacy equipment with connected metering infrastructure.
- Edge computing latency thresholds:Sub-50 millisecond processing requirements for robotic control systems drive co-location of compute with production machinery. Automotive stamping lines now specify edge node proximity as a procurement criterion.
- Southeast Asia smart city clusters:Singapore and Bangkok municipal data platforms aggregate multi-vendor sensor streams. Standardized API frameworks reduce integration friction for foreign infrastructure suppliers.
Market Restraints
- Semiconductor supply concentration:Industrial Ethernet switch ASIC fabrication concentrates at Taiwan foundries. Lead times for time-sensitive networking chipsets extend procurement cycles.
- CBRS spectrum licensing friction:FCC auction structures create uncertainty for US manufacturing campuses evaluating private cellular. Site-specific authorization timelines delay pilot-to-production transitions.
- Legacy OT-IT protocol incompatibility:Proprietary fieldbus systems in process industries resist standard IP migration. Brownfield integration requires protocol gateway layers that inflate system complexity.
Strategic Opportunities
- India industrial corridor buildouts:PLI scheme incentives for electronics manufacturing attract private 5G infrastructure investment. Gujarat and Tamil Nadu states offer land-banking for edge data center placement.
- Digital twin convergence:Physics simulation engines merge with real-time sensor feeds for predictive maintenance. Oil and gas operators pilot unified platforms that collapse previously separate software procurement.
- NIST cybersecurity framework mandates:Federal IoT procurement baselines create certified product categories. Vendors achieving FIPS 140-2 validation capture defense and critical infrastructure segments.
Industry Challenges
- OT security skill scarcity:Industrial control system expertise remains concentrated among aging practitioner cohorts. Universities lack curricula bridging network engineering with manufacturing process knowledge.
- Multi-vendor integration complexity:Heterogeneous sensor fleets from competing hardware suppliers resist unified management plane deployment. System integrators absorb margin erosion from custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Infrastructure Market |
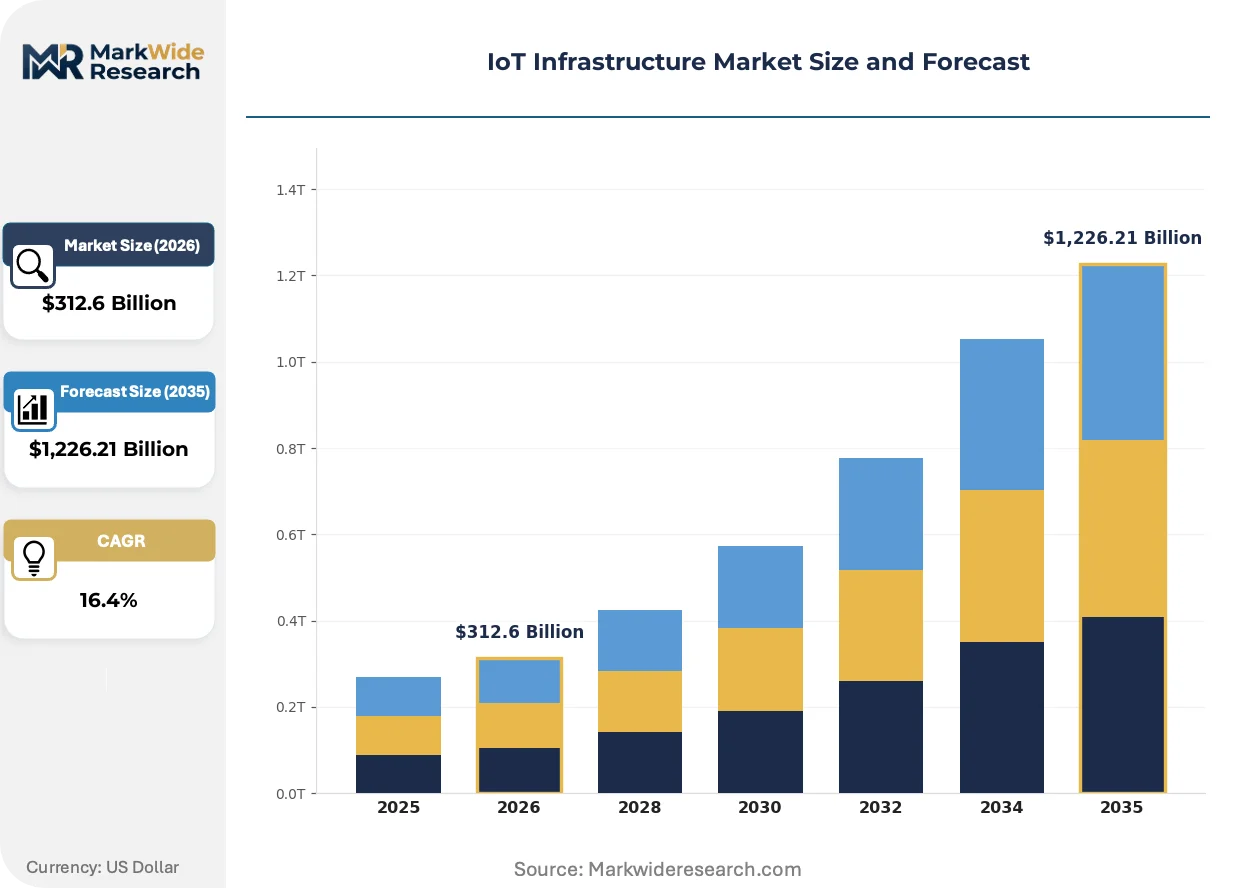
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $1,226.21 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Infrastructure Type: Edge Computing, Cloud Computing, Network Infrastructure, Security Framework Deployment Model: Private Cloud, Public Cloud, Hybrid Cloud, On-Premises Service Type: Managed Services, Professional Services, Consulting Services, Technical Support Use Case: Smart Cities, Industrial Automation, Healthcare Monitoring, Agricultural Solutions |
| Companies Covered | Intel, Amazon, Siemens, Google, Microsoft, PTC, ABB, Samsara, Cisco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Infrastructure Market Emerging Trajectories
Time-sensitive networking standards are collapsing the separation between information technology and operational technology infrastructure layers. This convergence eliminates redundant cabling and switching hardware while introducing new failure modes that vendors must engineer around.
Time-sensitive networking is digitizing motion control systems that previously relied on dedicated fieldbus architectures. Automotive assembly plants in Stuttgart and Wolfsburg adopt TSN-enabled servo drives to synchronize robotic welding sequences. The technology is digitizing machine tool coordination by enabling deterministic Ethernet transport of microsecond-precision timing signals.
EU AI Act risk classification rules now mandate algorithmic transparency documentation for connected safety systems. Medical device and autonomous machinery manufacturers must maintain model training logs and decision audit trails. High-risk IoT deployments in German automotive and French aerospace sectors face notified body review timelines that extend product launch schedules.
Industrial buyers now unbundle hardware procurement from multi-year managed service commitments. German Mittelstand manufacturers prefer capex-light subscription models for fleet monitoring and security patching. This preference shift concentrates vendor revenue in recurring service streams and compresses upfront equipment margins across Central European manufacturing clusters.
IoT Infrastructure Market Segmentation
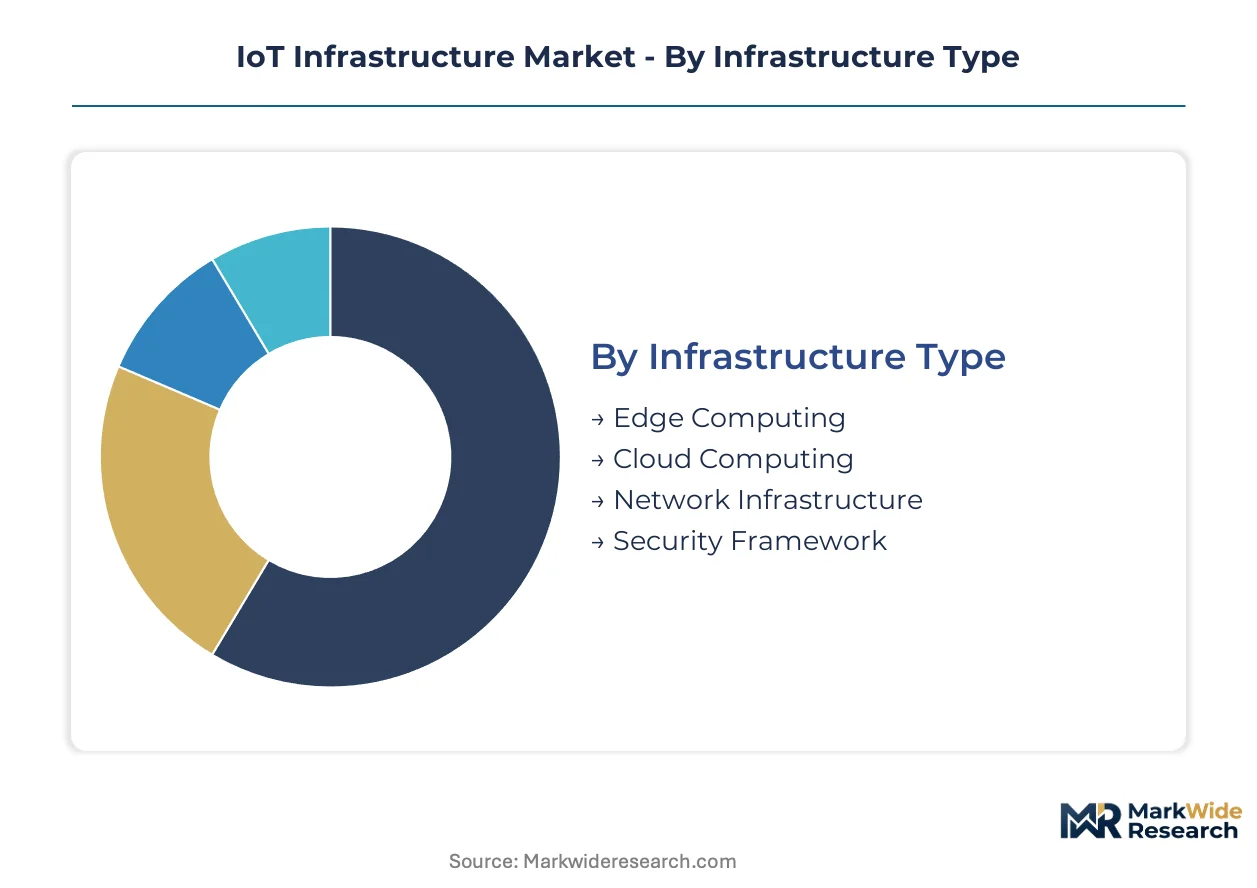
IoT infrastructure procurement patterns diverge sharply between latency-sensitive industrial workloads and data-sovereign municipal deployments. Infrastructure buyers select stack configurations based on where processing must occur relative to sensor sources.
Infrastructure Type:
Edge-to-cloud distribution requirements span microsecond-precision factory floors through centralized analytics warehouses.
- Edge Computing:Distributed compute nodes co-locate with production machinery to achieve sub-50 millisecond latency for robotic control systems. German automotive stamping lines specify edge proximity as mandatory procurement criteria under EU Green Deal factory mandates.
- Network Infrastructure:Industrial Ethernet switches and private 5G radio access networks form the connectivity backbone for brownfield retrofits. Taiwan foundry concentration for time-sensitive networking ASICs extends procurement cycles for German Mittelstand manufacturers.
- Cloud Computing:Centralized data lakes aggregate cross-facility telemetry for predictive maintenance model training.
- Security Framework:NIST-mandated encryption modules protect federal IoT procurements across US defense and critical infrastructure segments.
Established volume favors Network Infrastructure; emerging adoption favors Edge Computing.
Deployment Model:
Cost tier segmentation separates sovereign data requirements from cloud economics trade-offs.
- Hybrid Cloud:Split architectures process sensitive OT data on-premises while bursting analytics workloads to public infrastructure. German industrial zones favor this model to satisfy GDPR data residency while accessing elastic compute.
- Private Cloud:Captive infrastructure delivers guaranteed latency for safety-critical machinery control. French aerospace manufacturers deploy private stacks to meet EU AI Act algorithmic audit trail requirements.
- Public Cloud:AWS IoT Core and Azure IoT Hub connectivity services span edge-to-cloud integration.
- On-Premises:Air-gapped installations serve nuclear and defense facilities with NIST cybersecurity framework compliance.
Margin concentration sits with Private Cloud deployments; volume expansion runs through Hybrid Cloud configurations.
Service Type:
Customer maturity determines whether buyers self-operate or outsource fleet lifecycle management.
- Managed Services:Subscription-based fleet monitoring and security patching transfers operational burden to specialized operators. German Mittelstand manufacturers prefer capex-light models that compress upfront equipment margins.
- Professional Services:System integrators deploy custom middleware for multi-vendor sensor fleet unification. Brownfield protocol gateway development absorbs margin erosion across Central European manufacturing clusters.
- Consulting Services:Architecture design engagements precede large-scale smart city sensor network rollouts.
- Technical Support:Tiered response contracts cover time-critical industrial automation restoration.
Recurring revenue pools deepest in Managed Services; project-based Professional Services capture discrete transformation budgets.
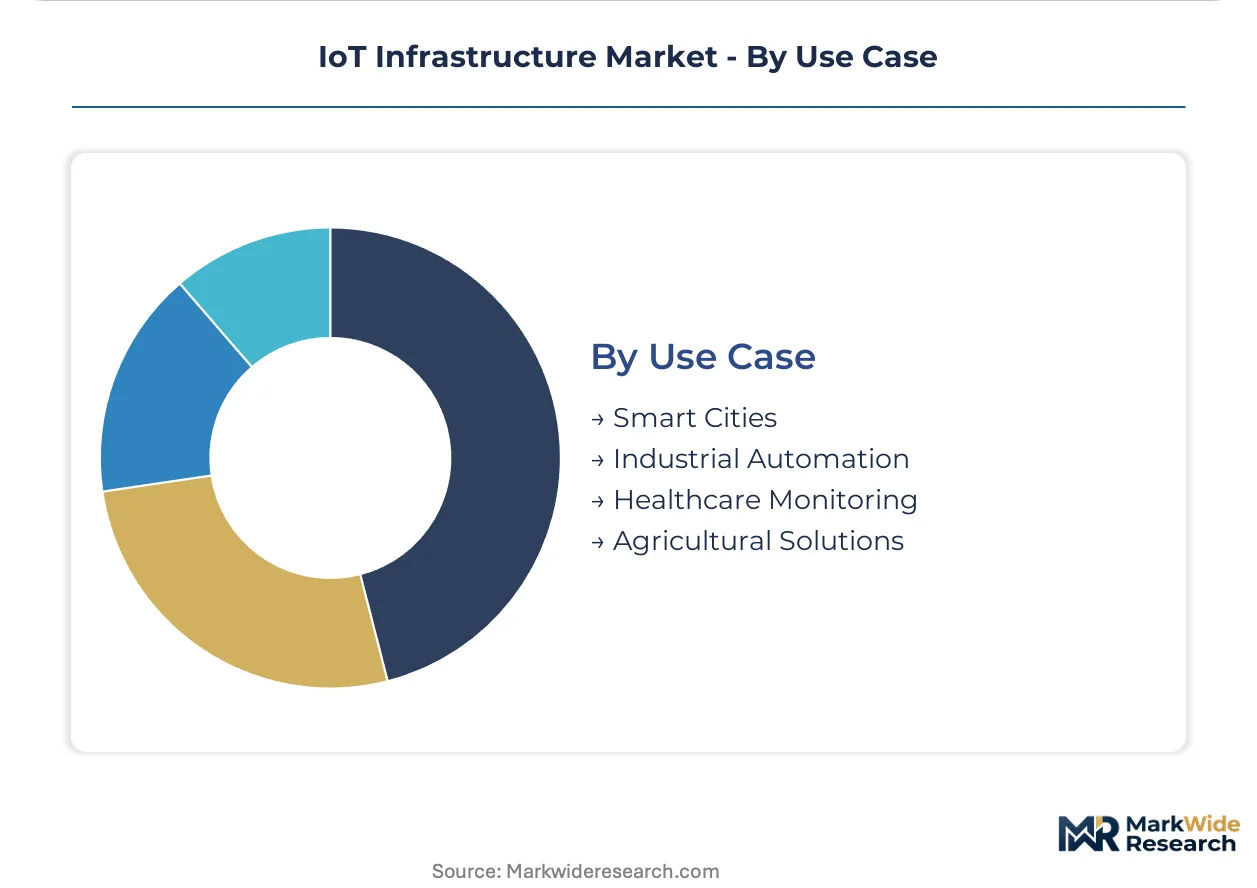
Use Case:
Application-driven demand concentrates where sensor density delivers measurable operational returns.
- Industrial Automation:Predictive maintenance and robotic coordination dominate private 5G network investment. Stuttgart and Wolfsburg automotive plants adopt TSN-enabled servo drives for microsecond-precision welding synchronization.
- Smart Cities:Singapore and Bangkok municipal data platforms aggregate multi-vendor environmental and traffic sensor streams. Standardized API frameworks reduce integration friction for foreign infrastructure suppliers.
- Healthcare Monitoring:Connected medical devices face EU AI Act high-risk classification with extended notified body review timelines.
- Agricultural Solutions:Precision irrigation and livestock tracking deploy across India PLI scheme electronics manufacturing corridors.
Current deployment scale favors Industrial Automation; steepest expansion trajectory belongs to Smart Cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German industrial zones where EU Green Deal mandates accelerate procurement, while Southeast Asian deployments compete primarily on deployment speed and sensor density economics.
Germany
Factory digitization under EU Green Deal mandates drives private 5G network investments across industrial corridors. KBA certification requirements shape automotive sector edge computing procurement standards. Stuttgart and Wolfsburg automotive clusters adopt TSN-enabled servo drives for microsecond-precision robotic welding synchronization.
United States
FCC spectrum allocations for CBRS and 5G private networks determine deployment feasibility across industrial campuses. NIST cybersecurity frameworks mandate baseline encryption standards for federal IoT procurements. Houston petrochemical complexes and Detroit automotive zones retrofit legacy equipment with connected metering infrastructure.
India
PLI scheme incentives for electronics manufacturing attract private 5G infrastructure investment into industrial corridors. TRAI spectrum policy frameworks enable enterprise-owned cellular networks for factory automation. Gujarat and Tamil Nadu states offer land-banking for edge data center placement near manufacturing clusters.
Singapore
Municipal data platforms aggregate multi-vendor environmental and traffic sensor streams for smart city operations. IMDA regulatory frameworks standardize API protocols for foreign infrastructure supplier integration. The city-state's sensor network rollout serves as reference architecture for Bangkok and Jakarta replication efforts.
France
EU AI Act algorithmic transparency requirements extend product launch timelines for connected safety systems. ANSM review protocols apply to medical device IoT deployments with high-risk classification. Toulouse aerospace manufacturers deploy private cloud stacks to satisfy audit trail documentation mandates.
IoT Infrastructure Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper technical positioning. The vendor landscape organizes around three strategic archetypes: cloud hyperscalers extending connectivity services, industrial automation incumbents leveraging factory floor relationships, and networking equipment suppliers controlling enterprise infrastructure channels. Consolidation pressure runs through M&A activity targeting edge software capabilities, while partnership formations between radio vendors and server manufacturers accelerate pre-integrated private 5G offerings.
Among cloud-native platform providers, Amazon and Microsoft exemplify the connectivity-service archetype, each anchoring distinct industrial workload strategies through edge-to-cloud integration stacks. Siemens occupies a position within the automation-heritage tier, representing European industrial equipment suppliers extending into digital infrastructure layers. Cisco sits within the networking-dominant archetype, leveraging enterprise channel control to bundle hardware-software infrastructure stacks.
| Leading Market Players |
|---|
| Intel |
| Amazon |
| Siemens |
| Microsoft |
| PTC |
| ABB |
| Samsara |
| Cisco |
| Others |
Supply Flow & Price Mechanics
Taiwan foundry concentration for industrial Ethernet switch ASICs creates simultaneous pricing tier compression and supply chain rigidity, forcing German Mittelstand manufacturers to absorb extended procurement cycles while vendors struggle to pass through input cost volatility.
Pricing Analysis
Configured-to-order pricing for private 5G edge nodes commands substantial premiums over standard industrial Ethernet switch configurations. Subscription-based managed service models now dominate German manufacturing procurement, compressing upfront equipment margins while shifting revenue to recurring streams. Price differentiation hinges on NIST cybersecurity framework certification tier and after-sales service bundling intensity. Cost compression in standard networking hardware is intensifying because Taiwanese foundry capacity constraints limit component availability.
Supply Chain Analysis
Contract manufacturing for industrial IoT gateways concentrates at Foxconn, Jabil, and Flex facilities across Taiwan, China, and Mexico. Semiconductor fabrication for time-sensitive networking ASICs draws from Taiwan foundries, South Korean memory suppliers, and Chinese passive component manufacturers. Single-source vulnerability around TSMC advanced node capacity threatens private 5G radio access network deployment timelines. Distribution runs through Cisco and Siemens enterprise channel partnerships with direct-to-factory fulfillment for large automotive OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IoT infrastructure demand tracks industrial capital expenditure cycles, with German automotive retooling programs and Southeast Asian smart city buildouts signaling an upswing phase.
For Market Incumbents:Entrench factory floor relationships through pre-integrated private 5G edge offerings that collapse radio and compute procurement decisions. Absorb edge software capabilities via targeted acquisition to counter cloud hyperscaler connectivity service expansion. Deepen channel control over German Mittelstand manufacturers by embedding subscription-based managed services into hardware contracts.
For New Entrants and Emerging Players:Pursue white-space opportunities in India PLI scheme industrial corridors where land-banked edge data center placement remains undersupplied. Target agricultural IoT solutions across Gujarat and Tamil Nadu manufacturing clusters with precision irrigation hardware bundled with TRAI-compliant private network services. Attack through vertical-specific API frameworks that reduce multi-vendor sensor integration friction for Southeast Asian municipal buyers.
For Investors and Strategic Acquirers:The market sits at a capacity-constrained phase that favors vendors with captive semiconductor supply arrangements and certified security module portfolios. Long-term viability rests on sustained industrial automation investment cycles and regulatory compliance service attach rates. Acquisition targets with FIPS 140-2 validation and EU AI Act documentation capabilities command defensive positioning. Monitor CBRS spectrum auction clearing prices and Taiwan foundry utilization rates as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-to-Cloud Platform Integration | AWS IoT Core and Azure IoT Hub partnerships collapse procurement friction for manufacturing OEMs. |
| Private 5G Radio Pre-Integration | Siemens and Nokia bundling accelerates German automotive plant deployment timelines. |
| TSN-Enabled Servo Drive Certification | Stuttgart stamping lines specify microsecond-precision timing for robotic welding synchronization. |
| NIST Cybersecurity Framework Validation | FIPS 140-2 certification unlocks US defense and critical infrastructure procurement channels. |
| Managed Service Subscription Conversion | German Mittelstand preference shifts concentrate vendor revenue in recurring security patching streams. |
Methodological Framework
The analysis maps edge computing nodes, network infrastructure hardware, cloud connectivity services, and security framework modules, each validated through plant engineers, OEM procurement teams, system integrators, and hyperscaler platform specialists. Primary interviews with industrial automation directors and municipal IT architects combined with secondary validation against FCC spectrum allocation records, EU AI Act implementation guidance, and NIST cybersecurity framework documentation. Bottom-up sensor deployment tallies triangulate against top-down infrastructure spending estimates from national industrial digitization programs.
Assumptions held fixed include EU Green Deal factory mandate enforcement timelines and Taiwan semiconductor foundry capacity allocation priorities, while CBRS licensing velocity and India PLI scheme disbursement rates were varied across scenarios. Segmentation dimensions modeled encompass infrastructure type, deployment model, service type, and use case application with geographic regulatory cluster overlays. CAGRs derive from installed base expansion rates and replacement cycle compression for legacy fieldbus systems. Forecast inputs include German automotive production forecasts and Southeast Asian smart city sensor density targets.
Sensitivities concentrate around Taiwan geopolitical risk scenarios and EU AI Act notified body review timeline extensions. Forecasts reflect documented assumptions regarding industrial Ethernet switch ASIC supply continuity and private 5G spectrum license clearing efficiency. Quarterly review of Taiwan foundry utilization rates and German industrial order intake indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Global Residential Smart Thermostats Market
Internet of Things (IoT)
Lora and Lorawan IoT Connectivity Market
Internet of Things (IoT)
IoT in Warehouse Management Market
Internet of Things (IoT)
IoT Smart Poles Market
Internet of Things (IoT)
IoT Lpwans Market
Internet of Things (IoT)
North America and Europe IoT Gateway Market
Internet of Things (IoT)
South Africa IoT Market
Internet of Things (IoT)
US Smart Thermostat Market
Internet of Things (IoT)
Smart Pool Systems Market
Internet of Things (IoT)
IoT Development Kit Market
Internet of Things (IoT)
IoT Middleware Market
Internet of Things (IoT)
LAMEA Bluetooth 5.0 Market
Internet of Things (IoT)
Global IoT Elevators Market
Internet of Things (IoT)
Cellular Internet of Things (IoT) Devices Market
Internet of Things (IoT)
Narrowband-Internet of Things (NB-IoT) Market
Internet of Things (IoT)
IoT IAM Market