
 Medical Morphine Market | 2026-2036
Medical Morphine Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Morphine Market Foresight
A capital-intensity divergence between large-scale API manufacturers and finished-dose packagers is bifurcating competitive returns in medical morphine. Mallinckrodt Pharmaceuticals leverages its vertically integrated poppy straw processing infrastructure to control upstream alkaloid supply. Pfizer Inc. anchors its position through sustained investment in sterile injectable capacity across North American manufacturing sites. Sun Pharmaceutical Industries competes on cost structure by operating high-volume oral solid dose facilities in India.
Medical morphine is a phenanthrene opioid alkaloid derived from opium poppy, typically formulated as sulfate or hydrochloride salts with purity specifications exceeding 98% for pharmaceutical grade. Its primary purpose is potent analgesia in severe pain states where non-opioid therapies prove inadequate. Injectable delivery modes command premium pricing in acute care settings where rapid titration determines therapeutic outcomes. Extended-release tablets dominate volume in palliative care facilities seeking steady-state plasma concentrations. Oral solutions retain structural importance in home care settings where dysphagia or pediatric dosing complicates solid administration.
The FDA Risk Evaluation and Mitigation Strategy and the DEA production quota system jointly constrain supply elasticity and shape manufacturer inventory planning. DEA scheduling under Controlled Substances Act Schedule II mandates dual-locked storage, witnessed waste destruction, and serialized chain-of-custody documentation that elevates distribution costs. Manufacturers must monitor how state-level prescription drug monitoring programs and institutional opioid stewardship protocols redirect demand toward abuse-deterrent formulations and alternative delivery technologies.
Market Dynamics
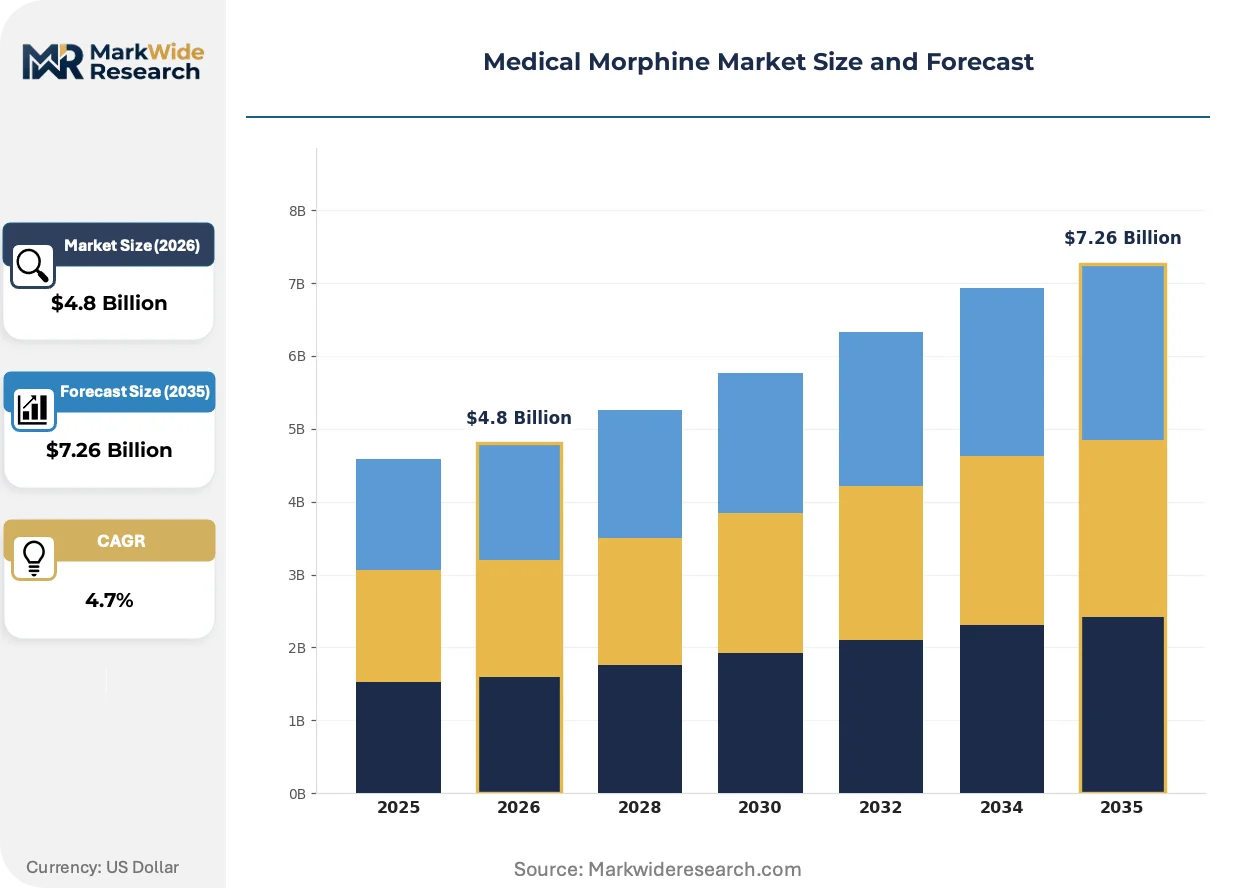
The DEA production quota system and FDA Risk Evaluation and Mitigation Strategy are compressing supply elasticity while palliative care expansion pulls demand upward, creating a structural tension between access imperatives and control mandates.
Growth Catalysts
- Palliative care infrastructure:Hospice and long-term care facilities in the United States are expanding morphine procurement for terminal cancer pain management. State-level certificate-of-need programs are approving new dedicated palliative units.
- Extended-release formulation demand:Steady-state plasma concentration requirements from institutional pain protocols favor long-acting tablets over immediate-release alternatives. Hospital formularies are prioritizing these SKUs.
- EMA centralized procedure harmonization:European marketing authorization streamlining is reducing time-to-market for sulfate and hydrochloride salt formulations across EU member states.
Market Restraints
- Poppy straw supply concentration:Tasmania and Turkey control the majority of raw alkaloid feedstock, exposing API manufacturers to geopolitical and climatic disruption risk.
- Schedule II storage and distribution costs:The Controlled Substances Act mandates dual-locked warehousing, witnessed waste destruction, and serialized chain-of-custody documentation that elevates per-unit logistics expenditure.
- Abuse-deterrent formulation substitution:Polymer-matrix and prodrug technologies for oxycodone and hydrocodone are capturing share in moderate-to-severe pain segments where morphine previously dominated.
Strategic Opportunities
- Home care oral solution penetration:Dysphagia and pediatric dosing requirements in the United States are creating demand for liquid formulations outside institutional settings.
- Indian domestic market expansion:CDSCO regulatory streamlining and government insurance scheme expansion are opening access to cancer pain populations previously reliant on codeine.
- Abuse-deterrent morphine development:EMA and FDA parallel scientific advice pathways are accelerating approval timelines for gel-cap and multi-particulate formulations with intranasal abuse resistance.
Industry Challenges
- Sterile injectable manufacturing capacity:Aseptic fill-finish line qualification and isolator technology deployment require capital commitments that strain mid-scale API producers.
- Opioid stewardship compliance:Institutional protocols and prescription drug monitoring program integration demand specialized pharmacovigilance personnel that compete for talent with biologics manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Morphine Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Solution, Injectable, Extended-Release Tablets, Immediate-Release Tablets Delivery Mode: Subcutaneous, Intravenous, Oral, Epidural End User: Hospitals, Home Care Settings, Palliative Care Facilities, Rehabilitation Centers Therapy Area: Cancer Pain Management, Chronic Pain Relief, Postoperative Pain Treatment, Terminal Illness |
| Companies Covered | Mallinckrodt Pharmaceuticals, Pfizer Inc., Purdue Pharma, Teva Pharmaceutical Industries, Sun Pharmaceutical Industries, Johnson Matthey Fine Chemicals, AbbVie Inc., Hikma Pharmaceuticals, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Morphine Market Shifts & Advancements
Formulation technology and regulatory science are converging to reshape how morphine products demonstrate differentiation, with delivery mechanism innovation outpacing molecular modification in competitive positioning.
Implantable osmotic pump systems are miniaturizing. Palliative care units in Germany and the United States are piloting subcutaneous reservoir devices that eliminate oral administration burden for end-stage patients. This hardware is miniaturizing from wearable patch dimensions to injectable depot formats, compressing the boundary between acute and chronic pain management modalities.
The FDA's Risk Evaluation and Mitigation Strategy for extended-release opioids mandates prescriber certification and patient counseling documentation. Manufacturers must maintain restricted distribution programs with audited pharmacies. Extended-release tablet producers bear the heaviest compliance burden, with some reallocating R&D toward abuse-deterrent alternative salts.
Hospital procurement committees are consolidating analgesic formularies around single-source contracts with abuse-deterrent portfolios. Group purchasing organizations in the United States are bundling morphine with comparator opioids, displacing standalone SKU selection. This concentration is most visible in integrated delivery networks across the Midwest and Southeast regions.
Medical Morphine Market Segmentation
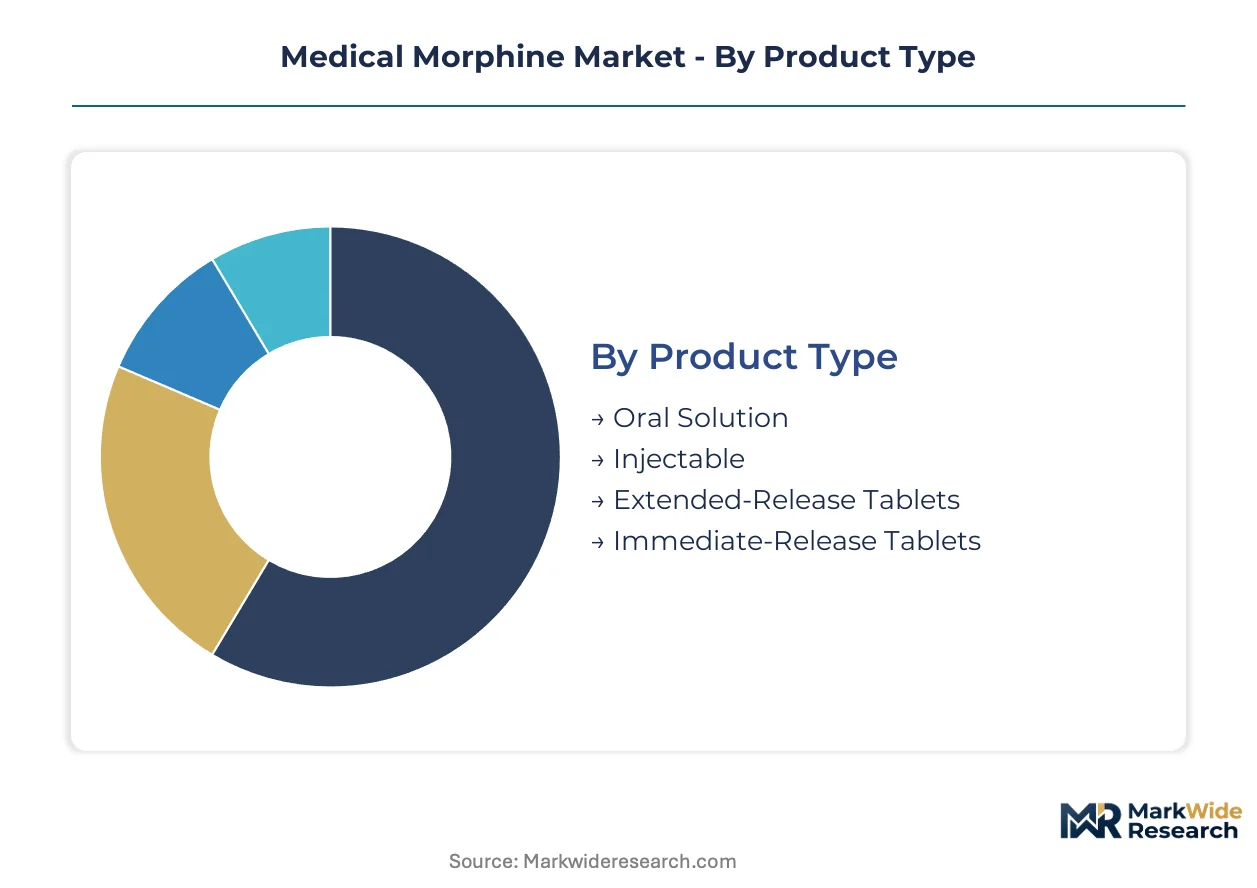
Medical morphine demand fragments across formulation technologies and care settings. Each segment carries distinct regulatory burdens, margin profiles, and competitive dynamics that shape manufacturer portfolio priorities.
Product Type:
Margin pools concentrate in extended-release and injectable formats where formulation complexity erects barriers to commoditization.
- Injectable:Sterile sulfate or hydrochloride solutions for rapid titration in acute care. Demand clusters in United States surgical wards and oncology units where prescriber preference for IV push administration sustains premium positioning against oral alternatives.
- Extended-Release Tablets:Polymer-matrix or osmotic pump technologies delivering 12-24 hour plasma concentration stability. Palliative care facilities in Germany and the United States favor these SKUs for terminal cancer protocols requiring minimal dosing frequency.
- Oral Solution:Concentrated liquid formulations for dysphagia and pediatric populations. Home care penetration in the United States drives volume.
- Immediate-Release Tablets:Short-acting solid doses for breakthrough pain. Pricing pressure from generic substitution compresses returns.
The dominant share belongs to Extended-Release Tablets, while Injectable formats are gaining share fastest through hospital formulary consolidation.
Delivery Mode:
Volume distribution tracks institutional capability — acute care sites with anesthesia infrastructure anchor intravenous and epidural channels.
- Intravenous:Direct vascular administration enabling minute-scale titration. United States hospital-based cancer centers and post-surgical units maintain this as the default for severe, unstable pain.
- Subcutaneous:Depot injections and continuous infusion via portable pumps. Palliative care adoption in Germany and Australia expands this channel for patients transitioning from institutional to home settings.
- Oral:Swallowed tablets and solutions for stable chronic pain. Accessibility advantages sustain structural importance despite slower onset.
- Epidural:Perioperative and obstetric applications requiring anesthesia specialist presence. Concentrated in tertiary United States hospitals with dedicated pain services.
Intravenous administration retains the largest volume position, though Subcutaneous delivery is expanding most quickly through ambulatory palliative programs.
End User:
Procurement authority and reimbursement pathways determine segment profitability — institutional buyers with formularies command pricing leverage that home care channels cannot replicate.
- Hospitals:Integrated delivery networks and academic medical centers with pharmacy and therapeutics committees. United States group purchasing organization contracts bundle morphine with comparator opioids, compressing standalone SKU margins.
- Palliative Care Facilities:Dedicated hospice units and long-term care sites prioritizing steady-state analgesia. State-level certificate-of-need approvals for new palliative units in the United States are expanding addressable demand.
- Home Care Settings:Outpatient and residential care where oral solutions dominate. Dysphagia prevalence among elderly cancer patients sustains liquid formulation requirements.
- Rehabilitation Centers:Post-acute facilities managing pain during functional recovery. Lower acuity thresholds limit morphine to step-therapy protocols after non-opioid failure.
Hospitals command the dominant procurement volume, while Palliative Care Facilities are climbing the fastest as dedicated terminal illness infrastructure expands.
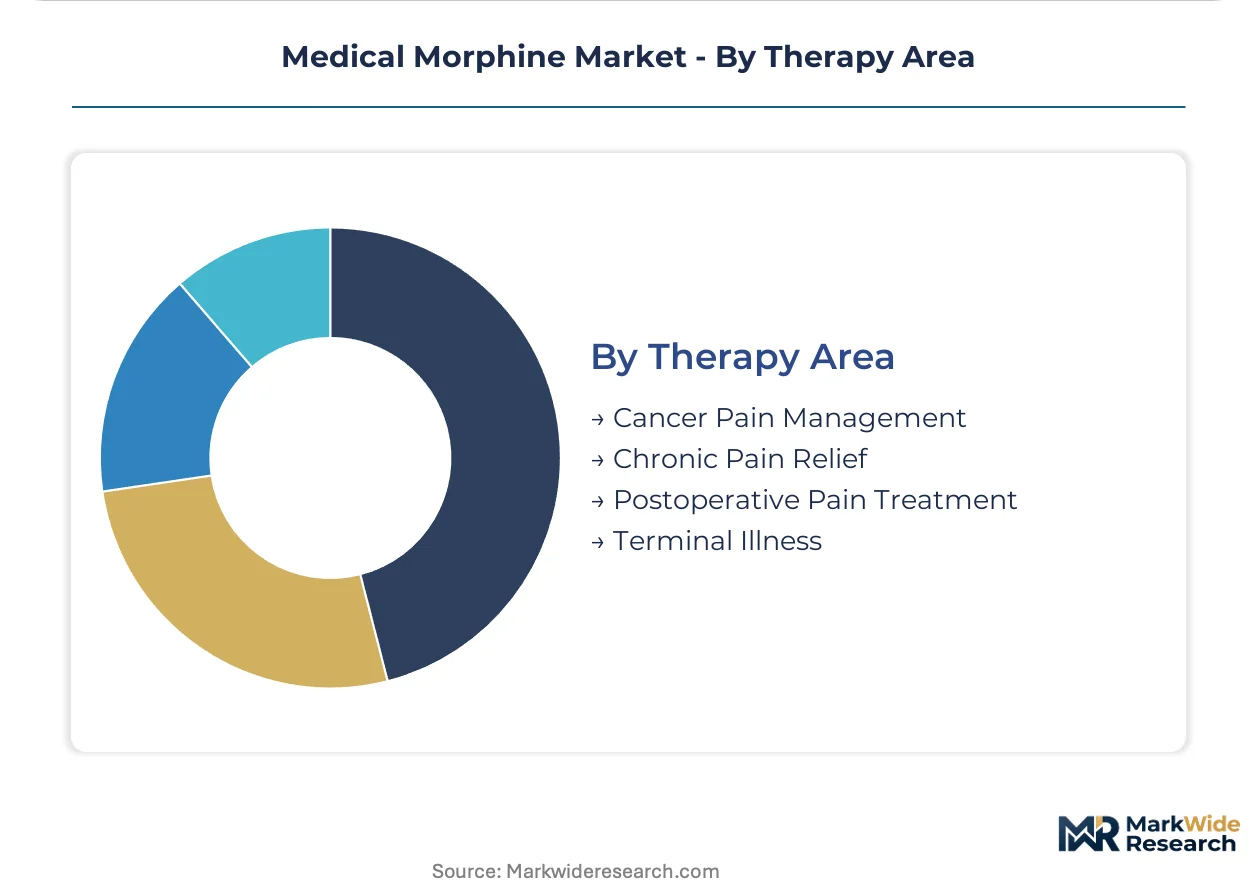
Therapy Area:
Clinical evidence requirements and regulatory scrutiny intensity vary sharply — cancer indications face lighter abuse-deterrent mandates than non-malignant chronic pain.
- Cancer Pain Management:WHO analgesic ladder compliance and oncology guideline alignment. United States National Comprehensive Cancer Network protocols maintain morphine as second-line strong opioid after oxycodone failure.
- Terminal Illness:End-of-life care where rapid titration and sedation balance take precedence over abuse concerns. Hospice benefit structures in the United States remove prior authorization barriers.
- Postoperative Pain Treatment:Acute surgical recovery with multimodal analgesia protocols. Enhanced recovery after surgery programs are displacing standalone opioid reliance.
- Chronic Pain Relief:Non-malignant persistent pain where CDC guideline thresholds and state prescription drug monitoring program scrutiny constrain duration and dose.
Cancer Pain Management holds the dominant position, while Terminal Illness applications are expanding most quickly through hospice infrastructure growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes medical morphine predominantly through hospital-based cancer pain protocols, while Germany and Australia favor subcutaneous delivery in ambulatory palliative settings. India remains concentrated in oral solid doses for cost-constrained domestic oncology programs.
United States
FDA Risk Evaluation and Mitigation Strategy and DEA production quotas constrain supply elasticity for extended-release formulations. Hospital group purchasing organizations bundle morphine with comparator opioids across Midwest and Southeast integrated delivery networks. The National Comprehensive Cancer Network protocols in Boston and Houston academic medical centers maintain morphine as second-line strong opioid therapy.
Germany
Palliative care infrastructure expansion drives subcutaneous depot injection adoption for home-based terminal patients. EMA centralized marketing authorization harmonization accelerates sulfate salt formulation approvals across federal states. The Rhineland and Bavaria regions pilot implantable osmotic pump systems in dedicated hospice units.
Australia
Ambulatory palliative programs expand subcutaneous continuous infusion via portable pumps for patients transitioning from institutional to residential care. The Therapeutic Goods Administration aligns scheduling requirements with opioid stewardship protocols. Sydney and Melbourne pain services concentrate epidural administration capacity in tertiary referral centers.
India
CDSCO regulatory streamlining and government insurance scheme expansion open access to cancer pain populations previously reliant on codeine. Domestic oral solid dose manufacturing in Gujarat and Maharashtra competes on cost structure against imported alternatives. Karnataka and Tamil Nadu oncology centers build dedicated palliative units with state-level certificate-of-need approvals.
United Kingdom
NHS formularies prioritize extended-release tablets for steady-state analgesia in hospice benefit structures. The Medicines and Healthcare products Regulatory Agency maintains alignment with EMA abuse-deterrent formulation guidance. London and Manchester academic medical centers consolidate procurement through regional pharmacy and therapeutics committees.
Medical Morphine Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in medical morphine manufacturing. Three archetypes dominate competitive positioning: vertically integrated poppy straw processors controlling upstream alkaloid supply, sterile injectable specialists with North American manufacturing footprints, and high-volume oral solid dose fabricators operating from Indian cost bases. Capacity expansion and abuse-deterrent formulation licensing represent the dominant competitive moves as institutional procurement committees consolidate formularies around bundled opioid portfolios.
Within the integrated processor tier, Mallinckrodt Pharmaceuticals exemplifies upstream control through captive poppy straw infrastructure. Pfizer Inc. anchors the sterile injectable specialist position with sustained capacity investment across North American sites. Sun Pharmaceutical Industries occupies the cost-driven oral solid dose archetype through high-volume manufacturing in India. These three entities represent distinct strategic vectors rather than direct substitutability.
| Leading Market Players |
|---|
| Mallinckrodt Pharmaceuticals |
| Pfizer Inc. |
| Purdue Pharma |
| Teva Pharmaceutical Industries |
| Sun Pharmaceutical Industries |
| Johnson Matthey Fine Chemicals |
| AbbVie Inc. |
| Hikma Pharmaceuticals |
| Sanofi |
| Others |
Supply & Pricing Matrix
DEA production quotas and FDA Risk Evaluation and Mitigation Strategy certification tiers gate both supply qualification and price differentiation simultaneously. Manufacturers holding extended-release REMS authorization command premium positioning against immediate-release commodity suppliers, while quota-constrained API producers face margin compression from locked-in alkaloid costs.
Pricing Analysis
Long-term offtake contracts between hospital group purchasing organizations and sterile injectable specialists dominate transaction structures, displacing spot-market volume. Price differentiation rests on REMS certification tier and abuse-deterrent formulation complexity, with polymer-matrix technologies sustaining premium positioning against conventional sulfate salts. Cost compression in immediate-release tablets is intensifying because Indian oral solid dose manufacturers are expanding export capacity. Home care channels exhibit highest price sensitivity due to out-of-pocket oral solution exposure, while academic medical centers with bundled contracts show lowest sensitivity.
Supply Chain Analysis
Tasmania and Turkey anchor raw alkaloid feedstock production, controlling upstream poppy straw concentrate supply. API manufacturing draws from Tasmanian thebaine-rich cultivars and Turkish morphine-extraction infrastructure, with finished-dose production tethered to Indian oral solid dose facilities and North American sterile fill-finish sites. Single-source vulnerability concentrates in Tasmanian climatic exposure and Turkish geopolitical risk. Distribution runs through DEA-registered dual-locked warehousing networks with serialized chain-of-custody documentation to institutional pharmacies and hospice benefit managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical morphine procurement is shifting toward platform-economy consolidation as hospital formularies bundle opioids through integrated delivery network contracts, creating interoperability lock-in between GPOs and abuse-deterrent portfolio holders.
For Market Incumbents: Shield market position by deepening captive poppy straw processing infrastructure against Tasmanian supply disruption, and accelerate abuse-deterrent formulation R&D through FDA-EMA parallel scientific advice pathways to preempt oxycodone polymer-matrix substitution in cancer pain protocols. For New Entrants and Emerging Players: CDSCO fast-track certification for oral solid dose oncology products opens white-space penetration in Karnataka and Tamil Nadu palliative units, with government insurance scheme reimbursement creating the most penetrable access channel. Target subcutaneous depot injection capacity gaps in German ambulatory hospice programs as the go-to-market anchor. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sterile injectable isolator technology deployment, favoring acquisition targets with existing aseptic fill-finish qualification over greenfield capacity builds. Watch for DEA quota reallocation announcements as inflection indicators for API manufacturer margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Abuse-Deterrent Formulation Development | FDA-EMA parallel scientific advice accelerates approval timelines for intranasal-resistant gel-cap technologies. |
| Backward Integration into Poppy Straw Processing | Mallinckrodt-style captive alkaloid supply insulates against Tasmanian climatic and Turkish geopolitical disruption. |
| Sterile Injectable Capacity Expansion | Isolator technology deployment in North American sites captures hospital formulary consolidation toward bundled portfolios. |
| Home Care Oral Solution Penetration | Dysphagia-targeted liquid formulations access out-of-pocket elderly cancer populations outside GPO contracts. |
| Indian Domestic Market Expansion | CDSCO streamlining and government insurance schemes convert codeine-reliant oncology patients to morphine access. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA REMS documentation, DEA production quota records, EMA centralized procedure filings, and hospital GPO contract databases. Interviews with formulary directors, palliative care pharmacists, regulatory affairs leads at API manufacturers, and procurement managers at integrated delivery networks informed demand-side dynamics. Secondary validation drew from CMS Medicare hospice benefit utilization data, state-level certificate-of-need approvals, and WHO analgesic ladder compliance audits. Bottom-up SKU-level volume builds triangulated against top-down national consumption estimates from controlled substance tracking systems.
Segmentation dimensions modeled span formulation technology, delivery mode, end-user procurement authority, and therapy area regulatory scrutiny across the projection horizon. CAGRs were derived from trend-line extrapolation of palliative care infrastructure expansion, adjusted for DEA quota elasticity constraints and abuse-deterrent substitution rates. Industry-specific forecast inputs include state-level certificate-of-need approval velocity and EMA centralized marketing authorization harmonization timelines.
Decision-makers should treat outputs as directional under assumptions of stable DEA scheduling, continued REMS enforcement, and unaltered hospice benefit structures; material deviation would warrant model refresh. Specific risk factors include poppy straw crop failure, rescheduling to Schedule I, and breakthrough non-opioid analgesic approval. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Medicated Pain Relieving Plasters Market
Pain Management
Companion Animal Postoperative Pain Management Therapeutics Market
Pain Management
Intravenous (IV) Ibuprofen Market
Pain Management
OTC Painkiller Market
Pain Management
Muscle Tension Dysphonia Treatment Market
Pain Management
Global Pain Management Market
Pain Management
Migraine Management Market
Pain Management
Chemotherapy Induced Pain Market
Pain Management
Global Visceral Pain Treatment Market
Pain Management
Asia-Pacific Chronic Disease Management Market
Pain Management
Tattoo Numbing Cream Market
Pain Management
Global Chiropractic Care Market
Pain Management
Advanced Cancer Pain Management Market
Pain Management
Cancer Pain Management Market
Pain Management
Pain Management Devices Market
Pain Management
Provoked Vestibulodynia Treatment Market